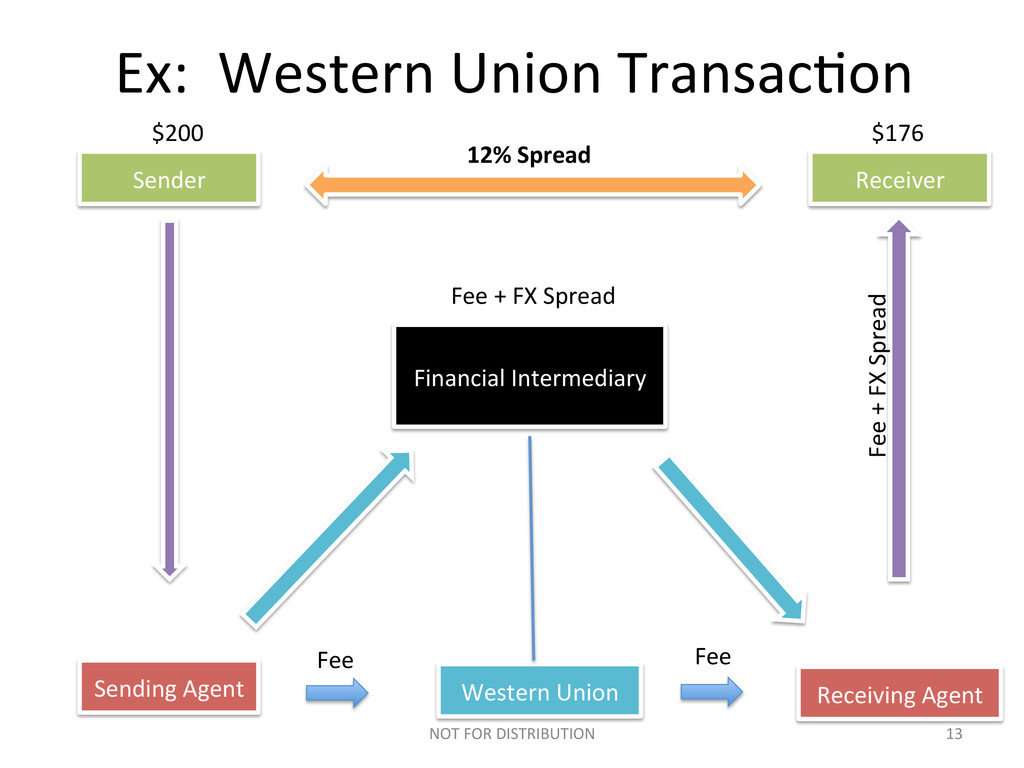
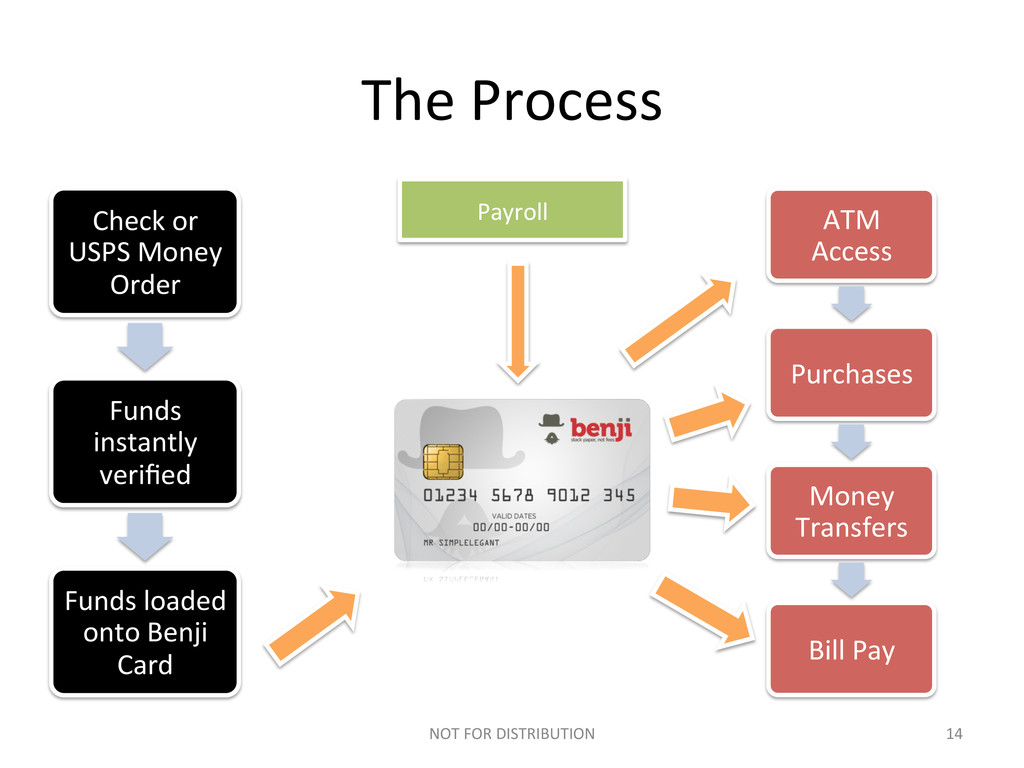
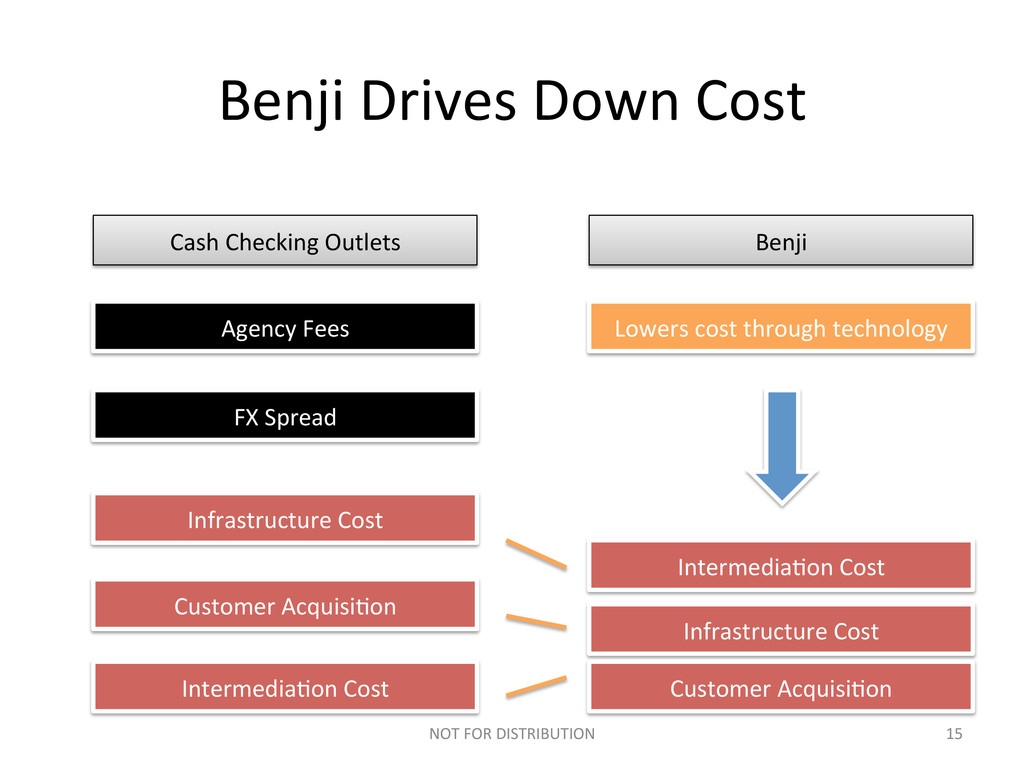
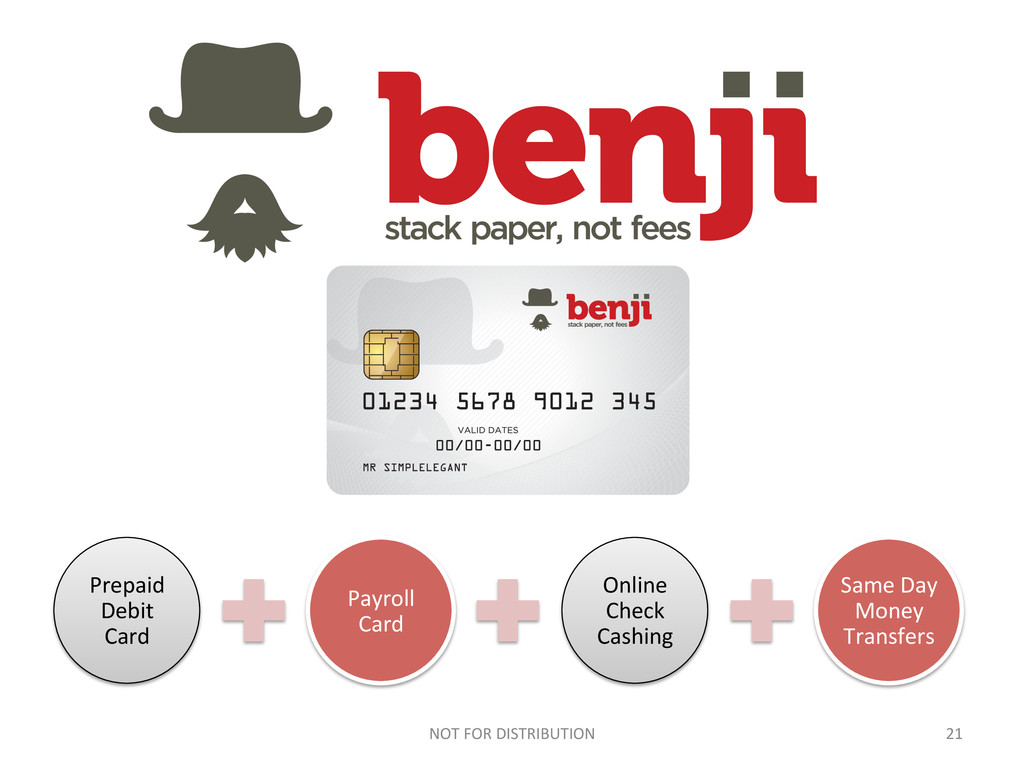
makes Alterna>ve Financial Solu>ons more affordable and convenient to the underbanked consumer • Benji’s goal is to disrupt the brick and mortar Cash Checking Outlets by lowering intermedia>on and infrastructure costs through technology • Stack Paper, Not Fees -‐ Benji NOT FOR DISTRIBUTION 2
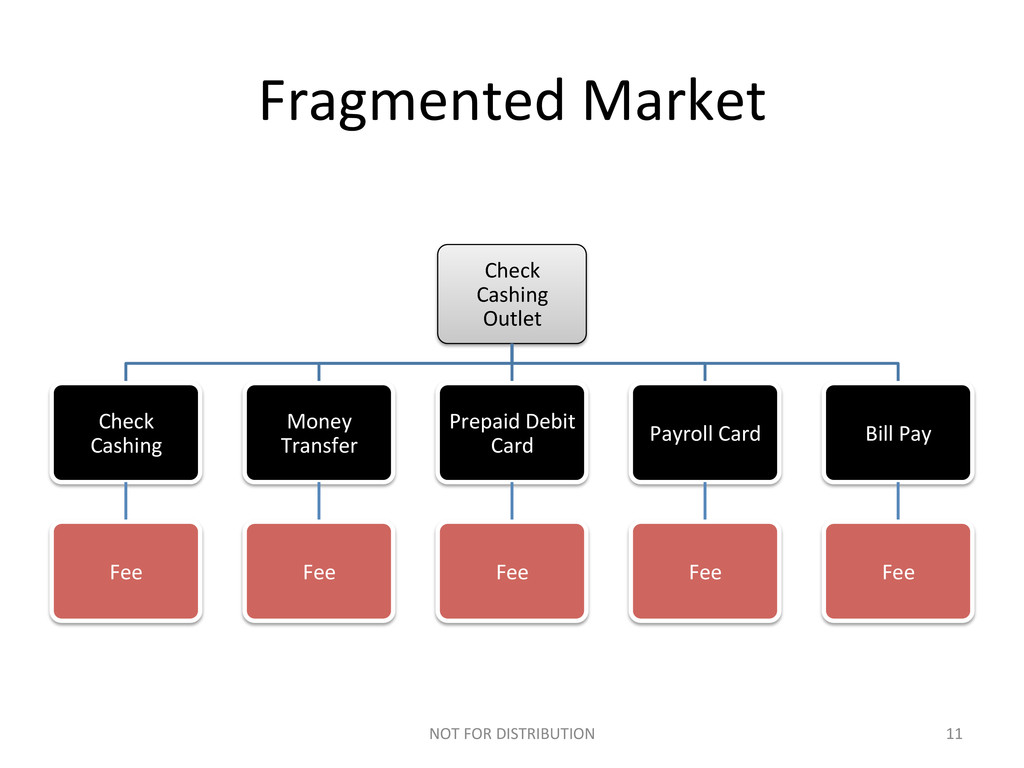
interest and fees last year alone to conduct financial transac>ons • Recent regulatory changes have prevented banks from charging certain overdraN fees and interest, this has created an acquisi4ve marketplace • The problem is two fold 1. Cash Checking Outlets dominate the distribu>on of Alterna>ve Financial Services (AFS) 2. Highly fragmented marketplace NOT FOR DISTRIBUTION 3
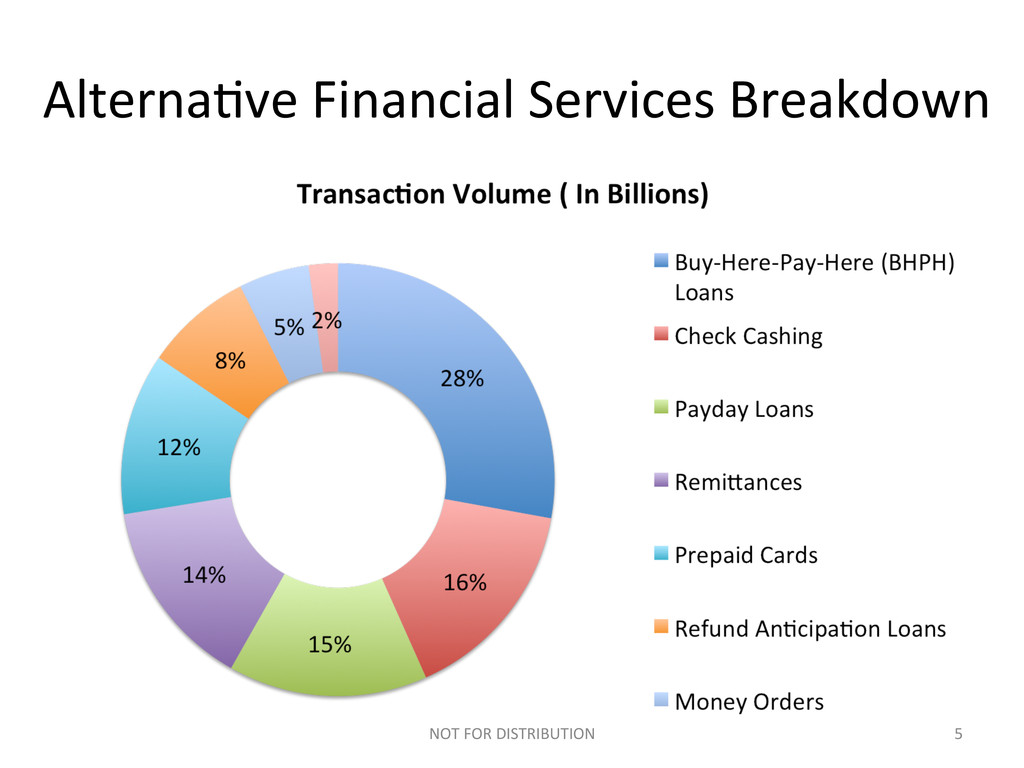
• $680b in transac>on volume last year • $78b in interest and fees – Prepaid Debit Cards – Payroll Cards – RemiYance – Check Cashing – Bill Pay – Pay Day Loans NOT FOR DISTRIBUTION 4
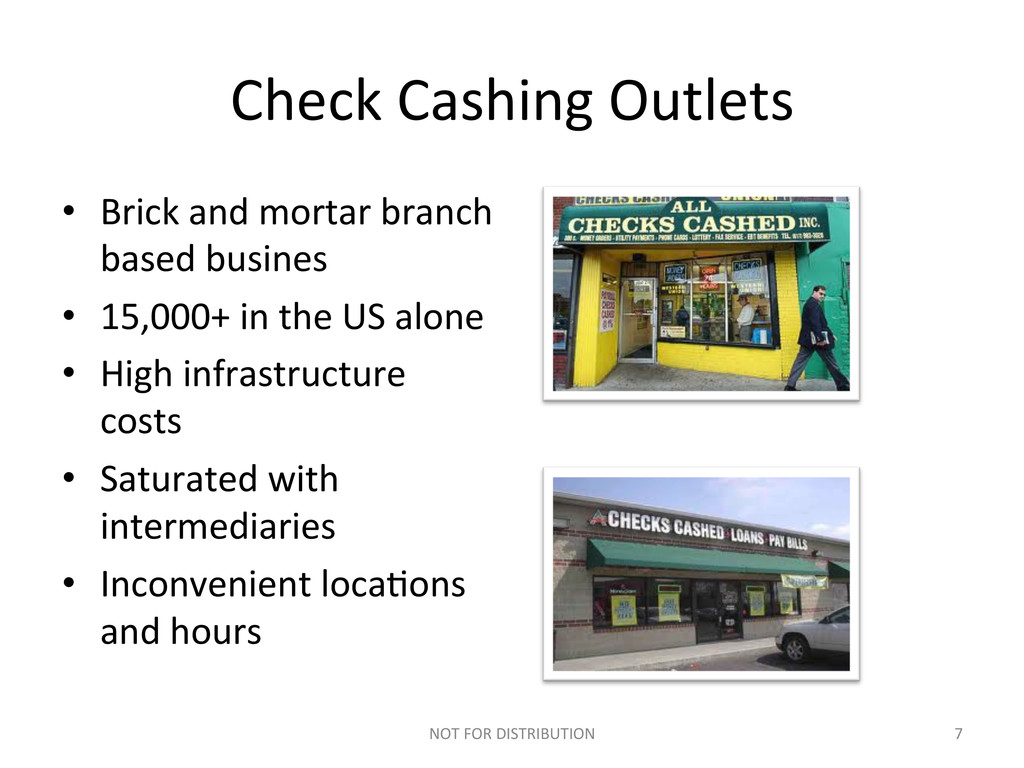
based busines • 15,000+ in the US alone • High infrastructure costs • Saturated with intermediaries • Inconvenient loca>ons and hours NOT FOR DISTRIBUTION 7
– Check cashing – Same day money transfers – Bill Pay • How this helps – Lower infrastructure costs = lower fees – Removes many of the intermediaries – 24/7 access NOT FOR DISTRIBUTION 8
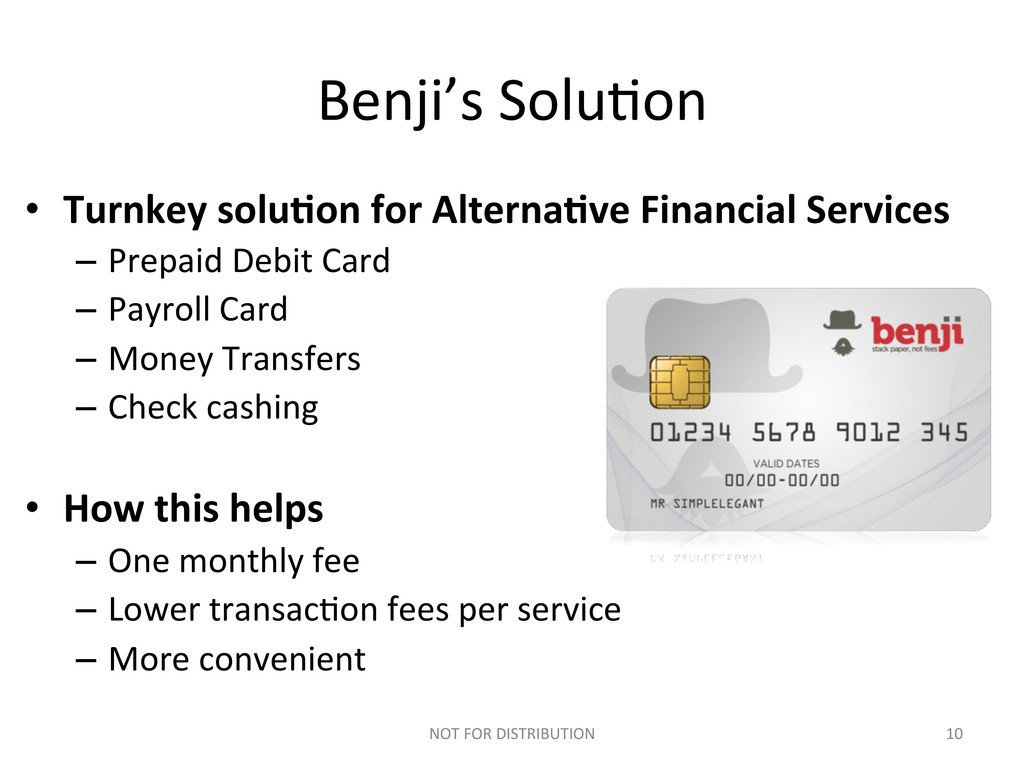
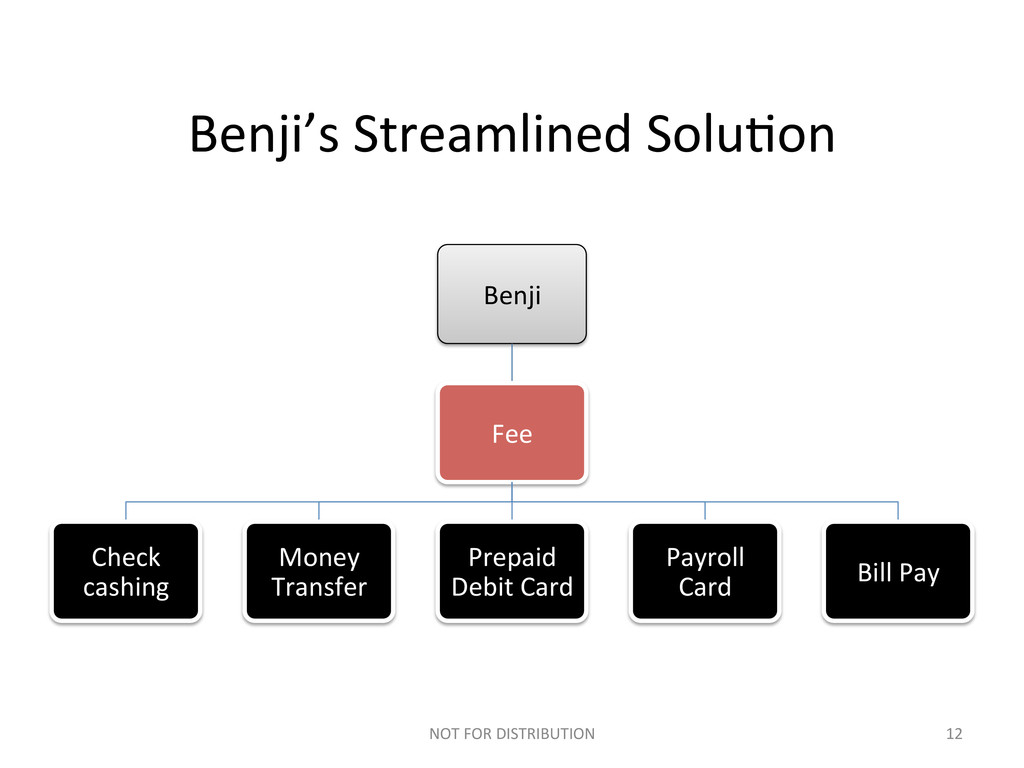
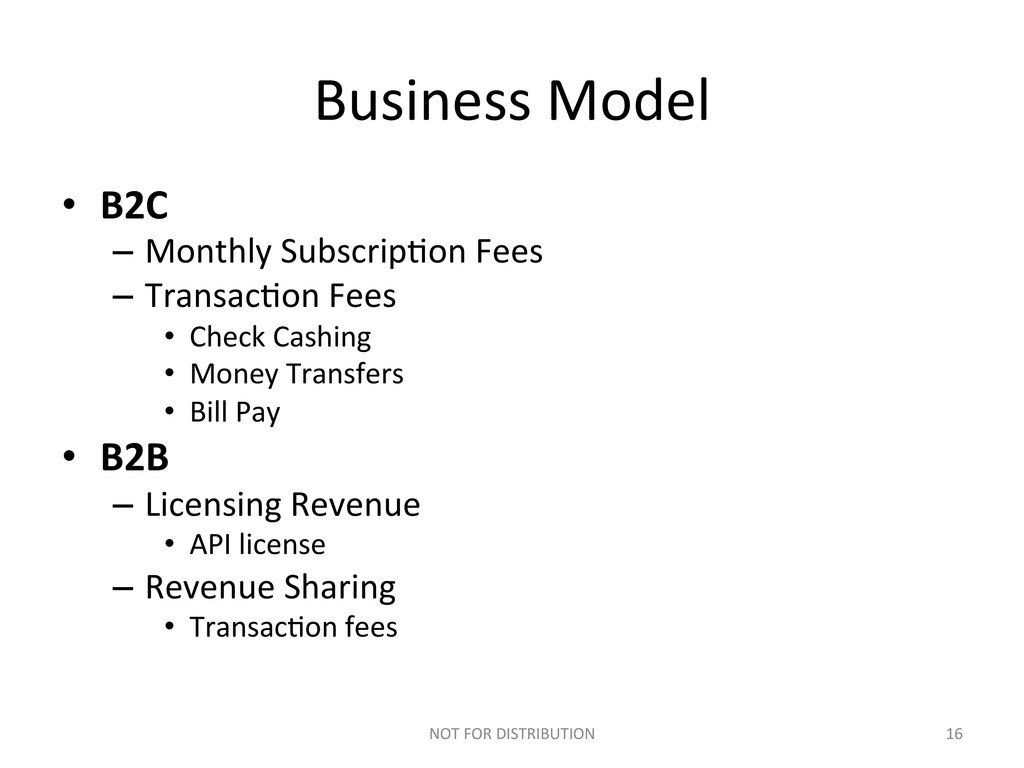
– Prepaid Debit Card – Payroll Card – Money Transfers – Check cashing • How this helps – One monthly fee – Lower transac>on fees per service – More convenient NOT FOR DISTRIBUTION 10
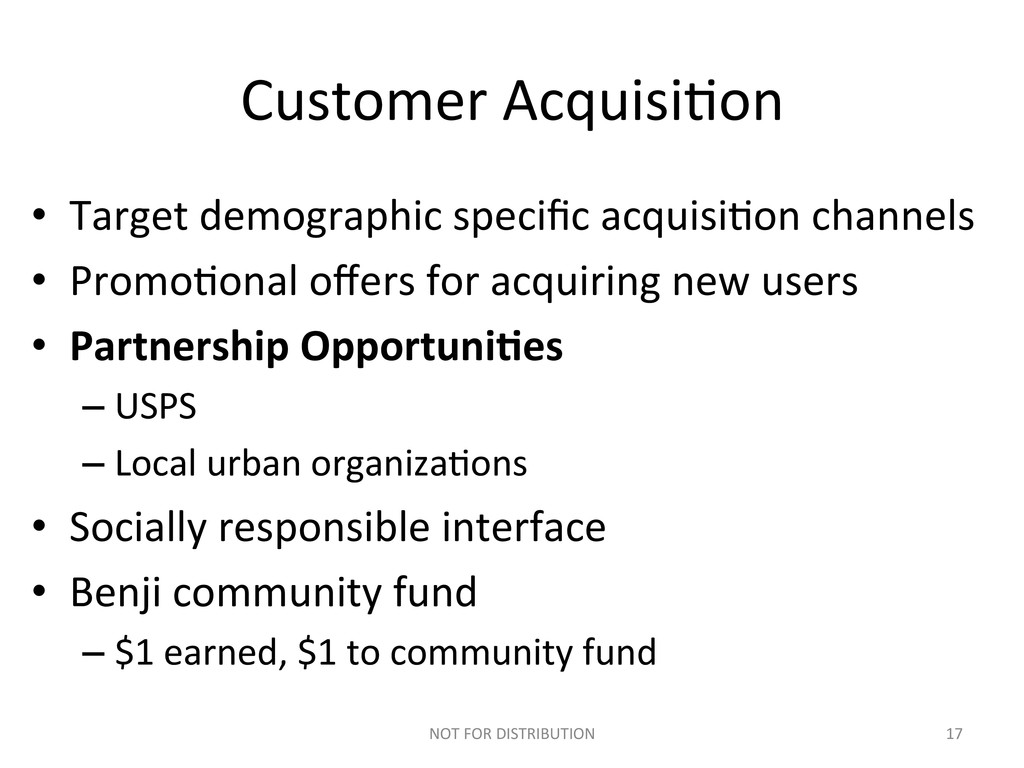
• Promo>onal offers for acquiring new users • Partnership Opportuni4es – USPS – Local urban organiza>ons • Socially responsible interface • Benji community fund – $1 earned, $1 to community fund NOT FOR DISTRIBUTION 17
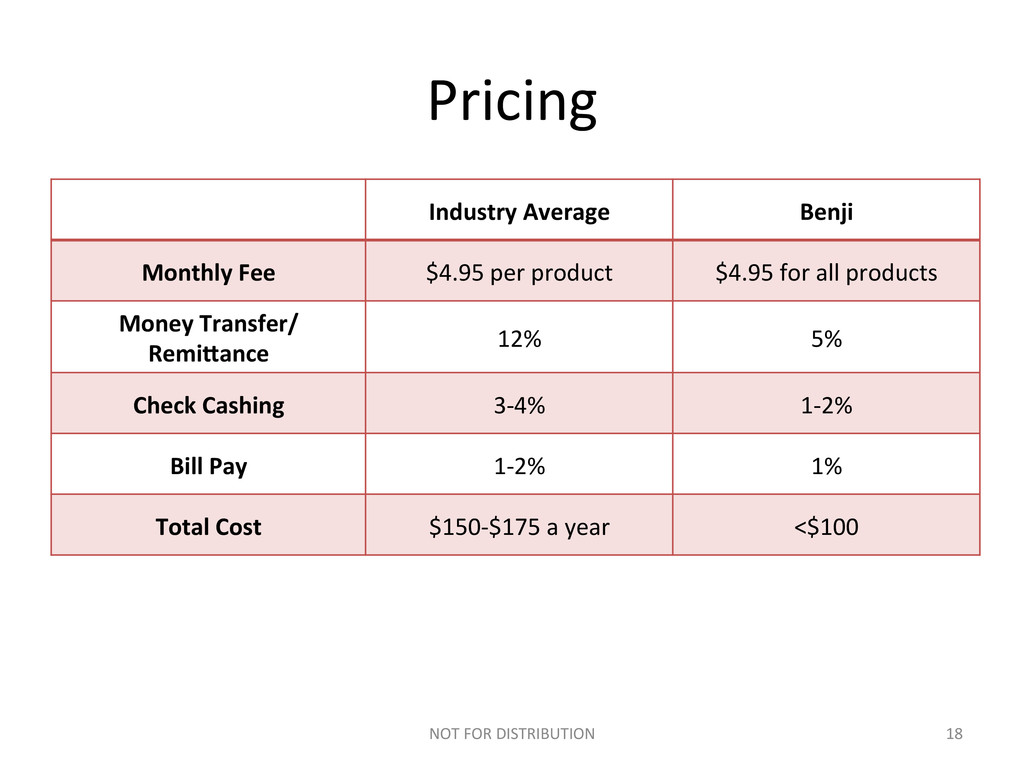
$4.95 per product $4.95 for all products Money Transfer/ RemiQance 12% 5% Check Cashing 3-‐4% 1-‐2% Bill Pay 1-‐2% 1% Total Cost $150-‐$175 a year <$100 NOT FOR DISTRIBUTION 18
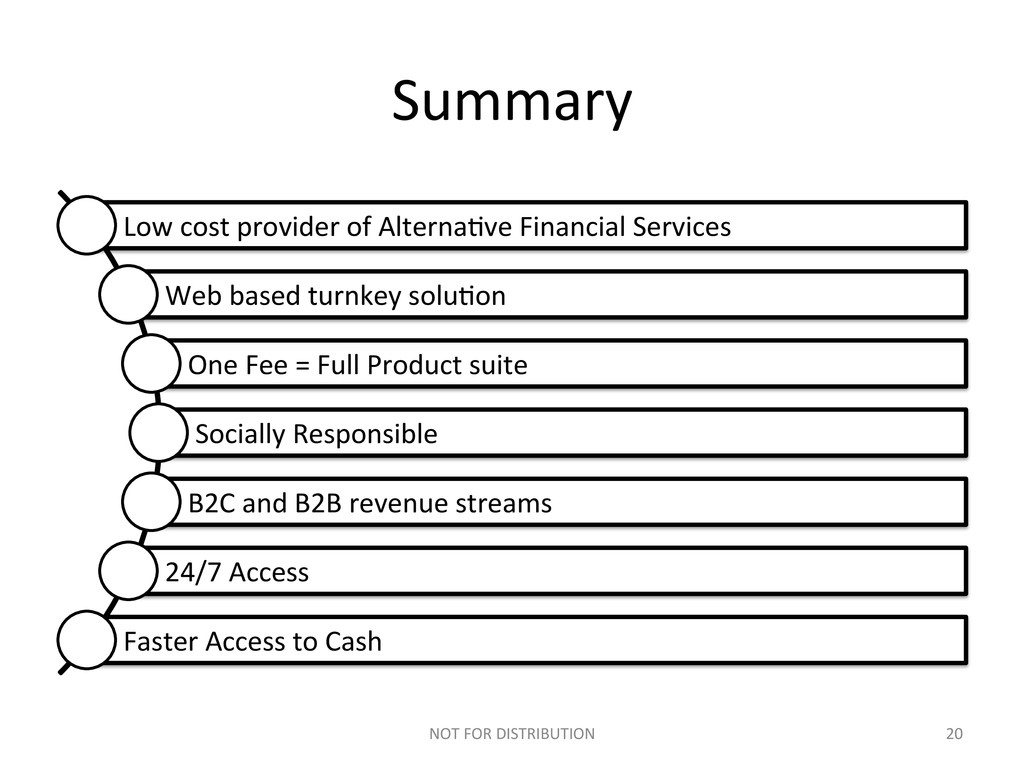
Web based turnkey solu>on One Fee = Full Product suite Socially Responsible B2C and B2B revenue streams 24/7 Access Faster Access to Cash NOT FOR DISTRIBUTION 20


 jonpalan
 tammyeverts
 malarkey
 ipullrank
 samtorres
 jnunemaker
 jct
 katiecoart
 wjessup
 moore
 reverentgeek
 leimatthew05