Upgrade to Pro — share decks privately, control downloads, hide ads and more …

Personal loans in South Africa: a quick compari...

Avatar for LoanHub24 LoanHub24
October 15, 2025
6

Personal loans in South Africa: a quick comparison framework

A short, practical deck that shows how to compare personal-loan offers without harming your credit score. Learn the difference between soft vs hard enquiries, how APR, fees, and term translate into total cost, and what NCA affordability checks mean for you. Includes a one-page checklist and a worked example you can reuse. Built for busy South African consumers and professionals who want a clear, POPIA-aware process—no sales, just steps.

Resources: Personal-loans guide

Avatar for LoanHub24

LoanHub24

October 15, 2025

Transcript

  1. Why compare properly Compare: APR, fees, term, credit checks Avoid:

    multiple hard checks, unclear fees, “guaranteed approval” Two R50 000 loans can differ by thousands of rand because of fees and term. APR bundles interest + compulsory fees, so it’s the only apples-to-apples number. Hard checks can dent your score; do one when you’re ready, not five.
  2. Docs to prep (5–10 min) Bring: SA ID • last

    3–6 months payslips + bank statements • proof of address (≤3 months) Know your budget: target instalment you can actually afford Having documents ready speeds up pre-qualification and lets you compare real offers (not generic “from X%”). Know your max monthly you can pay without stress; this steers term selection.
  3. APR vs Rate (the key) Rate = interest only APR

    = interest + initiation + monthly service + compulsory insurance Rule: Always compare APR for true cost If Offer A is 20% rate with big fees and Offer B is 22% with small fees, B’s APR can be lower and cheaper overall. Ask lenders for APR or compute total cost including all compulsory fees.
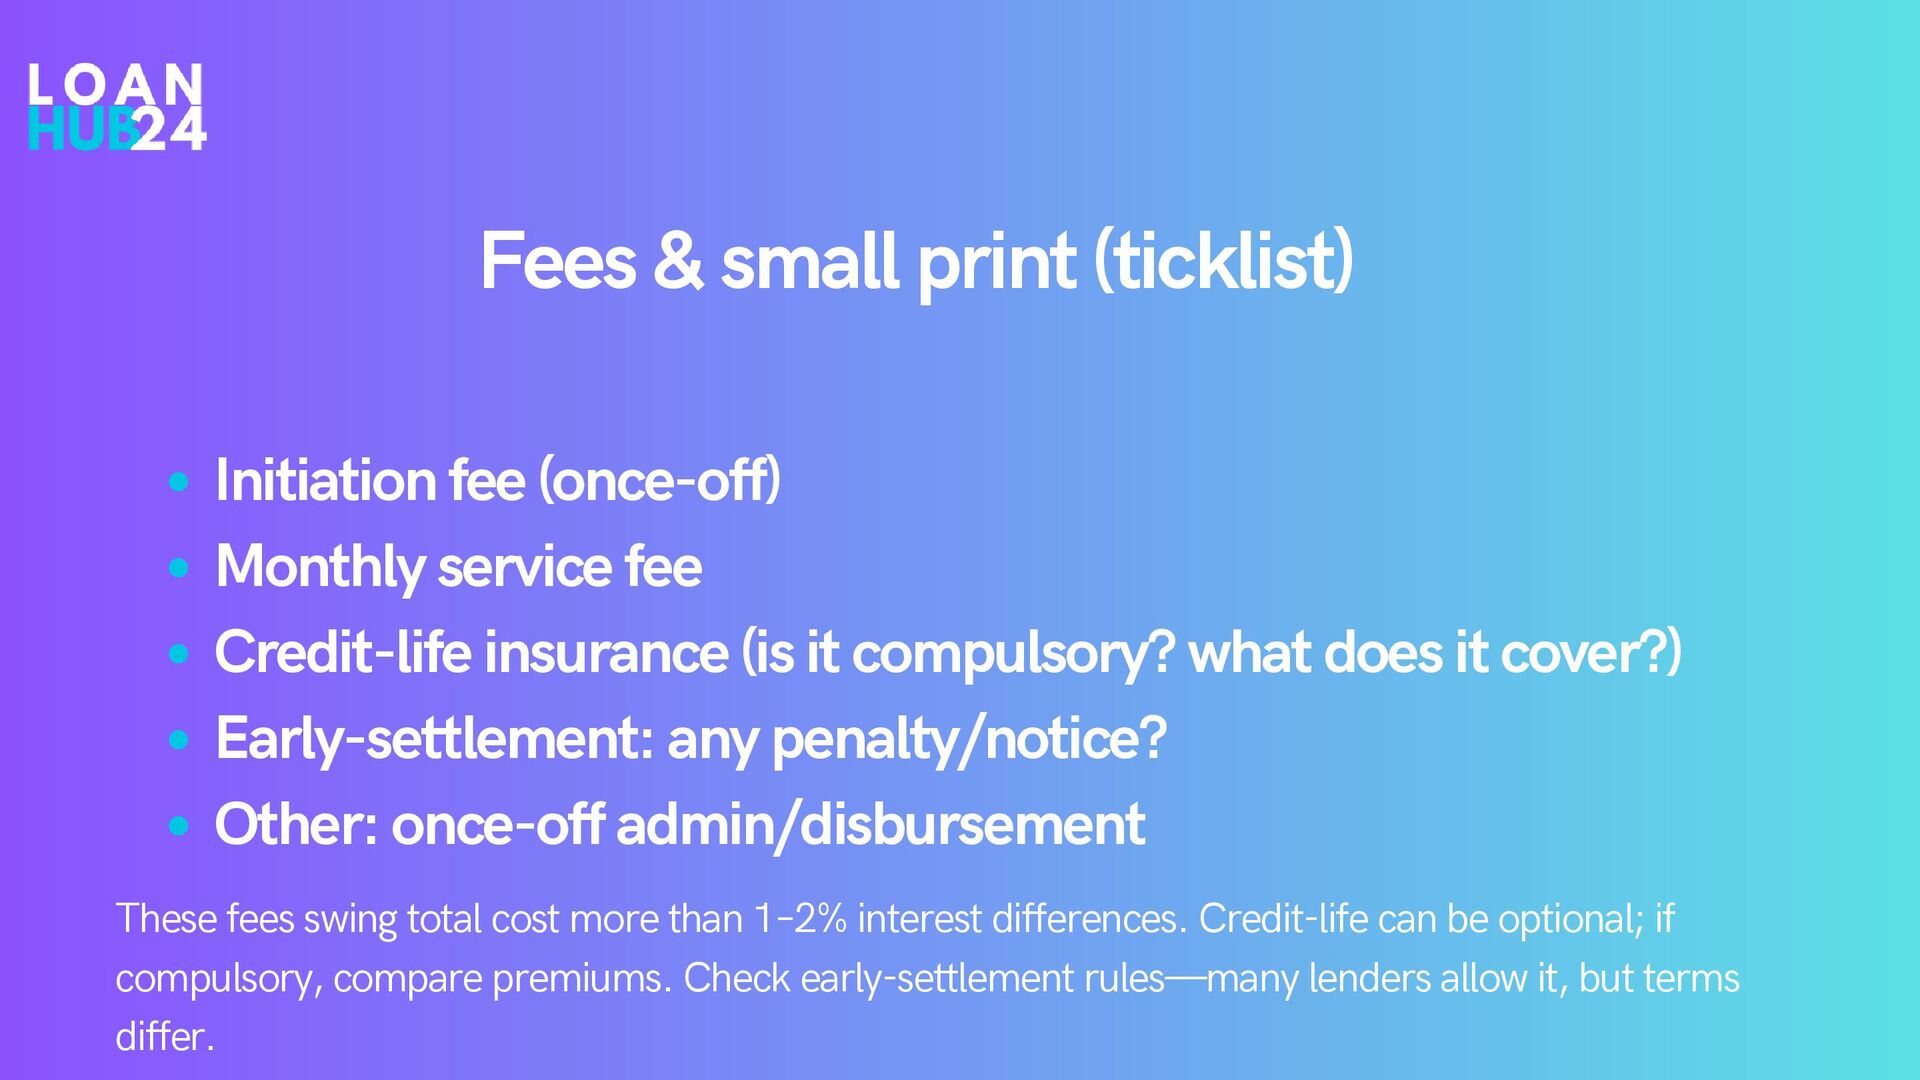
  4. Fees & small print (ticklist) Initiation fee (once-off) Monthly service

    fee Credit-life insurance (is it compulsory? what does it cover?) Early-settlement: any penalty/notice? Other: once-off admin/disbursement These fees swing total cost more than 1–2% interest differences. Credit-life can be optional; if compulsory, compare premiums. Check early-settlement rules—many lenders allow it, but terms differ.
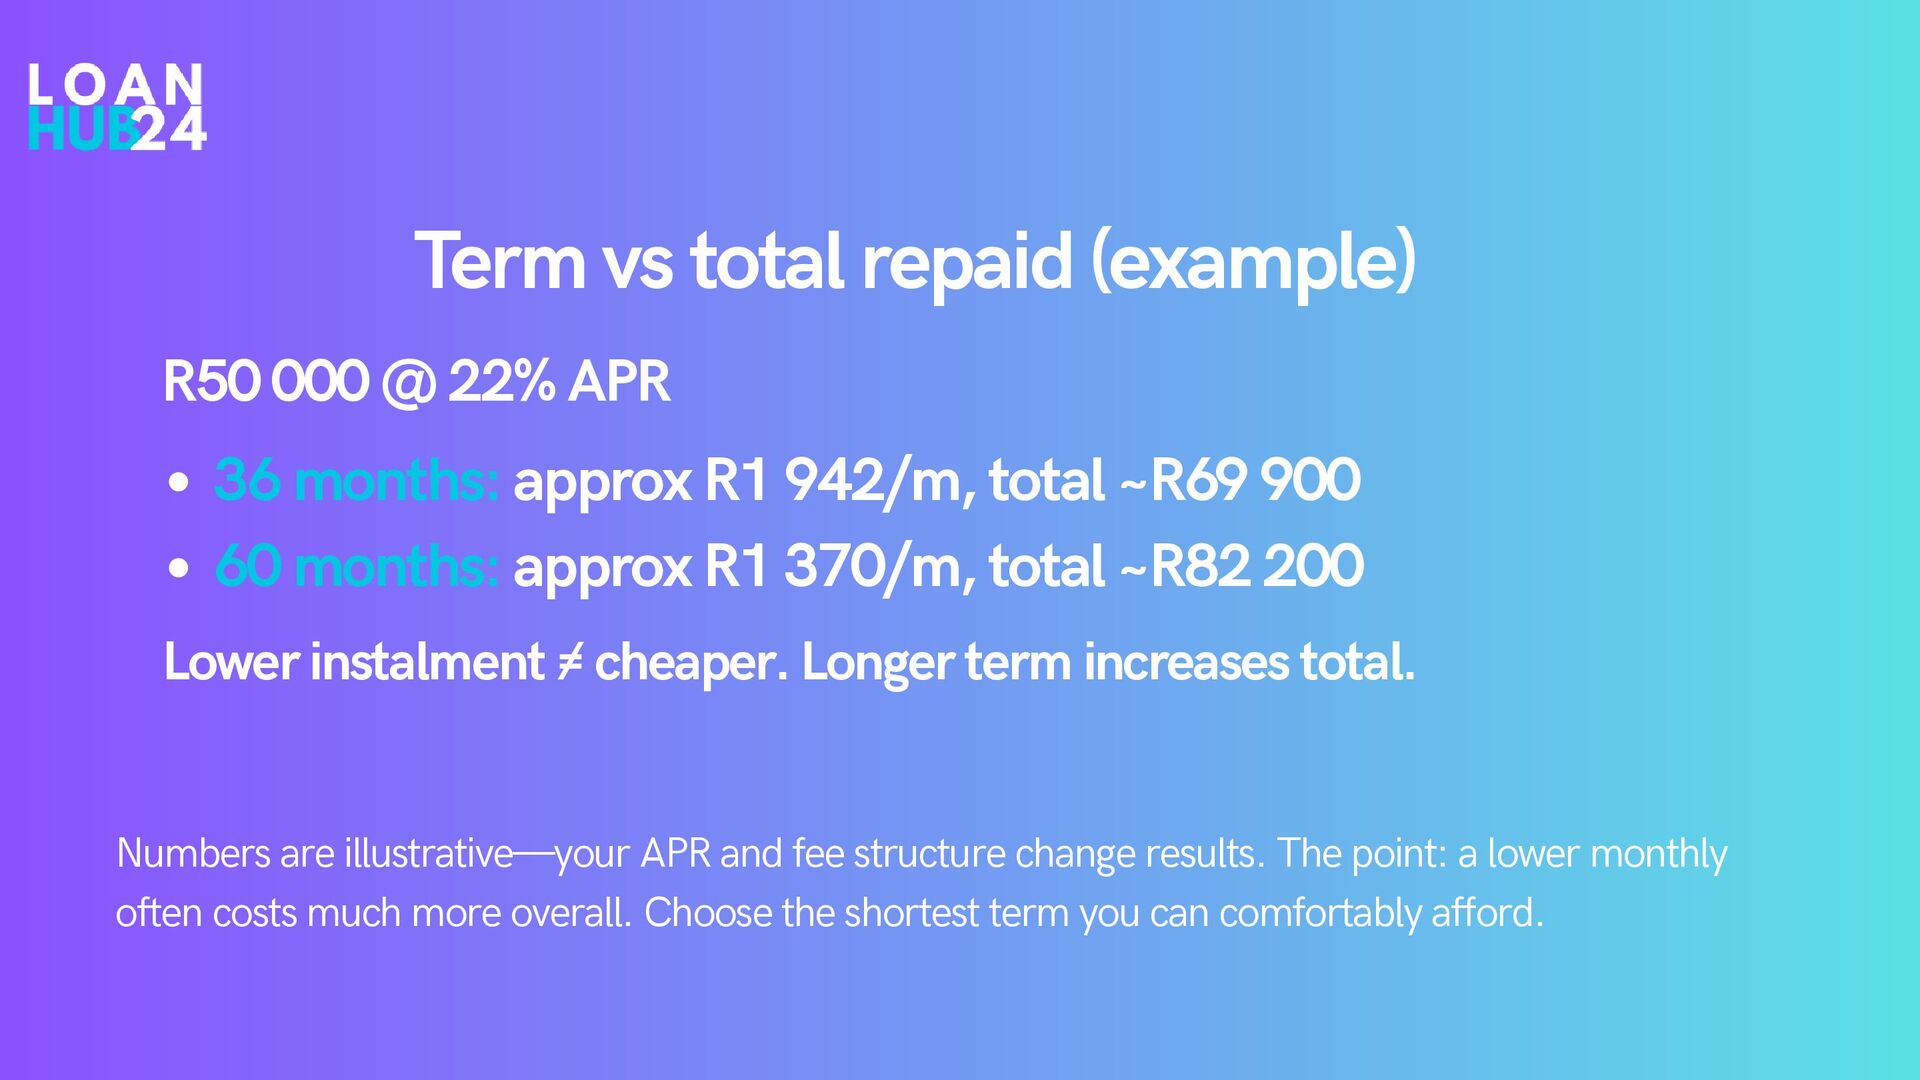
  5. Term vs total repaid (example) 36 months: approx R1 942/m,

    total ~R69 900 60 months: approx R1 370/m, total ~R82 200 Numbers are illustrative—your APR and fee structure change results. The point: a lower monthly often costs much more overall. Choose the shortest term you can comfortably afford. Lower instalment ≠ cheaper. Longer term increases total. R50 000 @ 22% APR
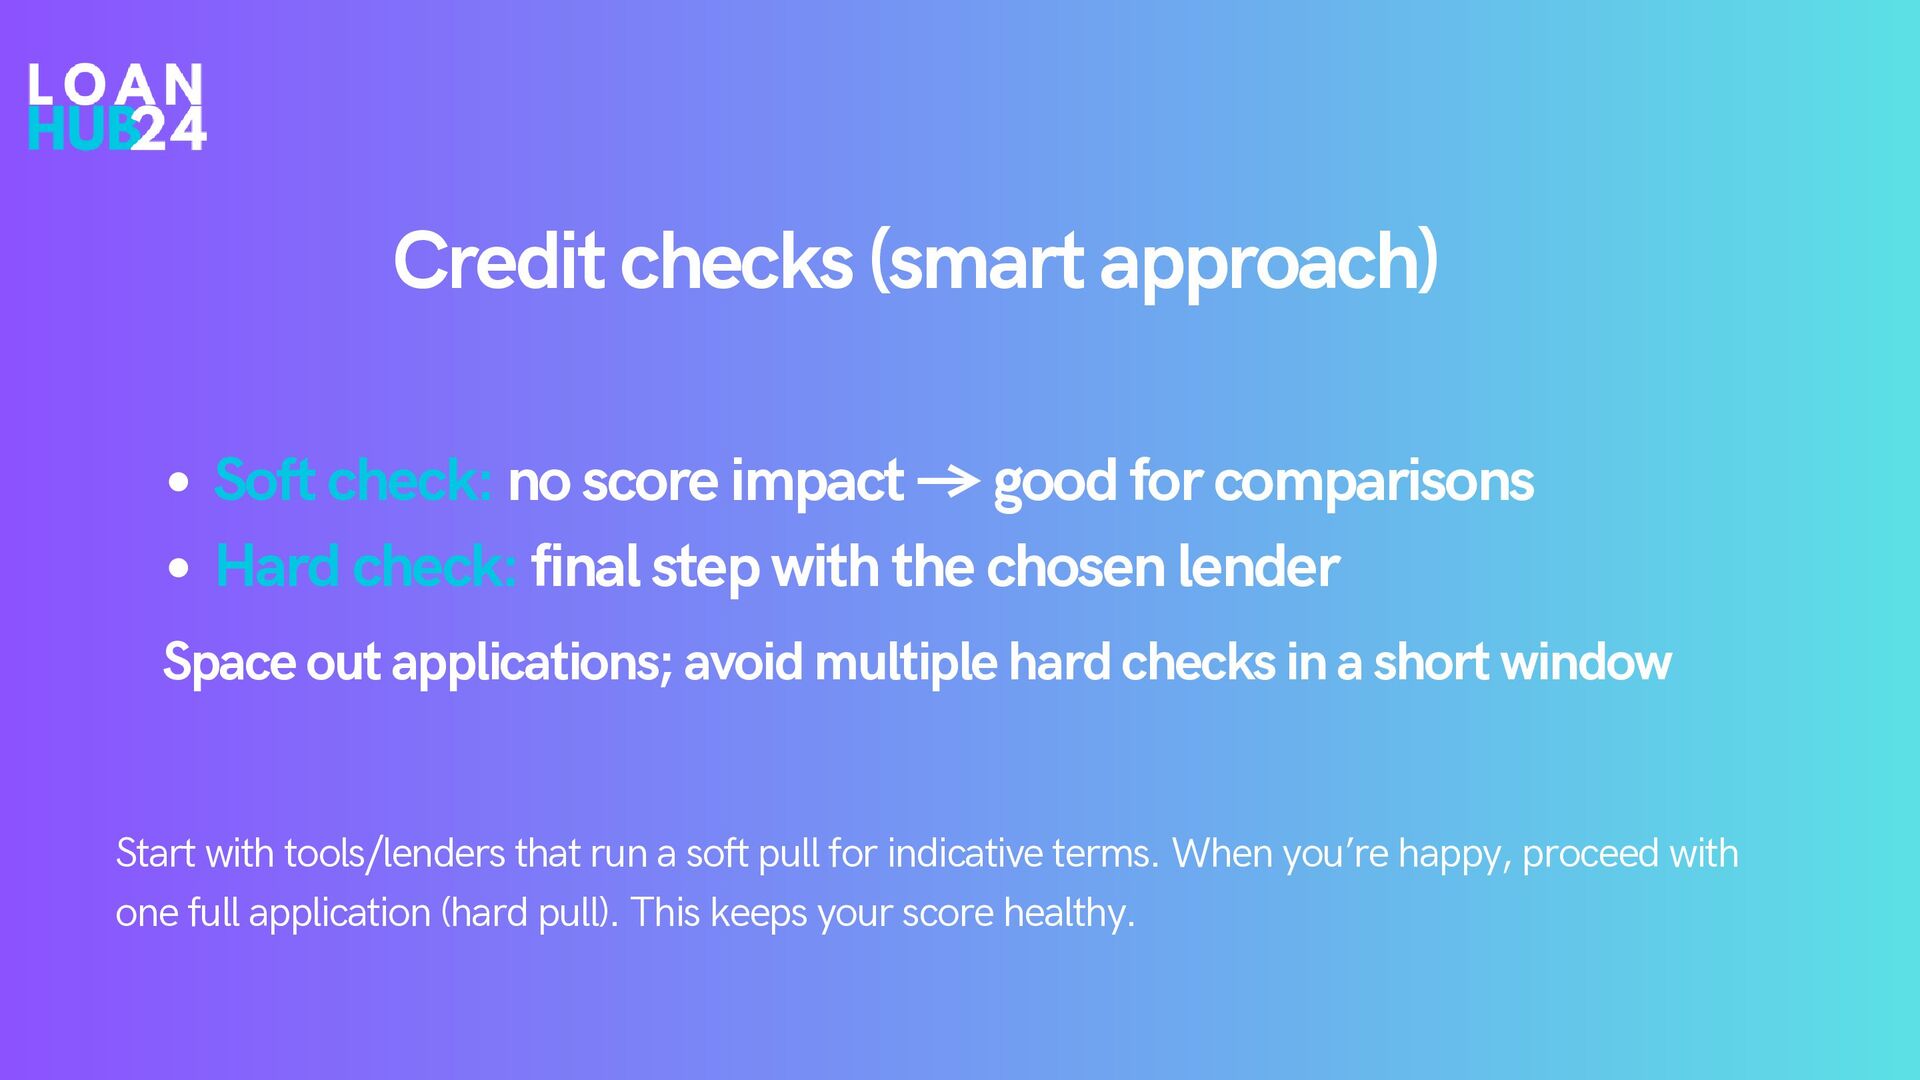
  6. Credit checks (smart approach) Soft check: no score impact →

    good for comparisons Hard check: final step with the chosen lender Start with tools/lenders that run a soft pull for indicative terms. When you’re happy, proceed with one full application (hard pull). This keeps your score healthy. Space out applications; avoid multiple hard checks in a short window
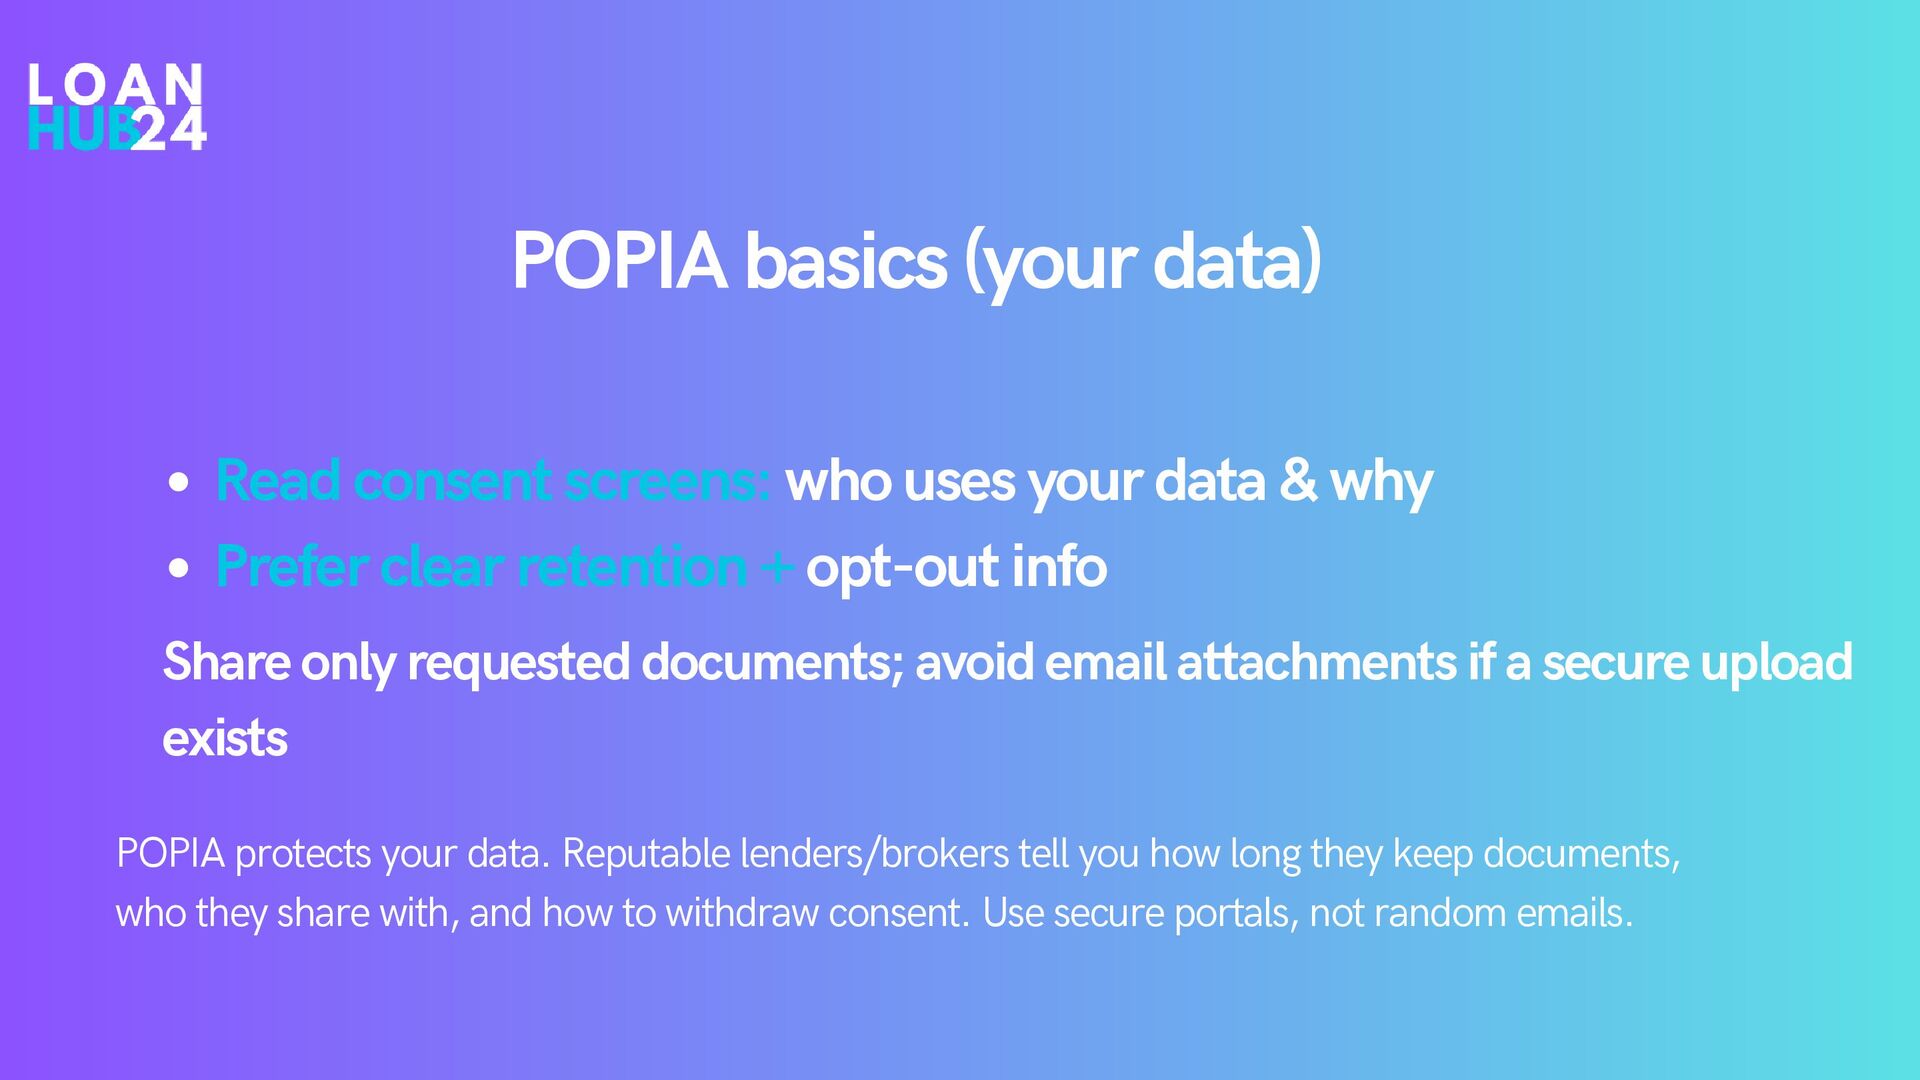
  7. POPIA basics (your data) Read consent screens: who uses your

    data & why Prefer clear retention + opt-out info POPIA protects your data. Reputable lenders/brokers tell you how long they keep documents, who they share with, and how to withdraw consent. Use secure portals, not random emails. Share only requested documents; avoid email attachments if a secure upload exists
  8. Quick red flags “Guaranteed approval” for everyone No APR /

    fee breakdown Pressure to pay upfront fees to unlock a loan Vague contacts, no SA company info Legit lenders show APR/fees clearly and don’t charge upfront to “release” funds. Walk away from urgency tactics or poor transparency.
  9. Your next step Free checklist + calculator tips https://loanhub24.co.za/ Compare

    once, choose confidently. Use the checklist to line up offers side-by-side. If two look close, pick the lower APR and the shortest affordable term. Then do one full application.