of tax agreement – The mechanism under Tennessee law to lower real and personal property taxes • There is no standard PILOT arrangement • Communities take different approaches, but most consider – Number of jobs – Wages – Investment
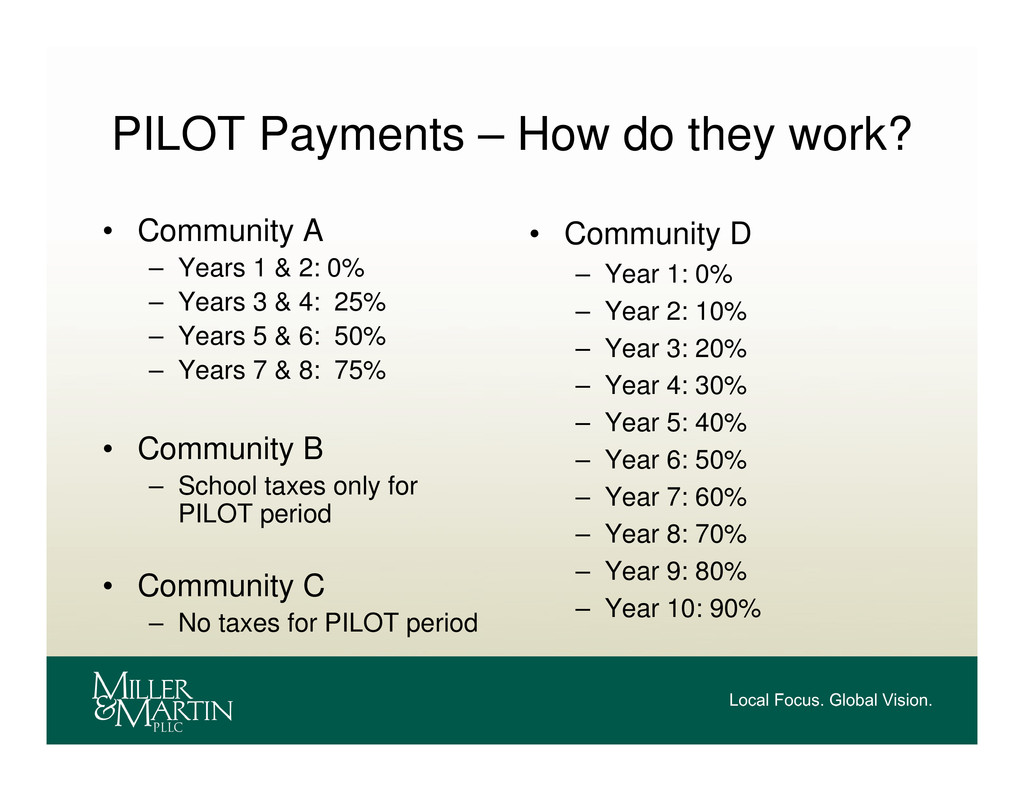
– Years 1 & 2: 0% – Years 3 & 4: 25% – Years 5 & 6: 50% – Years 7 & 8: 75% • Community B – School taxes only for PILOT period • Community C – No taxes for PILOT period • Community D – Year 1: 0% – Year 2: 10% – Year 3: 20% – Year 4: 30% – Year 5: 40% – Year 6: 50% – Year 7: 60% – Year 8: 70% – Year 9: 80% – Year 10: 90%
All property must be subject to taxation, with limited constitutional exceptions – This prohibits cities and counties from granting tax abatements directly to private industry – But, the legislature is authorized to exempt governmentally owned property • Industrial Development Boards – Statutory property tax exemption – Broad powers relating to specified “projects” – Authorization to enter into in lieu of tax agreements • Other authority: Housing & education projects
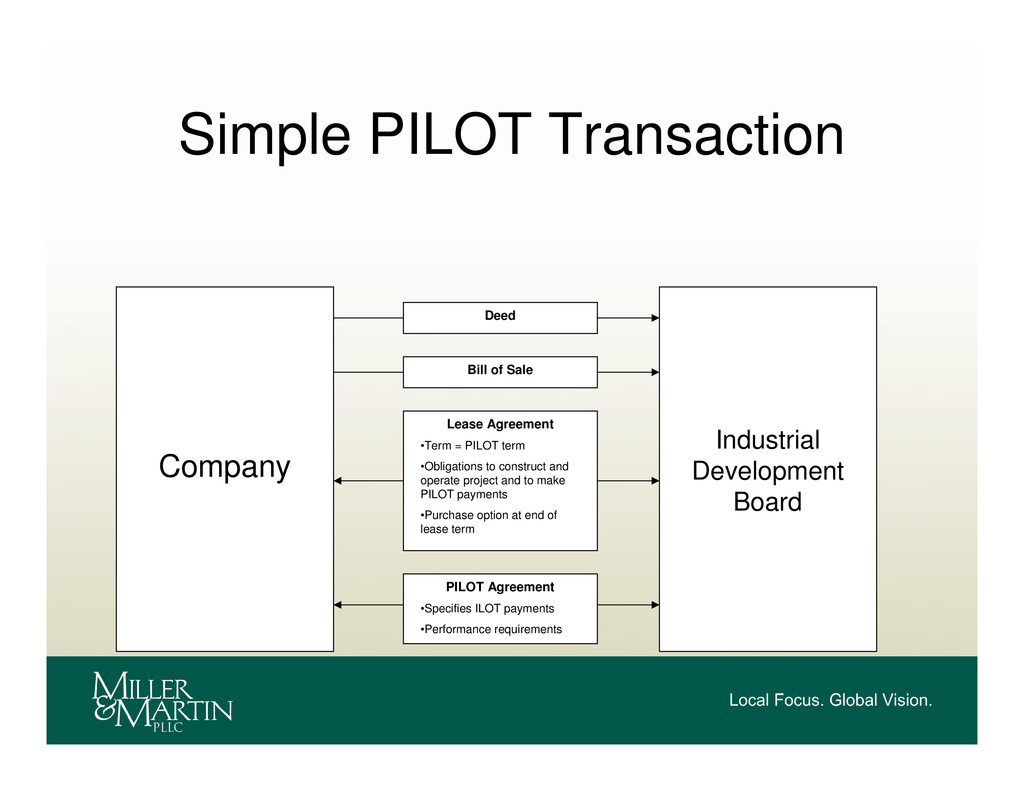
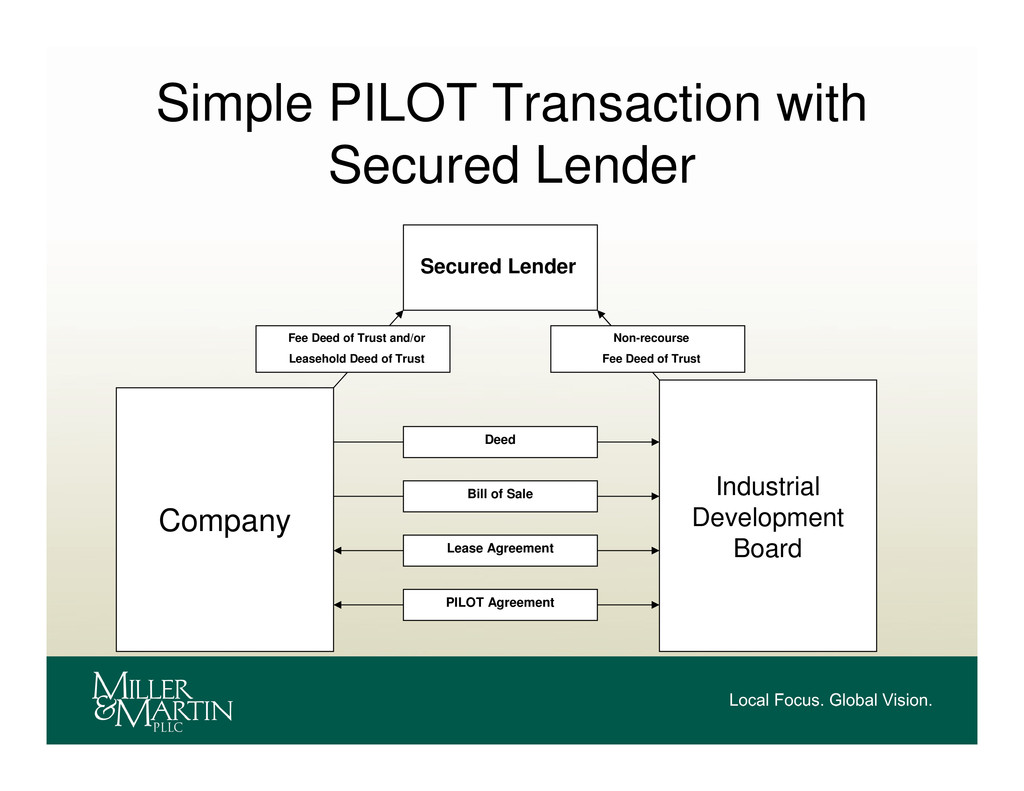
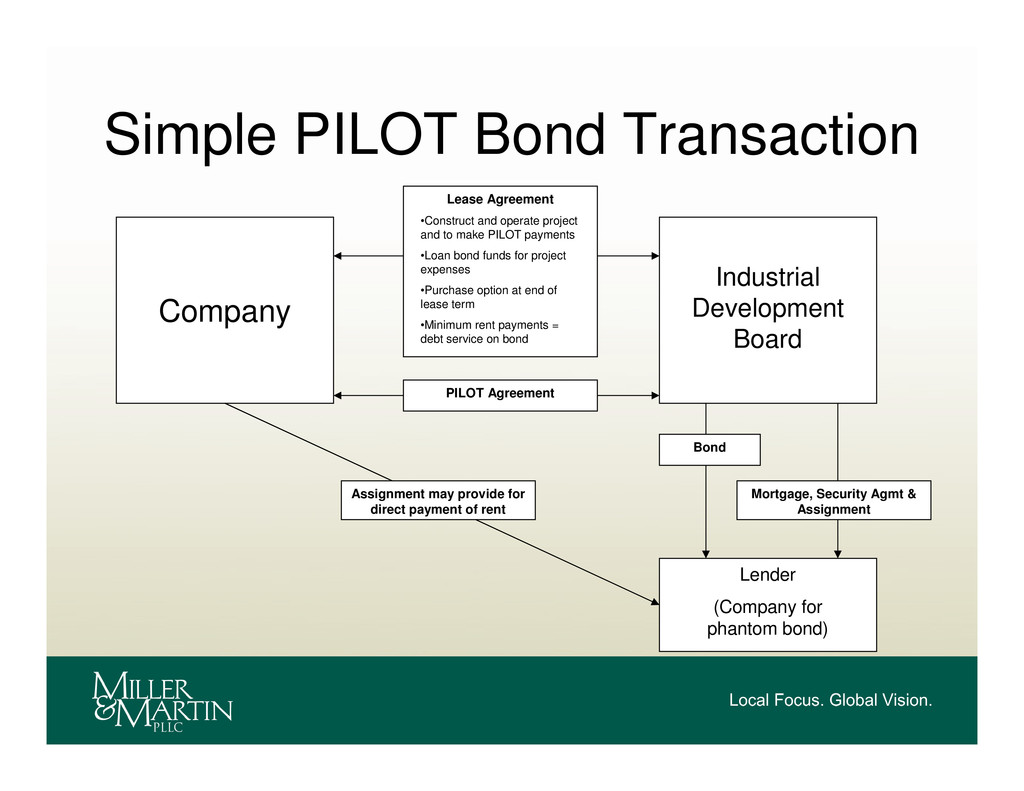
= PILOT term •Obligations to construct and operate project and to make PILOT payments •Purchase option at end of lease term PILOT Agreement •Specifies ILOT payments •Performance requirements Deed Bill of Sale
property are taxable interests in TN • Less of an issue in areas that limit PILOTs to new investment – PILOTs offered for new expansions only – Existing property on tax rolls is not eligible for reduced PILOT (i.e., existing property is effectively taxed at 100%) – Imputed rent from new improvements counts • Manage through re-opener provisions in PILOT agreements? • Manage through bond or “phantom bond” issues
Lender (Company for phantom bond) Lease Agreement •Construct and operate project and to make PILOT payments •Loan bond funds for project expenses •Purchase option at end of lease term •Minimum rent payments = debt service on bond Bond Mortgage, Security Agmt & Assignment Assignment may provide for direct payment of rent
issuance of city or county debt • Designate specific development area and dedicate projected incremental tax revenues toward payment of IDB debt for infrastructure improvements within area • Adoption of economic impact plan by city and county after public hearing • Division of property taxes into “base tax amount” and “excess tax amount”
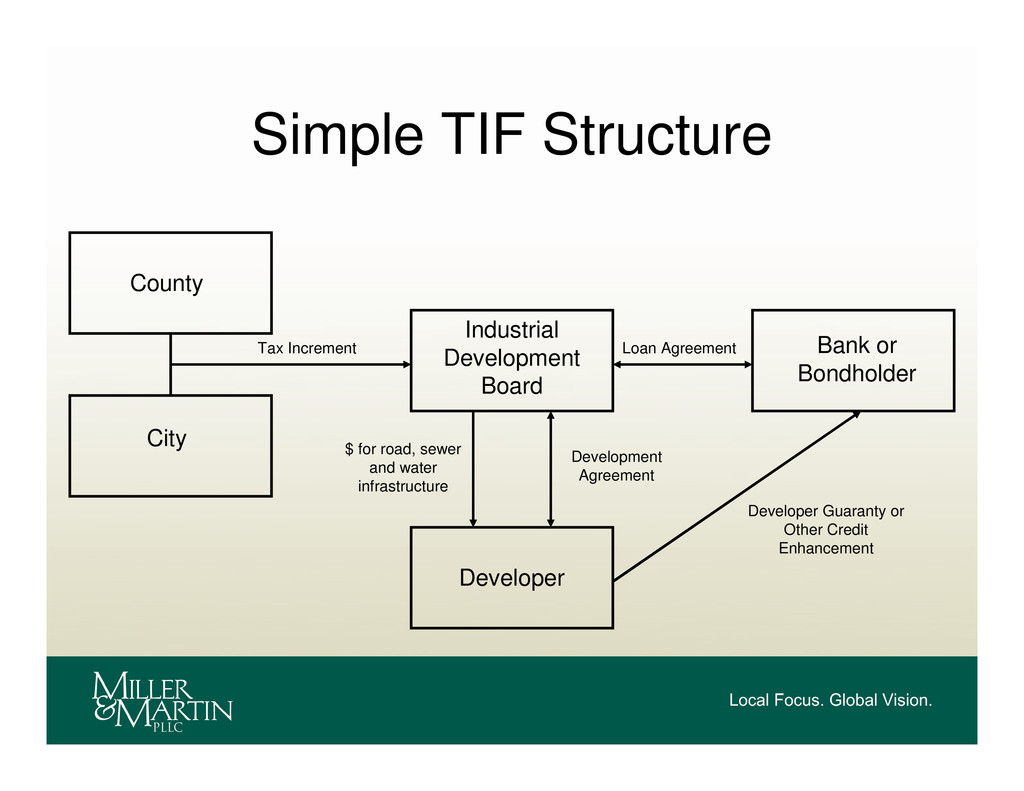
Bank or Bondholder Developer Development Agreement Developer Guaranty or Other Credit Enhancement Loan Agreement $ for road, sewer and water infrastructure
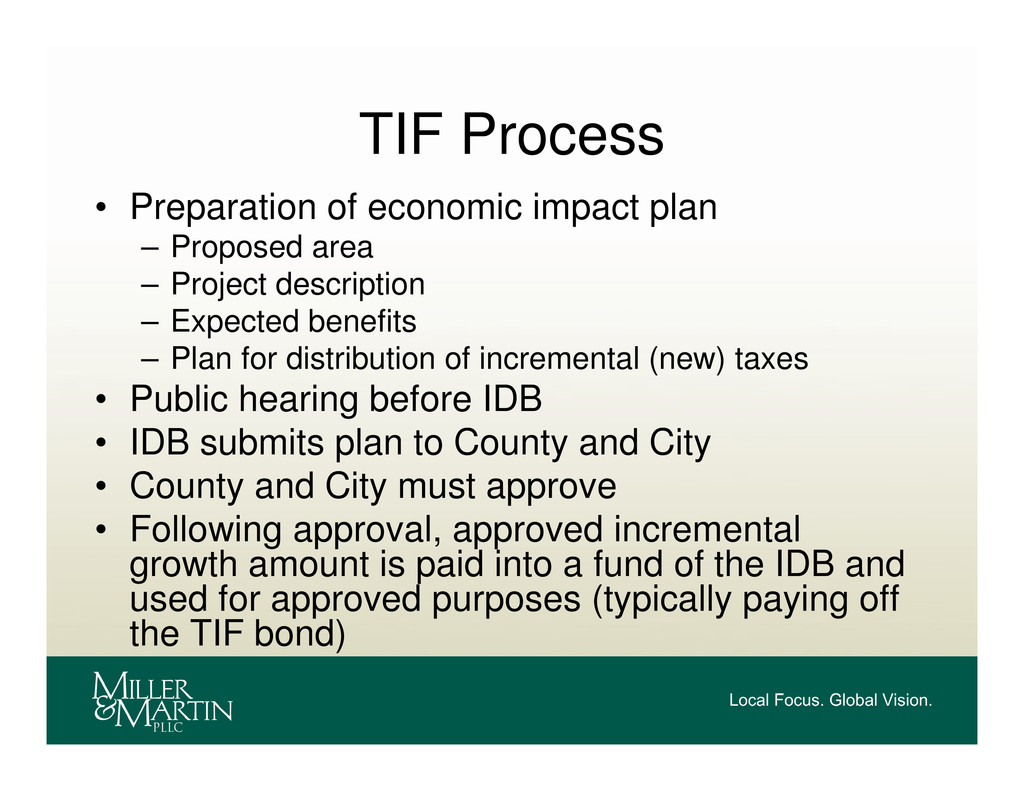
area – Project description – Expected benefits – Plan for distribution of incremental (new) taxes • Public hearing before IDB • IDB submits plan to County and City • County and City must approve • Following approval, approved incremental growth amount is paid into a fund of the IDB and used for approved purposes (typically paying off the TIF bond)
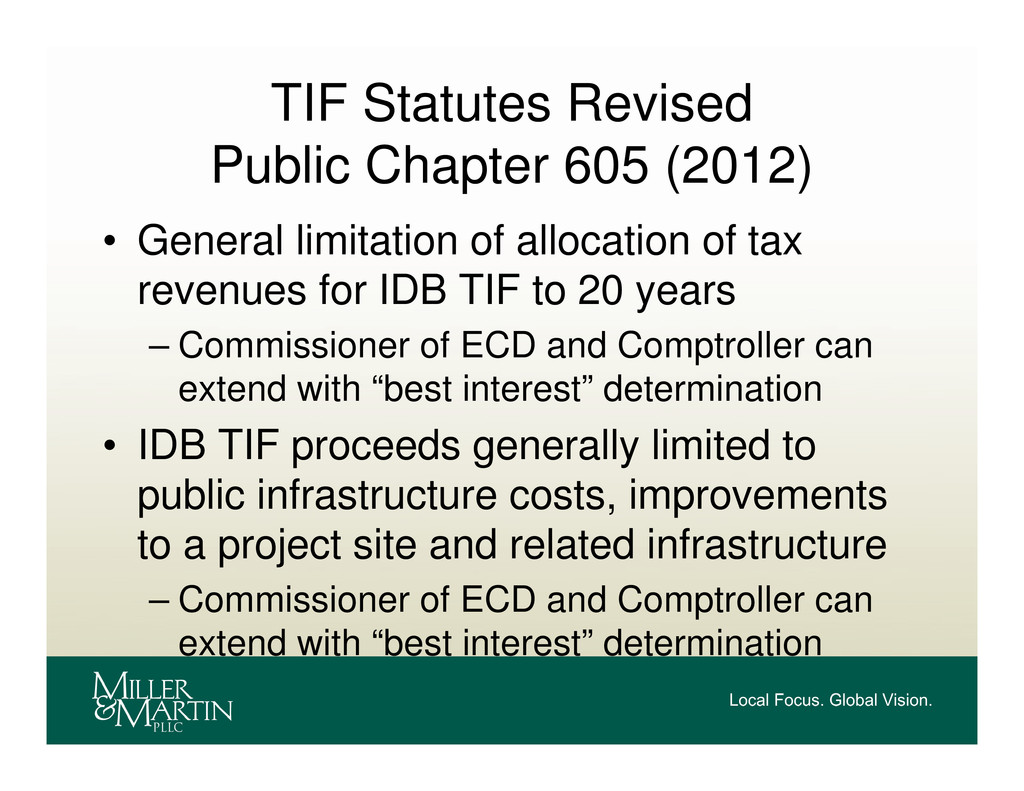
of allocation of tax revenues for IDB TIF to 20 years – Commissioner of ECD and Comptroller can extend with “best interest” determination • IDB TIF proceeds generally limited to public infrastructure costs, improvements to a project site and related infrastructure – Commissioner of ECD and Comptroller can extend with “best interest” determination
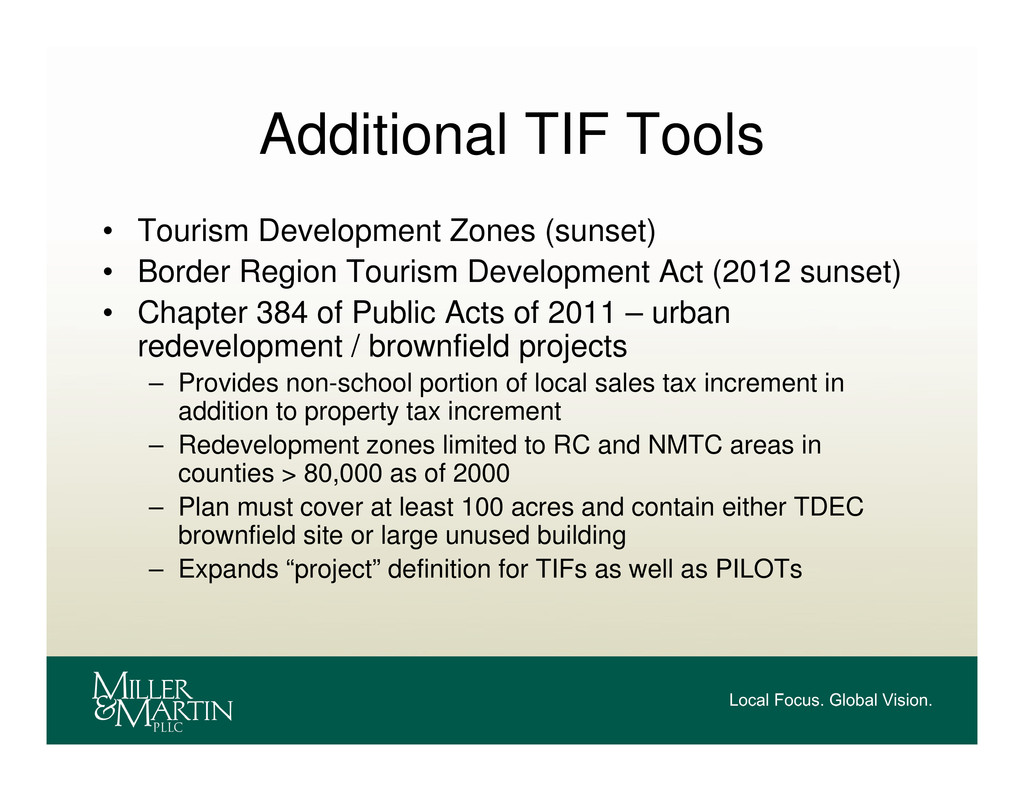
Region Tourism Development Act (2012 sunset) • Chapter 384 of Public Acts of 2011 – urban redevelopment / brownfield projects – Provides non-school portion of local sales tax increment in addition to property tax increment – Redevelopment zones limited to RC and NMTC areas in counties > 80,000 as of 2000 – Plan must cover at least 100 acres and contain either TDEC brownfield site or large unused building – Expands “project” definition for TIFs as well as PILOTs
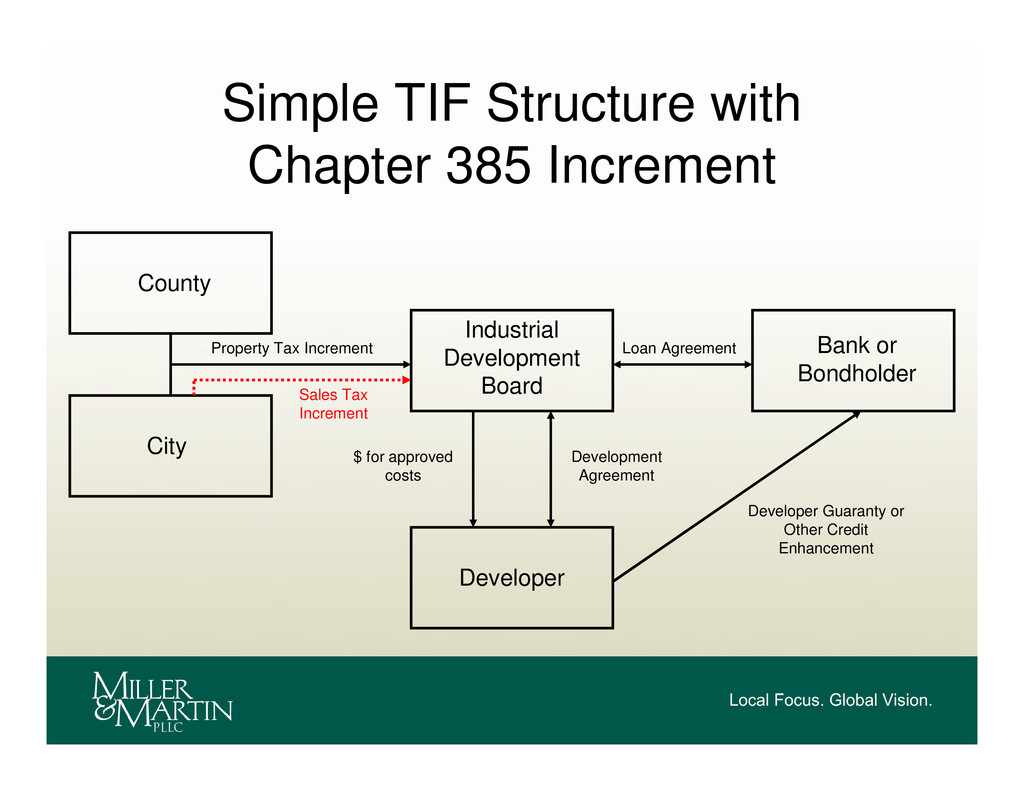
County City Industrial Development Board Bank or Bondholder Developer Development Agreement Developer Guaranty or Other Credit Enhancement Loan Agreement $ for approved costs Sales Tax Increment


 ya1990
 jacobtomlinson
 techseoconnect
 khoart
 inesmontani
 tonyrice
 katarinadahlin
 destraynor
 afnizarnur
 bkeepers
 chriscoyier
 nonsquared
 codingconduct