Real properties Increasing Cash Flow with Cost Segregation Studies & Energy Policy Act Of 2005 This document and/or electronic file contains information that (a) is or may be LEGALLY PRIVILEGED, CONFIDENTIAL, PROPRIETARY IN NATURE, OR OTHERWISE PROTECTED BY LAW FROM DISCLOSURE, and (b) is intended only for the use of CORE. Solutions Group LLC. You must have written authorization from CORE to use, copy or distribute any part of this document as it’s strictly prohibited.
= to identify all construction-related costs that can be depreciated over 5, 7 and 15 years and reclassified from 39, 31.5 and 27.5 years • Traditional depreciation for Real Property is 39 years for commercial property and 27.5 years for residential rental property • Personal property is depreciated much quicker and can be depreciated over 5, 7, 10, and 15 years • Reducing tax lives results in accelerated depreciation deductions, a reduced tax liability, and increased cash flow Would you Rather Get Your Money Back Today or in 39 Years? “You must pay taxes. But there's no law that says you gotta leave a tip.”
Generates Cash Flow and Minimizes Taxes • Look back study for catch-up of depreciation could generate refund • Free up money for future investments or green initiatives • Benefit to clients includes ability to expense versus capitalization of real property when conducting demolition or when remodeling is involved. • Reduces real estate property taxes • Increase Cash Flow for Maximum Bank Financing
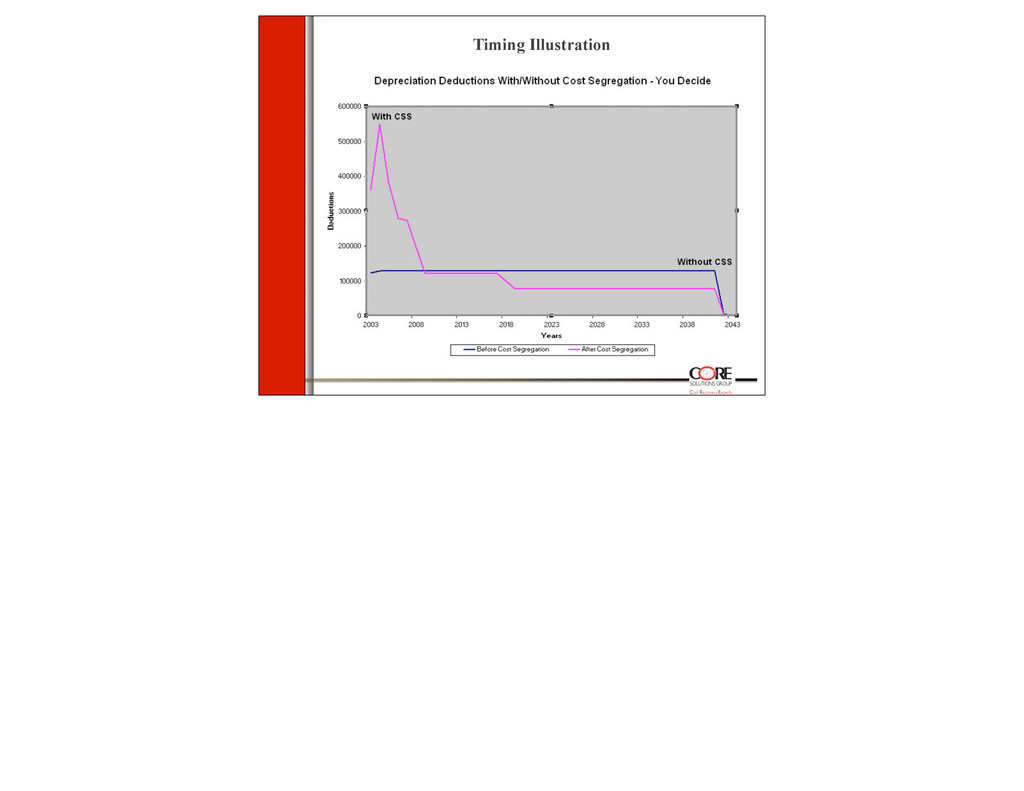
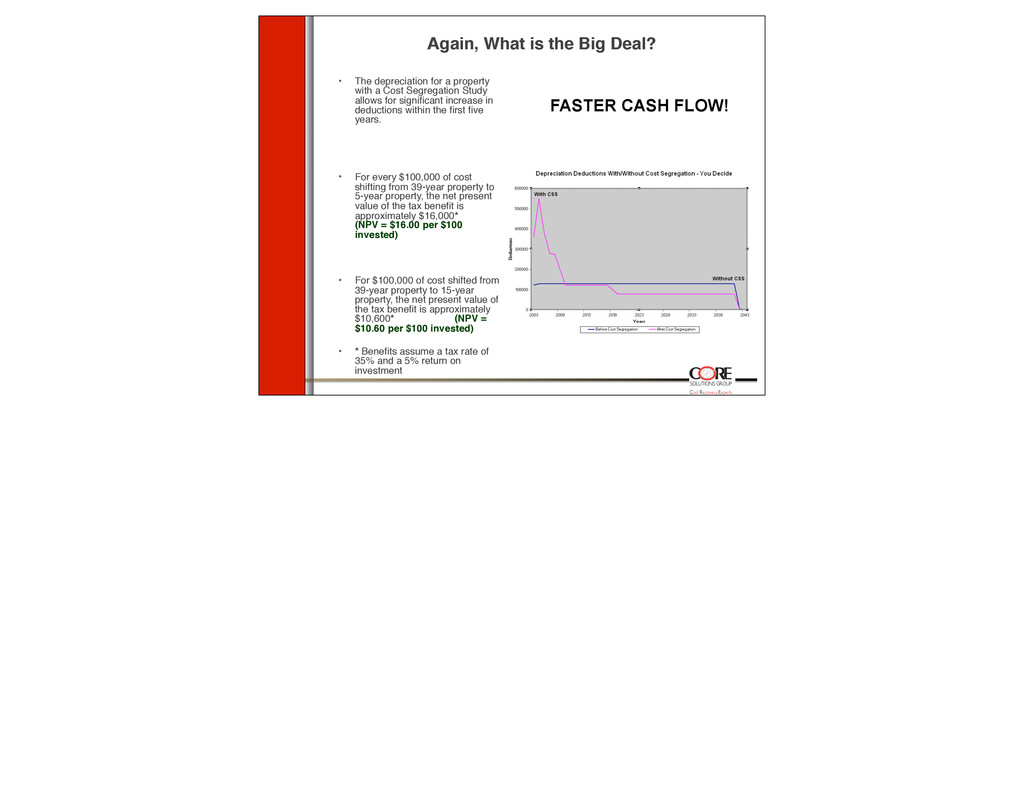
The depreciation for a property with a Cost Segregation Study allows for significant increase in deductions within the first five years. For every $100,000 of cost shifting from 39-year property to 5-year property, the net present value of the tax benefit is approximately $16,000* For $100,000 of cost shifted from 39-year property to 15-year property, the net present value of the tax benefit is approximately$10,600* * Benefits assume a tax rate of 35% and a 5% return on investment
around since the 1960’s – it was called Component Depreciation There have been over 200 court cases and IRS rulings supporting the benefits of CS Initial cases were related to Investment Tax Credit (ITC) and whether items related to a structure could qualify for a credit. Congress enacted ACRS 1981 with new shorter lives 40 year life reduced to 15, 18 & 19 years Simultaneously disallowed component depreciation MACRS enacted in 1986 reiterated disallowance of component depreciation
- 109 TC 21 (1997) Court reinstated and expanded a form of component depreciation Certain costs related to specific ordinary use equipment (building support systems that would otherwise be viewed as structural) qualify to be depreciated over life of underlying asset.
IRS released Legal Memorandum 19921045 in which the IRS agreed not to contest the (HCA) reclassification of building costs into different asset categories that result in shorter depreciation lives This legal memorandum directs agents to verify that an engineering study has been done to identify portions of the building's system not related to the operation and maintenance of the building Without these detailed studies, IRS agents are advised NOT to accept the reclassifications Allocations based on “logical and objective” measures Not based on non-contemporaneous data, or assumptions without supporting records
in April 2004 • Developed to assist Field Examiners • “WHY” are cost segregation studies performed? • “HOW” are they prepared? • “WHAT” to review and look for? • IRS Cost Segregation Audit Techniques Guide – Assist Field Examiners “Why” are CSS performed? “How” they are prepared? “What” to review and look for?
“It is not unusual for engineering consultants to classify 20 to 40 percent of construction as personal property” Audit Technique Guide “Investors find a friend in the IRS” “Cost Segregation Studies fast growing tax strategy” “Property Owners Profit from Change in Tax Law”
service since January 1st, 1987 Existing buildings undergoing renovation, remodeling, restoration, or expansion Major leasehold improvements to any building made after January 1st, 1987 Inheritance of commercial and investment real properties Preconstruction planning to recommend possible modification to the building designs to increase shorter-life asset classification
Up” – Look Back • If a cost segregation study is conducted on an existing building, The unclaimed depreciation on personal property components that were previously classified as real property can be deducted as a Code Sec. 481 (a) adjustment in the year of change The automatic change of accounting rules of Rev. Proc. 2002-9, apply • If a cost segregation study is performed on a building that was placed in service in a tax year that ended before December 30, 2003, The IRS will allow a tax payer to file amended returns to claim the benefits Interest is payable by the IRS on the refund New: Under the American Recovery and Reinvestment Act of 2009 Get cash back if you have NOL’S in 2008 and 2009. CARRY BACK TO 2003,2004,2005, 2006, 2007!
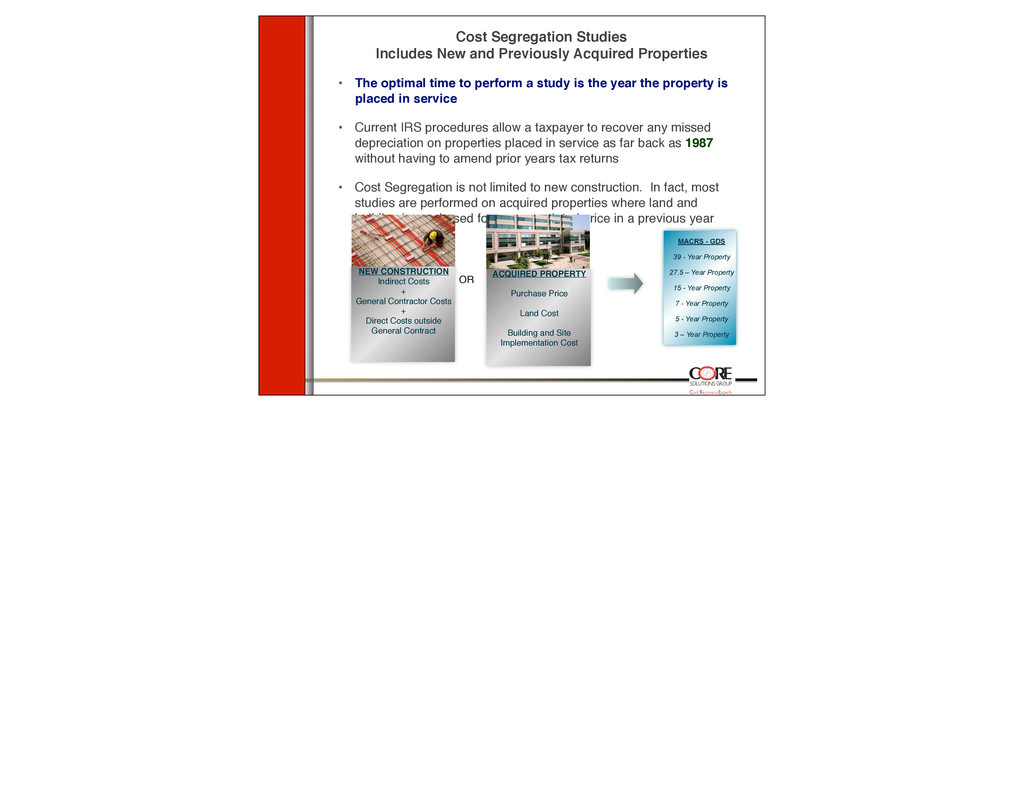
Acquired Properties • The optimal time to perform a study is the year the property is placed in service • Current IRS procedures allow a taxpayer to recover any missed depreciation on properties placed in service as far back as 1987 without having to amend prior years tax returns • Cost Segregation is not limited to new construction. In fact, most studies are performed on acquired properties where land and building is purchased for one negotiated price in a previous year OR MACRS - GDS 39 - Year Property 27.5 – Year Property 15 - Year Property 7 - Year Property 5 - Year Property 3 – Year Property NEW CONSTRUCTION Indirect Costs + General Contractor Costs + Direct Costs outside General Contract ACQUIRED PROPERTY Purchase Price Land Cost Building and Site Implementation Cost
– Would You Take the Cash Savings Today? CSS Illustration No. 1 • A taxpayer purchases (or constructs) a strip mall for $4 million (land excluded) • Without a Cost Segregation Study, the taxpayer would have depreciated $4,000,000 as a 39-year asset over 40 years (straight-line, HY convention)
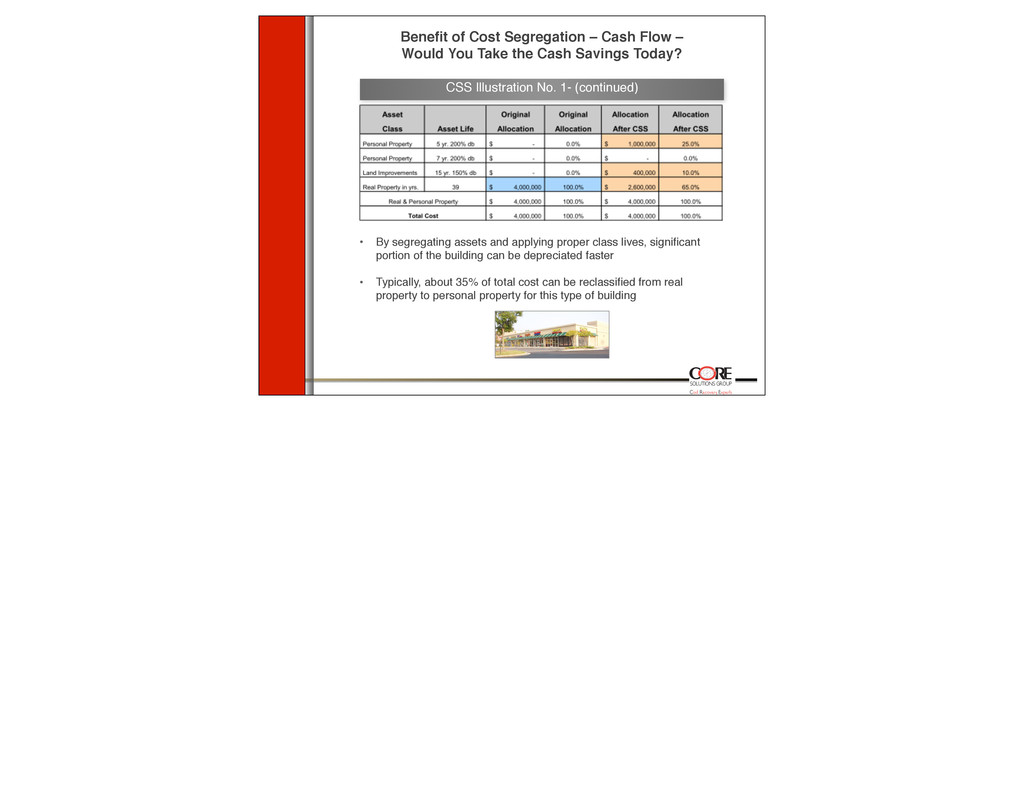
– Would You Take the Cash Savings Today? • By segregating assets and applying proper class lives, significant portion of the building can be depreciated faster • Typically, about 35% of total cost can be reclassified from real property to personal property for this type of building CSS Illustration No. 1- (continued)
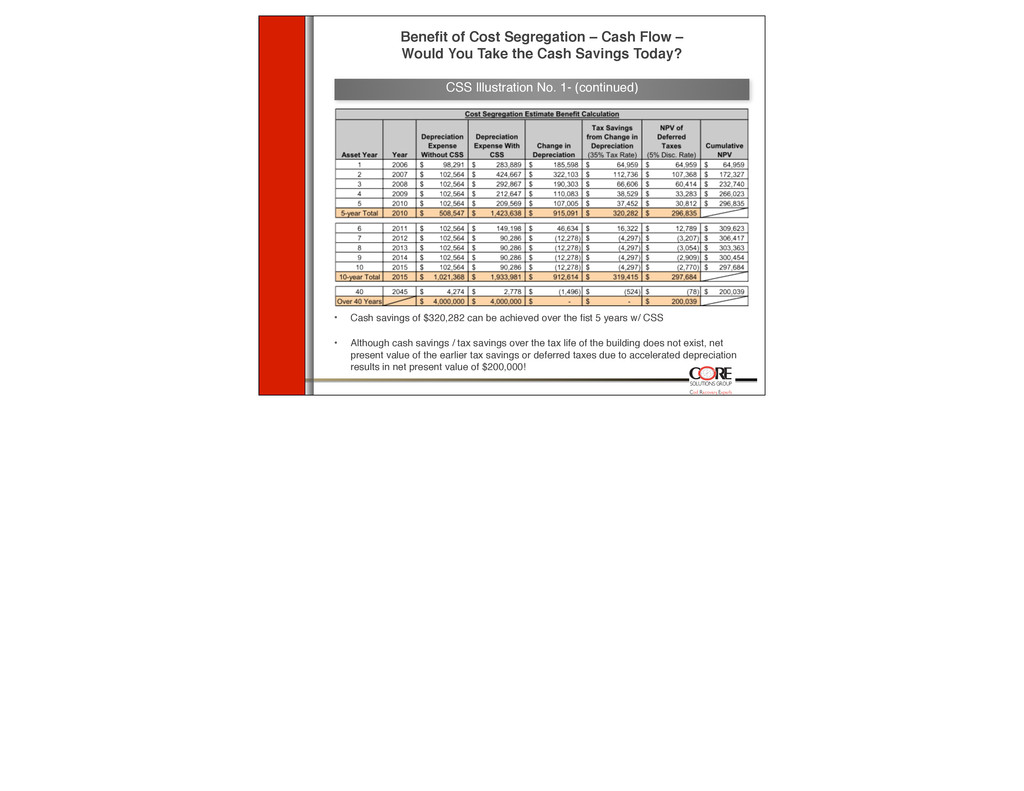
– Would You Take the Cash Savings Today? • Cash savings of $320,282 can be achieved over the fist 5 years w/ CSS • Although cash savings / tax savings over the tax life of the building does not exist, net present value of the earlier tax savings or deferred taxes due to accelerated depreciation results in net present value of $200,000! CSS Illustration No. 1- (continued)
The depreciation for a property with a Cost Segregation Study allows for significant increase in deductions within the first five years. • For every $100,000 of cost shifting from 39-year property to 5-year property, the net present value of the tax benefit is approximately $16,000* (NPV = $16.00 per $100 invested) • For $100,000 of cost shifted from 39-year property to 15-year property, the net present value of the tax benefit is approximately $10,600* (NPV = $10.60 per $100 invested) • * Benefits assume a tax rate of 35% and a 5% return on investment FASTER CASH FLOW!
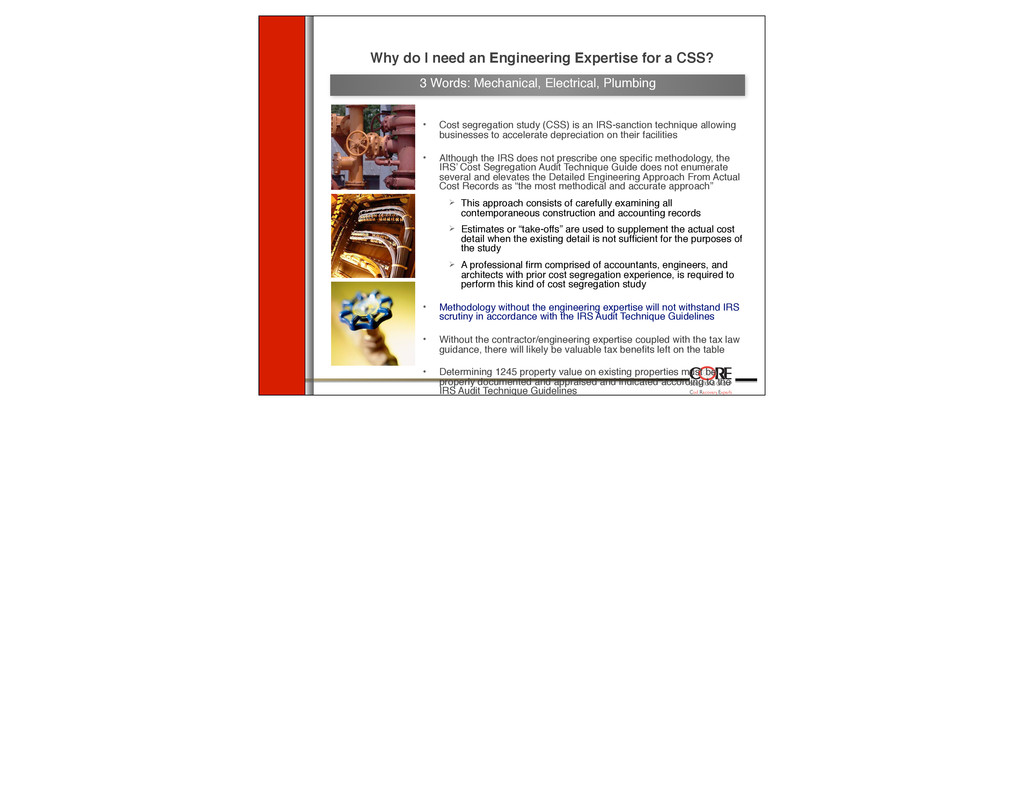
for a CSS? • Cost segregation study (CSS) is an IRS-sanction technique allowing businesses to accelerate depreciation on their facilities • Although the IRS does not prescribe one specific methodology, the IRS’ Cost Segregation Audit Technique Guide does not enumerate several and elevates the Detailed Engineering Approach From Actual Cost Records as “the most methodical and accurate approach” This approach consists of carefully examining all contemporaneous construction and accounting records Estimates or “take-offs” are used to supplement the actual cost detail when the existing detail is not sufficient for the purposes of the study A professional firm comprised of accountants, engineers, and architects with prior cost segregation experience, is required to perform this kind of cost segregation study • Methodology without the engineering expertise will not withstand IRS scrutiny in accordance with the IRS Audit Technique Guidelines • Without the contractor/engineering expertise coupled with the tax law guidance, there will likely be valuable tax benefits left on the table • Determining 1245 property value on existing properties must be properly documented and appraised and indicated according to the IRS Audit Technique Guidelines 3 Words: Mechanical, Electrical, Plumbing
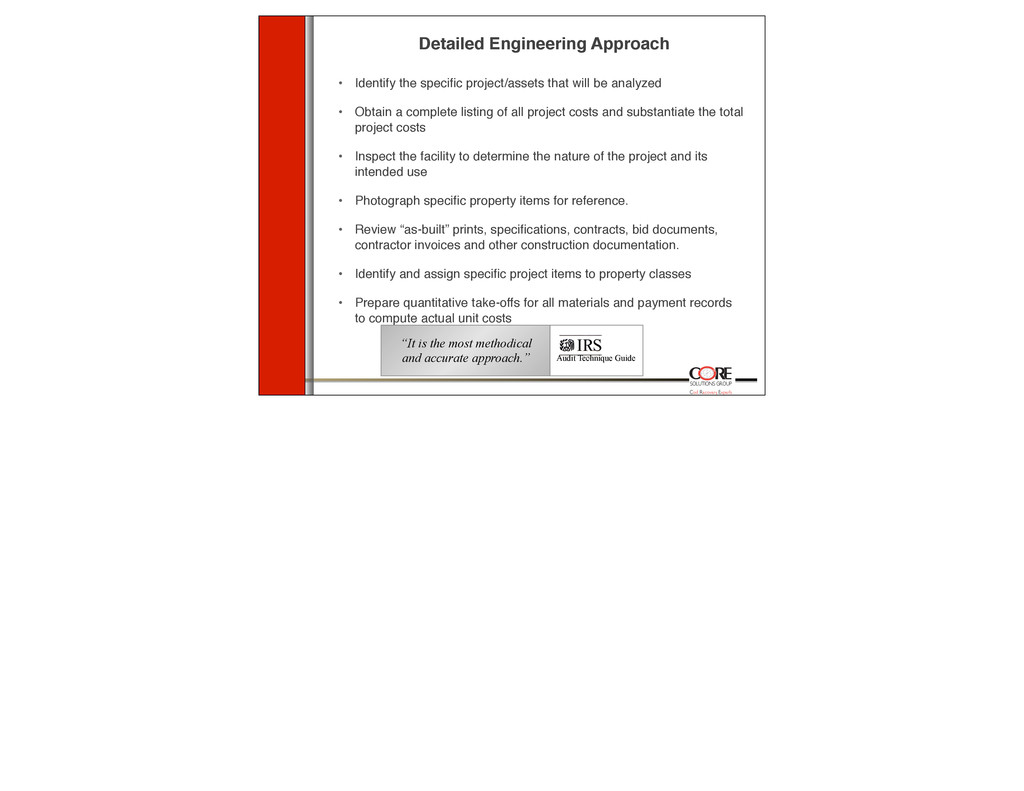
project/assets that will be analyzed • Obtain a complete listing of all project costs and substantiate the total project costs • Inspect the facility to determine the nature of the project and its intended use • Photograph specific property items for reference. • Review “as-built” prints, specifications, contracts, bid documents, contractor invoices and other construction documentation. • Identify and assign specific project items to property classes • Prepare quantitative take-offs for all materials and payment records to compute actual unit costs Audit Technique Guide “It is the most methodical and accurate approach.”
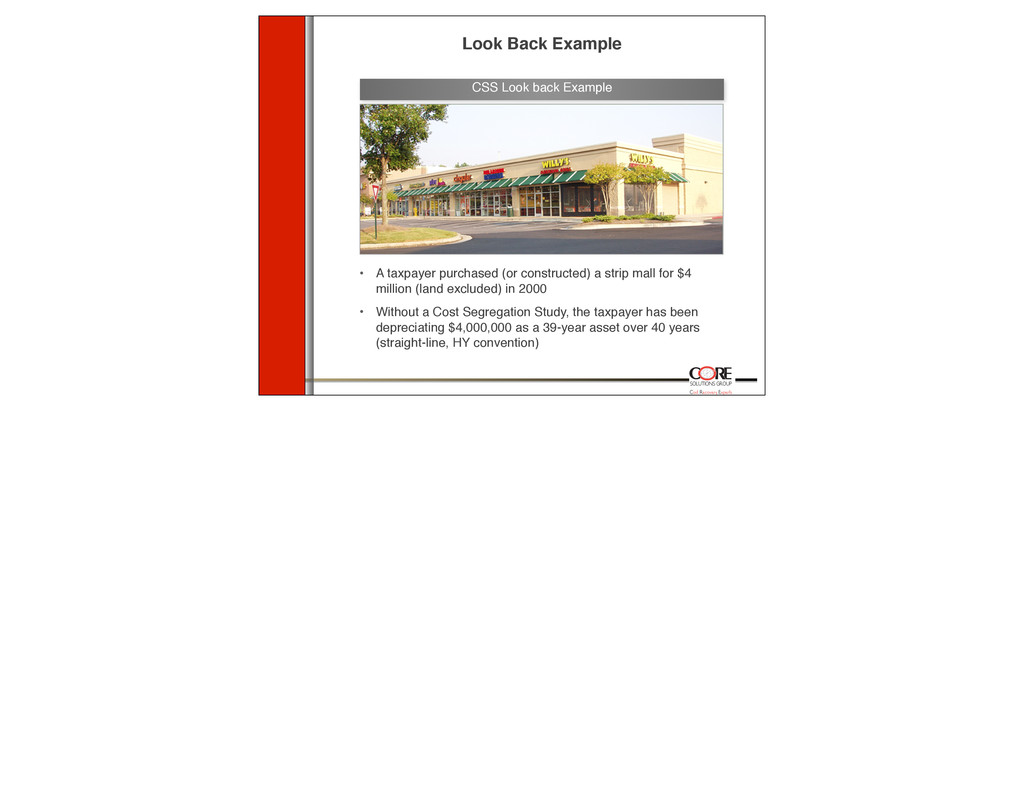
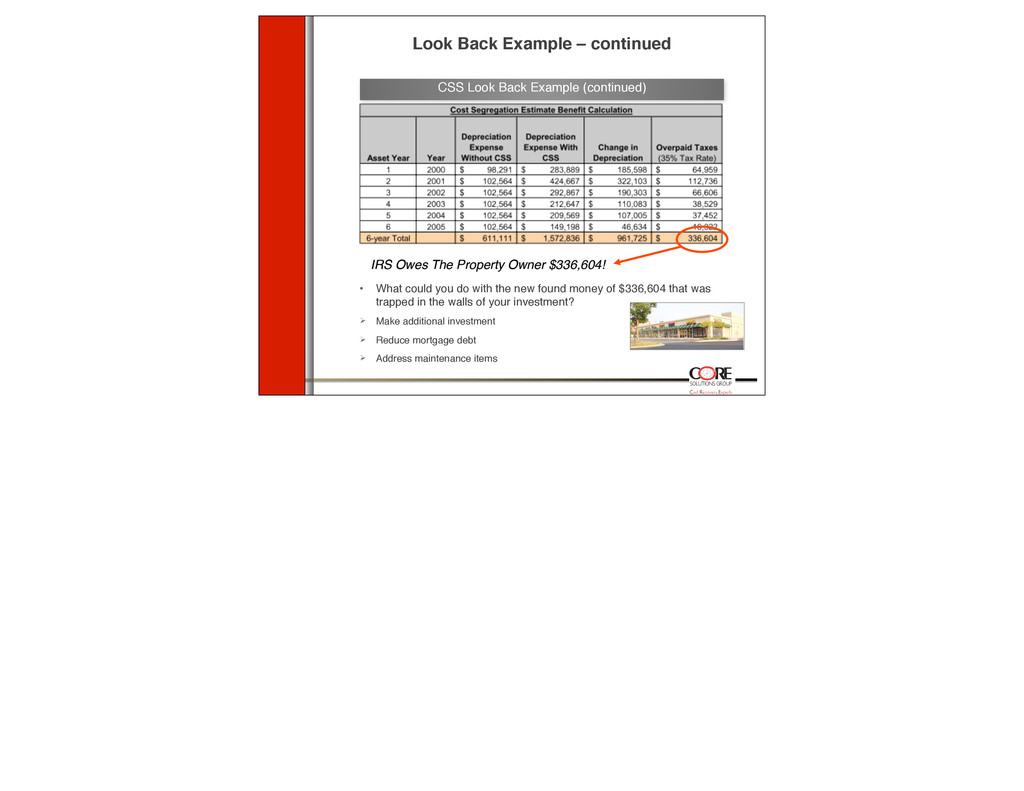
• A taxpayer purchased (or constructed) a strip mall for $4 million (land excluded) in 2000 • Without a Cost Segregation Study, the taxpayer has been depreciating $4,000,000 as a 39-year asset over 40 years (straight-line, HY convention)
could you do with the new found money of $336,604 that was trapped in the walls of your investment? Make additional investment Reduce mortgage debt Address maintenance items CSS Look Back Example (continued) IRS Owes The Property Owner $336,604!
In the design phase, CORE can help make the building more tax efficient by identifying business components from the structural components • Example: Law Firm uses hinges for $1MM decorative lobby shelving versus attaching shelving with a permanent adhesive Total property is able to be moved from 39-year depreciation to 5-year depreciation for a tremendous savings • Example: Hospital installs $1.8MM floating floor system versus permanent attached flooring Structurally as sound, cash savings from more attractive depreciation schedule substantial
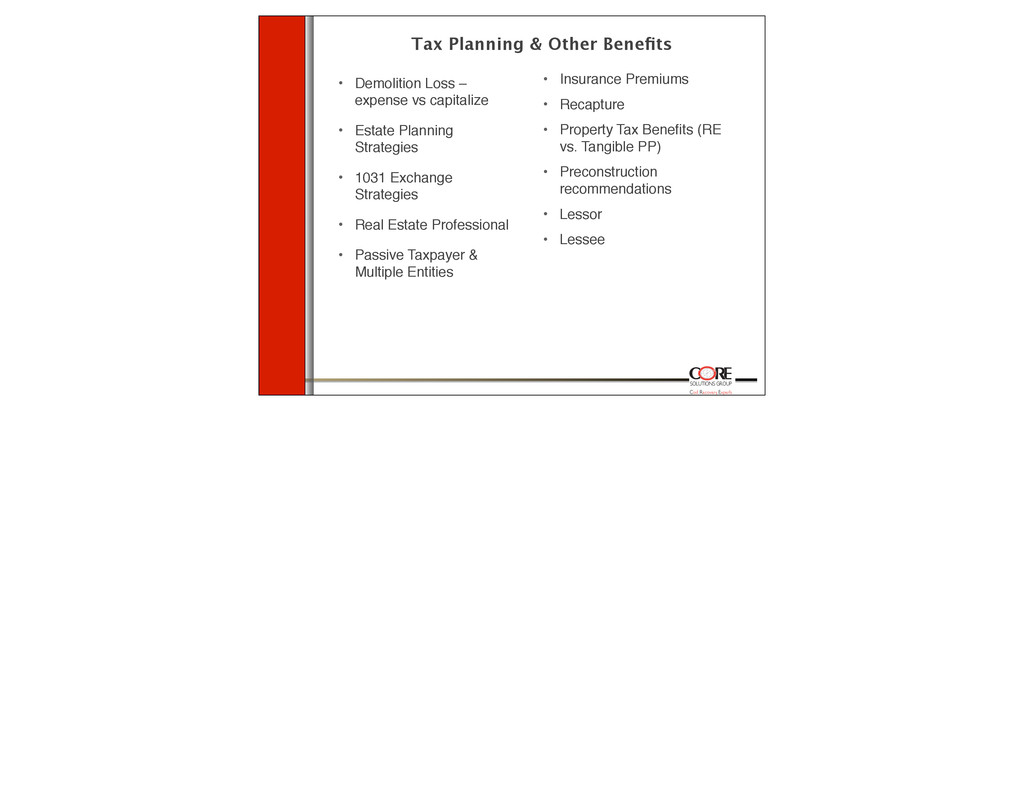
Segregation Study • There are a number of benefits to your insurance program after completing a Cost Segregation study: Lower premiums. By providing the insurance underwriter with a Cost Segregation study, they can better understand your risk, their company’s exposure and accurately rate your insurance – There is no more guess work on the underwriters behalf and that guess work usually works in their favor in the way of higher premiums to you In the wake of the recent natural disasters affecting the insurance market, most insurance policies are changing from blanket policies to stated value – Each location will carry a stated value on the policy and in the event of a claim that is the maximum you can collect – A Cost Segregation study will provide you with the piece of mind that you are insured to full value – Cost segregation studies allow property owners to accurately insure their business property, leading to a more cost effective use of your insurance dollar
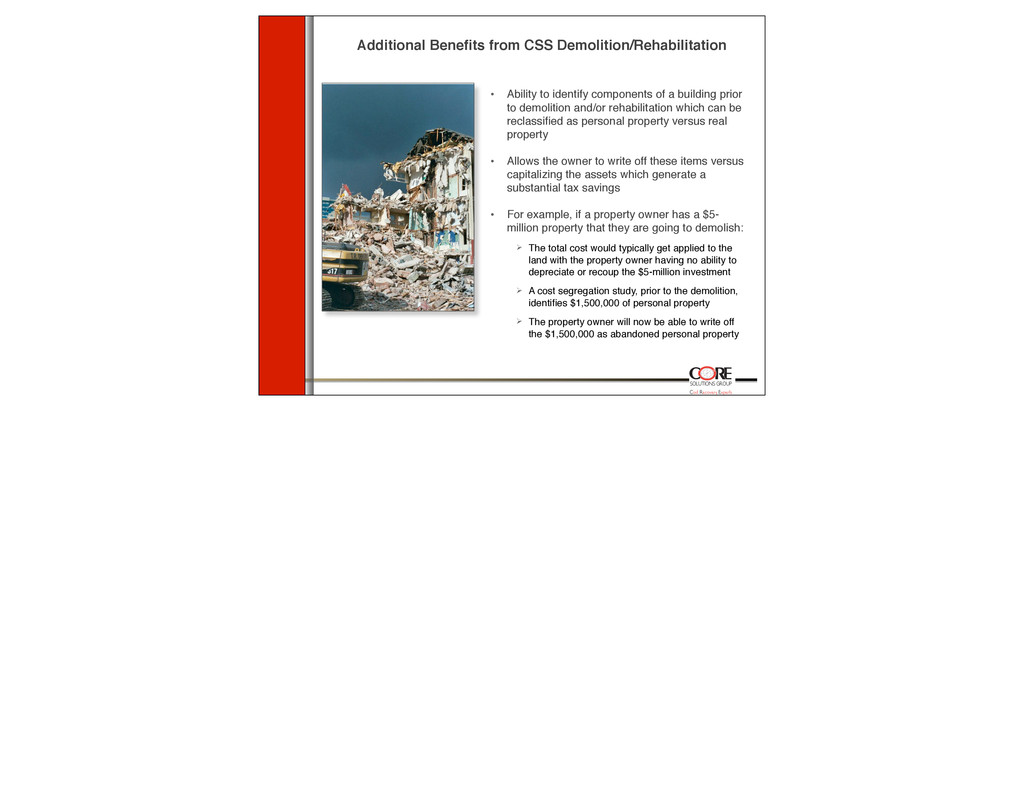
to identify components of a building prior to demolition and/or rehabilitation which can be reclassified as personal property versus real property • Allows the owner to write off these items versus capitalizing the assets which generate a substantial tax savings • For example, if a property owner has a $5- million property that they are going to demolish: The total cost would typically get applied to the land with the property owner having no ability to depreciate or recoup the $5-million investment A cost segregation study, prior to the demolition, identifies $1,500,000 of personal property The property owner will now be able to write off the $1,500,000 as abandoned personal property
Increase non-cash expense to reduce income and thus minimize dividend distribution, allowing increased cash flow for additional acquisitions • REIT dividends have 3 components: Ordinary Dividends Long-Term Capital Gains Dividends Return of Capital Dividends • Due to the favorable tax treatment of Return of Capital Dividends (taxed at the long-term capital gains rate of 15% or 25% and tax payment is deferred until the sale of the share), investors typically prefer dividends with the greatest percentage of Return of Capital • Cost Segregation increases the Return of Capital component; thereby, increasing the Taxable Equivalent Yield • DIVIDEND GROWTH IS INCREASED A significant source of dividend growth is acquisitions – REIT must pay out a minimum of 90% of taxable income as dividends, and many REITs pay out over 100% of taxable income.
constructs assets associated with those of a modern green he/she is afforded the opportunity to place the assets in service and depreciate the basis over the life of the asset The taxpayer can maximize its depreciable benefits through the implementation of a Cost Segregation report! • On November 29, 2001 the IRS issued Rev. Rul. 2001-60, addressing the treatment of certain land preparation costs incurred in the construction of golf course greens. The revenue ruling supersedes Rev. Rul. 55-290 MODERN GREENS DRAIN TILES AND DRAINAGE SYSTEMS IRRIGATION PIPE PUMP STATIONS AND THE PIPING NECESSARY TO DISTRIBUTE THE WATER SUBSURFACE LAYERS CART PATHS EXTERIOR/CART PATH LIGHTING Golf Course Depreciation Optimization Overview Using Cost Segregation Study & Implementation Under Rev. Proc. 99-49
of Both Worlds - • Most valuable tax deferral strategies for real estate are: Cost Segregation (Accelerated depreciation of real estate) 1031 Exchanges (Deferral on the disposition of appreciated property) • How To Best Utilize Both Strategies Real Estate Investors and their advisors must understand issues in utilizing both strategies • Real vs. Personal Property Real and personal property under section 1031 is determined by state law In contrast, the definition of real and personal property for cost segregation studies is determined under federal law Property such as wall coverings, carpeting, special purpose wiring or other installations affixed to the building can be considered real property under state law and like kind for section 1031 purposes, but be considered personal property in cost segregation studies Real estate owners can benefit from both the gain deferral under section 1031 for real estate exchanges and the enhanced cost recovery deductions of cost segregation study
test - Sec. 1.48-1 (c) • Is the property capable of being moved? • Has it been moved? • Is the property designed or constructed to remain permanently in place? • Are there circumstances which tend to show the expected or intended length of affixation - i.e. may or will be moved? • How substantial of a job is removal of the property & how time consuming? • Is it readily movable? • How much damage will the property sustain upon removal? • What is the manner of affixation of the property to the land? Factors that now govern whether property is permanent or can be reclassified in accordance with IRS Audit Technique Guidelines:
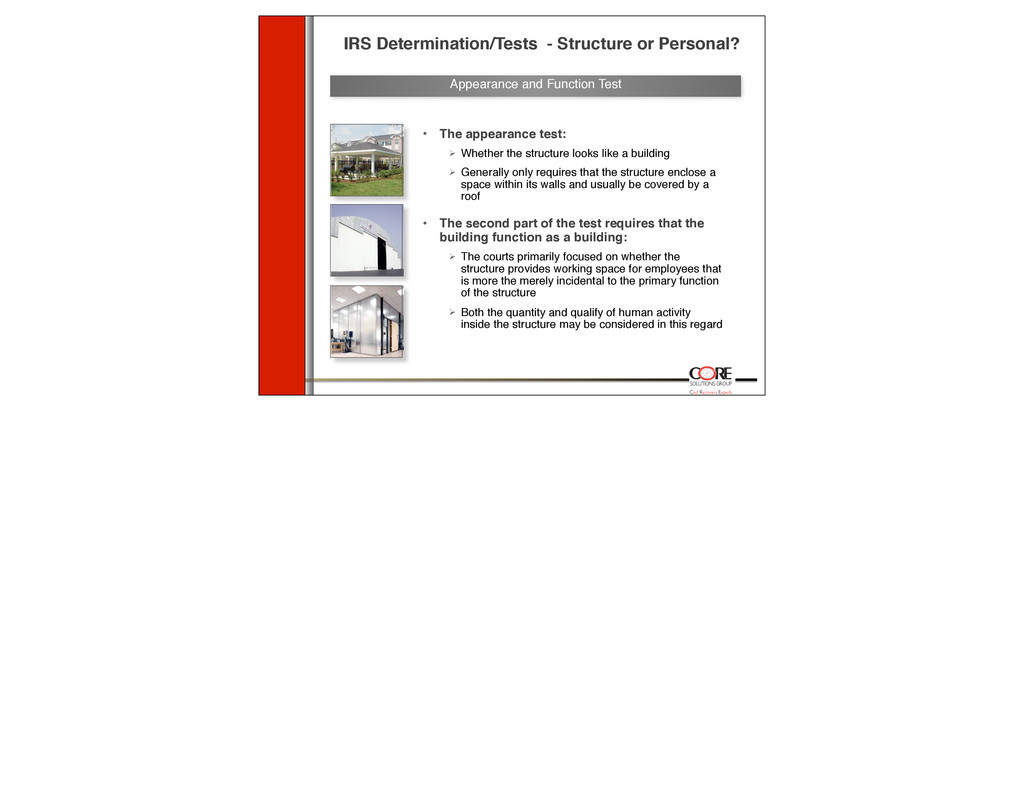
The appearance test: Whether the structure looks like a building Generally only requires that the structure enclose a space within its walls and usually be covered by a roof • The second part of the test requires that the building function as a building: The courts primarily focused on whether the structure provides working space for employees that is more the merely incidental to the primary function of the structure Both the quantity and qualify of human activity inside the structure may be considered in this regard Appearance and Function Test
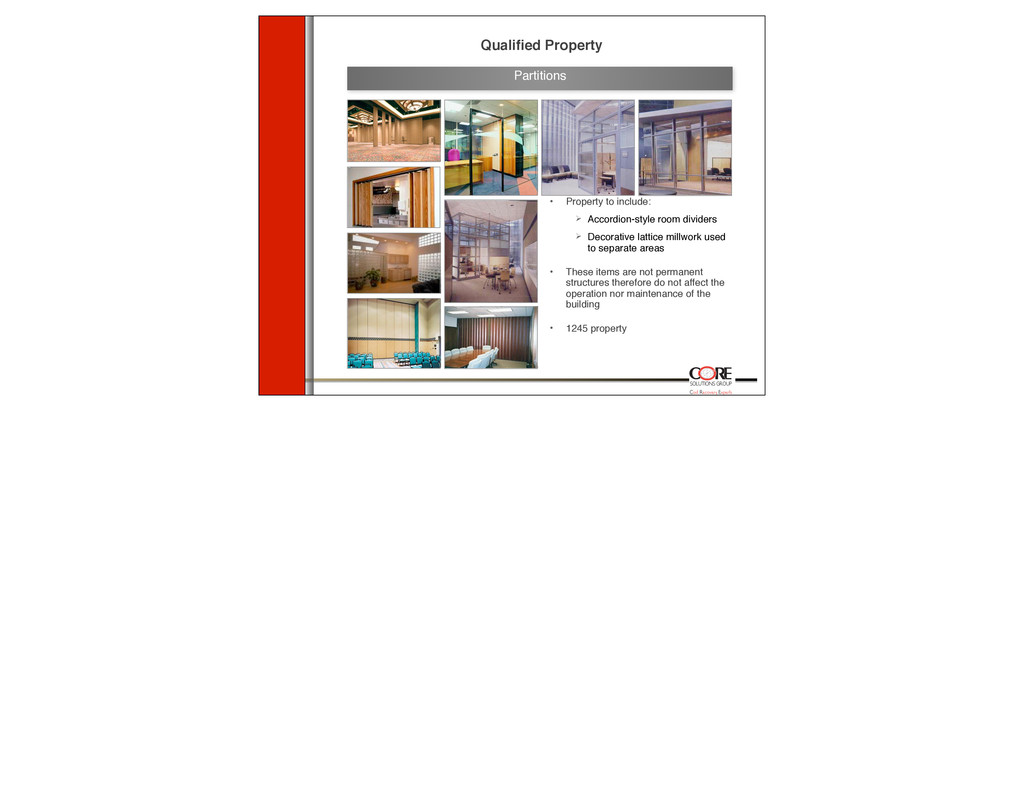
Accordion-style room dividers Decorative lattice millwork used to separate areas • These items are not permanent structures therefore do not affect the operation nor maintenance of the building • 1245 property Partitions
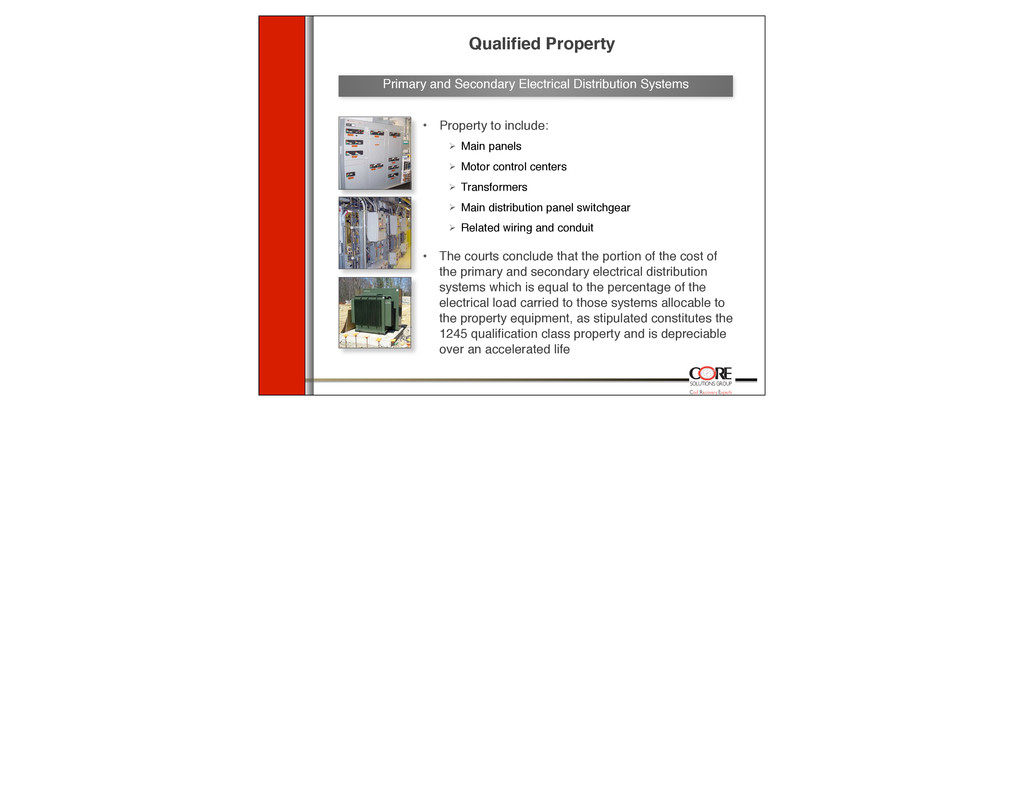
Main panels Motor control centers Transformers Main distribution panel switchgear Related wiring and conduit • The courts conclude that the portion of the cost of the primary and secondary electrical distribution systems which is equal to the percentage of the electrical load carried to those systems allocable to the property equipment, as stipulated constitutes the 1245 qualification class property and is depreciable over an accelerated life Primary and Secondary Electrical Distribution Systems
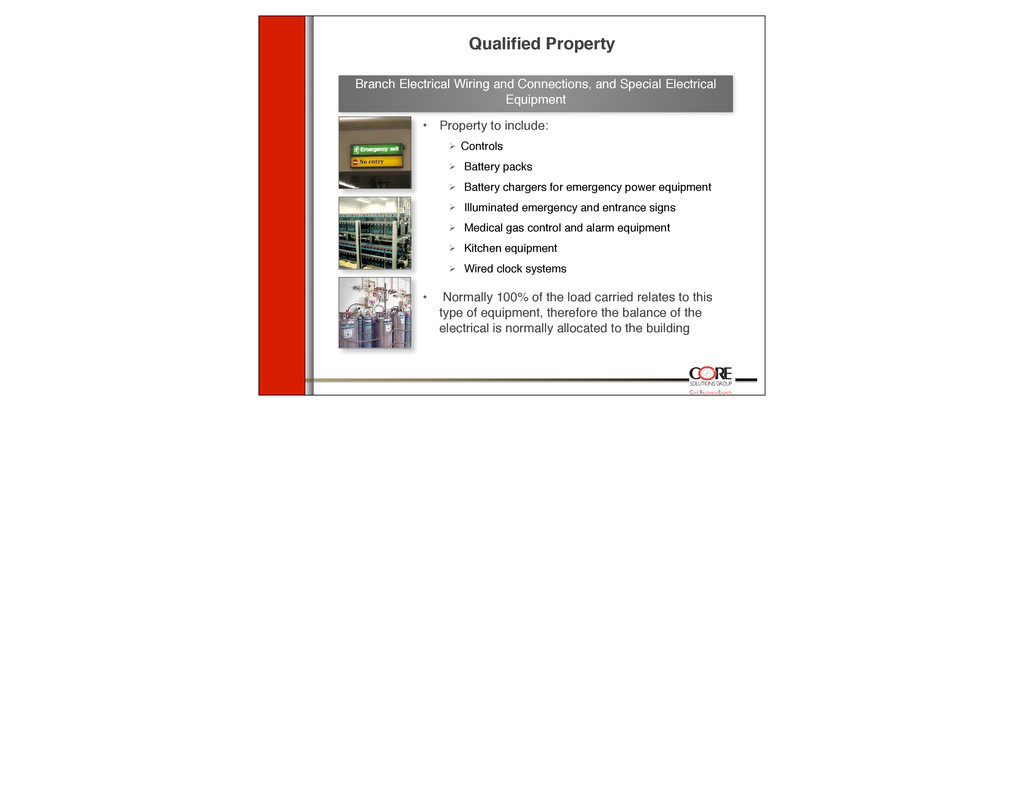
Controls Battery packs Battery chargers for emergency power equipment Illuminated emergency and entrance signs Medical gas control and alarm equipment Kitchen equipment Wired clock systems • Normally 100% of the load carried relates to this type of equipment, therefore the balance of the electrical is normally allocated to the building Branch Electrical Wiring and Connections, and Special Electrical Equipment
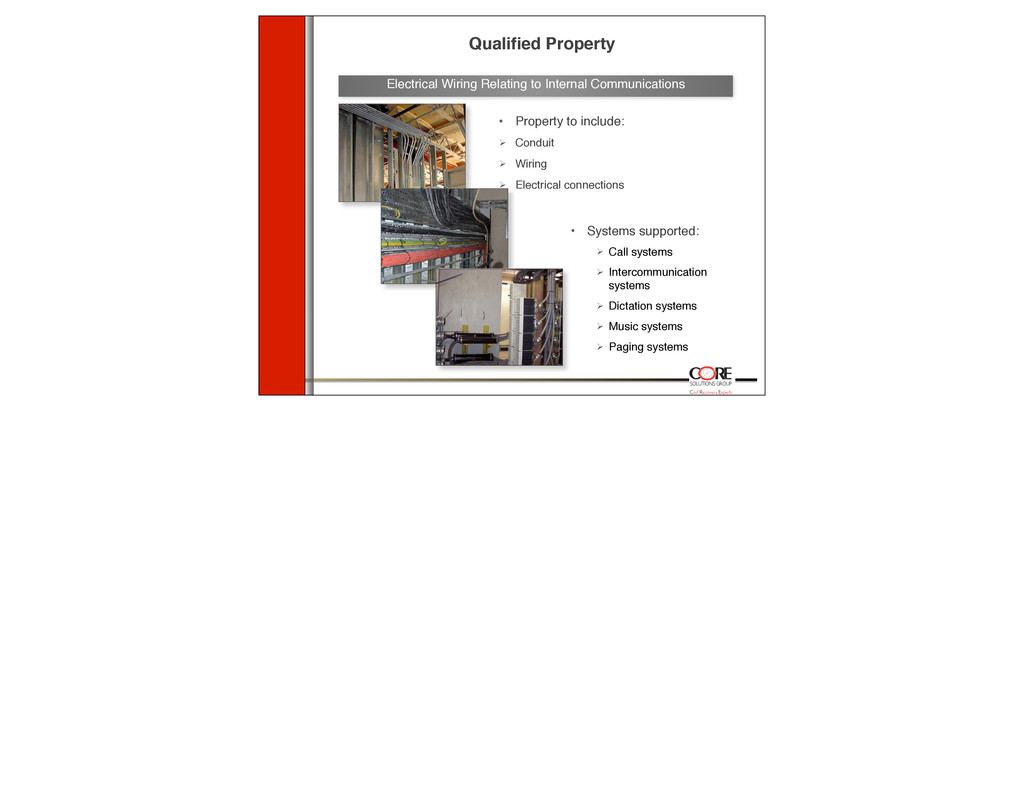
systems Intercommunication systems Dictation systems Music systems Paging systems Electrical Wiring Relating to Internal Communications • Property to include: Conduit Wiring Electrical connections
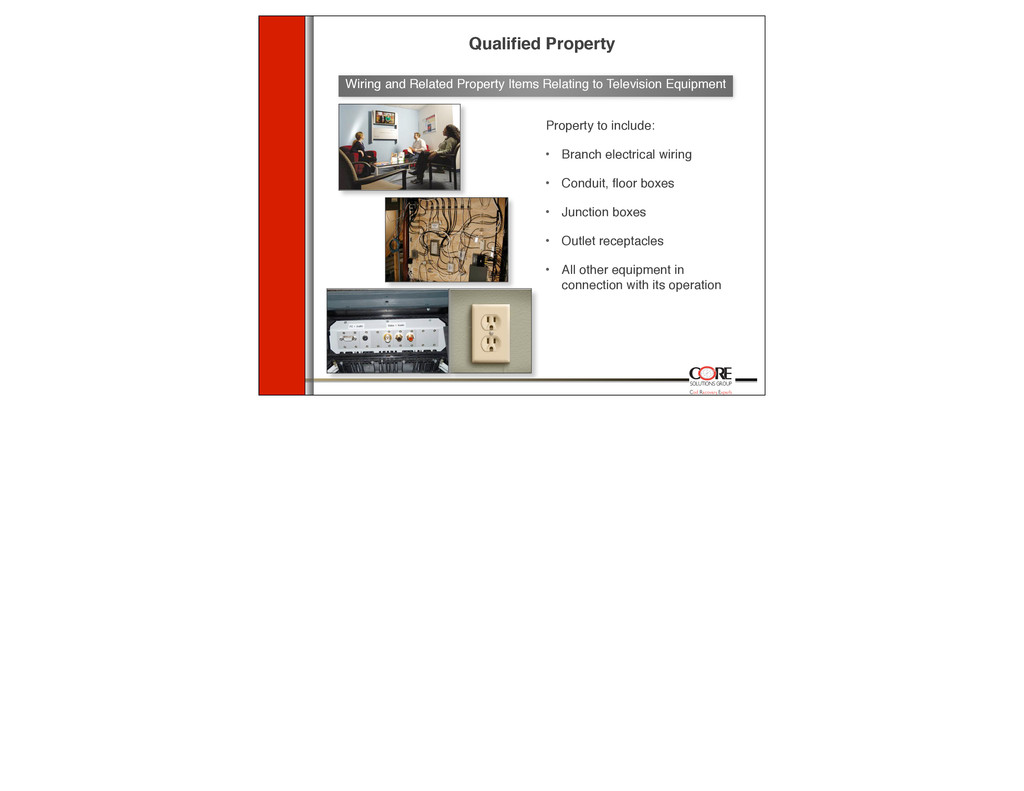
electrical wiring • Conduit, floor boxes • Junction boxes • Outlet receptacles • All other equipment in connection with its operation Wiring and Related Property Items Relating to Television Equipment
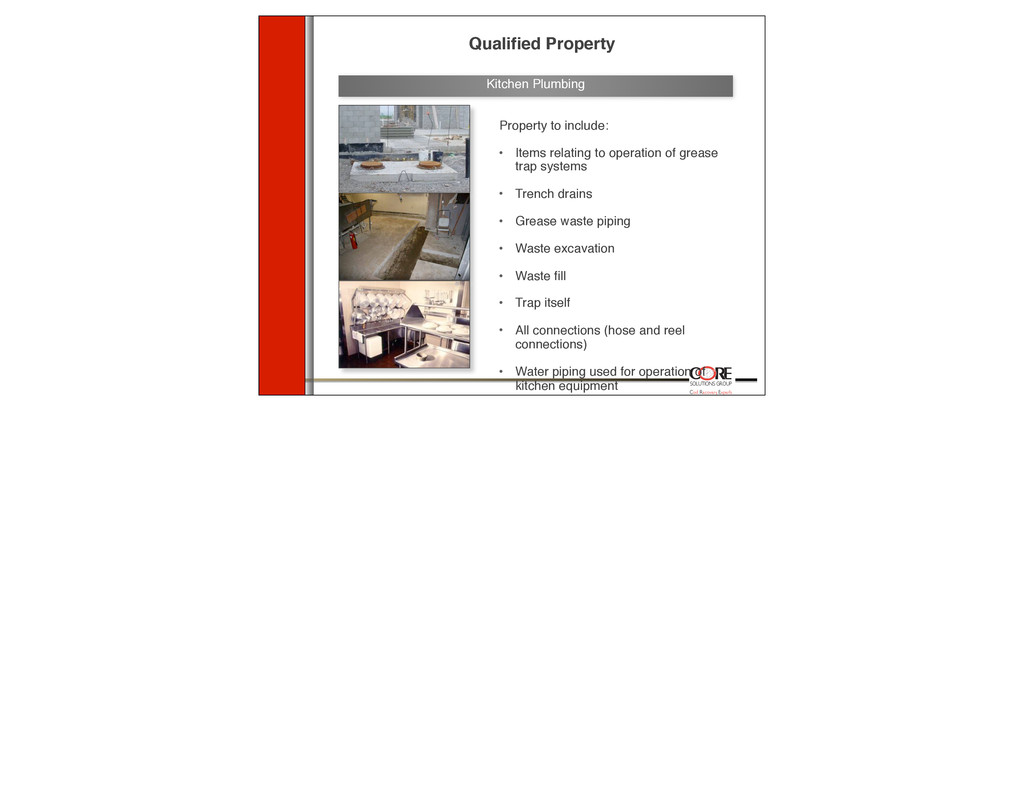
relating to operation of grease trap systems • Trench drains • Grease waste piping • Waste excavation • Waste fill • Trap itself • All connections (hose and reel connections) • Water piping used for operation of kitchen equipment Kitchen Plumbing
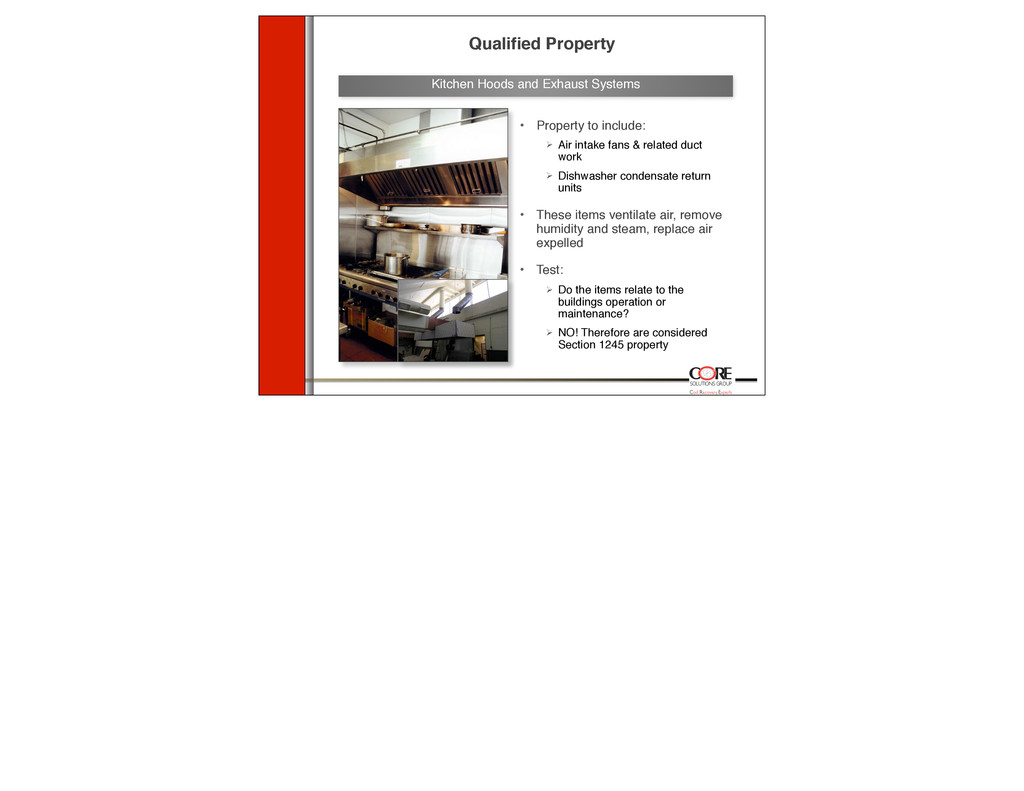
Air intake fans & related duct work Dishwasher condensate return units • These items ventilate air, remove humidity and steam, replace air expelled • Test: Do the items relate to the buildings operation or maintenance? NO! Therefore are considered Section 1245 property Kitchen Hoods and Exhaust Systems
Dramatic reduction in taxable income • Increased cash flow for investment opportunities and business expansion • Property tax savings • Insurance savings www.coreadvisors.net Don Gardner 888-706-4646 x-395 Email: [email protected]
Buildings, Warehouses, etc. Also Includes Public Buildings, e.g., Schools Buildings over 50,000 sq foot New construction or major renovations Note: Public Buildings: Tax Benefit Can Pass Through to “Person Primarily Responsible for Designing the Building”.
1331 of the Energy Policy Act of 2005 provides for and allows a tax deduction for energy efficient commercial buildings that reduce annual energy and power consumption by 50% compared to the American Society of Heating, Refrigerating and Air Conditioning Engineers standard of 2001. Up to $0.60 / sq ft for any of the 3 Energy-Using Systems: Lighting HVAC Building Envelope Note: Tax Benefit can total $1.80 per sq foot if a reduction in energy consumption reaches 50%.
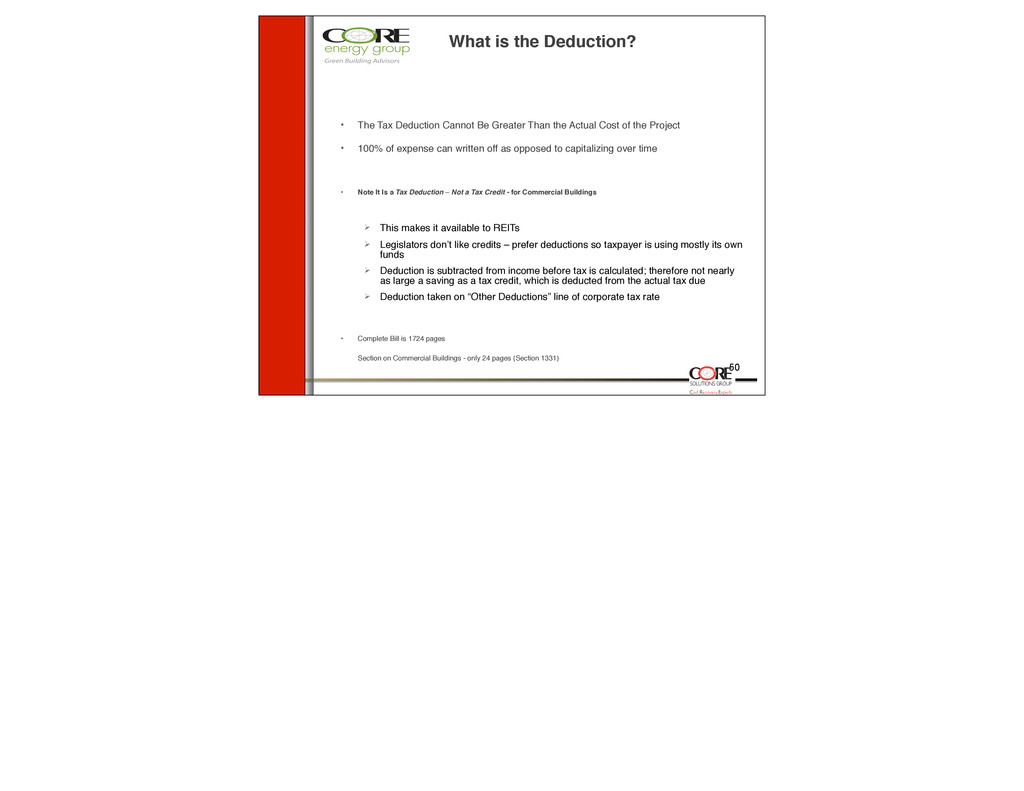
Tax Deduction Cannot Be Greater Than the Actual Cost of the Project • 100% of expense can written off as opposed to capitalizing over time • Note It Is a Tax Deduction – Not a Tax Credit - for Commercial Buildings This makes it available to REITs Legislators don’t like credits – prefer deductions so taxpayer is using mostly its own funds Deduction is subtracted from income before tax is calculated; therefore not nearly as large a saving as a tax credit, which is deducted from the actual tax due Deduction taken on “Other Deductions” line of corporate tax rate • Complete Bill is 1724 pages ! Section on Commercial Buildings - only 24 pages (Section 1331)
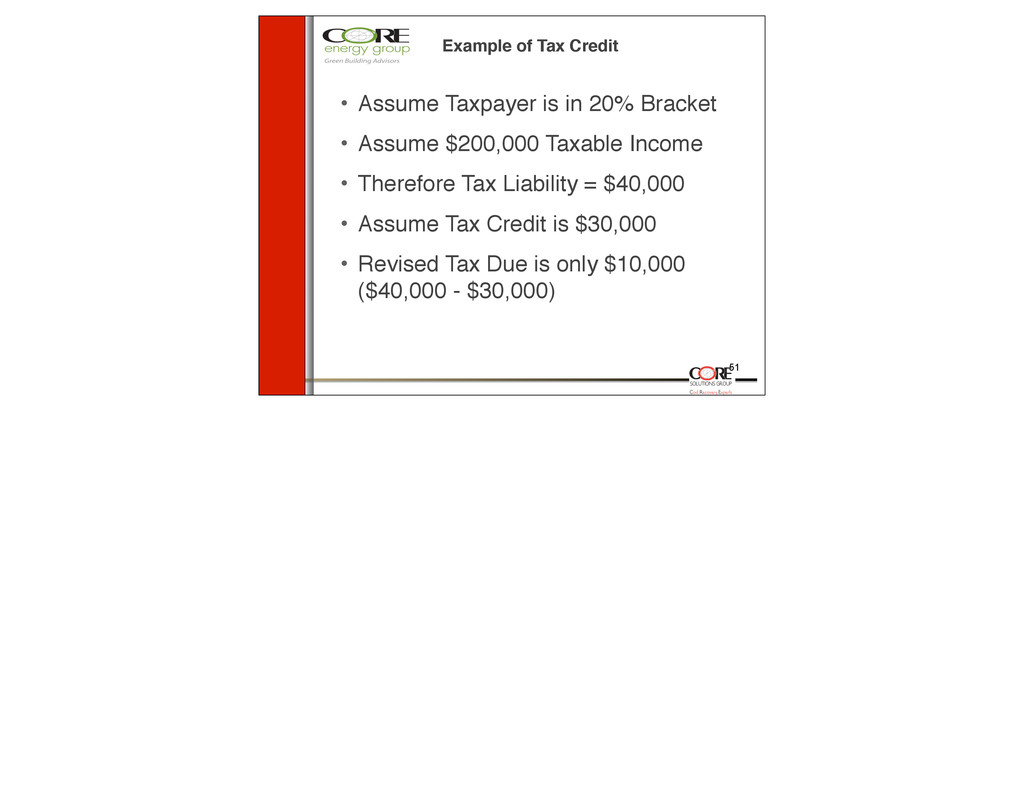
Taxpayer is in 20% Bracket • Assume $200,000 Taxable Income • Therefore Tax Liability = $40,000 • Assume Tax Credit is $30,000 • Revised Tax Due is only $10,000 ($40,000 - $30,000)
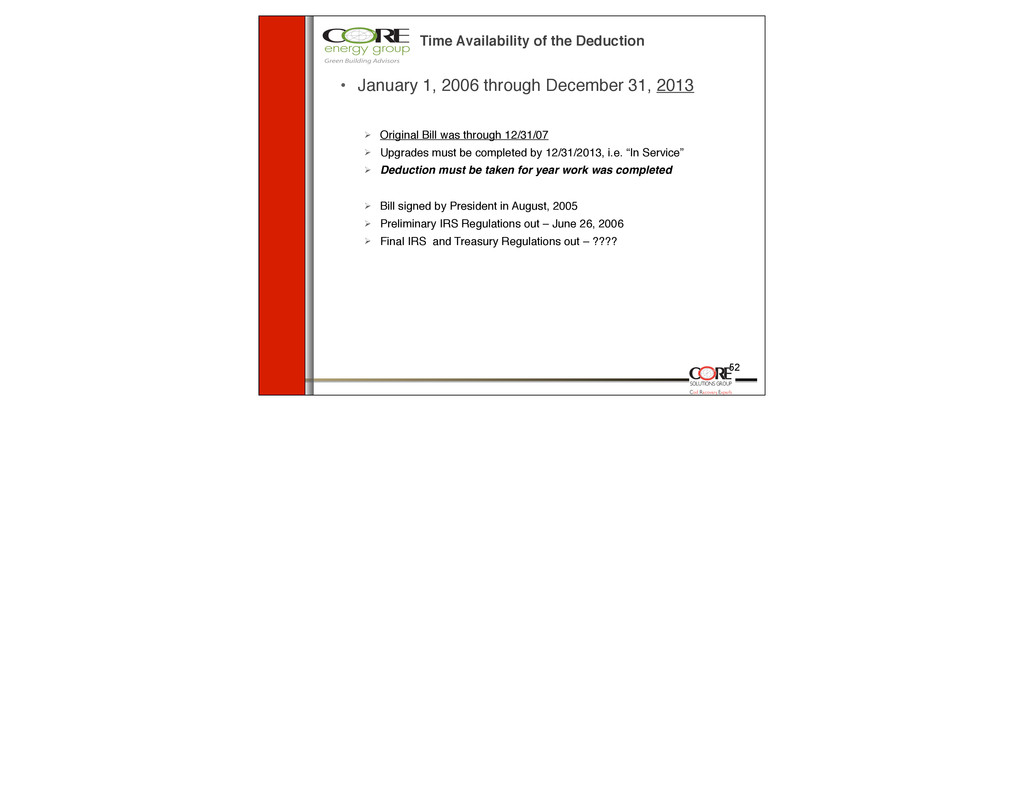
January 1, 2006 through December 31, 2013 Original Bill was through 12/31/07 Upgrades must be completed by 12/31/2013, i.e. “In Service” Deduction must be taken for year work was completed Bill signed by President in August, 2005 Preliminary IRS Regulations out – June 26, 2006 Final IRS and Treasury Regulations out – ????
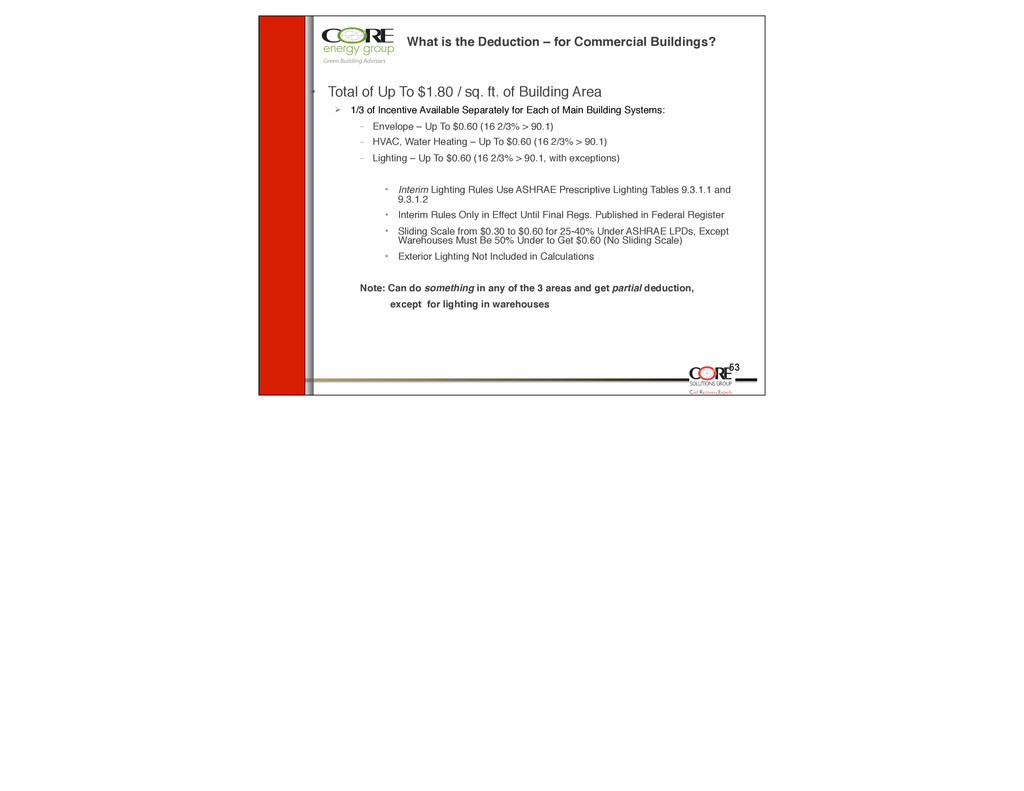
Commercial Buildings? • Total of Up To $1.80 / sq. ft. of Building Area 1/3 of Incentive Available Separately for Each of Main Building Systems: – Envelope – Up To $0.60 (16 2/3% > 90.1) – HVAC, Water Heating – Up To $0.60 (16 2/3% > 90.1) – Lighting – Up To $0.60 (16 2/3% > 90.1, with exceptions) • Interim Lighting Rules Use ASHRAE Prescriptive Lighting Tables 9.3.1.1 and 9.3.1.2 • Interim Rules Only in Effect Until Final Regs. Published in Federal Register • Sliding Scale from $0.30 to $0.60 for 25-40% Under ASHRAE LPDs, Except Warehouses Must Be 50% Under to Get $0.60 (No Sliding Scale) • Exterior Lighting Not Included in Calculations Note: Can do something in any of the 3 areas and get partial deduction, except for lighting in warehouses
3rd Party Inspectors – Review Plans & In-Place Construction – Cannot Be Employee of Entity Claiming Deduction – Professional Engineer – Licensed Contractor
Energy Standard 90.1-2001, as in effect on April 3, 2003 Includes Addenda 90.1a-2003, 90.1b-2002, 90.1c-2002, 90.1d-2002, 90.1k-2002 • Performance Rating Method (PRM) of Appendix G of Standard 90.1-2004
Modeling the Building? Programs Are Listed on DOE Website: www.eere.energy.gov/buildings/info/ tax_credit_2006.html www.eere.energy.gov/buildings/info/ qualified_software/ As of 02/20/2007, there were 6 programs listed – 3 private, 3 public
is available per sq foot? • What does epac stand for? • Can non profits benefit from EPACT? • When is the best time to do a cost seg study? • How much additional tax benefit can someone receive if they own a $3,000,000 building? • Does someone have to be profitable to benefit from a cost segregation study?
• Gas & Electricity Consumption • Mechanical Systems • Lighting Systems • Building Envelope • Alternative Energy Options • Waste into energy programs • Carbon Neutral Programs • LEED Certification • Utility Rebates • Tax Incentives


 sachag
 baasie
 carmenintech
 tmiket
 chriscoyier
 coloredviolet
 katarinadahlin
 aleyda
 samanthasiow
 kristinabergwall1
 jacobian
 morganepeng