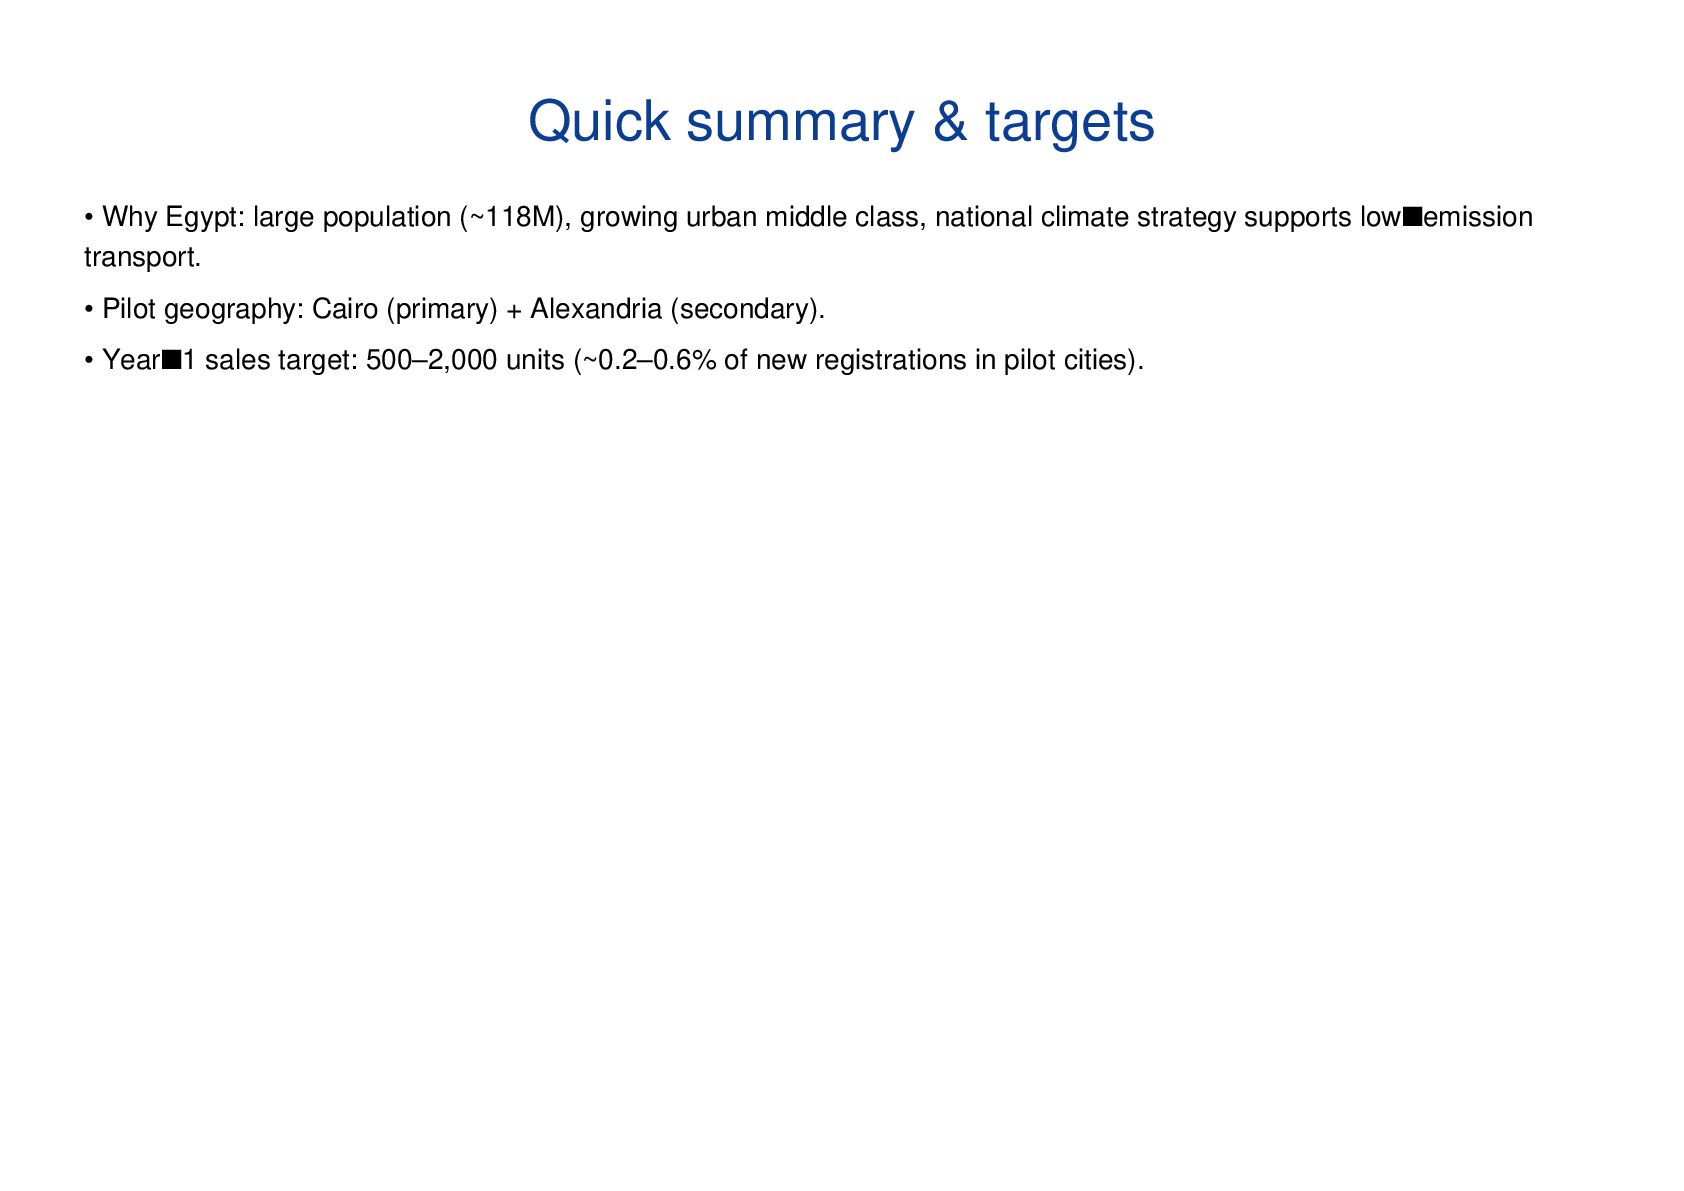
growing urban middle class, national climate strategy supports lowsemission transport. • Pilot geography: Cairo (primary) + Alexandria (secondary). • Years1 sales target: 500–2,000 units (~0.2–0.6% of new registrations in pilot cities).
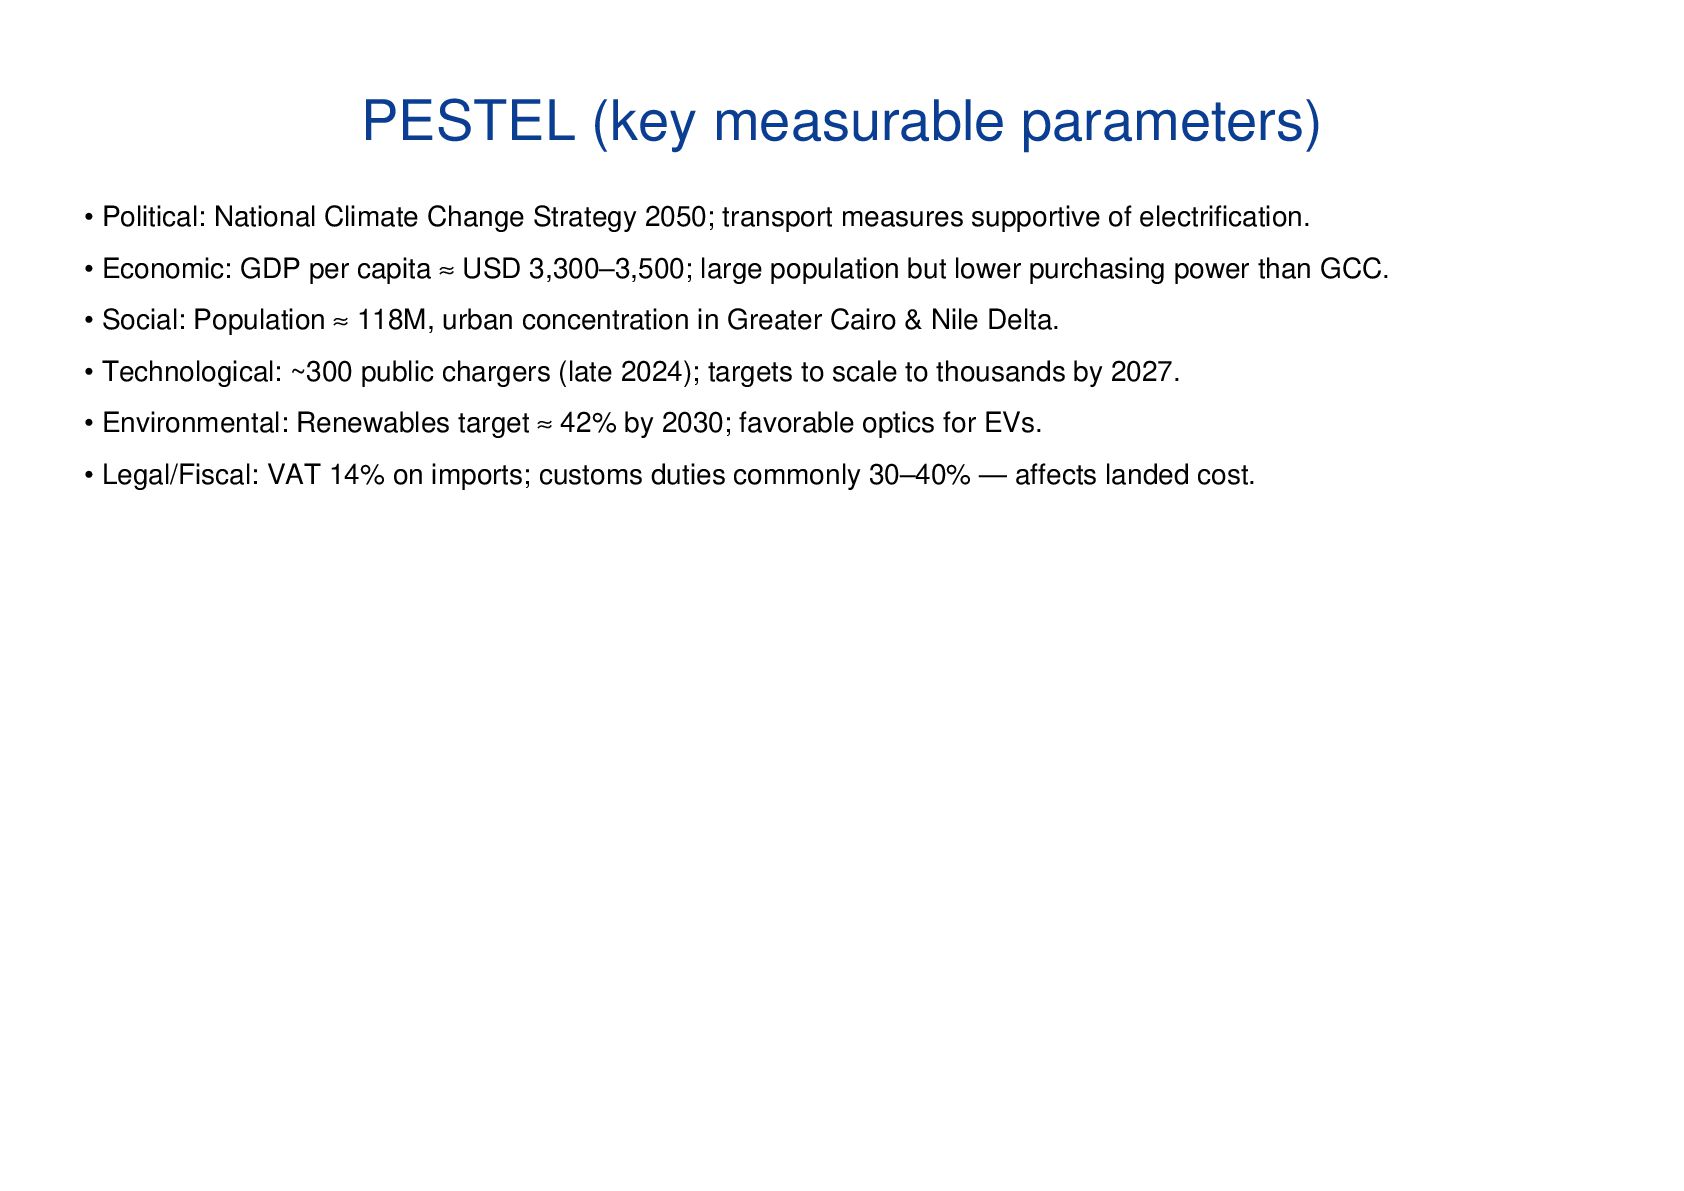
2050; transport measures supportive of electrification. • Economic: GDP per capita ≈ USD 3,300–3,500; large population but lower purchasing power than GCC. • Social: Population ≈ 118M, urban concentration in Greater Cairo & Nile Delta. • Technological: ~300 public chargers (late 2024); targets to scale to thousands by 2027. • Environmental: Renewables target ≈ 42% by 2030; favorable optics for EVs. • Legal/Fiscal: VAT 14% on imports; customs duties commonly 30–40% — affects landed cost.
with high visibility (expect high customer expectations). • Question Marks: Value/mainstream EV entrants — high growth, low share currently. • Cash Cows: Established ICE/HEV models with mature channels. • Our positioning: Value-for-money mainstream EV (Question Mark → Star in 12–24 months).
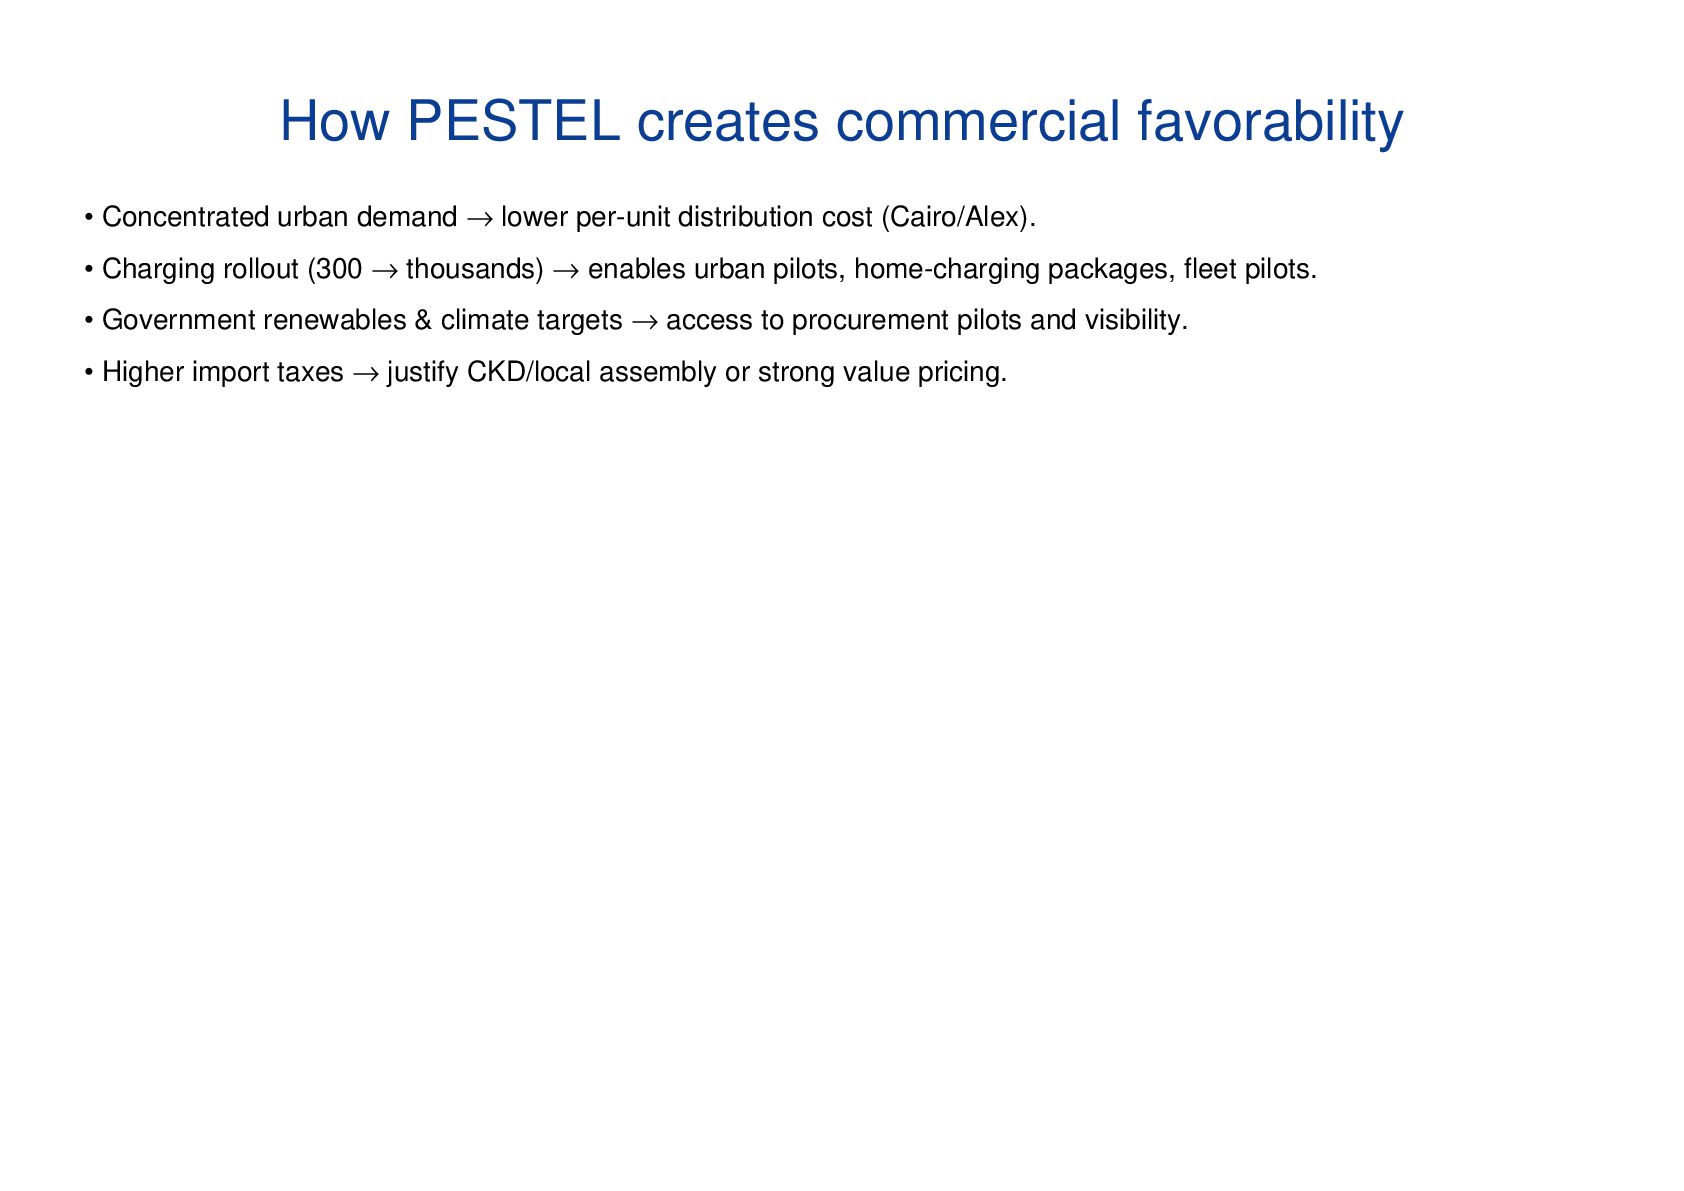
UAE? → larger addressable market & strategic value of local assembly. • How to mitigate charging gaps? → home charging, DC sites, fleet pilots, partner installers. • Potential partners: Ministry of Transport, NREA, local charging operators, banks for fleet finance, major real-estate operators.
share with team, prepare presentation slides with visuals. • If you want: I can create an Arabic version, embed charts, or export a PDF for submission.


 cassininazir
 uxyall
 jonoalderson
 livdayseo
 pwiseman
 sferik
 jonrohan
 baasie
 popppiees
 techseoconnect
 mclloyd