Upgrade to Pro — share decks privately, control downloads, hide ads and more …

Clean Fuel Technology Limited

Clean Fuel Technology Limited

Avatar for Intellectual Capital

Intellectual Capital

February 11, 2017

Other Decks in Technology

Transcript

  1. PUBLIC-PRIVATE PARTNERSHIP ―E-IDCOT & AEP CLEAN FUEL TECHNOLOGY Pre-investment Conference

    SPONSORS / PARTNERS: American Energy Producers, LLC Eco-Industrial Development Company of Tobago Ltd (EIDCOT)
  2. Eco-Industrial Development Company of Tobago Ltd (EIDCOT) and American Energy

    Producers, LLC (AEP) have signed an MOU for a proposed public-private partnership (PPP) for development of a 500 - barrel per day (bpd) ultra-clean diesel plant at a greenfield site at the Cove Eco-Industrial and Business Park (CEIBP), in Tobago. The project will be followed by a 6,800 bpd bio-jet fuel plant and a subsequent 27,800 bpd hybrid plant producing ultra-clean diesel and bio-jet fuel. PUBLIC-PRIVATE PARTNERSHIP PPP Enabling company: Clean Fuel Technology Limited (CFT)
  3. Why CFT? Environmentally-friendly fuel provider CFT offers environmentally friendly solutions

    and an economically viable business model for converting natural gas into ultra-clean diesel and bio-jet fuel. 01 Response to niche market opportunities CFT is positioned to benefit from upcoming restrictions and penalties on emissions for the marine and aviation sectors globally. Utilising best-in-class technology CFT combines the world-leading technology such as Fischer-Tropsch, and ExxonMobil technology to produce finished products ready for use. 02 03
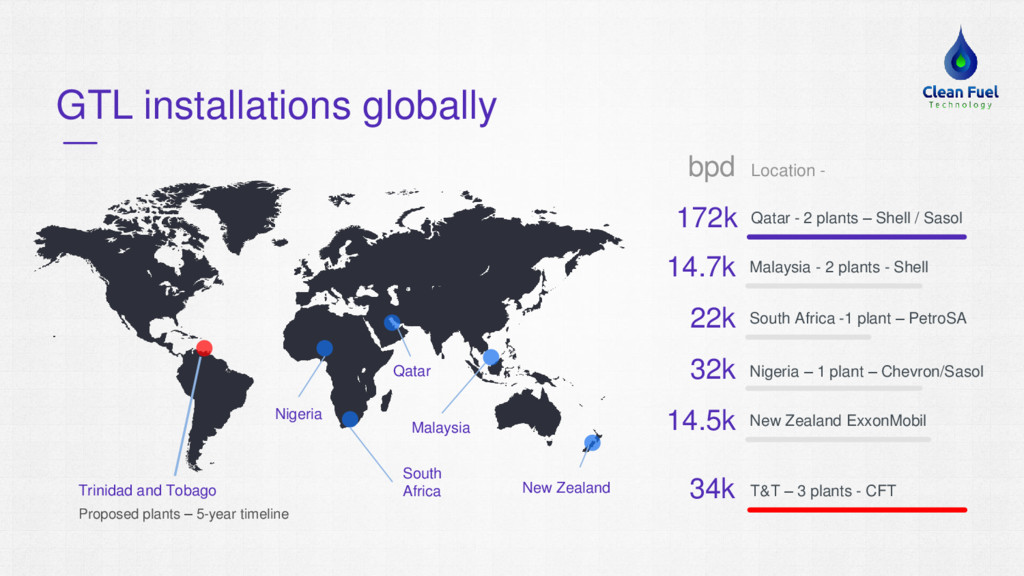
  4. GTL installations globally Qatar - 2 plants – Shell /

    Sasol Trinidad and Tobago 172k Malaysia - 2 plants - Shell 14.7k South Africa -1 plant – PetroSA 22k Nigeria – 1 plant – Chevron/Sasol 32k New Zealand ExxonMobil 14.5k Proposed plants – 5-year timeline bpd Location - T&T – 3 plants - CFT 34k South Africa Malaysia Qatar Nigeria New Zealand
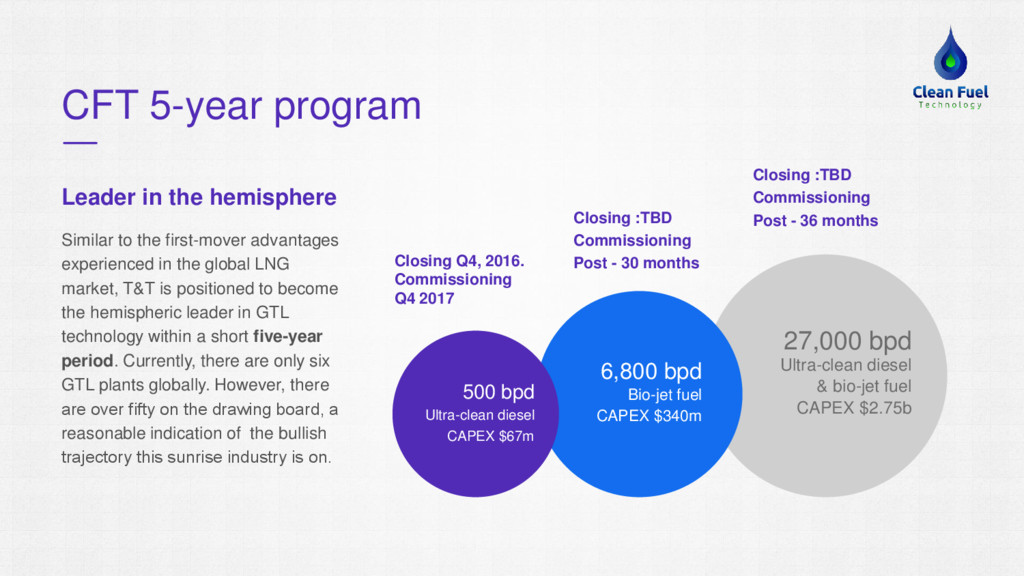
  5. CFT 5-year program 27,000 bpd Ultra-clean diesel & bio-jet fuel

    CAPEX $2.75b 6,800 bpd Bio-jet fuel CAPEX $340m 500 bpd Ultra-clean diesel CAPEX $67m Similar to the first-mover advantages experienced in the global LNG market, T&T is positioned to become the hemispheric leader in GTL technology within a short five-year period. Currently, there are only six GTL plants globally. However, there are over fifty ​on the drawing board, a reasonable indication of the bullish trajectory this sunrise industry is on.​ Leader in the hemisphere Closing :TBD Commissioning Post - 36 months Closing :TBD Commissioning Post - 30 months Closing Q4, 2016. Commissioning Q4 2017
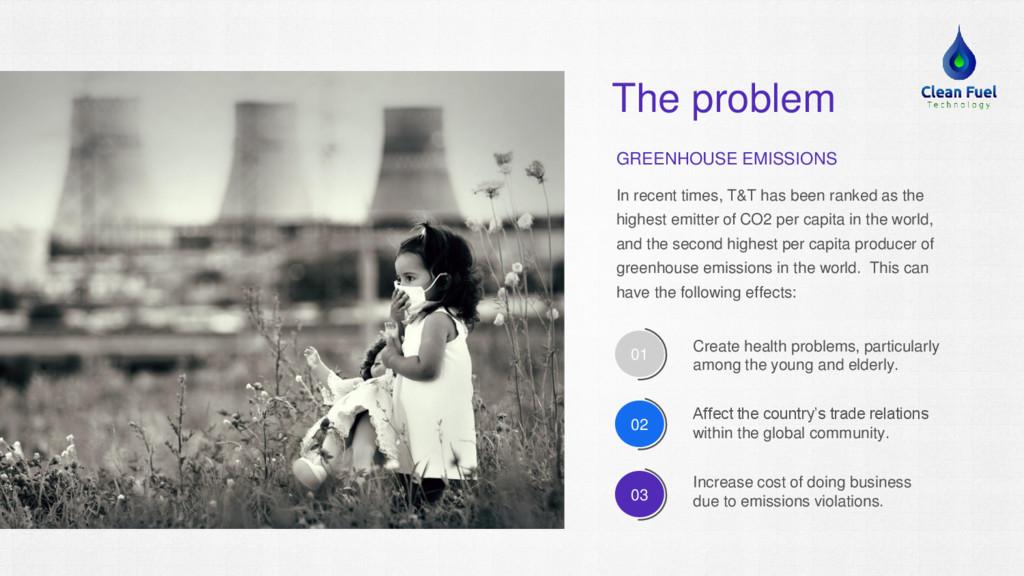
  6. The problem In recent times, T&T has been ranked as

    the highest emitter of CO2 per capita in the world, and the second highest per capita producer of greenhouse emissions in the world. This can have the following effects: Create health problems, particularly among the young and elderly. GREENHOUSE EMISSIONS 01 02 03 Affect the country’s trade relations within the global community. Increase cost of doing business due to emissions violations.
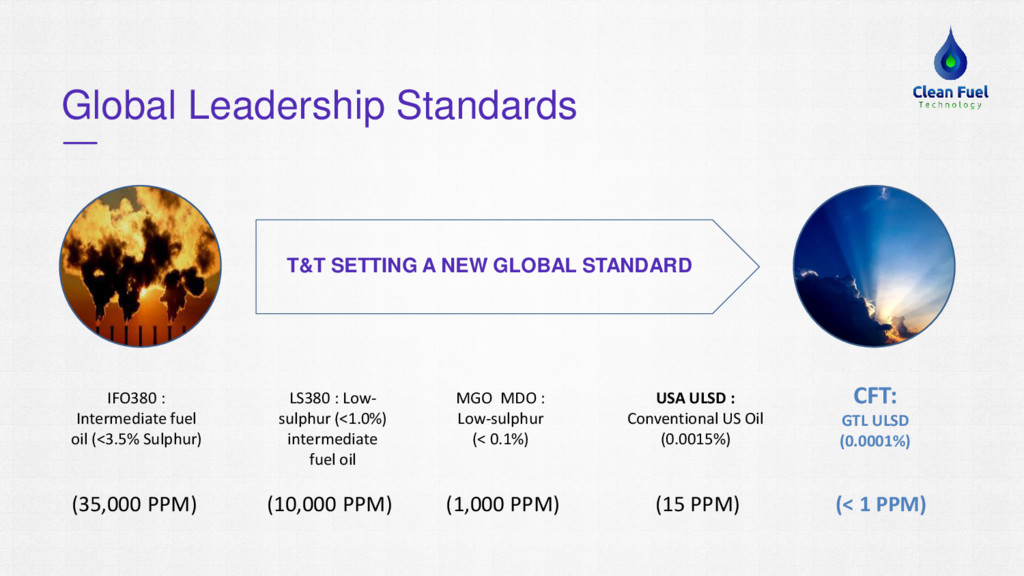
  7. Global Leadership Standards LS380 : Low- sulphur (<1.0%) intermediate fuel

    oil T&T SETTING A NEW GLOBAL STANDARD CFT: GTL ULSD (0.0001%) IFO380 : Intermediate fuel oil (<3.5% Sulphur) MGO MDO : Low-sulphur (< 0.1%) USA ULSD : Conventional US Oil (0.0015%) (10,000 PPM) (35,000 PPM) (1,000 PPM) (15 PPM) (< 1 PPM)
  8. The industry is moving towards clean fuel technology. The International

    Civil Aviation Organization (ICAO) is implementing emission control standards for airlines as early as 2020. New emission standards for jet fuel
  9. What’s ahead for marine fuel? The industry is moving towards

    clean fuel technology. Under an international shipping convention signed by more than 150 countries and adopted by the International Maritime Organization, marine-sulfur levels will be required to drop to 0.5% from the current 3.5% in 2020 Some regions, such as Europe and the U.S., are moving ahead faster to adopt these standards..
  10. Product off-take CFT will sell its products on a fixed

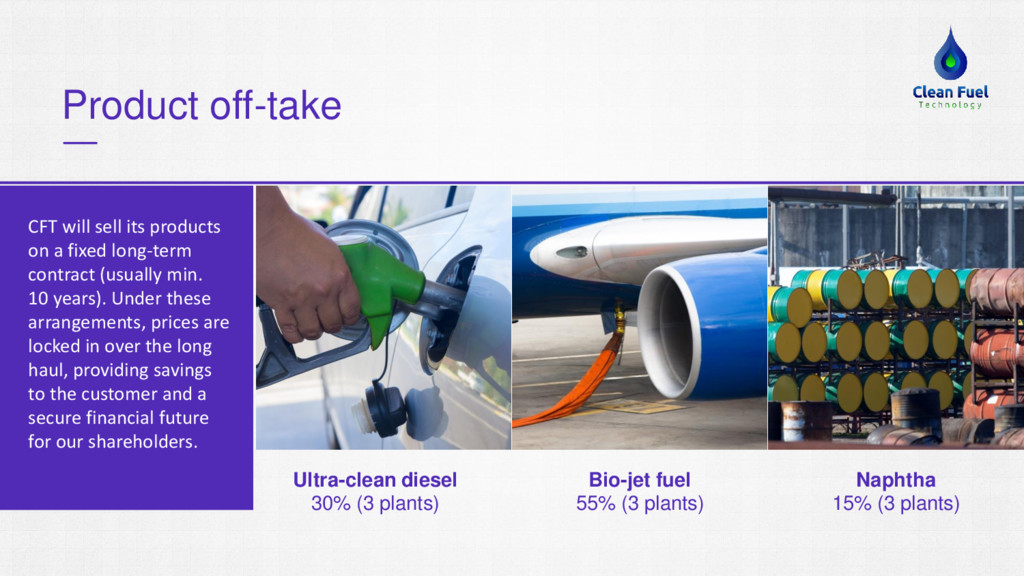
    long-term contract (usually min. 10 years). Under these arrangements, prices are locked in over the long haul, providing savings to the customer and a secure financial future for our shareholders. Ultra-clean diesel 30% (3 plants) Bio-jet fuel 55% (3 plants) Naphtha 15% (3 plants)
  11. Low sulphur industry trends Rotterdam Low Sulphur Bunker Sales "Almost

    Tripled" in 2015 Source: Port of Rotterdam Authority - Monday January 25, 2016 Sales of low sulphur gas oil and diesel at the Port of Rotterdam is said to have increased from 0.7 million to 1.8 million m3 in 2015. The Port of Rotterdam Authority Friday announced that sales of low sulphur gas oil and diesel "almost tripled" from 1.8 million m3 in 2015 compared 0.7 million m3 during the previous year. The increase in the low sulphur bunker sales, which has been attributed to sulphur requirements for maritime shipping in the Emission Control Areas (ECAs) of the North Sea and the Baltic Sea, is said to have come at the expense of the sales of fuel oil, which fell from 9.8 million m3 in 2014 to 8.7 million m3 in 2015. "The Port of Rotterdam Authority welcomes this development since gas oil and diesel are significantly less polluting than fuel oil. The Port Authority is committed to cleaner shipping," said the port authority.
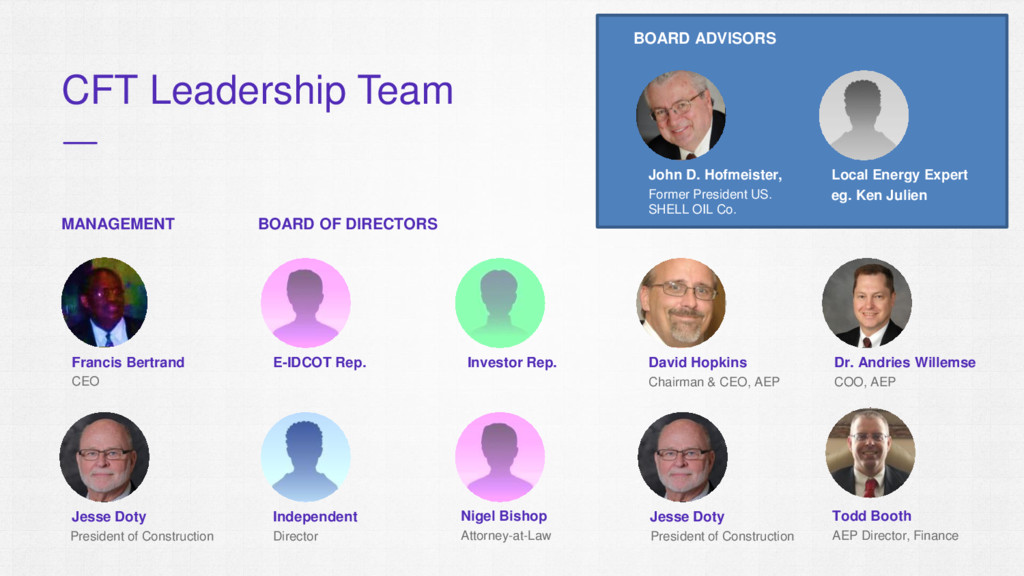
  12. Dr. Andries Willemse COO, AEP CFT Leadership Team David Hopkins

    Chairman & CEO, AEP Investor Rep. E-IDCOT Rep. Independent Director MANAGEMENT BOARD OF DIRECTORS Francis Bertrand CEO Jesse Doty President of Construction Jesse Doty President of Construction John D. Hofmeister, Former President US. SHELL OIL Co. Local Energy Expert eg. Ken Julien BOARD ADVISORS Todd Booth AEP Director, Finance Nigel Bishop Attorney-at-Law
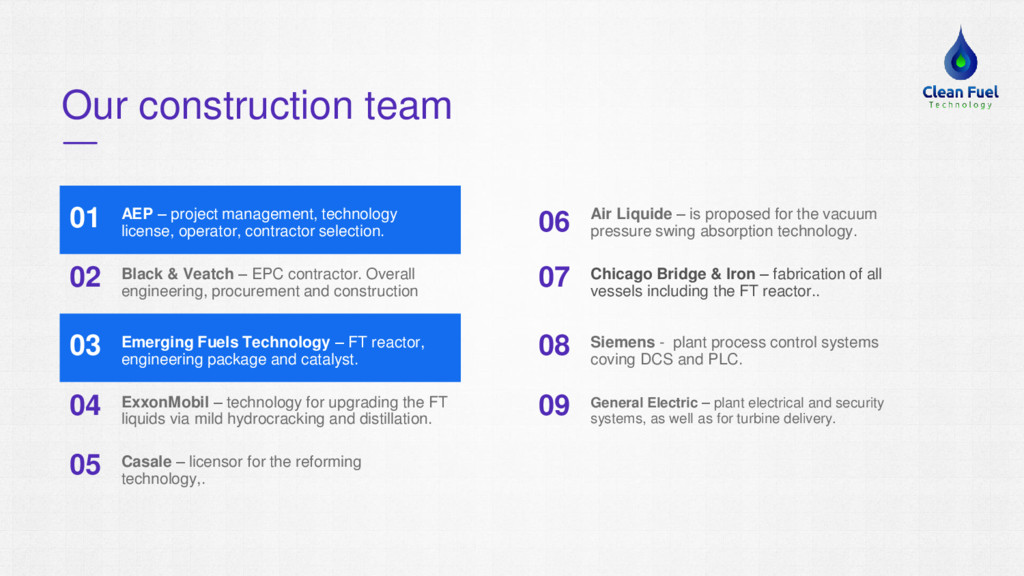
  13. AEP – project management, technology license, operator, contractor selection. Black

    & Veatch – EPC contractor. Overall engineering, procurement and construction Emerging Fuels Technology – FT reactor, engineering package and catalyst. ExxonMobil – technology for upgrading the FT liquids via mild hydrocracking and distillation. Casale – licensor for the reforming technology,. Air Liquide – is proposed for the vacuum pressure swing absorption technology. Chicago Bridge & Iron – fabrication of all vessels including the FT reactor.. Siemens - plant process control systems coving DCS and PLC. General Electric – plant electrical and security systems, as well as for turbine delivery. Our construction team 01 02 03 04 05 06 07 08 09
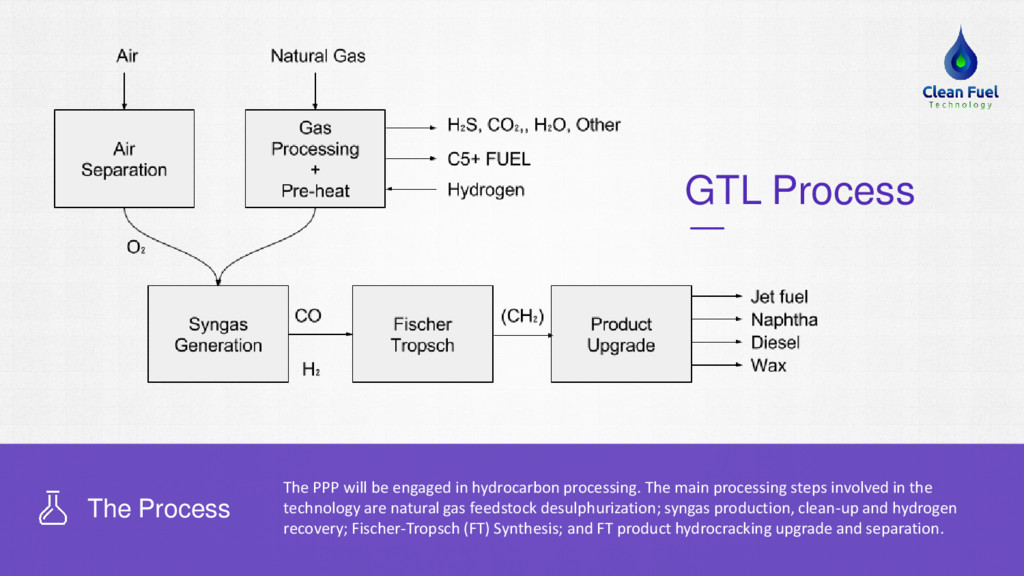
  14. The PPP will be engaged in hydrocarbon processing. The main

    processing steps involved in the technology are natural gas feedstock desulphurization; syngas production, clean-up and hydrogen recovery; Fischer-Tropsch (FT) Synthesis; and FT product hydrocracking upgrade and separation. The Process GTL Process
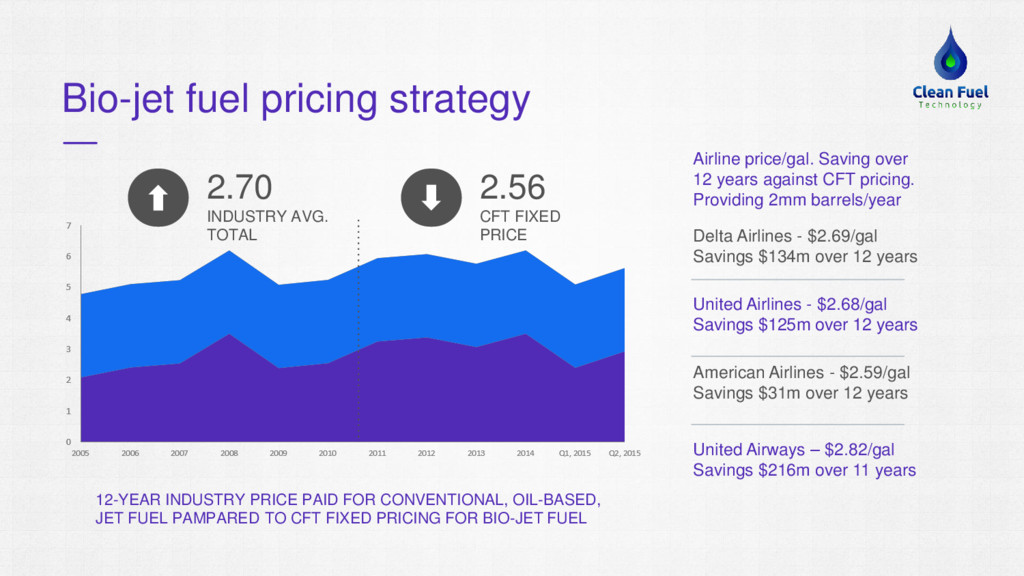
  15. United Airways – $2.82/gal Savings $216m over 11 years American

    Airlines - $2.59/gal Savings $31m over 12 years United Airlines - $2.68/gal Savings $125m over 12 years Delta Airlines - $2.69/gal Savings $134m over 12 years 2.70 INDUSTRY AVG. TOTAL Airline price/gal. Saving over 12 years against CFT pricing. Providing 2mm barrels/year Bio-jet fuel pricing strategy 12-YEAR INDUSTRY PRICE PAID FOR CONVENTIONAL, OIL-BASED, JET FUEL PAMPARED TO CFT FIXED PRICING FOR BIO-JET FUEL 2.56 CFT FIXED PRICE
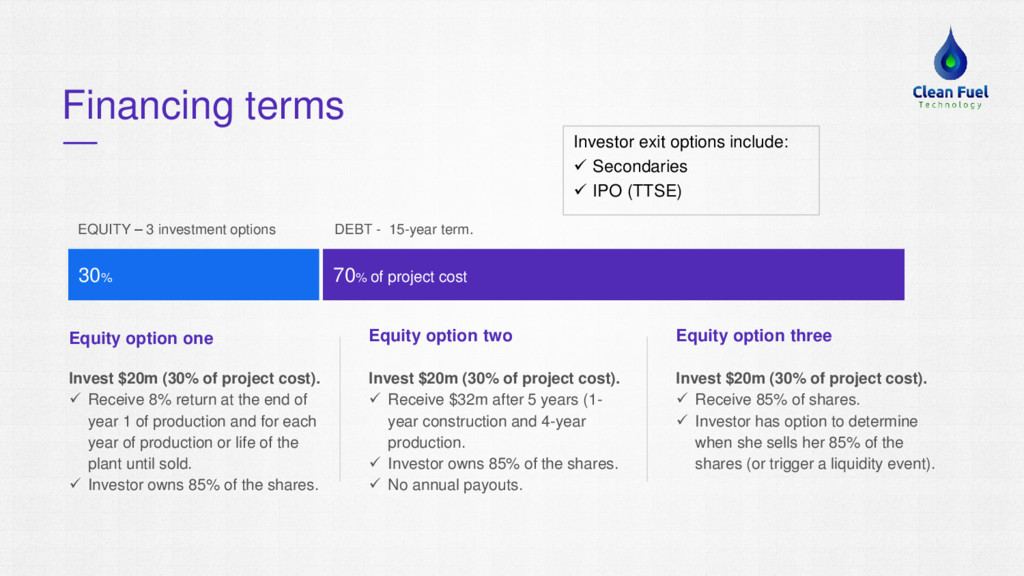
  16. Financing terms Invest $20m (30% of project cost).  Receive

    8% return at the end of year 1 of production and for each year of production or life of the plant until sold.  Investor owns 85% of the shares. Equity option one Equity option two Equity option three 30% 70% of project cost EQUITY – 3 investment options DEBT - 15-year term. Invest $20m (30% of project cost).  Receive $32m after 5 years (1- year construction and 4-year production.  Investor owns 85% of the shares.  No annual payouts. Invest $20m (30% of project cost).  Receive 85% of shares.  Investor has option to determine when she sells her 85% of the shares (or trigger a liquidity event). Investor exit options include:  Secondaries  IPO (TTSE)
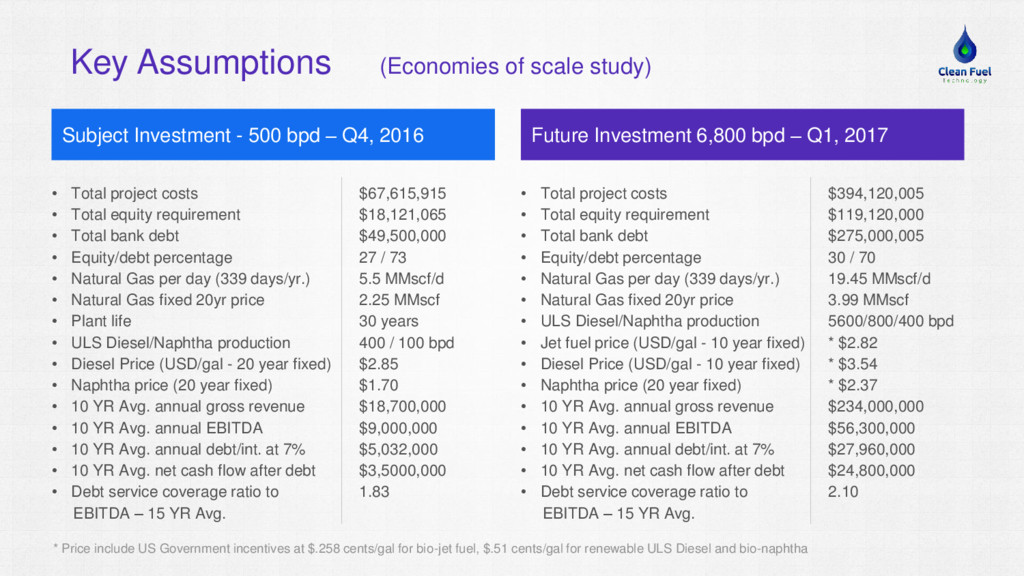
  17. Key Assumptions (Economies of scale study) • Total project costs

    $67,615,915 • Total equity requirement $18,121,065 • Total bank debt $49,500,000 • Equity/debt percentage 27 / 73 • Natural Gas per day (339 days/yr.) 5.5 MMscf/d • Natural Gas fixed 20yr price 2.25 MMscf • Plant life 30 years • ULS Diesel/Naphtha production 400 / 100 bpd • Diesel Price (USD/gal - 20 year fixed) $2.85 • Naphtha price (20 year fixed) $1.70 • 10 YR Avg. annual gross revenue $18,700,000 • 10 YR Avg. annual EBITDA $9,000,000 • 10 YR Avg. annual debt/int. at 7% $5,032,000 • 10 YR Avg. net cash flow after debt $3,5000,000 • Debt service coverage ratio to 1.83 EBITDA – 15 YR Avg. Subject Investment - 500 bpd – Q4, 2016 Future Investment 6,800 bpd – Q1, 2017 • Total project costs $394,120,005 • Total equity requirement $119,120,000 • Total bank debt $275,000,005 • Equity/debt percentage 30 / 70 • Natural Gas per day (339 days/yr.) 19.45 MMscf/d • Natural Gas fixed 20yr price 3.99 MMscf • ULS Diesel/Naphtha production 5600/800/400 bpd • Jet fuel price (USD/gal - 10 year fixed) * $2.82 • Diesel Price (USD/gal - 10 year fixed) * $3.54 • Naphtha price (20 year fixed) * $2.37 • 10 YR Avg. annual gross revenue $234,000,000 • 10 YR Avg. annual EBITDA $56,300,000 • 10 YR Avg. annual debt/int. at 7% $27,960,000 • 10 YR Avg. net cash flow after debt $24,800,000 • Debt service coverage ratio to 2.10 EBITDA – 15 YR Avg. * Price include US Government incentives at $.258 cents/gal for bio-jet fuel, $.51 cents/gal for renewable ULS Diesel and bio-naphtha
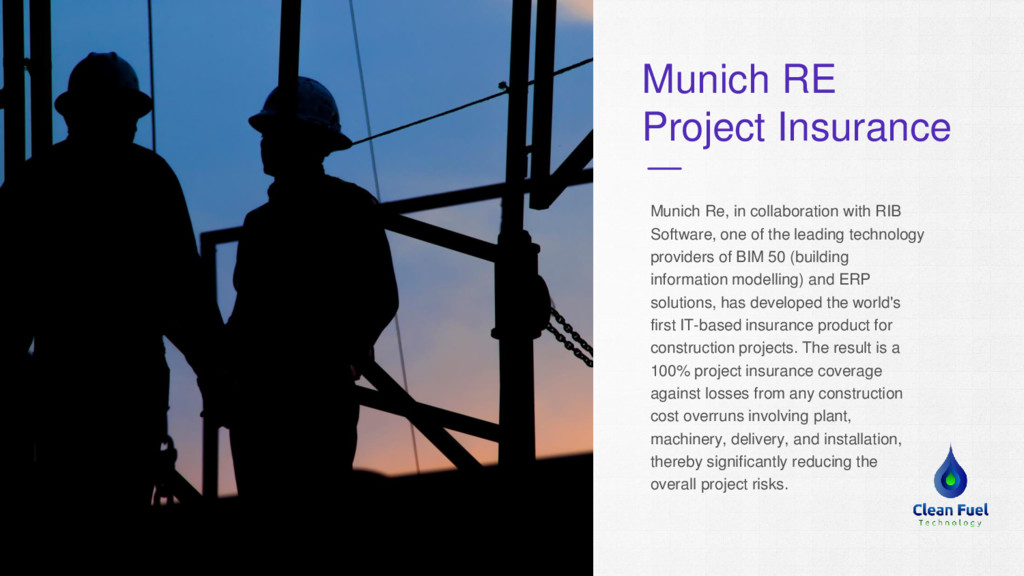
  18. Munich RE Project Insurance Munich Re, in collaboration with RIB

    Software, one of the leading technology providers of BIM 50 (building information modelling) and ERP solutions, has developed the world's first IT-based insurance product for construction projects. The result is a 100% project insurance coverage against losses from any construction cost overruns involving plant, machinery, delivery, and installation, thereby significantly reducing the overall project risks.
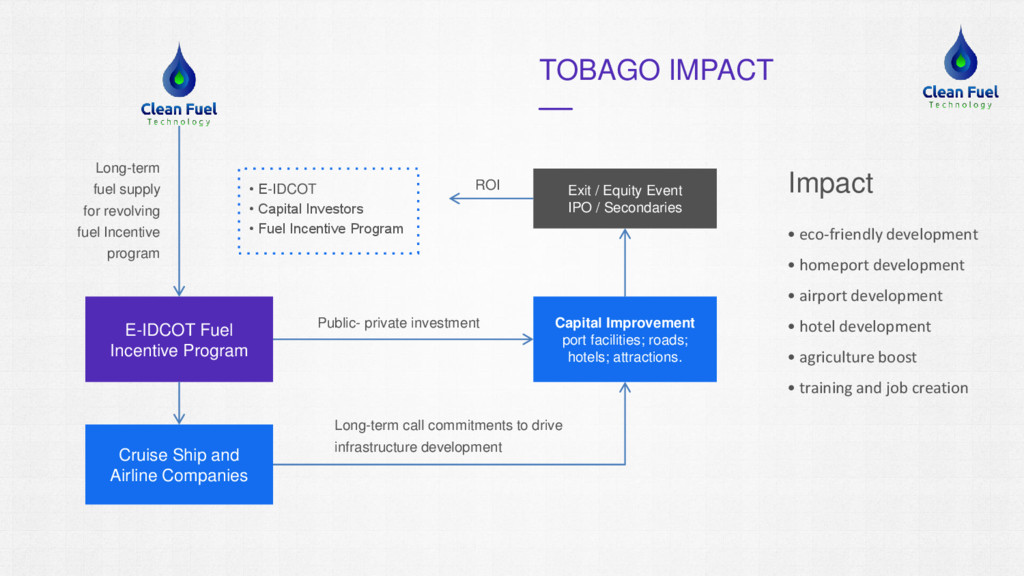
  19. Capital Improvement port facilities; roads; hotels; attractions. Cruise Ship and

    Airline Companies • E-IDCOT • Capital Investors • Fuel Incentive Program Impact Long-term fuel supply for revolving fuel Incentive program E-IDCOT Fuel Incentive Program TOBAGO IMPACT Exit / Equity Event IPO / Secondaries Long-term call commitments to drive infrastructure development Public- private investment ROI • eco-friendly development • homeport development • airport development • hotel development • agriculture boost • training and job creation