Upgrade to Pro — share decks privately, control downloads, hide ads and more …

5 Social-Media-Hacks, die dein Profil 2025 durc...

5 Social-Media-Hacks, die dein Profil 2025 durch die Decke gehen lassen

Also, du willst auf Social Media so richtig abheben, oder? Egal, ob du ein aufstrebender Influencer, ein kleiner Unternehmer oder einfach jemand bist, der sein Insta-Profil aufpolieren will – es kann sich anfühlen, als würdest du in ein schwarzes Loch schreien. Hier kommen Social-Media-Boosting-Dienste ins Spiel, quasi dein Turbo für mehr Aufmerksamkeit. Ich hab ein bisschen im Netz gestöbert, mir angeschaut, was seriös ist und was nicht, und eine Liste der Top 5 Dienste für 2025 zusammengestellt. Die sind echt top, kein Quatsch, und ich starte mit meinem Favoriten, weil er einfach so gut ist.

1. Fanexplosion – Der deutsche Champion für Social-Media-Wachstum

Los geht’s mit Fanexplosion. Dieser deutsche Anbieter ist seit 2019 am Start und macht keine halben Sachen. Was mir echt gefällt, ist, wie ehrlich die daherkommen – kein Bot-Mist, sondern Qualität. Sie bieten alles, von Instagram Follower kaufen bis TikTok-Views, und ihre Seite ist super transparent. Du kannst genau auswählen, was du brauchst, zum Beispiel „Deutsche Instagram Follower“ für den lokalen Vibe oder YouTube-Views, um deine Videos zu pushen. Die Lieferung ist schnell (meist in 24–72 Stunden), und sie haben eine lebenslange Nachfüllgarantie, was echt praktisch ist, falls mal ein paar Follower abfallen. Außerdem mag ich, dass sie keine Abos haben – einmal zahlen, fertig. Es fühlt sich an, als würden die wirklich wollen, dass du Erfolg hast, und nicht nur dein Geld. Perfekt für alle, die Qualität ohne Stress wollen.

2. SocialWick – Der globale Publikumsliebling

Als Nächstes haben wir SocialWick, ein großer Name in der Social-Media-Welt. Die sind bekannt für krasse Preise – z. B. 0,11 € für 10 Instagram-Follower, echt verrückt. Sie decken tonnenweise Plattformen ab, von Spotify-Streams bis Twitter-Likes, und liefern ziemlich schnell. Der Nachteil? Es fühlt sich manchmal etwas unpersönlich an, so als wärst du nur eine Nummer in ihrer riesigen Warteschlange. Trotzdem, wenn du einen schnellen Boost für kleines Geld suchst, sind die eine gute Wahl. Nur nicht erwarten, dass sie dir die Hand halten.

3. Followerfabrik – Der lokale Mitbewerber

Followerfabrik ist ein weiterer deutscher Anbieter mit einer treuen Fangemeinde (haha, Wortspiel). Die legen den Fokus auf Instagram und bieten Follower, Likes und Story-Views, vor allem mit „echten“ deutschen Nutzern. Ihre lebenslange Garantie ist ein Pluspunkt, und sie haben gute Bewertungen auf Seiten wie ProvenExpert. Aber ehrlich, ihre Webseite wirkt etwas hakelig im Vergleich zu anderen, und die Preise sind ein bisschen happig für das, was du kriegst. Gut, wenn du den deutschen Markt abzielst, aber vielleicht nicht so flexibel, wenn du global wachsen willst.

4. Followershark – Der Newcomer

Followershark ist noch ziemlich neu, macht aber schon ordentlich Wellen mit ihrer schicken Webseite und großen Versprechen. Sie konzentrieren sich auf Instagram und TikTok, bieten Follower und Likes zu fairen Preisen (ab 0,80 € für Insta-Follower). Sie setzen stark auf den „seriös“-Faktor, was beruhigend ist, aber ihre Erfolgsgeschichte ist noch nicht so lang wie bei anderen, also ein kleines Risiko. Wenn du Lust hast, einen frischen Dienst mit modernem Flair auszuprobieren, sind die einen Blick wert. Aber ich würd klein anfangen, um sie zu testen.

5. MediaMister – Der Alleskönner

Zum Schluss haben wir MediaMister, ein Dienst, der schon ewig existiert und quasi jede Plattform abdeckt – Instagram, YouTube, sogar LinkedIn. Sie sind zuverlässig, liefern schrittweise, damit es natürlich aussieht. Der Haken? Die Preise sind etwas höher, und der Prozess fühlt sich ein bisschen altmodisch an, so wie Bestellen aus einem Katalog. Trotzdem eine sichere Bank, wenn du einen All-in-one-Dienst für all deine Social-Media-Bedürfnisse suchst.

Avatar for Chris Den

Chris Den

June 26, 2025

More Decks by Chris Den

Other Decks in Technology

Transcript

  1. Hedge Fund Alpha The Best Stock Picks of The Best

    Hedge Funds Q2 2022 Issue:41 August 24, 2022 Inside This Issue 2 Best Performing HFs Strategy 3 Short Portfolio of Battleground Stocks 4 Investing Commentary: 6 In-depth Analysis of New Stock Picks 20 25 Billionaire Fund Managers 47 Most Popular Stocks Among Hedge Funds 53 Most Concentrated Positions Among Hedge Funds 55 High Conviction Picks of Value Hedge Funds 57 Concentrated High Conviction Hedge Fund Bets 58 Highlights From Hedge Fund Investor Letters Don’t pay hedge funds hefty fees when you can buy the best stock picks of best hedge fund managers at a fraction of what they charge Executive Summary We emailed this quarter’s stock picks on August 16th. Our Best Performing Hedge Funds Strategy gained 19.5% between May 17th and August 16th. We updated this strategy’s methodology 27 months ago. The new stock picks of this strategy are presented on page 2. Sixty six months ago we started using an additional indicator to potentially help us avoid high volatility stocks which may experience large losses. We have been saying that a portfolio of these popular stocks with high short interest can be used to hedge our long exposure. See page 3 for the new list of these battleground stocks with high short interest. We recommend that you should hedge at least 20% of your long exposure by shorting these stocks. These stocks gained 22.6% since February 2017, vs. 101.3% gain for the S&P 500 Index during the same period).
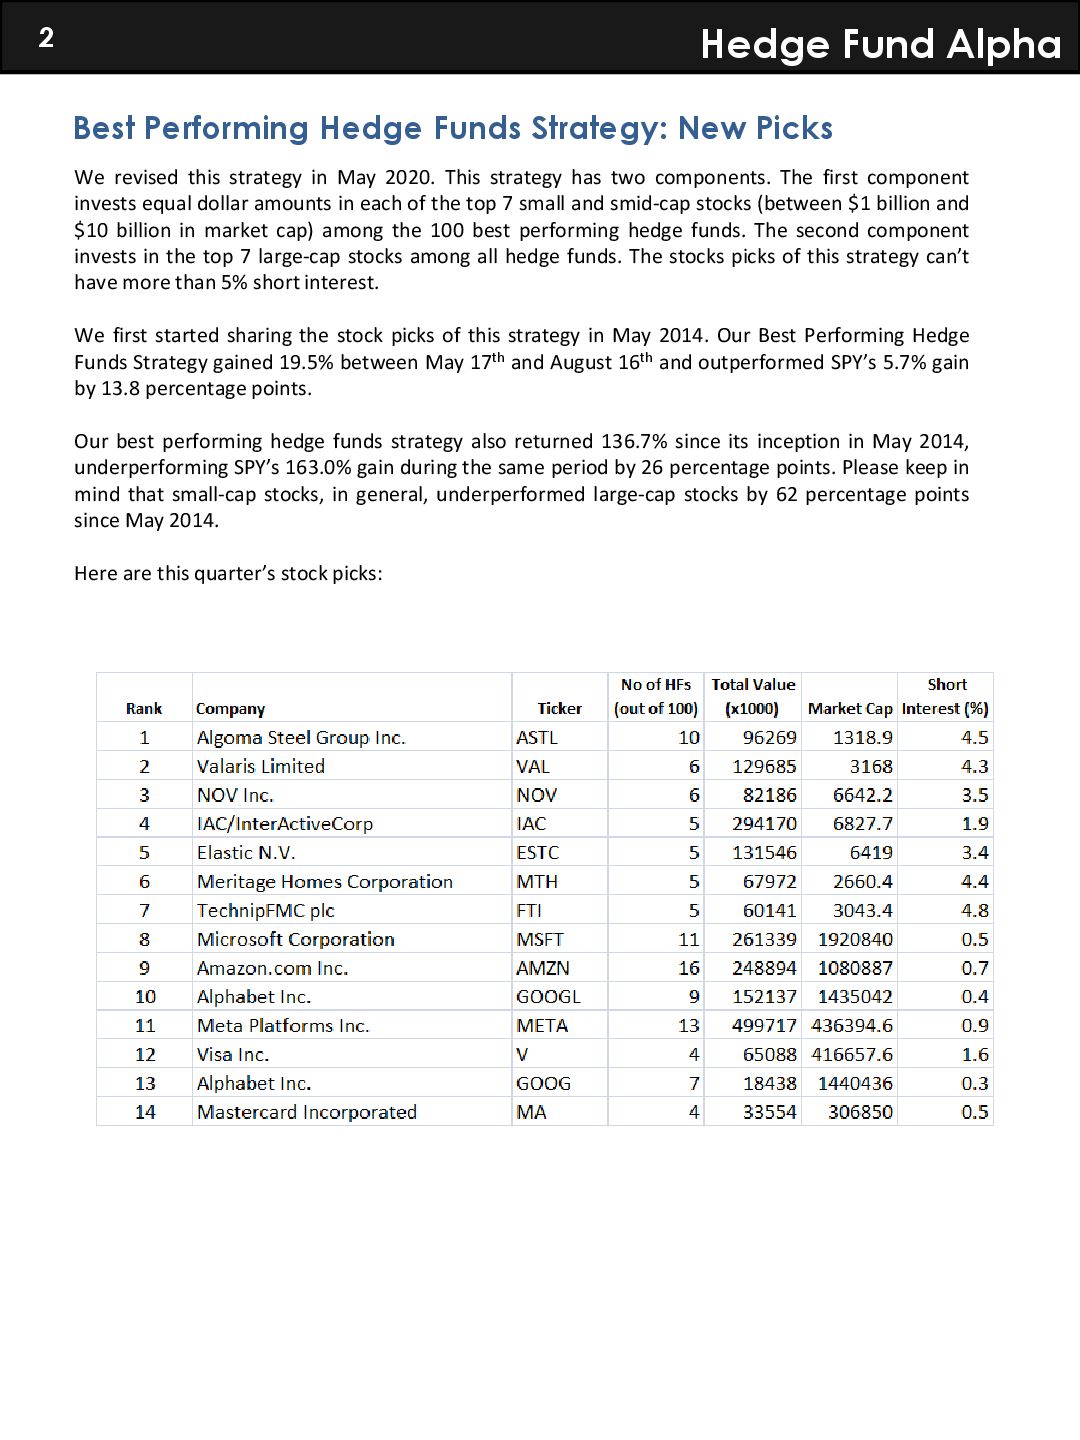
  2. Hedge Fund Alpha 2 Best Performing Hedge Funds Strategy: New

    Picks We revised this strategy in May 2020. This strategy has two components. The first component invests equal dollar amounts in each of the top 7 small and smid-cap stocks (between $1 billion and $10 billion in market cap) among the 100 best performing hedge funds. The second component invests in the top 7 large-cap stocks among all hedge funds. The stocks picks of this strategy can’t have more than 5% short interest. We first started sharing the stock picks of this strategy in May 2014. Our Best Performing Hedge Funds Strategy gained 19.5% between May 17th and August 16th and outperformed SPY’s 5.7% gain by 13.8 percentage points. Our best performing hedge funds strategy also returned 136.7% since its inception in May 2014, underperforming SPY’s 163.0% gain during the same period by 26 percentage points. Please keep in mind that small-cap stocks, in general, underperformed large-cap stocks by 62 percentage points since May 2014. Here are this quarter’s stock picks:
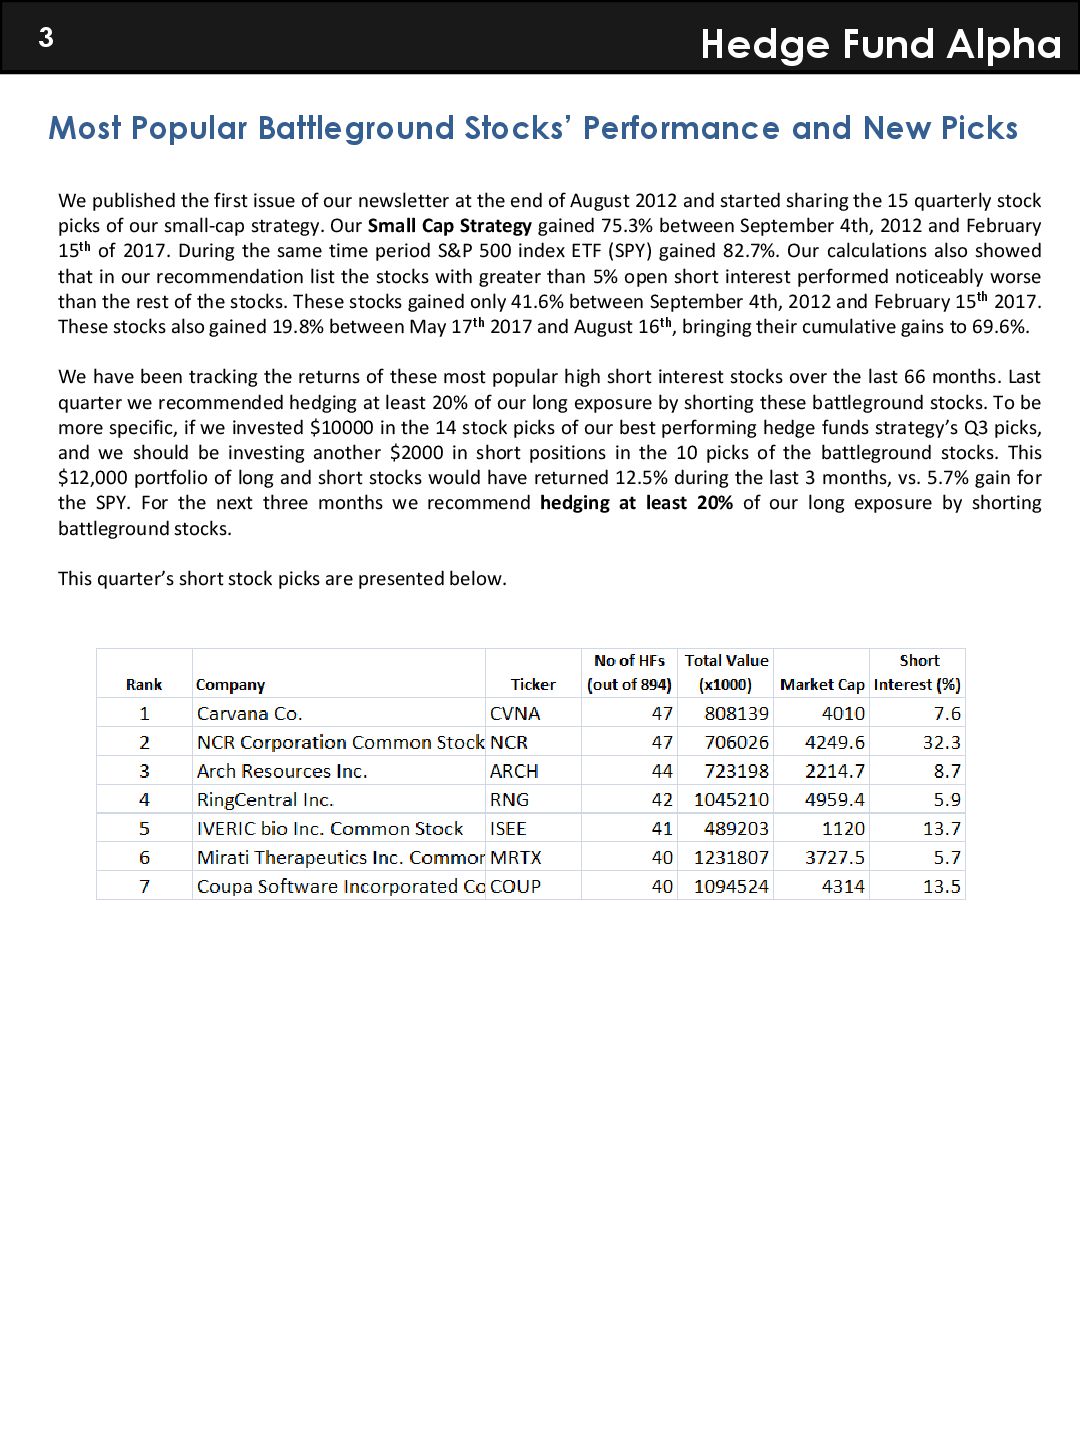
  3. Hedge Fund Alpha 3 Most Popular Battleground Stocks’ Performance and

    New Picks We published the first issue of our newsletter at the end of August 2012 and started sharing the 15 quarterly stock picks of our small-cap strategy. Our Small Cap Strategy gained 75.3% between September 4th, 2012 and February 15th of 2017. During the same time period S&P 500 index ETF (SPY) gained 82.7%. Our calculations also showed that in our recommendation list the stocks with greater than 5% open short interest performed noticeably worse than the rest of the stocks. These stocks gained only 41.6% between September 4th, 2012 and February 15th 2017. These stocks also gained 19.8% between May 17th 2017 and August 16th, bringing their cumulative gains to 69.6%. We have been tracking the returns of these most popular high short interest stocks over the last 66 months. Last quarter we recommended hedging at least 20% of our long exposure by shorting these battleground stocks. To be more specific, if we invested $10000 in the 14 stock picks of our best performing hedge funds strategy’s Q3 picks, and we should be investing another $2000 in short positions in the 10 picks of the battleground stocks. This $12,000 portfolio of long and short stocks would have returned 12.5% during the last 3 months, vs. 5.7% gain for the SPY. For the next three months we recommend hedging at least 20% of our long exposure by shorting battleground stocks. This quarter’s short stock picks are presented below.
  4. Hedge Fund Alpha 4 Investing Commentary from Dr. Inan Dogan

    Rules based investing is getting harder by the day. When I started developing my first quantitative investment strategies using insider trading data 20 years ago, historical stock market data told us that small-cap stocks outperform large-cap stocks and value stocks outperform growth stocks over long periods of time. During the last 7 years seasoned fund managers were baffled as large-cap growth stocks absolutely killed small-cap value stocks. In our quarterly newsletter we use “quantitative rules” to identify the best stocks to buy using hedge fund holdings data. Our initial strategy worked beautifully until 2016. At the beginning of 2017 we took action and revised our methodology by incorporating hedge funds’ short interest in each stock. At the same time we also launched a new “judgment-based” investment strategy in our monthly newsletter. Instead of strict quantitative rules that determine when we should buy and sell a stock, I personally analyzed each investment idea and made buy/sell recommendations in our monthly newsletter. Our monthly newsletter’s portfolio of stock picks returned 156.6% since March 2017 and beat the S&P 500 ETFs by 67 percentage points. One important thing I did differently in our monthly newsletter is that I became very patient with each investment idea and didn’t easily sell stocks that performed well in our portfolio. This made a huge difference in terms of performance. Another change we made was changing our beta exposure based on our market outlook. For example we started shorting the S&P 500 Index in February 2020 right before the coronavirus pandemic started. We covered our short positions at the end of March 2020 and these actions helped us turn potentially large losses into large gains. At the end of this March we started shorting the S&P 500 ETF (SPY) and liquidating some of our positions. Currently our net beta exposure in our monthly newsletter’s portfolio is around 50%. I believe the probability of a US recession is around 50% right now. Long-term interest rates are around 3.05% today. If these rates go above 3.5% and stay there for a few months, I believe we will experience a recession and this will lead the S&P 500 Index fall below the 3250 level. There is a very narrow path that the Federal Reserve may accomplish a soft landing and we avoid recession. The market has been pricing in this possibility since the end of June and rose briefly above 4300. We haven’t made any changes to our opinion and stock recommendations despite the sentiment shift in the market. We never doubted that inflation in the US will come down. The question is whether the Fed can bring the inflation rate down to 3% (or below) without raising the short-term interest rates near 4%. US 2-year Treasury bonds yield 3.33% right now. We believe there is a decent possibility that this will rise above 3.75% in the coming months. That’s why we haven’t made any changes to our net exposure. This is a short-term bearish call and we may be wrong. We expect the US stocks deliver an average annual gain of 7-8% over the long-term. That’s why our net exposure is still a positive 50% despite we are pessimistic about the very short-term. We now have a 5+ year track record of actively picking stocks and managing our market exposure. S&P 500 ETFs returned around 73% during this period. Our portfolio of stock picks returned more than 147%. We outperformed the market in every year since 2017 except 2021. So far this year we are ahead of SPY. If you aren’t already subscribed to our monthly newsletter, please get in touch with us.
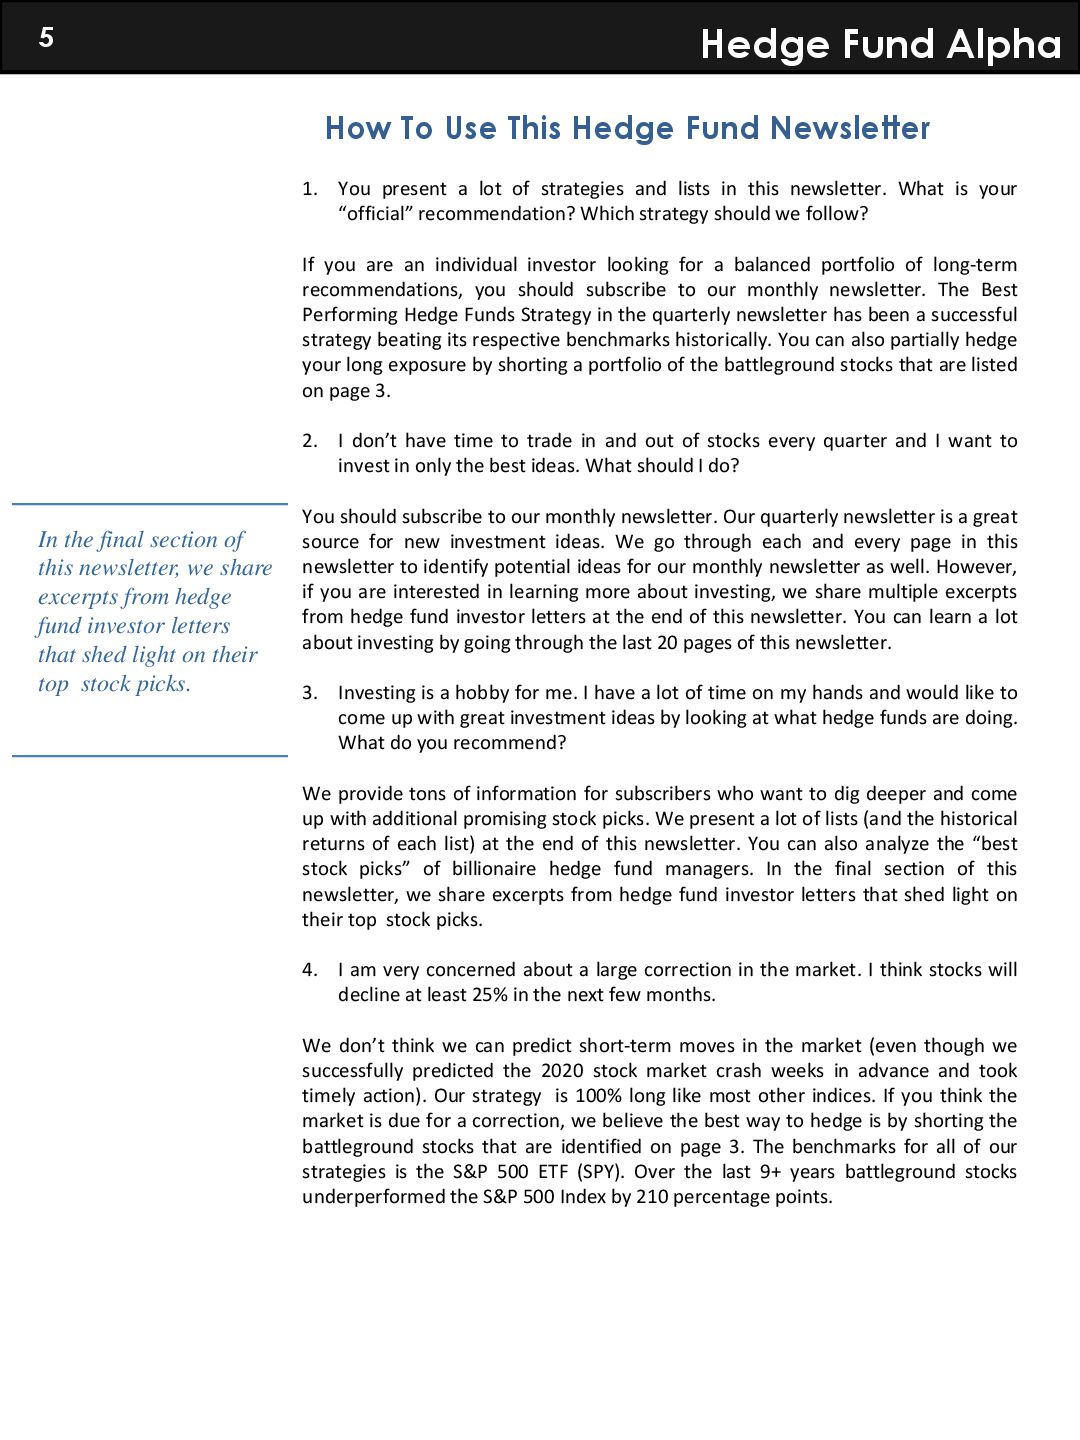
  5. Hedge Fund Alpha 5 How To Use This Hedge Fund

    Newsletter In the final section of this newsletter, we share excerpts from hedge fund investor letters that shed light on their top stock picks. 1. You present a lot of strategies and lists in this newsletter. What is your “official” recommendation? Which strategy should we follow? If you are an individual investor looking for a balanced portfolio of long-term recommendations, you should subscribe to our monthly newsletter. The Best Performing Hedge Funds Strategy in the quarterly newsletter has been a successful strategy beating its respective benchmarks historically. You can also partially hedge your long exposure by shorting a portfolio of the battleground stocks that are listed on page 3. 2. I don’t have time to trade in and out of stocks every quarter and I want to invest in only the best ideas. What should I do? You should subscribe to our monthly newsletter. Our quarterly newsletter is a great source for new investment ideas. We go through each and every page in this newsletter to identify potential ideas for our monthly newsletter as well. However, if you are interested in learning more about investing, we share multiple excerpts from hedge fund investor letters at the end of this newsletter. You can learn a lot about investing by going through the last 20 pages of this newsletter. 3. Investing is a hobby for me. I have a lot of time on my hands and would like to come up with great investment ideas by looking at what hedge funds are doing. What do you recommend? We provide tons of information for subscribers who want to dig deeper and come up with additional promising stock picks. We present a lot of lists (and the historical returns of each list) at the end of this newsletter. You can also analyze the “best stock picks” of billionaire hedge fund managers. In the final section of this newsletter, we share excerpts from hedge fund investor letters that shed light on their top stock picks. 4. I am very concerned about a large correction in the market. I think stocks will decline at least 25% in the next few months. We don’t think we can predict short-term moves in the market (even though we successfully predicted the 2020 stock market crash weeks in advance and took timely action). Our strategy is 100% long like most other indices. If you think the market is due for a correction, we believe the best way to hedge is by shorting the battleground stocks that are identified on page 3. The benchmarks for all of our strategies is the S&P 500 ETF (SPY). Over the last 9+ years battleground stocks underperformed the S&P 500 Index by 210 percentage points.
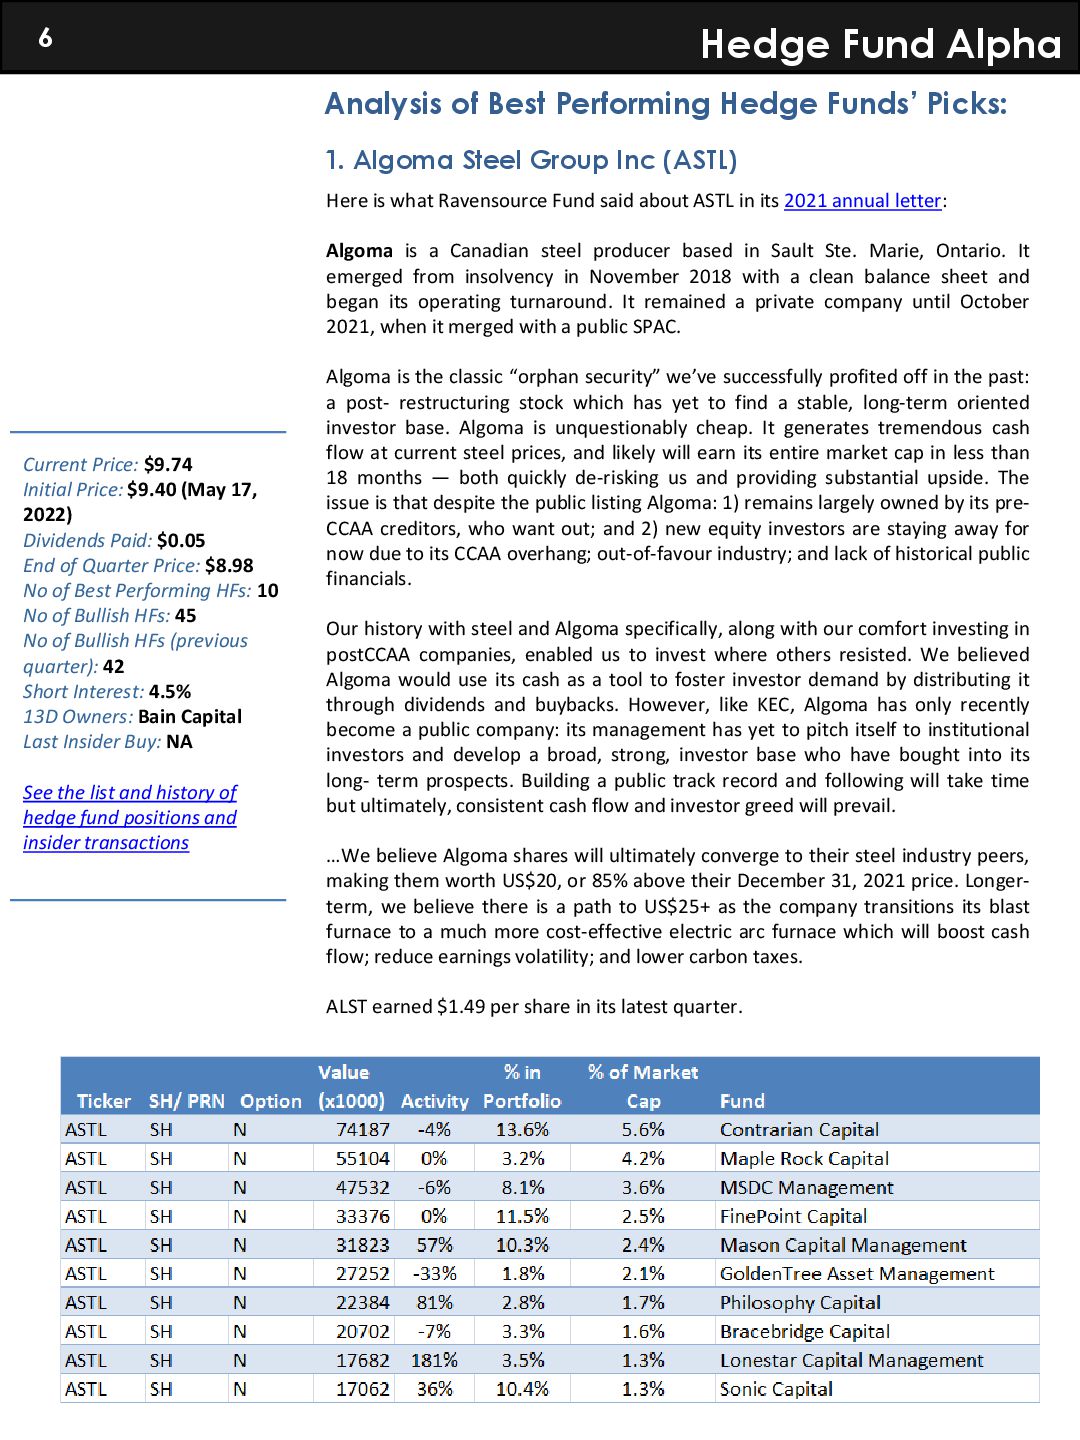
  6. Hedge Fund Alpha 6 Analysis of Best Performing Hedge Funds’

    Picks: 1. Algoma Steel Group Inc (ASTL) Current Price: $9.74 Initial Price: $9.40 (May 17, 2022) Dividends Paid: $0.05 End of Quarter Price: $8.98 No of Best Performing HFs: 10 No of Bullish HFs: 45 No of Bullish HFs (previous quarter): 42 Short Interest: 4.5% 13D Owners: Bain Capital Last Insider Buy: NA See the list and history of hedge fund positions and insider transactions Here is what Ravensource Fund said about ASTL in its 2021 annual letter: Algoma is a Canadian steel producer based in Sault Ste. Marie, Ontario. It emerged from insolvency in November 2018 with a clean balance sheet and began its operating turnaround. It remained a private company until October 2021, when it merged with a public SPAC. Algoma is the classic “orphan security” we’ve successfully profited off in the past: a post- restructuring stock which has yet to find a stable, long-term oriented investor base. Algoma is unquestionably cheap. It generates tremendous cash flow at current steel prices, and likely will earn its entire market cap in less than 18 months — both quickly de-risking us and providing substantial upside. The issue is that despite the public listing Algoma: 1) remains largely owned by its pre- CCAA creditors, who want out; and 2) new equity investors are staying away for now due to its CCAA overhang; out-of-favour industry; and lack of historical public financials. Our history with steel and Algoma specifically, along with our comfort investing in postCCAA companies, enabled us to invest where others resisted. We believed Algoma would use its cash as a tool to foster investor demand by distributing it through dividends and buybacks. However, like KEC, Algoma has only recently become a public company: its management has yet to pitch itself to institutional investors and develop a broad, strong, investor base who have bought into its long- term prospects. Building a public track record and following will take time but ultimately, consistent cash flow and investor greed will prevail. …We believe Algoma shares will ultimately converge to their steel industry peers, making them worth US$20, or 85% above their December 31, 2021 price. Longer- term, we believe there is a path to US$25+ as the company transitions its blast furnace to a much more cost-effective electric arc furnace which will boost cash flow; reduce earnings volatility; and lower carbon taxes. ALST earned $1.49 per share in its latest quarter.
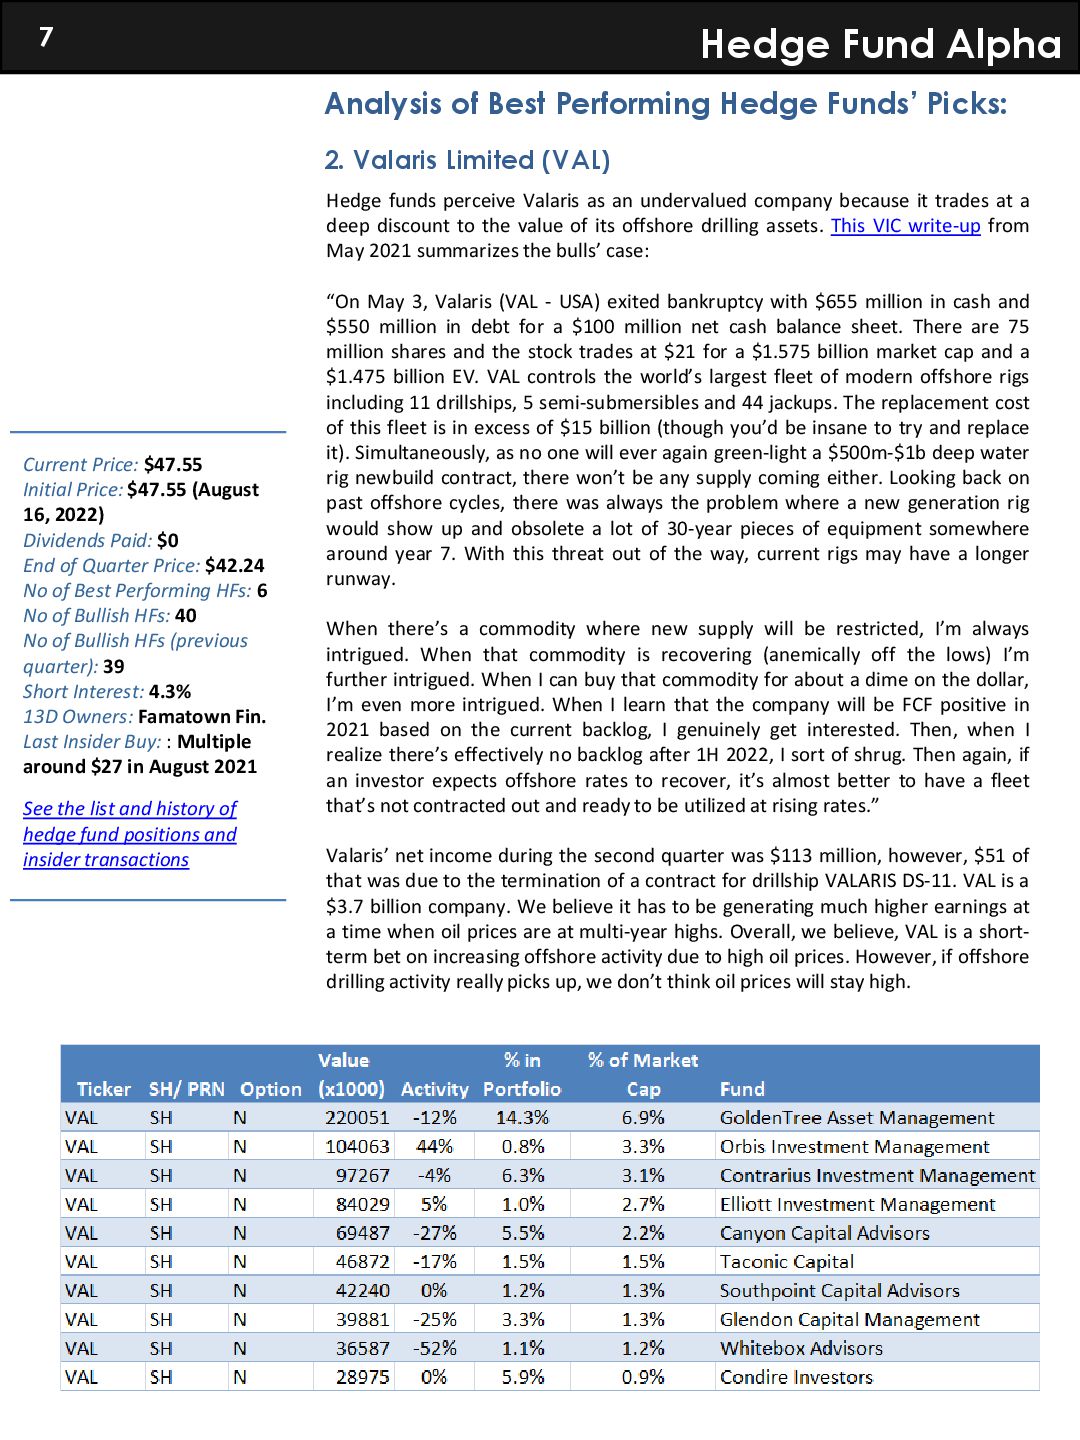
  7. Hedge Fund Alpha 7 Analysis of Best Performing Hedge Funds’

    Picks: 2. Valaris Limited (VAL) Current Price: $47.55 Initial Price: $47.55 (August 16, 2022) Dividends Paid: $0 End of Quarter Price: $42.24 No of Best Performing HFs: 6 No of Bullish HFs: 40 No of Bullish HFs (previous quarter): 39 Short Interest: 4.3% 13D Owners: Famatown Fin. Last Insider Buy: : Multiple around $27 in August 2021 See the list and history of hedge fund positions and insider transactions Hedge funds perceive Valaris as an undervalued company because it trades at a deep discount to the value of its offshore drilling assets. This VIC write-up from May 2021 summarizes the bulls’ case: “On May 3, Valaris (VAL - USA) exited bankruptcy with $655 million in cash and $550 million in debt for a $100 million net cash balance sheet. There are 75 million shares and the stock trades at $21 for a $1.575 billion market cap and a $1.475 billion EV. VAL controls the world’s largest fleet of modern offshore rigs including 11 drillships, 5 semi-submersibles and 44 jackups. The replacement cost of this fleet is in excess of $15 billion (though you’d be insane to try and replace it). Simultaneously, as no one will ever again green-light a $500m-$1b deep water rig newbuild contract, there won’t be any supply coming either. Looking back on past offshore cycles, there was always the problem where a new generation rig would show up and obsolete a lot of 30-year pieces of equipment somewhere around year 7. With this threat out of the way, current rigs may have a longer runway. When there’s a commodity where new supply will be restricted, I’m always intrigued. When that commodity is recovering (anemically off the lows) I’m further intrigued. When I can buy that commodity for about a dime on the dollar, I’m even more intrigued. When I learn that the company will be FCF positive in 2021 based on the current backlog, I genuinely get interested. Then, when I realize there’s effectively no backlog after 1H 2022, I sort of shrug. Then again, if an investor expects offshore rates to recover, it’s almost better to have a fleet that’s not contracted out and ready to be utilized at rising rates.” Valaris’ net income during the second quarter was $113 million, however, $51 of that was due to the termination of a contract for drillship VALARIS DS-11. VAL is a $3.7 billion company. We believe it has to be generating much higher earnings at a time when oil prices are at multi-year highs. Overall, we believe, VAL is a short- term bet on increasing offshore activity due to high oil prices. However, if offshore drilling activity really picks up, we don’t think oil prices will stay high.
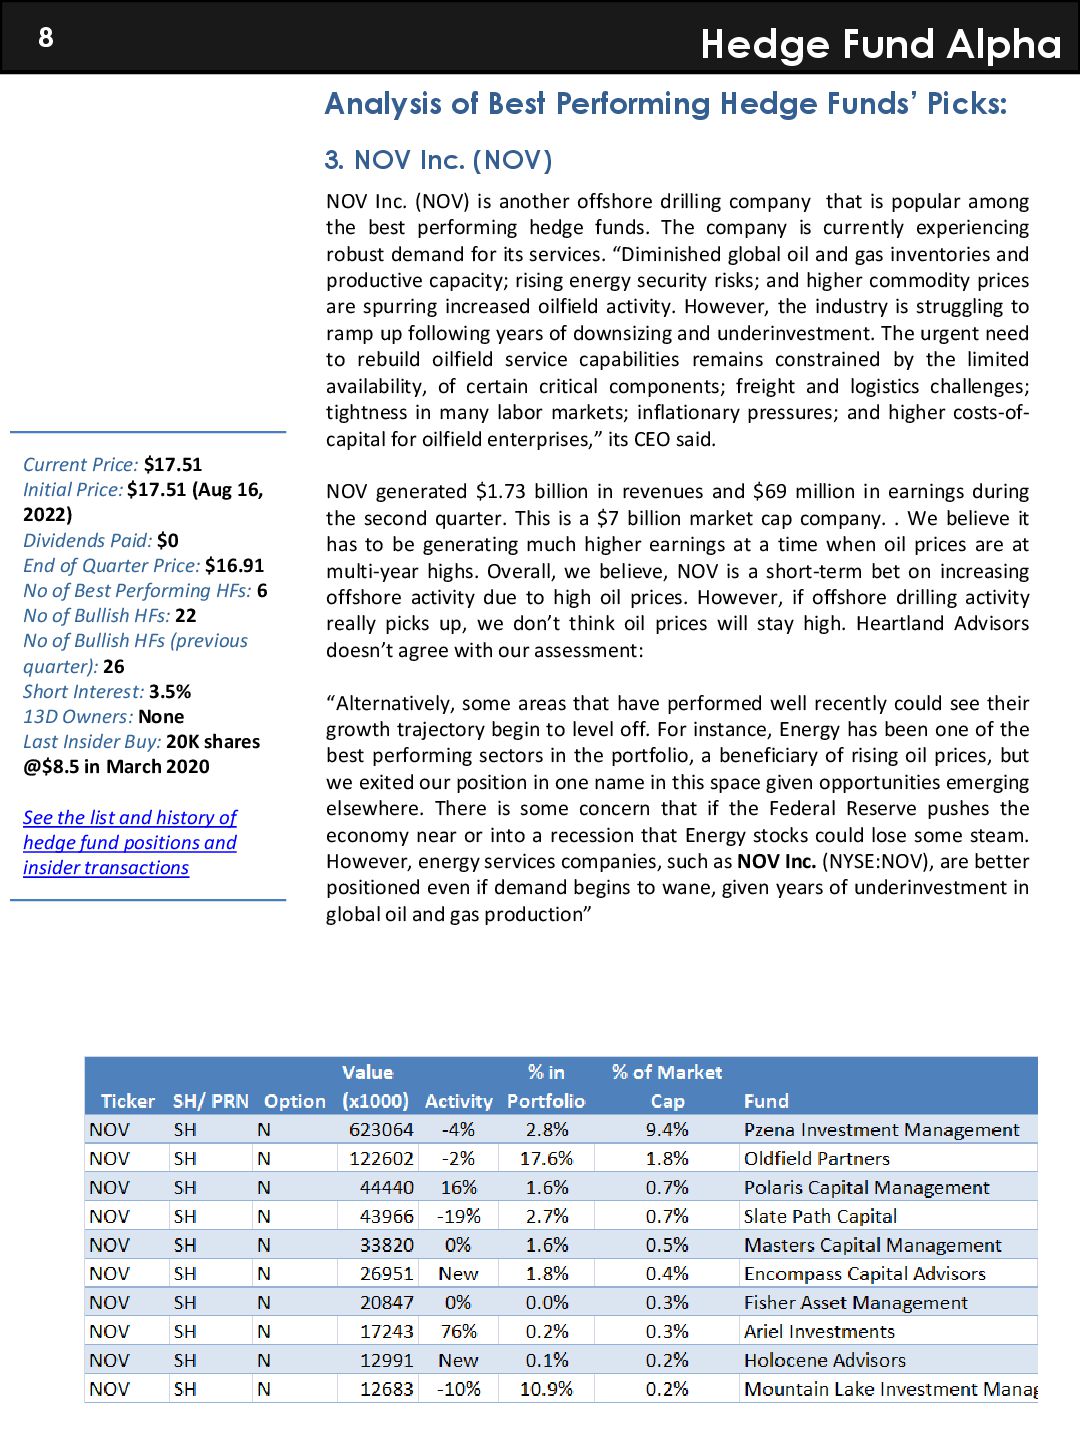
  8. Hedge Fund Alpha 8 Analysis of Best Performing Hedge Funds’

    Picks: 3. NOV Inc. (NOV) Current Price: $17.51 Initial Price: $17.51 (Aug 16, 2022) Dividends Paid: $0 End of Quarter Price: $16.91 No of Best Performing HFs: 6 No of Bullish HFs: 22 No of Bullish HFs (previous quarter): 26 Short Interest: 3.5% 13D Owners: None Last Insider Buy: 20K shares @$8.5 in March 2020 See the list and history of hedge fund positions and insider transactions NOV Inc. (NOV) is another offshore drilling company that is popular among the best performing hedge funds. The company is currently experiencing robust demand for its services. “Diminished global oil and gas inventories and productive capacity; rising energy security risks; and higher commodity prices are spurring increased oilfield activity. However, the industry is struggling to ramp up following years of downsizing and underinvestment. The urgent need to rebuild oilfield service capabilities remains constrained by the limited availability, of certain critical components; freight and logistics challenges; tightness in many labor markets; inflationary pressures; and higher costs-of- capital for oilfield enterprises,” its CEO said. NOV generated $1.73 billion in revenues and $69 million in earnings during the second quarter. This is a $7 billion market cap company. . We believe it has to be generating much higher earnings at a time when oil prices are at multi-year highs. Overall, we believe, NOV is a short-term bet on increasing offshore activity due to high oil prices. However, if offshore drilling activity really picks up, we don’t think oil prices will stay high. Heartland Advisors doesn’t agree with our assessment: “Alternatively, some areas that have performed well recently could see their growth trajectory begin to level off. For instance, Energy has been one of the best performing sectors in the portfolio, a beneficiary of rising oil prices, but we exited our position in one name in this space given opportunities emerging elsewhere. There is some concern that if the Federal Reserve pushes the economy near or into a recession that Energy stocks could lose some steam. However, energy services companies, such as NOV Inc. (NYSE:NOV), are better positioned even if demand begins to wane, given years of underinvestment in global oil and gas production”
  9. Hedge Fund Alpha 9 Analysis of Best Performing Hedge Funds’

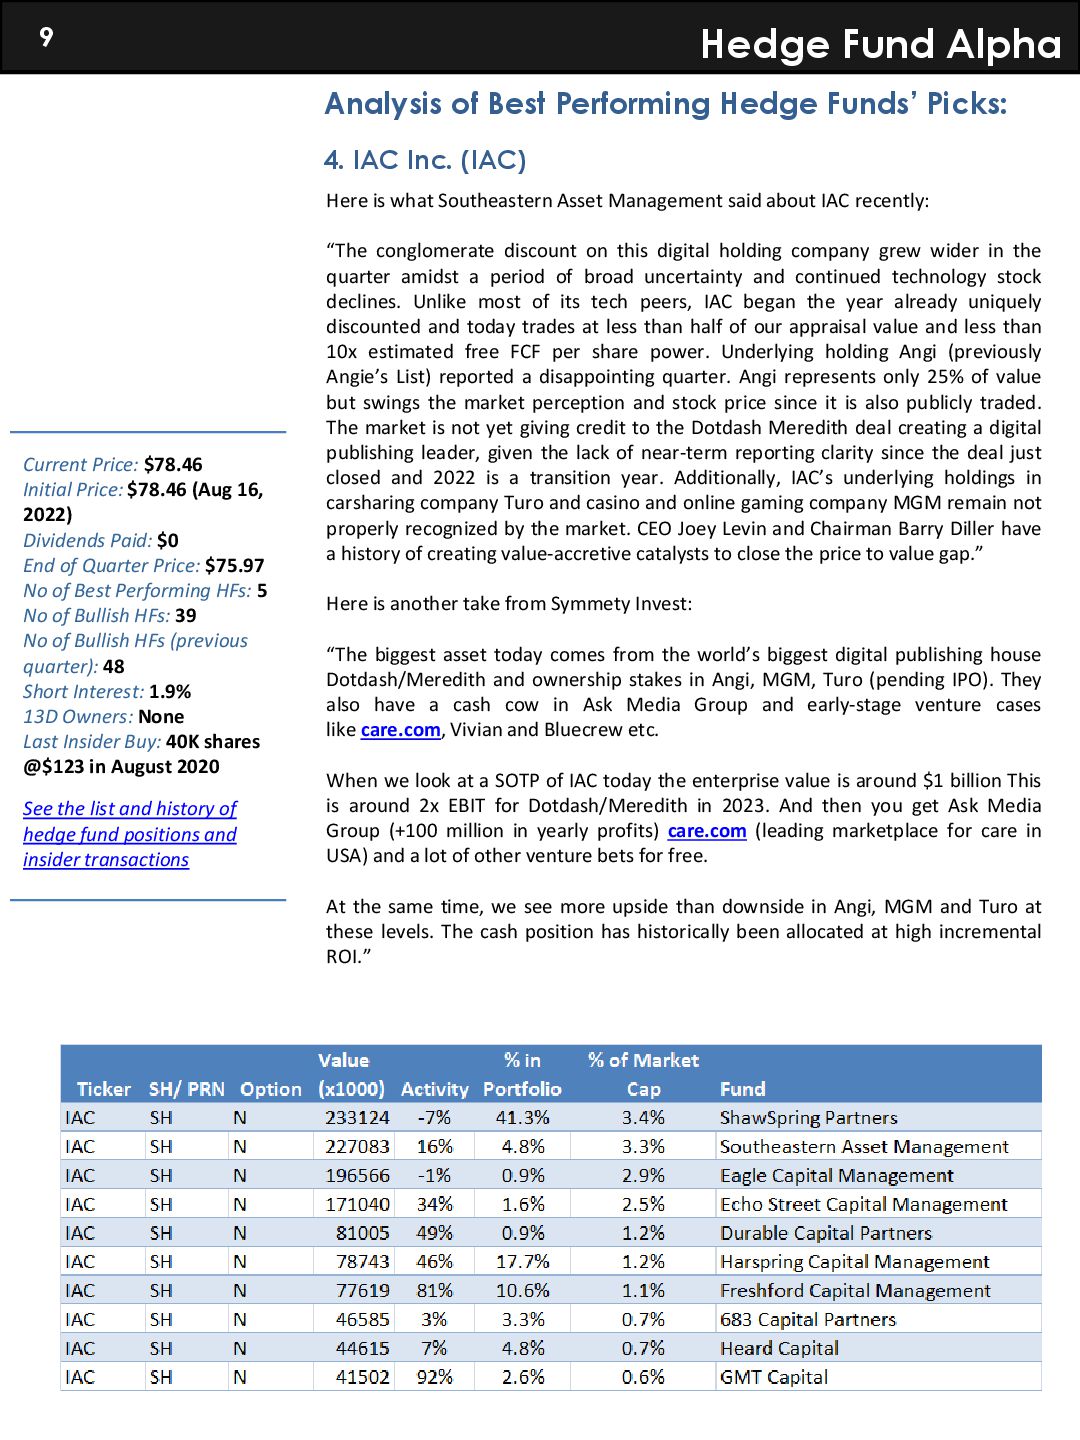
    Picks: 4. IAC Inc. (IAC) Current Price: $78.46 Initial Price: $78.46 (Aug 16, 2022) Dividends Paid: $0 End of Quarter Price: $75.97 No of Best Performing HFs: 5 No of Bullish HFs: 39 No of Bullish HFs (previous quarter): 48 Short Interest: 1.9% 13D Owners: None Last Insider Buy: 40K shares @$123 in August 2020 See the list and history of hedge fund positions and insider transactions Here is what Southeastern Asset Management said about IAC recently: “The conglomerate discount on this digital holding company grew wider in the quarter amidst a period of broad uncertainty and continued technology stock declines. Unlike most of its tech peers, IAC began the year already uniquely discounted and today trades at less than half of our appraisal value and less than 10x estimated free FCF per share power. Underlying holding Angi (previously Angie’s List) reported a disappointing quarter. Angi represents only 25% of value but swings the market perception and stock price since it is also publicly traded. The market is not yet giving credit to the Dotdash Meredith deal creating a digital publishing leader, given the lack of near-term reporting clarity since the deal just closed and 2022 is a transition year. Additionally, IAC’s underlying holdings in carsharing company Turo and casino and online gaming company MGM remain not properly recognized by the market. CEO Joey Levin and Chairman Barry Diller have a history of creating value-accretive catalysts to close the price to value gap.” Here is another take from Symmety Invest: “The biggest asset today comes from the world’s biggest digital publishing house Dotdash/Meredith and ownership stakes in Angi, MGM, Turo (pending IPO). They also have a cash cow in Ask Media Group and early-stage venture cases like care.com, Vivian and Bluecrew etc. When we look at a SOTP of IAC today the enterprise value is around $1 billion This is around 2x EBIT for Dotdash/Meredith in 2023. And then you get Ask Media Group (+100 million in yearly profits) care.com (leading marketplace for care in USA) and a lot of other venture bets for free. At the same time, we see more upside than downside in Angi, MGM and Turo at these levels. The cash position has historically been allocated at high incremental ROI.”
  10. Hedge Fund Alpha 10 Analysis of Best Performing Hedge Funds’

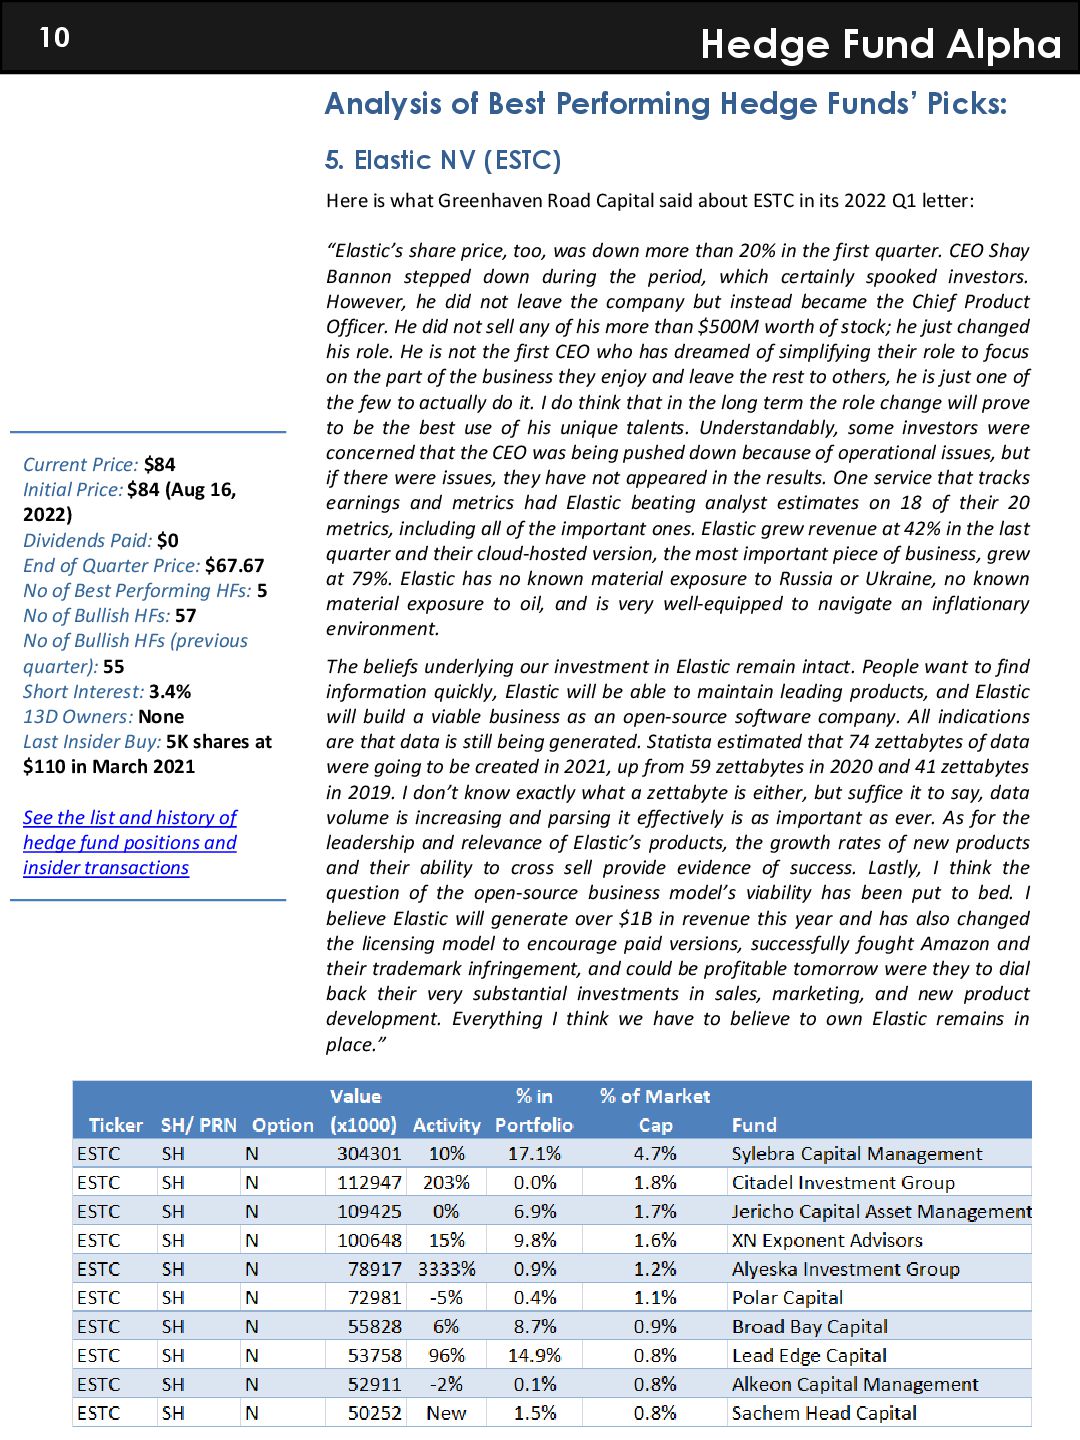
    Picks: 5. Elastic NV (ESTC) Current Price: $84 Initial Price: $84 (Aug 16, 2022) Dividends Paid: $0 End of Quarter Price: $67.67 No of Best Performing HFs: 5 No of Bullish HFs: 57 No of Bullish HFs (previous quarter): 55 Short Interest: 3.4% 13D Owners: None Last Insider Buy: 5K shares at $110 in March 2021 See the list and history of hedge fund positions and insider transactions Here is what Greenhaven Road Capital said about ESTC in its 2022 Q1 letter: “Elastic’s share price, too, was down more than 20% in the first quarter. CEO Shay Bannon stepped down during the period, which certainly spooked investors. However, he did not leave the company but instead became the Chief Product Officer. He did not sell any of his more than $500M worth of stock; he just changed his role. He is not the first CEO who has dreamed of simplifying their role to focus on the part of the business they enjoy and leave the rest to others, he is just one of the few to actually do it. I do think that in the long term the role change will prove to be the best use of his unique talents. Understandably, some investors were concerned that the CEO was being pushed down because of operational issues, but if there were issues, they have not appeared in the results. One service that tracks earnings and metrics had Elastic beating analyst estimates on 18 of their 20 metrics, including all of the important ones. Elastic grew revenue at 42% in the last quarter and their cloud-hosted version, the most important piece of business, grew at 79%. Elastic has no known material exposure to Russia or Ukraine, no known material exposure to oil, and is very well-equipped to navigate an inflationary environment. The beliefs underlying our investment in Elastic remain intact. People want to find information quickly, Elastic will be able to maintain leading products, and Elastic will build a viable business as an open-source software company. All indications are that data is still being generated. Statista estimated that 74 zettabytes of data were going to be created in 2021, up from 59 zettabytes in 2020 and 41 zettabytes in 2019. I don’t know exactly what a zettabyte is either, but suffice it to say, data volume is increasing and parsing it effectively is as important as ever. As for the leadership and relevance of Elastic’s products, the growth rates of new products and their ability to cross sell provide evidence of success. Lastly, I think the question of the open-source business model’s viability has been put to bed. I believe Elastic will generate over $1B in revenue this year and has also changed the licensing model to encourage paid versions, successfully fought Amazon and their trademark infringement, and could be profitable tomorrow were they to dial back their very substantial investments in sales, marketing, and new product development. Everything I think we have to believe to own Elastic remains in place.”
  11. Hedge Fund Alpha 11 Analysis of Best Performing Hedge Funds’

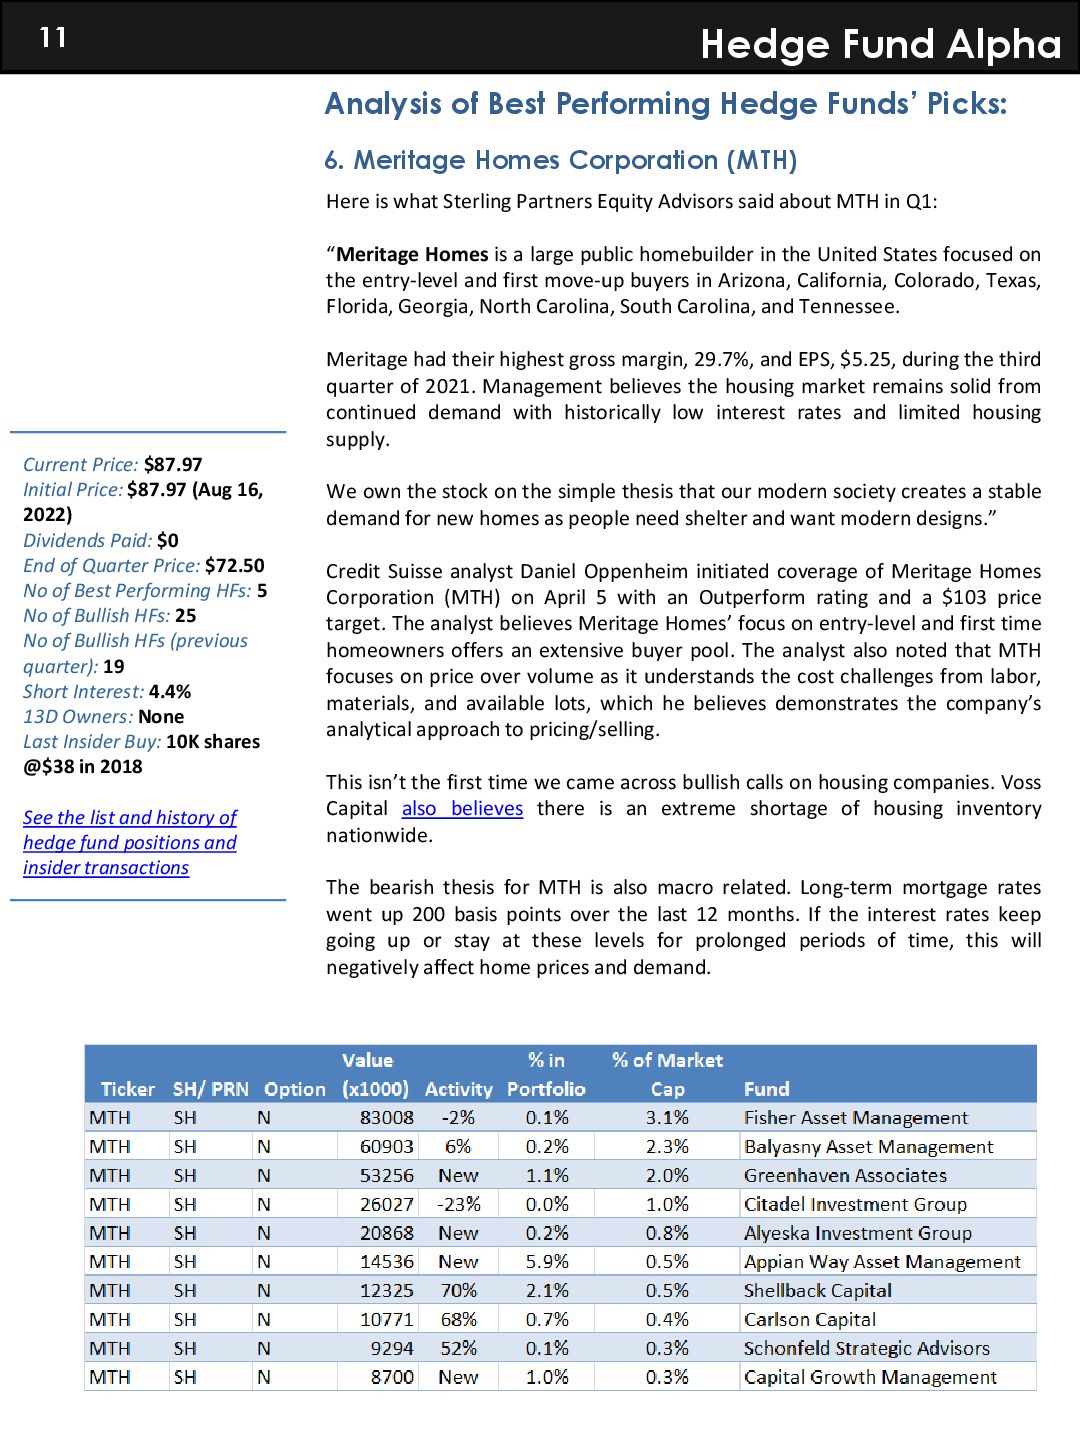
    Picks: 6. Meritage Homes Corporation (MTH) Current Price: $87.97 Initial Price: $87.97 (Aug 16, 2022) Dividends Paid: $0 End of Quarter Price: $72.50 No of Best Performing HFs: 5 No of Bullish HFs: 25 No of Bullish HFs (previous quarter): 19 Short Interest: 4.4% 13D Owners: None Last Insider Buy: 10K shares @$38 in 2018 See the list and history of hedge fund positions and insider transactions Here is what Sterling Partners Equity Advisors said about MTH in Q1: “Meritage Homes is a large public homebuilder in the United States focused on the entry-level and first move-up buyers in Arizona, California, Colorado, Texas, Florida, Georgia, North Carolina, South Carolina, and Tennessee. Meritage had their highest gross margin, 29.7%, and EPS, $5.25, during the third quarter of 2021. Management believes the housing market remains solid from continued demand with historically low interest rates and limited housing supply. We own the stock on the simple thesis that our modern society creates a stable demand for new homes as people need shelter and want modern designs.” Credit Suisse analyst Daniel Oppenheim initiated coverage of Meritage Homes Corporation (MTH) on April 5 with an Outperform rating and a $103 price target. The analyst believes Meritage Homes’ focus on entry-level and first time homeowners offers an extensive buyer pool. The analyst also noted that MTH focuses on price over volume as it understands the cost challenges from labor, materials, and available lots, which he believes demonstrates the company’s analytical approach to pricing/selling. This isn’t the first time we came across bullish calls on housing companies. Voss Capital also believes there is an extreme shortage of housing inventory nationwide. The bearish thesis for MTH is also macro related. Long-term mortgage rates went up 200 basis points over the last 12 months. If the interest rates keep going up or stay at these levels for prolonged periods of time, this will negatively affect home prices and demand.
  12. Hedge Fund Alpha 12 Analysis of Best Performing Hedge Funds’

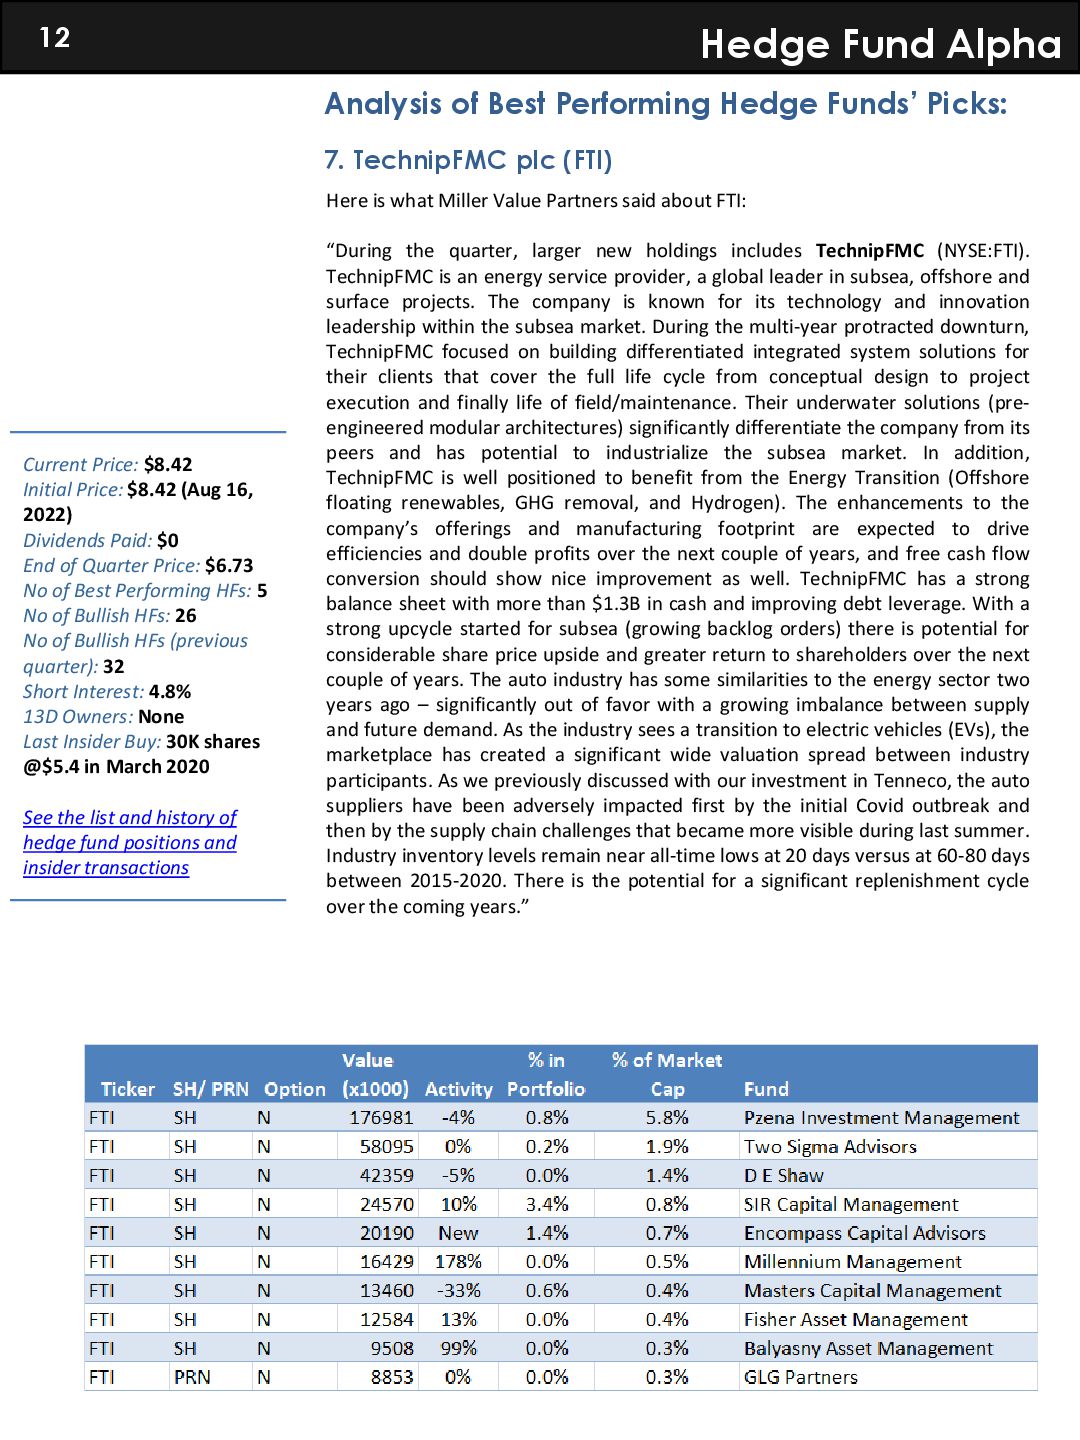
    Picks: 7. TechnipFMC plc (FTI) Current Price: $8.42 Initial Price: $8.42 (Aug 16, 2022) Dividends Paid: $0 End of Quarter Price: $6.73 No of Best Performing HFs: 5 No of Bullish HFs: 26 No of Bullish HFs (previous quarter): 32 Short Interest: 4.8% 13D Owners: None Last Insider Buy: 30K shares @$5.4 in March 2020 See the list and history of hedge fund positions and insider transactions Here is what Miller Value Partners said about FTI: “During the quarter, larger new holdings includes TechnipFMC (NYSE:FTI). TechnipFMC is an energy service provider, a global leader in subsea, offshore and surface projects. The company is known for its technology and innovation leadership within the subsea market. During the multi-year protracted downturn, TechnipFMC focused on building differentiated integrated system solutions for their clients that cover the full life cycle from conceptual design to project execution and finally life of field/maintenance. Their underwater solutions (pre- engineered modular architectures) significantly differentiate the company from its peers and has potential to industrialize the subsea market. In addition, TechnipFMC is well positioned to benefit from the Energy Transition (Offshore floating renewables, GHG removal, and Hydrogen). The enhancements to the company’s offerings and manufacturing footprint are expected to drive efficiencies and double profits over the next couple of years, and free cash flow conversion should show nice improvement as well. TechnipFMC has a strong balance sheet with more than $1.3B in cash and improving debt leverage. With a strong upcycle started for subsea (growing backlog orders) there is potential for considerable share price upside and greater return to shareholders over the next couple of years. The auto industry has some similarities to the energy sector two years ago – significantly out of favor with a growing imbalance between supply and future demand. As the industry sees a transition to electric vehicles (EVs), the marketplace has created a significant wide valuation spread between industry participants. As we previously discussed with our investment in Tenneco, the auto suppliers have been adversely impacted first by the initial Covid outbreak and then by the supply chain challenges that became more visible during last summer. Industry inventory levels remain near all-time lows at 20 days versus at 60-80 days between 2015-2020. There is the potential for a significant replenishment cycle over the coming years.”
  13. Hedge Fund Alpha 13 Analysis of Best Performing Hedge Funds’

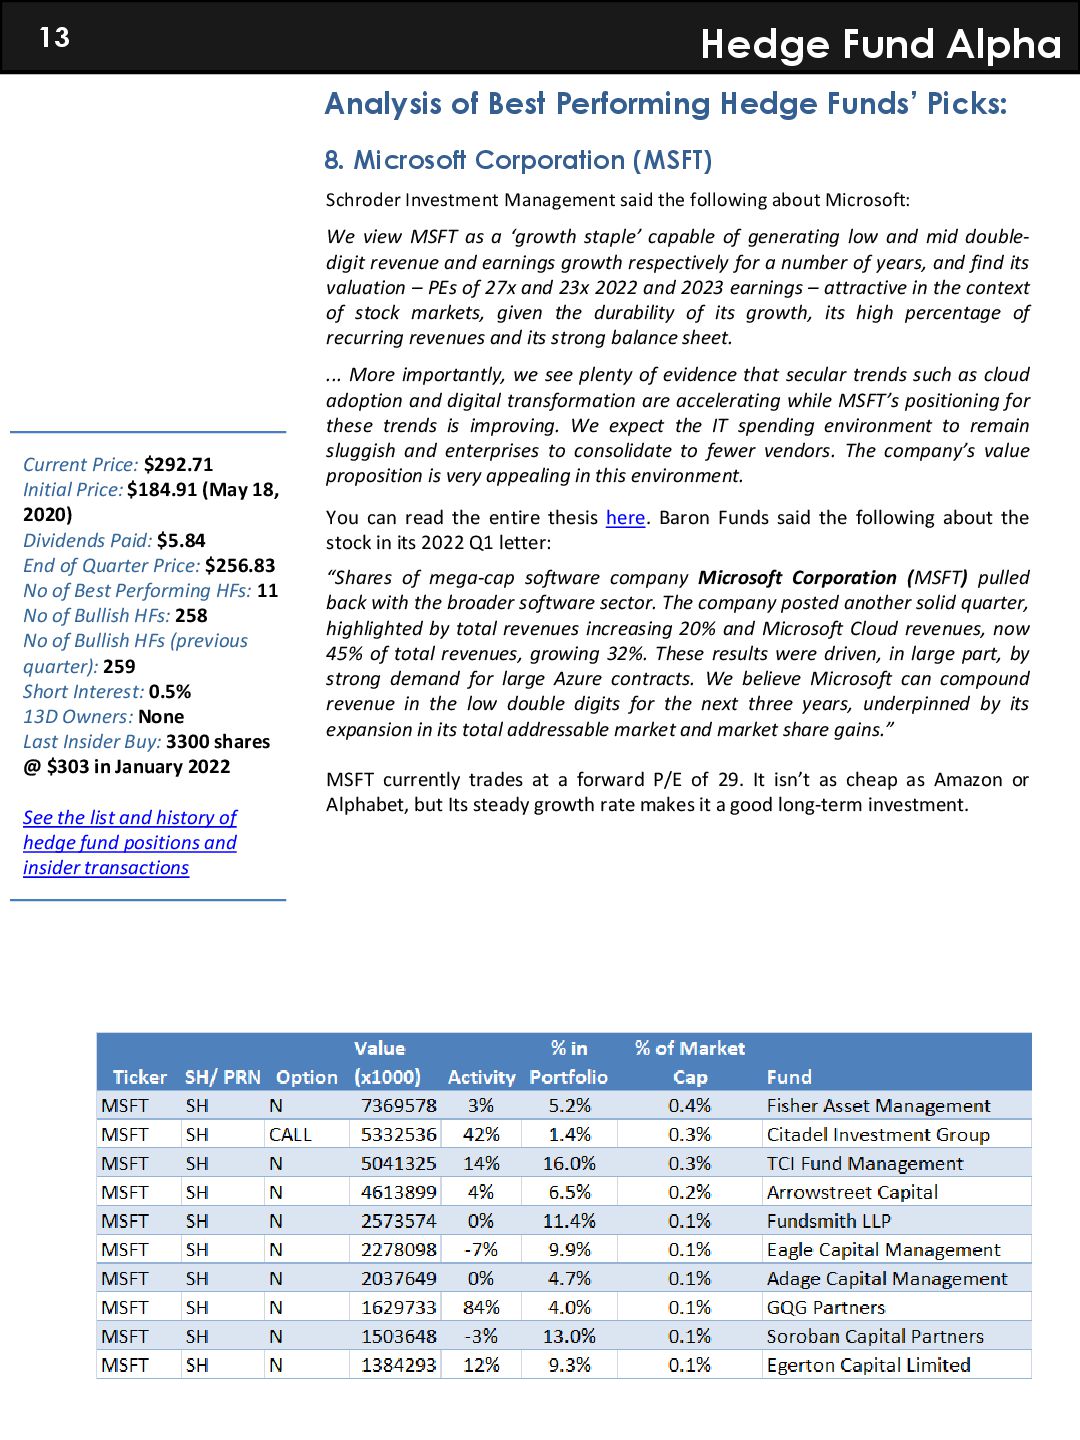
    Picks: 8. Microsoft Corporation (MSFT) Current Price: $292.71 Initial Price: $184.91 (May 18, 2020) Dividends Paid: $5.84 End of Quarter Price: $256.83 No of Best Performing HFs: 11 No of Bullish HFs: 258 No of Bullish HFs (previous quarter): 259 Short Interest: 0.5% 13D Owners: None Last Insider Buy: 3300 shares @ $303 in January 2022 See the list and history of hedge fund positions and insider transactions Schroder Investment Management said the following about Microsoft: We view MSFT as a ‘growth staple’ capable of generating low and mid double- digit revenue and earnings growth respectively for a number of years, and find its valuation – PEs of 27x and 23x 2022 and 2023 earnings – attractive in the context of stock markets, given the durability of its growth, its high percentage of recurring revenues and its strong balance sheet. ... More importantly, we see plenty of evidence that secular trends such as cloud adoption and digital transformation are accelerating while MSFT’s positioning for these trends is improving. We expect the IT spending environment to remain sluggish and enterprises to consolidate to fewer vendors. The company’s value proposition is very appealing in this environment. You can read the entire thesis here. Baron Funds said the following about the stock in its 2022 Q1 letter: “Shares of mega-cap software company Microsoft Corporation (MSFT) pulled back with the broader software sector. The company posted another solid quarter, highlighted by total revenues increasing 20% and Microsoft Cloud revenues, now 45% of total revenues, growing 32%. These results were driven, in large part, by strong demand for large Azure contracts. We believe Microsoft can compound revenue in the low double digits for the next three years, underpinned by its expansion in its total addressable market and market share gains.” MSFT currently trades at a forward P/E of 29. It isn’t as cheap as Amazon or Alphabet, but Its steady growth rate makes it a good long-term investment.
  14. Hedge Fund Alpha 14 Analysis of Best Performing Hedge Funds’

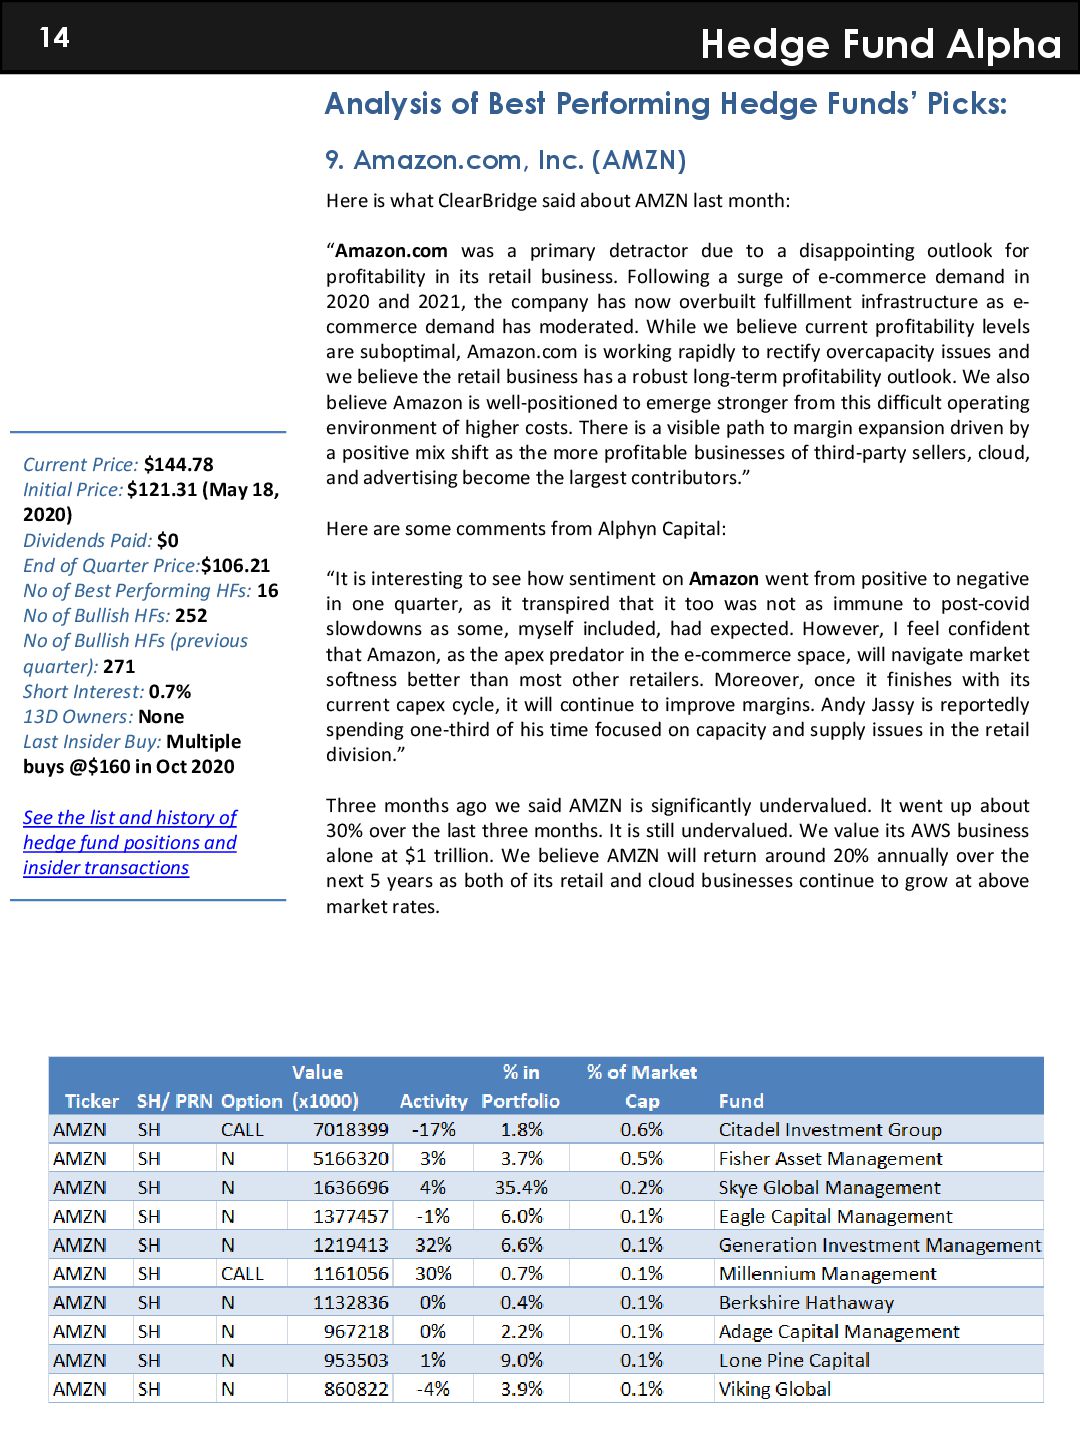
    Picks: 9. Amazon.com, Inc. (AMZN) Current Price: $144.78 Initial Price: $121.31 (May 18, 2020) Dividends Paid: $0 End of Quarter Price:$106.21 No of Best Performing HFs: 16 No of Bullish HFs: 252 No of Bullish HFs (previous quarter): 271 Short Interest: 0.7% 13D Owners: None Last Insider Buy: Multiple buys @$160 in Oct 2020 See the list and history of hedge fund positions and insider transactions Here is what ClearBridge said about AMZN last month: “Amazon.com was a primary detractor due to a disappointing outlook for profitability in its retail business. Following a surge of e-commerce demand in 2020 and 2021, the company has now overbuilt fulfillment infrastructure as e- commerce demand has moderated. While we believe current profitability levels are suboptimal, Amazon.com is working rapidly to rectify overcapacity issues and we believe the retail business has a robust long-term profitability outlook. We also believe Amazon is well-positioned to emerge stronger from this difficult operating environment of higher costs. There is a visible path to margin expansion driven by a positive mix shift as the more profitable businesses of third-party sellers, cloud, and advertising become the largest contributors.” Here are some comments from Alphyn Capital: “It is interesting to see how sentiment on Amazon went from positive to negative in one quarter, as it transpired that it too was not as immune to post-covid slowdowns as some, myself included, had expected. However, I feel confident that Amazon, as the apex predator in the e-commerce space, will navigate market softness better than most other retailers. Moreover, once it finishes with its current capex cycle, it will continue to improve margins. Andy Jassy is reportedly spending one-third of his time focused on capacity and supply issues in the retail division.” Three months ago we said AMZN is significantly undervalued. It went up about 30% over the last three months. It is still undervalued. We value its AWS business alone at $1 trillion. We believe AMZN will return around 20% annually over the next 5 years as both of its retail and cloud businesses continue to grow at above market rates.
  15. Hedge Fund Alpha 15 Analysis of Best Performing Hedge Funds’

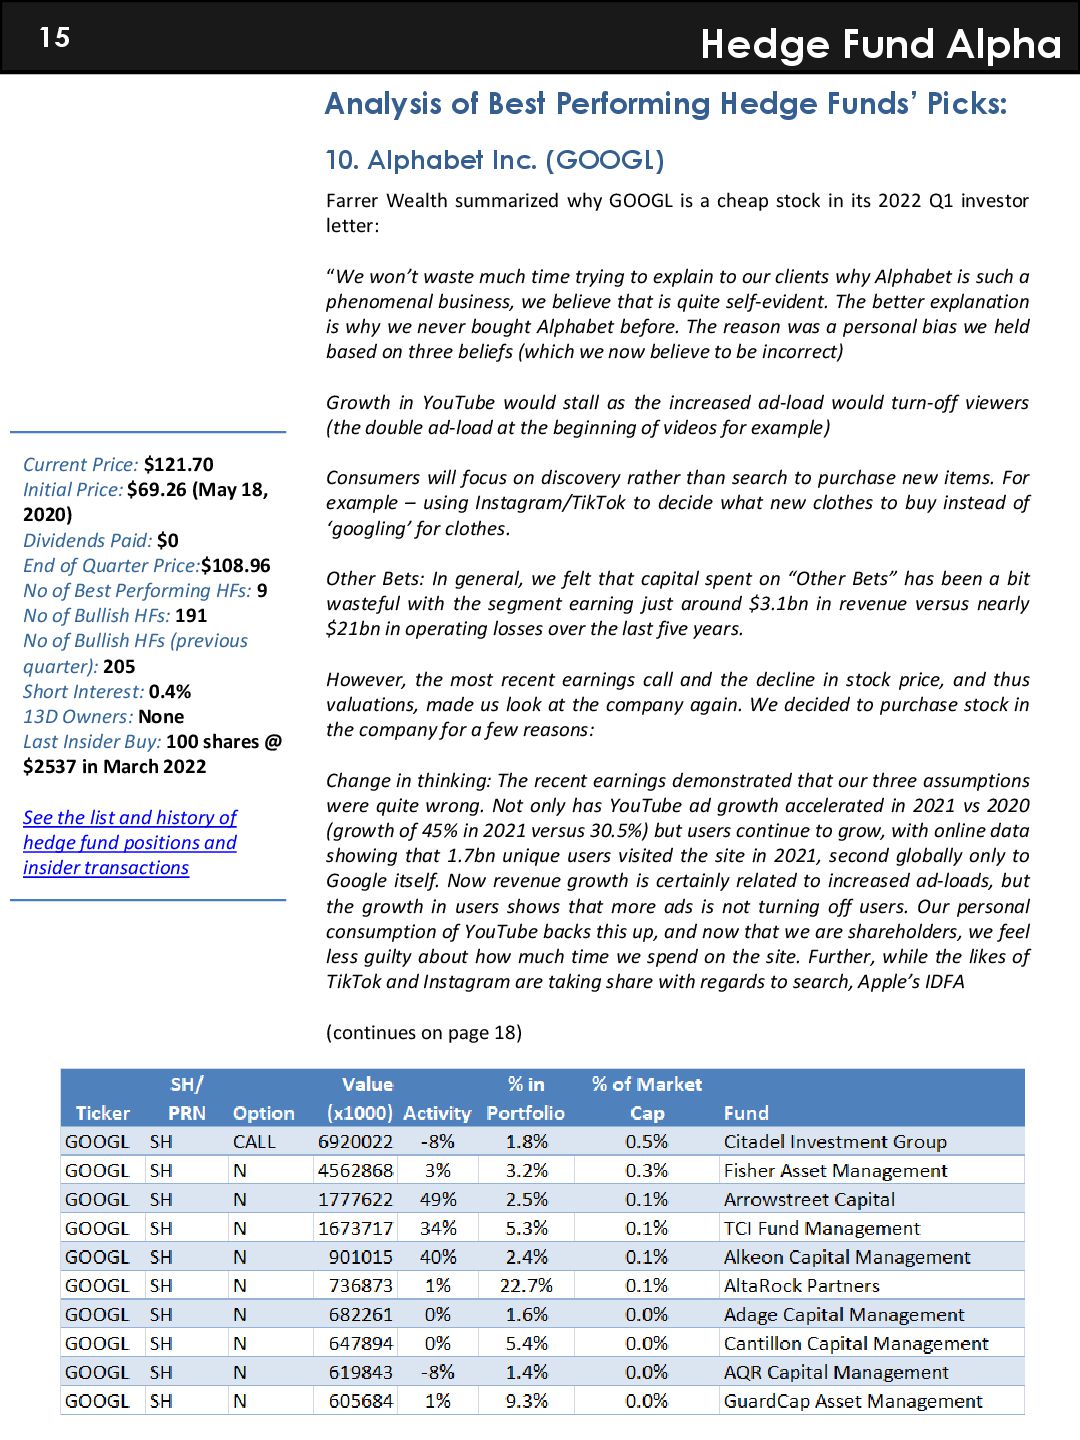
    Picks: 10. Alphabet Inc. (GOOGL) Current Price: $121.70 Initial Price: $69.26 (May 18, 2020) Dividends Paid: $0 End of Quarter Price:$108.96 No of Best Performing HFs: 9 No of Bullish HFs: 191 No of Bullish HFs (previous quarter): 205 Short Interest: 0.4% 13D Owners: None Last Insider Buy: 100 shares @ $2537 in March 2022 See the list and history of hedge fund positions and insider transactions Farrer Wealth summarized why GOOGL is a cheap stock in its 2022 Q1 investor letter: “We won’t waste much time trying to explain to our clients why Alphabet is such a phenomenal business, we believe that is quite self-evident. The better explanation is why we never bought Alphabet before. The reason was a personal bias we held based on three beliefs (which we now believe to be incorrect) Growth in YouTube would stall as the increased ad-load would turn-off viewers (the double ad-load at the beginning of videos for example) Consumers will focus on discovery rather than search to purchase new items. For example – using Instagram/TikTok to decide what new clothes to buy instead of ‘googling’ for clothes. Other Bets: In general, we felt that capital spent on “Other Bets” has been a bit wasteful with the segment earning just around $3.1bn in revenue versus nearly $21bn in operating losses over the last five years. However, the most recent earnings call and the decline in stock price, and thus valuations, made us look at the company again. We decided to purchase stock in the company for a few reasons: Change in thinking: The recent earnings demonstrated that our three assumptions were quite wrong. Not only has YouTube ad growth accelerated in 2021 vs 2020 (growth of 45% in 2021 versus 30.5%) but users continue to grow, with online data showing that 1.7bn unique users visited the site in 2021, second globally only to Google itself. Now revenue growth is certainly related to increased ad-loads, but the growth in users shows that more ads is not turning off users. Our personal consumption of YouTube backs this up, and now that we are shareholders, we feel less guilty about how much time we spend on the site. Further, while the likes of TikTok and Instagram are taking share with regards to search, Apple’s IDFA (continues on page 18)
  16. Hedge Fund Alpha 16 Analysis of Best Performing Hedge Funds’

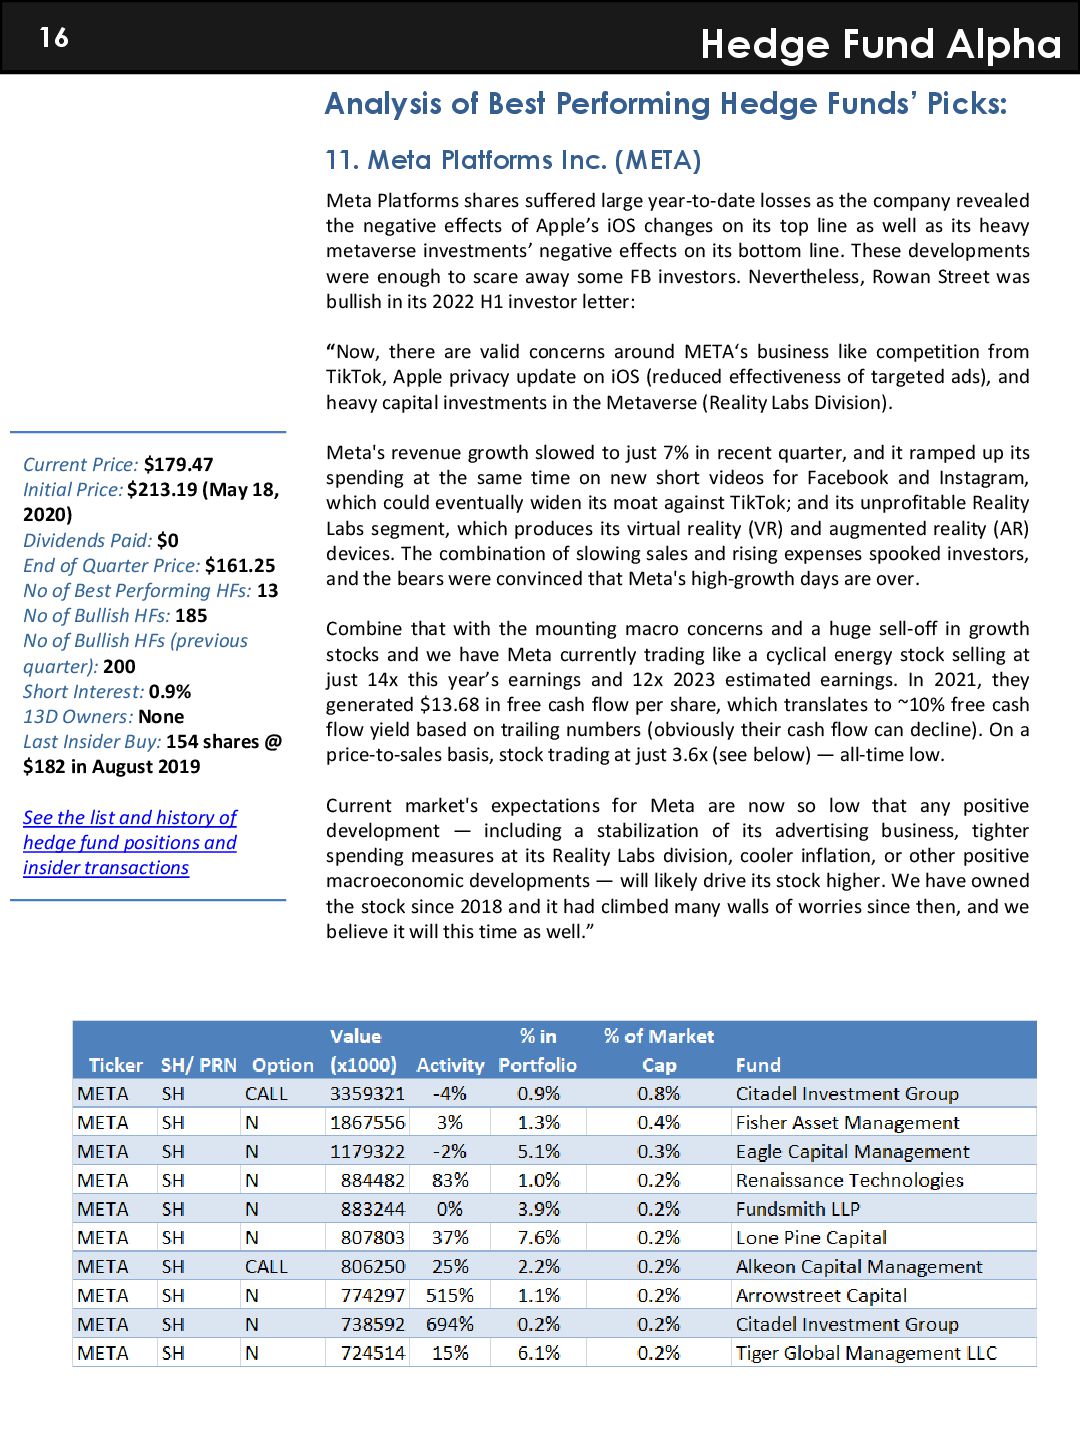
    Picks: 11. Meta Platforms Inc. (META) Current Price: $179.47 Initial Price: $213.19 (May 18, 2020) Dividends Paid: $0 End of Quarter Price: $161.25 No of Best Performing HFs: 13 No of Bullish HFs: 185 No of Bullish HFs (previous quarter): 200 Short Interest: 0.9% 13D Owners: None Last Insider Buy: 154 shares @ $182 in August 2019 See the list and history of hedge fund positions and insider transactions Meta Platforms shares suffered large year-to-date losses as the company revealed the negative effects of Apple’s iOS changes on its top line as well as its heavy metaverse investments’ negative effects on its bottom line. These developments were enough to scare away some FB investors. Nevertheless, Rowan Street was bullish in its 2022 H1 investor letter: “Now, there are valid concerns around META‘s business like competition from TikTok, Apple privacy update on iOS (reduced effectiveness of targeted ads), and heavy capital investments in the Metaverse (Reality Labs Division). Meta's revenue growth slowed to just 7% in recent quarter, and it ramped up its spending at the same time on new short videos for Facebook and Instagram, which could eventually widen its moat against TikTok; and its unprofitable Reality Labs segment, which produces its virtual reality (VR) and augmented reality (AR) devices. The combination of slowing sales and rising expenses spooked investors, and the bears were convinced that Meta's high-growth days are over. Combine that with the mounting macro concerns and a huge sell-off in growth stocks and we have Meta currently trading like a cyclical energy stock selling at just 14x this year’s earnings and 12x 2023 estimated earnings. In 2021, they generated $13.68 in free cash flow per share, which translates to ~10% free cash flow yield based on trailing numbers (obviously their cash flow can decline). On a price-to-sales basis, stock trading at just 3.6x (see below) — all-time low. Current market's expectations for Meta are now so low that any positive development — including a stabilization of its advertising business, tighter spending measures at its Reality Labs division, cooler inflation, or other positive macroeconomic developments — will likely drive its stock higher. We have owned the stock since 2018 and it had climbed many walls of worries since then, and we believe it will this time as well.”
  17. Hedge Fund Alpha 17 Analysis of Best Performing Hedge Funds’

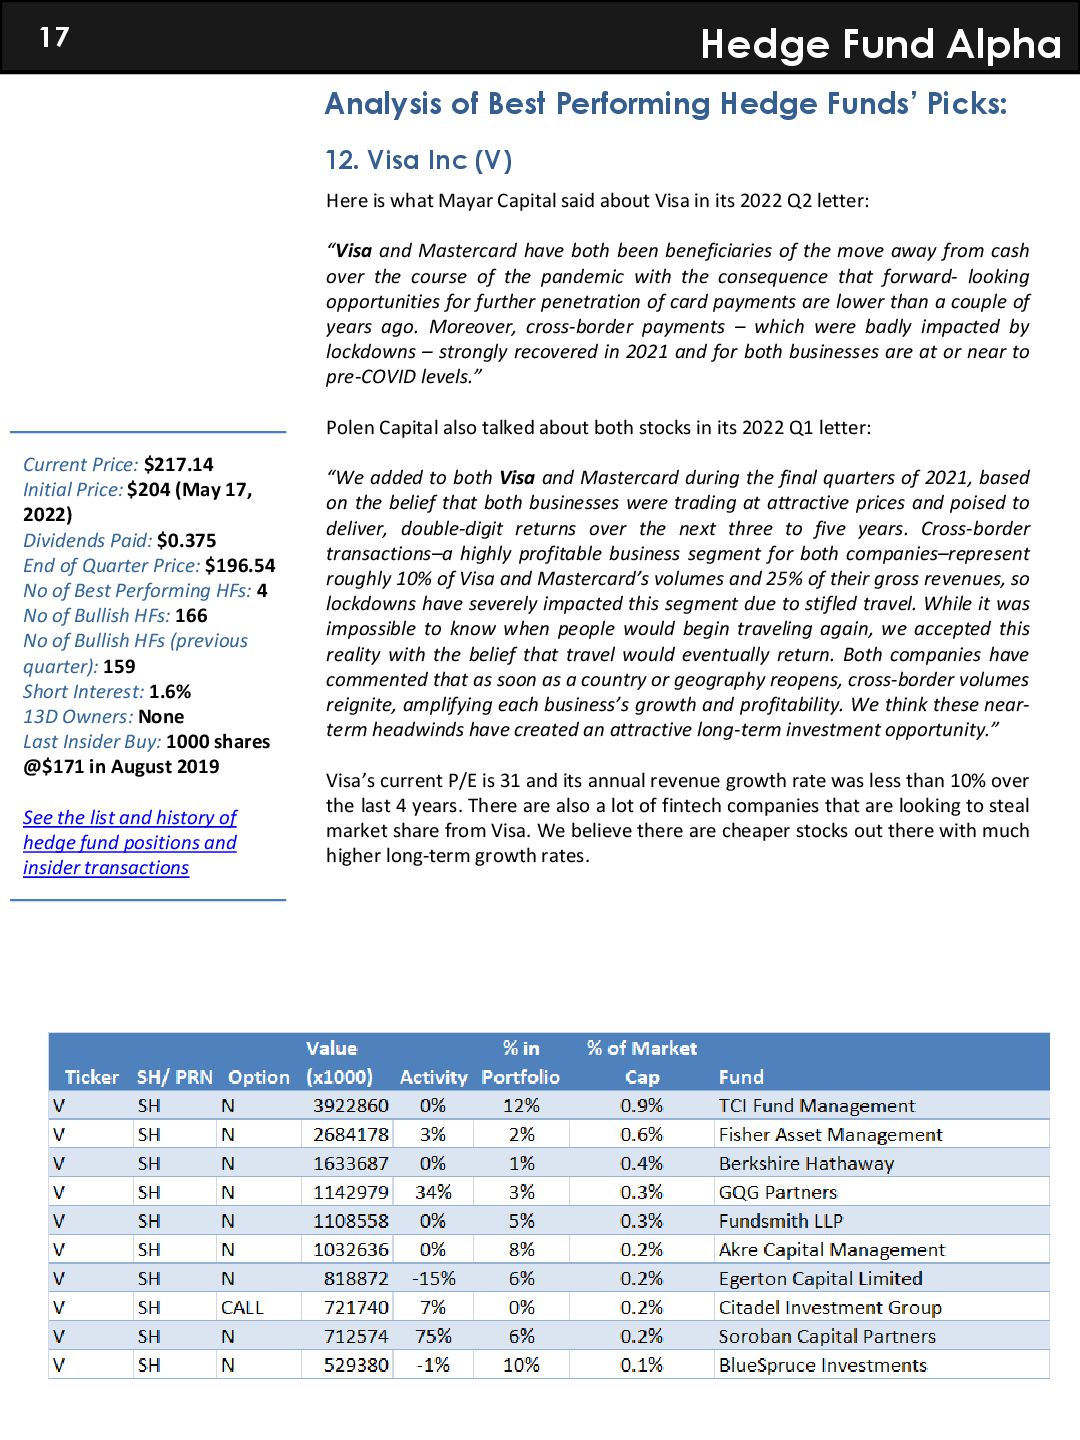
    Picks: 12. Visa Inc (V) Current Price: $217.14 Initial Price: $204 (May 17, 2022) Dividends Paid: $0.375 End of Quarter Price: $196.54 No of Best Performing HFs: 4 No of Bullish HFs: 166 No of Bullish HFs (previous quarter): 159 Short Interest: 1.6% 13D Owners: None Last Insider Buy: 1000 shares @$171 in August 2019 See the list and history of hedge fund positions and insider transactions Here is what Mayar Capital said about Visa in its 2022 Q2 letter: “Visa and Mastercard have both been beneficiaries of the move away from cash over the course of the pandemic with the consequence that forward- looking opportunities for further penetration of card payments are lower than a couple of years ago. Moreover, cross-border payments – which were badly impacted by lockdowns – strongly recovered in 2021 and for both businesses are at or near to pre-COVID levels.” Polen Capital also talked about both stocks in its 2022 Q1 letter: “We added to both Visa and Mastercard during the final quarters of 2021, based on the belief that both businesses were trading at attractive prices and poised to deliver, double-digit returns over the next three to five years. Cross-border transactions–a highly profitable business segment for both companies–represent roughly 10% of Visa and Mastercard’s volumes and 25% of their gross revenues, so lockdowns have severely impacted this segment due to stifled travel. While it was impossible to know when people would begin traveling again, we accepted this reality with the belief that travel would eventually return. Both companies have commented that as soon as a country or geography reopens, cross-border volumes reignite, amplifying each business’s growth and profitability. We think these near- term headwinds have created an attractive long-term investment opportunity.” Visa’s current P/E is 31 and its annual revenue growth rate was less than 10% over the last 4 years. There are also a lot of fintech companies that are looking to steal market share from Visa. We believe there are cheaper stocks out there with much higher long-term growth rates.
  18. Hedge Fund Alpha 18 Analysis of Best Performing Hedge Funds’

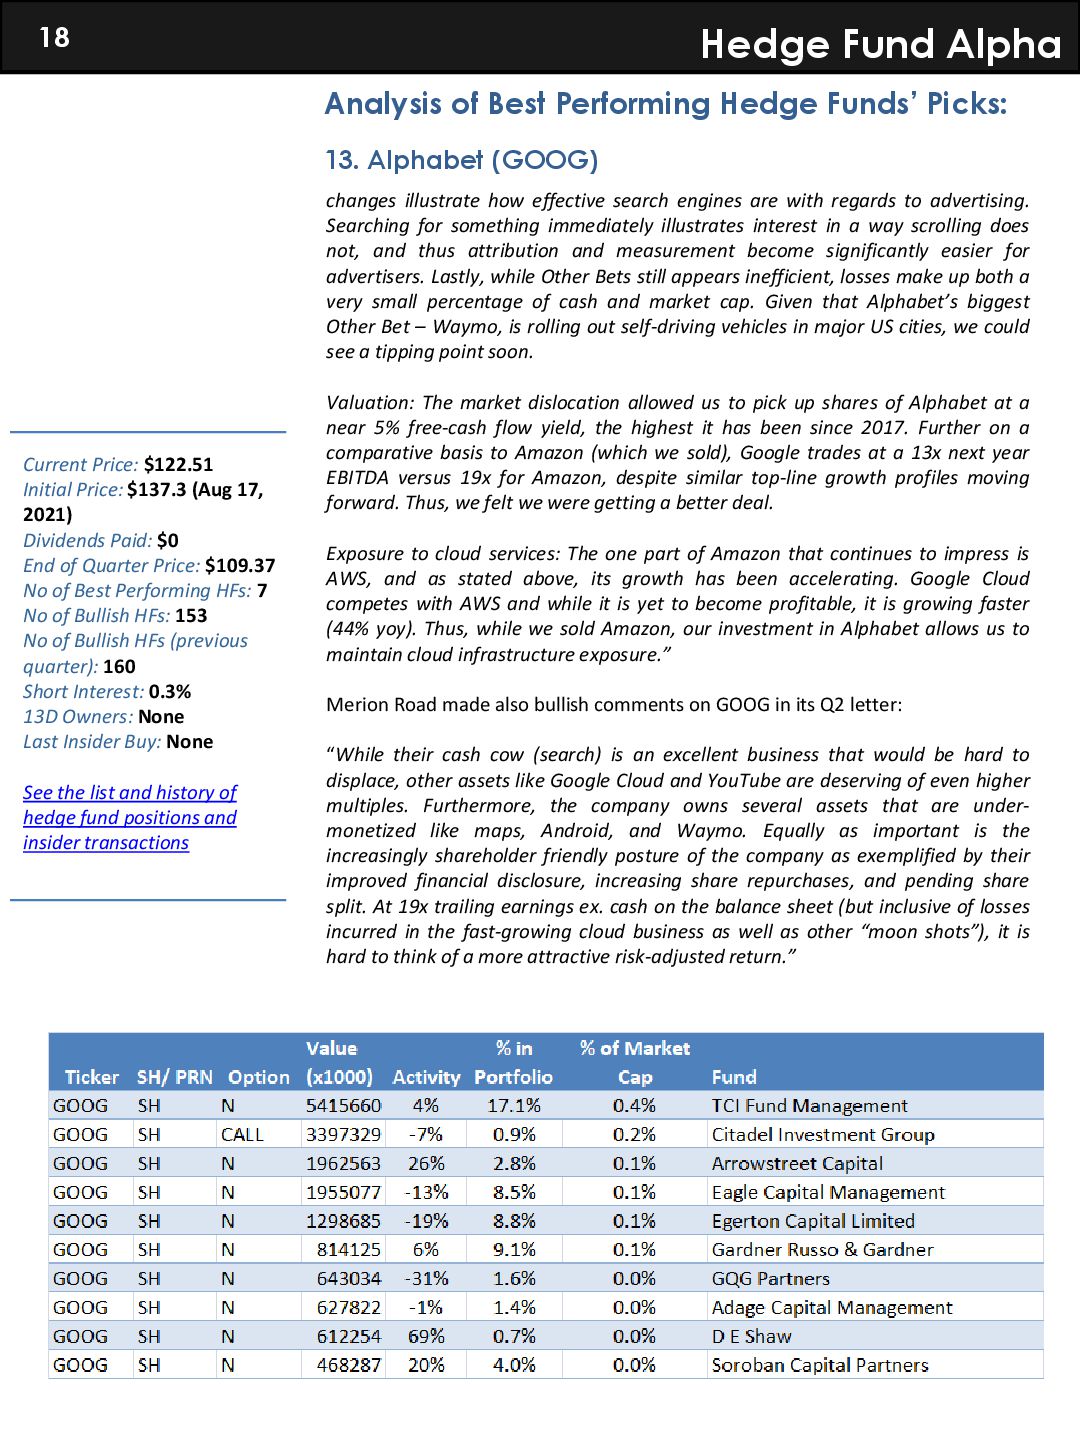
    Picks: 13. Alphabet (GOOG) Current Price: $122.51 Initial Price: $137.3 (Aug 17, 2021) Dividends Paid: $0 End of Quarter Price: $109.37 No of Best Performing HFs: 7 No of Bullish HFs: 153 No of Bullish HFs (previous quarter): 160 Short Interest: 0.3% 13D Owners: None Last Insider Buy: None See the list and history of hedge fund positions and insider transactions changes illustrate how effective search engines are with regards to advertising. Searching for something immediately illustrates interest in a way scrolling does not, and thus attribution and measurement become significantly easier for advertisers. Lastly, while Other Bets still appears inefficient, losses make up both a very small percentage of cash and market cap. Given that Alphabet’s biggest Other Bet – Waymo, is rolling out self-driving vehicles in major US cities, we could see a tipping point soon. Valuation: The market dislocation allowed us to pick up shares of Alphabet at a near 5% free-cash flow yield, the highest it has been since 2017. Further on a comparative basis to Amazon (which we sold), Google trades at a 13x next year EBITDA versus 19x for Amazon, despite similar top-line growth profiles moving forward. Thus, we felt we were getting a better deal. Exposure to cloud services: The one part of Amazon that continues to impress is AWS, and as stated above, its growth has been accelerating. Google Cloud competes with AWS and while it is yet to become profitable, it is growing faster (44% yoy). Thus, while we sold Amazon, our investment in Alphabet allows us to maintain cloud infrastructure exposure.” Merion Road made also bullish comments on GOOG in its Q2 letter: “While their cash cow (search) is an excellent business that would be hard to displace, other assets like Google Cloud and YouTube are deserving of even higher multiples. Furthermore, the company owns several assets that are under- monetized like maps, Android, and Waymo. Equally as important is the increasingly shareholder friendly posture of the company as exemplified by their improved financial disclosure, increasing share repurchases, and pending share split. At 19x trailing earnings ex. cash on the balance sheet (but inclusive of losses incurred in the fast-growing cloud business as well as other “moon shots”), it is hard to think of a more attractive risk-adjusted return.”
  19. Hedge Fund Alpha 19 Analysis of Best Performing Hedge Funds’

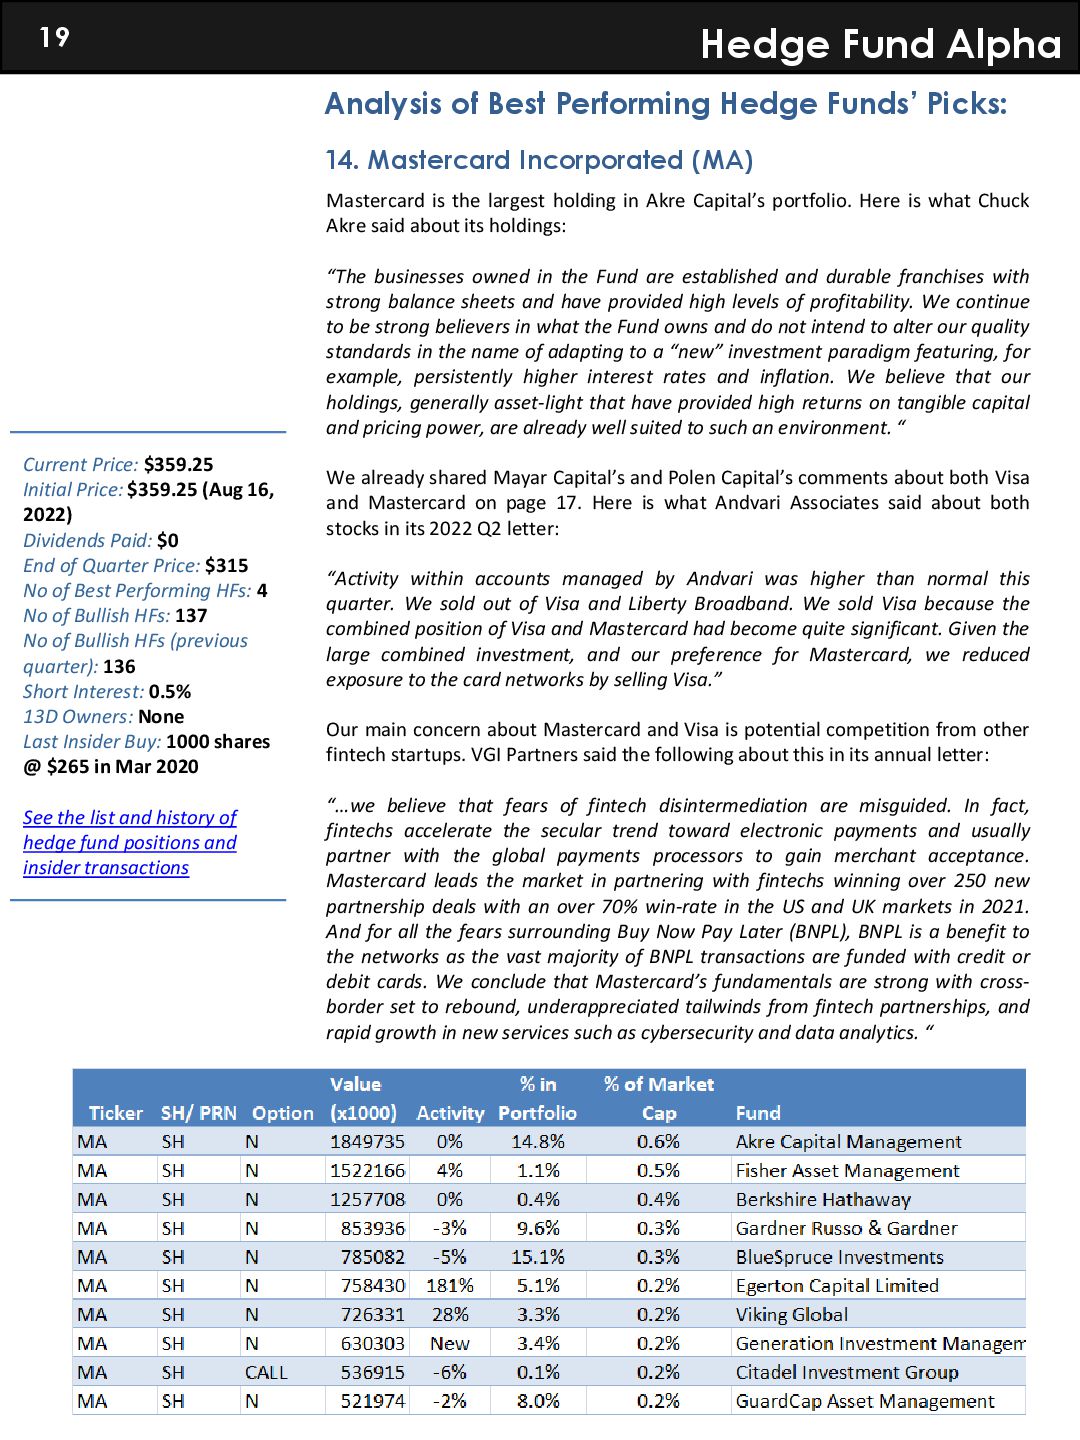
    Picks: 14. Mastercard Incorporated (MA) Current Price: $359.25 Initial Price: $359.25 (Aug 16, 2022) Dividends Paid: $0 End of Quarter Price: $315 No of Best Performing HFs: 4 No of Bullish HFs: 137 No of Bullish HFs (previous quarter): 136 Short Interest: 0.5% 13D Owners: None Last Insider Buy: 1000 shares @ $265 in Mar 2020 See the list and history of hedge fund positions and insider transactions Mastercard is the largest holding in Akre Capital’s portfolio. Here is what Chuck Akre said about its holdings: “The businesses owned in the Fund are established and durable franchises with strong balance sheets and have provided high levels of profitability. We continue to be strong believers in what the Fund owns and do not intend to alter our quality standards in the name of adapting to a “new” investment paradigm featuring, for example, persistently higher interest rates and inflation. We believe that our holdings, generally asset-light that have provided high returns on tangible capital and pricing power, are already well suited to such an environment. “ We already shared Mayar Capital’s and Polen Capital’s comments about both Visa and Mastercard on page 17. Here is what Andvari Associates said about both stocks in its 2022 Q2 letter: “Activity within accounts managed by Andvari was higher than normal this quarter. We sold out of Visa and Liberty Broadband. We sold Visa because the combined position of Visa and Mastercard had become quite significant. Given the large combined investment, and our preference for Mastercard, we reduced exposure to the card networks by selling Visa.” Our main concern about Mastercard and Visa is potential competition from other fintech startups. VGI Partners said the following about this in its annual letter: “…we believe that fears of fintech disintermediation are misguided. In fact, fintechs accelerate the secular trend toward electronic payments and usually partner with the global payments processors to gain merchant acceptance. Mastercard leads the market in partnering with fintechs winning over 250 new partnership deals with an over 70% win-rate in the US and UK markets in 2021. And for all the fears surrounding Buy Now Pay Later (BNPL), BNPL is a benefit to the networks as the vast majority of BNPL transactions are funded with credit or debit cards. We conclude that Mastercard’s fundamentals are strong with cross- border set to rebound, underappreciated tailwinds from fintech partnerships, and rapid growth in new services such as cybersecurity and data analytics. “
  20. Hedge Fund Alpha 20 Warren Buffett - Berkshire Hathaway Best

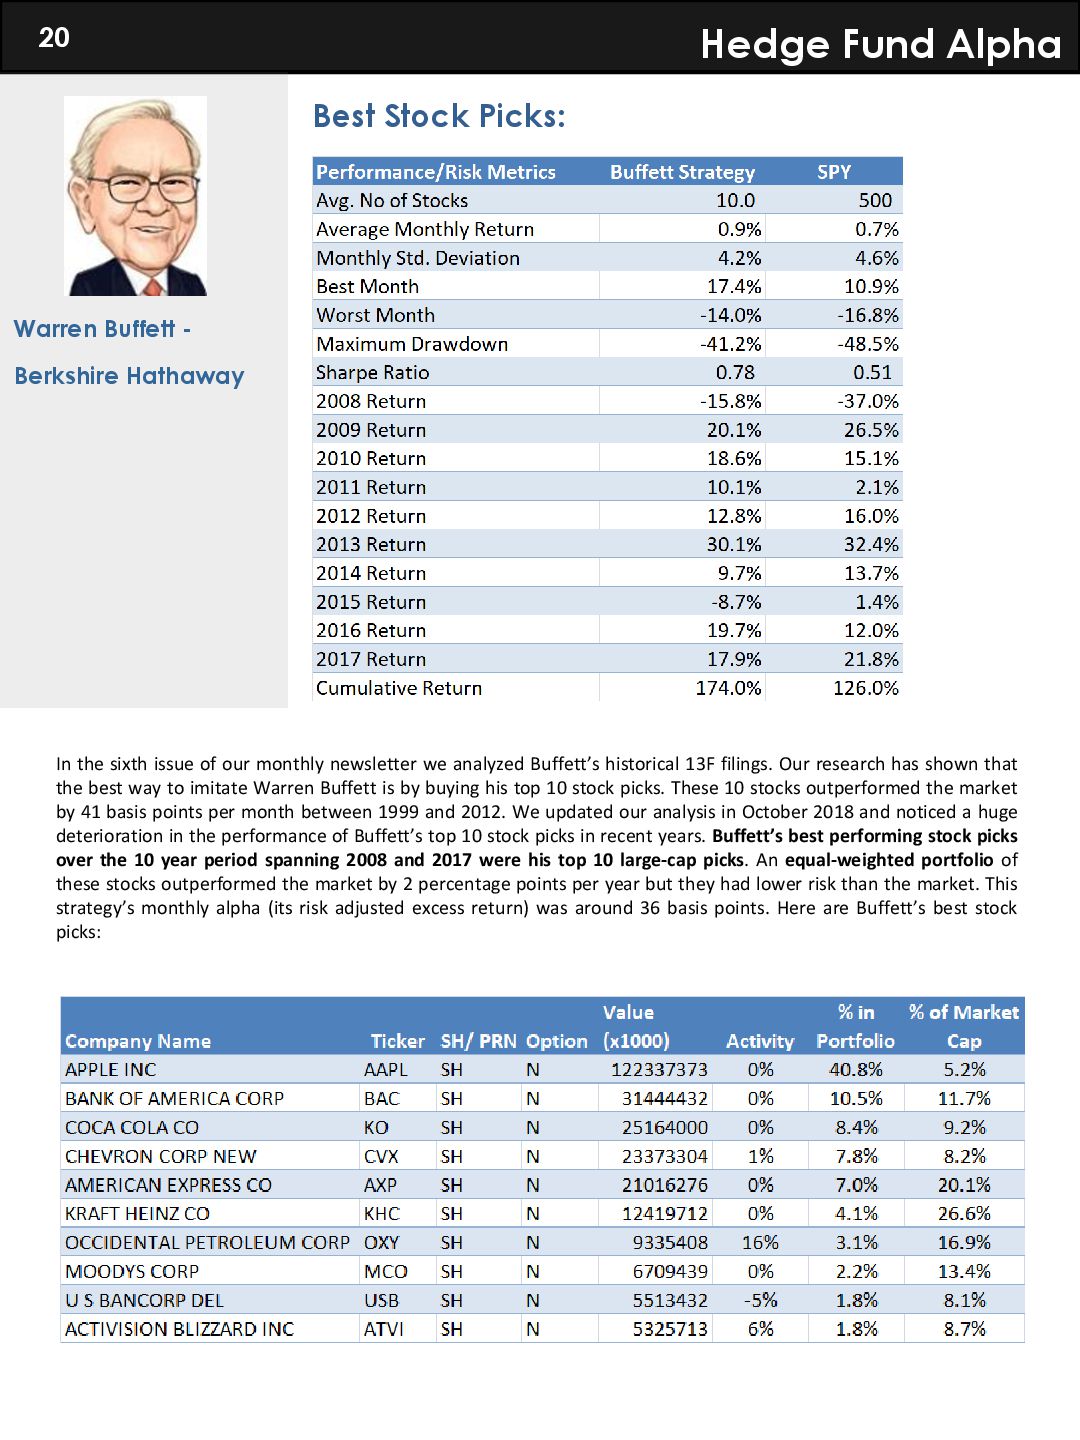
    Stock Picks: In the sixth issue of our monthly newsletter we analyzed Buffett’s historical 13F filings. Our research has shown that the best way to imitate Warren Buffett is by buying his top 10 stock picks. These 10 stocks outperformed the market by 41 basis points per month between 1999 and 2012. We updated our analysis in October 2018 and noticed a huge deterioration in the performance of Buffett’s top 10 stock picks in recent years. Buffett’s best performing stock picks over the 10 year period spanning 2008 and 2017 were his top 10 large-cap picks. An equal-weighted portfolio of these stocks outperformed the market by 2 percentage points per year but they had lower risk than the market. This strategy’s monthly alpha (its risk adjusted excess return) was around 36 basis points. Here are Buffett’s best stock picks:
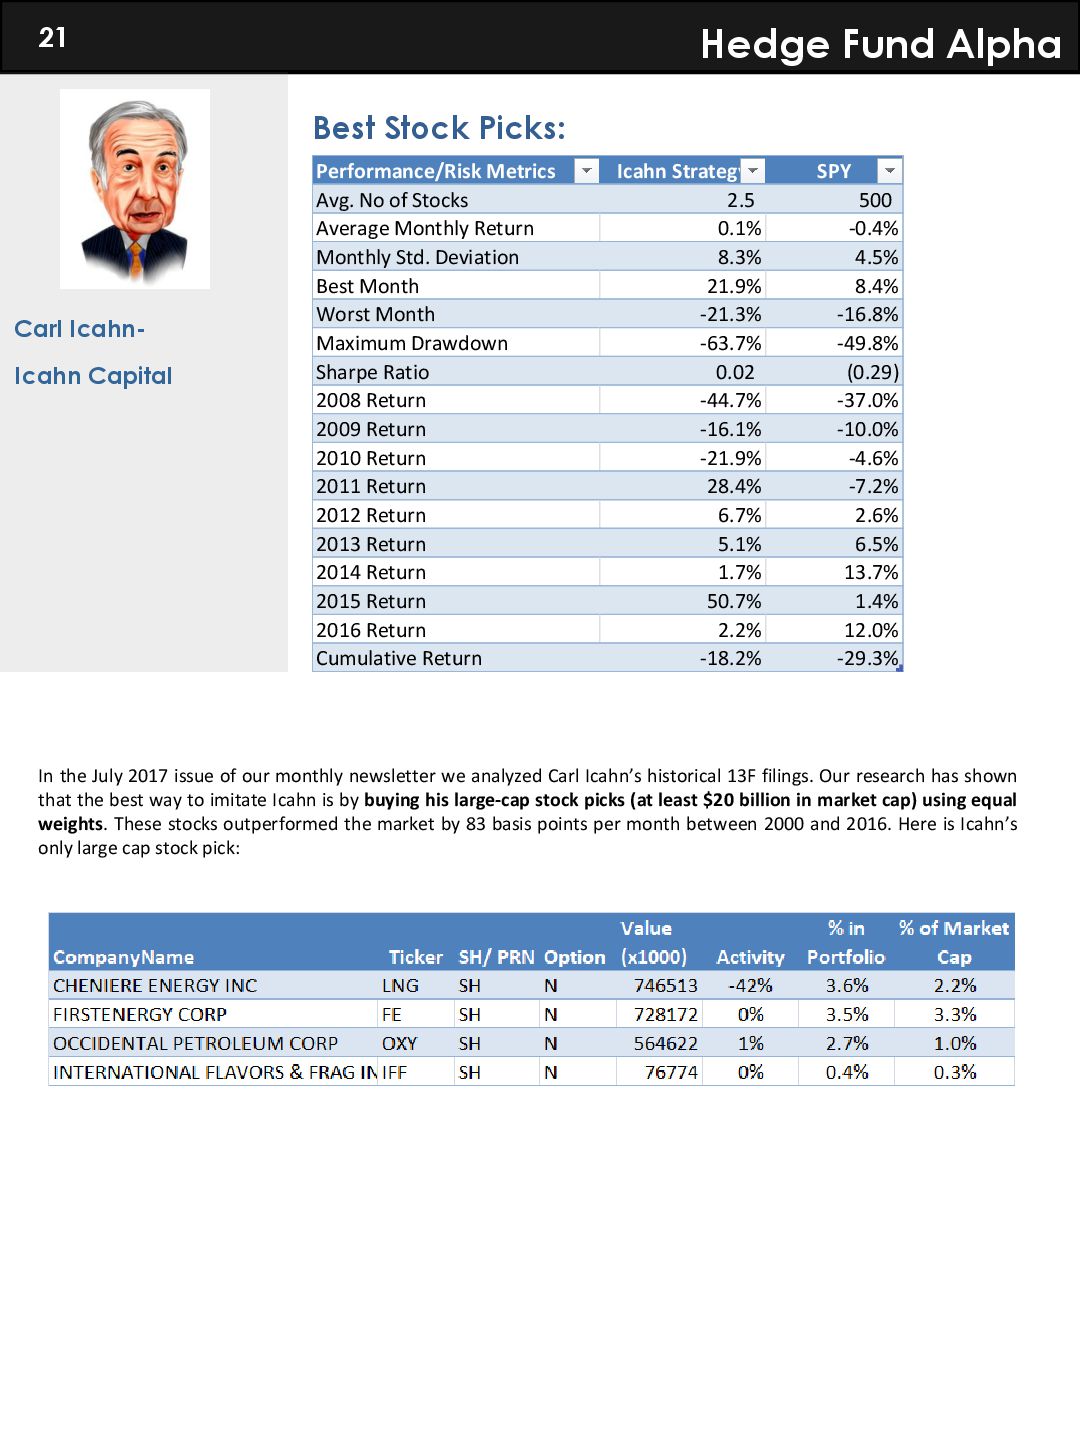
  21. Hedge Fund Alpha 21 Carl Icahn- Icahn Capital Best Stock

    Picks: Performance/Risk Metrics Icahn Strategy SPY Avg. No of Stocks 2.5 500 Average Monthly Return 0.1% -0.4% Monthly Std. Deviation 8.3% 4.5% Best Month 21.9% 8.4% Worst Month -21.3% -16.8% Maximum Drawdown -63.7% -49.8% Sharpe Ratio 0.02 (0.29) 2008 Return -44.7% -37.0% 2009 Return -16.1% -10.0% 2010 Return -21.9% -4.6% 2011 Return 28.4% -7.2% 2012 Return 6.7% 2.6% 2013 Return 5.1% 6.5% 2014 Return 1.7% 13.7% 2015 Return 50.7% 1.4% 2016 Return 2.2% 12.0% Cumulative Return -18.2% -29.3% In the July 2017 issue of our monthly newsletter we analyzed Carl Icahn’s historical 13F filings. Our research has shown that the best way to imitate Icahn is by buying his large-cap stock picks (at least $20 billion in market cap) using equal weights. These stocks outperformed the market by 83 basis points per month between 2000 and 2016. Here is Icahn’s only large cap stock pick:
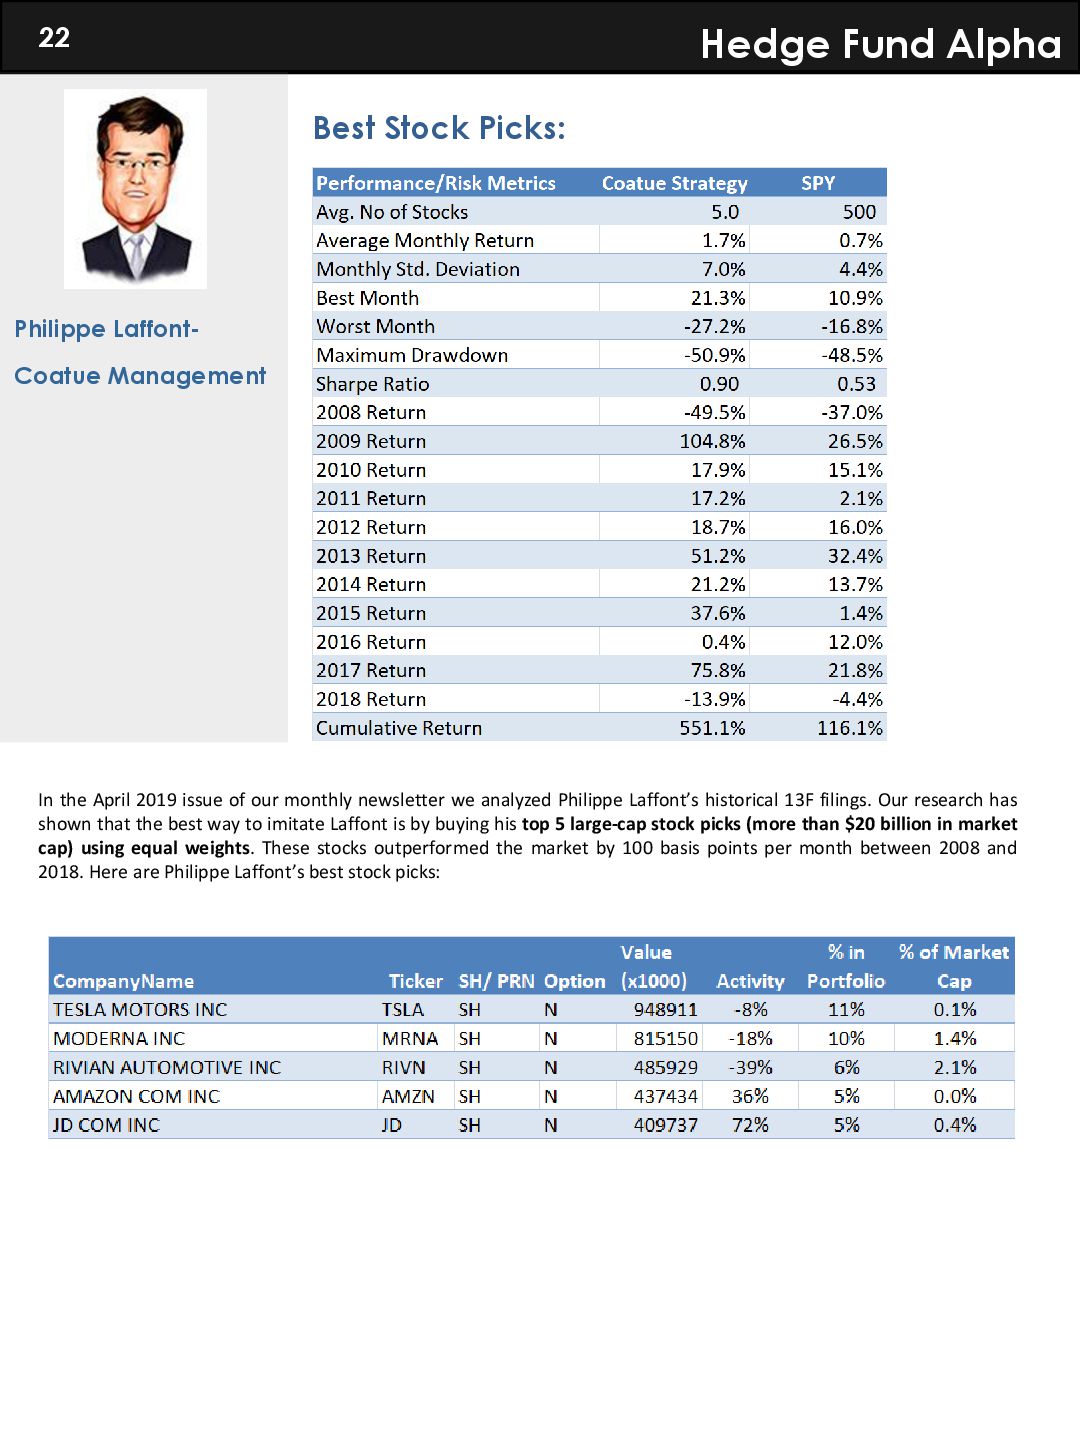
  22. Hedge Fund Alpha 22 Philippe Laffont- Coatue Management Best Stock

    Picks: In the April 2019 issue of our monthly newsletter we analyzed Philippe Laffont’s historical 13F filings. Our research has shown that the best way to imitate Laffont is by buying his top 5 large-cap stock picks (more than $20 billion in market cap) using equal weights. These stocks outperformed the market by 100 basis points per month between 2008 and 2018. Here are Philippe Laffont’s best stock picks:
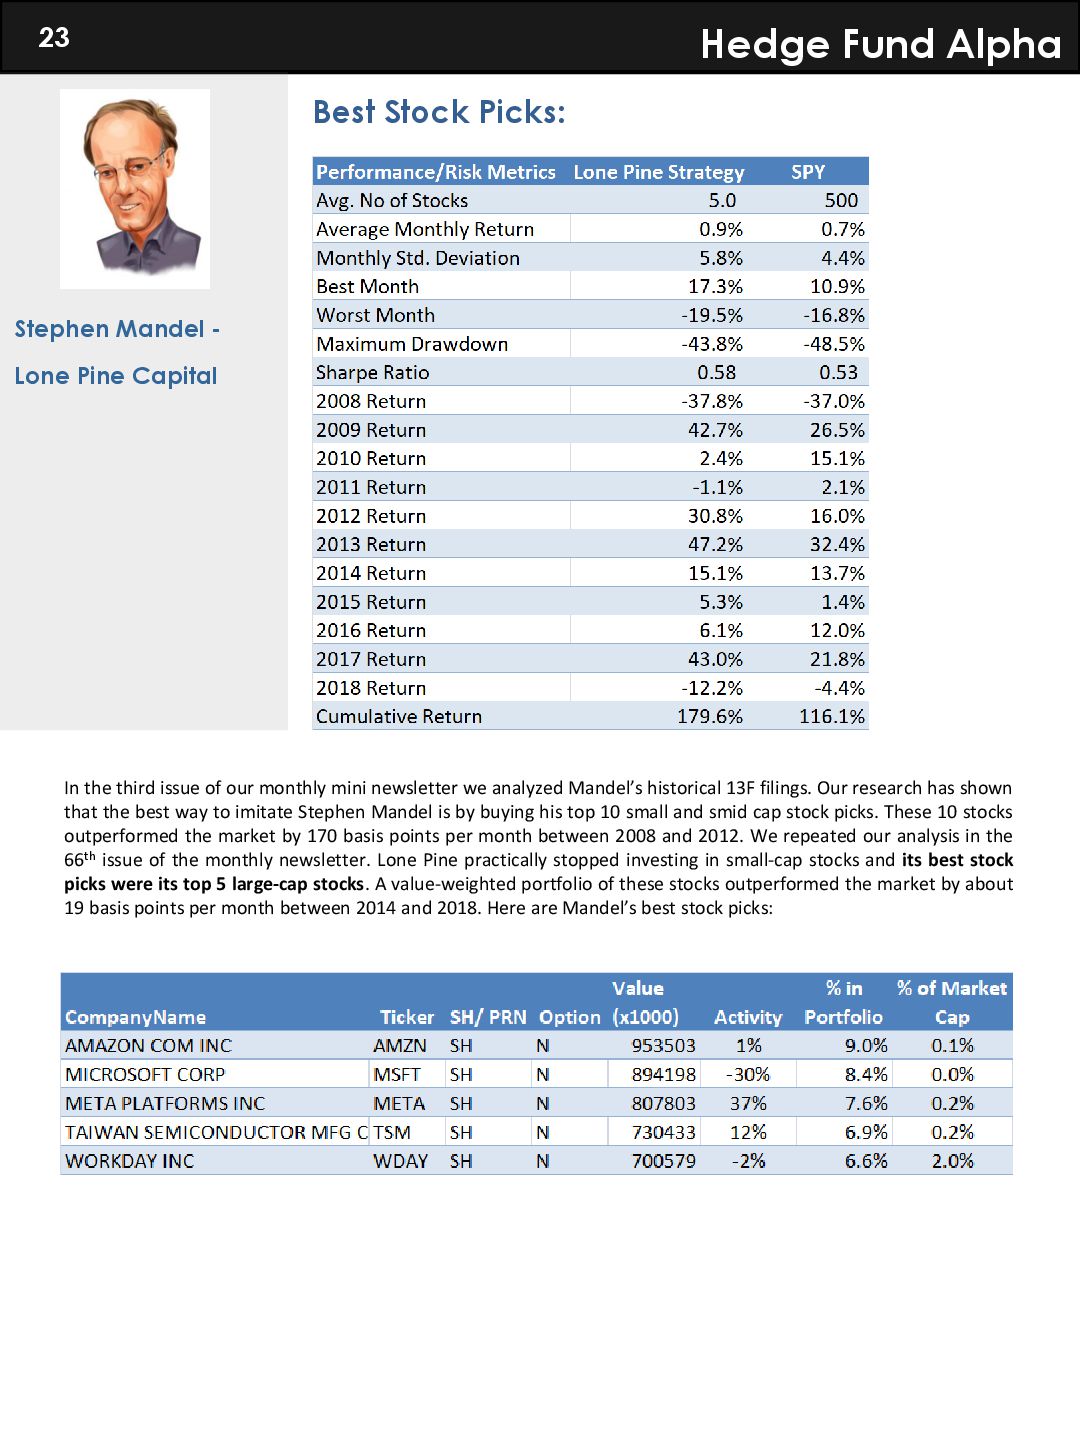
  23. Hedge Fund Alpha 23 Stephen Mandel - Lone Pine Capital

    Best Stock Picks: In the third issue of our monthly mini newsletter we analyzed Mandel’s historical 13F filings. Our research has shown that the best way to imitate Stephen Mandel is by buying his top 10 small and smid cap stock picks. These 10 stocks outperformed the market by 170 basis points per month between 2008 and 2012. We repeated our analysis in the 66th issue of the monthly newsletter. Lone Pine practically stopped investing in small-cap stocks and its best stock picks were its top 5 large-cap stocks. A value-weighted portfolio of these stocks outperformed the market by about 19 basis points per month between 2014 and 2018. Here are Mandel’s best stock picks:
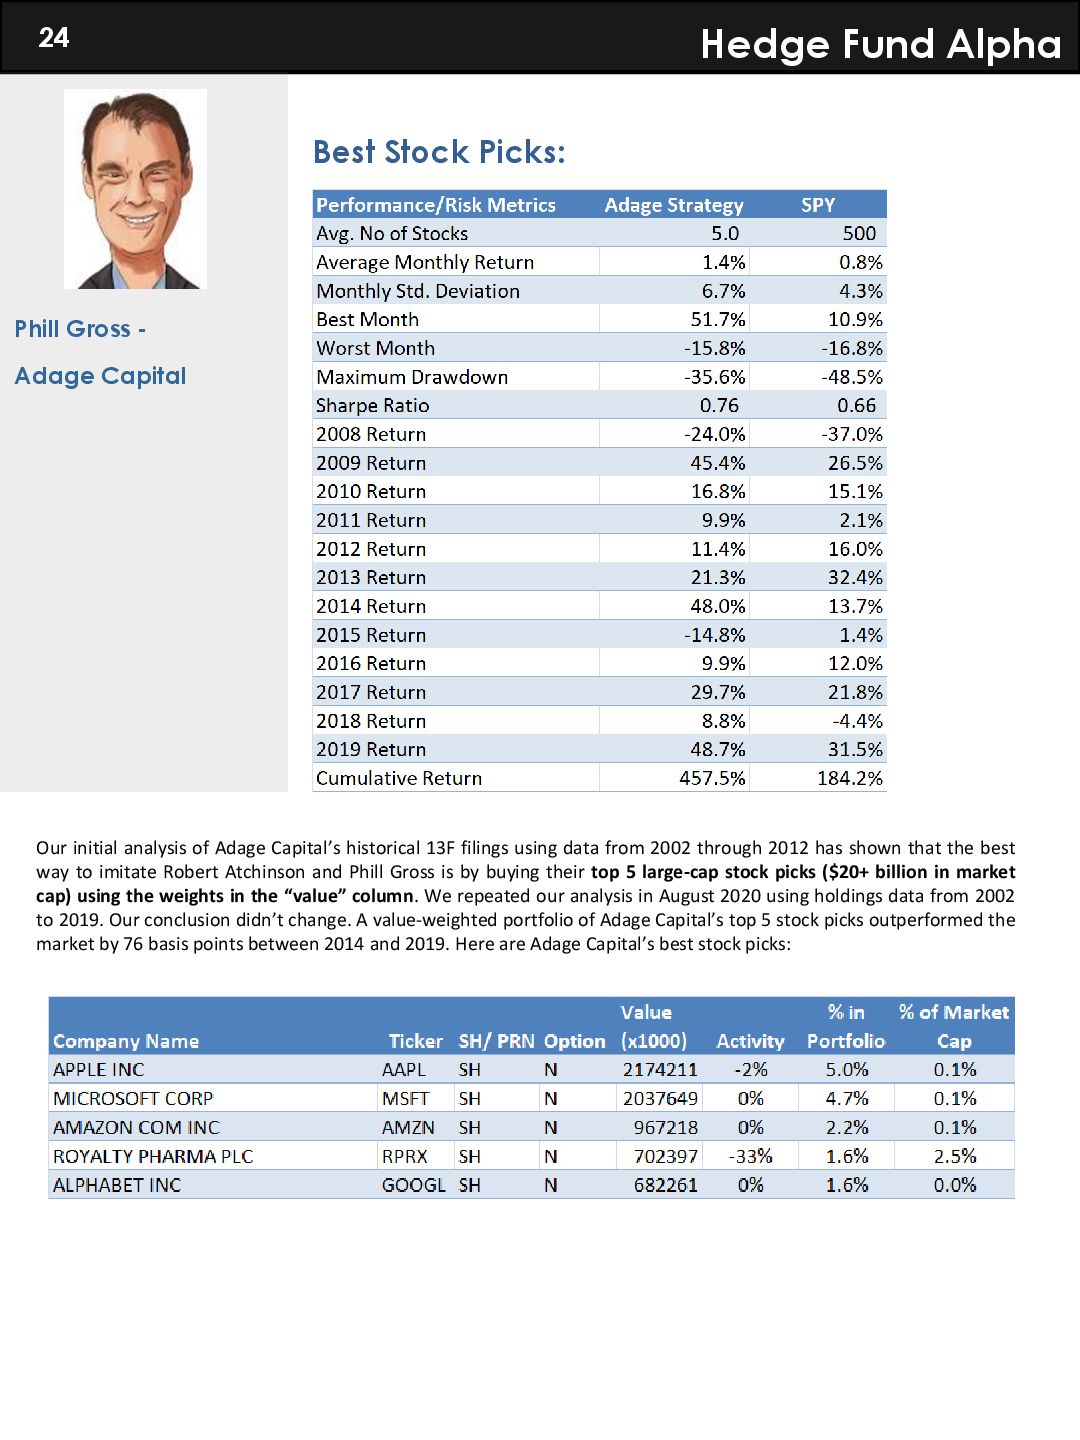
  24. Hedge Fund Alpha 24 Phill Gross - Adage Capital Best

    Stock Picks: Our initial analysis of Adage Capital’s historical 13F filings using data from 2002 through 2012 has shown that the best way to imitate Robert Atchinson and Phill Gross is by buying their top 5 large-cap stock picks ($20+ billion in market cap) using the weights in the “value” column. We repeated our analysis in August 2020 using holdings data from 2002 to 2019. Our conclusion didn’t change. A value-weighted portfolio of Adage Capital’s top 5 stock picks outperformed the market by 76 basis points between 2014 and 2019. Here are Adage Capital’s best stock picks:
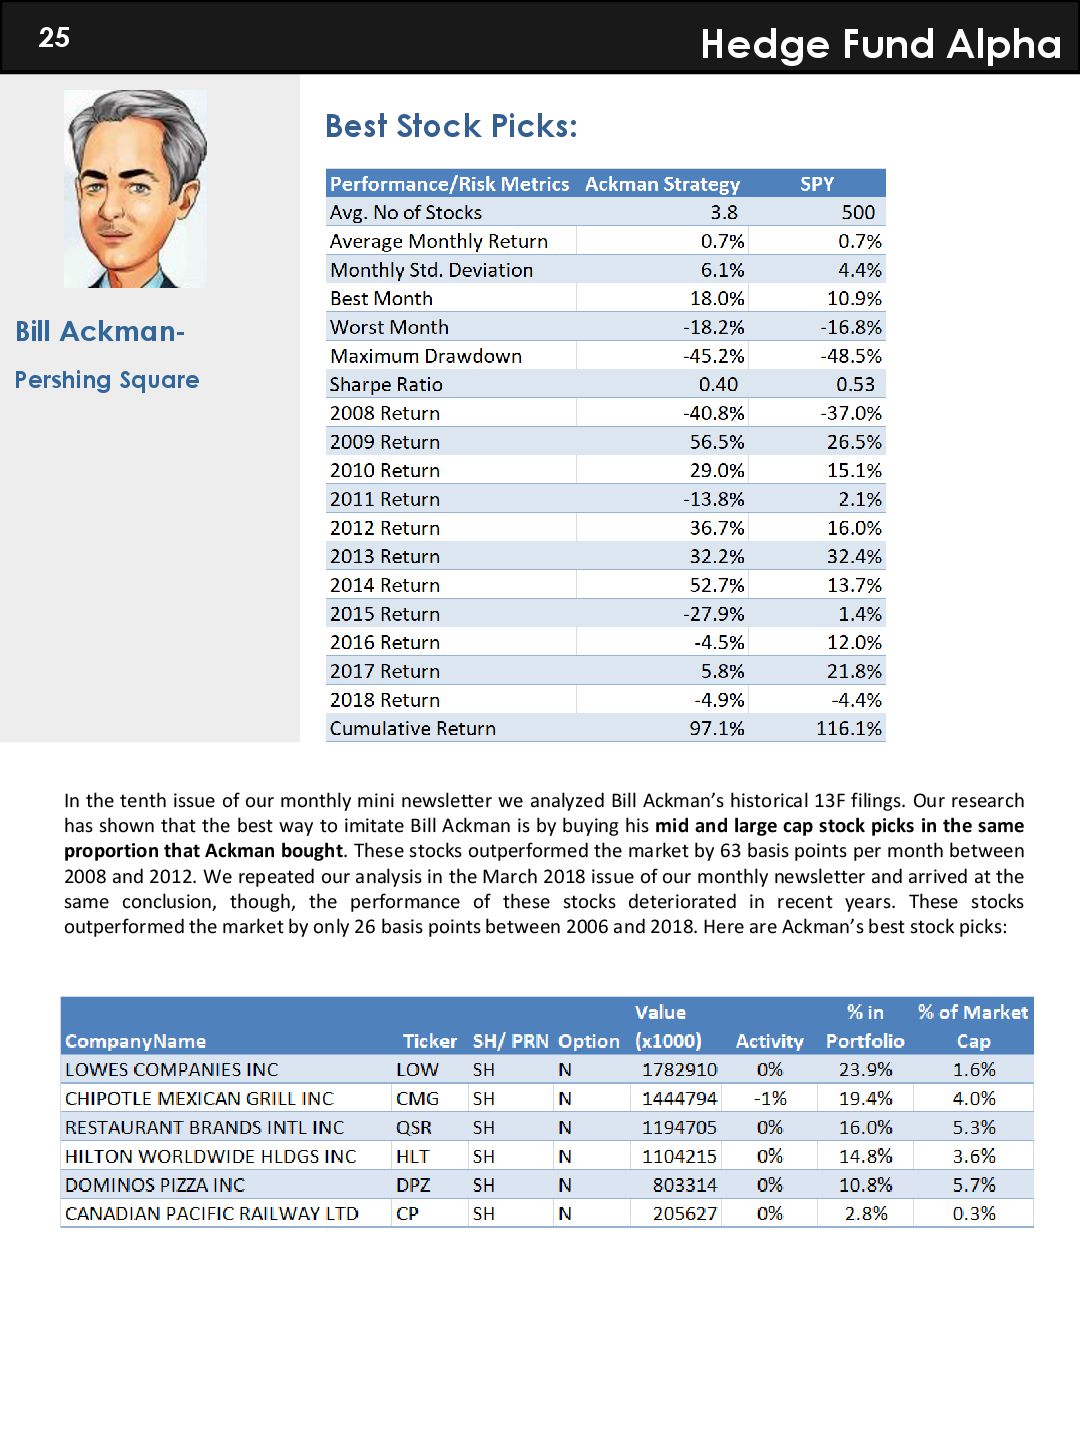
  25. Bill Ackman- Pershing Square Hedge Fund Alpha 25 Best Stock

    Picks: In the tenth issue of our monthly mini newsletter we analyzed Bill Ackman’s historical 13F filings. Our research has shown that the best way to imitate Bill Ackman is by buying his mid and large cap stock picks in the same proportion that Ackman bought. These stocks outperformed the market by 63 basis points per month between 2008 and 2012. We repeated our analysis in the March 2018 issue of our monthly newsletter and arrived at the same conclusion, though, the performance of these stocks deteriorated in recent years. These stocks outperformed the market by only 26 basis points between 2006 and 2018. Here are Ackman’s best stock picks:
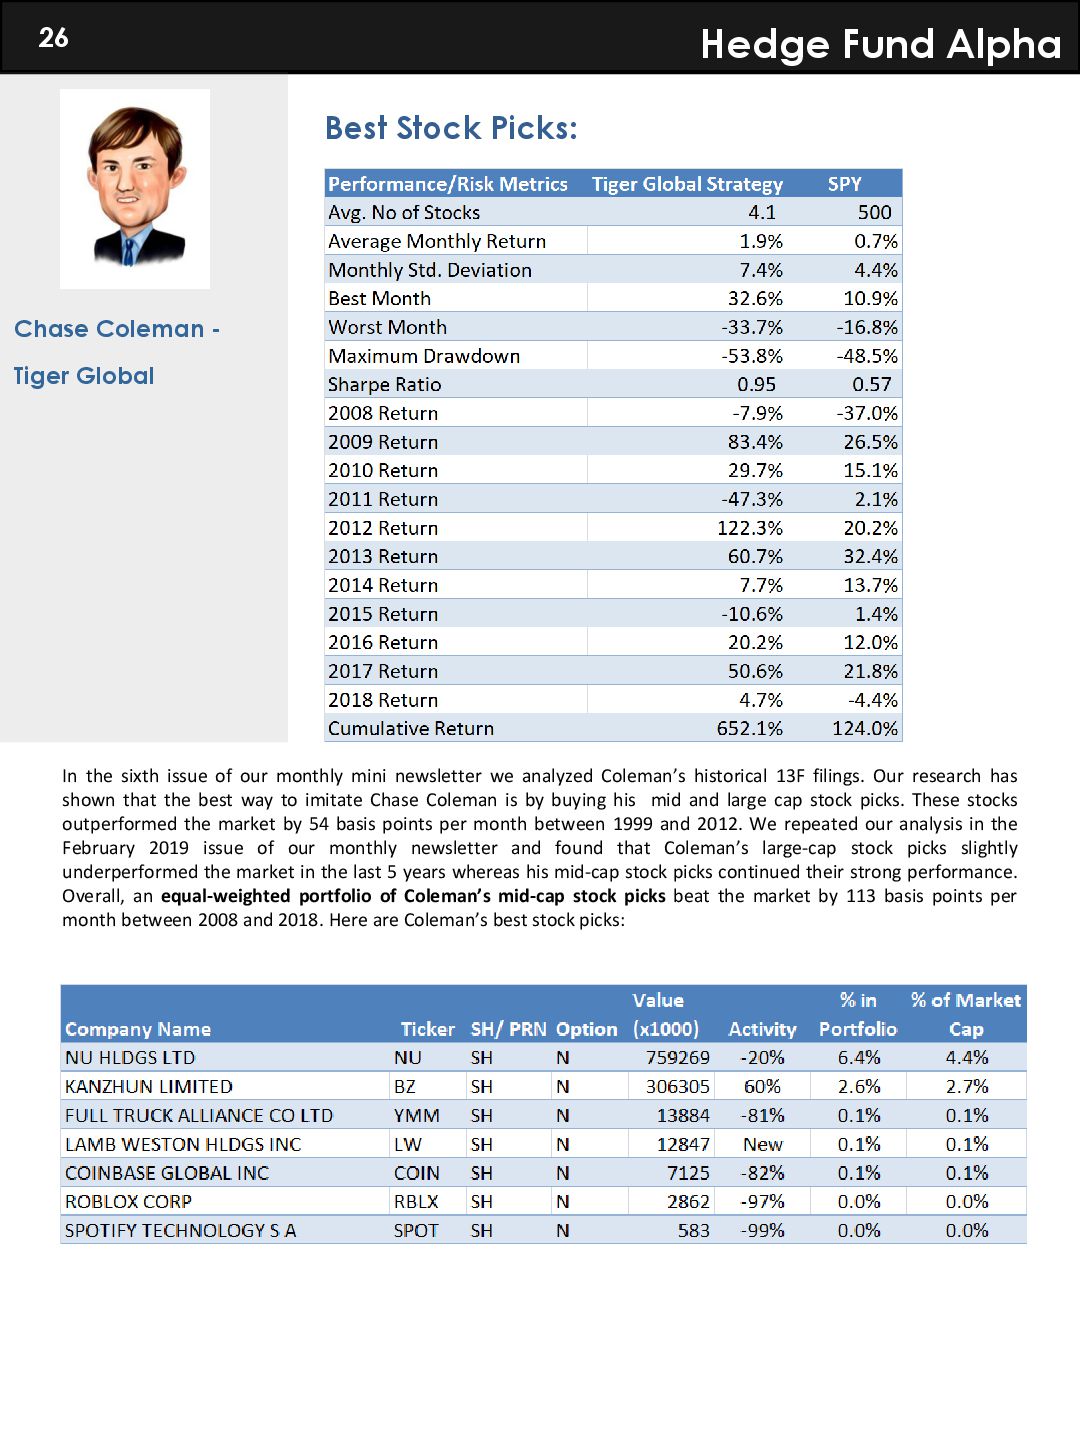
  26. Hedge Fund Alpha 26 Chase Coleman - Tiger Global Best

    Stock Picks: In the sixth issue of our monthly mini newsletter we analyzed Coleman’s historical 13F filings. Our research has shown that the best way to imitate Chase Coleman is by buying his mid and large cap stock picks. These stocks outperformed the market by 54 basis points per month between 1999 and 2012. We repeated our analysis in the February 2019 issue of our monthly newsletter and found that Coleman’s large-cap stock picks slightly underperformed the market in the last 5 years whereas his mid-cap stock picks continued their strong performance. Overall, an equal-weighted portfolio of Coleman’s mid-cap stock picks beat the market by 113 basis points per month between 2008 and 2018. Here are Coleman’s best stock picks:
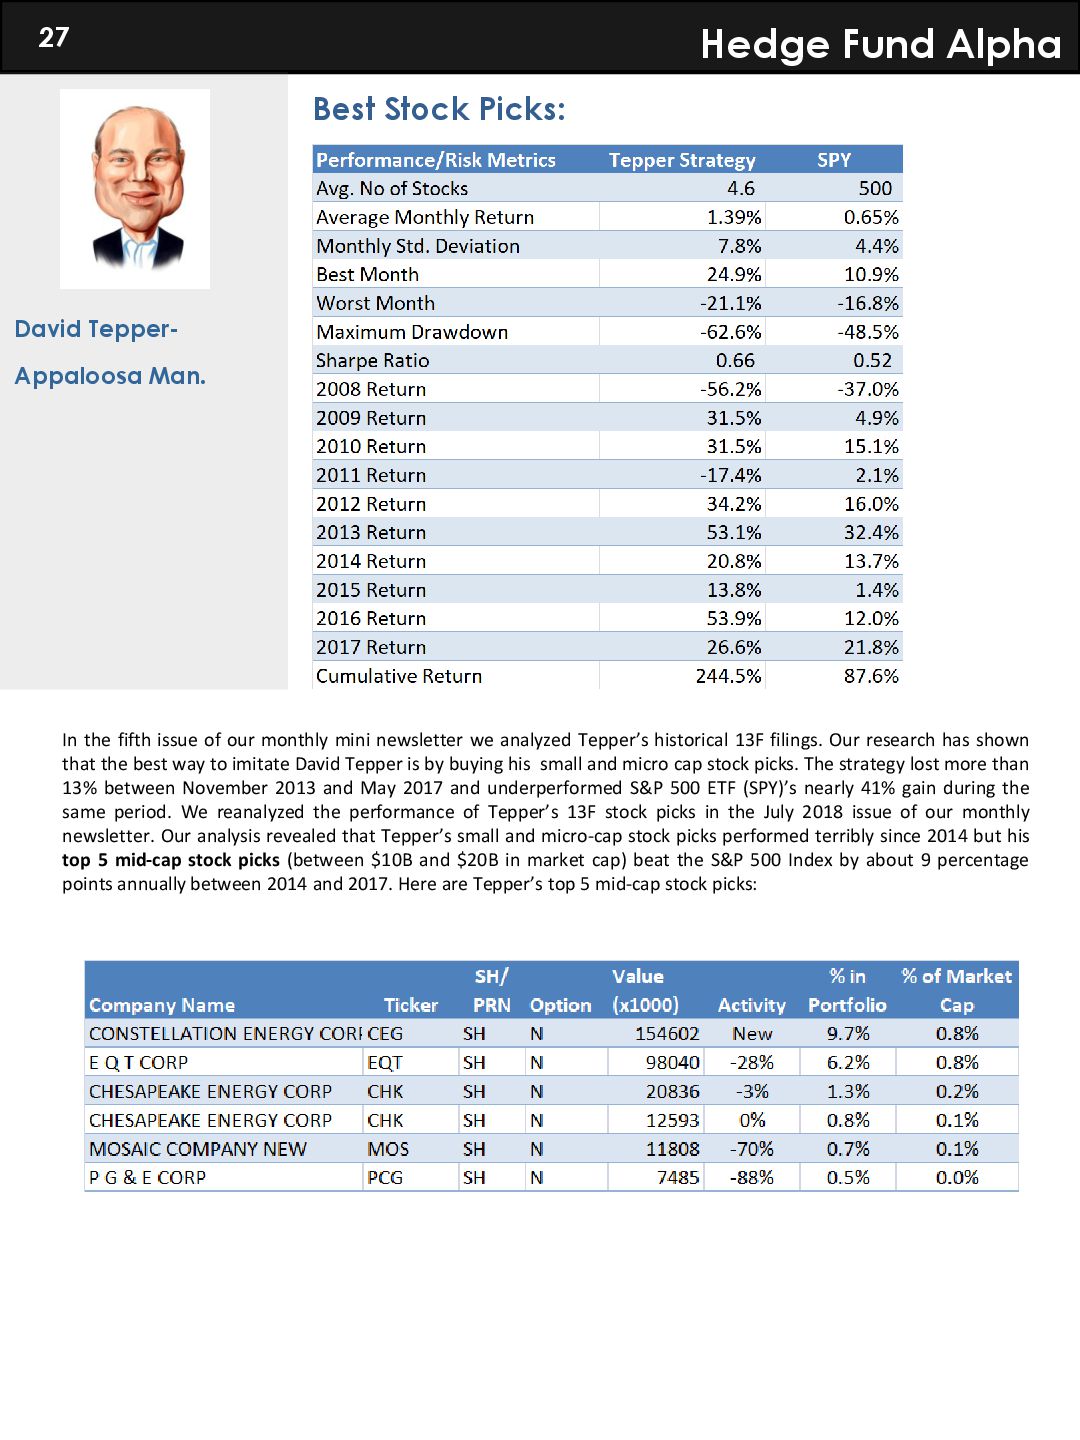
  27. Hedge Fund Alpha 27 David Tepper- Appaloosa Man. Best Stock

    Picks: In the fifth issue of our monthly mini newsletter we analyzed Tepper’s historical 13F filings. Our research has shown that the best way to imitate David Tepper is by buying his small and micro cap stock picks. The strategy lost more than 13% between November 2013 and May 2017 and underperformed S&P 500 ETF (SPY)’s nearly 41% gain during the same period. We reanalyzed the performance of Tepper’s 13F stock picks in the July 2018 issue of our monthly newsletter. Our analysis revealed that Tepper’s small and micro-cap stock picks performed terribly since 2014 but his top 5 mid-cap stock picks (between $10B and $20B in market cap) beat the S&P 500 Index by about 9 percentage points annually between 2014 and 2017. Here are Tepper’s top 5 mid-cap stock picks:
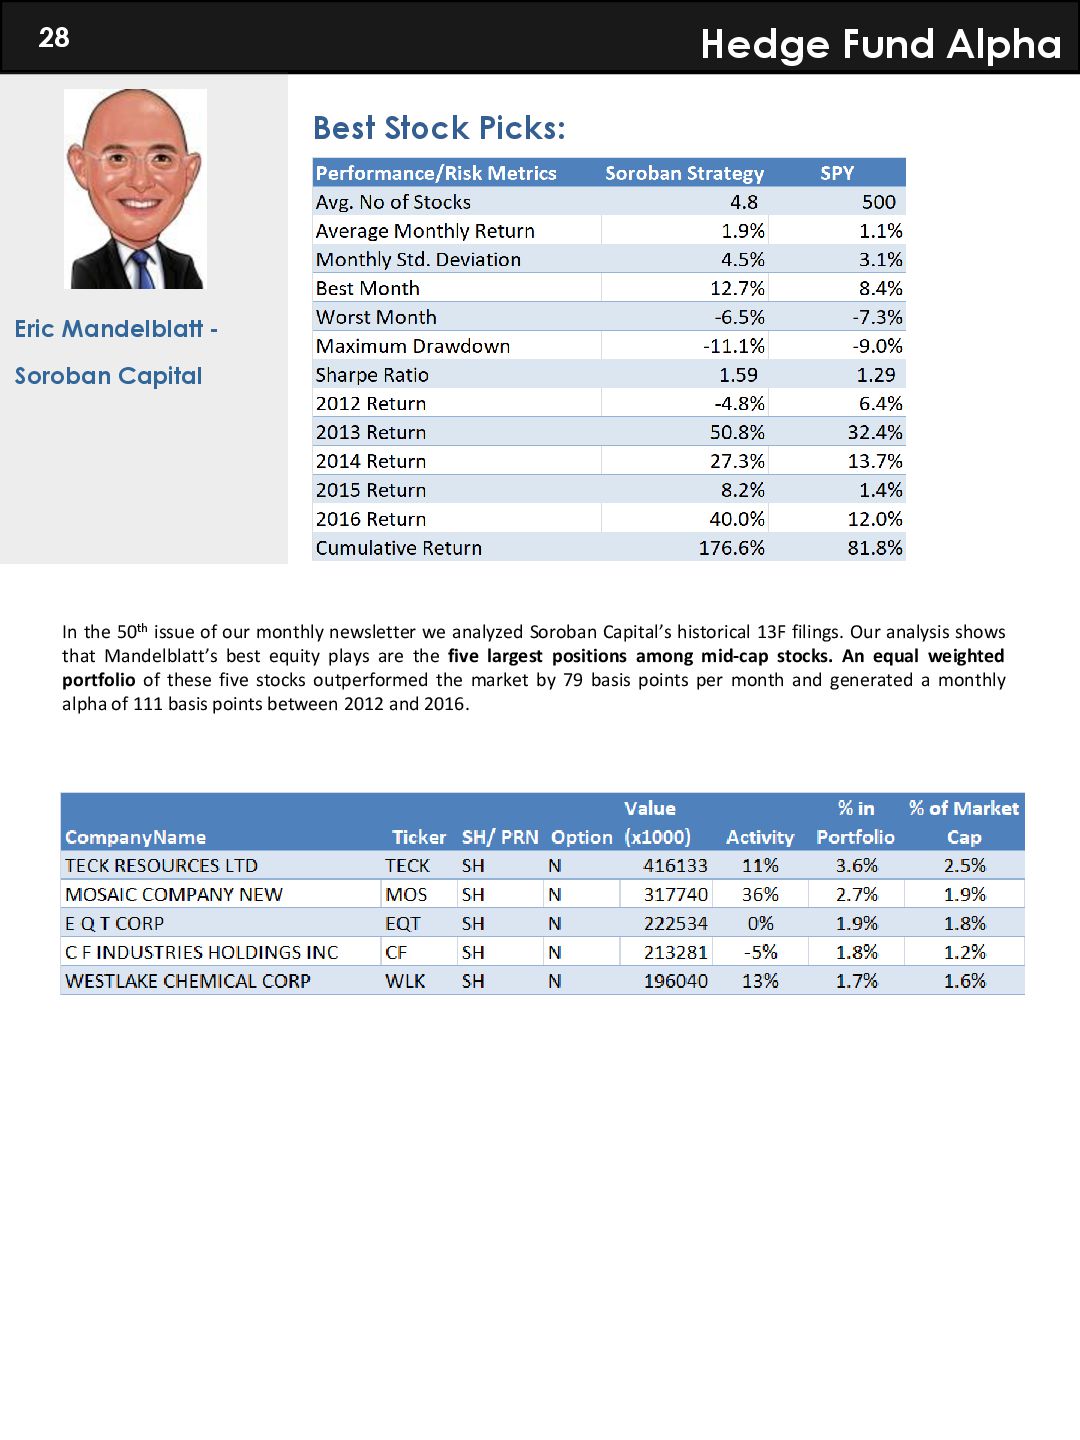
  28. Hedge Fund Alpha 28 Eric Mandelblatt - Soroban Capital Best

    Stock Picks: In the 50th issue of our monthly newsletter we analyzed Soroban Capital’s historical 13F filings. Our analysis shows that Mandelblatt’s best equity plays are the five largest positions among mid-cap stocks. An equal weighted portfolio of these five stocks outperformed the market by 79 basis points per month and generated a monthly alpha of 111 basis points between 2012 and 2016.
  29. Hedge Fund Alpha 29 Andreas Halvorsen - Viking Global Best

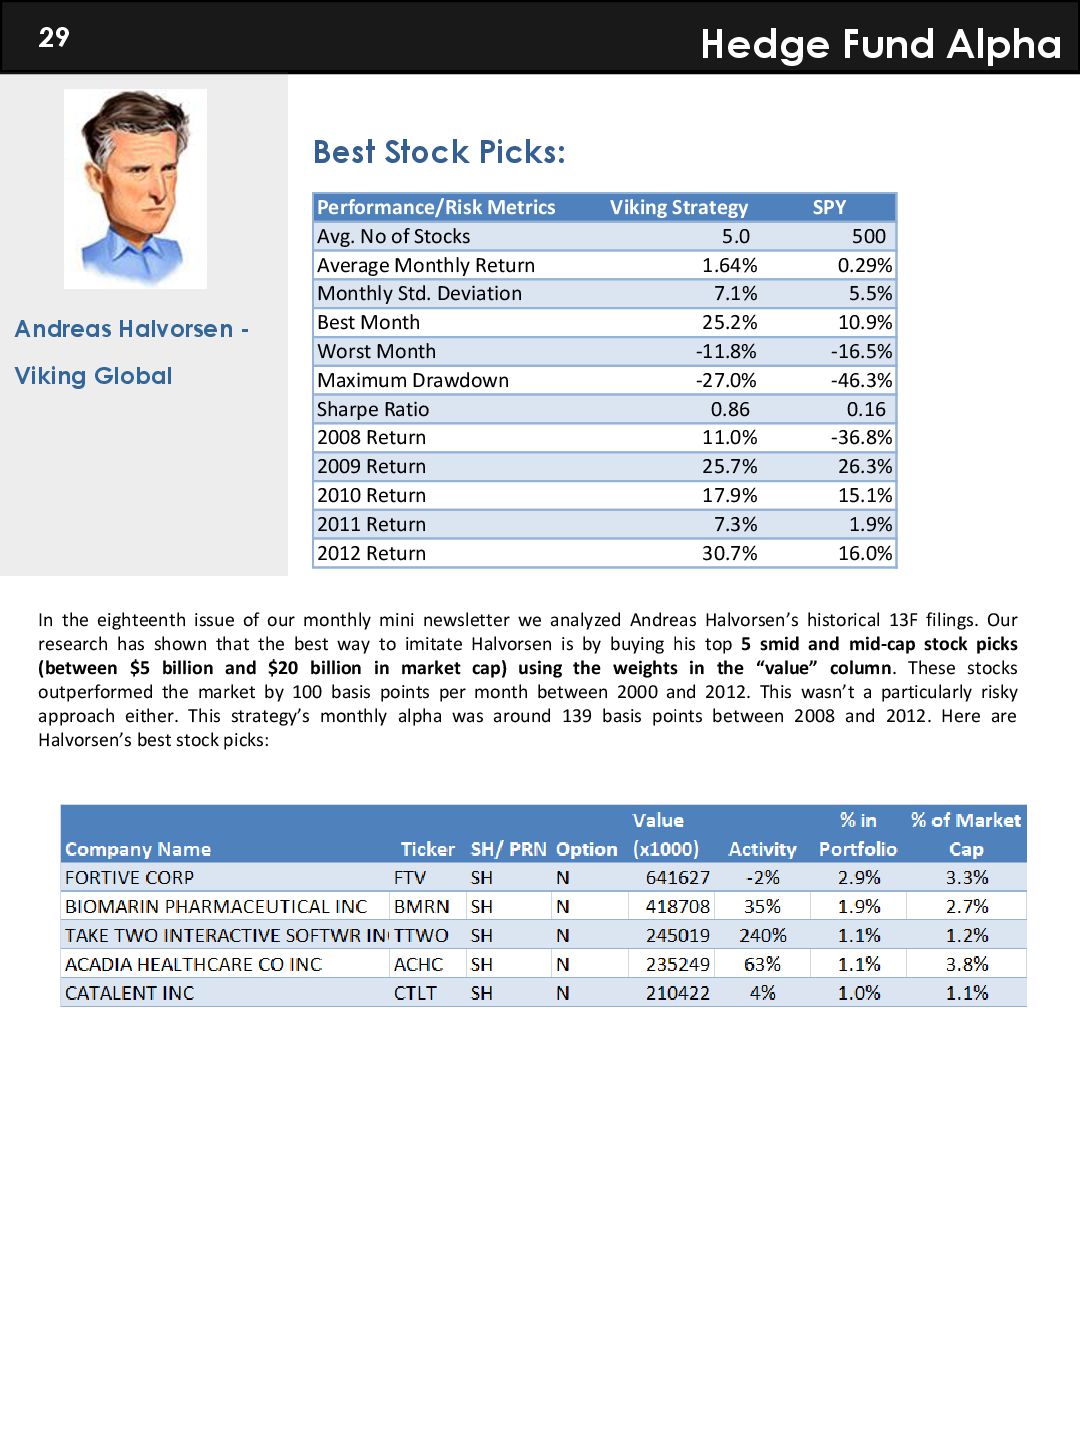
    Stock Picks: In the eighteenth issue of our monthly mini newsletter we analyzed Andreas Halvorsen’s historical 13F filings. Our research has shown that the best way to imitate Halvorsen is by buying his top 5 smid and mid-cap stock picks (between $5 billion and $20 billion in market cap) using the weights in the “value” column. These stocks outperformed the market by 100 basis points per month between 2000 and 2012. This wasn’t a particularly risky approach either. This strategy’s monthly alpha was around 139 basis points between 2008 and 2012. Here are Halvorsen’s best stock picks: Performance/Risk Metrics Viking Strategy SPY Avg. No of Stocks 5.0 500 Average Monthly Return 1.64% 0.29% Monthly Std. Deviation 7.1% 5.5% Best Month 25.2% 10.9% Worst Month -11.8% -16.5% Maximum Drawdown -27.0% -46.3% Sharpe Ratio 0.86 0.16 2008 Return 11.0% -36.8% 2009 Return 25.7% 26.3% 2010 Return 17.9% 15.1% 2011 Return 7.3% 1.9% 2012 Return 30.7% 16.0%
  30. Hedge Fund Alpha 30 Julian Robertson - Tiger Management Best

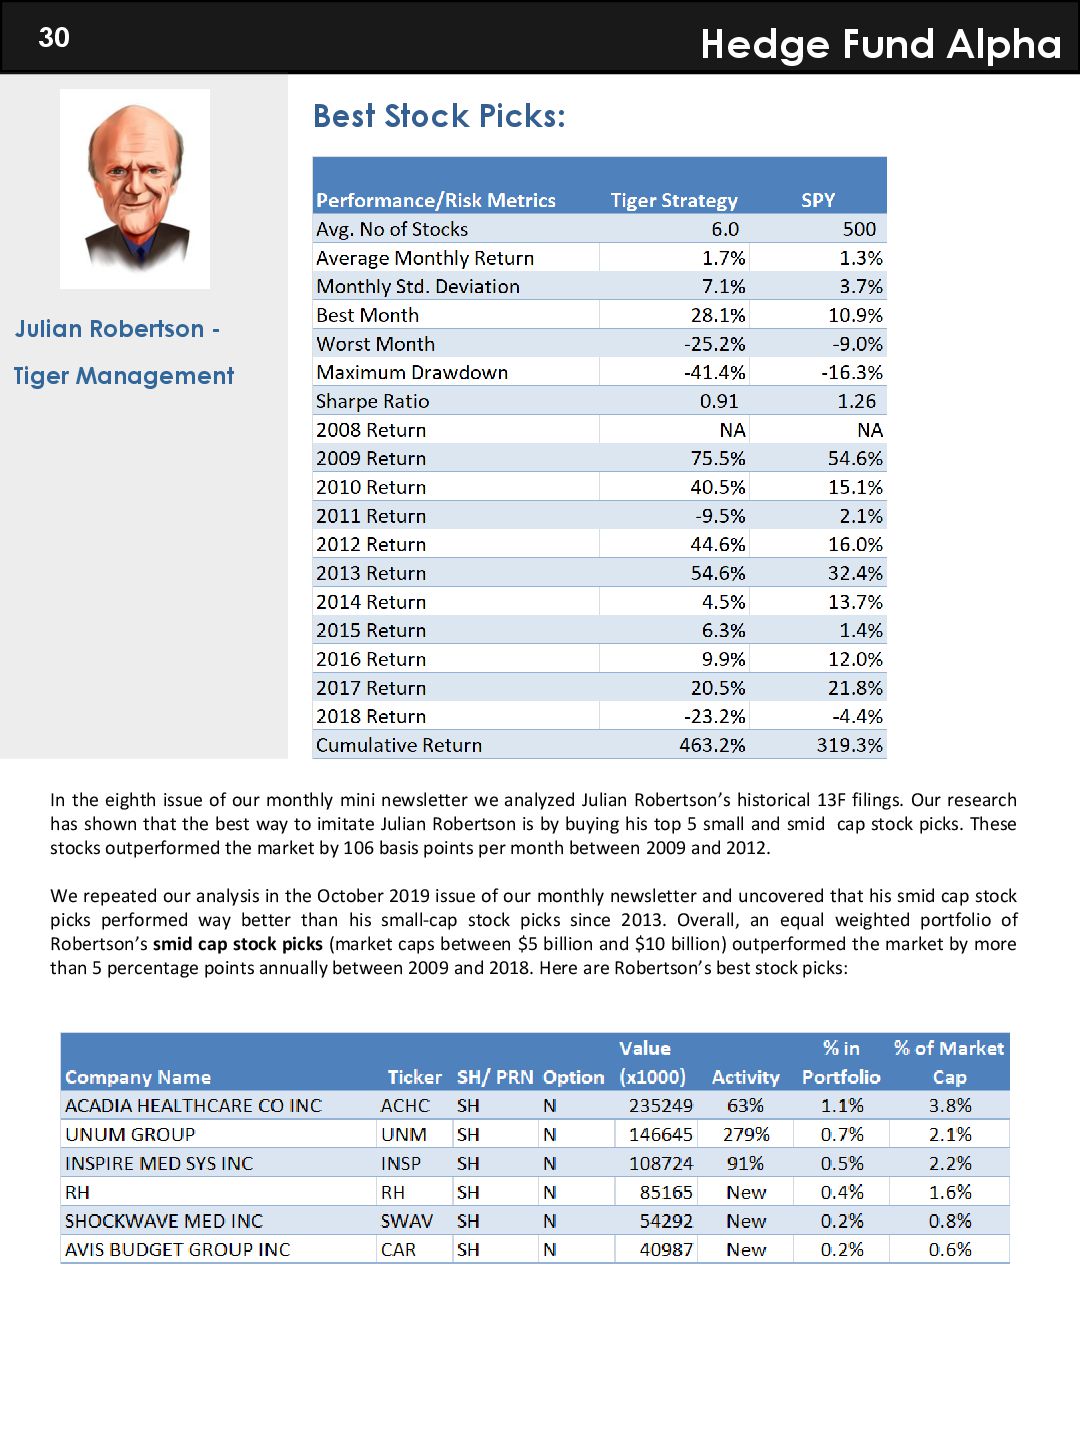
    Stock Picks: In the eighth issue of our monthly mini newsletter we analyzed Julian Robertson’s historical 13F filings. Our research has shown that the best way to imitate Julian Robertson is by buying his top 5 small and smid cap stock picks. These stocks outperformed the market by 106 basis points per month between 2009 and 2012. We repeated our analysis in the October 2019 issue of our monthly newsletter and uncovered that his smid cap stock picks performed way better than his small-cap stock picks since 2013. Overall, an equal weighted portfolio of Robertson’s smid cap stock picks (market caps between $5 billion and $10 billion) outperformed the market by more than 5 percentage points annually between 2009 and 2018. Here are Robertson’s best stock picks:
  31. Hedge Fund Alpha 31 Jim Simons - Renaissance Tech Best

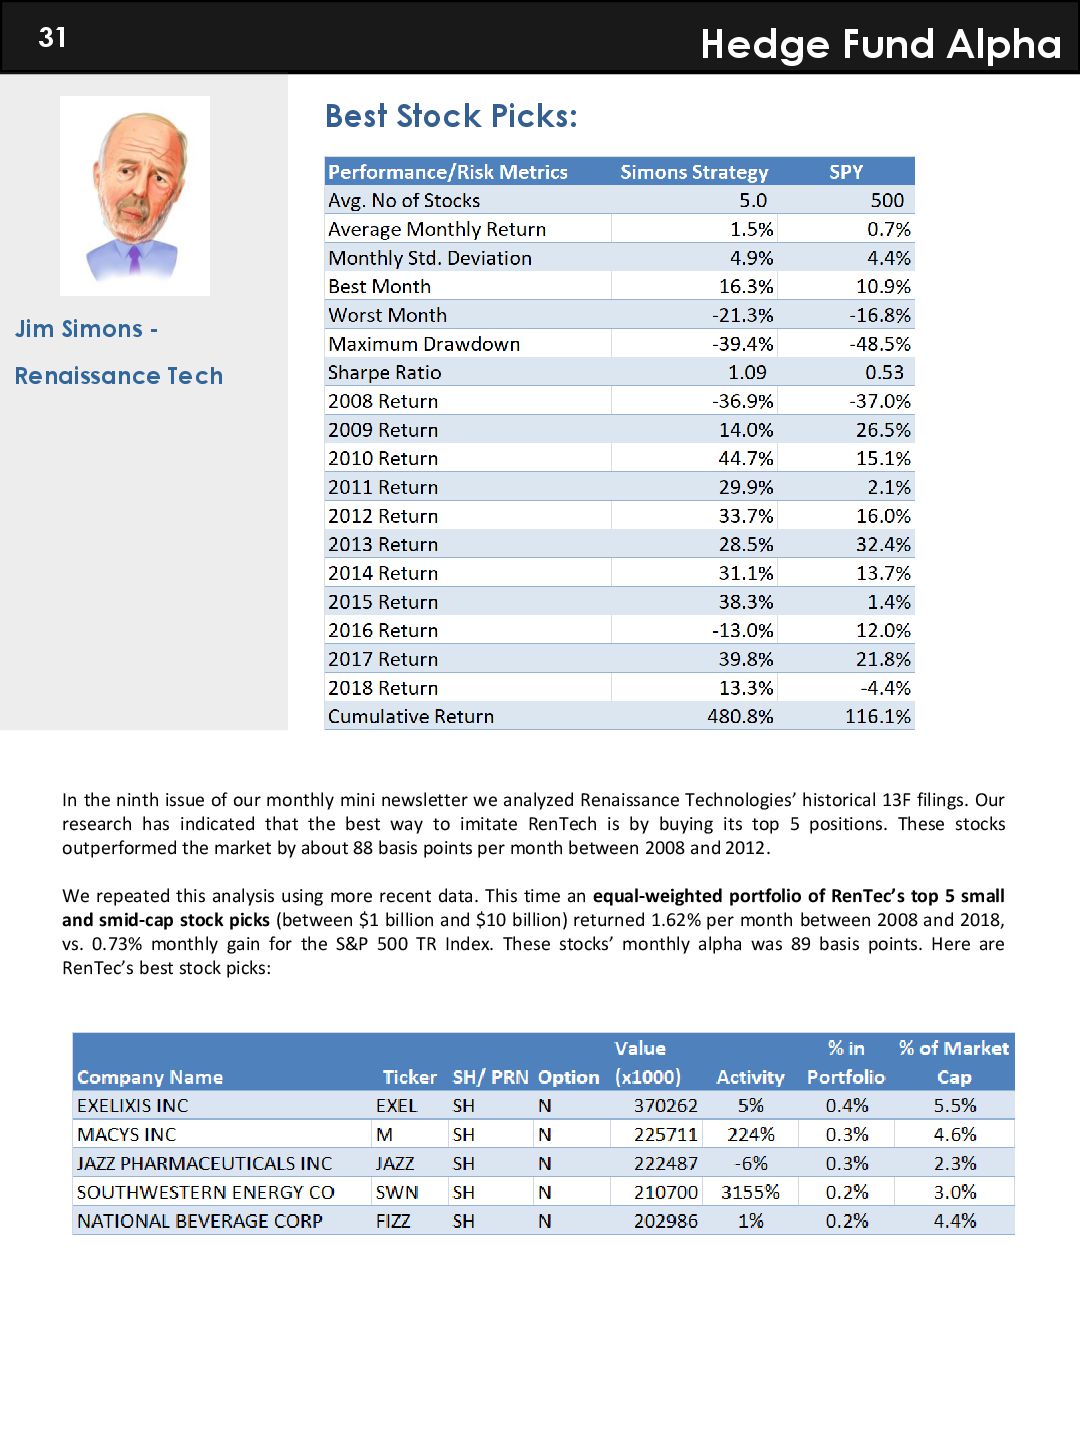
    Stock Picks: In the ninth issue of our monthly mini newsletter we analyzed Renaissance Technologies’ historical 13F filings. Our research has indicated that the best way to imitate RenTech is by buying its top 5 positions. These stocks outperformed the market by about 88 basis points per month between 2008 and 2012. We repeated this analysis using more recent data. This time an equal-weighted portfolio of RenTec’s top 5 small and smid-cap stock picks (between $1 billion and $10 billion) returned 1.62% per month between 2008 and 2018, vs. 0.73% monthly gain for the S&P 500 TR Index. These stocks’ monthly alpha was 89 basis points. Here are RenTec’s best stock picks:
  32. Hedge Fund Alpha 32 Jeff Smith - Starboard Value Best

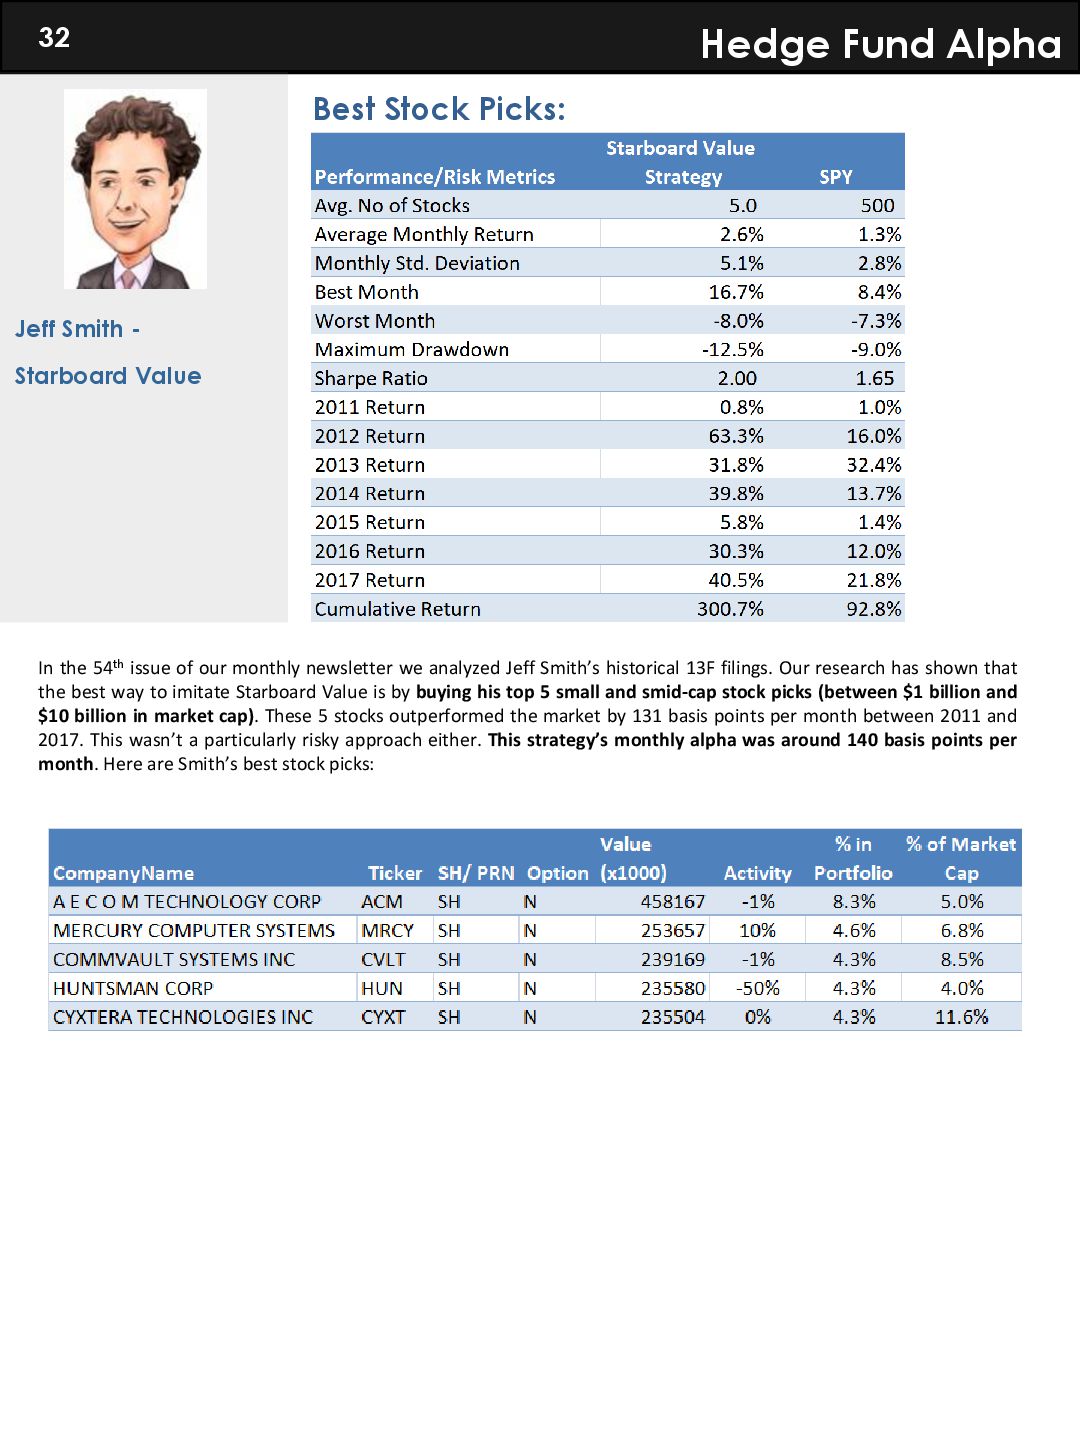
    Stock Picks: In the 54th issue of our monthly newsletter we analyzed Jeff Smith’s historical 13F filings. Our research has shown that the best way to imitate Starboard Value is by buying his top 5 small and smid-cap stock picks (between $1 billion and $10 billion in market cap). These 5 stocks outperformed the market by 131 basis points per month between 2011 and 2017. This wasn’t a particularly risky approach either. This strategy’s monthly alpha was around 140 basis points per month. Here are Smith’s best stock picks:
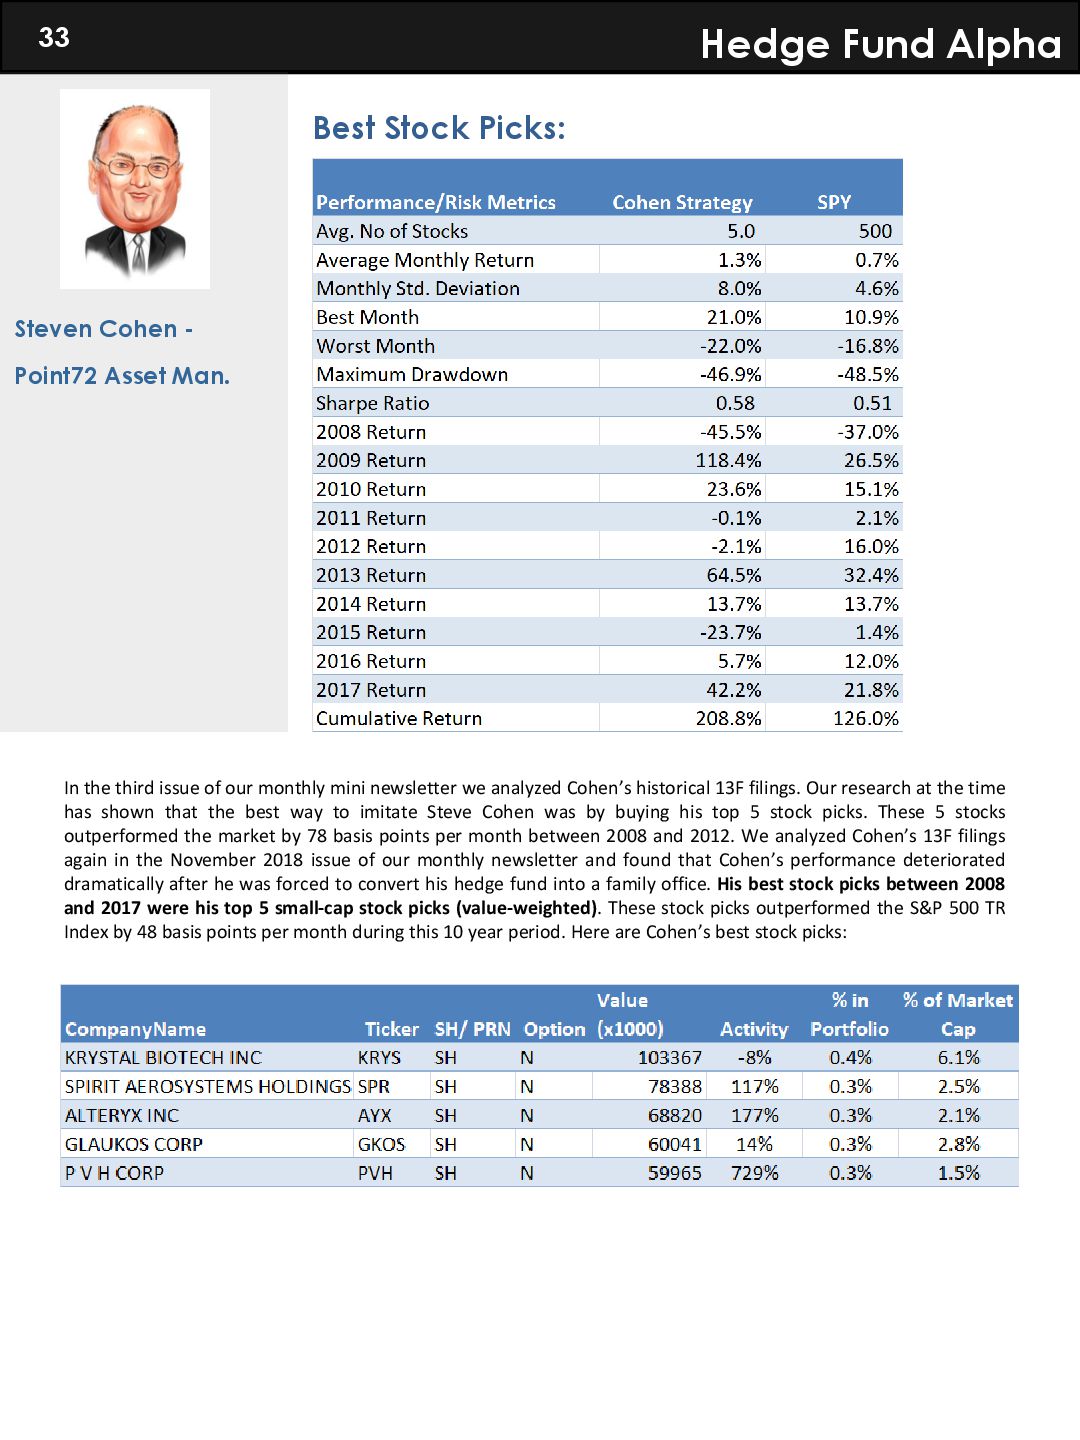
  33. Hedge Fund Alpha 33 Steven Cohen - Point72 Asset Man.

    Best Stock Picks: In the third issue of our monthly mini newsletter we analyzed Cohen’s historical 13F filings. Our research at the time has shown that the best way to imitate Steve Cohen was by buying his top 5 stock picks. These 5 stocks outperformed the market by 78 basis points per month between 2008 and 2012. We analyzed Cohen’s 13F filings again in the November 2018 issue of our monthly newsletter and found that Cohen’s performance deteriorated dramatically after he was forced to convert his hedge fund into a family office. His best stock picks between 2008 and 2017 were his top 5 small-cap stock picks (value-weighted). These stock picks outperformed the S&P 500 TR Index by 48 basis points per month during this 10 year period. Here are Cohen’s best stock picks:
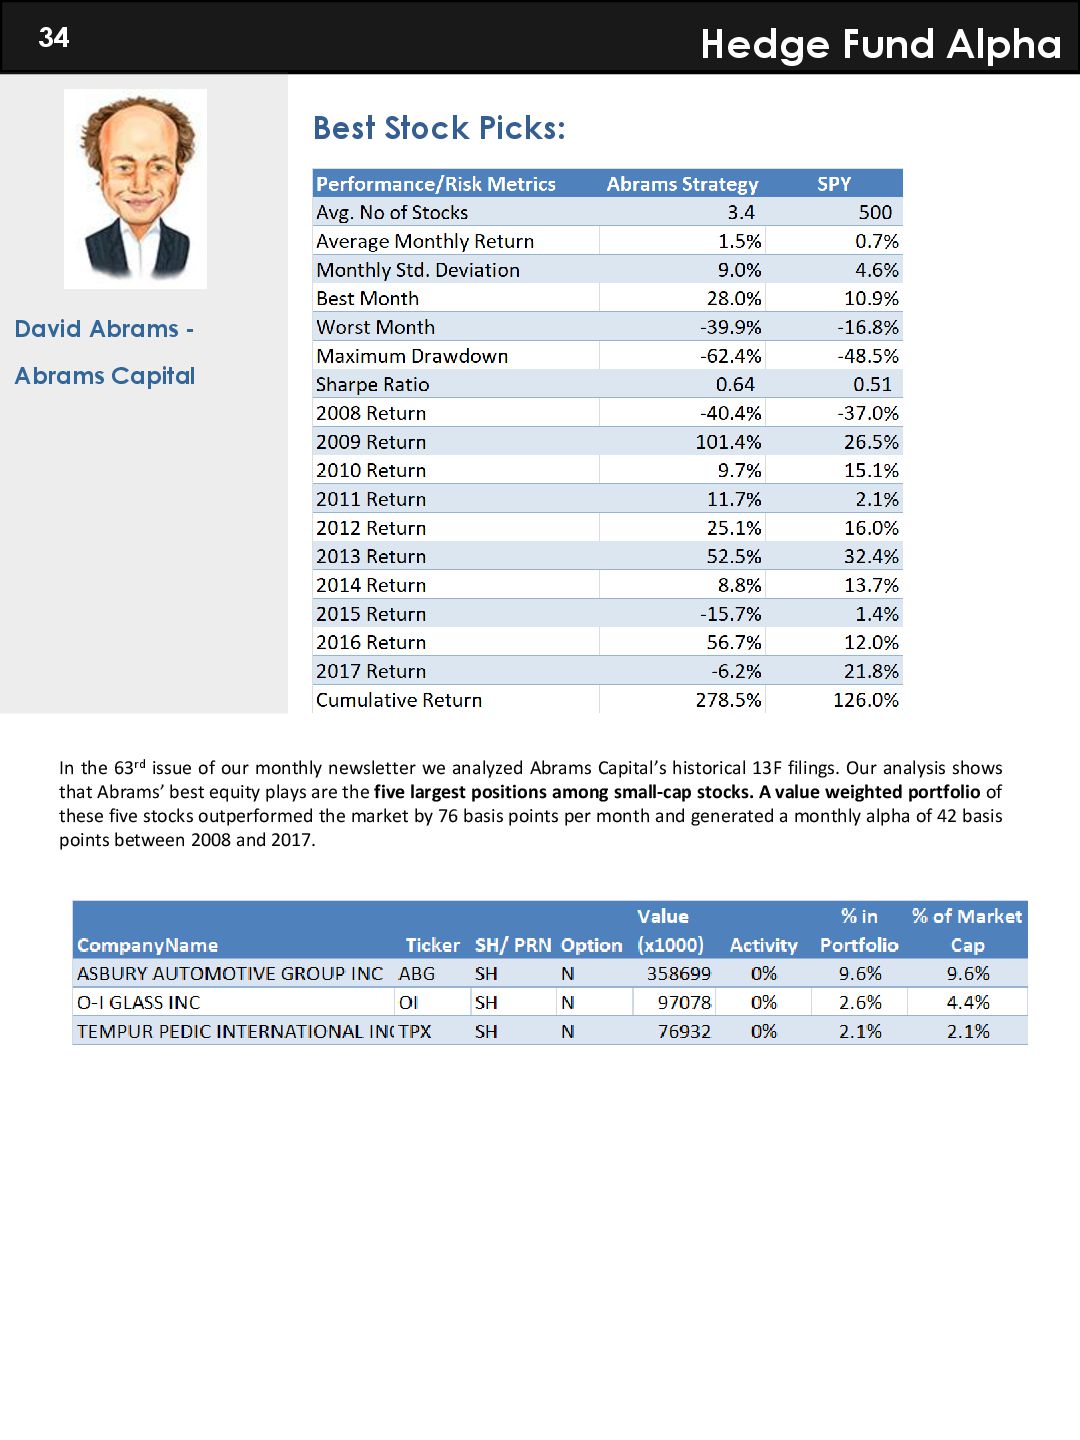
  34. Hedge Fund Alpha 34 David Abrams - Abrams Capital Best

    Stock Picks: In the 63rd issue of our monthly newsletter we analyzed Abrams Capital’s historical 13F filings. Our analysis shows that Abrams’ best equity plays are the five largest positions among small-cap stocks. A value weighted portfolio of these five stocks outperformed the market by 76 basis points per month and generated a monthly alpha of 42 basis points between 2008 and 2017.
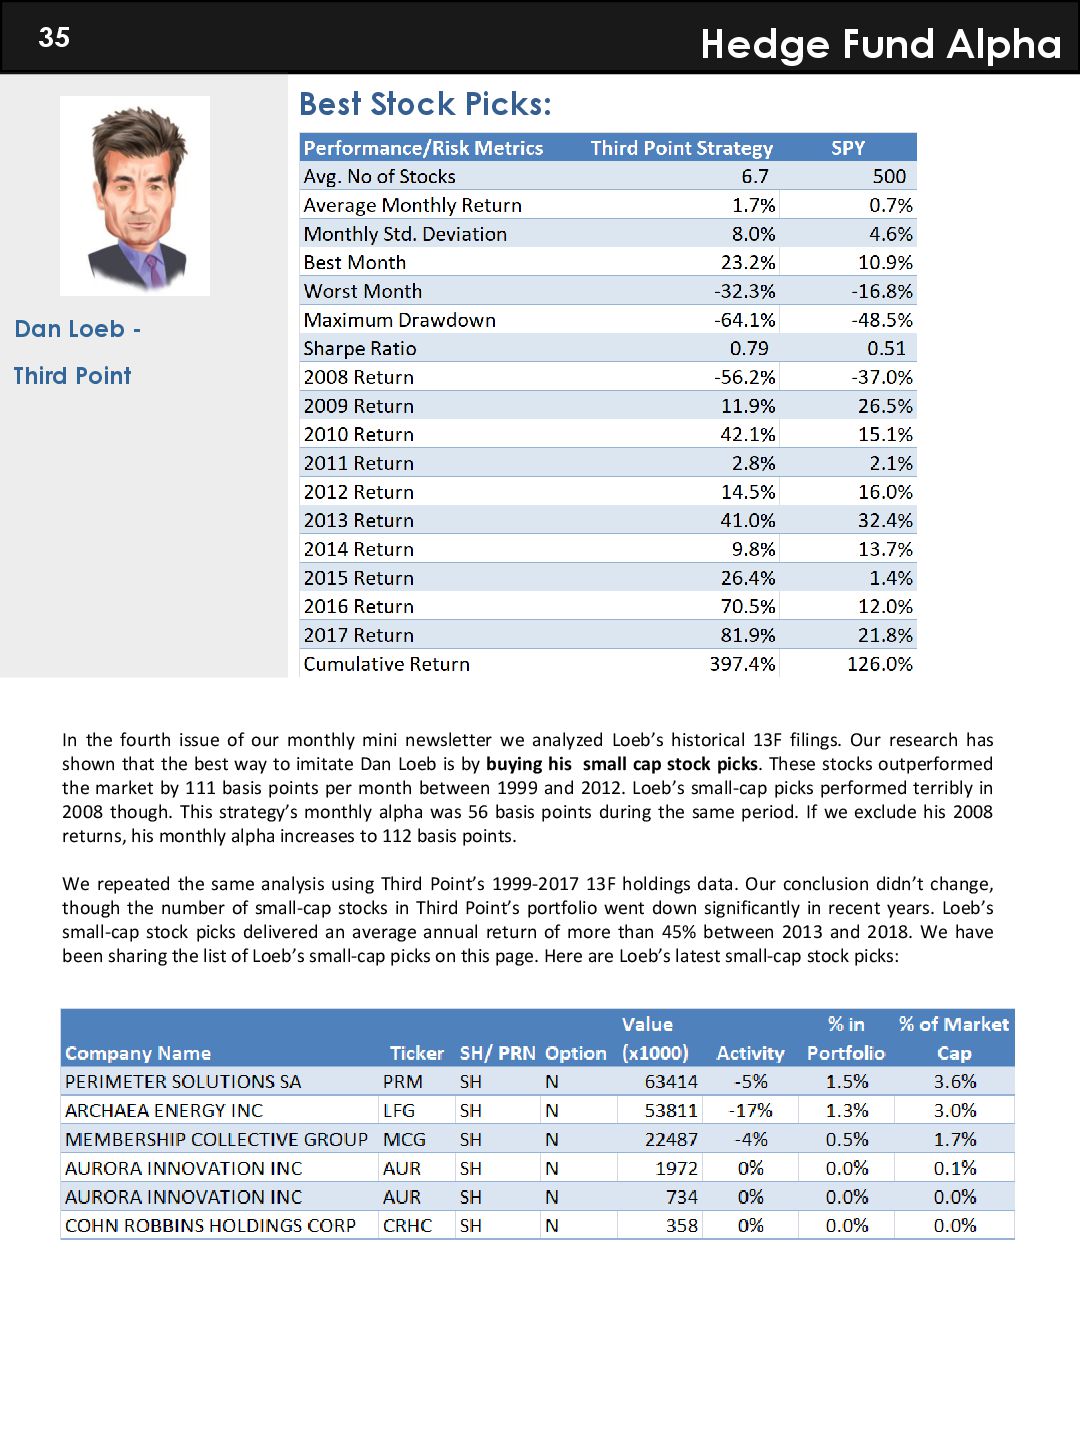
  35. Hedge Fund Alpha 35 Dan Loeb - Third Point Best

    Stock Picks: In the fourth issue of our monthly mini newsletter we analyzed Loeb’s historical 13F filings. Our research has shown that the best way to imitate Dan Loeb is by buying his small cap stock picks. These stocks outperformed the market by 111 basis points per month between 1999 and 2012. Loeb’s small-cap picks performed terribly in 2008 though. This strategy’s monthly alpha was 56 basis points during the same period. If we exclude his 2008 returns, his monthly alpha increases to 112 basis points. We repeated the same analysis using Third Point’s 1999-2017 13F holdings data. Our conclusion didn’t change, though the number of small-cap stocks in Third Point’s portfolio went down significantly in recent years. Loeb’s small-cap stock picks delivered an average annual return of more than 45% between 2013 and 2018. We have been sharing the list of Loeb’s small-cap picks on this page. Here are Loeb’s latest small-cap stock picks:
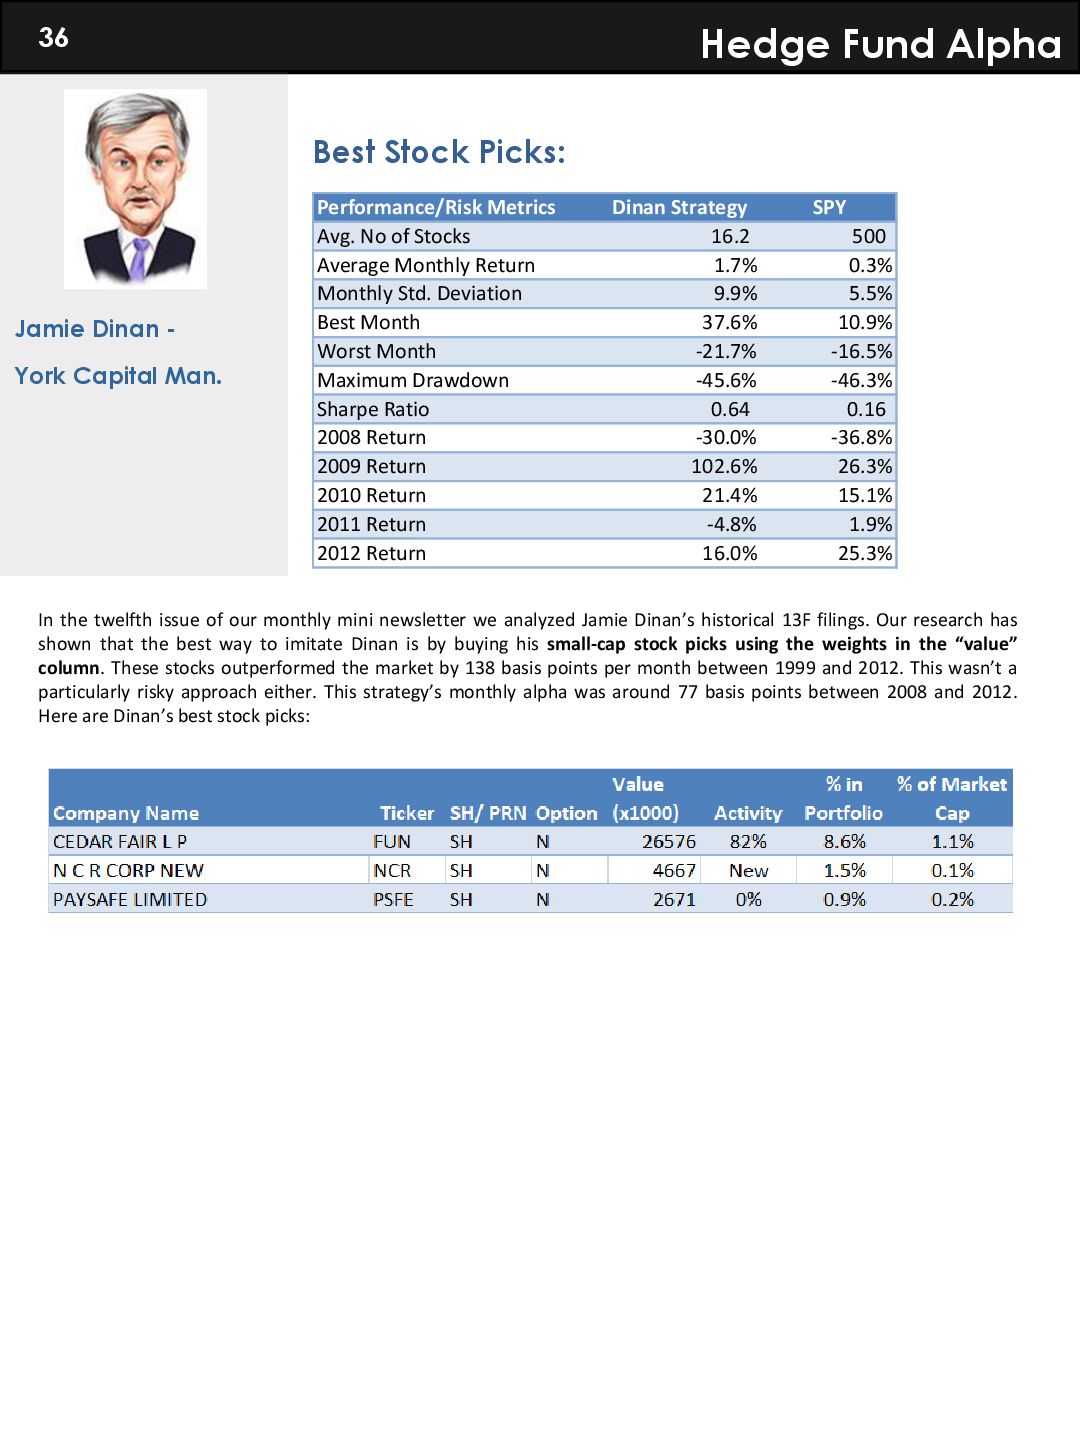
  36. Hedge Fund Alpha 36 Jamie Dinan - York Capital Man.

    Best Stock Picks: In the twelfth issue of our monthly mini newsletter we analyzed Jamie Dinan’s historical 13F filings. Our research has shown that the best way to imitate Dinan is by buying his small-cap stock picks using the weights in the “value” column. These stocks outperformed the market by 138 basis points per month between 1999 and 2012. This wasn’t a particularly risky approach either. This strategy’s monthly alpha was around 77 basis points between 2008 and 2012. Here are Dinan’s best stock picks: Performance/Risk Metrics Dinan Strategy SPY Avg. No of Stocks 16.2 500 Average Monthly Return 1.7% 0.3% Monthly Std. Deviation 9.9% 5.5% Best Month 37.6% 10.9% Worst Month -21.7% -16.5% Maximum Drawdown -45.6% -46.3% Sharpe Ratio 0.64 0.16 2008 Return -30.0% -36.8% 2009 Return 102.6% 26.3% 2010 Return 21.4% 15.1% 2011 Return -4.8% 1.9% 2012 Return 16.0% 25.3%
  37. Hedge Fund Alpha 37 Jeff Ubben and Mason Morfit -

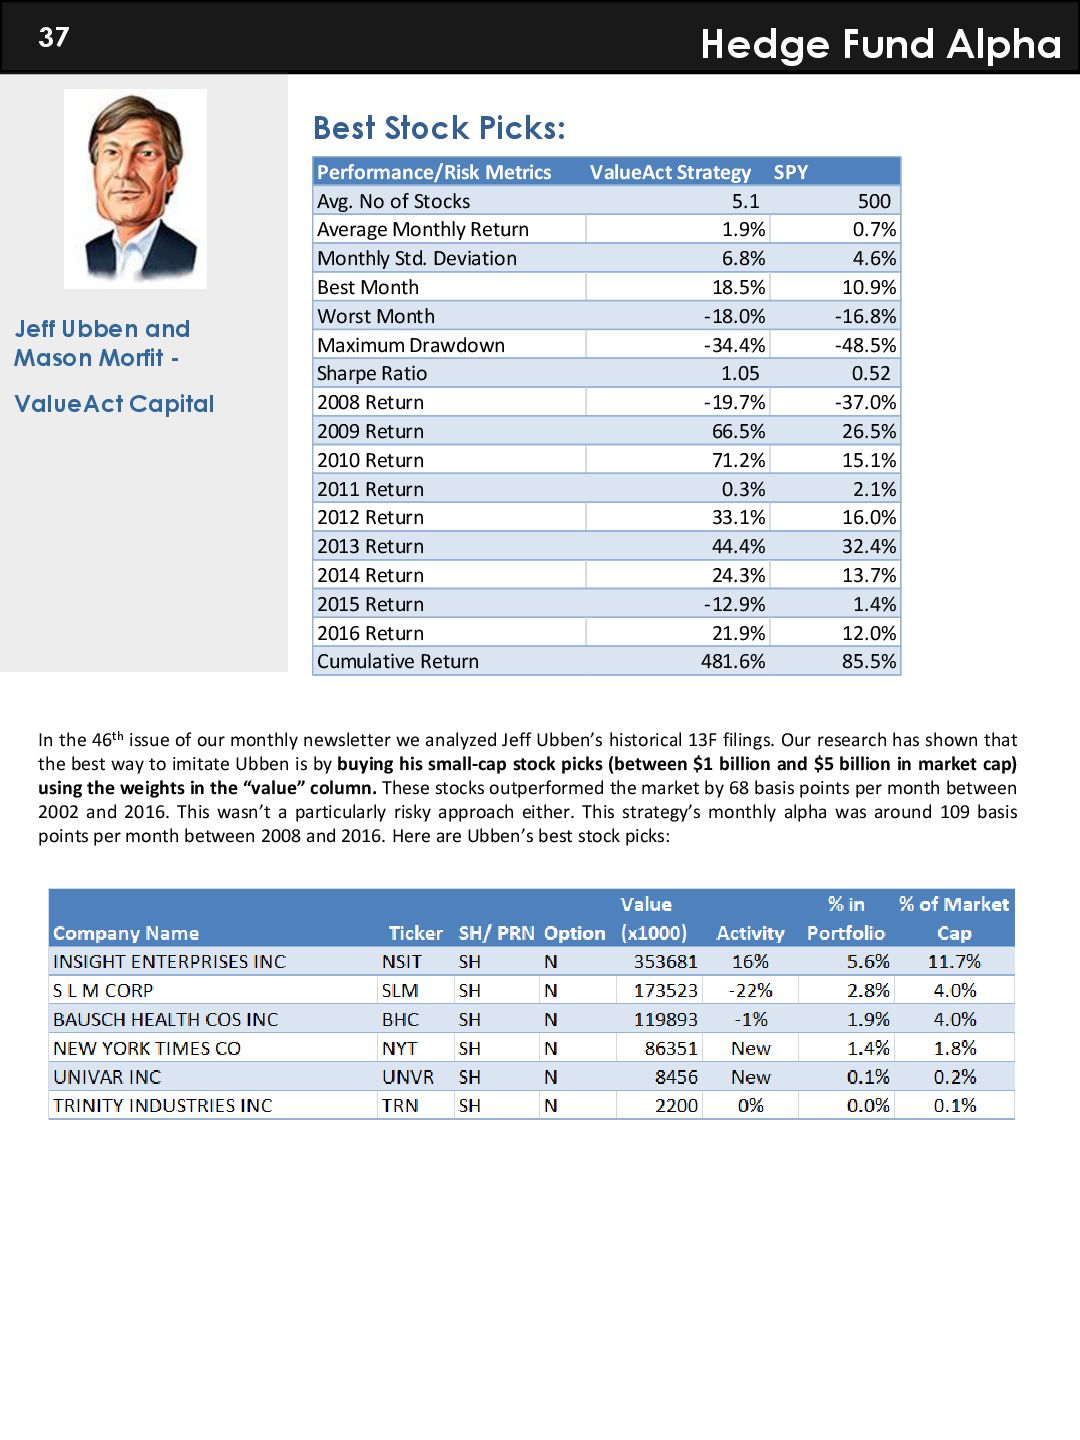
    ValueAct Capital Best Stock Picks: In the 46th issue of our monthly newsletter we analyzed Jeff Ubben’s historical 13F filings. Our research has shown that the best way to imitate Ubben is by buying his small-cap stock picks (between $1 billion and $5 billion in market cap) using the weights in the “value” column. These stocks outperformed the market by 68 basis points per month between 2002 and 2016. This wasn’t a particularly risky approach either. This strategy’s monthly alpha was around 109 basis points per month between 2008 and 2016. Here are Ubben’s best stock picks: Performance/Risk Metrics ValueAct Strategy SPY Avg. No of Stocks 5.1 500 Average Monthly Return 1.9% 0.7% Monthly Std. Deviation 6.8% 4.6% Best Month 18.5% 10.9% Worst Month -18.0% -16.8% Maximum Drawdown -34.4% -48.5% Sharpe Ratio 1.05 0.52 2008 Return -19.7% -37.0% 2009 Return 66.5% 26.5% 2010 Return 71.2% 15.1% 2011 Return 0.3% 2.1% 2012 Return 33.1% 16.0% 2013 Return 44.4% 32.4% 2014 Return 24.3% 13.7% 2015 Return -12.9% 1.4% 2016 Return 21.9% 12.0% Cumulative Return 481.6% 85.5%
  38. Ray Dalio - Bridgewater Associates Hedge Fund Alpha 38 Best

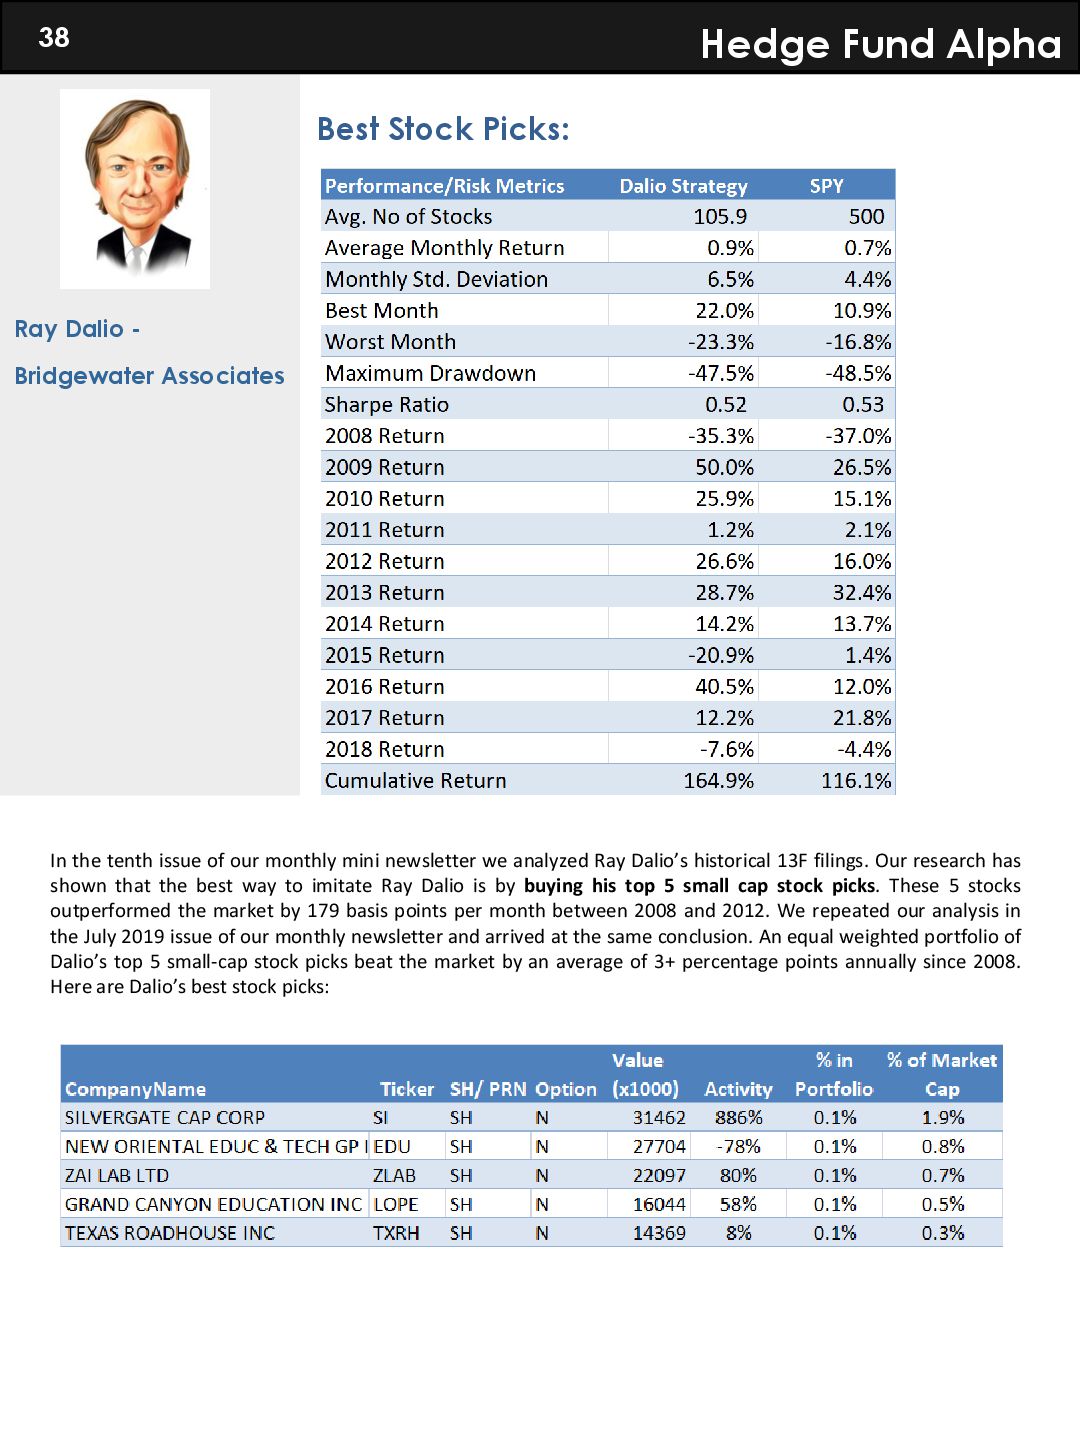
    Stock Picks: In the tenth issue of our monthly mini newsletter we analyzed Ray Dalio’s historical 13F filings. Our research has shown that the best way to imitate Ray Dalio is by buying his top 5 small cap stock picks. These 5 stocks outperformed the market by 179 basis points per month between 2008 and 2012. We repeated our analysis in the July 2019 issue of our monthly newsletter and arrived at the same conclusion. An equal weighted portfolio of Dalio’s top 5 small-cap stock picks beat the market by an average of 3+ percentage points annually since 2008. Here are Dalio’s best stock picks:
  39. Hedge Fund Alpha 39 Nelson Peltz - Trian Partners Best

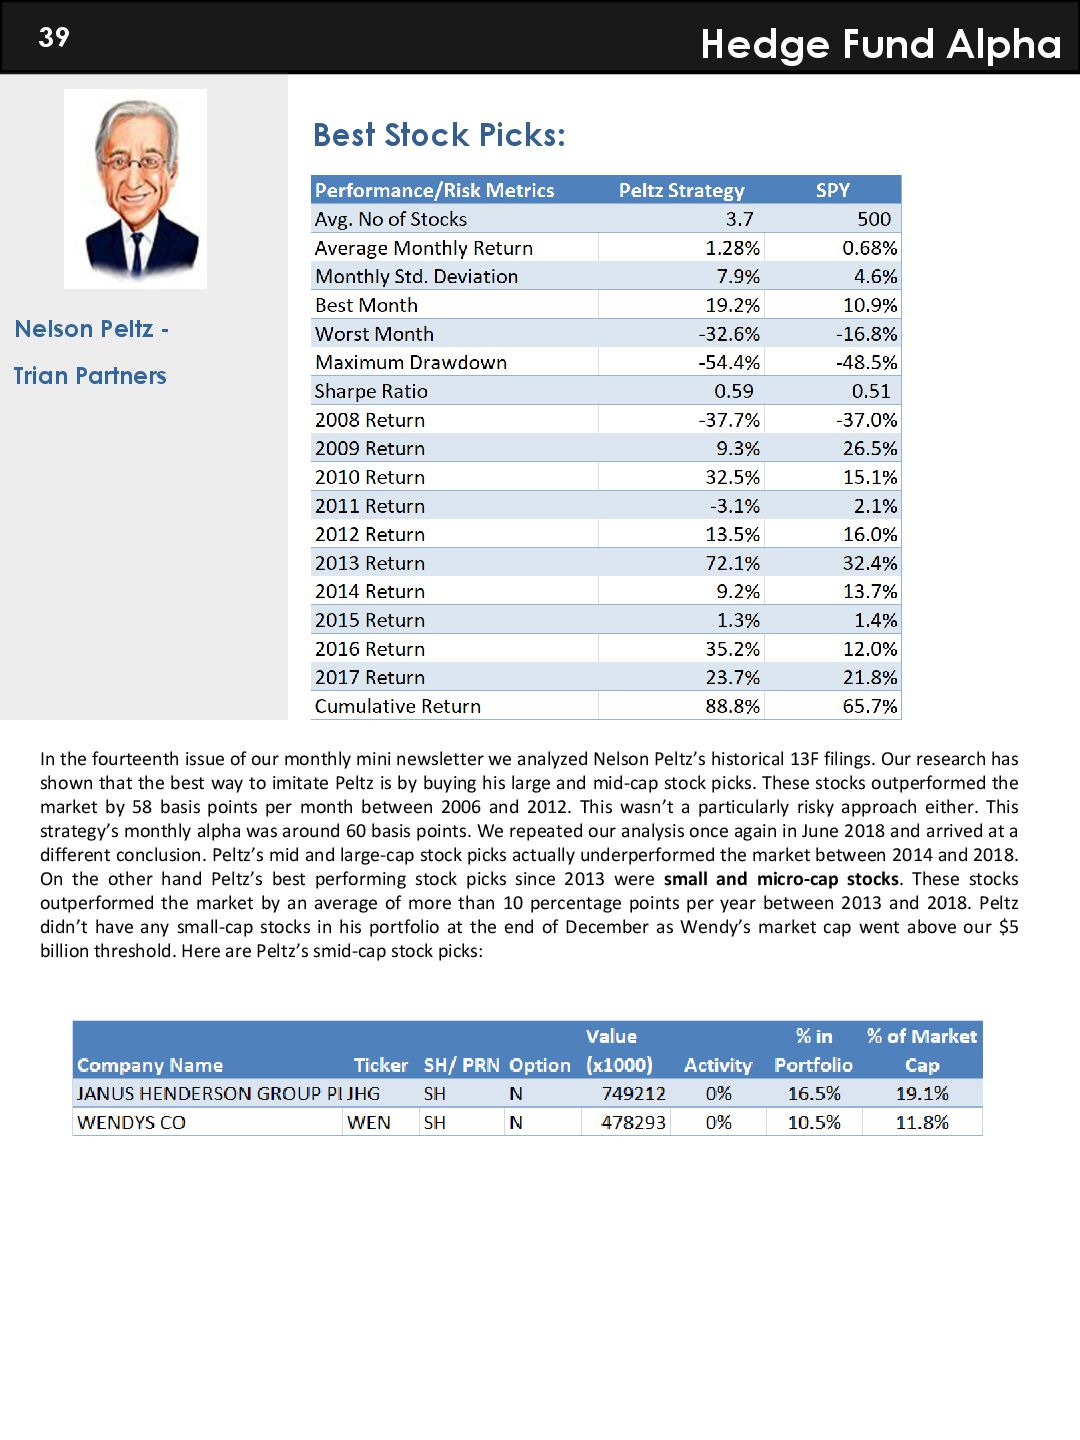
    Stock Picks: In the fourteenth issue of our monthly mini newsletter we analyzed Nelson Peltz’s historical 13F filings. Our research has shown that the best way to imitate Peltz is by buying his large and mid-cap stock picks. These stocks outperformed the market by 58 basis points per month between 2006 and 2012. This wasn’t a particularly risky approach either. This strategy’s monthly alpha was around 60 basis points. We repeated our analysis once again in June 2018 and arrived at a different conclusion. Peltz’s mid and large-cap stock picks actually underperformed the market between 2014 and 2018. On the other hand Peltz’s best performing stock picks since 2013 were small and micro-cap stocks. These stocks outperformed the market by an average of more than 10 percentage points per year between 2013 and 2018. Peltz didn’t have any small-cap stocks in his portfolio at the end of December as Wendy’s market cap went above our $5 billion threshold. Here are Peltz’s smid-cap stock picks:
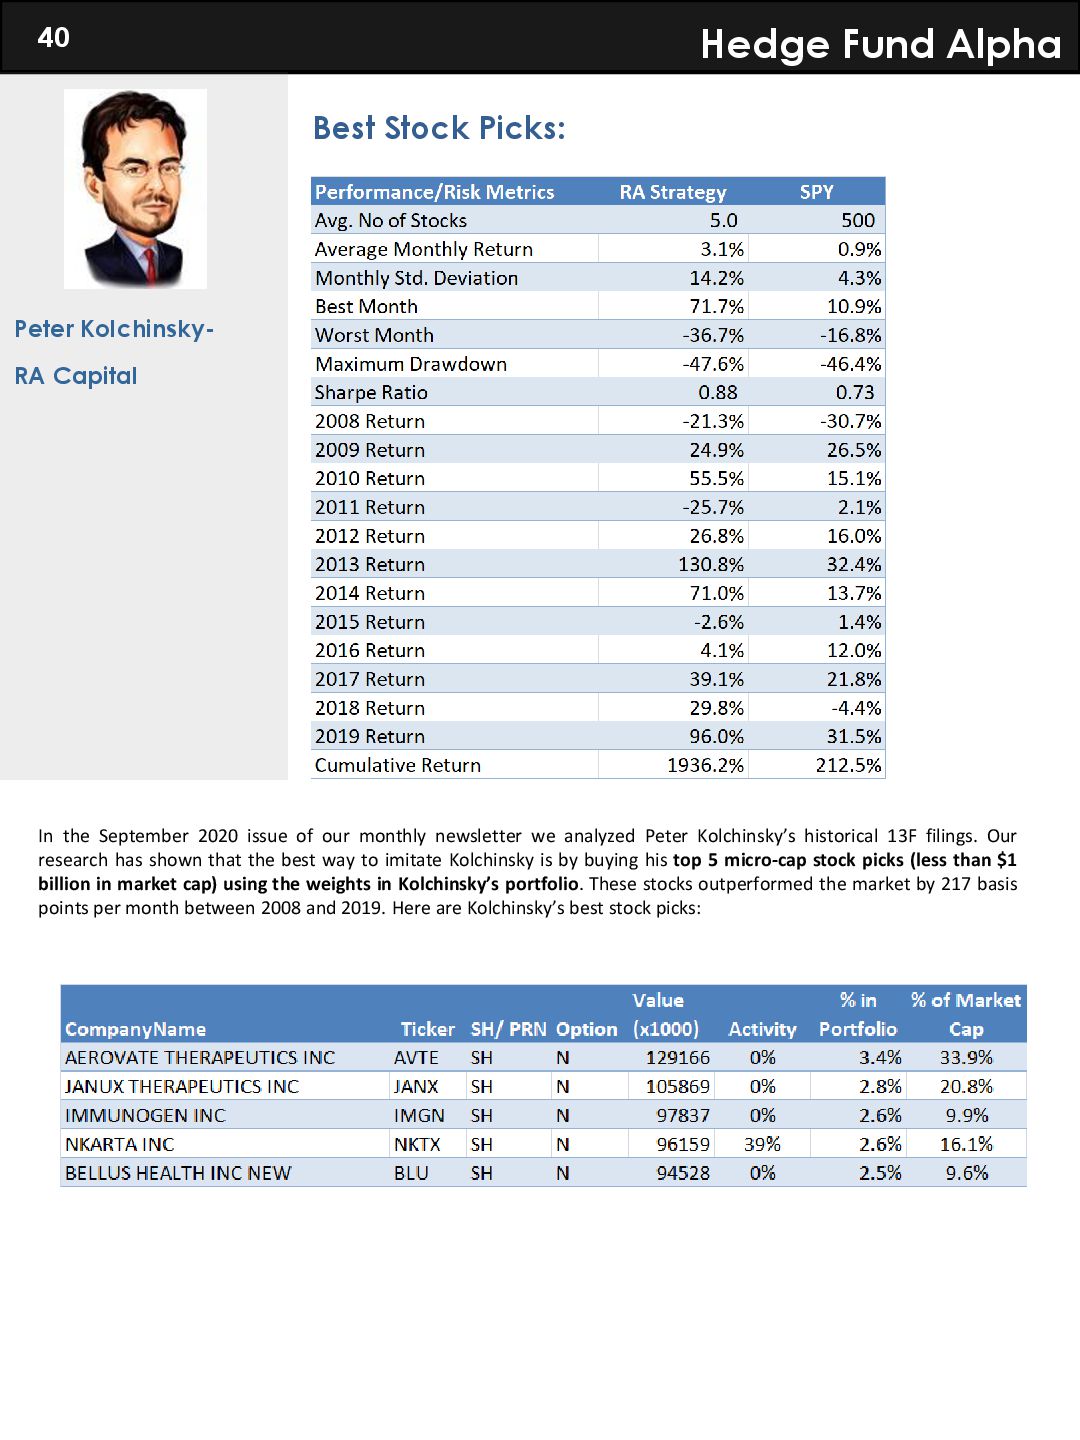
  40. Hedge Fund Alpha 40 Peter Kolchinsky- RA Capital Best Stock

    Picks: In the September 2020 issue of our monthly newsletter we analyzed Peter Kolchinsky’s historical 13F filings. Our research has shown that the best way to imitate Kolchinsky is by buying his top 5 micro-cap stock picks (less than $1 billion in market cap) using the weights in Kolchinsky’s portfolio. These stocks outperformed the market by 217 basis points per month between 2008 and 2019. Here are Kolchinsky’s best stock picks:
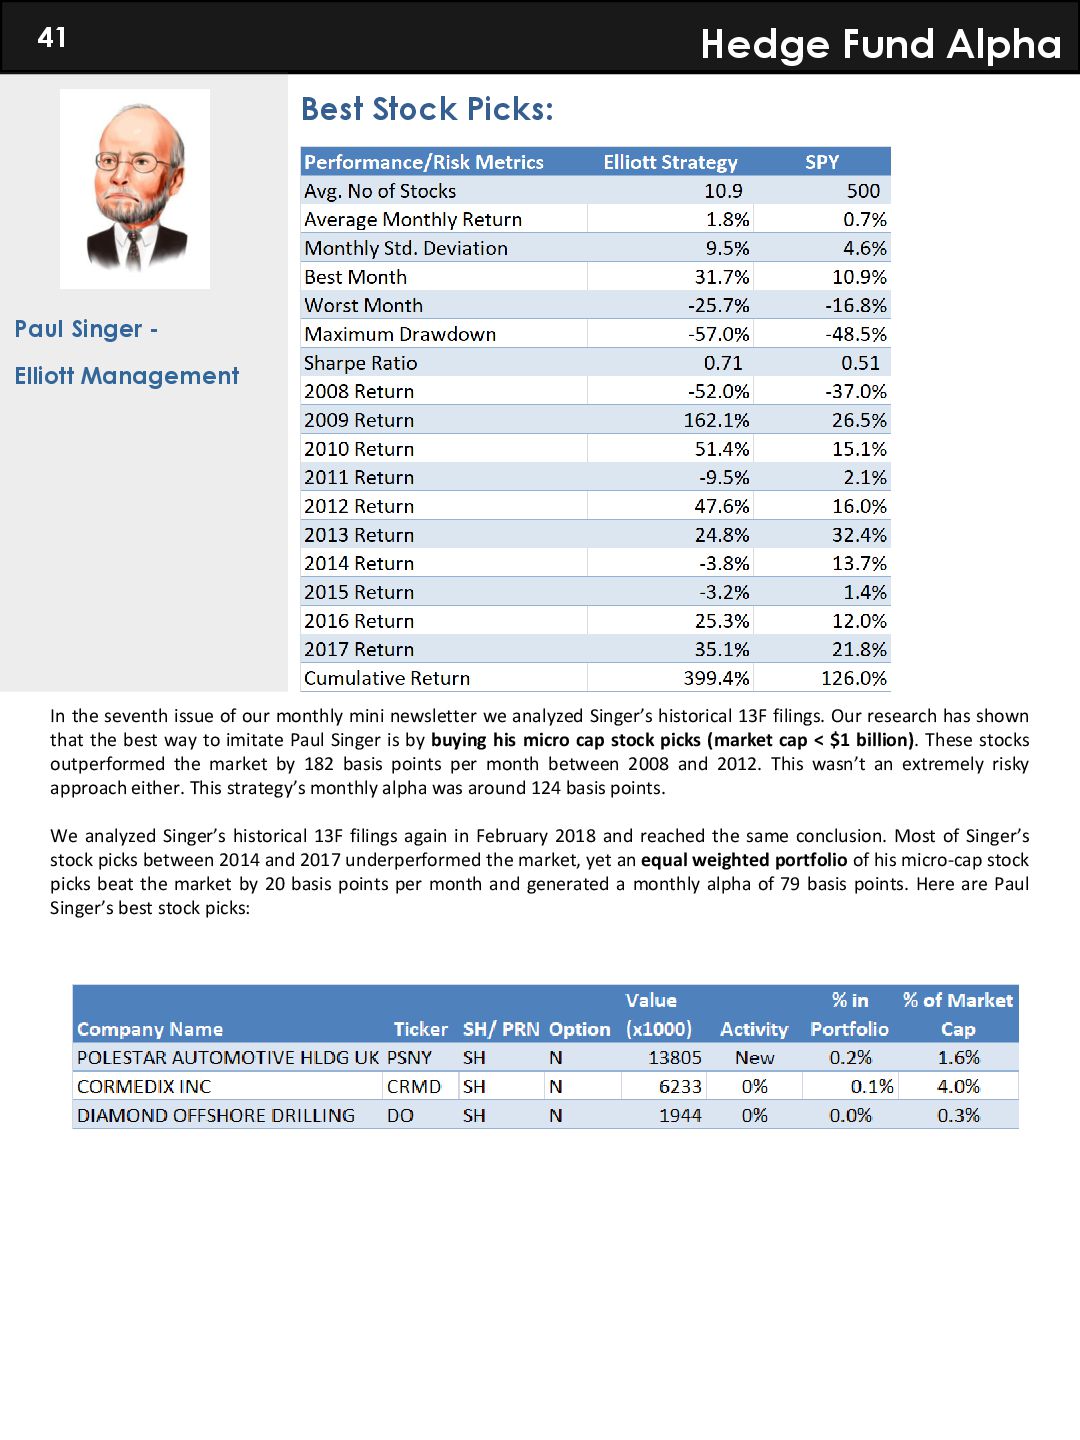
  41. Hedge Fund Alpha 41 Paul Singer - Elliott Management Best

    Stock Picks: In the seventh issue of our monthly mini newsletter we analyzed Singer’s historical 13F filings. Our research has shown that the best way to imitate Paul Singer is by buying his micro cap stock picks (market cap < $1 billion). These stocks outperformed the market by 182 basis points per month between 2008 and 2012. This wasn’t an extremely risky approach either. This strategy’s monthly alpha was around 124 basis points. We analyzed Singer’s historical 13F filings again in February 2018 and reached the same conclusion. Most of Singer’s stock picks between 2014 and 2017 underperformed the market, yet an equal weighted portfolio of his micro-cap stock picks beat the market by 20 basis points per month and generated a monthly alpha of 79 basis points. Here are Paul Singer’s best stock picks:
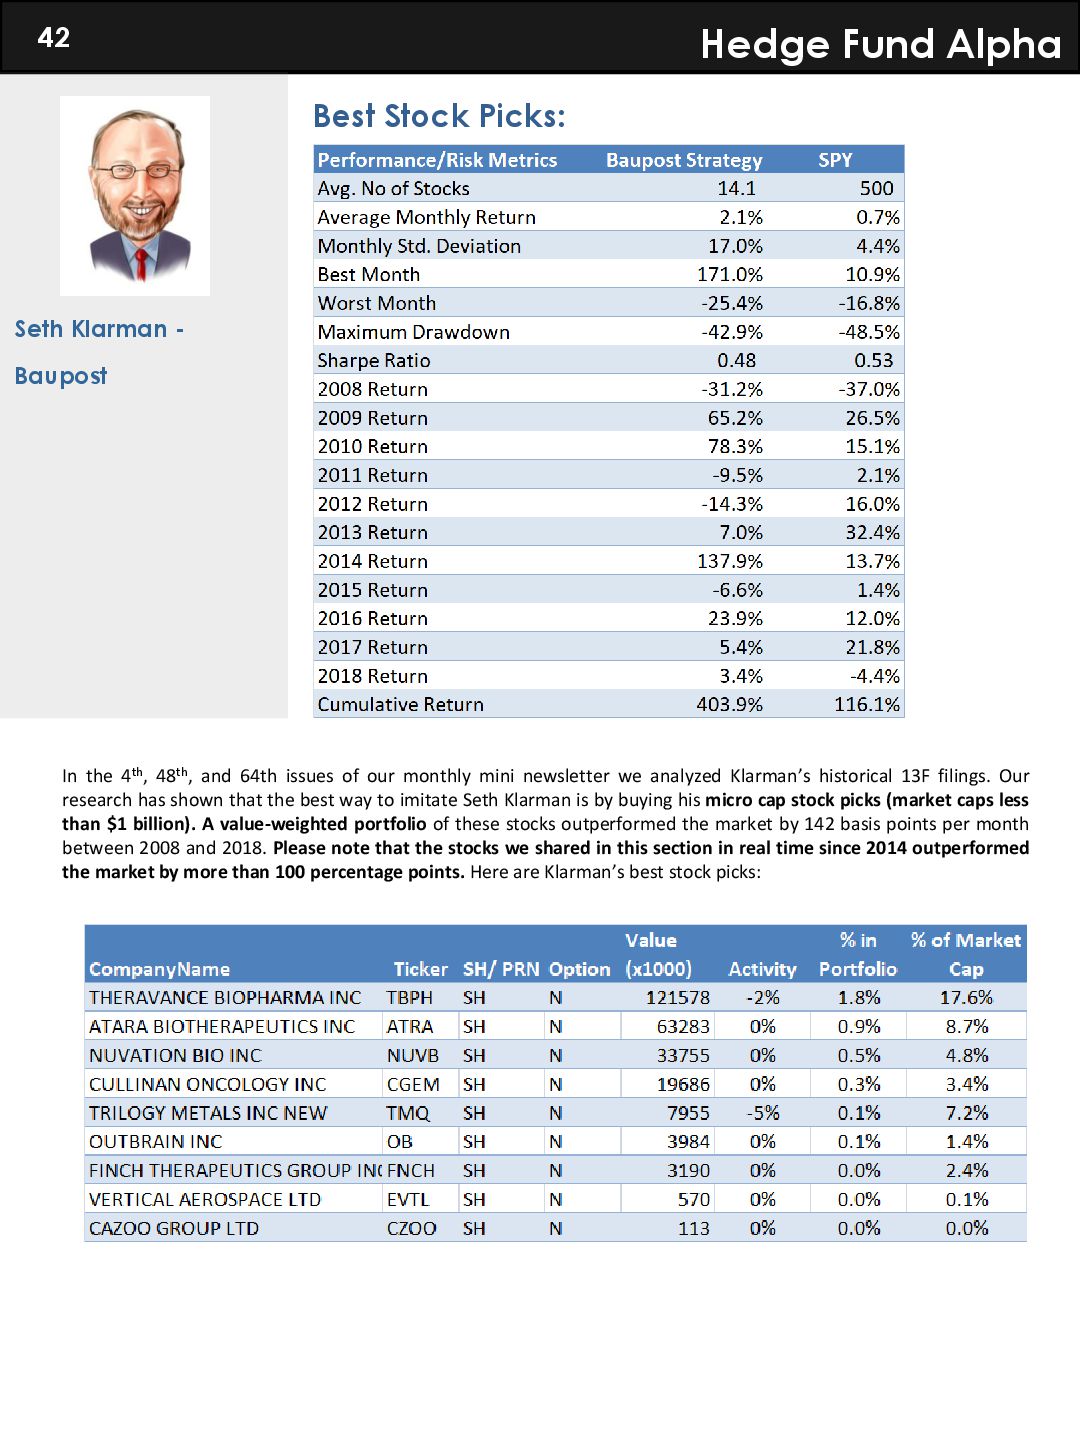
  42. Hedge Fund Alpha 42 Seth Klarman - Baupost Best Stock

    Picks: In the 4th, 48th, and 64th issues of our monthly mini newsletter we analyzed Klarman’s historical 13F filings. Our research has shown that the best way to imitate Seth Klarman is by buying his micro cap stock picks (market caps less than $1 billion). A value-weighted portfolio of these stocks outperformed the market by 142 basis points per month between 2008 and 2018. Please note that the stocks we shared in this section in real time since 2014 outperformed the market by more than 100 percentage points. Here are Klarman’s best stock picks:
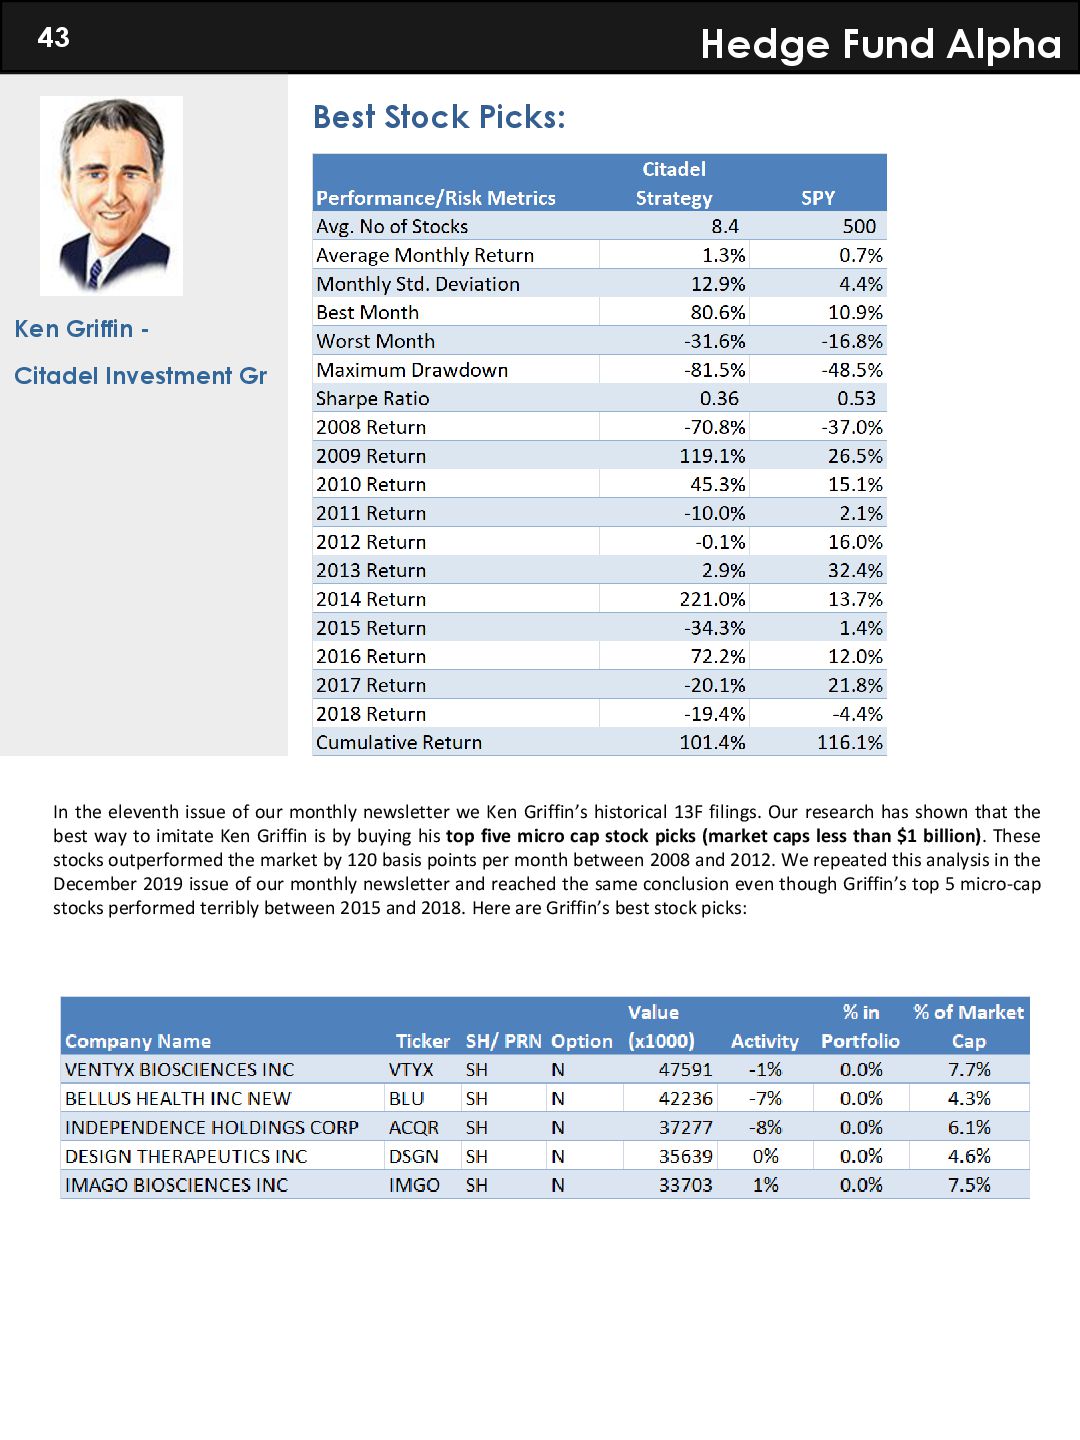
  43. Hedge Fund Alpha 43 Ken Griffin - Citadel Investment Gr

    Best Stock Picks: In the eleventh issue of our monthly newsletter we Ken Griffin’s historical 13F filings. Our research has shown that the best way to imitate Ken Griffin is by buying his top five micro cap stock picks (market caps less than $1 billion). These stocks outperformed the market by 120 basis points per month between 2008 and 2012. We repeated this analysis in the December 2019 issue of our monthly newsletter and reached the same conclusion even though Griffin’s top 5 micro-cap stocks performed terribly between 2015 and 2018. Here are Griffin’s best stock picks:
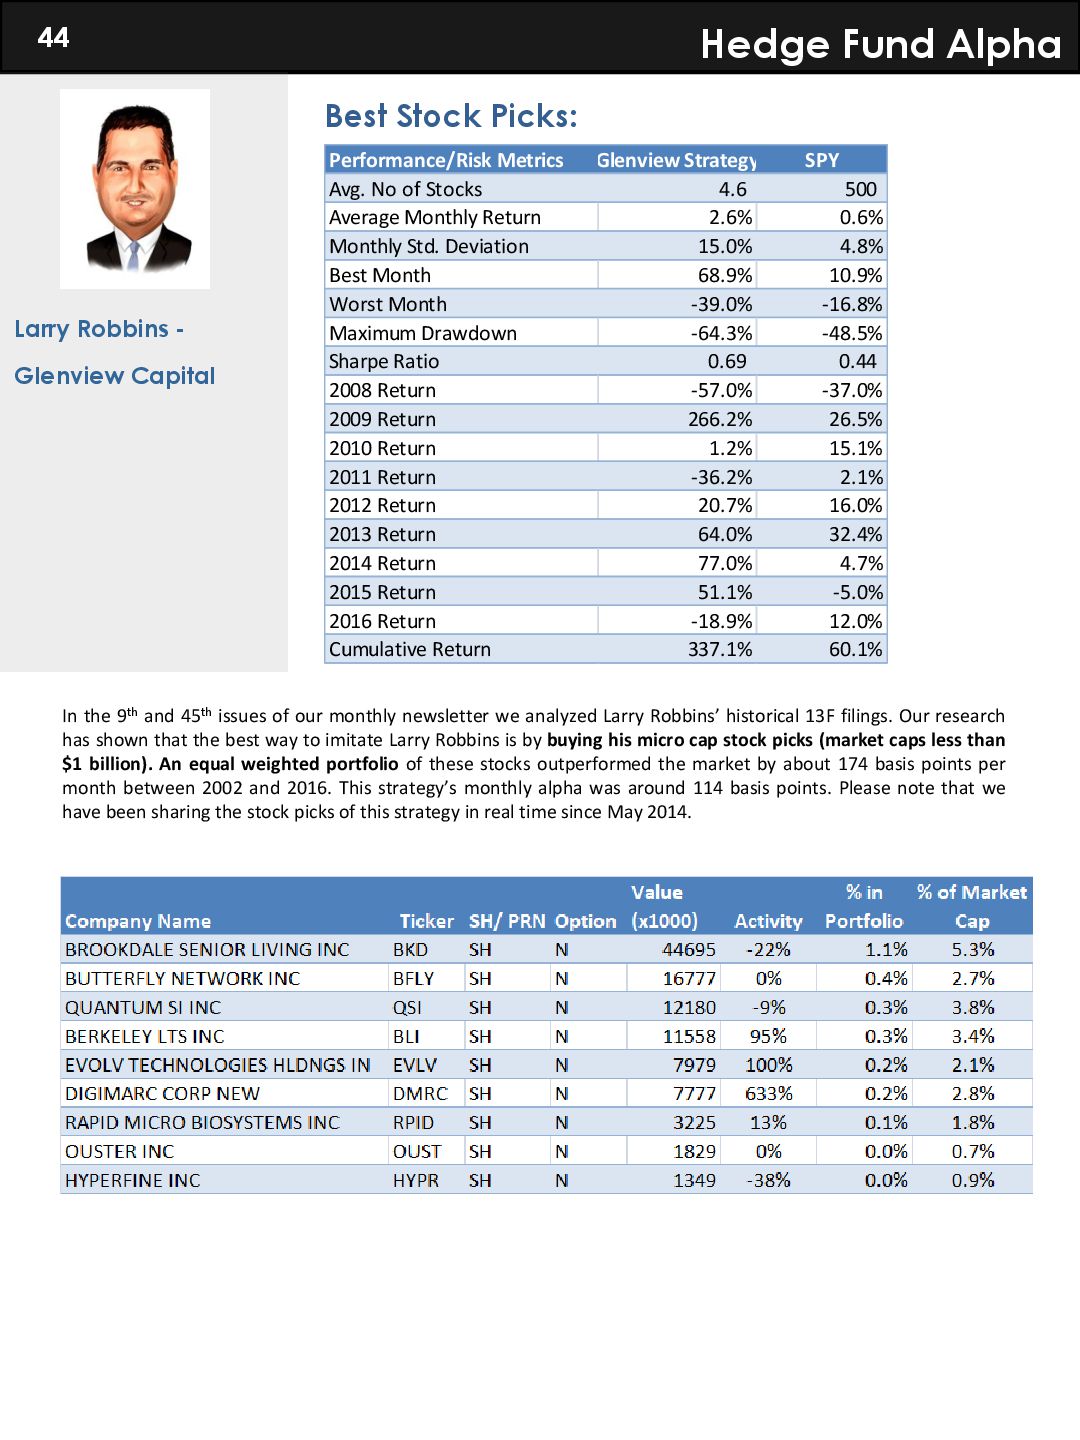
  44. Hedge Fund Alpha 44 Larry Robbins - Glenview Capital Best

    Stock Picks: In the 9th and 45th issues of our monthly newsletter we analyzed Larry Robbins’ historical 13F filings. Our research has shown that the best way to imitate Larry Robbins is by buying his micro cap stock picks (market caps less than $1 billion). An equal weighted portfolio of these stocks outperformed the market by about 174 basis points per month between 2002 and 2016. This strategy’s monthly alpha was around 114 basis points. Please note that we have been sharing the stock picks of this strategy in real time since May 2014. Performance/Risk Metrics Glenview Strategy SPY Avg. No of Stocks 4.6 500 Average Monthly Return 2.6% 0.6% Monthly Std. Deviation 15.0% 4.8% Best Month 68.9% 10.9% Worst Month -39.0% -16.8% Maximum Drawdown -64.3% -48.5% Sharpe Ratio 0.69 0.44 2008 Return -57.0% -37.0% 2009 Return 266.2% 26.5% 2010 Return 1.2% 15.1% 2011 Return -36.2% 2.1% 2012 Return 20.7% 16.0% 2013 Return 64.0% 32.4% 2014 Return 77.0% 4.7% 2015 Return 51.1% -5.0% 2016 Return -18.9% 12.0% Cumulative Return 337.1% 60.1%
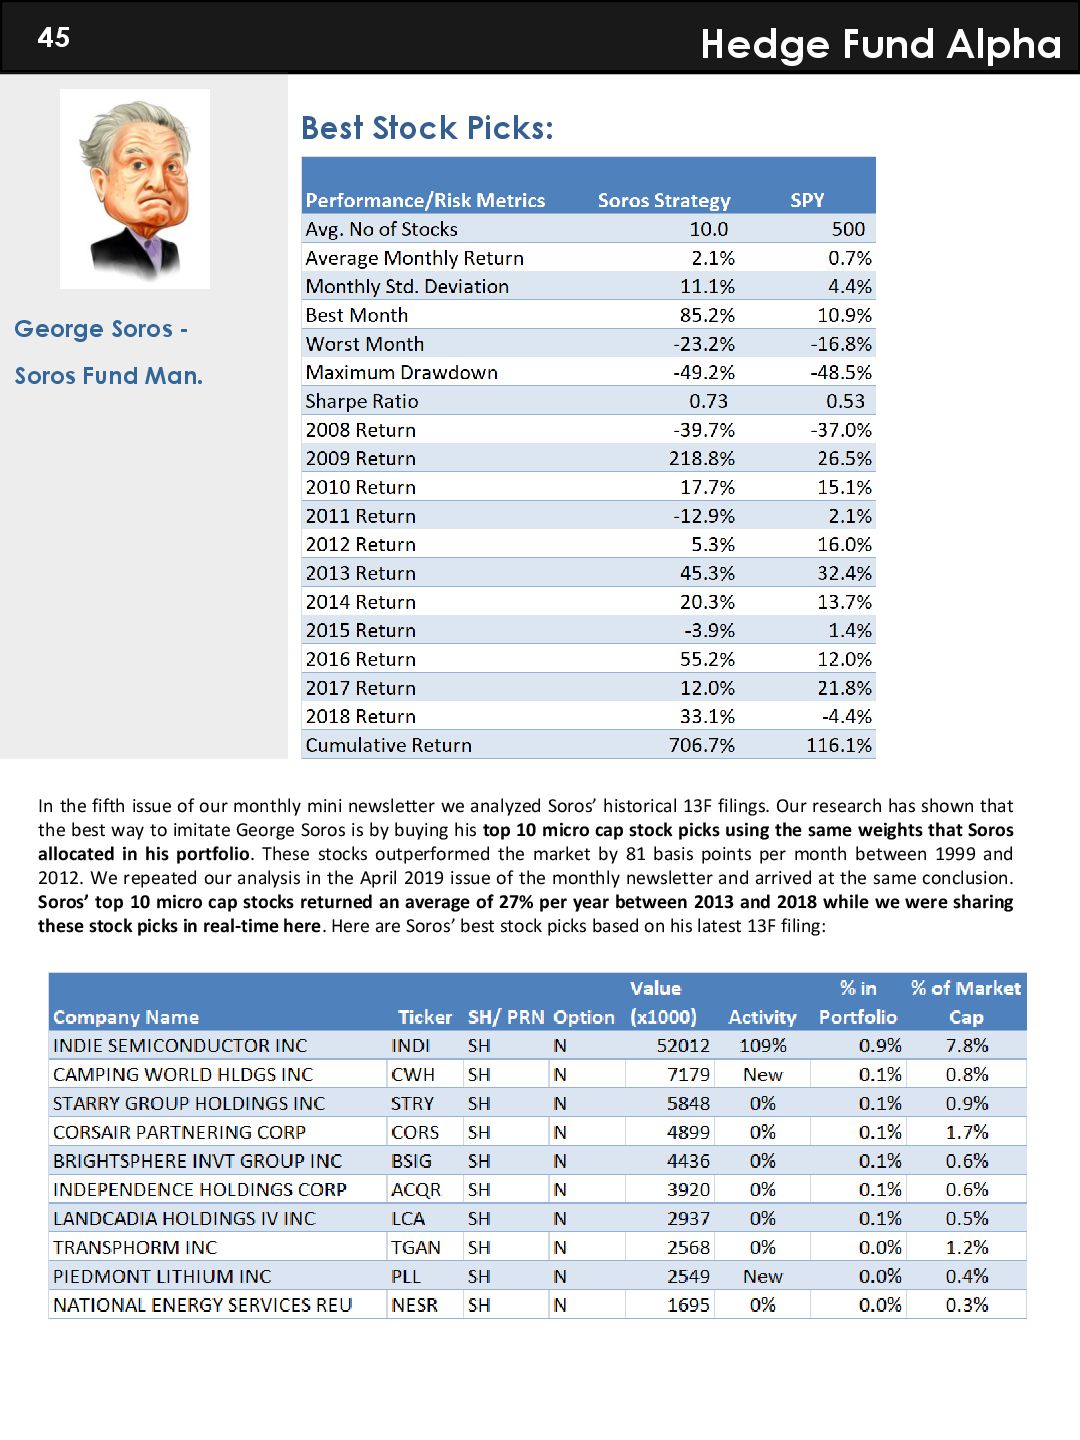
  45. Hedge Fund Alpha 45 George Soros - Soros Fund Man.

    Best Stock Picks: In the fifth issue of our monthly mini newsletter we analyzed Soros’ historical 13F filings. Our research has shown that the best way to imitate George Soros is by buying his top 10 micro cap stock picks using the same weights that Soros allocated in his portfolio. These stocks outperformed the market by 81 basis points per month between 1999 and 2012. We repeated our analysis in the April 2019 issue of the monthly newsletter and arrived at the same conclusion. Soros’ top 10 micro cap stocks returned an average of 27% per year between 2013 and 2018 while we were sharing these stock picks in real-time here. Here are Soros’ best stock picks based on his latest 13F filing:
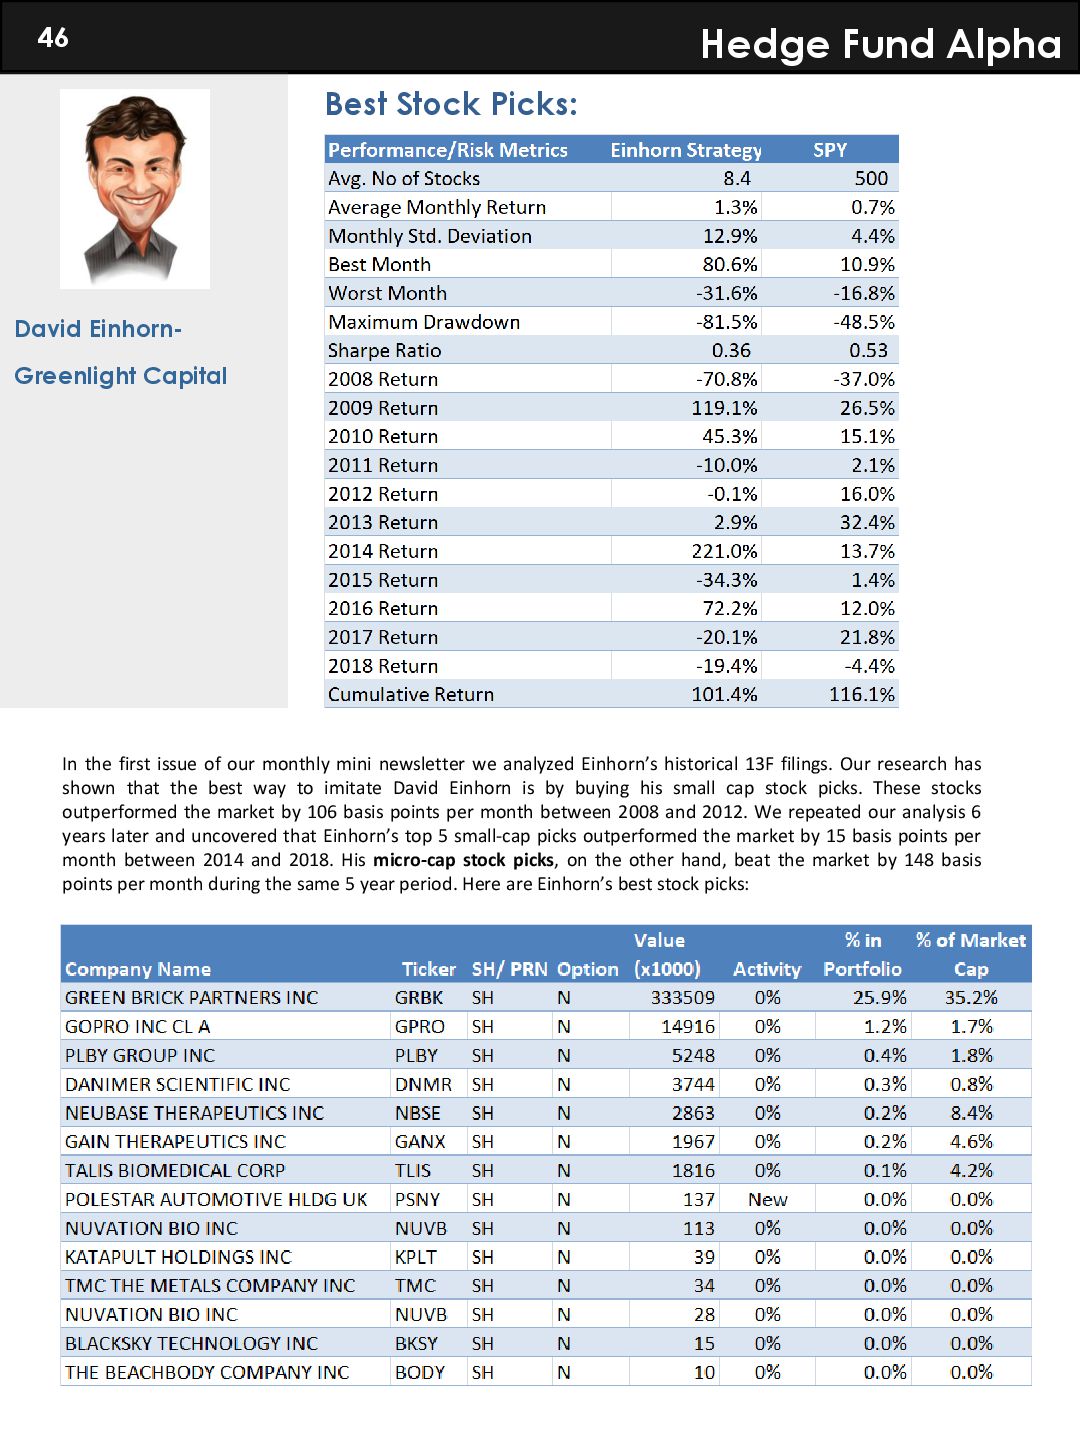
  46. Hedge Fund Alpha 46 David Einhorn- Greenlight Capital Best Stock

    Picks: In the first issue of our monthly mini newsletter we analyzed Einhorn’s historical 13F filings. Our research has shown that the best way to imitate David Einhorn is by buying his small cap stock picks. These stocks outperformed the market by 106 basis points per month between 2008 and 2012. We repeated our analysis 6 years later and uncovered that Einhorn’s top 5 small-cap picks outperformed the market by 15 basis points per month between 2014 and 2018. His micro-cap stock picks, on the other hand, beat the market by 148 basis points per month during the same 5 year period. Here are Einhorn’s best stock picks:
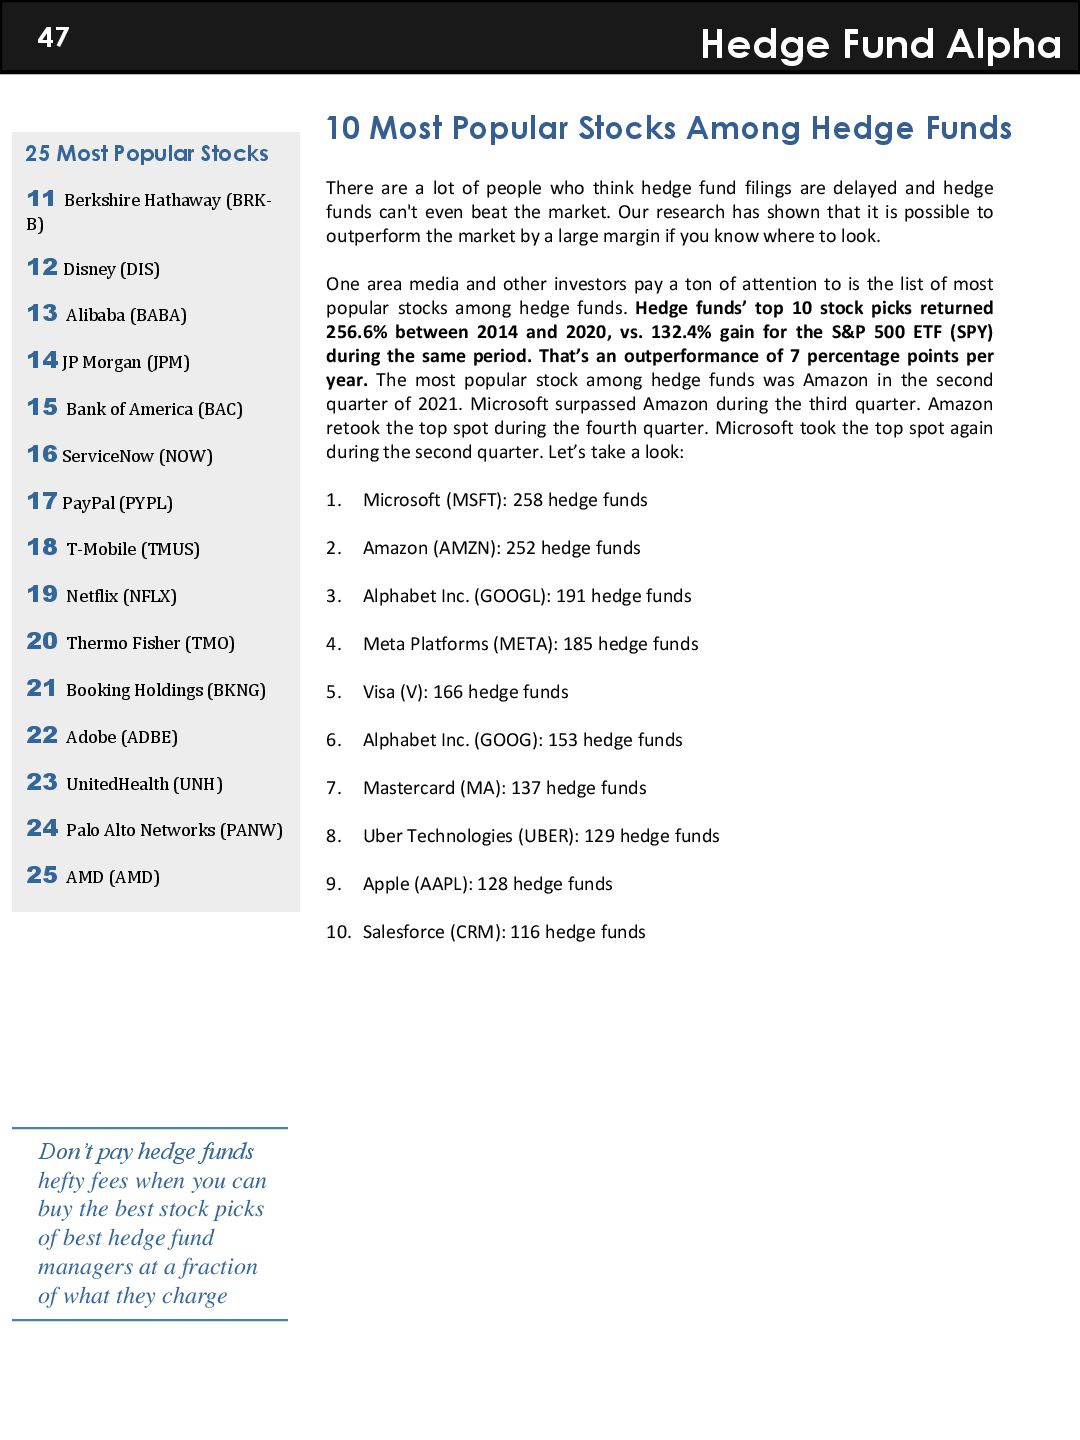
  47. Q1 2011 25 Most Popular Stocks 11 Berkshire Hathaway (BRK-

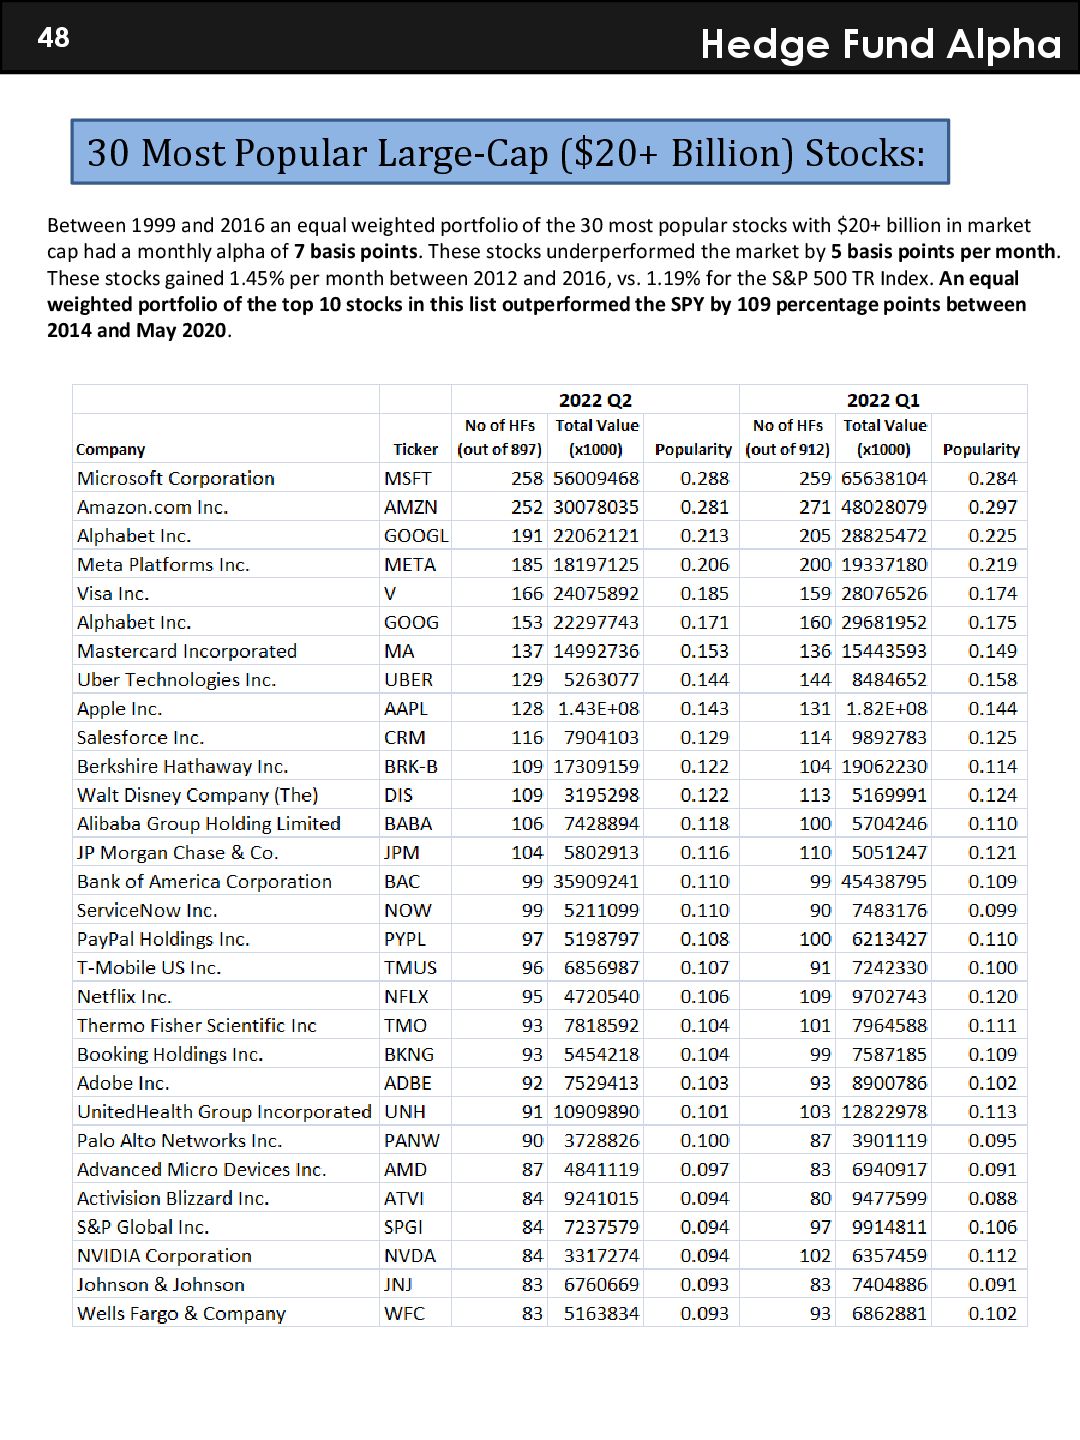
    B) 12 Disney (DIS) 13 Alibaba (BABA) 14 JP Morgan (JPM) 15 Bank of America (BAC) 16 ServiceNow (NOW) 17 PayPal (PYPL) 18 T-Mobile (TMUS) 19 Netflix (NFLX) 20 Thermo Fisher (TMO) 21 Booking Holdings (BKNG) 22 Adobe (ADBE) 23 UnitedHealth (UNH) 24 Palo Alto Networks (PANW) 25 AMD (AMD) Don’t pay hedge funds hefty fees when you can buy the best stock picks of best hedge fund managers at a fraction of what they charge 10 Most Popular Stocks Among Hedge Funds There are a lot of people who think hedge fund filings are delayed and hedge funds can't even beat the market. Our research has shown that it is possible to outperform the market by a large margin if you know where to look. One area media and other investors pay a ton of attention to is the list of most popular stocks among hedge funds. Hedge funds’ top 10 stock picks returned 256.6% between 2014 and 2020, vs. 132.4% gain for the S&P 500 ETF (SPY) during the same period. That’s an outperformance of 7 percentage points per year. The most popular stock among hedge funds was Amazon in the second quarter of 2021. Microsoft surpassed Amazon during the third quarter. Amazon retook the top spot during the fourth quarter. Microsoft took the top spot again during the second quarter. Let’s take a look: 1. Microsoft (MSFT): 258 hedge funds 2. Amazon (AMZN): 252 hedge funds 3. Alphabet Inc. (GOOGL): 191 hedge funds 4. Meta Platforms (META): 185 hedge funds 5. Visa (V): 166 hedge funds 6. Alphabet Inc. (GOOG): 153 hedge funds 7. Mastercard (MA): 137 hedge funds 8. Uber Technologies (UBER): 129 hedge funds 9. Apple (AAPL): 128 hedge funds 10. Salesforce (CRM): 116 hedge funds Hedge Fund Alpha 47
  48. Hedge Fund Alpha 48 30 Most Popular Large-Cap ($20+ Billion)

    Stocks: Between 1999 and 2016 an equal weighted portfolio of the 30 most popular stocks with $20+ billion in market cap had a monthly alpha of 7 basis points. These stocks underperformed the market by 5 basis points per month. These stocks gained 1.45% per month between 2012 and 2016, vs. 1.19% for the S&P 500 TR Index. An equal weighted portfolio of the top 10 stocks in this list outperformed the SPY by 109 percentage points between 2014 and May 2020.
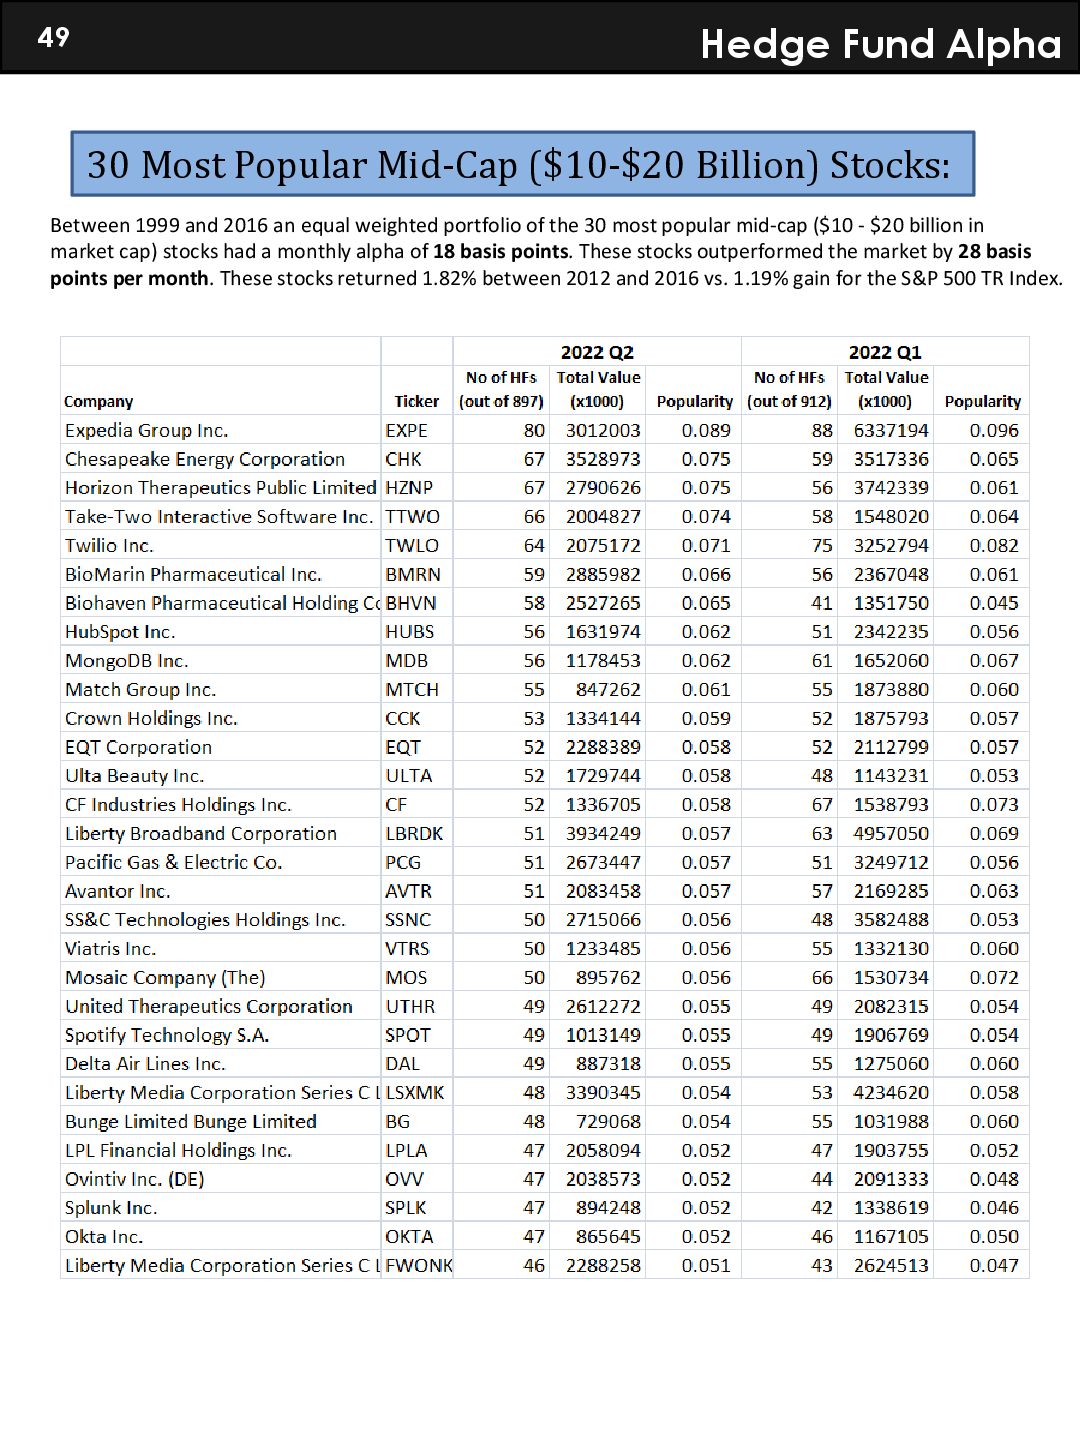
  49. Hedge Fund Alpha 49 30 Most Popular Mid-Cap ($10-$20 Billion)

    Stocks: Between 1999 and 2016 an equal weighted portfolio of the 30 most popular mid-cap ($10 - $20 billion in market cap) stocks had a monthly alpha of 18 basis points. These stocks outperformed the market by 28 basis points per month. These stocks returned 1.82% between 2012 and 2016 vs. 1.19% gain for the S&P 500 TR Index.
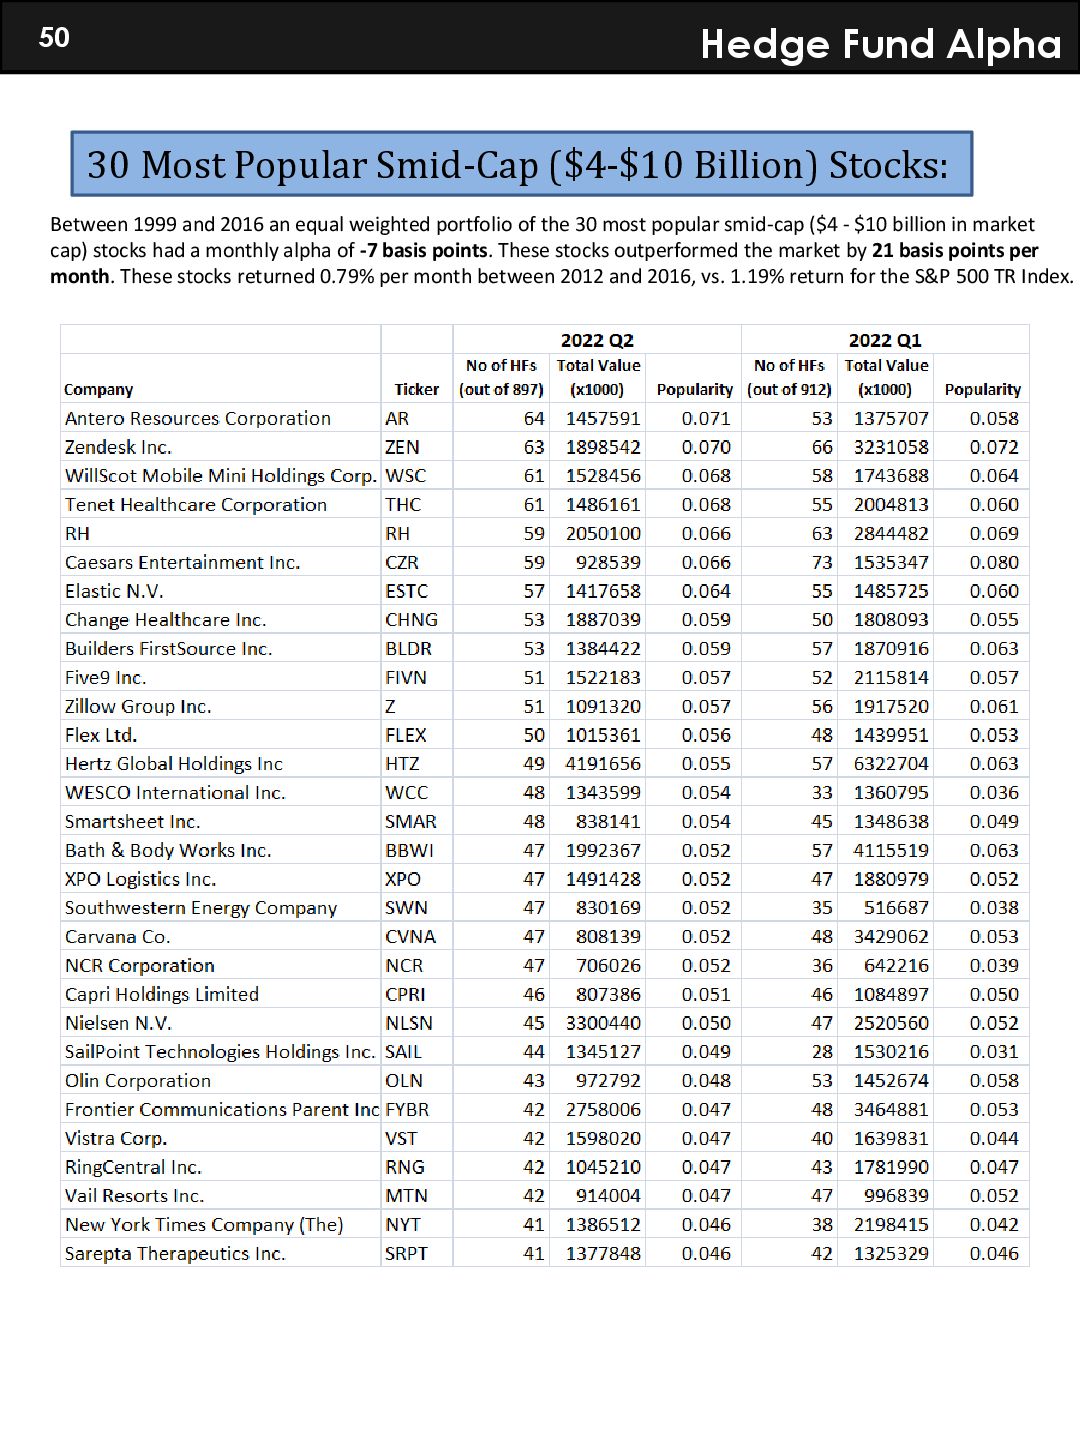
  50. Hedge Fund Alpha 50 30 Most Popular Smid-Cap ($4-$10 Billion)

    Stocks: Between 1999 and 2016 an equal weighted portfolio of the 30 most popular smid-cap ($4 - $10 billion in market cap) stocks had a monthly alpha of -7 basis points. These stocks outperformed the market by 21 basis points per month. These stocks returned 0.79% per month between 2012 and 2016, vs. 1.19% return for the S&P 500 TR Index.
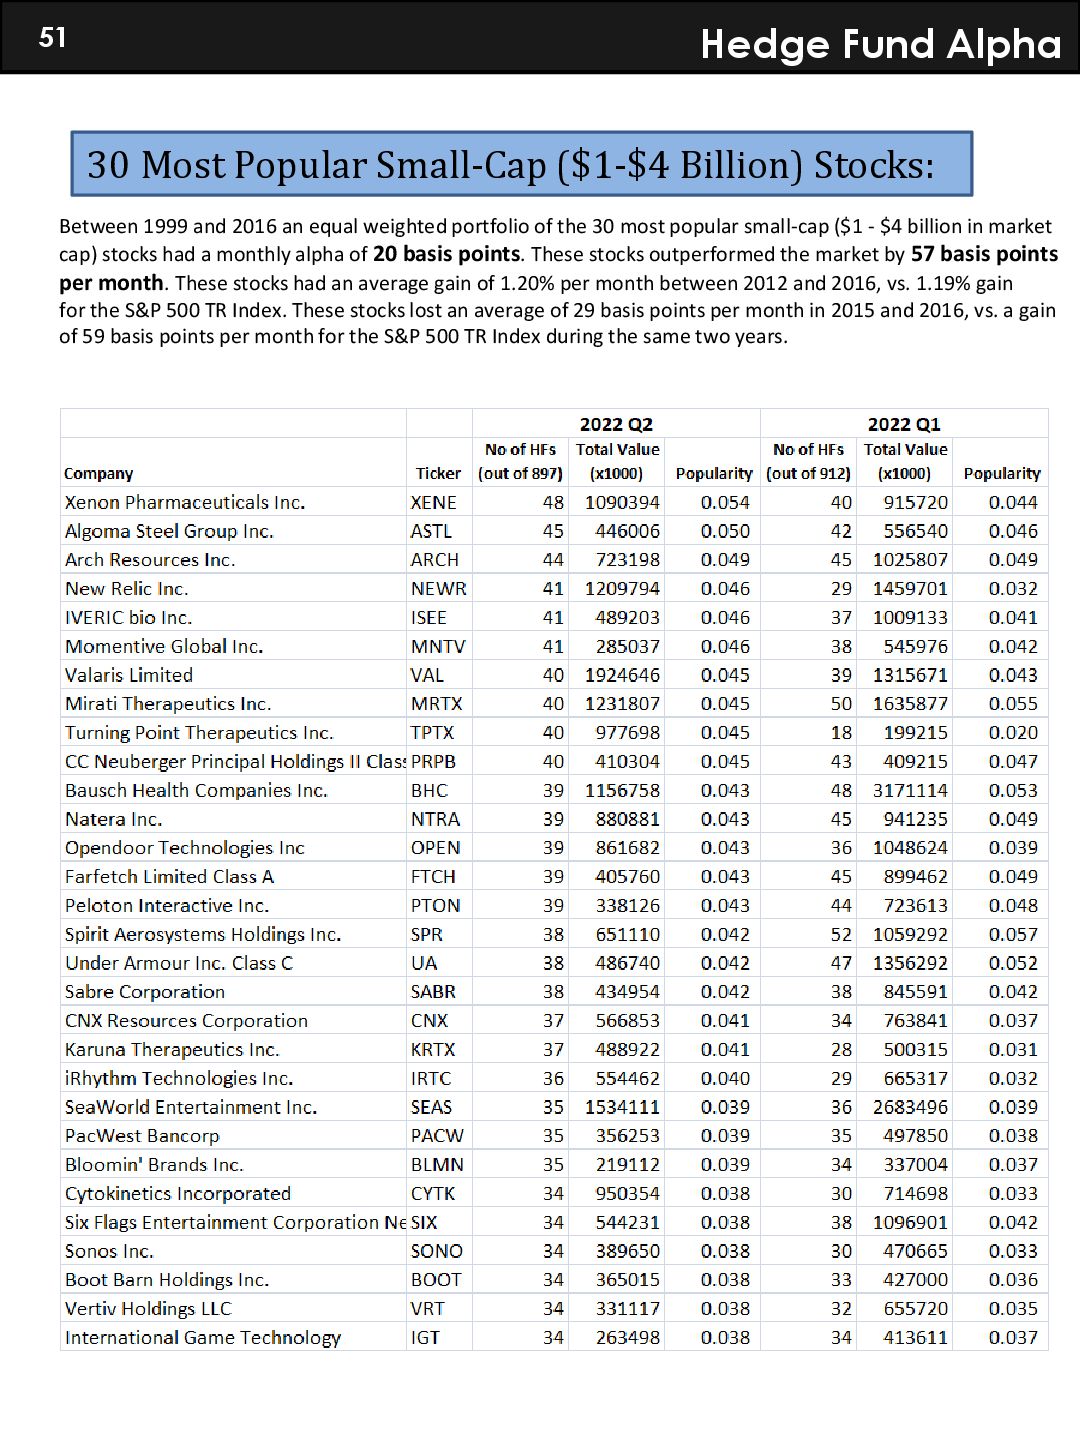
  51. Hedge Fund Alpha 51 30 Most Popular Small-Cap ($1-$4 Billion)

    Stocks: Between 1999 and 2016 an equal weighted portfolio of the 30 most popular small-cap ($1 - $4 billion in market cap) stocks had a monthly alpha of 20 basis points. These stocks outperformed the market by 57 basis points per month. These stocks had an average gain of 1.20% per month between 2012 and 2016, vs. 1.19% gain for the S&P 500 TR Index. These stocks lost an average of 29 basis points per month in 2015 and 2016, vs. a gain of 59 basis points per month for the S&P 500 TR Index during the same two years.
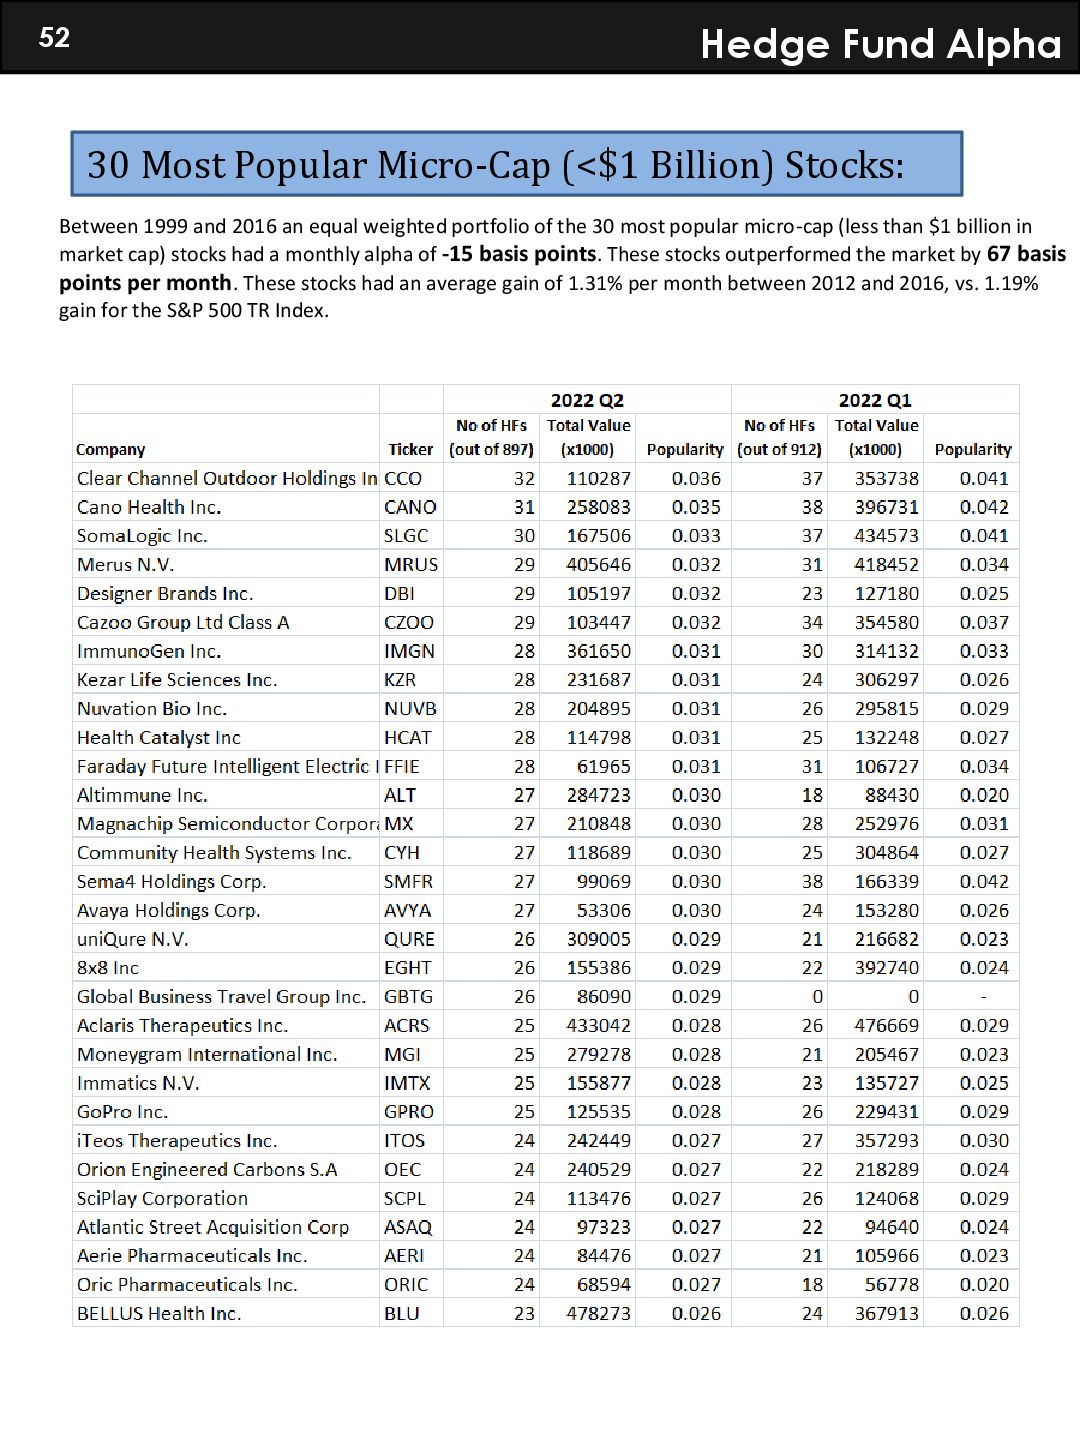
  52. Hedge Fund Alpha 52 30 Most Popular Micro-Cap (<$1 Billion)

    Stocks: Between 1999 and 2016 an equal weighted portfolio of the 30 most popular micro-cap (less than $1 billion in market cap) stocks had a monthly alpha of -15 basis points. These stocks outperformed the market by 67 basis points per month. These stocks had an average gain of 1.31% per month between 2012 and 2016, vs. 1.19% gain for the S&P 500 TR Index.
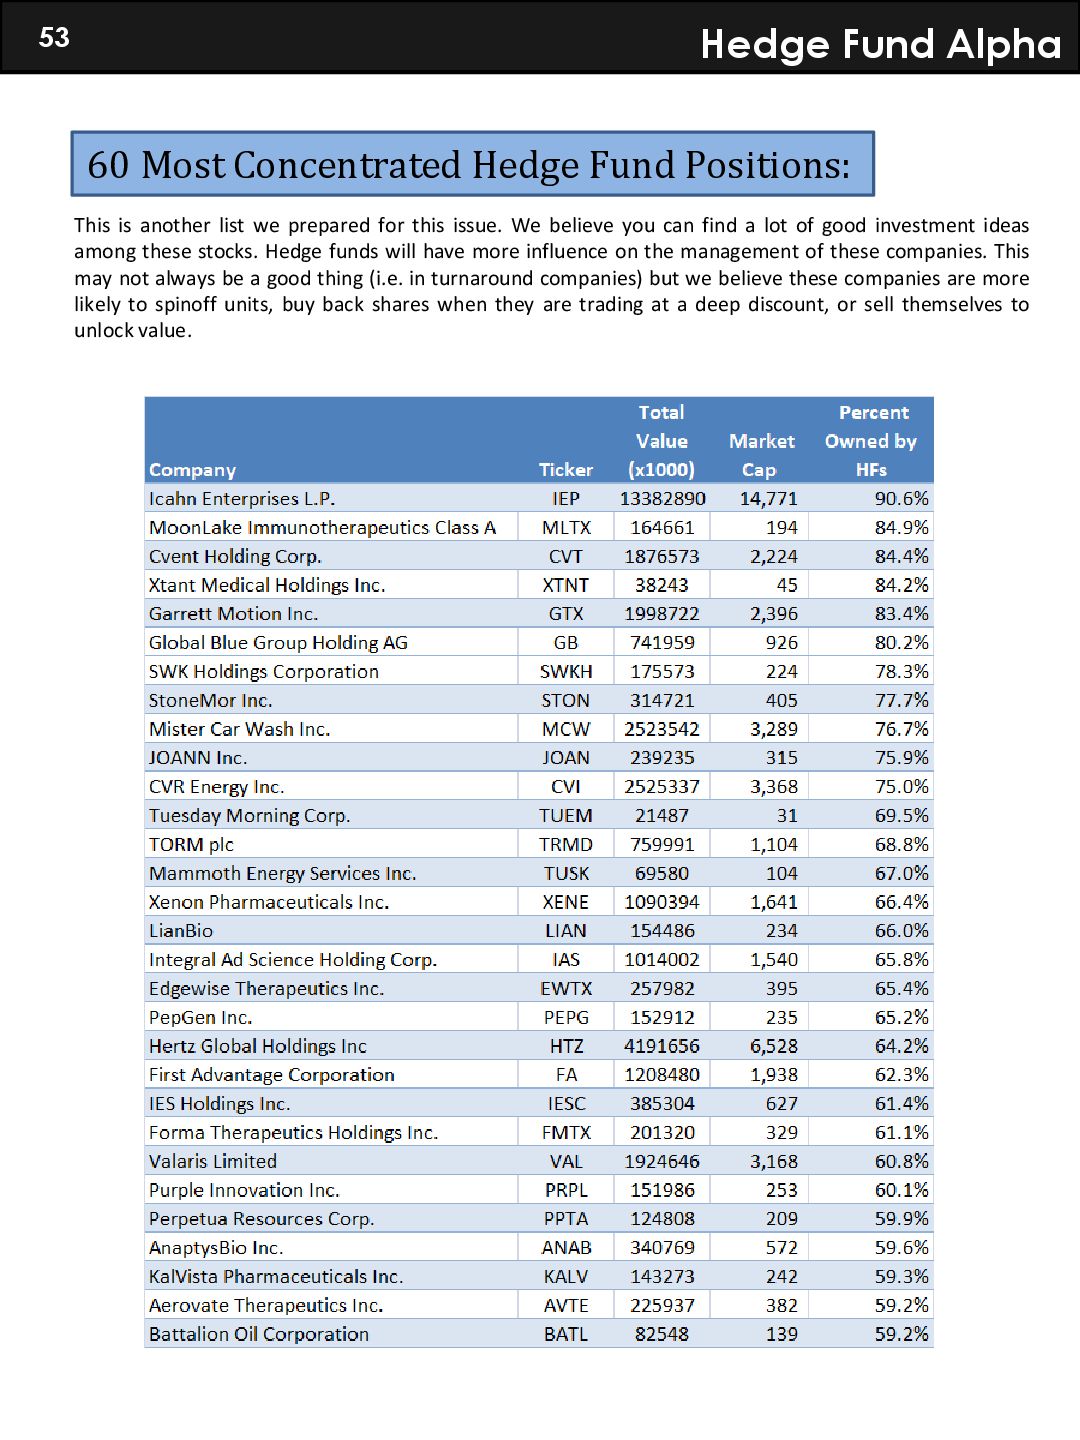
  53. Hedge Fund Alpha 53 60 Most Concentrated Hedge Fund Positions:

    This is another list we prepared for this issue. We believe you can find a lot of good investment ideas among these stocks. Hedge funds will have more influence on the management of these companies. This may not always be a good thing (i.e. in turnaround companies) but we believe these companies are more likely to spinoff units, buy back shares when they are trading at a deep discount, or sell themselves to unlock value.
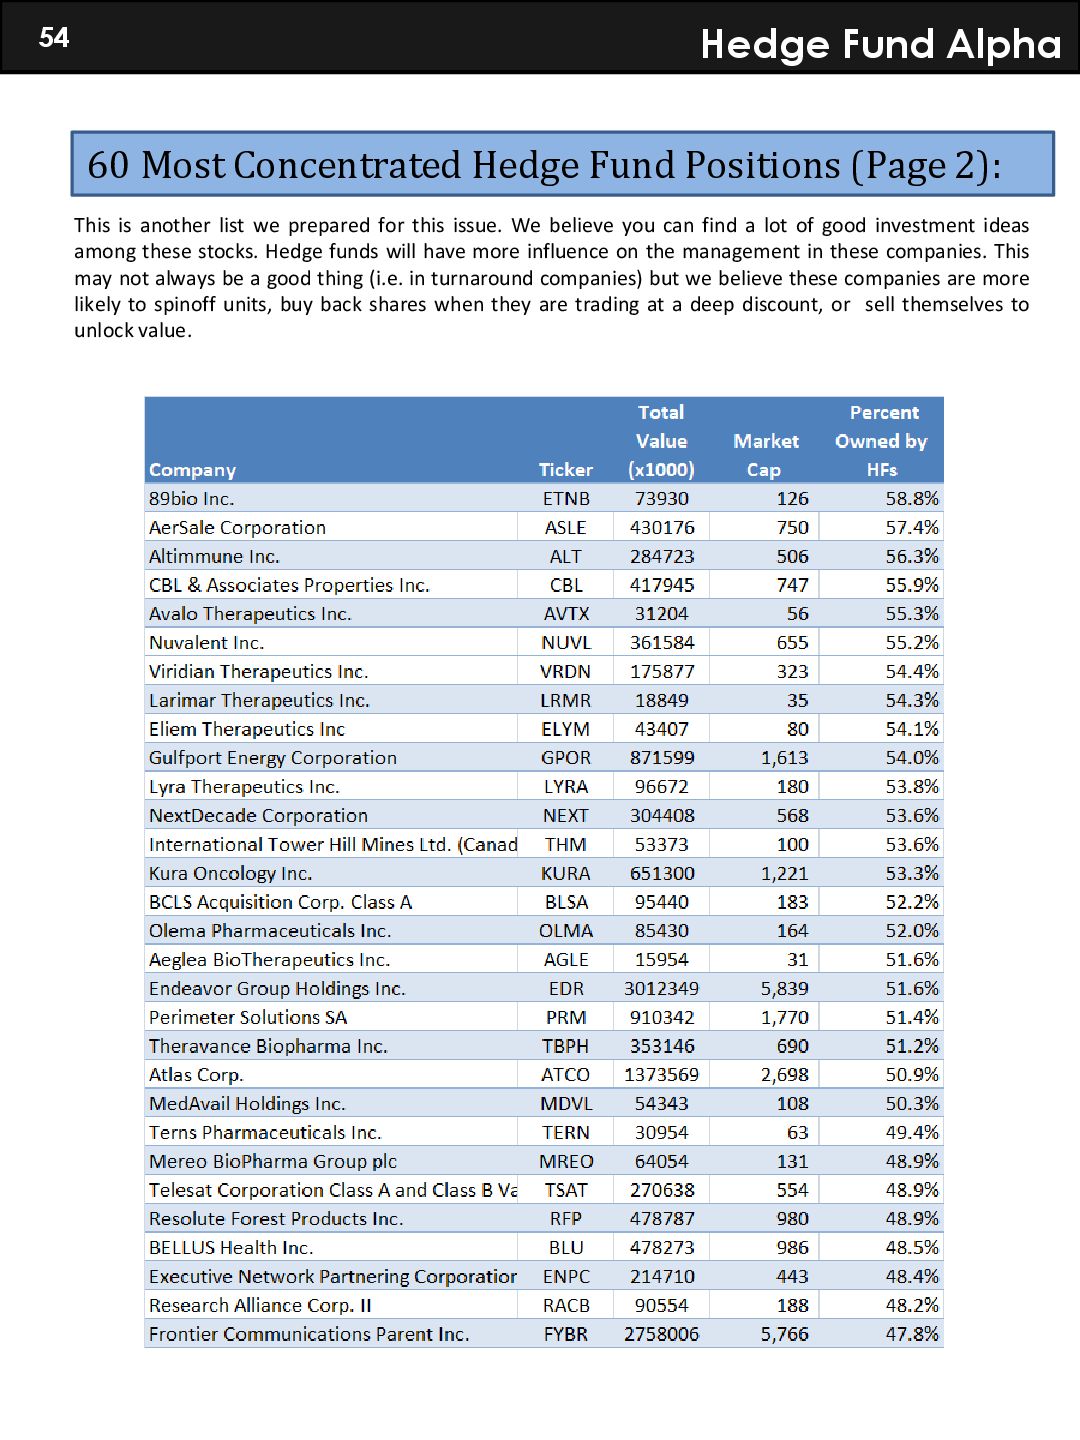
  54. Hedge Fund Alpha 54 60 Most Concentrated Hedge Fund Positions

    (Page 2): This is another list we prepared for this issue. We believe you can find a lot of good investment ideas among these stocks. Hedge funds will have more influence on the management in these companies. This may not always be a good thing (i.e. in turnaround companies) but we believe these companies are more likely to spinoff units, buy back shares when they are trading at a deep discount, or sell themselves to unlock value.
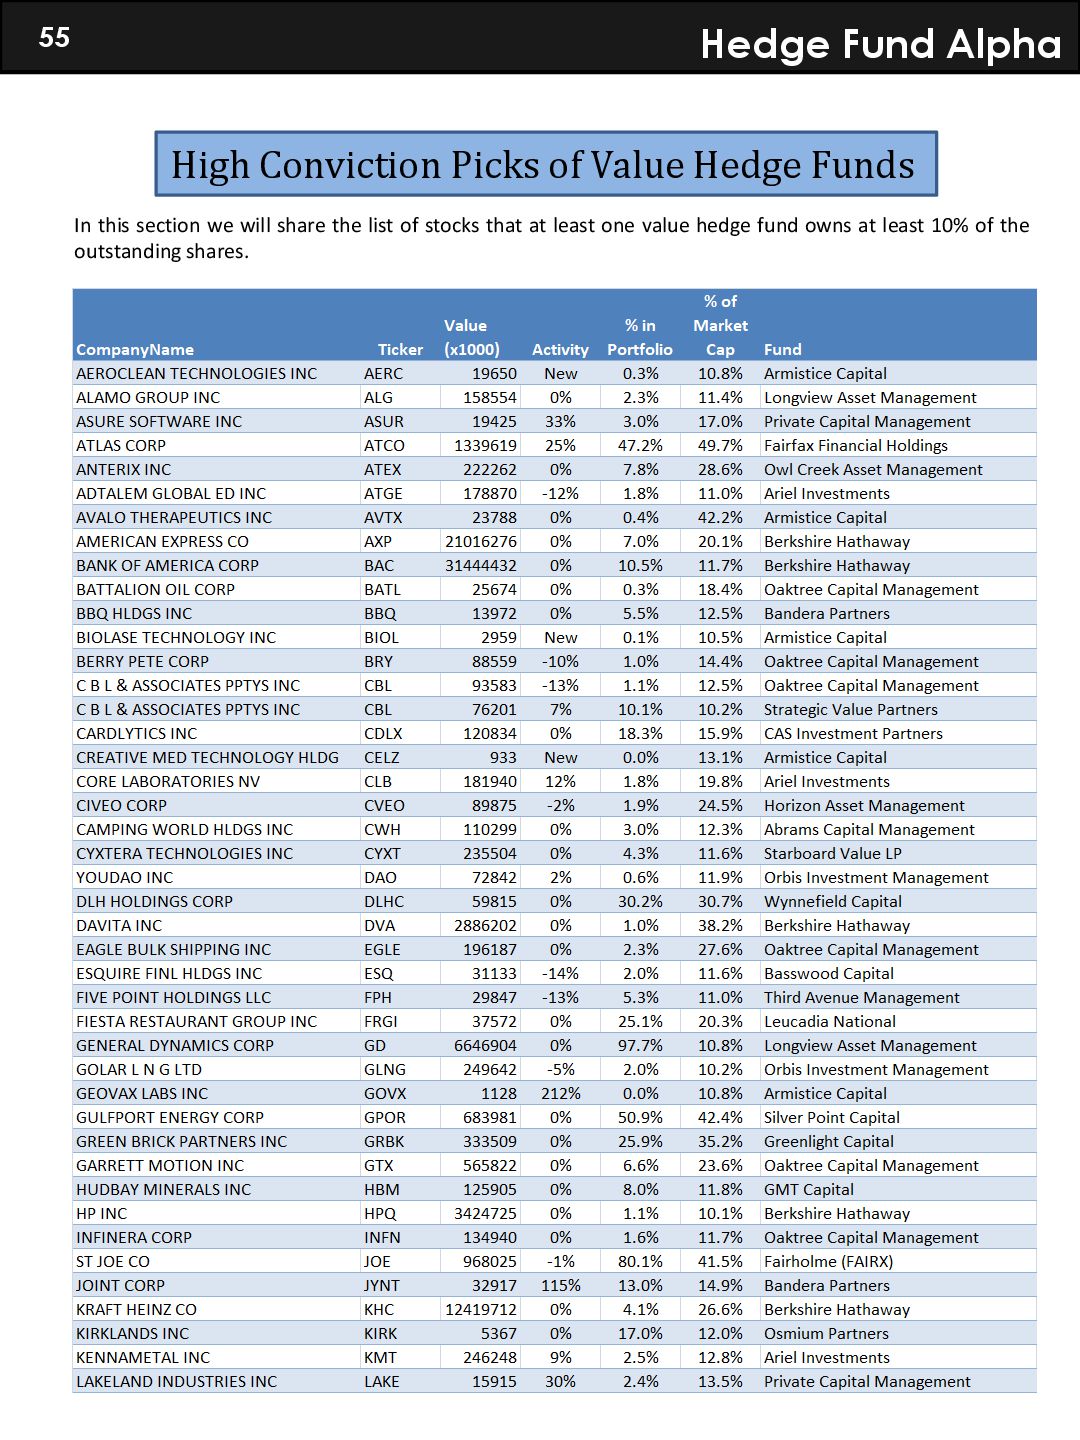
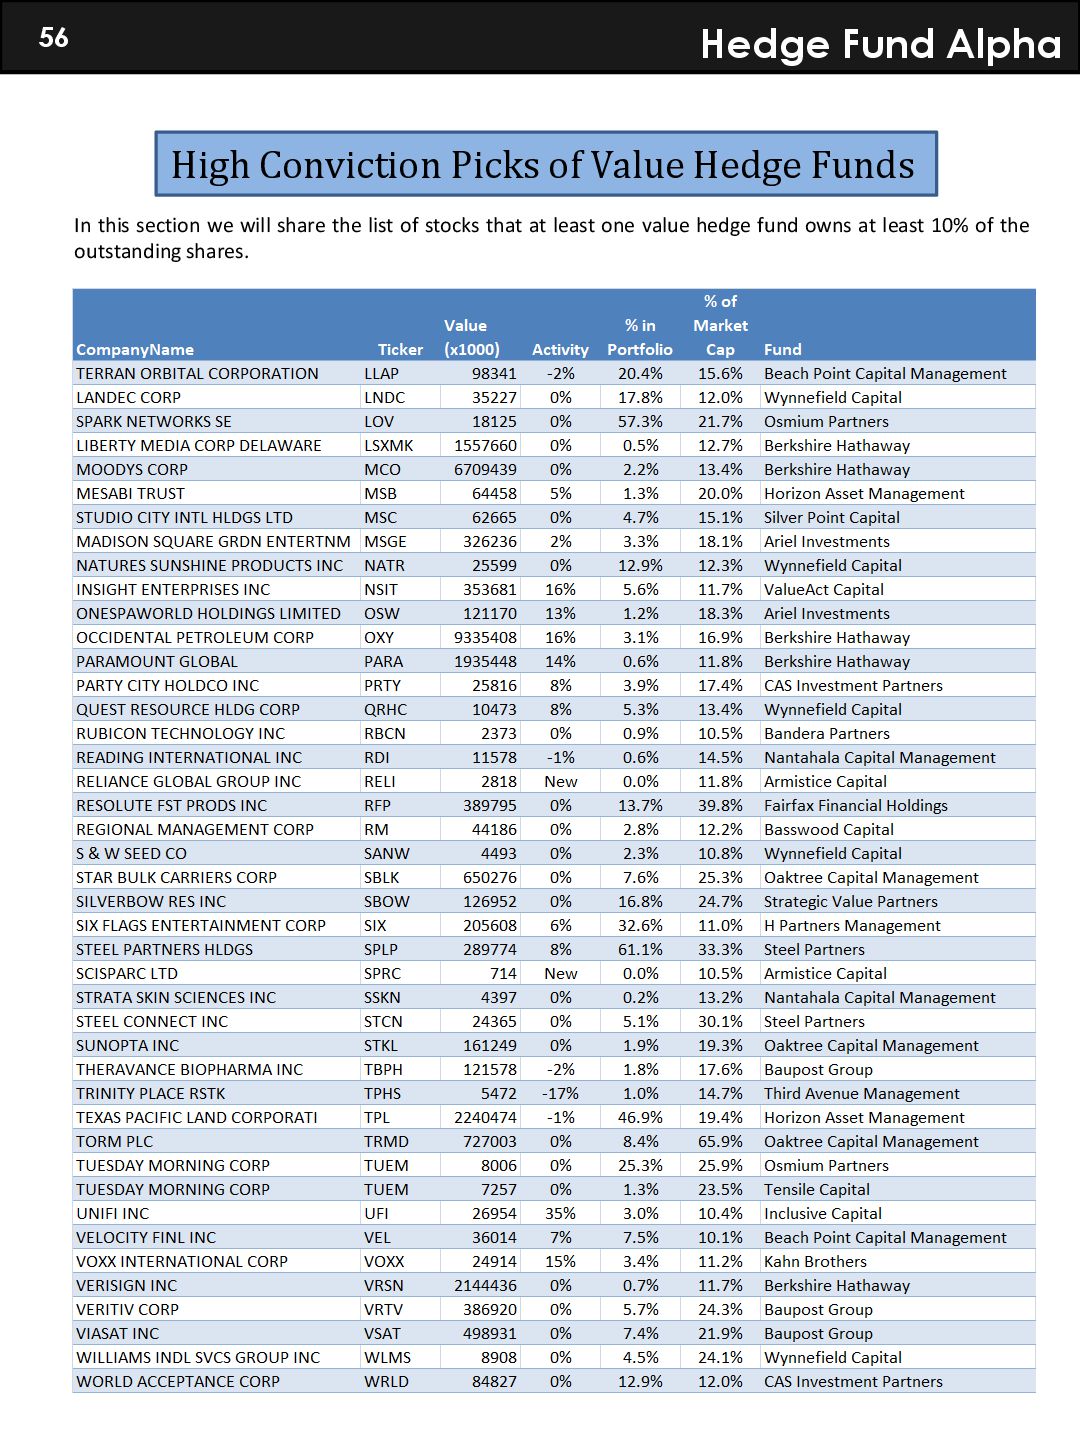
  55. Hedge Fund Alpha 55 High Conviction Picks of Value Hedge

    Funds In this section we will share the list of stocks that at least one value hedge fund owns at least 10% of the outstanding shares.
  56. Hedge Fund Alpha 56 High Conviction Picks of Value Hedge

    Funds In this section we will share the list of stocks that at least one value hedge fund owns at least 10% of the outstanding shares.
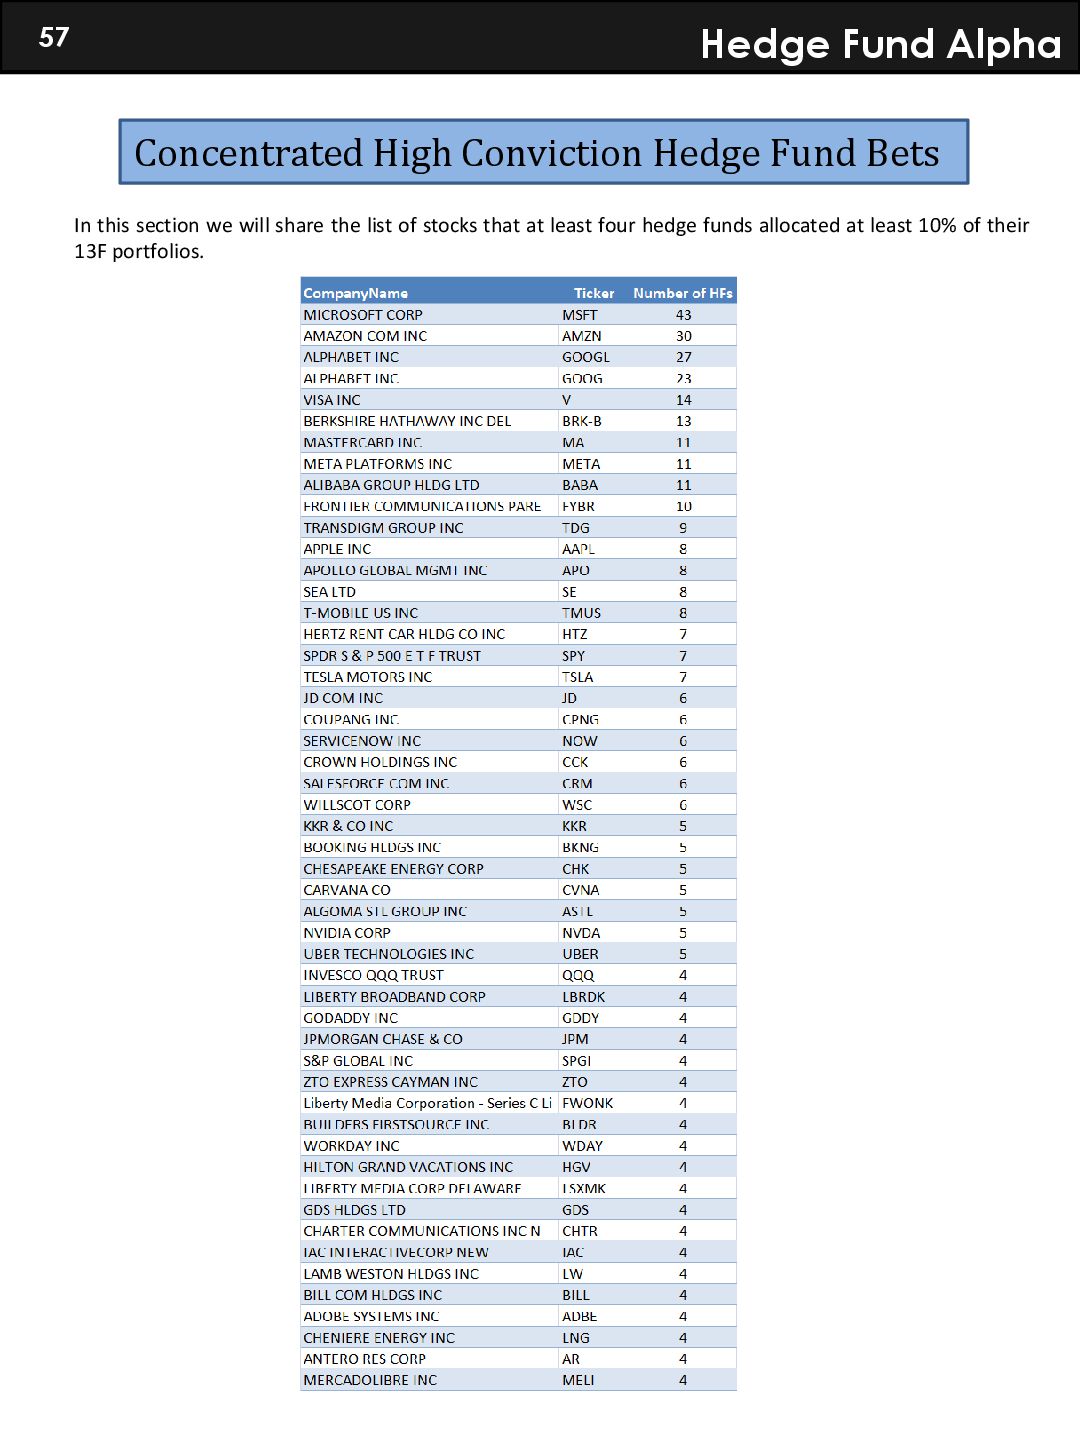
  57. Hedge Fund Alpha 57 Concentrated High Conviction Hedge Fund Bets

    In this section we will share the list of stocks that at least four hedge funds allocated at least 10% of their 13F portfolios.
  58. Hedge Fund Alpha 58 Highlights From Hedge Fund Investor Letters

    We are going to share excerpts from the following hedge funds’ investor letters: Oakmark Capital, Rondure Global, Horizon Kinetics, Bronte Capital, Voss Capital, Greenlight Capital, Third Point, Alta Fox, and RV Capital. We will start off with Bill Nygren’s markets recap and outlook: On Monday, June 13, the S&P 500 Index fell 3.9% to 3750, bringing the decline from its January 3 record high to 21.8%. The media focused on the market being down more than 20%, meaning this decline was now a “bear market.” Financial professionals in the media advised investors to act “appropriately.” What that meant went unexplained, but the implication was that, with the market down so much, you need to be more careful. Can history help us decide how we should invest in a bear market? Over the 77 years for which we have daily price data for the S&P 500, there have been 12 bear markets. Let’s look at the previous 11. The median bear market low occurred 117 days following the day the market was down 20%. The shortest time to the ultimate bottom was one day after falling 20%, which occurred in October 1957. The longest was more than two years, September 1946 to June 1949. If this bear market behaves like its predecessors, it is a coin-flip whether it bottoms by October. What were equity returns immediately following bear markets? For the 11 previous bear markets, the median additional decline after the market was down 20% was another 10% loss. Despite those declines, two years from the time the market first hit down 20%, the median gain was 33%. That statistic is especially interesting because the two-year price increase from a random purchase date has been just over half as much, 17%. Perhaps the advisors who are now urging extra caution are being driven by their emotions rather than data. Recession On April 28, the U.S. Commerce Department’s Bureau of Economic Analysis reported that first-quarter GDP grew at 6.5%. On the surface, that looks like a nice increase from the sub-5% growth over both the past 5 and 10 years. But the GDP number that merits the most attention is real GDP, where the growth is adjusted for inflation. With first-quarter inflation running at 8.1%, the highest in more than 30 years, real GDP declined 1.4%. Economists attributed the first-quarter decline to high inflation, a high trade deficit and a decrease in inventory investment, saying that all three should improve throughout the year. But with the second quarter now in the rear-view mirror, it doesn’t look like the headwind has lessened. A recession is typically defined as two consecutive quarters of declining real GDP, so if the June quarter also declined, we are already in a recession. It’s probably 50/50. So, what should that mean for your investment strategy?
  59. Hedge Fund Alpha 59 Highlights From Hedge Fund Investor Letters

    We looked at the 12 recessions that have occurred since 1945 (the period we have access to daily S&P 500 prices) to see the price change in the S&P 500 during the two years after it was known that a recession had begun. The median two-year price increase in the S&P 500 was 25%, and only one of the 12 periods showed a negative return. Remember that the median two-year price increase from random purchase dates during those 77 years was only 17%, so the recession returns were actually higher. If the late July announcement of the second-quarter real GDP turns out to be negative, don’t be bothered: There is no evidence that below-average investment returns are likely to follow. Inflation Inflation, as measured by the annual CPI, spiked above 8% in October 1973 and remained elevated until its peak of 14.6% in March 1980. It fell back below 8% in February 1982 and remained mostly under control until this past year. After troughing below zero in 2009, inflation increased to 5.4% in July 2021, and we were asked to believe that it was caused by the Covid-19 pandemic and would prove to be transitory. The steady climb of inflation to 8.6% in May of 2022 is stretching the meaning of the term “transitory.” High inflation almost always leads to higher interest rates, which erode the value of long-duration assets because they make future cash flows less valuable. Bonds, with their fixed interest payments and maturity values, are the hardest hit. Businesses can offset inflation by raising prices, but historically that has only been a partial offset. We expect our portfolios to perform better than average during higher inflation because we own energy companies that benefit from higher oil prices and banks that profit from a larger spread between their lending and deposit rates. Further, our portfolios have P/E ratios significantly lower than the S&P 500, meaning our “duration” is less than the market’s, diminishing the value reduction caused by higher rates. If inflation is a negative for equities, does that mean we should sell stocks when inflation is high? We went back to our 77-year data on S&P 500 prices and examined what the two-year returns were following inflation rising above 8%. Before this quarter, there were only five periods since 1945 when inflation exceeded 8%. An investor purchasing the S&P 500 following the announcement that the trailing annual CPI increase was above 8% and holding for two years showed a median price increase of 17%, the same as for a random two-year period over the past 77 years. Though it is tempting to believe that one should sell stocks following the onset of a bear market, a recession or a period of high inflation, the data suggest otherwise. Stock prices anticipate future events before they occur. After the news is out, it is typically too late to profit. That’s what makes timing the stock market so hard, and that is why we suggest not trying. Instead, we encourage dollar-cost averaging for investing new capital and rebalancing the portfolio after large market moves. Disappointing Quarter The Russell 1000 Value Index fell 11% in the quarter, much less than the 17% decline for the S&P 500. We expected to compare more favorably to the Russell Value in a down market. What happened? Though we had a couple of company-specific disappointments, including Netflix, which is discussed in our Fund letters,
  60. Hedge Fund Alpha 60 Highlights From Hedge Fund Investor Letters

    we were most surprised by how poorly bank stocks performed. I said “bank stocks” instead of “banks” because I want to differentiate between business performance, which was good, and stock price performance, which wasn’t. We believe that investors are simply looking at how much bank stocks declined in the past two recessions and anticipating a repeat performance. But we believe several facts make that unlikely. First, banks are much better capitalized today. As an example, Bank of America projects a higher tangible equity ratio at the bottom of the Fed’s severely adverse scenario than it had at the top that preceded the Great Recession. Second, banks have historically lowered lending standards before a recession to maintain revenue growth, but every bank we own today is committed to maintaining lending standards and measuring growth on a per-share basis, which gives credit for capital used to reduce shares outstanding. Third, banks today benefit from economies of scale much more so than in the past: Costs for regulatory compliance, fraud protection and digital banking, for example, do not grow linearly with size. That means that being big is a competitive advantage, which results in market share gains as measured by primary checking account relationships. Finally, valuations are extremely depressed: The S&P 500 sells for about 15 times expected 2023 profits, compared to the banks we own that range from 4 to 8 times expected earnings. Our short-term focus is always on business performance, which has been good, rather than stock performance, because in the long run, they converge. Rondure Global on Inflation: 9.1%. There is not a single person in the financial world who does not know this number. 2% is the other one. There is a lot of space between these two numbers, and many correctly hold the Federal Reserve (aka Team Transitory) accountable as they sat idly by last year watching inflation pressures mount. Had they started reducing their monthly $120 billion bond purchases and calmly raising the Federal Funds rate during the 2021 window of economic recovery, fiscal support and robust financial markets, we would not be facing an economic recession and financial market instability as the US Central Bank hits the panic button. For context, let’s look at two numbers. We will not dwell on the past for too long. It is far more interesting to puzzle out the future. During the period post-Global Financial Crisis or GFC (March 2009) to the Covid pandemic (January 2020) inflation averaged 1.6%, comfortably under the Fed’s 2% target. In 2021 inflation rose from 1.4% in January to 7.0% by December. As of May 2022, it stands at a 41 year high of 8.6%. The drivers are well-known. The common global denominator is the massive and ongoing postGFC injections of liquidity by Central Banks which became even more intense during the pandemic. Also, persistent Covid-induced supply bottlenecks, structural supply chain reorganization, the Russian-Ukraine war and consequent impact on commodity prices are major contributors. Combined with Central Bank lethargy, investors are left wondering just how entrenched inflation is…it is really the only question that matters.
  61. Hedge Fund Alpha 61 Highlights From Hedge Fund Investor Letters

    Since Paul Volcker broke the back of inflation in the late 70’s/early 80’s, the US 10-year sovereign bond has essentially been a one-way bet. Any investment professional with less than 40+ years in the financial markets knows nothing but the Fed put. Their neural pathways are deeply entrenched. And since US Treasuries, specifically the 10-year bond, is considered the risk-free rate against which all other risk assets in the global financial system are priced, this “perma-put” has reverberated around the world; Stocks, corporate/sovereign bonds, commodities, property prices globally have all been supported by US Central Bank policy. SPACs, or blank check companies, are perhaps the epitome of the absurdity that accompanies persistent ultra-loose monetary policy. One thing has made Central Bank actions and the bond bull market possible: Low inflation. Between 1983 and 2020, inflation averaged 2.6%, not too far above the Fed’s 2% target rate. This gave them cover to lower rates and keep them low which fueled the technology bubble (1996- 2000) and the housing bubble (2003-2008) that ended in tears with the GFC in 2008. Since 2008, The Federal Reserve put has been in overdrive. No need to go into detail on this, it is a widely covered subject. The point is most investors are wired to expect monetary policy to bail them out. Thank goodness for neuroplasticity. Anyone under the age of 70 in the financial world will need to create new neural connections in order to break old ways of thinking. Until inflation is under control, the Fed must remain restrictive, like a boa constrictor around its prey, tightening until it’s over. This has basic mathematical implications for us financial analysts. Higher discount rate equates to lower valuations. Thus, looking to the prior 10 years of valuation history for context on a given stock is an exercise in myopia. The embedded discount rate is too low. We are looking back pre-GFC for insight. Multiples are much lower. It makes sense: The rate at which we must discount future cash flow rises with the 10-yr US bond yield. Turning to Europe, they are in a different position than the United States. They have a war in their backyard, and they are dependent on the aggressor for hydrocarbons, especially natural gas. Russia is the most important natural gas supplier to the EU, at ~45% of gas imports in 2021. This is over twice the size of the second largest exporter to the EU, Norway. Natural gas dependence has become an albatross for Europe since Russia invaded Ukraine in February 2022. Condemnation and economic sanctions imposed by EU members have been met with threats of supply cutoffs and actual curtailments, making diversification of supply even more imperative. Russia has cut supply through Nord Stream 1, a major pipeline into Europe, by 60%. Dependency on Russian gas will decline gradually and be replaced with regional supplies (Norway, Algeria) and LNG (US, Qatar, Australia). In the meantime, the war has exacerbated the inflation problem in the Eurozone that has accelerated to an all-time high in June, up 8.6% year-over-year, mainly driven by food and energy prices but also broadening and intensifying into other goods and services. Clearly the war is slowing growth, disrupting trade, causing shortages in various goods and pushing up prices of food and energy. The potential for a long and deep recession makes monetary policy normalization tricky, which is why the European Central Bank (ECB) is reluctant to tighten aggressively. As well, the ECB has been very clear that the pandemic emergency purchase program (PEPP) will reinvest principal payments from maturing securities, asymmetrically across countries if required, to avoid “fragmentation” aka a revenge of the PIIGS (Portugal, Italy, Ireland, Greece, and Spain, which all had too much debt going into the GFC). A decade after the European debt crisis, it is astounding that peripheral Eurozone economies are still so fragile that
  62. Hedge Fund Alpha 62 Hedge Fund Investor Letters: Stock Highlight

    they are a potential source of destabilization as rates rise. The ECB has guided to an initial 25bps hike in July and another, size unknown, in September. The euro has sunk toward parity with the dollar, a function of the war and relatively faster rate hikes in the US. Unfortunately, euro weakness only exacerbates Eurozone inflation by making imports more expensive. If the Eurozone is cautious with respect to the pace of tightening, Japan is downright adamant about holding the 10-year JGB yield at 25 bps. Shockingly, Shinzo Abe, Japan’s longest serving Prime Minister (2012-2020) and champion of Abenomics, was assassinated on July 7, 2022. His economic policies were based on the “three arrows” of monetary easing, fiscal stimulus, and structural reform. The aim was to galvanize the Japanese economy that had suffered years of deflation and sluggish economic growth post the 1991 bursting of the asset bubble. While the first two arrows were implemented quickly and with some success, the third arrow unsurprisingly has proved more difficult to implement. The headline issue in Japan today is the Bank of Japan’s (BOJ) seemingly unshakeable adherence to Abenomics-borne yield curve control (YCC) and the consequent extraordinary weakness in the yen that has depreciated over 30% versus the dollar since the onset of the Covid-19 to the weakest level in almost a quarter of a century. While the rest of the world (ex-China) raises interest rates to combat inflation, the BOJ continues to defend a 0.25% cap on their 10-yr JGB with unlimited bond purchases. As in Europe, currency weakness is a function of widening interest rate differentials and the increasingly attractive carry trade. Abe was hugely influential behind the scenes (“shadow shotgun”) and a major proponent of YCC as a means to stimulate growth. There is some question now as to policy direction and the durability of the BOJ’s current monetary stance now that Abe has passed and inflation is rising, although not yet to levels in the US and Europe. Regarding China, Premier Li Keqiang summed it up nicely: “China’s economy is recovering but the foundation of that recovery is not solid, and more efforts are still needed.” Indeed, achieving their GDP growth target of 5.5% in 2022 will require an acceleration in growth in the second half of the year and many doubt this is possible. Supporting economic growth heading into the 20th Party Congress in November is crucial for Xi Jinping who wants to further consolidate his power. The two-month Shanghai lockdown is over however, the Zero-Covid policy is still in place, making further lockdowns a material risk to recovery. In the meantime, with inflation in check, infrastructure spend is accelerating as local governments issue bonds and rapidly deploy funds. Total government spend has increased 12.4% in the first five months of 2022, the highest on record for a comparable period and many other monetary and fiscal stimulus measures are being implemented to revive growth. For now, optimism reigns and the stock market is outperforming other major markets around the world.
  63. Hedge Fund Alpha 63 Hedge Fund Investor Letters: Stock Highlight

    Horizon Kinetics on Refining Capacity: Unfortunately, refinery capacity is another structural inflationary supply constraint we face. While the U.S. refining industry is the world’s largest, with 128 facilities, there were 135 at the start of 2020, and 324 in 1981. The capacity figures (as opposed to the number of refineries) are not as stark: at year-end 1984, refineries operated at only 74% of capacity in aggregate, while they now operate at a 90% utilization rate. The higher utilization offset much of the plant closures. Also, existing refineries benefit from efficiency and capacity improvements, which has probably added 1% per year or so to the aggregate figure. Nevertheless, the U.S. has lost 1 million barrels/day of capacity since the beginning of 2020, which is a 5.4% reduction, though not all of it is permanent. Some are being dismantled, and some facilities are being repurposed, such as for biofuels production. Five percent in a couple of years is a major supply reduction for a critical commodity. That’s short-term. More importantly, since 1984, refining capacity has increased by only 15% while domestic oil consumption rose by 29%. This is the problem. Nor is it just a domestic phenomenon. Globally, about 3 million barrels/day have been lost since 2020. Two of Australia’s four refineries have closed in the past couple of years. Here’s an interesting data point relative to the U.S. refining industry: in May, the Australian government agreed to pay the two remaining refineries up to $1.8 billion through 2030, to keep the plants open and for upgrades to produce cleaner fuel. The two plants have a combined capacity of only 237,000 barrels/day. The last major refinery built in the U.S., quite some time ago – more of which below – has a capacity of 585,000 barrels/day. Why not just build more? Refining is highly capital-intensive, with notoriously deep and volatile profit/loss cycles, and has been subject to increasing political, regulatory and financing constraints. This will sound familiar from prior discussions about the reserves-replacement challenges for oil or copper, only it’s far, far worse. It would be exceedingly difficult, even for a party actually interested in building a sizable refinery, to secure suitable land, the zoning and regulatory approvals, financing, and even equipment. A new project, even assuming, for the purposes of discussion, receipt of the eventual allowances, could take a decade to build. In other words, who would want to build and, if they did, who would want to lend or provide capital? From a return on invested capital perspective, it is a most unattractive industry. How unattractive? The newest refinery with sizable downstream capacity was built in 1977 – 45 years ago. Here’s a synopsis from a highly informed party. This is an industry insider with a known vantage point, so one should take his utterances with that awareness – or wariness – but perhaps informative nonetheless: “We haven’t had a refinery built in the United States since the 1970s,” [Chevron] Chief Executive Officer Mike Wirth said in an interview on Bloomberg TV. “My personal view is there will never be another new refinery built in the United States...You’re looking at committing capital 10 years out, that will need decades to offer a return for shareholders, in a policy environment where governments around the world are saying: we don’t want these products…We’re receiving mixed signals in these policy discussions.”
  64. Hedge Fund Alpha 64 Hedge Fund Investor Letters: Stock Highlight

    Third Point on Disney (DIS): After taking our exposures to almost zero, in recent weeks we have identified several new positions and covered most of our single name shorts, bringing our current exposure back over 40%. Our largest recent addition has been an investment in The Walt Disney Company, which we bought at near its 2022 lows after having exited at the end of Q4 2021 and in the beginning of this year. We are pleased by the strength they are showing across business lines and the progress of Disney’s transformation from “analog” to “digital”, following a blueprint familiar to us from past investments. A letter to management sharing our views about additional value creation measures they should consider is available below: “Congratulations on a terrific quarter and positive momentum in Parks, ESPN, and media and entertainment. We were particularly pleased to see the strength in DTC subscriber growth, the key driver of Disney’s long-term transformation towards less volatile, ultimately higher margin cashflows with a greater return on invested capital. As we wrote to our investors at the time of our initial investment in 2020, which highlighted the extraordinary potential of Disney+, we liken this evolution of the Company from “analog” theatrical releases towards digital distribution to Microsoft’s transition from selling software in plastic wrap boxes to a SaaS model. We expect to see the quality of Disney’s financial results improve as the Company’s business shifts further. We have had over two years to observe management navigate the most challenging time in Disney’s history, as you led the organization to simultaneously grow the DTC business, guide the Parks from pandemic closures to record-revenues and profits, and create quality entertainment content. This quarter’s results are an important proof point that Disney’s complex transformation is succeeding and our confidence in Disney’s current trajectory is such that we have, in recent weeks, repurchased a significant stake in the Company. We have also filed Hart-Scott-Rodino approval with the Federal Trade Commission so that we can engage with management and the Board in order to work directly and constructively with all parties, since the Company will likely require additional strategic, capital allocation, and governance changes to ensure its success. I realize some of our suggestions may already be in the works, but since we do not possess any material non-public information, we thought it might be useful to share our thinking on five important initiatives that we believe will unlock further value in the near-term. 1. Cost Cutting: Disney’s costs are among the highest in the industry, and we believe Disney significantly underearns relative to its potential. We urge the Company to embark on a cost cutting program that addresses both margins and the disposal of excess underperforming assets. 2. Dividend Policy: In a prior letter, we proposed that the Company continue the policy initiated under Covid when parks were closed to suspend payment of a cash dividend. We urge the Company to preserve this policy and use free cash flow to pay down debt, repurchase shares, or organically reinvest in the business.
  65. Hedge Fund Alpha 65 Hedge Fund Investor Letters: Stock Highlight

    3. Hulu: We believe that integrating Hulu directly into the Disney+ DTC platform will provide significant cost and revenue synergies, ultimately reigniting growth in the domestic market. We urge the Company to make every attempt to acquire Comcast’s remaining minority stake prior to the contractual deadline in early 2024. We believe that it would even be prudent for Disney to pay a modest premium to accelerate the integration but are cognizant that the seller may have an unreasonable price expectation at this time (while noting the seller has already made the decision to prematurely remove their own content from the platform.) We know this is a priority for you and hope there is a deal to be had before Comcast is contractually obligated to do so in about 18 months. 4. ESPN: ESPN is a great business that currently generates significant free cash flow, enabling the Company to pay down debt and increase strategic options down the line. In addition, we realize ESPN content is part of the bundle being offered to subscribers of other products, both in Disney’s Linear and DTC businesses. Despite these advantages, we believe that a strong case can be made that the ESPN business should be spun off to shareholders with an appropriate debt load that will alleviate leverage at the parent Company. The important questions to ask before commencing a spinoff are: Will both companies be better off? Will the needs of customers be better served? Can any synergies that exist between the two companies be replicated by contractual arrangements? Will the transaction contribute to creating long-term value for Disney shareholders? While acknowledging that broader capital structure considerations may be at issue, we believe that the answer to all four of these questions is affirmative. Employees of ESPN could be compensated in a security directly tied to their performance. ESPN would have greater flexibility to pursue business initiatives that may be more difficult as part of Disney, such as sports betting. Customers of ESPN and sports leagues would be better served by a focused management team driving a leadership position in sports distribution. We believe that most arrangements between the two companies can be replicated contractually, in the way eBay spun PayPal while continuing to utilize the product to process payments. Lastly, as a result of this transaction, both companies will attract shareholders seeking the respective qualities of each company, allowing the Disney parent multiple to expand as its earnings growth rate increases and the remaining business is no longer haunted by the specter of cord cutting. While I understand you have considered this idea in the past, we urge the Company to retain advisors to reassess the desirability of the transaction in the current environment, recognizing that a key determination would be the proforma capitalizations, cashflow and credit profile of both companies. 5. Board Refresh: Disney is a world-class company that deserves a world-class board of directors who possess diverse talents and experience with strengths in technology, advertising, and consumer engagement, as well as proven track records of leading large complex organizations and creating
  66. Hedge Fund Alpha 66 Hedge Fund Investor Letters: Stock Highlight

    shareholder value. This is not meant to single out any current board members, but we believe there are gaps in talent and experience as a group that must be addressed. Third Point has identified potential board members who we believe would make essential contributions to the Company’s Board at this critical time. We would be happy to make an introduction. I look forward to discussing these topics with you, Christine, and when practicable, the Board and company advisors. Voss Capital on Extreme Networks (EXTR) EXTR is now the Voss Value Fund’s third largest position at 10% of the portfolio (behind GFF and SWIR). EXTR is a leader in wireless and wired networking equipment (switches, access points, routers), particularly in large scale, complex wi-fi deployments such as hospitals and sprawling university campuses. The Fund has owned EXTR since the middle of 2020 and have previously shared our research on it publicly (see the Voss Q3 2020 Quarterly Letter). At the start of 2020, the company had a >3.0x net leverage ratio and new product orders briefly collapsed around the Covid-related shutdowns. Fast forward to today and leverage is under 1.0x and the shares are even cheaper at 7.5x our next twelve months free cash flow estimate (as of the middle of July), despite their product order backlog being well over 10x what is historically normal. In other words, right as its valuation hits a historic low on a free cash flow basis, we believe the company’s visibility has never been higher. As EXTR’s backlog is realized over the next ~10 quarters, combined with its burgeoning software platform that is just now hitting significant scale (generating >$100 million in recurring revenue while growing 40% yearover-year), we believe the company will generate $750 million in free cash flowover the next three years, which compares favorably to a current market cap of just $1.2 billion and an enterprise value of $1.4 billion. In our view, consensus estimates are far too low for each of the next three years. Even as we heavily discount management’s long-term guidance and assume a slower fiscal 2024 from a bookings (signed contracts) perspective, we get the following profile:
  67. Hedge Fund Alpha 67 Hedge Fund Investor Letters: Stock Highlight

    With the stock’s valuation and risk/reward profile arguably much more attractive now than at the time of our first purchases when the stock was $4, why does the opportunity exist? First, to state the obvious, almost all small cap tech stocks have been brutally bludgeoned—dragged down by the non-profitable tech stock bubble bursting. Furthermore, from our vantage point the market is suffering from a combination of short-termism and lack of faith in management’s detailed outlook that was presented recently at their analyst day on June 2nd. If the management team is even near the ballpark of executing on their 3-year vision, the stock will be trading at 4x FCF given the enormous amounts of cash we expect to accrue on the balance sheet between now and FY 2025 (ended June 2025). From discussions with resellers/channel partners and competitors, to attending their user conference and speaking with customers, converging lines of evidence from multiple independent sources support the plausibility that EXTR is taking market share in real-time from Cisco and is poised to show robust growth— even through a hypothetical industry downturn that exceeds the magnitude of 2009’s. EXTR’s hardware order backlog is typically $20 - $40 million in any given quarter comprised solely of orders that came in near the end of the quarter as they normally ship every order they get immediately. Today that backlog stands at $513 million, and their lead times are the lowest in the industry (certainly ahead of Cisco, who is prioritizing their largest customers). The vast majority of the orders are wanted “as soon as possible.” Additionally, it appears management has enough visibility in the sales pipeline and order trends to publicly state they believe the backlog will continue to grow through Fiscal Year 2023: “Next year, we talked about adding – growing the top line because of releasing supply chain. But we'll still be constrained. So, we'll add another – we expect maybe $150 million, call it in backlog.” -CEO Ed Meyercord, Needham Tech and Media, May 19th, 2022 If that does indeed come to fruition, we estimate the Product backlog would be around $600 million a year from now when their Fiscal 2023 ends. A key to remember is that these are non-cancellable orders. The backlog going from $105 million to $513 million in FY 2022 means that over the last 12 months EXTR has temporarily foregone over $400 million of high incremental margin revenue that they would have recognized if they weren’t supply constrained. There is also significant service and software revenue tied to this hardware backlog, as customers will sign software deals once the hardware ships. Thus, we estimate these forthcoming hardware sales will provide an additional $75 million in recurring software and services revenue. By our calculations, if backlog had remained static over the last four quarters, revenue growth would have been > 45% over the past year, rather than the 10% they reported. SaaS subscription revenue, already impressive at $100 million ARR and growing at 40%, would be closer to $150 million. While we don’t expect 45% growth to be sustainable, in our view the company is being valued as a 10% (or lower) grower rather than the market share taker in a positively trending industry with secular growth tailwinds.
  68. Hedge Fund Alpha 68 Hedge Fund Investor Letters: Stock Highlight

    The company should also have some additional hardware revenue buffers in FY2024 and 2025 after they work through the current backlog, as they have two major projects with Verizon and Ericsson that could generate an incremental $75-$100 million in revenue a year for several years in a row. And although we are not currently modeling it, we also expect them to continue to take market share from Cisco. This is important because each 1% market share gain is quite impactful to Extreme, i.e., ~$200 million in incremental revenues, and ~$75 million in annual FCF. With our channel checks indicating that Cisco has “all but abandoned” the middle market, we think EXTR has a timely window of opportunity to take more market share. ExtremeCloud IQ Backlog: As mentioned, there is significant Cloud IQ revenue coming from the giant hardware backlog, likely in the range of $50 million of subscription revenue just in the current backlog (in addition to another ~$25 million of annual maintenance revenue).The second major driver that is increasing visibility is the emergent scaling of the ExtremeCloud IQ platform. Back in 2020, while the company was growing their cloud bookings at a strong pace, it was off a low (and undisclosed) base. The company was moving a lot of their customer base, particularly their wireless equipment base, to subscription contracts. Now, even as the company has passed $100 million in ARR for their Cloud Management software, there are several credible growth drivers that we believe make management’s seemingly aggressive forecast (+40% ARR CAGR 2022-2025) realistic and maybe even conservative. Here are the main drivers as we see them: 1. Backlog: As mentioned, there is significant Cloud IQ revenue coming from the giant hardware backlog, likely in the range of $50 million of subscription revenue just in the current backlog (in addition to another ~$25 million of annual maintenance revenue). 2. Renewals: The most common duration of a subscription contract is three years. Of note, customers were put on “teaser” rates initially, with the expectation that pricing would rise at the time of renewal. The company is just now beginning to enter a period of large potential renewals (really ramping in 3-4 quarters from now as we lap three years for customers who signed in 2020) and expects 90%+ gross customer retention, with net revenue retention moving towards 100%. Given the large discount given initially and the hassle of a “rip and replace,” we think this 100% bar seems attainable and likely conservative. 3. Copilot/Digital Twin: The company has also been beta testing the “next generation” of features that automates the network in the form of new modules called Copilot and Digital Twin. Copilot adds significant additional features that allows for network automation, while Digital Twin is a cloud oriented solution that allows for more robust, virtualized testing infrastructure. In addition to getting higher base prices on their renewals, EXTR’s sales force will be attempting to upsell these new modules, which carry 50-60% ARPU increases. 4. SD-WAN: The company has fully integrated and launched their SD-WAN (software defined wide area network) product into the market that they acquired last year (Ipanema). SD-WAN, when deployed, will carry a very significant uplift to ARPU. It’s our understanding that to hit their growth targets, they need only penetrate about 2% of their 50,000 customers over three years, and only are targeting 250 SD-WAN customers in 2023. This would represent ~20% of their total estimated ARR growth over the next few years.
  69. Hedge Fund Alpha 69 Hedge Fund Investor Letters: Stock Highlight

    All four of these drivers seem to be quite significant and it appears reasonable to us that ARR could move from ~$105 million at the end of June 2022 to $250 million by 2025 (matching the midpoint of the 40% CAGR management is guiding to). However, for now we are modeling 34% cloud revenue growth as we are taking what we believe to be a conservative approach on renewals until we see more evidence of solid sales execution. We would also note in our view that most of the cannibalization in moving some of their software revenue to ExtremeCloud IQ has already occurred. Their software license/maintenance was around $40 million a year and it has now dropped to under $12 million a year, so one will soon see a positive inflection in total Recurring Revenue dollars and thus the stock will likely screen better and potentially begin to attract more growth focused software investors. Management has said that expedited shipping and elevated freight rates have knocked down product gross margins by an incredible 700-900 bps12, and that as freight rates return to earth, they will start to reap the benefits of their significant SKU count reduction and product consolidation onto their Universal Hardware platform. However, for the sake of conservatism, we assume hardware gross margins do not rise above 60% (vs management’s guidance of 64%) as it is possible they have to give back some of their recent price hikes as industry supply constraints ease. EXTR shares look very attractive on a relative value basis versus its larger networking equipment peers, as well as on an absolute basis at 9x our NTM FCF estimates (our FCF estimate is ~50% above the consensus estimate), even after the stock’s recent run from $8.50 to ~$13. At 8x our Bear case FCF estimate, the stock has downside to only ~$9 (hence our significant upsizing of the position recently <$9) and at 15x our bull case 2025 FCF estimate, our price target moves up to ~$40. We take comfort in the fact that in 2008, EXTR’s product revenue grew and in 2009 it declined by only 9.5%.13 Given their product order backlog is currently ~25x the size it was at the end of 2019, we are comfortable that EXTR can grow even through an economic depression. The risks for Extreme mostly revolve around timing and management credibility on forecasts. At times they have been overly optimistic, particularly around forecasts from acquisitions, as well as recently around gross margins. However, if management loses additional credibility and the stock gets stuck in a penalty box, we believe there would be strategic suitors who would be interested in acquiring the company for its customer base and industry-leading cloud technology, along with significant sales and marketing and R&D synergies. Valued at an enterprise value of just 2x gross profit and 9x FCF, the risk feels highly asymmetric to the upside.
  70. Hedge Fund Alpha 70 Hedge Fund Investor Letters: Stock Highlight

    Alta Fox on Everbridge Inc. (EVBG) Everbridge is an enterprise SaaS business that provides mass notification and critical event management (CEM) software in a world with increasing risks (natural disasters/weather, civil unrest, pandemic, active shooters, etc). The software allows large corporates to better manage employees and assets during times of disruption. Everbridge serves 47 of the Fortune 50, has 110%+ net revenue retention, gross margins approaching 80%, and EBITDA margins that are beginning to meaningfully inflect higher. This is a great business. However, the stock has always been far too expensive for us to underwrite to acceptable IRR thresholds within a reasonable valuation framework. As recently as late last year, investors were willing to pay ~14x forward revenue for Everbridge as the stock price topped out at ~$160/share. The sudden departure of the company’s CEO in December 2021 as well as forward guidance below the Street’s lofty expectations, prompted a precipitous fall in EVBG’s share price. In December, when Everbridge’s former CEO left to take the CEO role at a large PE-backed cloud business, he likely knew that EVBG trading at 14x revenue with slowing growth meant limited upside ahead (and limited personal wealth creation). Since the CEO’s departure and decline in stock price, a prominent activist investor has taken a stake in the business and is advocating that the board initiate a process to sell the business. Given investors have lost confidence in the management team and board’s ability to create long term value in the public markets, we agree that the company should immediately pursue a sale. We believe the quality of the business along with the upside potential for profit margins and the current valuation make Everbridge an extremely attractive target for private equity buyers who are currently sitting on substantial amounts of dry powder. Orlando Bravo, the co-founder of tech PE giant Thoma Bravo said it best during his appearance on CNBC on May 24: “For us in private equity, as a buyer and operator of software companies, this environment of five times forward revenue is the buying opportunity of a lifetime.” We believe the CEO departure, two disappointing 2022 guides, and broader market volatility have put Everbridge into the penalty box. Current sell-side expectations appear far too low, as consensus assumes the company will grow revenue 16% in 2023 and EBITDA margins will expand to 12.5%. The company’s Co- CEO clearly believes the business will perform better than sellside expectations, as he stated the following at an investor conference in May: “Wouldn’t be surprised if next year, there’s a quarter where adjusted EBITDA margin starts with a two and ultimately, we’ll see where that top line growth rate shakes out. If it looks like we’re going to be growing in the mid-teens, then we will drive adjusted EBITDA towards mid-20s, maybe even 30%.” Today, EVBG is valued at ~3x consensus 2023 revenue (which appears low) with the stock at ~$30/share, down more than 80% from its 2021 highs. At ~3x forward revenue, investors can buy a high-quality enterprise software business with sticky and recurring revenue, inflecting margins, and a potential take- private catalyst. While we believe a sale of the company is in the best interest of all stakeholders, even if the company stays public, we estimate investors can achieve a ~30% IRR over the next several years as Everbridge’s EBITDA margins expand to the mid-30s and assuming a modest 13x EBITDA multiple.
  71. Hedge Fund Alpha 71 Hedge Fund Investor Letters: Stock Highlight

    Greenlight Capital on Twitter (TWTR): In April, Musk agreed to buy TWTR for $54.20 per share. Then, in May, he appeared to change his mind. The case law on this is quite clear. If it were anyone other than Musk, we would handicap the odds of the buyer wiggling out of the deal to be much less than 5%, or the percentage of bots that might be on Twitter. But, it is Musk and therefore many believe that the laws again won’t apply. One former judge on the Delaware Chancery Court (where the case is being heard) went on CNBC to speculate that the court might let him out of the deal because Musk won’t respect the judgment, which would embarrass the court. Another variation is the court might rule against him, but TWTR might not be able to enforce the judgment. Apparently, many people either believe these outcomes are acceptable or, in the alternative, are just the way the world works. We hope it isn’t so. Actually, we can do more than hope. We purchased a position in TWTR at an average of $37.24 per share. At this price there is $17 per share of upside if TWTR prevails in court and we believe about $17 per share of downside, if the deal breaks. So, we are getting 50-50 odds on something that should happen 95%+ of the time. We think that the incentive of the Delaware Chancery Court, the preeminent and most respected business court in the nation, is to actually follow the law and apply it here. If it lets Musk off the hook, it will invite many future buyer’s remorse suits. Cynical buyers might contract with targets and then use the threat of litigation and the resulting uncertainty to recut the deal. The Delaware Chancery Court has spent years developing case law relating to merger agreements. The resulting precedent and clear understanding of buyers’ contractual obligations has created a great deal of predictability in this sphere. It will be up to Chancellor McCormick to follow that precedent and protect the sanctity of the court. We like the risk- reward that she will. Bronte Capital on Meta Platforms (META): The most notable cheap stock is Meta Platforms (née Facebook). Meta is priced at 3.5 times run-rate revenue, 12 times earnings and under 8 times EBITDA. The earnings are suppressed by large expenditures on a future 3-D world (the “metaverse”) which presumably has lots of revenue opportunities (but which strains our sense of credulity). Whatever – the traditional business has had revenue growth for over a decade and the revenue growth has never gone under 20 percent.
  72. Hedge Fund Alpha 72 Hedge Fund Investor Letters: Stock Highlight

    Realistically it will now though. Competition from TikTok is a threat, as is increased regulation. Finally, the original Facebook plaform (but not Instagram) has declining appeal to young people. In the twelve months ending 31 March 2022, the company repurchased over US$50 billion in common stock mostly funded by cash generated, but also by running down cash balances somewhat. To not make money in this stock, the future has to be far worse than the past or present. That is certainly possible. Facebook has behaved very badly, never letting privacy concerns or ethics stand between them and a pile of dollars. The Cambridge Analytica scandal happened to Facebook, not to Google. The European Union in particular has passed privacy regulations that are extremely hostile to Facebook’s business. The future could go very wrong. We think we will make money in this stock, but we are not sure. RV Capital on Credit Acceptance (CACC) : Our largest position both at the start of the year and today is Credit Acceptance, a lender to subprime borrowers to purchase a used car. I explained our reasons for investing in Credit Acceptance in my 2014 letter. I was very optimistic about the investment then – naturally, otherwise why else invest – but the investment has surpassed my high expectations. From 2014 through 2021, adjusted earnings per share grew by 21.4%, 19.6%, 15.7%, 38.9%, 22.2%, 10.3%, and 34.2% respectively. This is the stuff that investing dreams are made of – each year varied from good to fantastic. Great though the company’s operational performance was, what supercharged growth in earnings per share was the company's willingness to repurchase its own shares. At the time we invested, the company had 20.6 m shares outstanding. As of 25 July this year, that number stands at 12.9 m. This means that not only has the company greatly increased its earnings power, but our share of those earnings has increased by 60% over the holding period. If you think the investment has been plain sailing though, you would be mistaken. I have lost count of the number of times, the share price fell by 10%, 20%, or more in a single day based on some piece of news or other that supposedly impaired the company’s value. It is a wonderful illustration of Ben Graham’s dictum that in the short run the market is a voting machine and in the long run, it is a weighing machine. With the used car market in disarray and a recession potentially on the horizon (when is a recession ever not potentially on a horizon?), the share price development this year reflects the market’s concerns about what the immediate future holds. I am not concerned on either count.
  73. Hedge Fund Alpha 73 Hedge Fund Investor Letters: Stock Highlight

    The recent surge in used car prices has been great for loan performance at Credit Acceptance but priced its core sub-prime customer out of the market. As a result, Credit Acceptance has seen declining unit volumes (though the trend shifted in the most recent quarter). A normalisation in the used car market would be a tailwind in this regard. No doubt, it would be accompanied by headlines about how terrible the decline in used car prices would be for loan performance, but, in reality, the proceeds from repossessed cars are a relatively minor source of cash flow for the company. All the company’s energy goes into “keeping the customer in the car” – a refrain I repeatedly heard whenever I visited the company’s collections centre. A recession would be a short-term negative for loan performance as employment levels closely correlate with collections. However, historically Credit Acceptance has made the greatest strides in earnings performance when other lenders are forced to scale back lending. Credit Acceptance is the company with the strongest balance sheet and the highest margins. As a result, should other lenders be forced to scale back lending in a more hostile economic environment, it should be able to lean in. The headlines may be ugly, but if history is anything to go by, Credit Acceptance will do fine. Moreover, you can be sure the company will use any share price declines to lower the share count further. Credit Acceptance is, for sure, a company that passes the Buffett test – you can enjoy it when the share price falls.