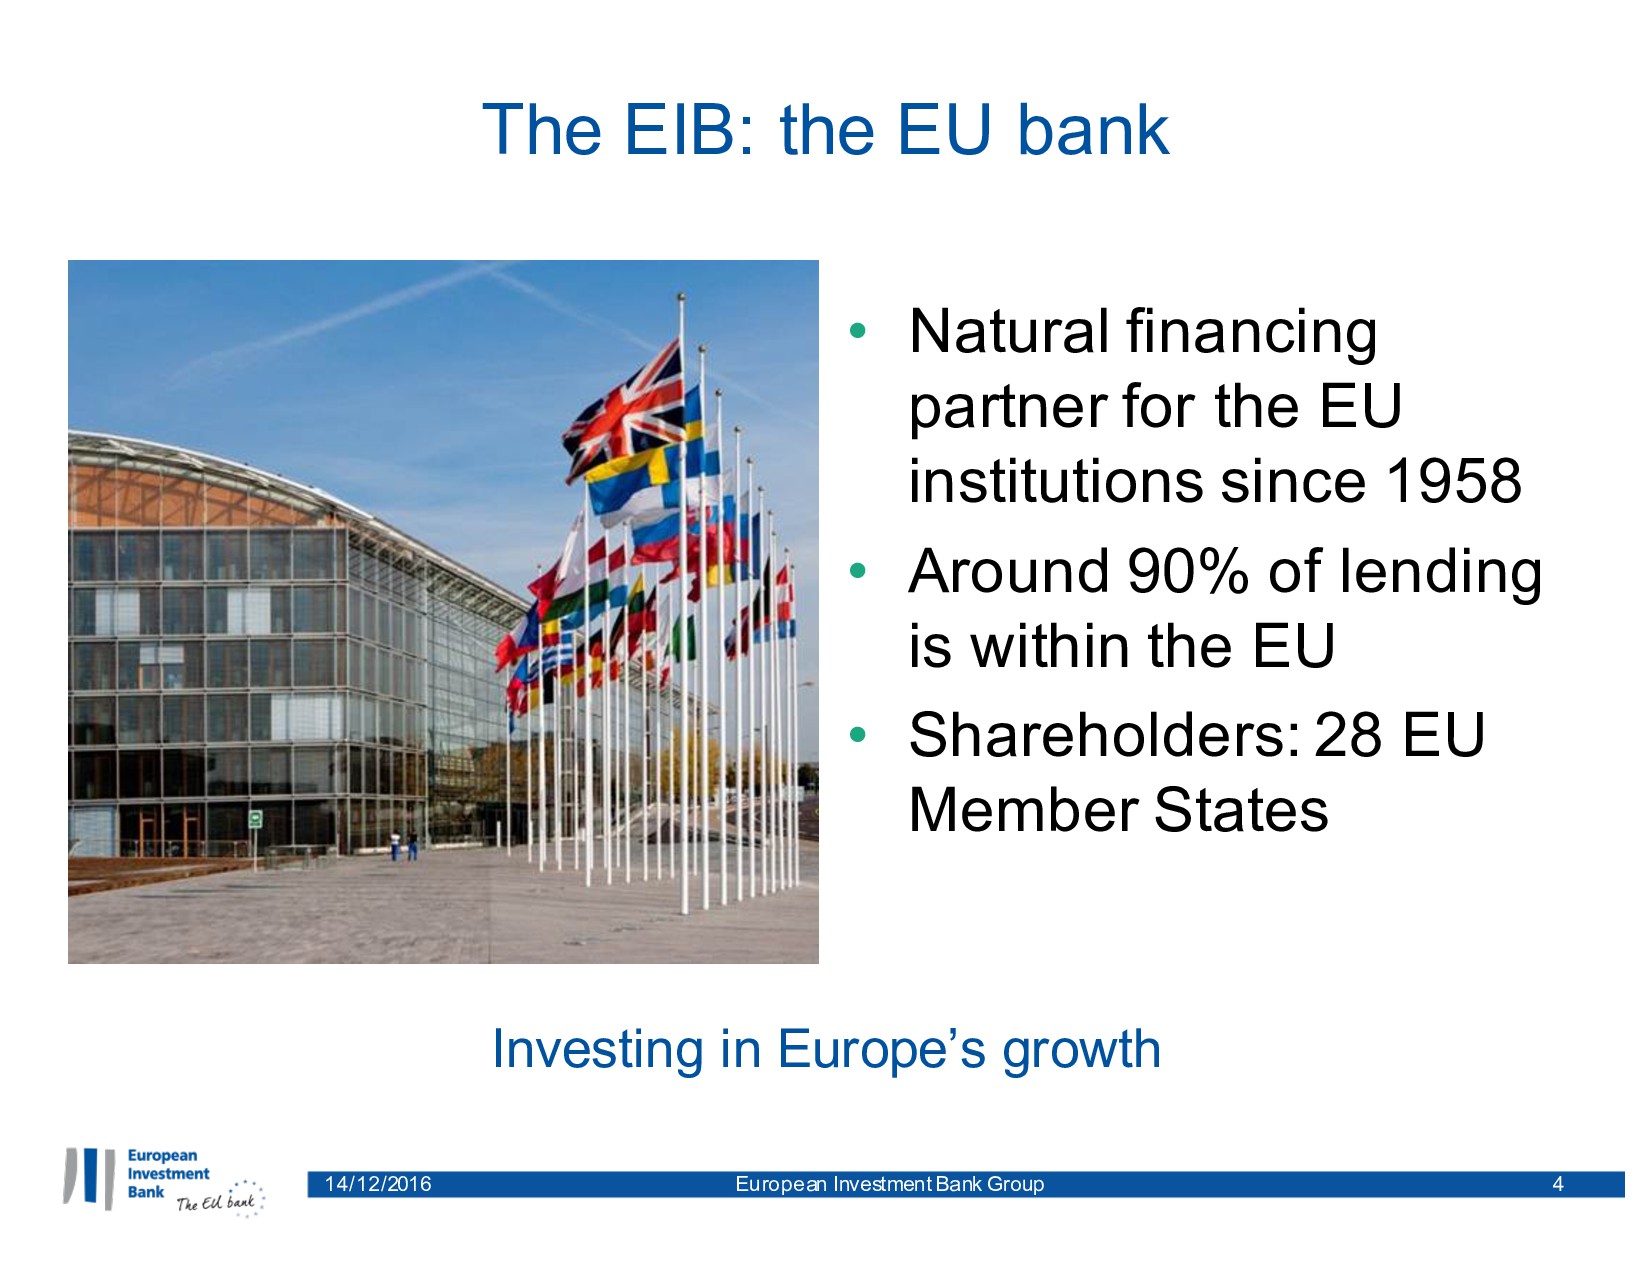
4 Investing in Europe’s growth • Natural financing partner for the EU institutions since 1958 • Around 90% of lending is within the EU • Shareholders: 28 EU Member States
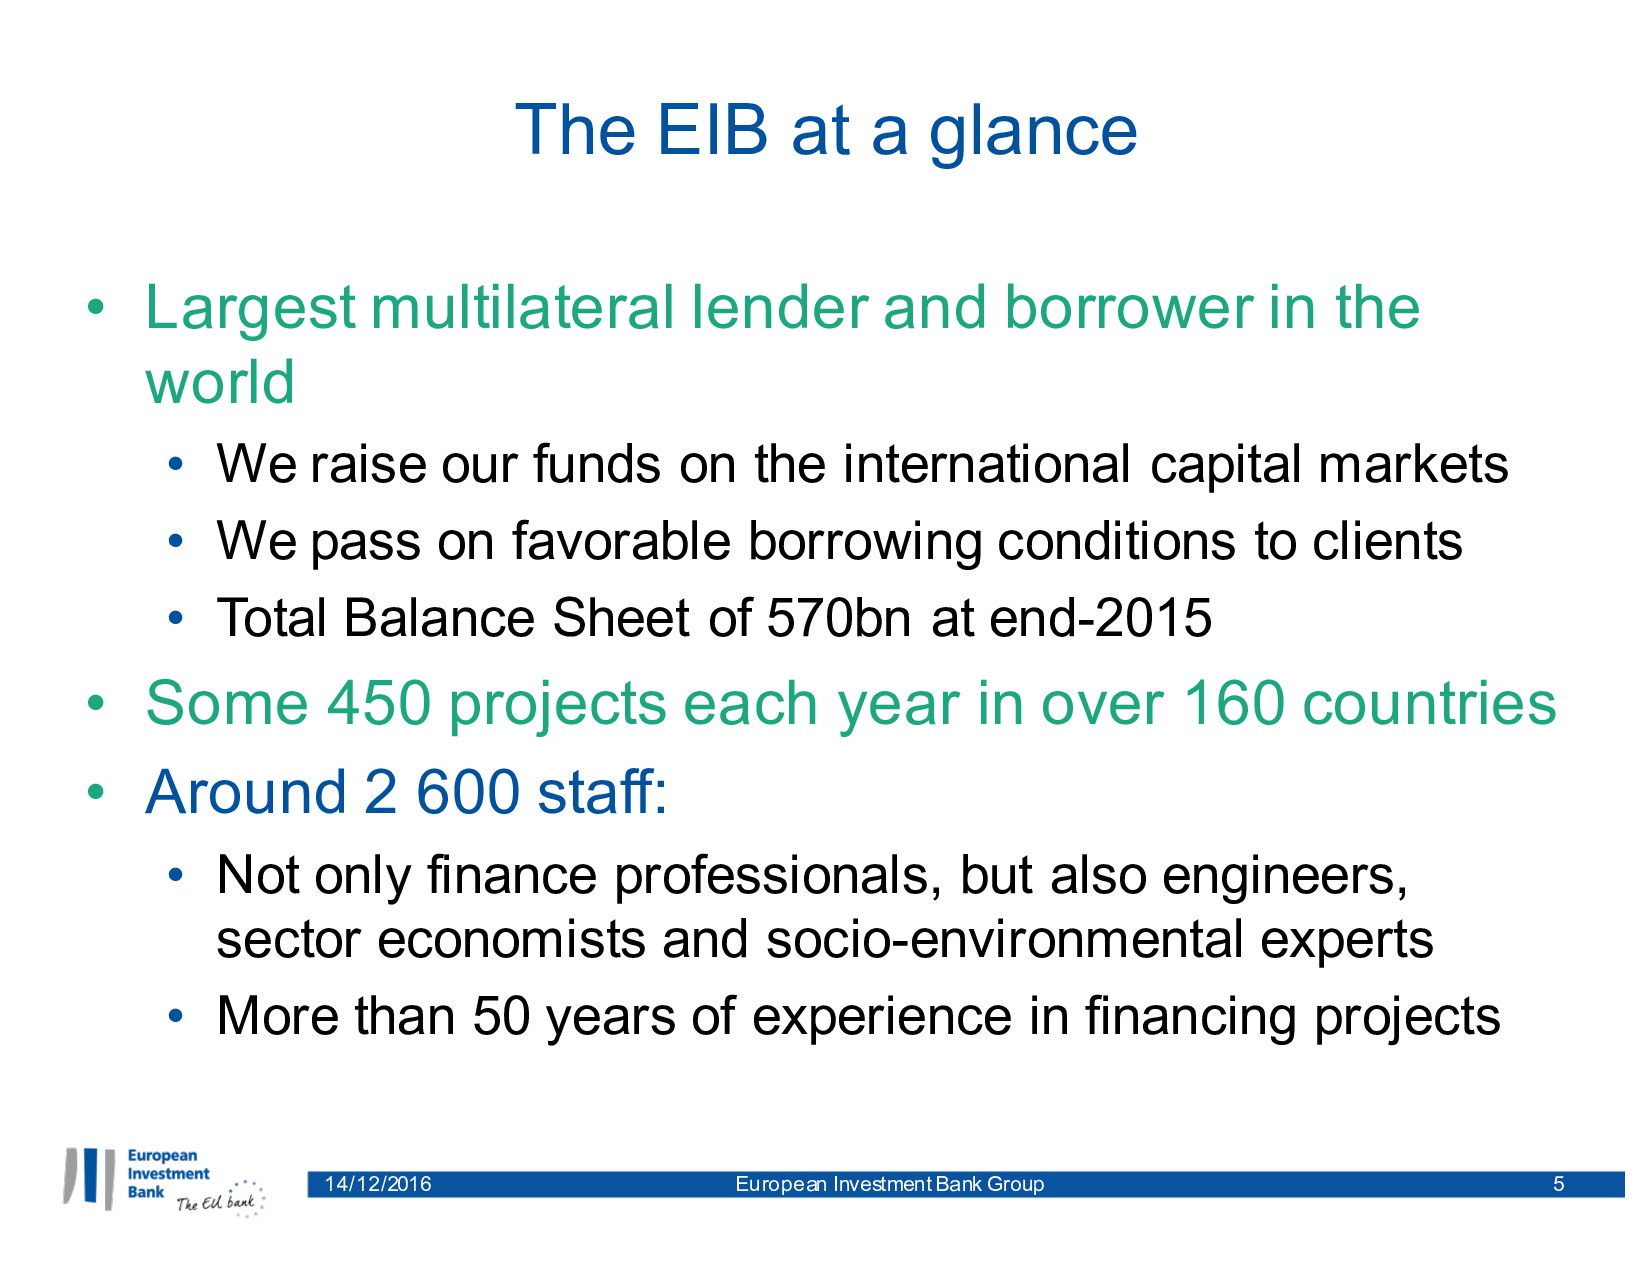
borrower in the world • We raise our funds on the international capital markets • We pass on favorable borrowing conditions to clients • Total Balance Sheet of 570bn at end-2015 • Some 450 projects each year in over 160 countries • Around 2 600 staff: • Not only finance professionals, but also engineers, sector economists and socio-environmental experts • More than 50 years of experience in financing projects 14/12/2016 European Investment Bank Group 5
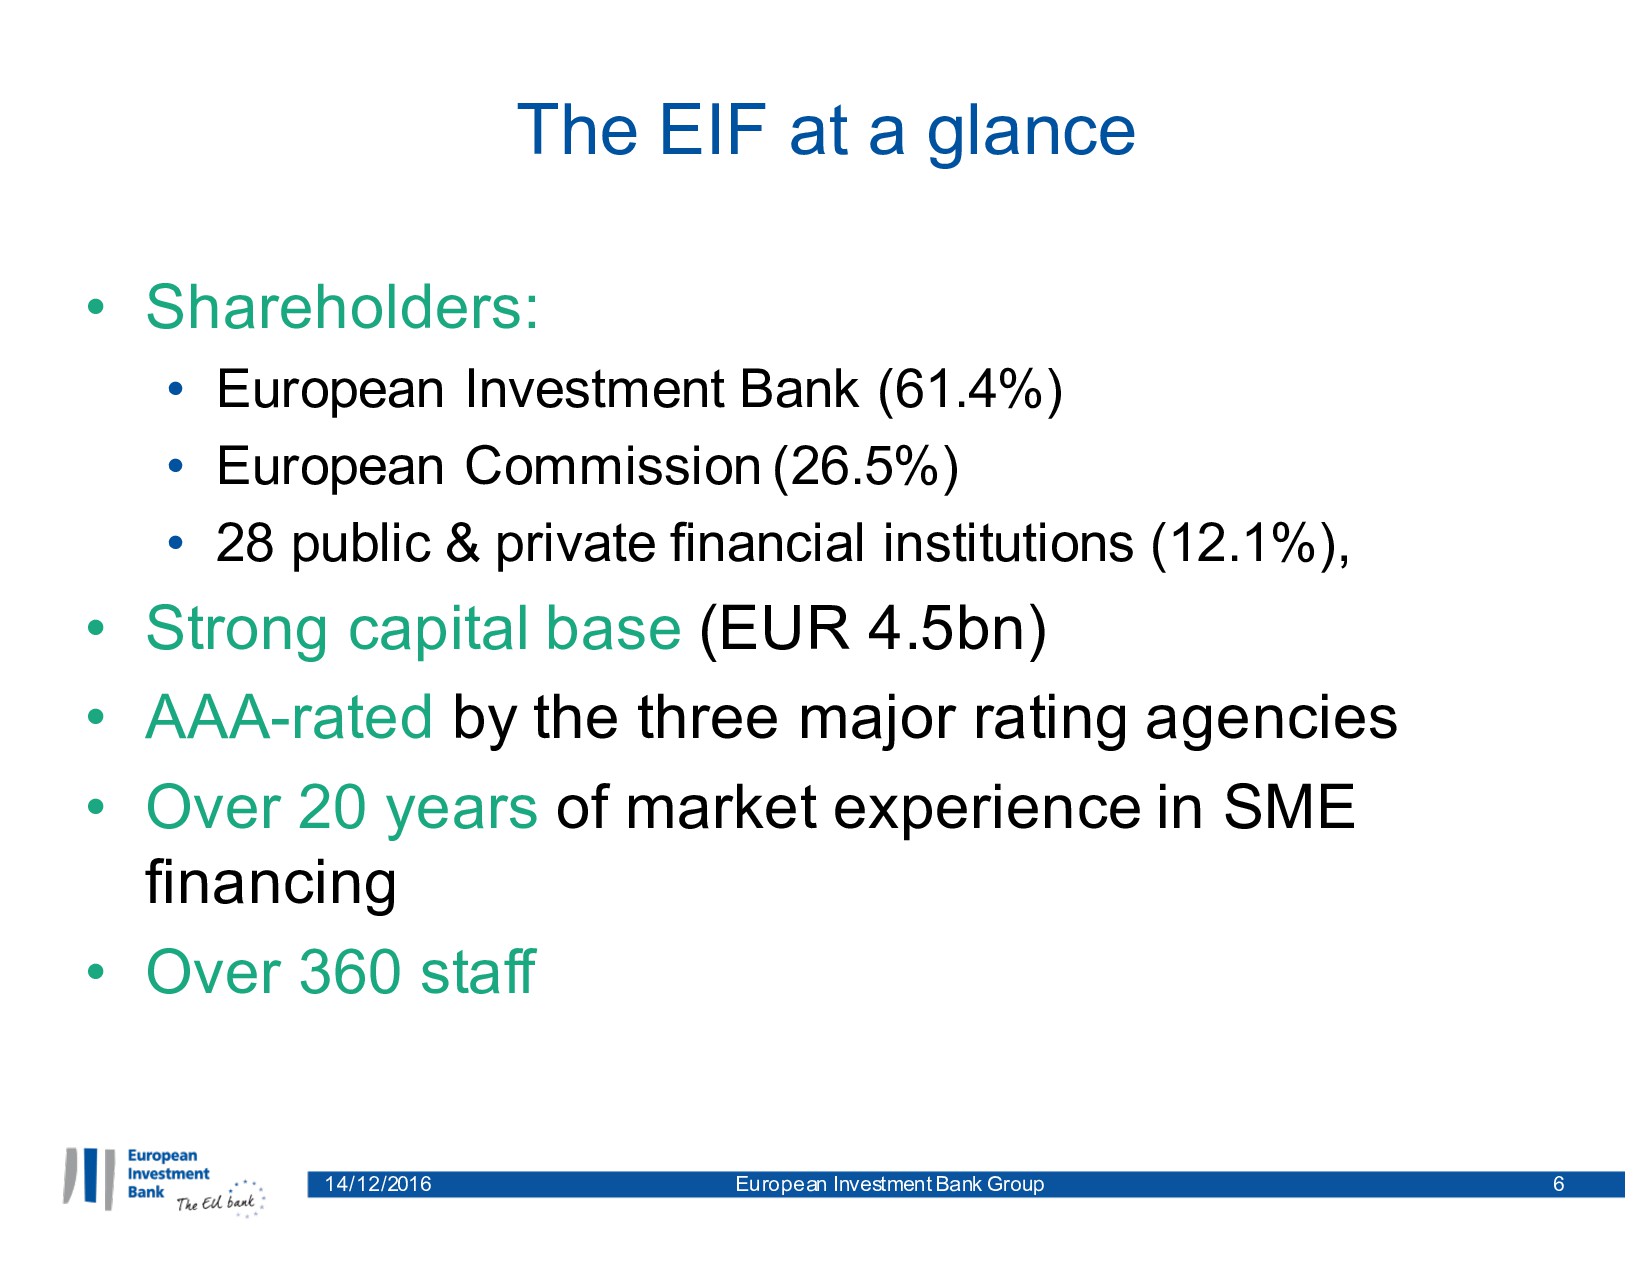
Bank (61.4%) • European Commission (26.5%) • 28 public & private financial institutions (12.1%), • Strong capital base (EUR 4.5bn) • AAA-rated by the three major rating agencies • Over 20 years of market experience in SME financing • Over 360 staff 14/12/2016 European Investment Bank Group 6
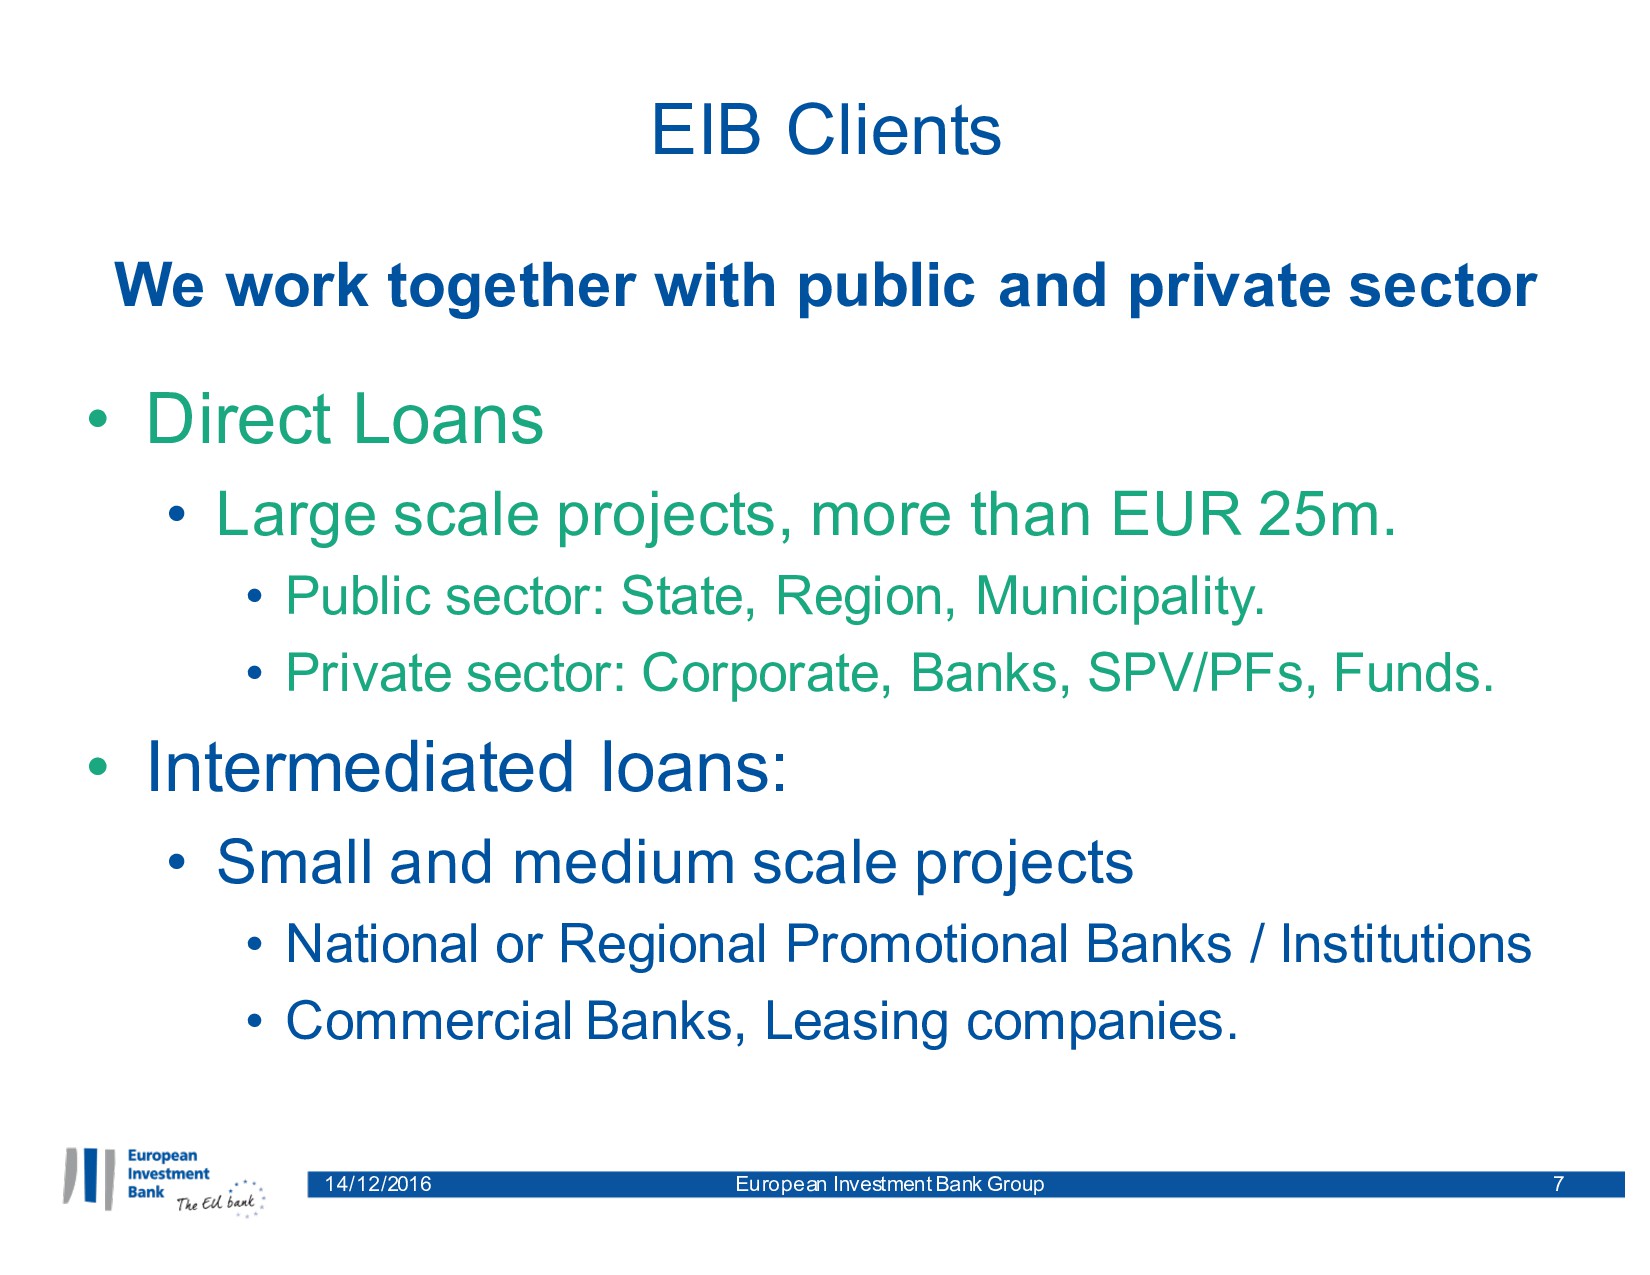
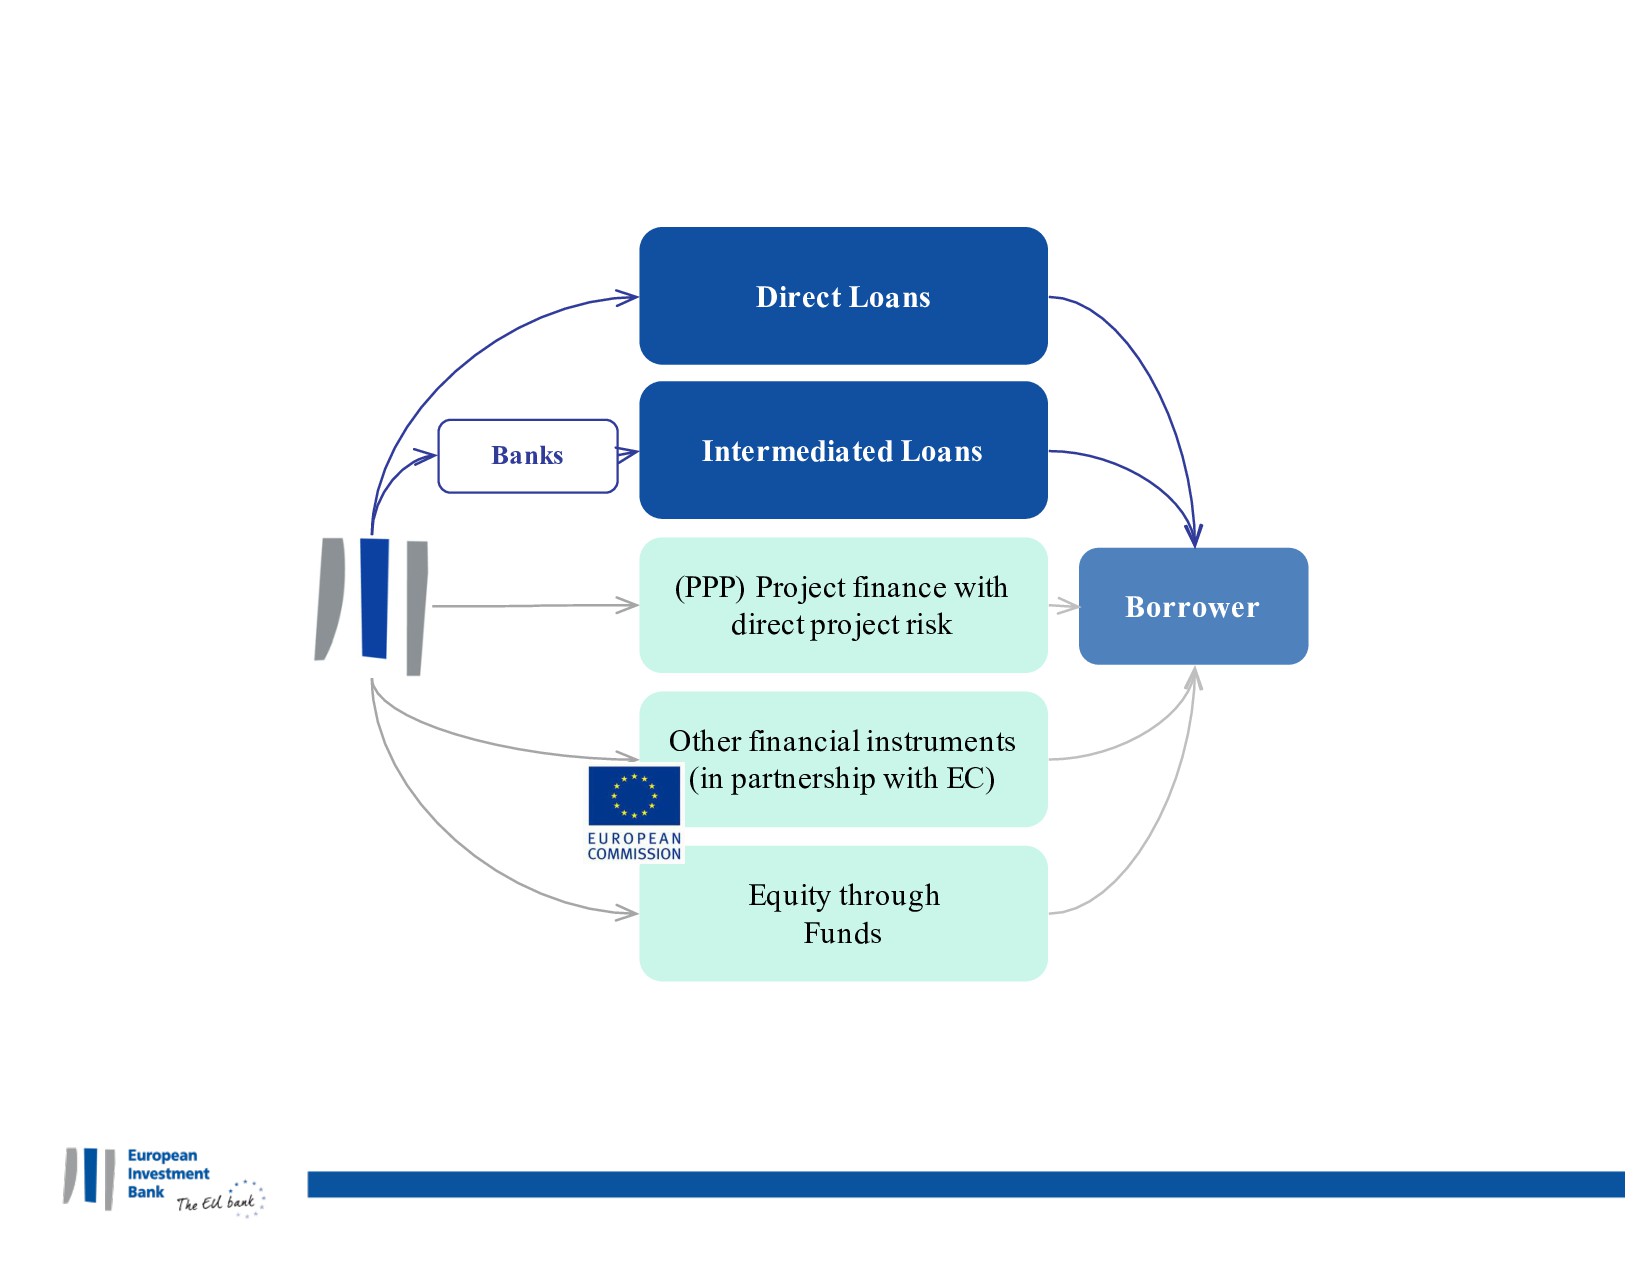
14/12/2016 European Investment Bank Group 7 • Direct Loans • Large scale projects, more than EUR 25m. • Public sector: State, Region, Municipality. • Private sector: Corporate, Banks, SPV/PFs, Funds. • Intermediated loans: • Small and medium scale projects • National or Regional Promotional Banks / Institutions • Commercial Banks, Leasing companies.
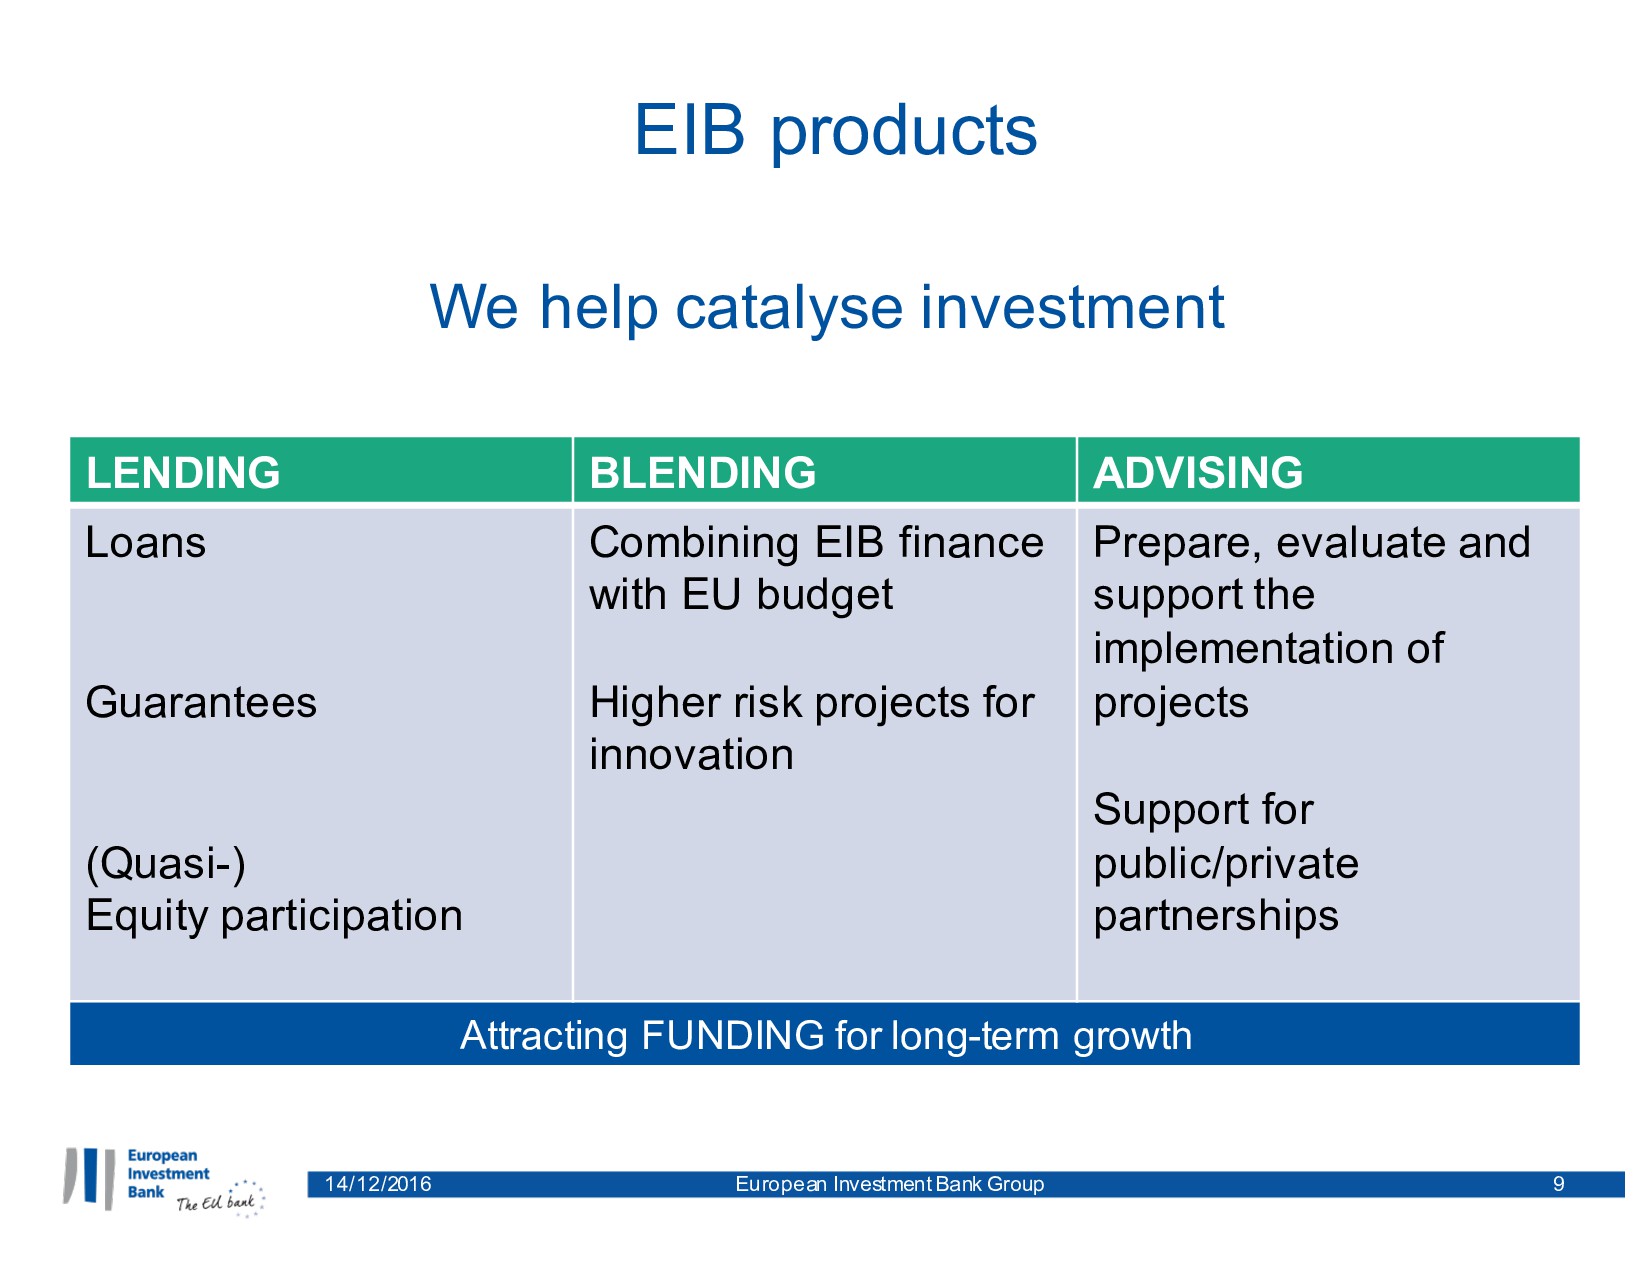
Group 9 LENDING BLENDING ADVISING Loans Guarantees (Quasi-) Equity participation Combining EIB finance with EU budget Higher risk projects for innovation Prepare, evaluate and support the implementation of projects Support for public/private partnerships Attracting FUNDING for long-term growth
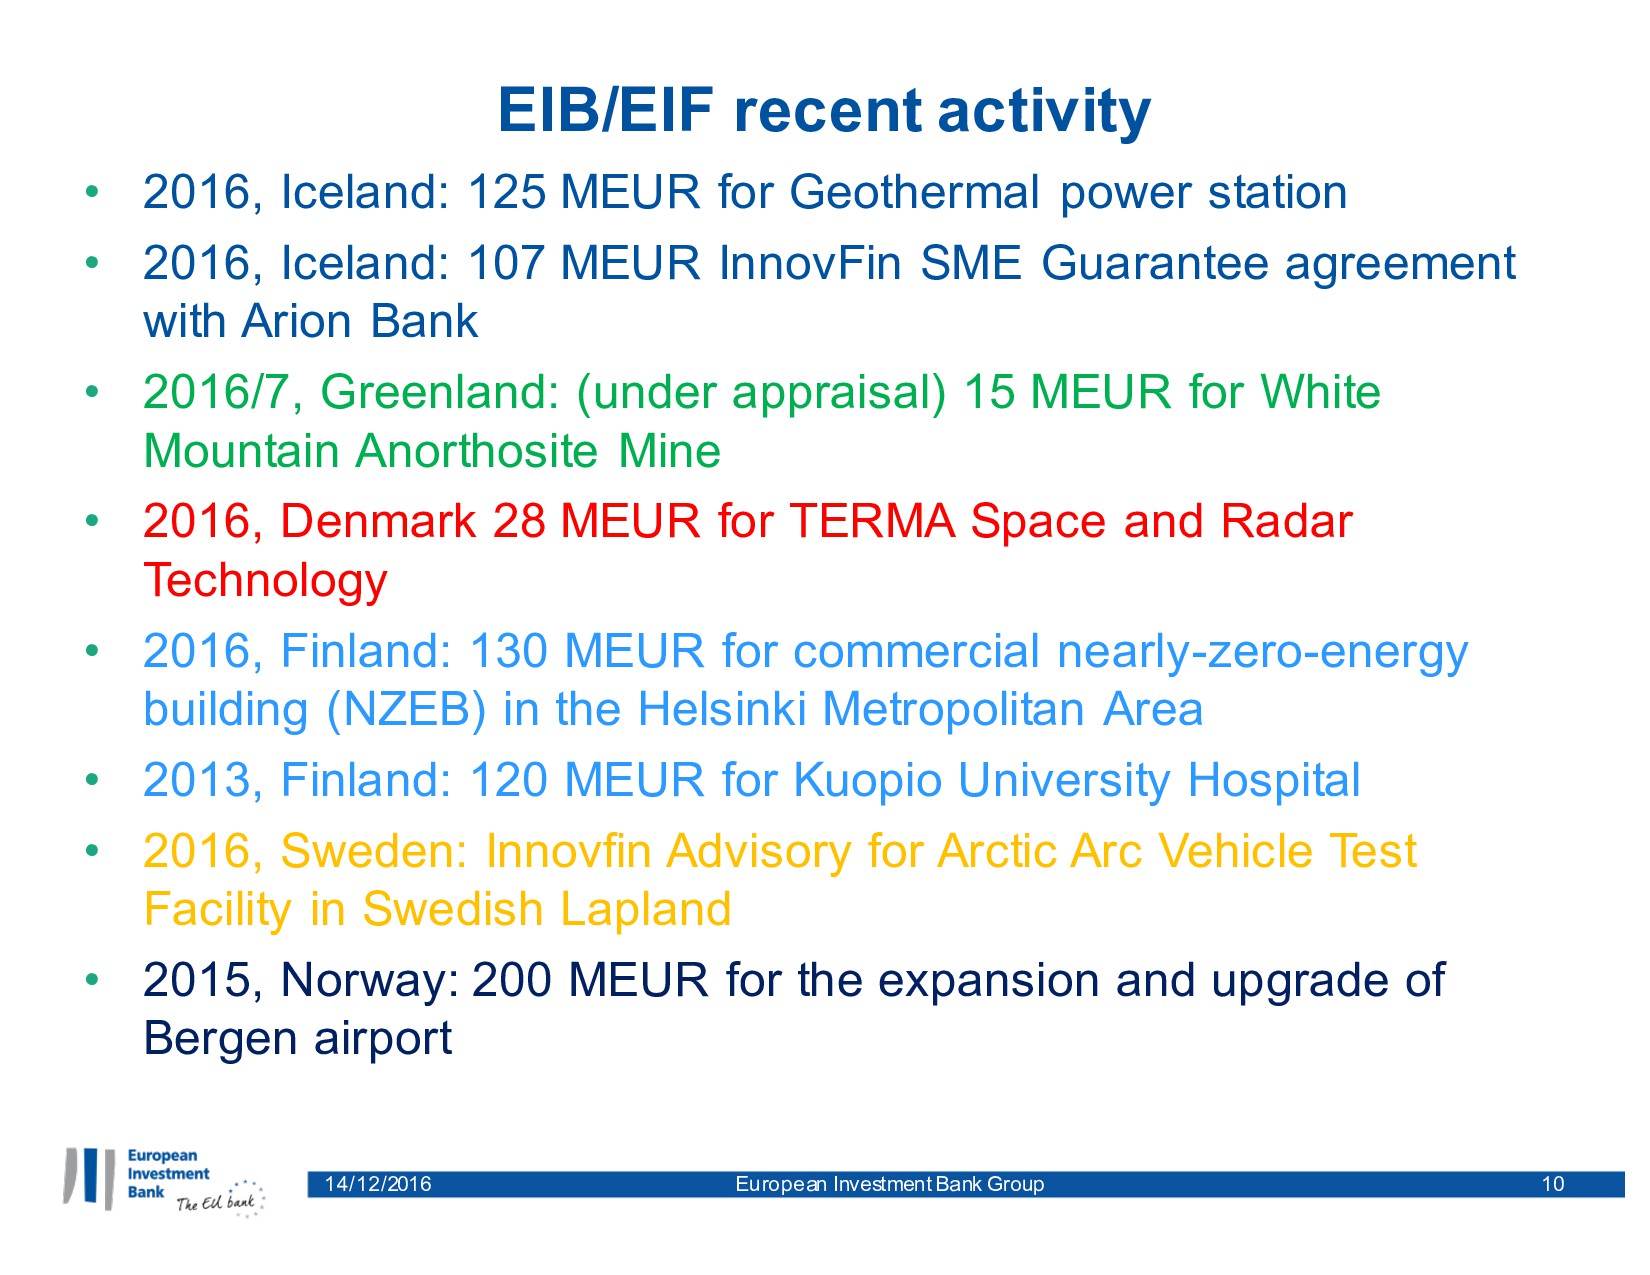
MEUR for Geothermal power station • 2016, Iceland: 107 MEUR InnovFin SME Guarantee agreement with Arion Bank • 2016/7, Greenland: (under appraisal) 15 MEUR for White Mountain Anorthosite Mine • 2016, Denmark 28 MEUR for TERMA Space and Radar Technology • 2016, Finland: 130 MEUR for commercial nearly-zero-energy building (NZEB) in the Helsinki Metropolitan Area • 2013, Finland: 120 MEUR for Kuopio University Hospital • 2016, Sweden: Innovfin Advisory for Arctic Arc Vehicle Test Facility in Swedish Lapland • 2015, Norway: 200 MEUR for the expansion and upgrade of Bergen airport EIB/EIF recent activity
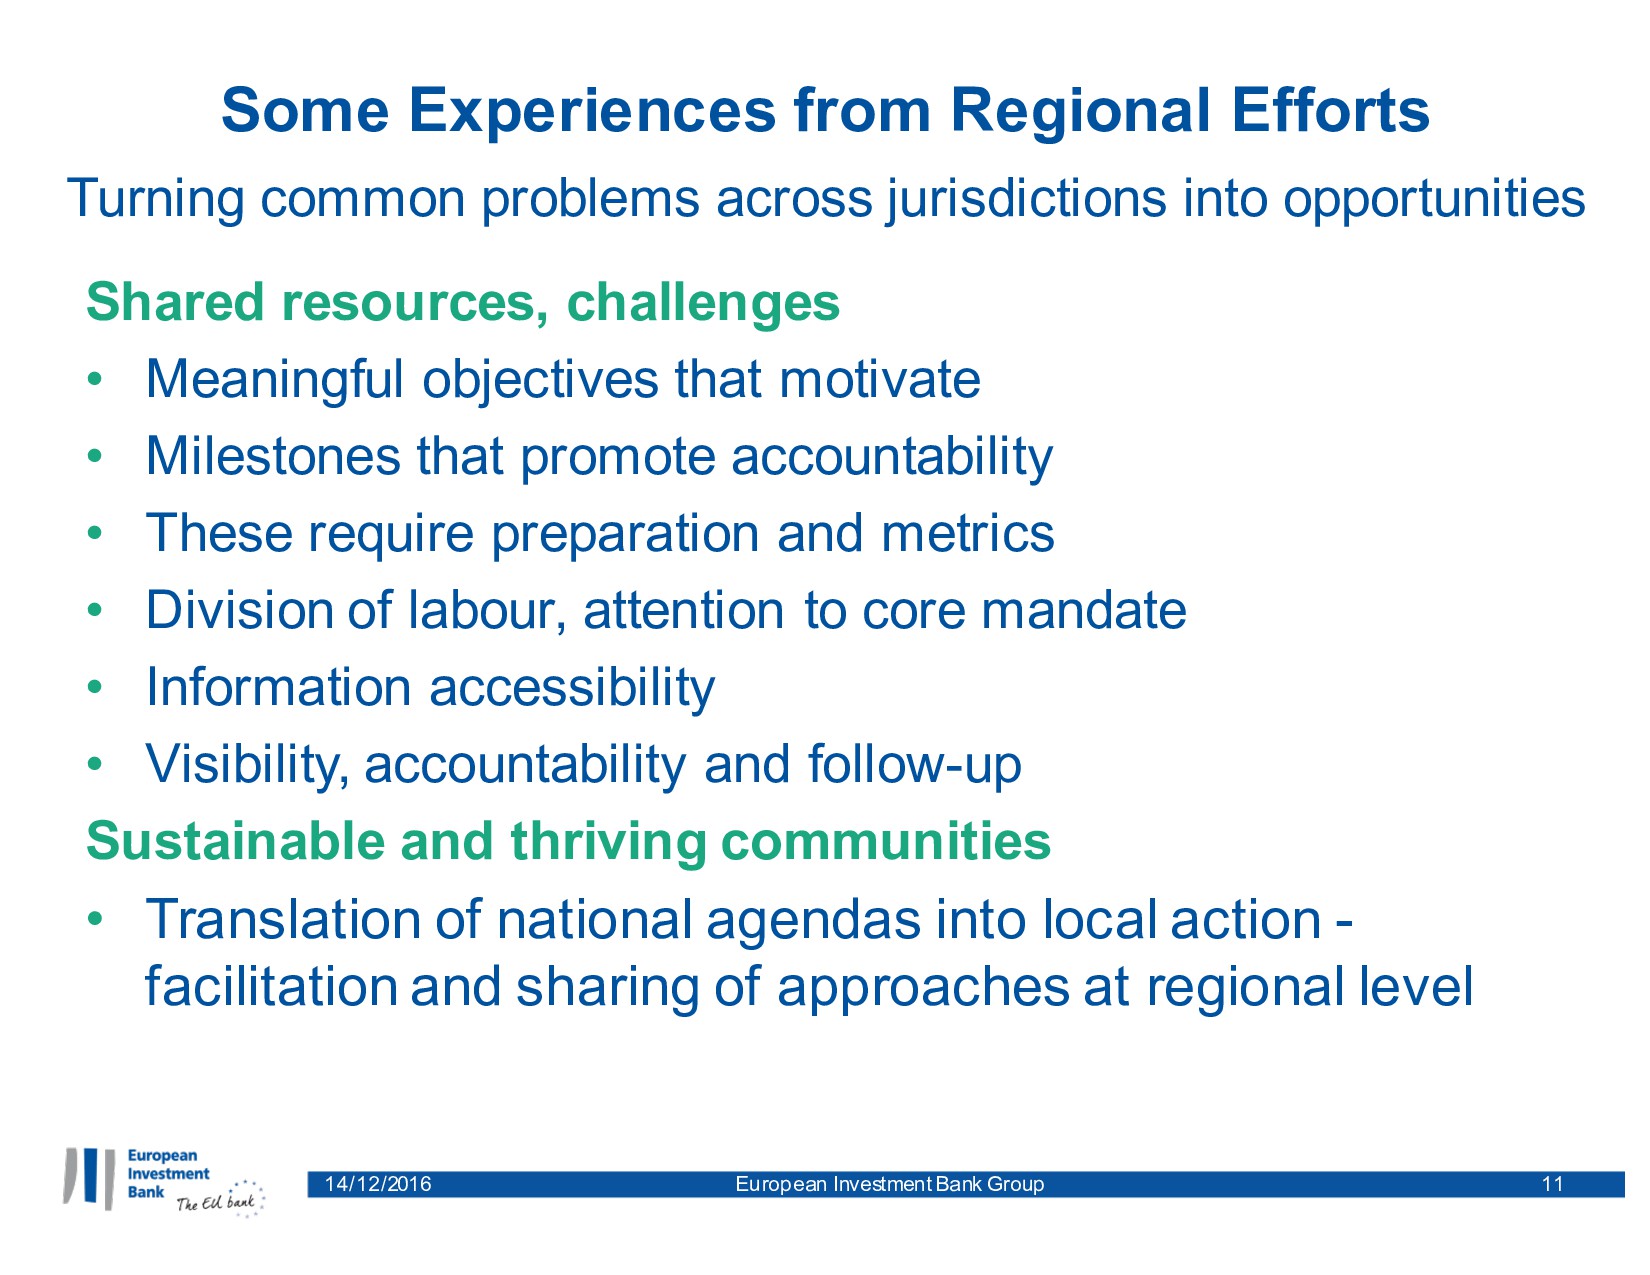
Efforts Turning common problems across jurisdictions into opportunities Shared resources, challenges • Meaningful objectives that motivate • Milestones that promote accountability • These require preparation and metrics • Division of labour, attention to core mandate • Information accessibility • Visibility, accountability and follow-up Sustainable and thriving communities • Translation of national agendas into local action - facilitation and sharing of approaches at regional level
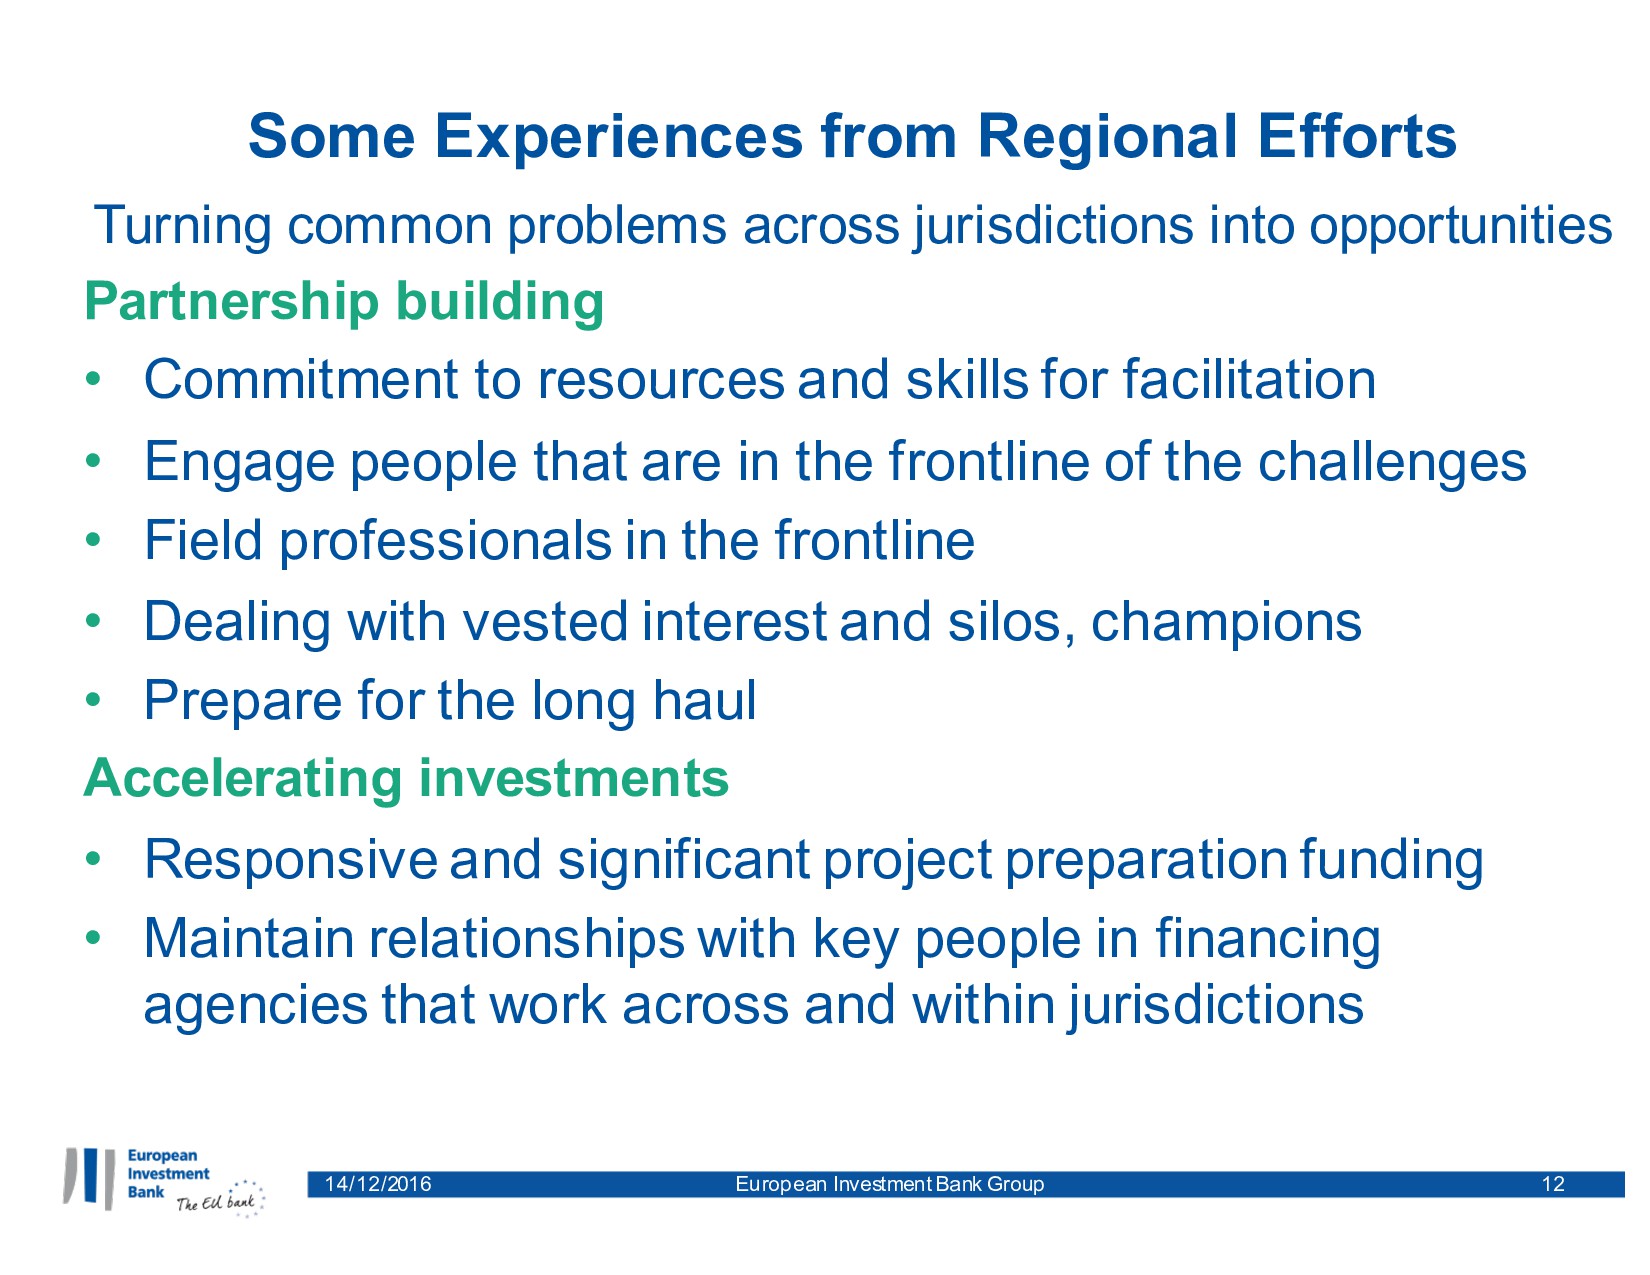
to resources and skills for facilitation • Engage people that are in the frontline of the challenges • Field professionals in the frontline • Dealing with vested interest and silos, champions • Prepare for the long haul Accelerating investments • Responsive and significant project preparation funding • Maintain relationships with key people in financing agencies that work across and within jurisdictions Some Experiences from Regional Efforts Turning common problems across jurisdictions into opportunities
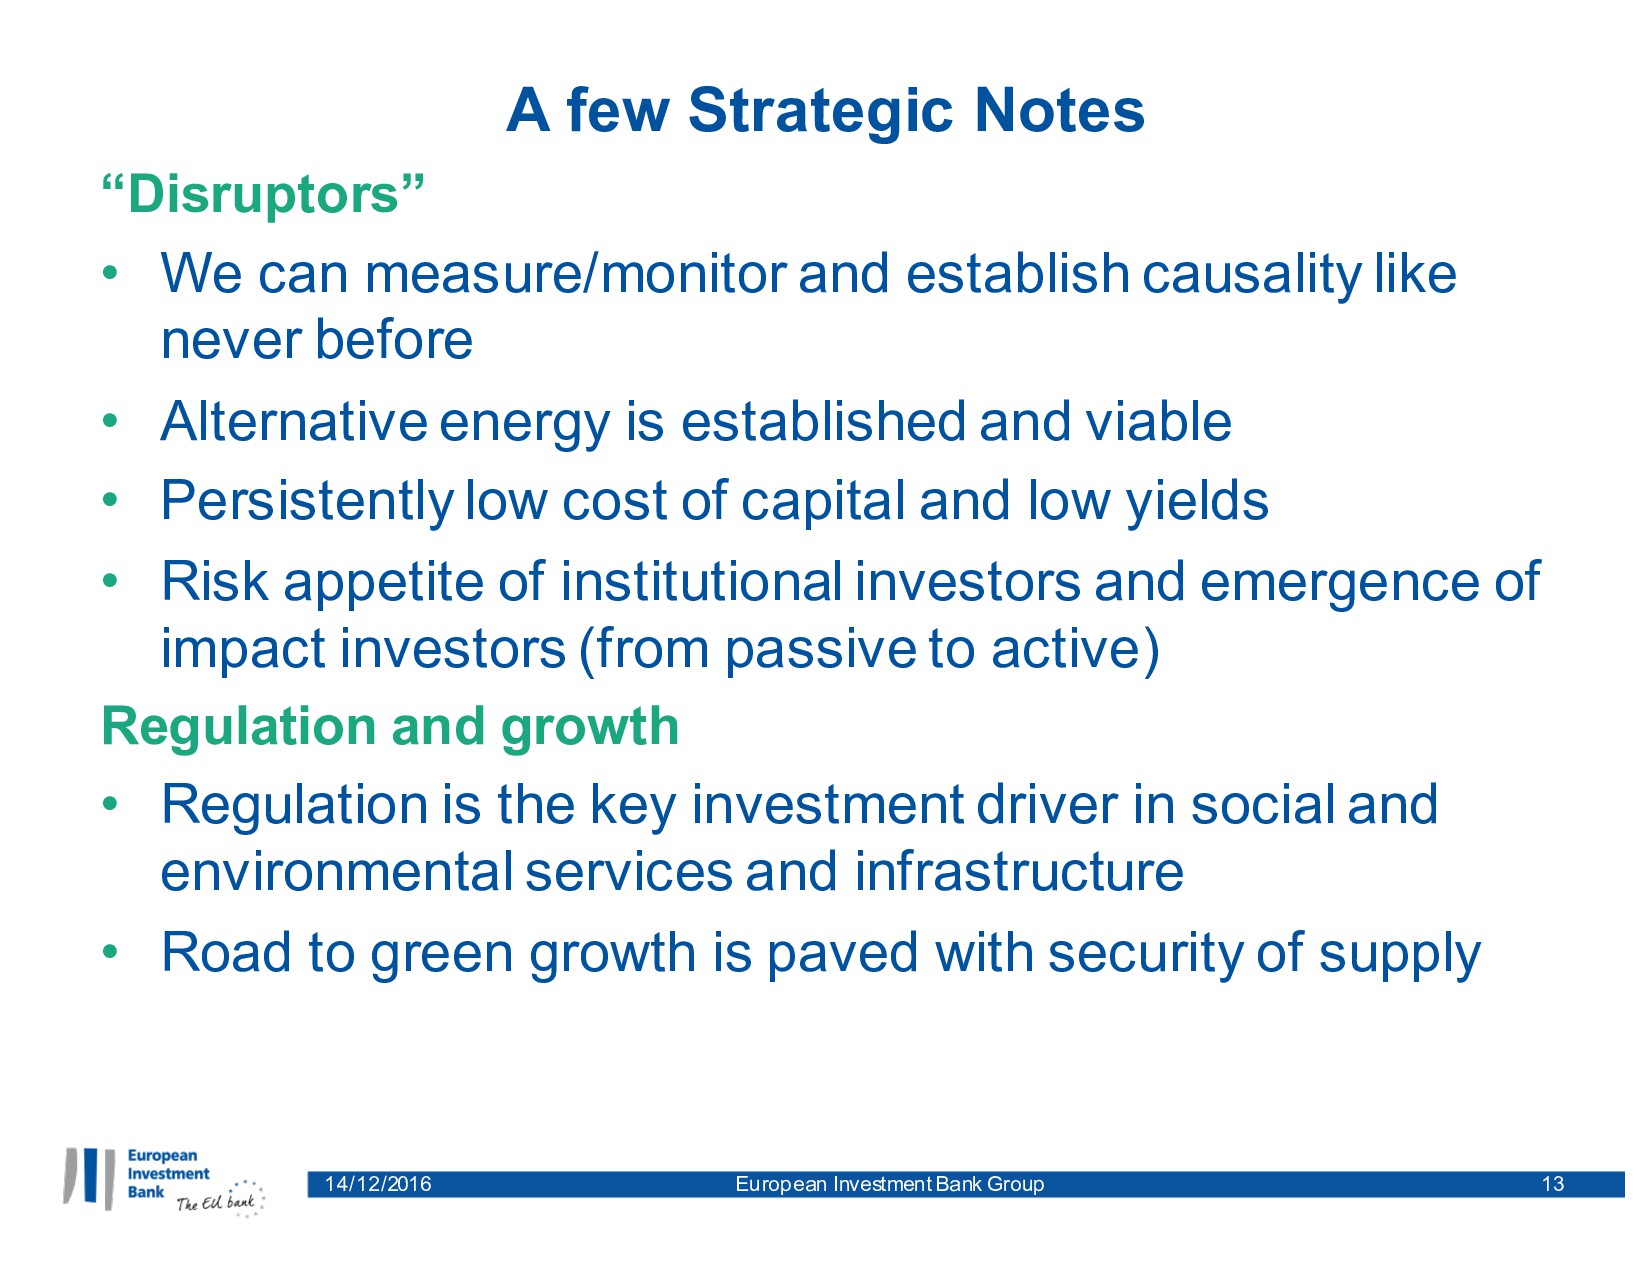
measure/monitor and establish causality like never before • Alternative energy is established and viable • Persistently low cost of capital and low yields • Risk appetite of institutional investors and emergence of impact investors (from passive to active) Regulation and growth • Regulation is the key investment driver in social and environmental services and infrastructure • Road to green growth is paved with security of supply A few Strategic Notes
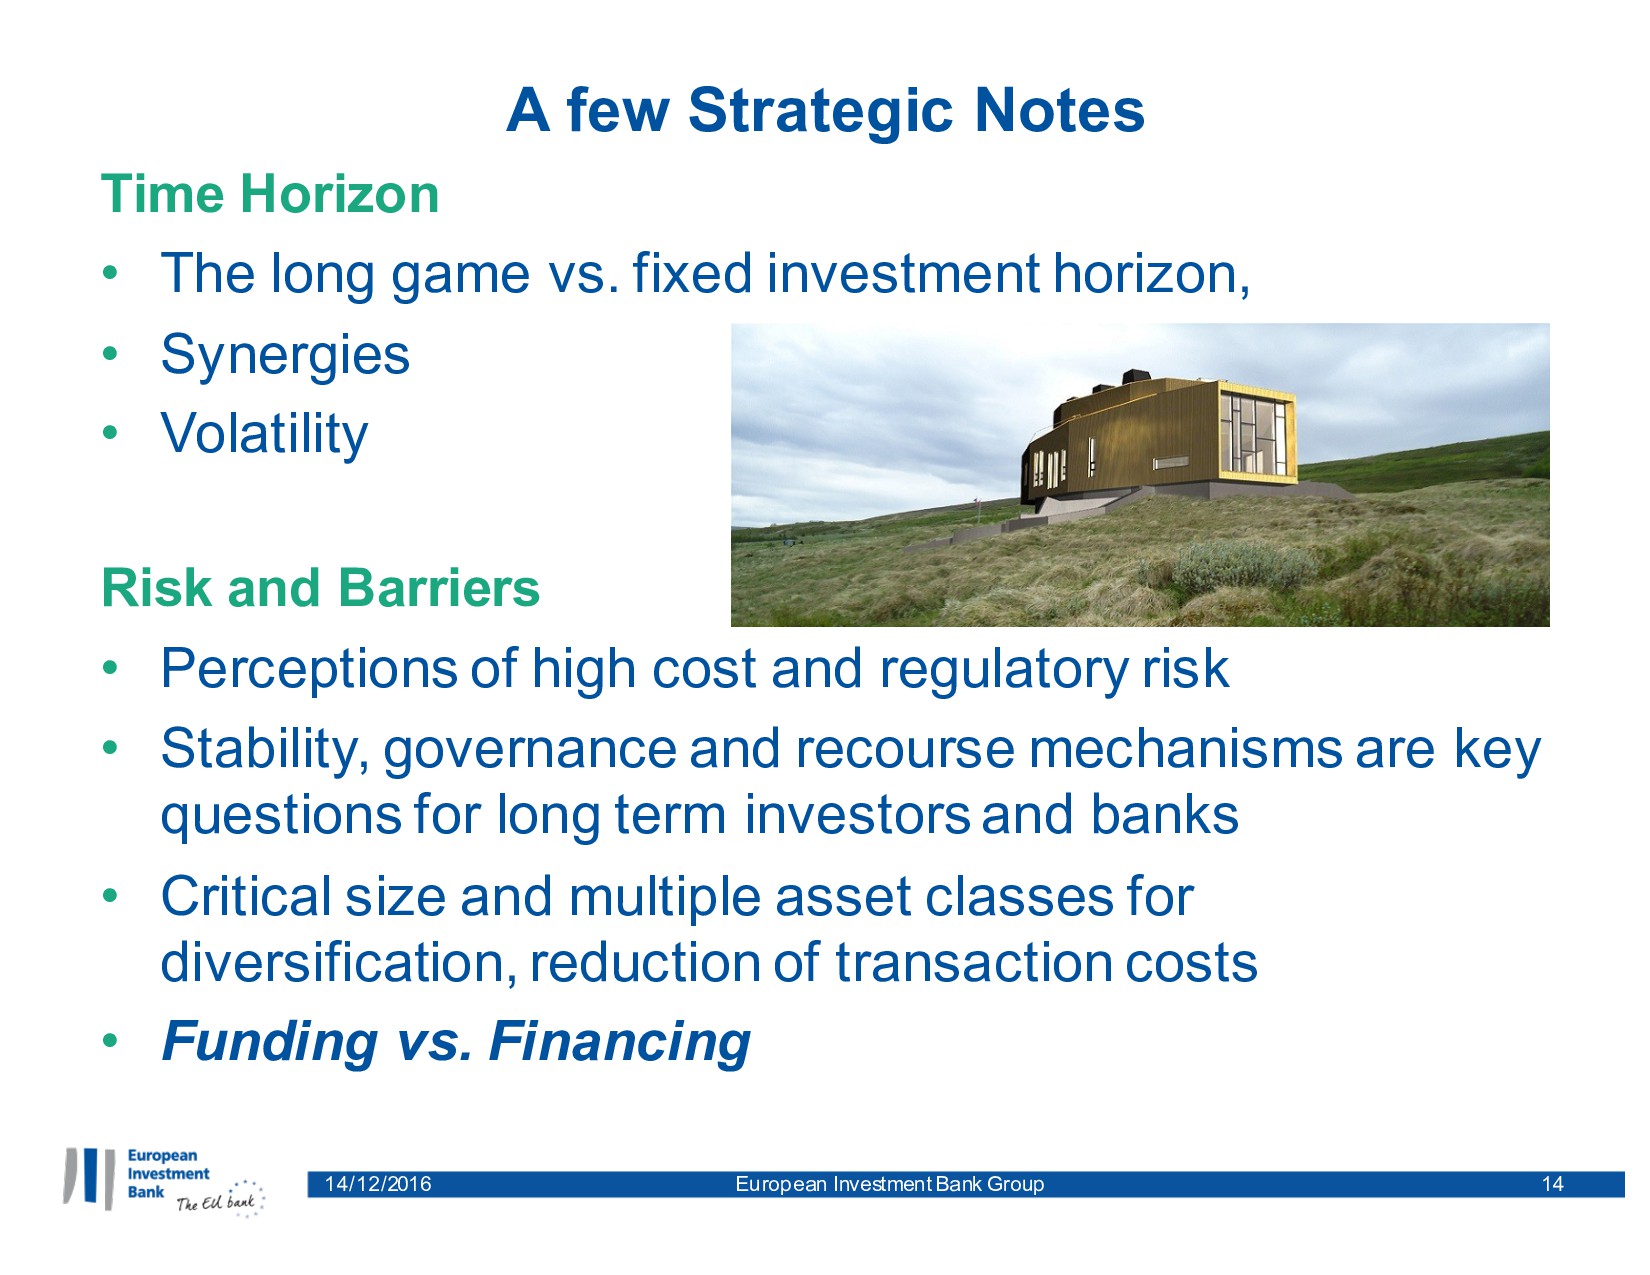
long game vs. fixed investment horizon, • Synergies • Volatility Risk and Barriers • Perceptions of high cost and regulatory risk • Stability, governance and recourse mechanisms are key questions for long term investors and banks • Critical size and multiple asset classes for diversification, reduction of transaction costs • Funding vs. Financing A few Strategic Notes
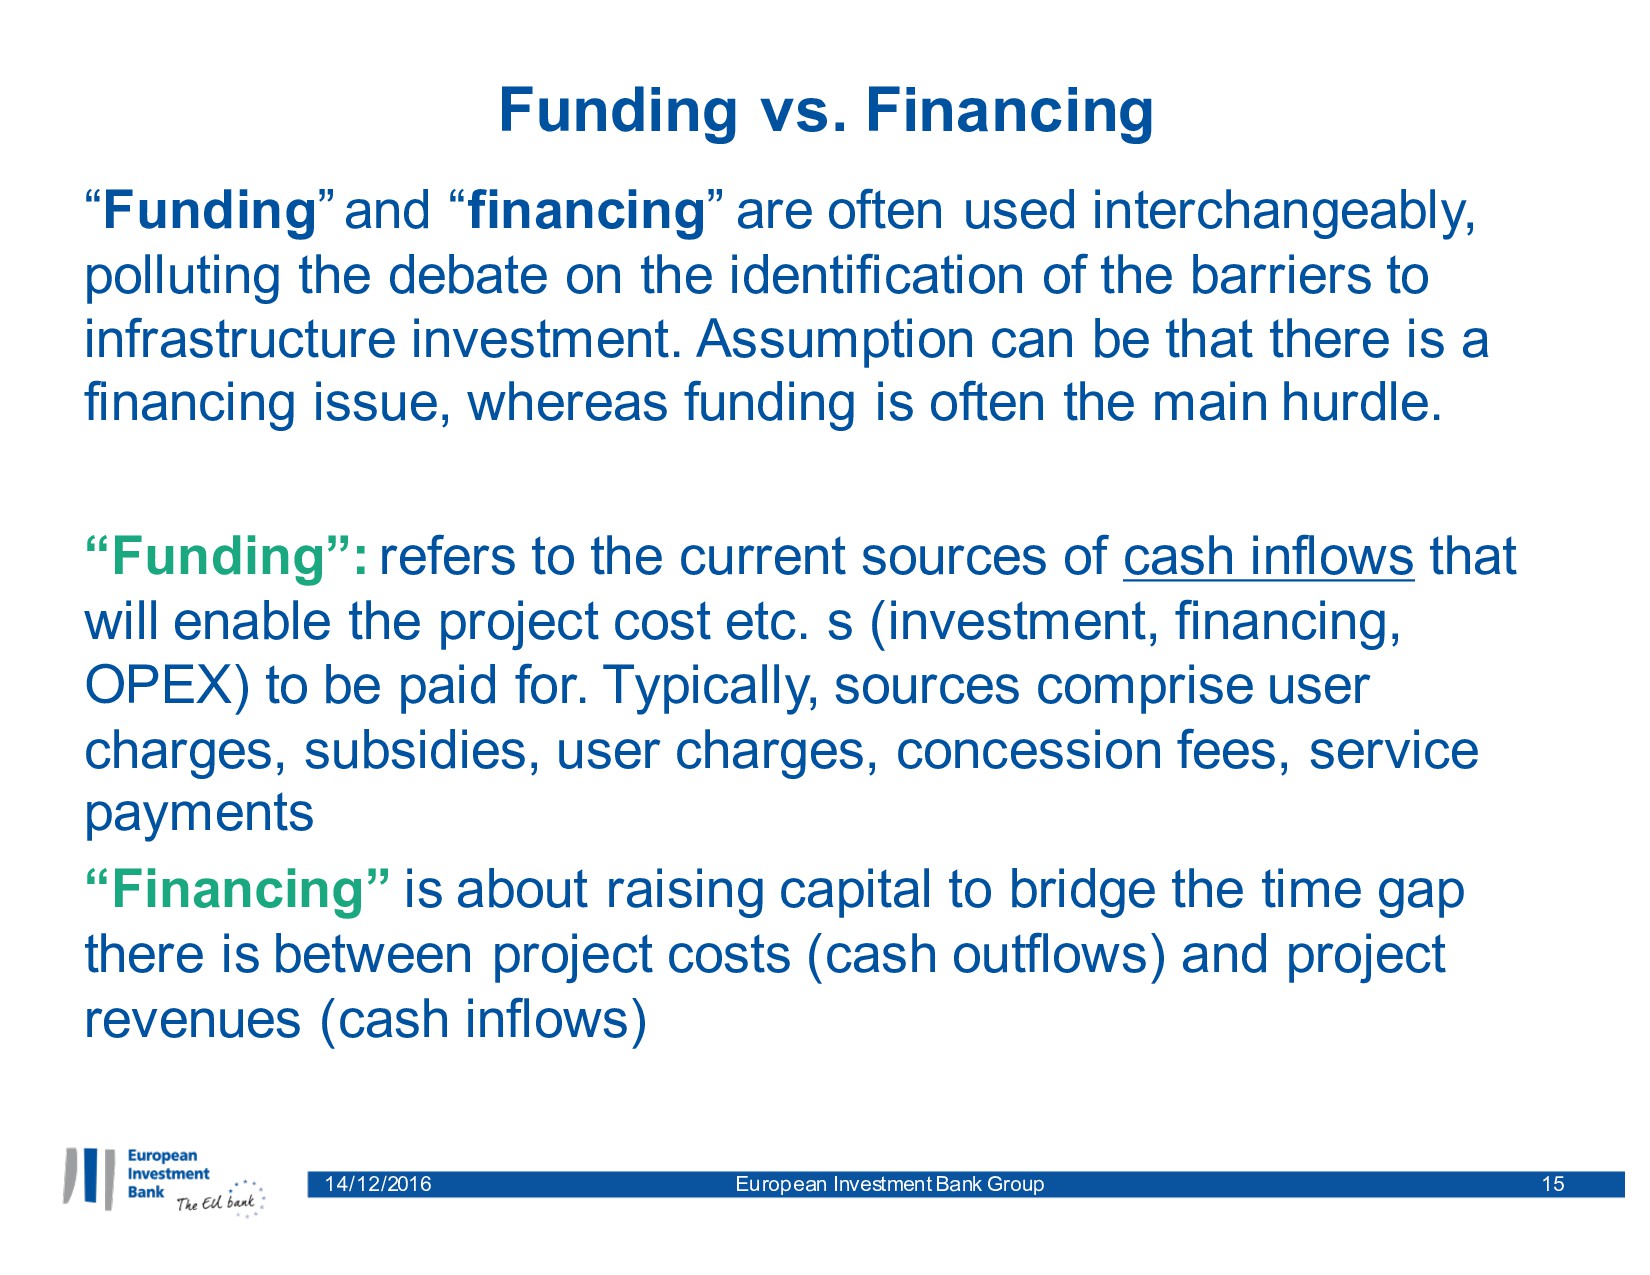
often used interchangeably, polluting the debate on the identification of the barriers to infrastructure investment. Assumption can be that there is a financing issue, whereas funding is often the main hurdle. “Funding”: refers to the current sources of cash inflows that will enable the project cost etc. s (investment, financing, OPEX) to be paid for. Typically, sources comprise user charges, subsidies, user charges, concession fees, service payments “Financing” is about raising capital to bridge the time gap there is between project costs (cash outflows) and project revenues (cash inflows) Funding vs. Financing
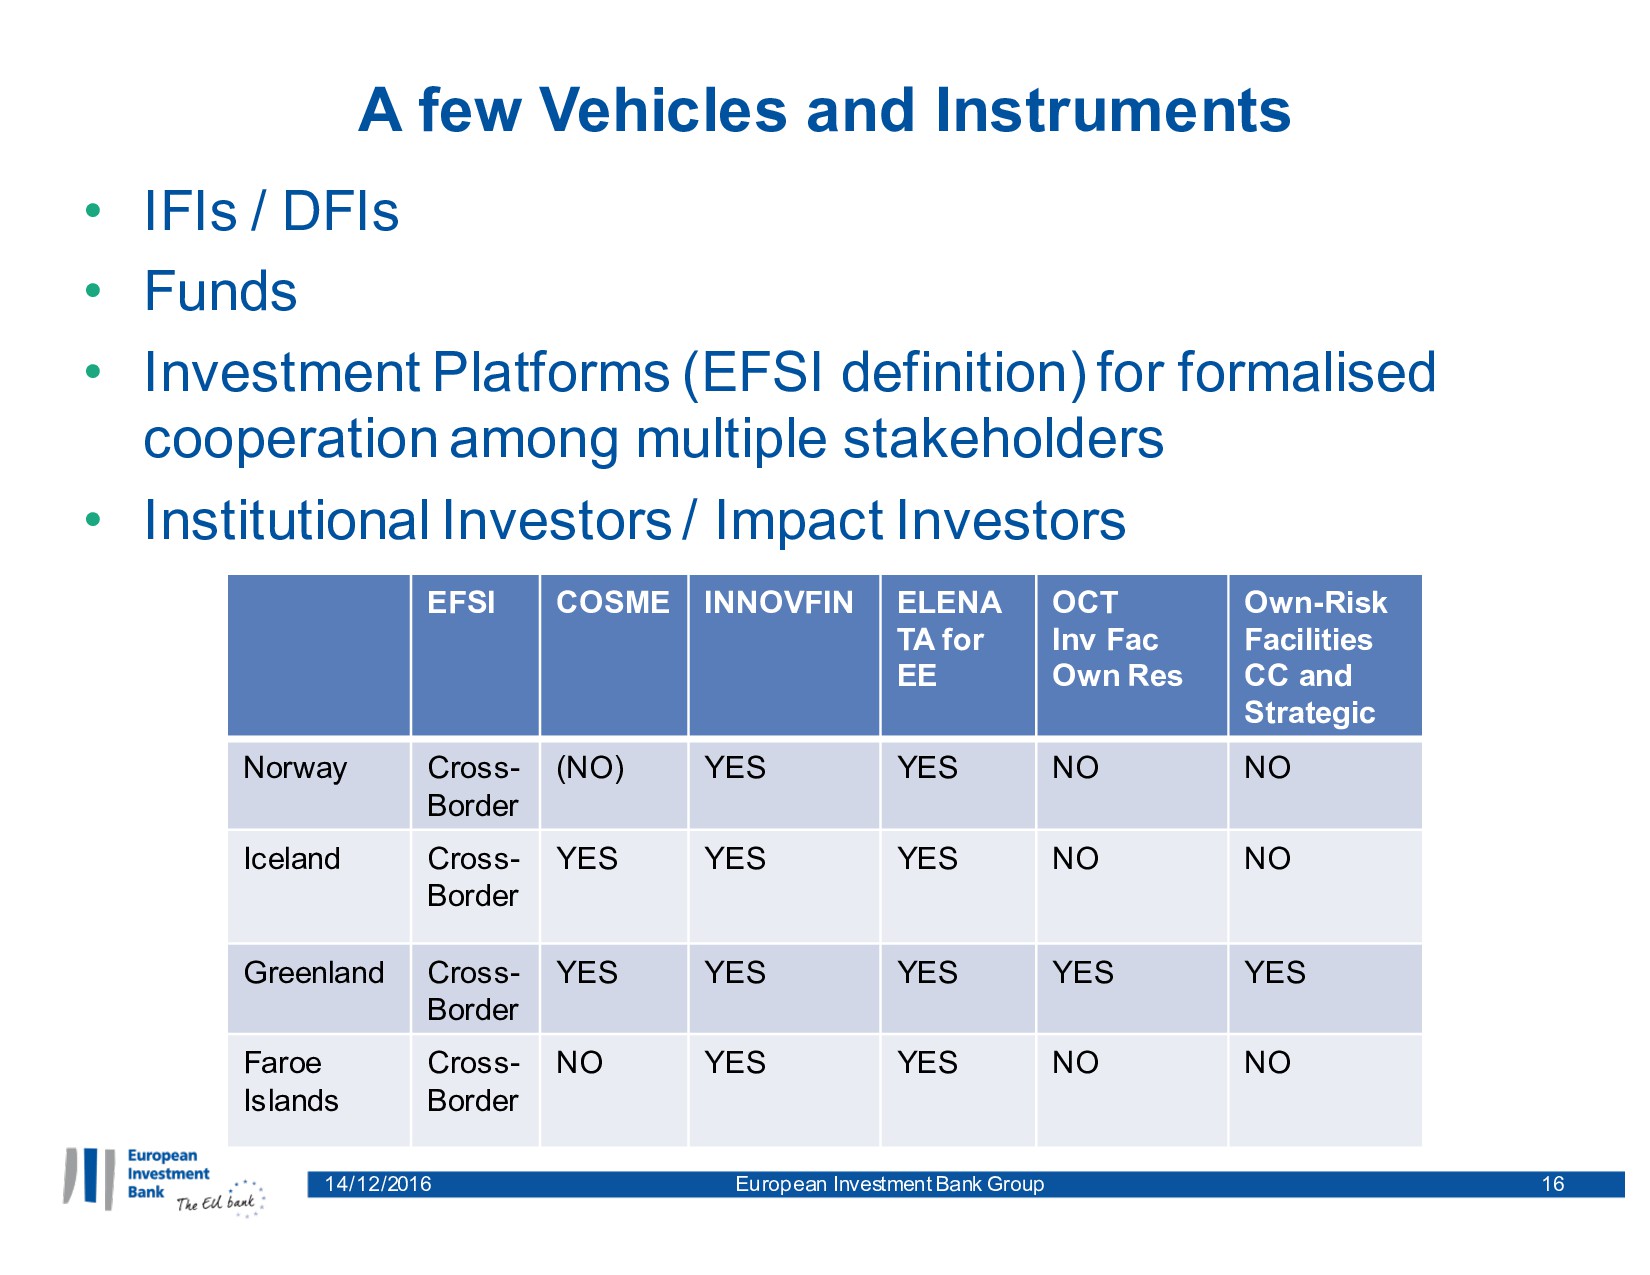
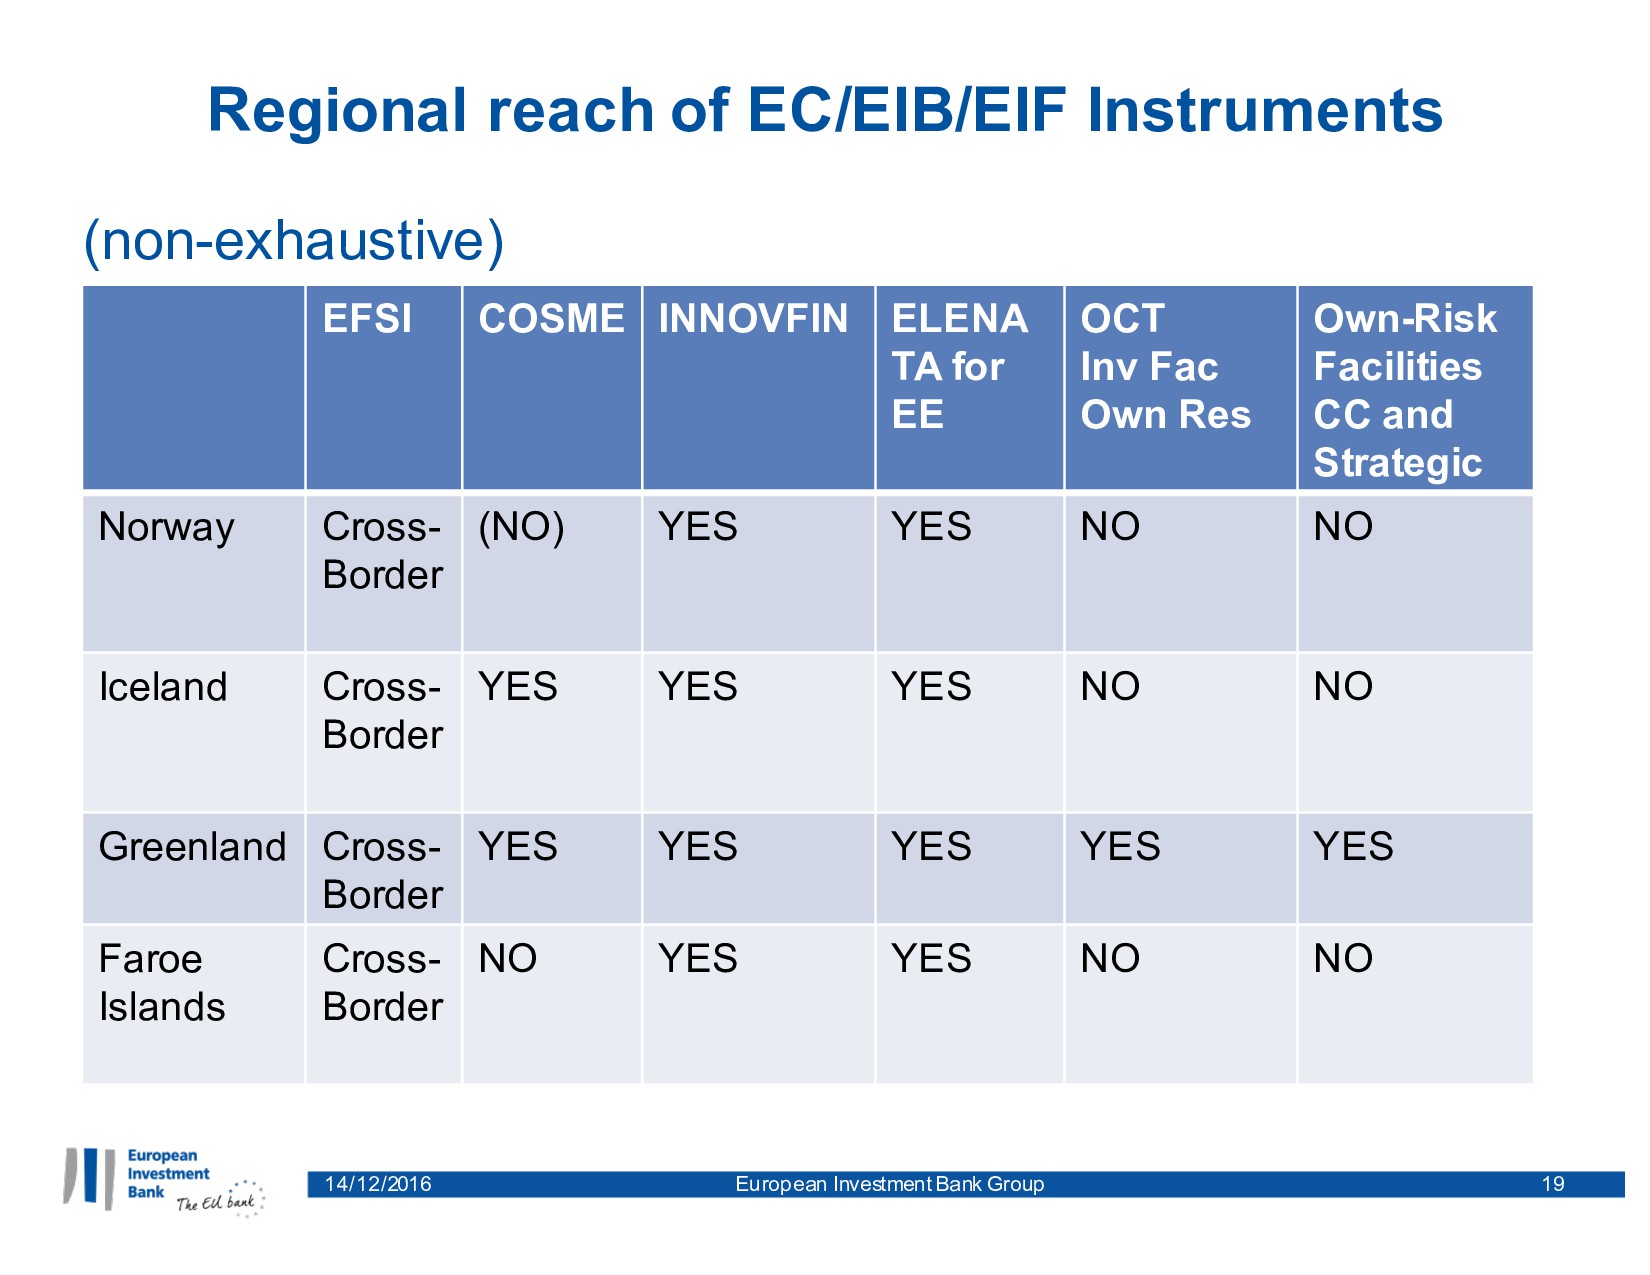
• Funds • Investment Platforms (EFSI definition) for formalised cooperation among multiple stakeholders • Institutional Investors / Impact Investors A few Vehicles and Instruments EFSI COSME INNOVFIN ELENA TA for EE OCT Inv Fac Own Res Own-Risk Facilities CC and Strategic Norway Cross- Border (NO) YES YES NO NO Iceland Cross- Border YES YES YES NO NO Greenland Cross- Border YES YES YES YES YES Faroe Islands Cross- Border NO YES YES NO NO
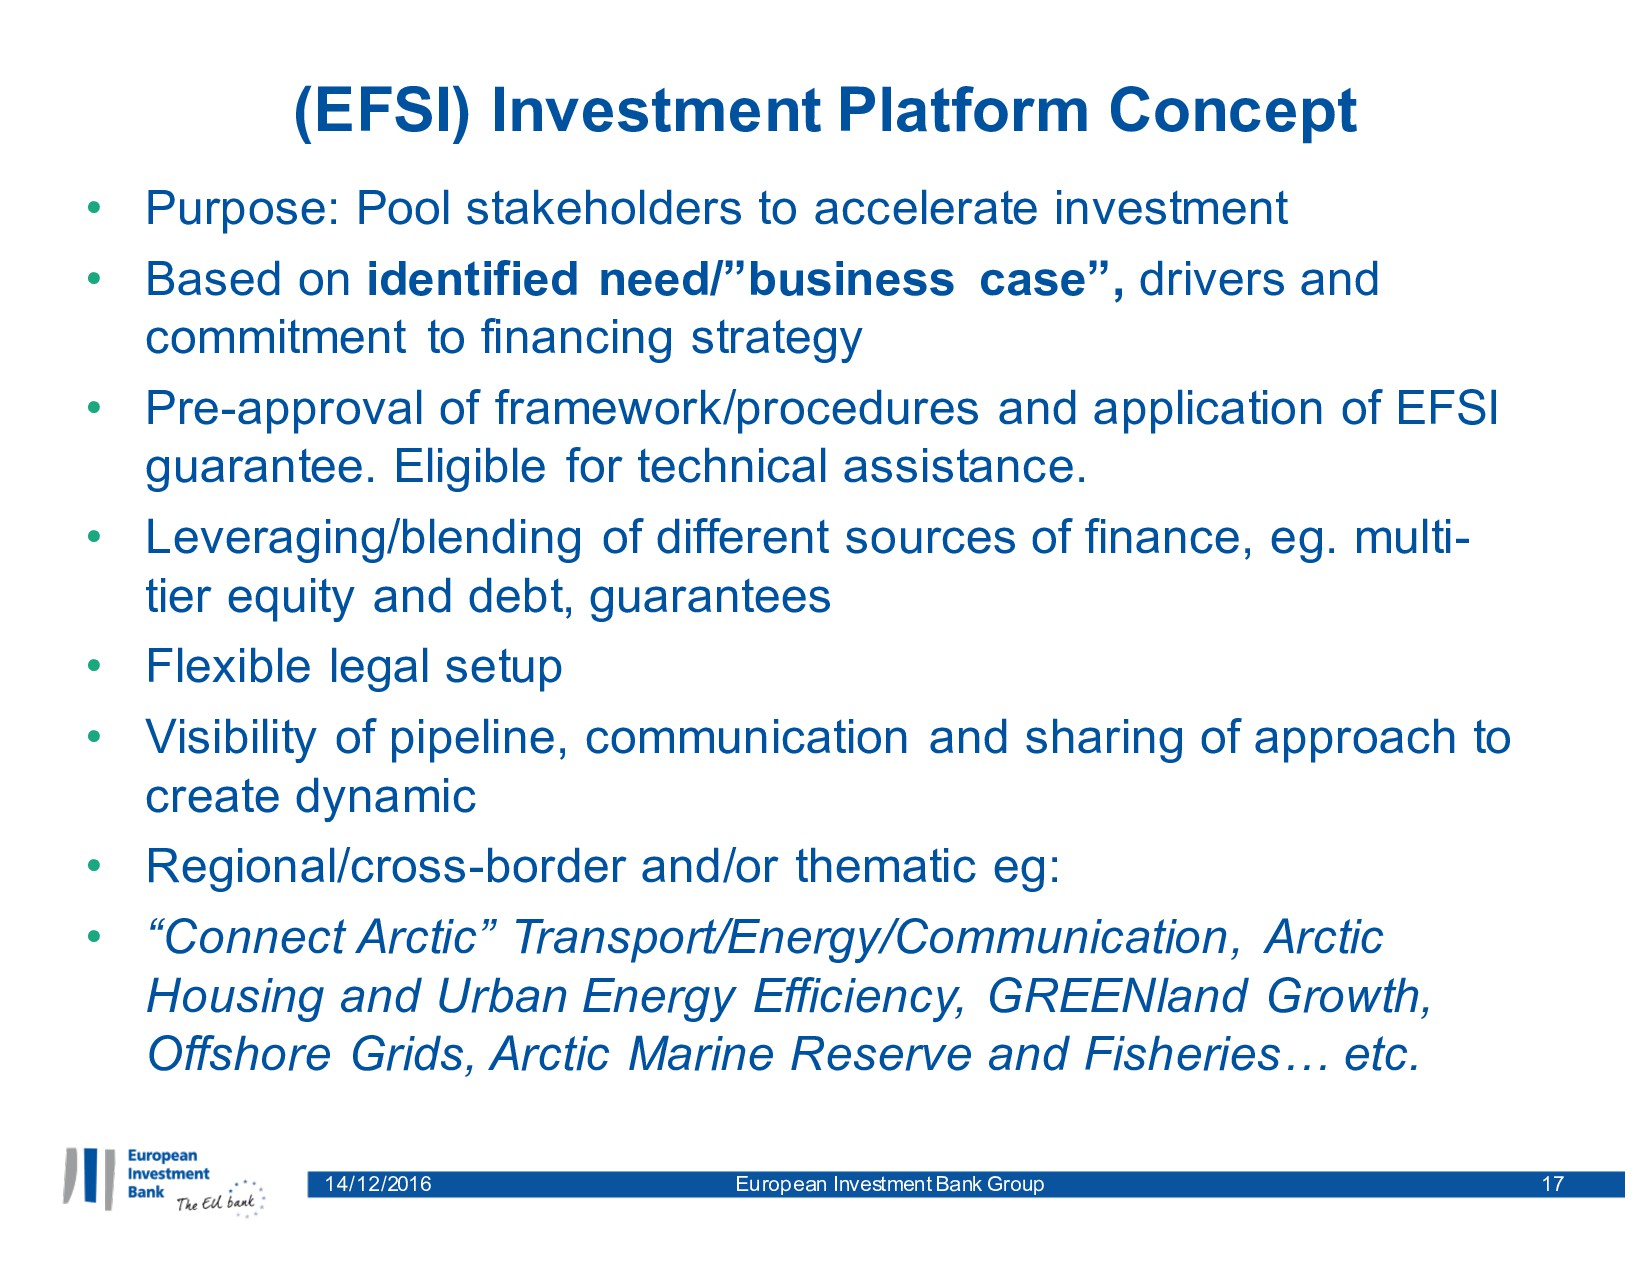
to accelerate investment • Based on identified need/”business case”, drivers and commitment to financing strategy • Pre-approval of framework/procedures and application of EFSI guarantee. Eligible for technical assistance. • Leveraging/blending of different sources of finance, eg. multi- tier equity and debt, guarantees • Flexible legal setup • Visibility of pipeline, communication and sharing of approach to create dynamic • Regional/cross-border and/or thematic eg: • “Connect Arctic” Transport/Energy/Communication, Arctic Housing and Urban Energy Efficiency, GREENland Growth, Offshore Grids, Arctic Marine Reserve and Fisheries… etc. (EFSI) Investment Platform Concept
EC/EIB/EIF Instruments EFSI COSME INNOVFIN ELENA TA for EE OCT Inv Fac Own Res Own-Risk Facilities CC and Strategic Norway Cross- Border (NO) YES YES NO NO Iceland Cross- Border YES YES YES NO NO Greenland Cross- Border YES YES YES YES YES Faroe Islands Cross- Border NO YES YES NO NO


 ipfbrussels
 schlessera
 rabernat
 danielanewman
 keathley
 jlugia
 maggiecrowley
 szymonslowik
 kneath
 shlominoach
 jonoalderson
 aleyda
 samanthasiow