Upgrade to Pro — share decks privately, control downloads, hide ads and more …

CNP

Avatar for Levin Easterly Levin Easterly
August 26, 2020
15

 CNP

Avatar for Levin Easterly

Levin Easterly

August 26, 2020

Transcript

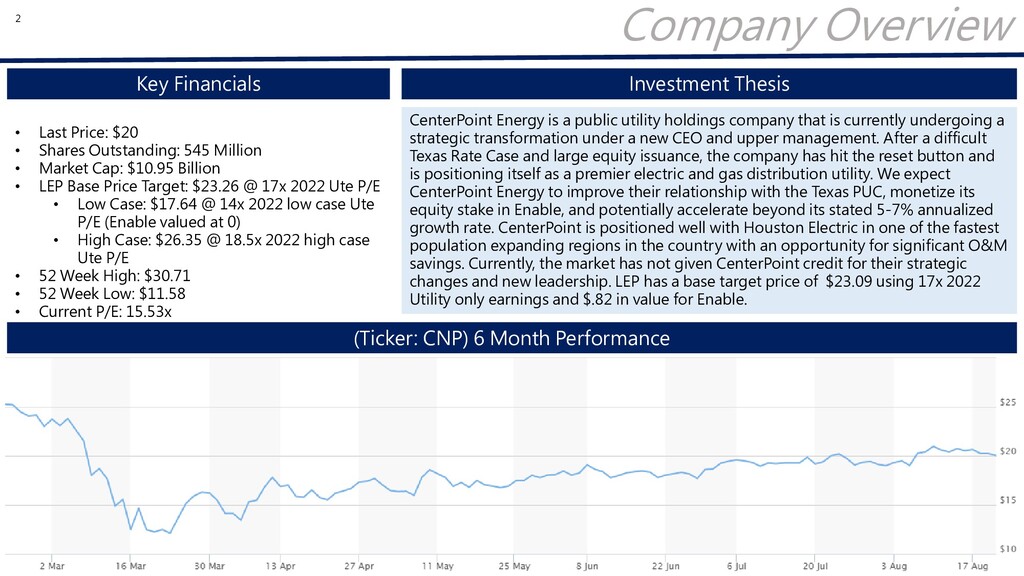
  1. Company Overview Key Financials Investment Thesis (Ticker: CNP) 6 Month

    Performance • Last Price: $20 • Shares Outstanding: 545 Million • Market Cap: $10.95 Billion • LEP Base Price Target: $23.26 @ 17x 2022 Ute P/E • Low Case: $17.64 @ 14x 2022 low case Ute P/E (Enable valued at 0) • High Case: $26.35 @ 18.5x 2022 high case Ute P/E • 52 Week High: $30.71 • 52 Week Low: $11.58 • Current P/E: 15.53x CenterPoint Energy is a public utility holdings company that is currently undergoing a strategic transformation under a new CEO and upper management. After a difficult Texas Rate Case and large equity issuance, the company has hit the reset button and is positioning itself as a premier electric and gas distribution utility. We expect CenterPoint Energy to improve their relationship with the Texas PUC, monetize its equity stake in Enable, and potentially accelerate beyond its stated 5-7% annualized growth rate. CenterPoint is positioned well with Houston Electric in one of the fastest population expanding regions in the country with an opportunity for significant O&M savings. Currently, the market has not given CenterPoint credit for their strategic changes and new leadership. LEP has a base target price of $23.09 using 17x 2022 Utility only earnings and $.82 in value for Enable. 2
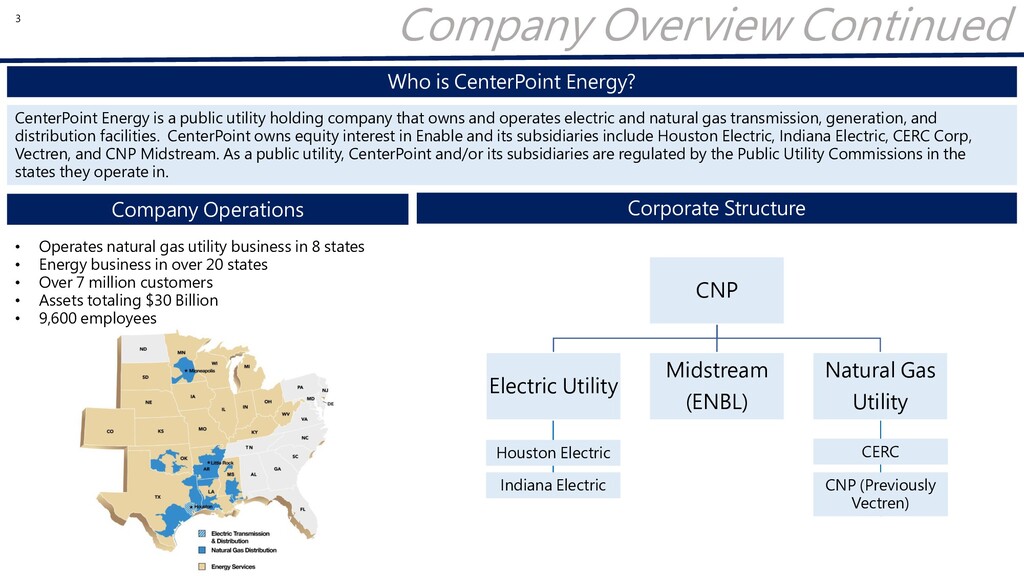
  2. Company Overview Continued Company Operations Corporate Structure Who is CenterPoint

    Energy? CenterPoint Energy is a public utility holding company that owns and operates electric and natural gas transmission, generation, and distribution facilities. CenterPoint owns equity interest in Enable and its subsidiaries include Houston Electric, Indiana Electric, CERC Corp, Vectren, and CNP Midstream. As a public utility, CenterPoint and/or its subsidiaries are regulated by the Public Utility Commissions in the states they operate in. • Operates natural gas utility business in 8 states • Energy business in over 20 states • Over 7 million customers • Assets totaling $30 Billion • 9,600 employees CNP Electric Utility Midstream (ENBL) Natural Gas Utility Houston Electric Indiana Electric CERC CNP (Previously Vectren) 3
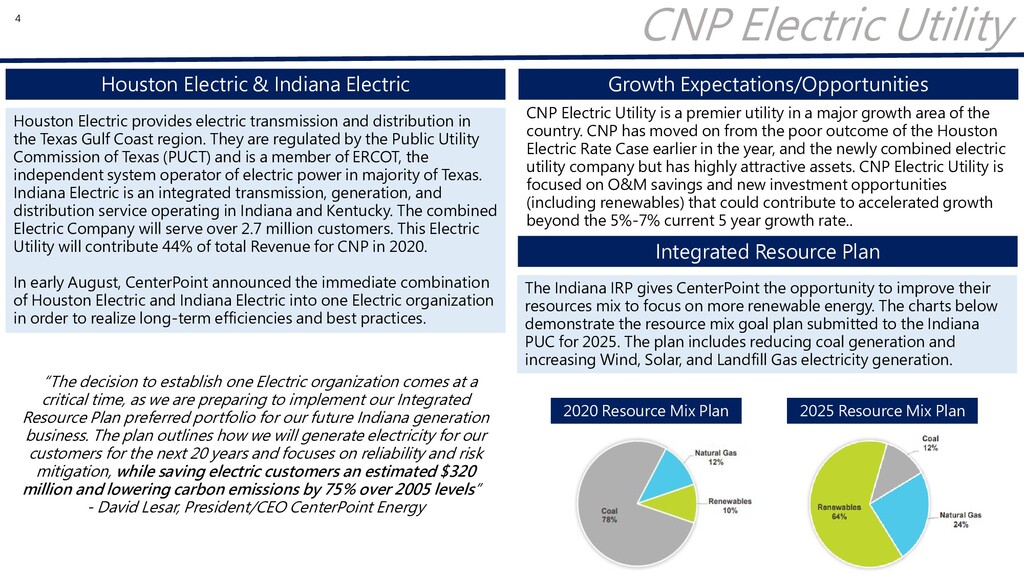
  3. CNP Electric Utility Houston Electric & Indiana Electric Houston Electric

    provides electric transmission and distribution in the Texas Gulf Coast region. They are regulated by the Public Utility Commission of Texas (PUCT) and is a member of ERCOT, the independent system operator of electric power in majority of Texas. Indiana Electric is an integrated transmission, generation, and distribution service operating in Indiana and Kentucky. The combined Electric Company will serve over 2.7 million customers. This Electric Utility will contribute 44% of total Revenue for CNP in 2020. In early August, CenterPoint announced the immediate combination of Houston Electric and Indiana Electric into one Electric organization in order to realize long-term efficiencies and best practices. “The decision to establish one Electric organization comes at a critical time, as we are preparing to implement our Integrated Resource Plan preferred portfolio for our future Indiana generation business. The plan outlines how we will generate electricity for our customers for the next 20 years and focuses on reliability and risk mitigation, while saving electric customers an estimated $320 million and lowering carbon emissions by 75% over 2005 levels” - David Lesar, President/CEO CenterPoint Energy Growth Expectations/Opportunities CNP Electric Utility is a premier utility in a major growth area of the country. CNP has moved on from the poor outcome of the Houston Electric Rate Case earlier in the year, and the newly combined electric utility company but has highly attractive assets. CNP Electric Utility is focused on O&M savings and new investment opportunities (including renewables) that could contribute to accelerated growth beyond the 5%-7% current 5 year growth rate.. Integrated Resource Plan The Indiana IRP gives CenterPoint the opportunity to improve their resources mix to focus on more renewable energy. The charts below demonstrate the resource mix goal plan submitted to the Indiana PUC for 2025. The plan includes reducing coal generation and increasing Wind, Solar, and Landfill Gas electricity generation. 2020 Resource Mix Plan 2025 Resource Mix Plan 4
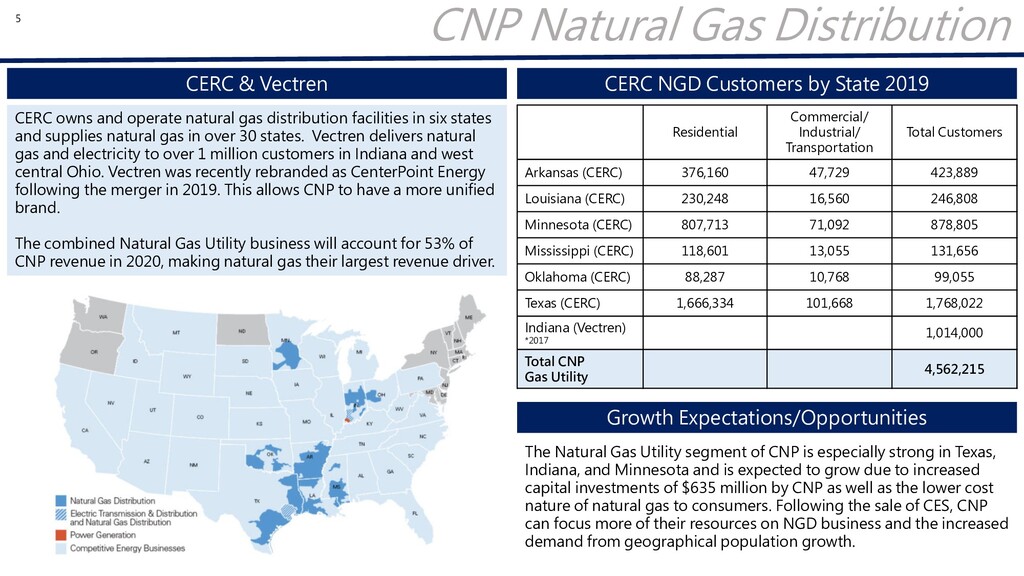
  4. CNP Natural Gas Distribution CERC & Vectren CERC owns and

    operate natural gas distribution facilities in six states and supplies natural gas in over 30 states. Vectren delivers natural gas and electricity to over 1 million customers in Indiana and west central Ohio. Vectren was recently rebranded as CenterPoint Energy following the merger in 2019. This allows CNP to have a more unified brand. The combined Natural Gas Utility business will account for 53% of CNP revenue in 2020, making natural gas their largest revenue driver. CERC NGD Customers by State 2019 Residential Commercial/ Industrial/ Transportation Total Customers Arkansas (CERC) 376,160 47,729 423,889 Louisiana (CERC) 230,248 16,560 246,808 Minnesota (CERC) 807,713 71,092 878,805 Mississippi (CERC) 118,601 13,055 131,656 Oklahoma (CERC) 88,287 10,768 99,055 Texas (CERC) 1,666,334 101,668 1,768,022 Indiana (Vectren) *2017 1,014,000 Total CNP Gas Utility 4,562,215 Growth Expectations/Opportunities The Natural Gas Utility segment of CNP is especially strong in Texas, Indiana, and Minnesota and is expected to grow due to increased capital investments of $635 million by CNP as well as the lower cost nature of natural gas to consumers. Following the sale of CES, CNP can focus more of their resources on NGD business and the increased demand from geographical population growth. 5
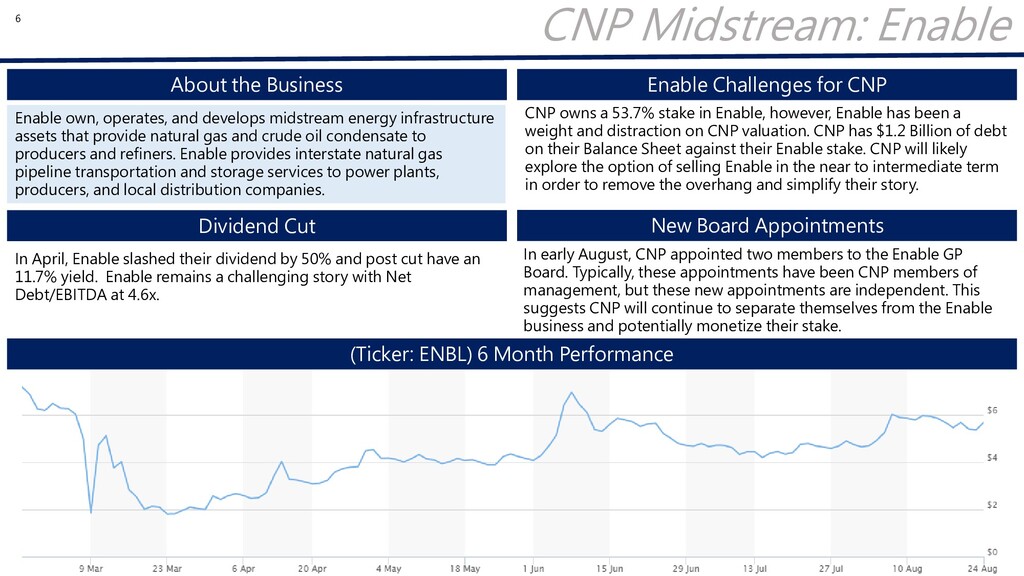
  5. CNP Midstream: Enable About the Business Enable Challenges for CNP

    Enable own, operates, and develops midstream energy infrastructure assets that provide natural gas and crude oil condensate to producers and refiners. Enable provides interstate natural gas pipeline transportation and storage services to power plants, producers, and local distribution companies. CNP owns a 53.7% stake in Enable, however, Enable has been a weight and distraction on CNP valuation. CNP has $1.2 Billion of debt on their Balance Sheet against their Enable stake. CNP will likely explore the option of selling Enable in the near to intermediate term in order to remove the overhang and simplify their story. (Ticker: ENBL) 6 Month Performance Dividend Cut In April, Enable slashed their dividend by 50% and post cut have an 11.7% yield. Enable remains a challenging story with Net Debt/EBITDA at 4.6x. New Board Appointments In early August, CNP appointed two members to the Enable GP Board. Typically, these appointments have been CNP members of management, but these new appointments are independent. This suggests CNP will continue to separate themselves from the Enable business and potentially monetize their stake. 6
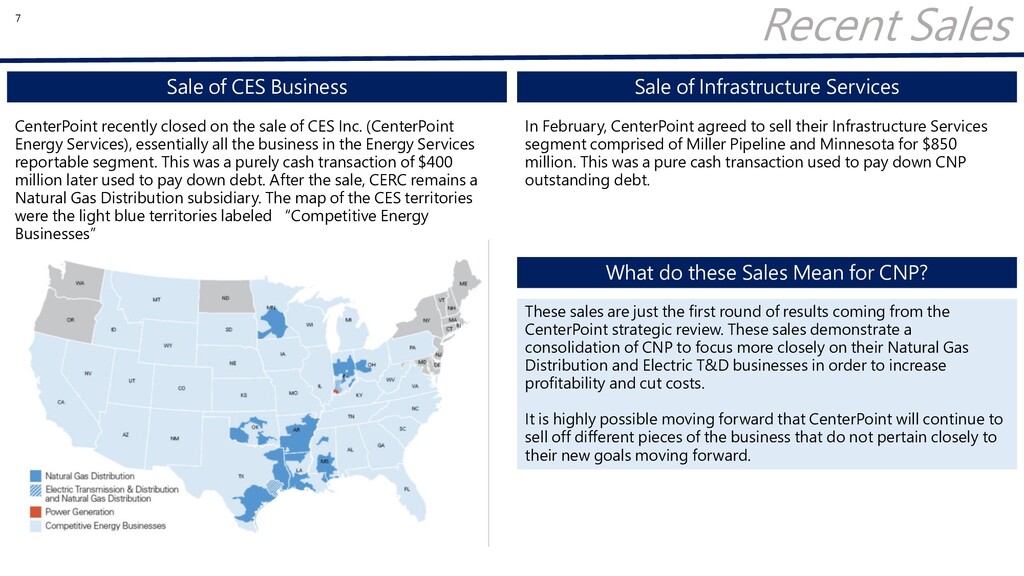
  6. Recent Sales Sale of CES Business CenterPoint recently closed on

    the sale of CES Inc. (CenterPoint Energy Services), essentially all the business in the Energy Services reportable segment. This was a purely cash transaction of $400 million later used to pay down debt. After the sale, CERC remains a Natural Gas Distribution subsidiary. The map of the CES territories were the light blue territories labeled “Competitive Energy Businesses” Sale of Infrastructure Services In February, CenterPoint agreed to sell their Infrastructure Services segment comprised of Miller Pipeline and Minnesota for $850 million. This was a pure cash transaction used to pay down CNP outstanding debt. What do these Sales Mean for CNP? These sales are just the first round of results coming from the CenterPoint strategic review. These sales demonstrate a consolidation of CNP to focus more closely on their Natural Gas Distribution and Electric T&D businesses in order to increase profitability and cut costs. It is highly possible moving forward that CenterPoint will continue to sell off different pieces of the business that do not pertain closely to their new goals moving forward. 7
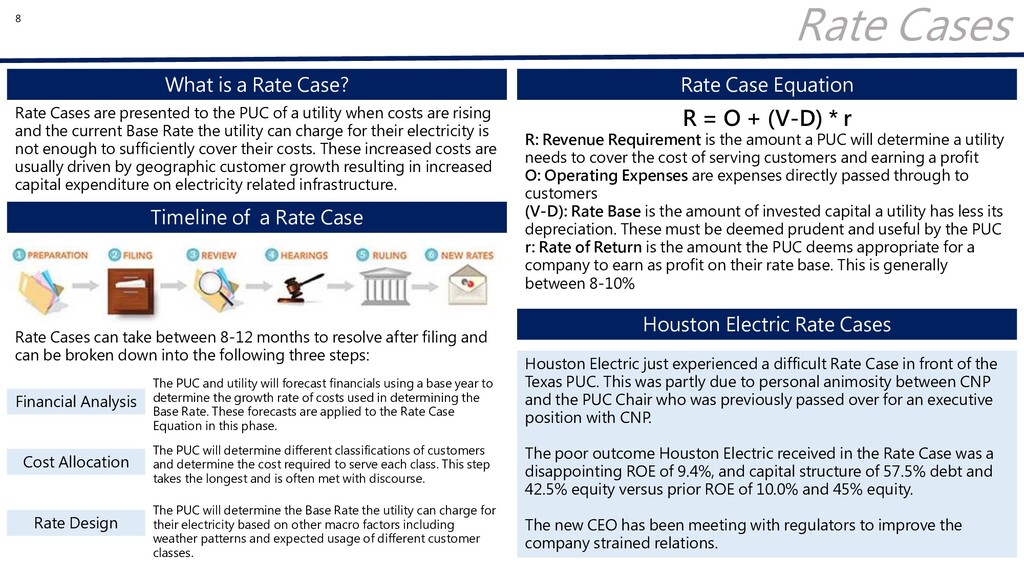
  7. Rate Cases What is a Rate Case? Rate Cases are

    presented to the PUC of a utility when costs are rising and the current Base Rate the utility can charge for their electricity is not enough to sufficiently cover their costs. These increased costs are usually driven by geographic customer growth resulting in increased capital expenditure on electricity related infrastructure. Timeline of a Rate Case Rate Cases can take between 8-12 months to resolve after filing and can be broken down into the following three steps: Financial Analysis Cost Allocation Rate Design Rate Case Equation R = O + (V-D) * r R: Revenue Requirement is the amount a PUC will determine a utility needs to cover the cost of serving customers and earning a profit O: Operating Expenses are expenses directly passed through to customers (V-D): Rate Base is the amount of invested capital a utility has less its depreciation. These must be deemed prudent and useful by the PUC r: Rate of Return is the amount the PUC deems appropriate for a company to earn as profit on their rate base. This is generally between 8-10% Houston Electric Rate Cases The PUC and utility will forecast financials using a base year to determine the growth rate of costs used in determining the Base Rate. These forecasts are applied to the Rate Case Equation in this phase. The PUC will determine different classifications of customers and determine the cost required to serve each class. This step takes the longest and is often met with discourse. The PUC will determine the Base Rate the utility can charge for their electricity based on other macro factors including weather patterns and expected usage of different customer classes. Houston Electric just experienced a difficult Rate Case in front of the Texas PUC. This was partly due to personal animosity between CNP and the PUC Chair who was previously passed over for an executive position with CNP. The poor outcome Houston Electric received in the Rate Case was a disappointing ROE of 9.4%, and capital structure of 57.5% debt and 42.5% equity versus prior ROE of 10.0% and 45% equity. The new CEO has been meeting with regulators to improve the company strained relations. 8
  8. LEP Valuation Price Targets SOTP Value Based on Peer Averages

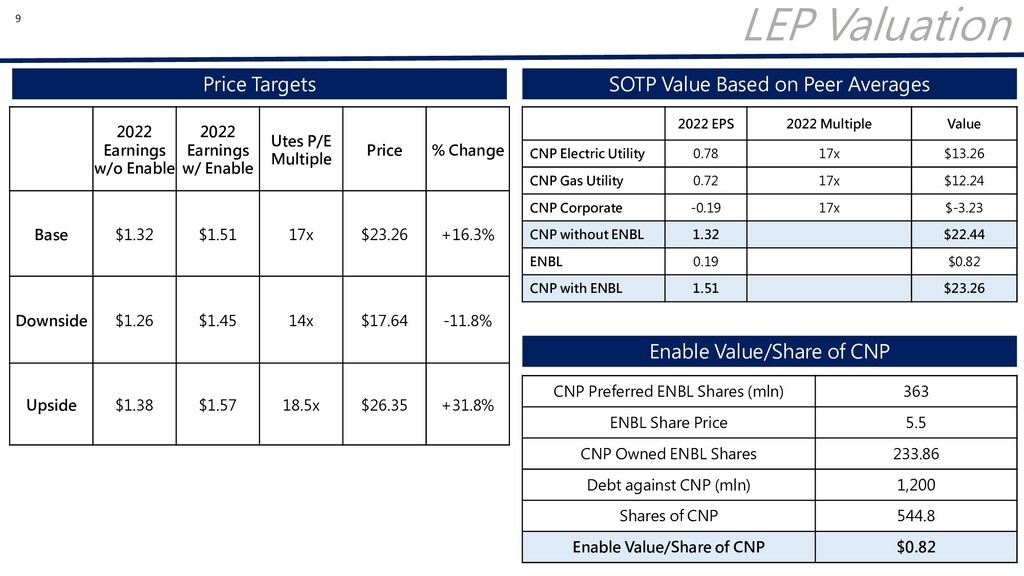
    2022 EPS 2022 Multiple Value CNP Electric Utility 0.78 17x $13.26 CNP Gas Utility 0.72 17x $12.24 CNP Corporate -0.19 17x $-3.23 CNP without ENBL 1.32 $22.44 ENBL 0.19 $0.82 CNP with ENBL 1.51 $23.26 9 CNP Preferred ENBL Shares (mln) 363 ENBL Share Price 5.5 CNP Owned ENBL Shares 233.86 Debt against CNP (mln) 1,200 Shares of CNP 544.8 Enable Value/Share of CNP $0.82 Enable Value/Share of CNP 2022 Earnings w/o Enable 2022 Earnings w/ Enable Utes P/E Multiple Price % Change Base $1.32 $1.51 17x $23.26 +16.3% Downside $1.26 $1.45 14x $17.64 -11.8% Upside $1.38 $1.57 18.5x $26.35 +31.8%
  9. Peer 2022 P/E Multiples Multi Industry Peers Company Ticker 2022

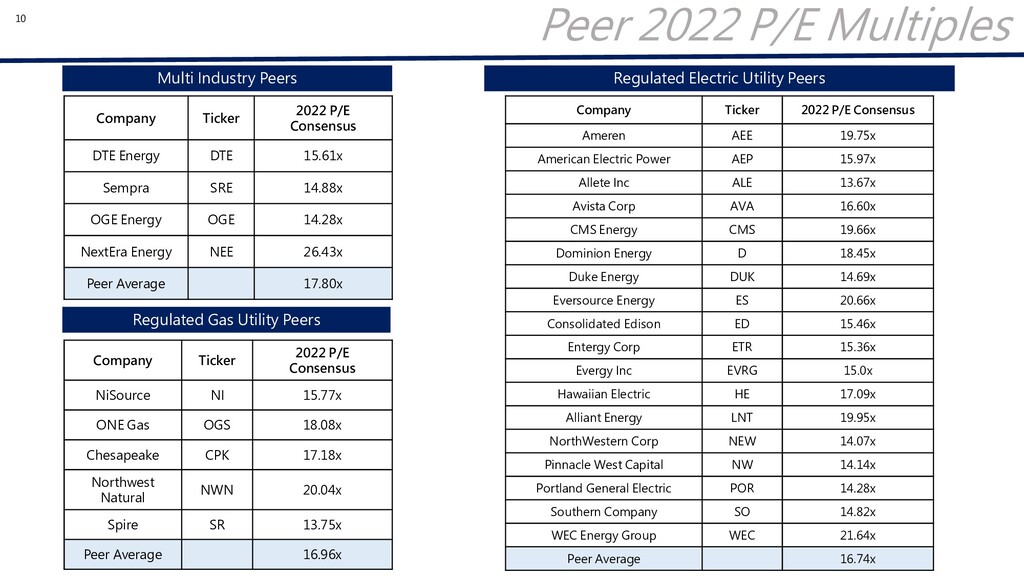
    P/E Consensus DTE Energy DTE 15.61x Sempra SRE 14.88x OGE Energy OGE 14.28x NextEra Energy NEE 26.43x Peer Average 17.80x Regulated Gas Utility Peers Company Ticker 2022 P/E Consensus NiSource NI 15.77x ONE Gas OGS 18.08x Chesapeake CPK 17.18x Northwest Natural NWN 20.04x Spire SR 13.75x Peer Average 16.96x Regulated Electric Utility Peers Company Ticker 2022 P/E Consensus Ameren AEE 19.75x American Electric Power AEP 15.97x Allete Inc ALE 13.67x Avista Corp AVA 16.60x CMS Energy CMS 19.66x Dominion Energy D 18.45x Duke Energy DUK 14.69x Eversource Energy ES 20.66x Consolidated Edison ED 15.46x Entergy Corp ETR 15.36x Evergy Inc EVRG 15.0x Hawaiian Electric HE 17.09x Alliant Energy LNT 19.95x NorthWestern Corp NEW 14.07x Pinnacle West Capital NW 14.14x Portland General Electric POR 14.28x Southern Company SO 14.82x WEC Energy Group WEC 21.64x Peer Average 16.74x 10
  10. What is the Street Missing? New Management and Strategic Review

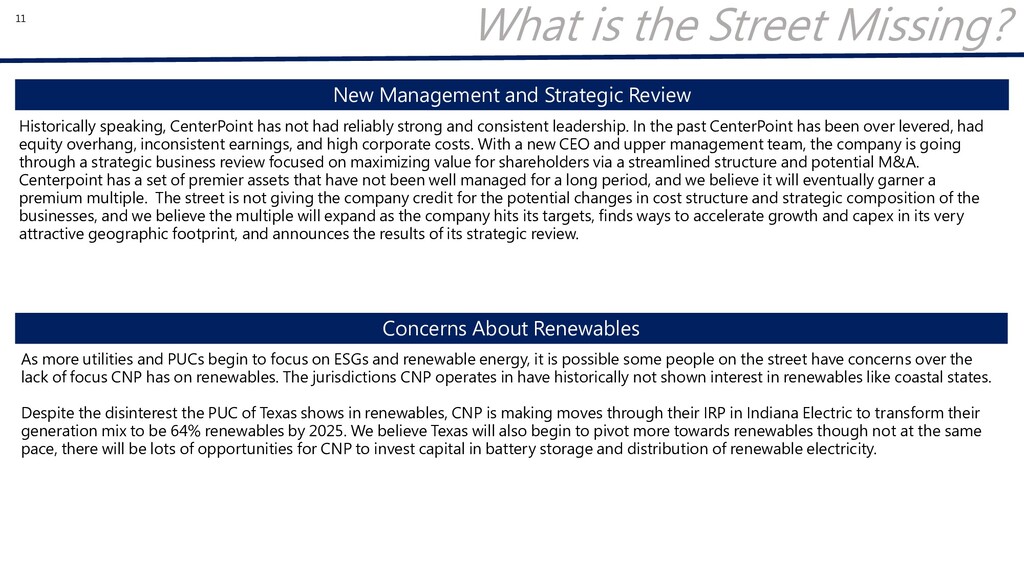
    Historically speaking, CenterPoint has not had reliably strong and consistent leadership. In the past CenterPoint has been over levered, had equity overhang, inconsistent earnings, and high corporate costs. With a new CEO and upper management team, the company is going through a strategic business review focused on maximizing value for shareholders via a streamlined structure and potential M&A. Centerpoint has a set of premier assets that have not been well managed for a long period, and we believe it will eventually garner a premium multiple. The street is not giving the company credit for the potential changes in cost structure and strategic composition of the businesses, and we believe the multiple will expand as the company hits its targets, finds ways to accelerate growth and capex in its very attractive geographic footprint, and announces the results of its strategic review. Concerns About Renewables As more utilities and PUCs begin to focus on ESGs and renewable energy, it is possible some people on the street have concerns over the lack of focus CNP has on renewables. The jurisdictions CNP operates in have historically not shown interest in renewables like coastal states. Despite the disinterest the PUC of Texas shows in renewables, CNP is making moves through their IRP in Indiana Electric to transform their generation mix to be 64% renewables by 2025. We believe Texas will also begin to pivot more towards renewables though not at the same pace, there will be lots of opportunities for CNP to invest capital in battery storage and distribution of renewable electricity. 11
  11. Catalysts Strategic Review Approval and Certainty Around CapEx with an

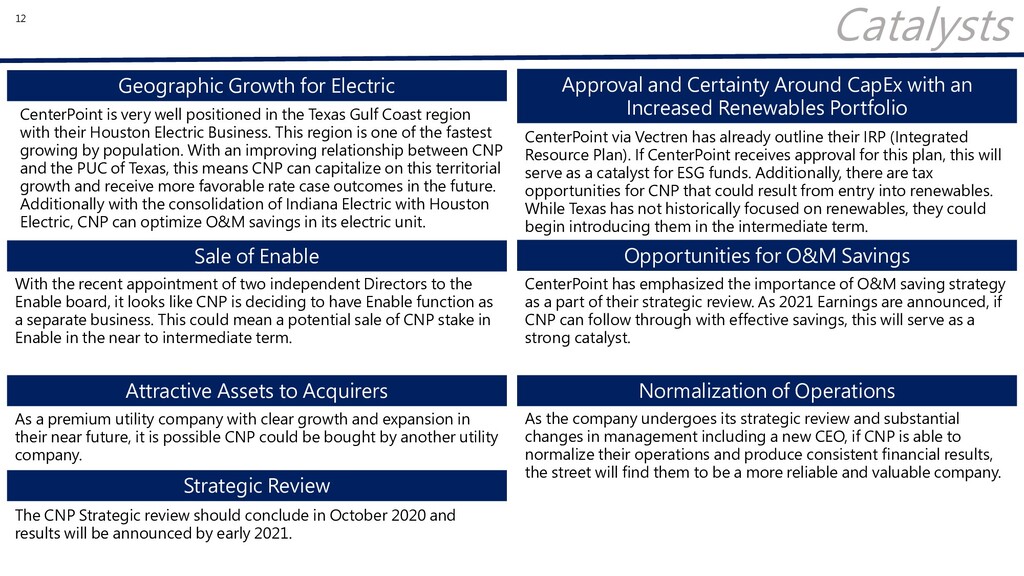
    Increased Renewables Portfolio Sale of Enable Attractive Assets to Acquirers Normalization of Operations Opportunities for O&M Savings Geographic Growth for Electric The CNP Strategic review should conclude in October 2020 and results will be announced by early 2021. CenterPoint via Vectren has already outline their IRP (Integrated Resource Plan). If CenterPoint receives approval for this plan, this will serve as a catalyst for ESG funds. Additionally, there are tax opportunities for CNP that could result from entry into renewables. While Texas has not historically focused on renewables, they could begin introducing them in the intermediate term. With the recent appointment of two independent Directors to the Enable board, it looks like CNP is deciding to have Enable function as a separate business. This could mean a potential sale of CNP stake in Enable in the near to intermediate term. CenterPoint is very well positioned in the Texas Gulf Coast region with their Houston Electric Business. This region is one of the fastest growing by population. With an improving relationship between CNP and the PUC of Texas, this means CNP can capitalize on this territorial growth and receive more favorable rate case outcomes in the future. Additionally with the consolidation of Indiana Electric with Houston Electric, CNP can optimize O&M savings in its electric unit. As a premium utility company with clear growth and expansion in their near future, it is possible CNP could be bought by another utility company. CenterPoint has emphasized the importance of O&M saving strategy as a part of their strategic review. As 2021 Earnings are announced, if CNP can follow through with effective savings, this will serve as a strong catalyst. As the company undergoes its strategic review and substantial changes in management including a new CEO, if CNP is able to normalize their operations and produce consistent financial results, the street will find them to be a more reliable and valuable company. 12