economics highlights the role of social preferences in decisions. Popula;ons in real (not experimental) public goods tend to be very heterogeneous. Group composi;on may impact the sustainability of voluntary public good contribu;ons. • Conduct agent-‐based simula<ons of contribu<ons to an actual public good (microfinance groups), varying group composi<on and social preferences. – Why? To systema;cally examine the effect of these factors on contribu;ons, as an actual experimental seIng would be innapropriate.
-‐ computa;onal model(s) of individual behaviour(s) with mechanisms for: -‐ sensing the environment and other agents -‐ keeping an internal state about what they know -‐ selec;ng ac;ons (i.e. how and when will an act occur) Interac<on -‐ rules that either determine, or result in emergent, organisa;on paLerns -‐ asynchronous / dynamic interac;on may prevent a full analy;cal approach -‐ scale (number and/or density of agents) maLers Environment (physical / symbolical) representa;on of where / how agents (and stakeholders!) interact
Issues -‐ individual / social behaviour oRen is subject to influences that one can only understand with detailed contextual (oRen only qualita;ve) insights. data about social phenomena is oRen: -‐ non-‐existent, thus requiring fund/;me to collect and process it -‐ unavailable due to privacy agreements, such as non-‐disclosure agreements -‐ if at hand, informa;on is typically limited (incomplete or outdated) Purpose -‐ control environments and repeat experiments to test hypotheses according to a implemented theory containing assump;ons about individual / social behaviour -‐ to gain insights about social phenomena (both about known and unknown scenarios) -‐ discuss findings with expert stakeholders / policy-‐makers
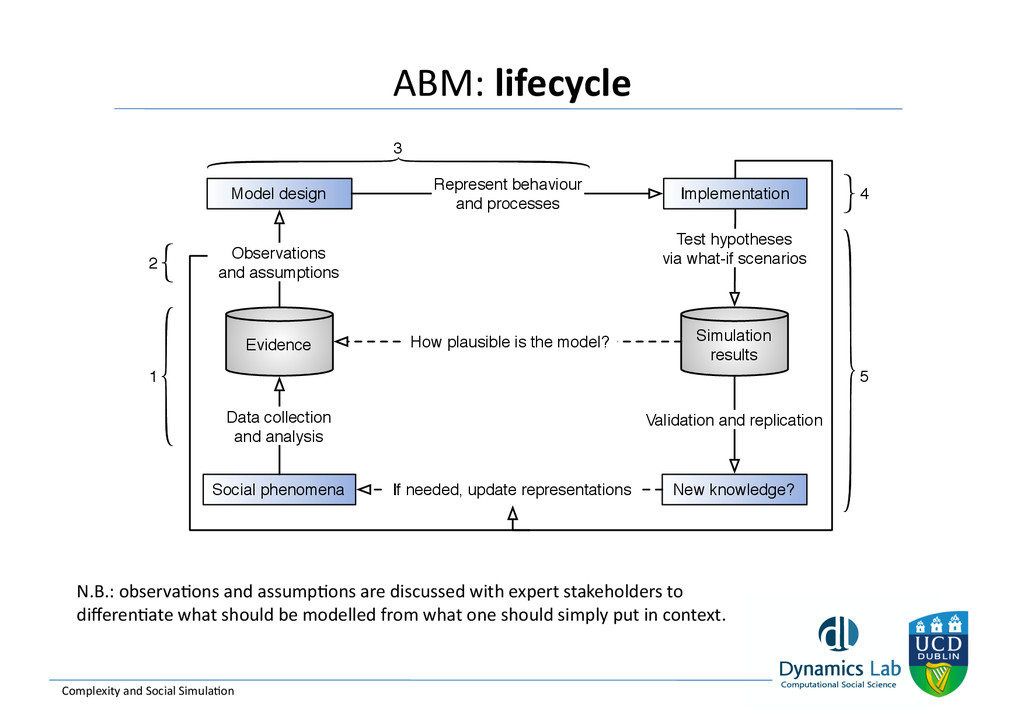
Implementation New knowledge? Social phenomena Evidence Simulation results Represent behaviour and processes Test hypotheses via what-if scenarios Validation and replication Observations and assumptions Data collection and analysis If needed, update representations How plausible is the model? 1 2 3 4 5 N.B.: observa;ons and assump;ons are discussed with expert stakeholders to differen;ate what should be modelled from what one should simply put in context.
• The provision of public goods provision can be directly linked to welfare and poverty : – important examples of public goods for the ci;zenry include: health services, schools, clean water, urban sanita;on, roads, microfinance, etc. • Tradi<onal economic analysis suggests under-‐provision of public goods – stemming from individuals considering only their own costs and benefits associated with contribu;ng, disregarding benefits accrued from others – behavioural / experimental economics suggest that, while individuals do selfish choices, many also sacrifice their own well-‐being for others (i.e. there is significant heterogeneity in social preferences)
help people get out of poverty.z (Muhammad Yunus) ( a public good: microfinance Complexity and Social Simula;on Key concepts of microfinance (credit, savings, insurance, etc.) -‐ clientele: typically those who cannot access tradi;onal banking -‐ social collateral: the collec;ve responsibility over credit effec;vely subs;tutes tradi;onal assets to backup funding -‐ methodology: local ins;tu;ons implement the general framework with adapta;ons to local needs (i.e. developed / developing economies)
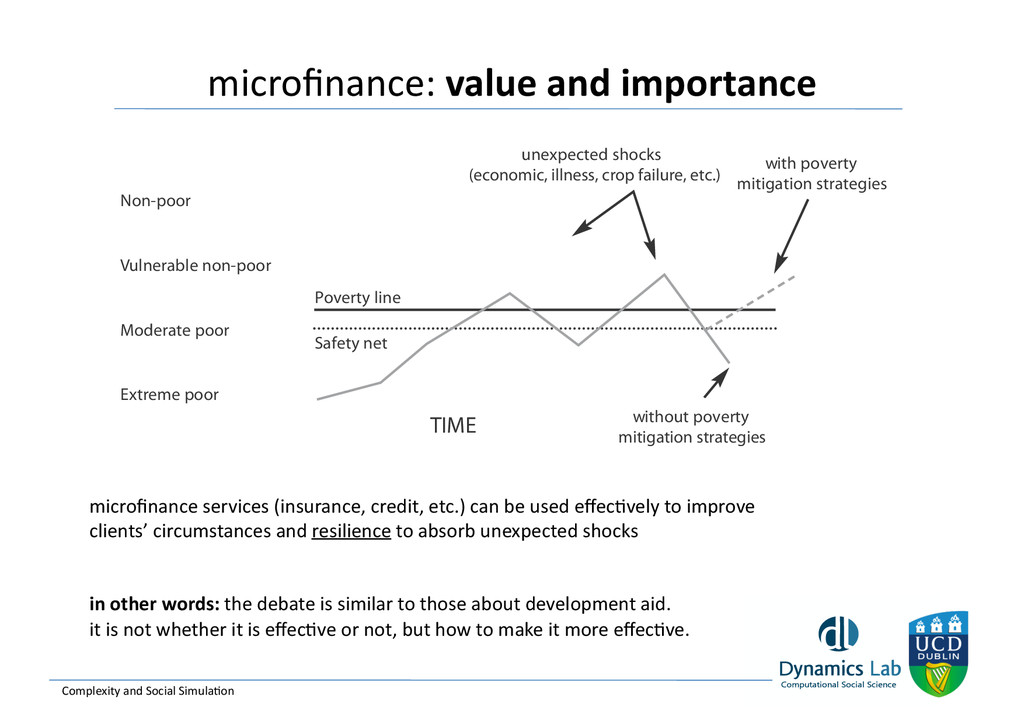
Non-poor Vulnerable non-poor Moderate poor Extreme poor Safety net unexpected shocks (economic, illness, crop failure, etc.) with poverty mitigation strategies without poverty mitigation strategies Poverty line TIME microfinance services (insurance, credit, etc.) can be used effec;vely to improve clients’ circumstances and resilience to absorb unexpected shocks in other words: the debate is similar to those about development aid. it is not whether it is effec;ve or not, but how to make it more effec;ve.
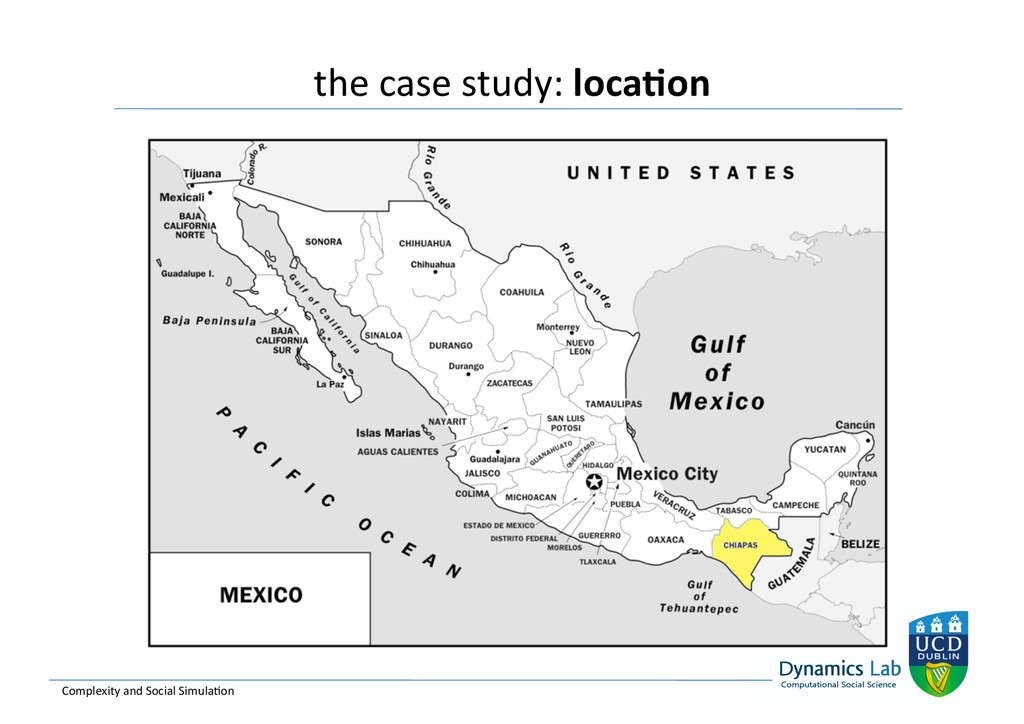
Bank) pioneer -‐ based in Chiapas, Mexico, with over 20.000 ac;ve clients in groups of 3 to 7, following an adapta;on of the (Grameen Bank) use assorta;ve matching (endogenous and geographically bound peer selec;on) -‐ instead of considering tradi;onal assets, required by tradi;onal banks, social collateral of applicants are assessed along with the local poverty line -‐ understanding the financial and social status quo of their clients is key to adapt services with less risk (e.g. how ins;tu;onal norms interplay with group compliance strategies) the case study: context Complexity and Social Simula;on
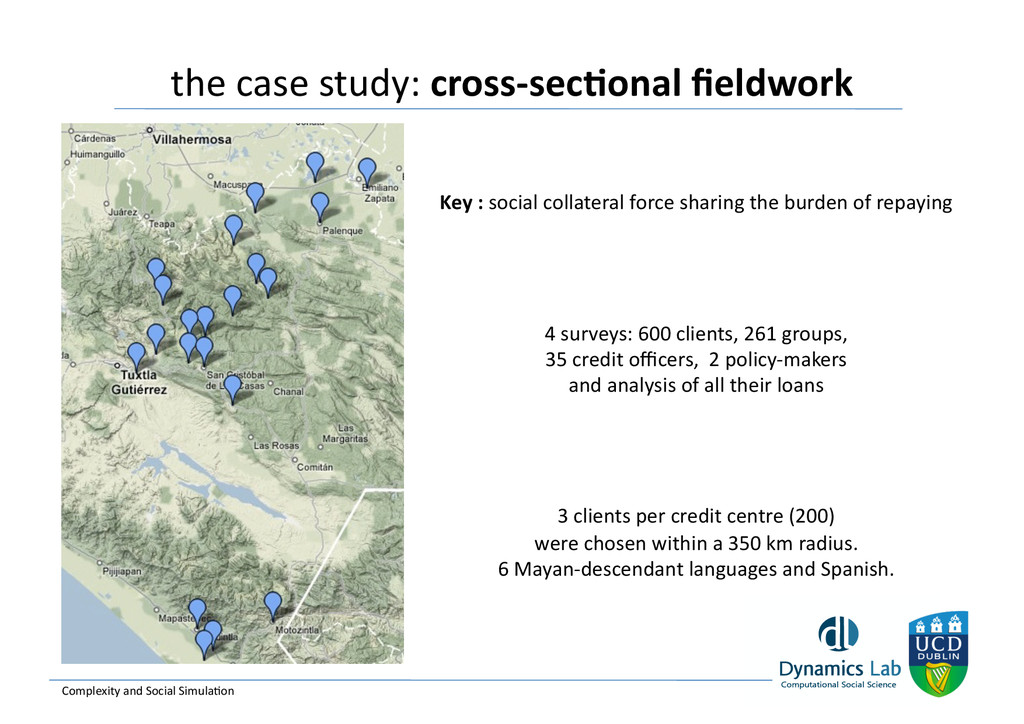
Key : social collateral force sharing the burden of repaying 4 surveys: 600 clients, 261 groups, 35 credit officers, 2 policy-‐makers and analysis of all their loans 3 clients per credit centre (200) were chosen within a 350 km radius. 6 Mayan-‐descendant languages and Spanish.
financially stable ins;tu;ons are interested, from a sustainability perspec;ve, to beLer understand – both qualita;vely and quan;ta;vely – their groups -‐ microfinance ins;tu;ons (MFIs) have to avoid overpowering external dependence and harness the social collateral (the group dynamics) -‐ yet collec;ng and analysing such data (specially longitudinally) can be prohibi;vely expensive and ;me-‐consuming for MFIs -‐ despite the likelihood of improving understanding on how clients self-‐ organise regarding defaul;ng members and debt, there is no a priori guarantee that such effort will produce findings directly useful for policy-‐making.
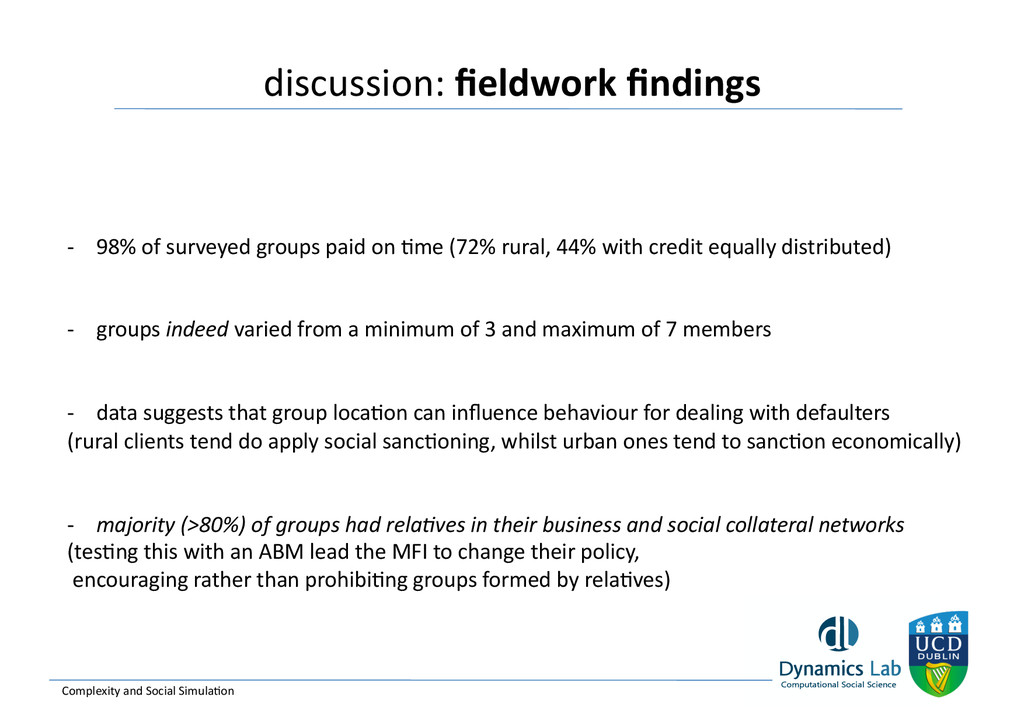
98% of surveyed groups paid on ;me (72% rural, 44% with credit equally distributed) -‐ groups indeed varied from a minimum of 3 and maximum of 7 members -‐ data suggests that group loca;on can influence behaviour for dealing with defaulters (rural clients tend do apply social sanc;oning, whilst urban ones tend to sanc;on economically) -‐ majority (>80%) of groups had rela=ves in their business and social collateral networks (tes;ng this with an ABM lead the MFI to change their policy, encouraging rather than prohibi;ng groups formed by rela;ves)
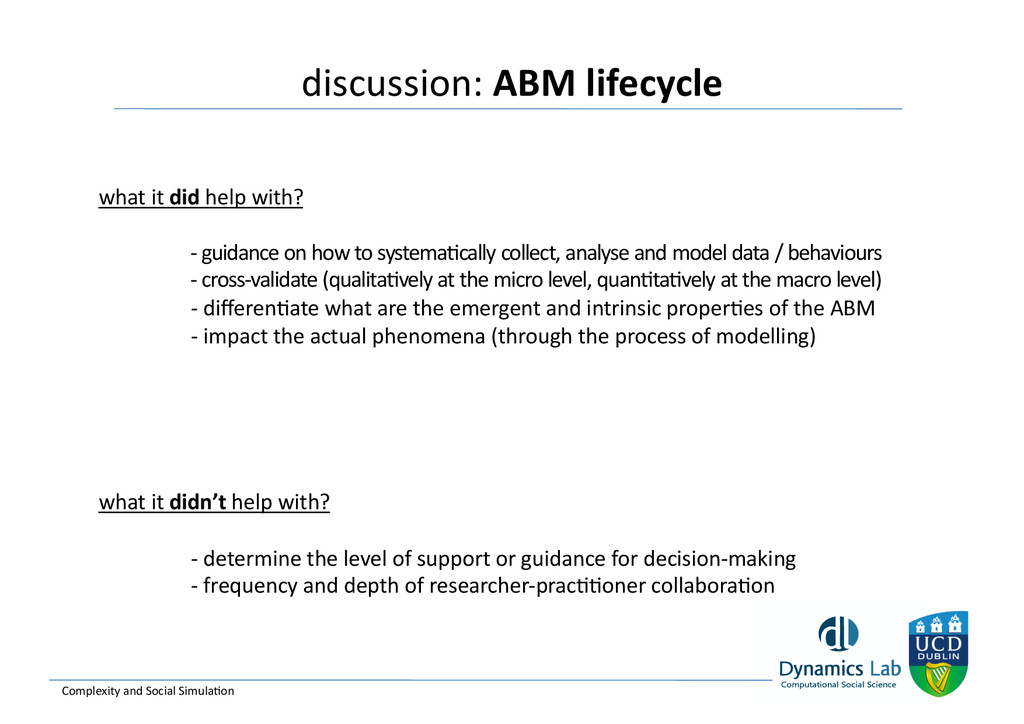
what it did help with? -‐ guidance on how to systema;cally collect, analyse and model data / behaviours -‐ cross-‐validate (qualita;vely at the micro level, quan;ta;vely at the macro level) -‐ differen;ate what are the emergent and intrinsic proper;es of the ABM -‐ impact the actual phenomena (through the process of modelling) what it didn’t help with? -‐ determine the level of support or guidance for decision-‐making -‐ frequency and depth of researcher-‐prac;;oner collabora;on
decision-‐makers par;cipated in every stage of the research process for elici;ng data and modelling assump;ons into the ABM -‐ fieldwork findings were more promptly related to, both in terms of ;me and scale, to a known state of their socio-‐economic phenomenon. (i.e. it is important to relate results to events that can s;ll be observed) -‐ the ini;al unfamiliarity of decision-‐ and policy-‐makers with ABM did influence some of their skep;cism when assessing / evalua;ng it.
-‐ computa<onal models are formal, synthesised representa;ons of a phenomenon that is usually not analysed as such, so that can be difficult to discuss with stakeholders -‐ the increasing demand / popularity to assess poten<al outcomes of socio-‐economic phenomena is turning simula;ons into a form of surrogate reasoning -‐ computa;onal methods and techniques are oRen alien to the stakeholders (i.e. informing actual policy by interpre;ng ABM results is not straighjorward)
-‐ communica;ng with non-‐experts the inner workings of an ABM is difficult (the concept is grasped easily, but that is not enough to inform policy-‐making) -‐ there are major difficul<es to communicate and assess the actual usefulness of an ABM (par;cularly when datasets cannot be directly compared) -‐ the laborious but fruijul endeavour of involving stakeholders in the research process can provide them with a sense of ownership about what is being developed -‐ tradi;onal quan;ta;ve and qualita;ve research methodologies can lead to useful descrip;ons of an actual socio-‐economic phenomenon (so that an ABM can complement these approaches)
in the modelling process can minimise issues of communica;on and provide a sense of ownership over the generated results; (b) lack of (or minimal frac;onaliza;on) in social preferences can impact posi;vely in the provision of public good (i.e. credit quotas are repaid on ;me); -‐ this study has some scalability poten;al, despite insights being context-‐dependant -‐ a par;cipatory approach can bridge the gap between the stakeholders and researchers -‐ this informed an actual policy change regula;ng the funding of over 20.000 credit clients


 ftakahashi
 institutdelelevage
 afroscript
 microbaseinc
 tattaka
 yukinobaba
 monochromegane
 shunk031
 satai
 enochan
 tmiket
 thirion
 codingconduct
 trishagee
 kimpetersen
 iamctodd
 inesmontani
 marcelosomers
 lemiorhan
 leimatthew05
 garrettdimon
 quramy