Upgrade to Pro — share decks privately, control downloads, hide ads and more …

Tax on PF Withdrawal: EPF Tax Rules Guide 2026

Sponsored · Your Podcast. Everywhere. Effortlessly. Share. Educate. Inspire. Entertain. You do you. We'll handle the rest. →
Avatar for Sats Sats
October 14, 2026

Tax on PF Withdrawal: EPF Tax Rules Guide 2026

Understand the tax on PF withdrawal with this comprehensive guide to EPF tax rules in 2026. Learn how the five-year continuous service rule affects tax exemption, when premature PF withdrawals may become taxable, how TDS applies to eligible withdrawals above ₹50,000, and why TDS is different from your final income tax liability.

This presentation also covers EPF transfers when changing jobs, Form 121 declarations, and essential checks to complete before withdrawing your provident fund balance.

Whether you are a salaried employee, working professional, or first-time PF claimant, this guide will help you understand the key factors affecting EPF withdrawal taxation and make more informed financial decisions.

Read the complete guide: https://www.bloggercap.info/tax-on-pf-withdrawal/

Explore the full article for more information on EPF taxation, withdrawal rules, and tax planning.

Avatar for Sats

Sats

October 14, 2026

Other Decks in Business

Transcript

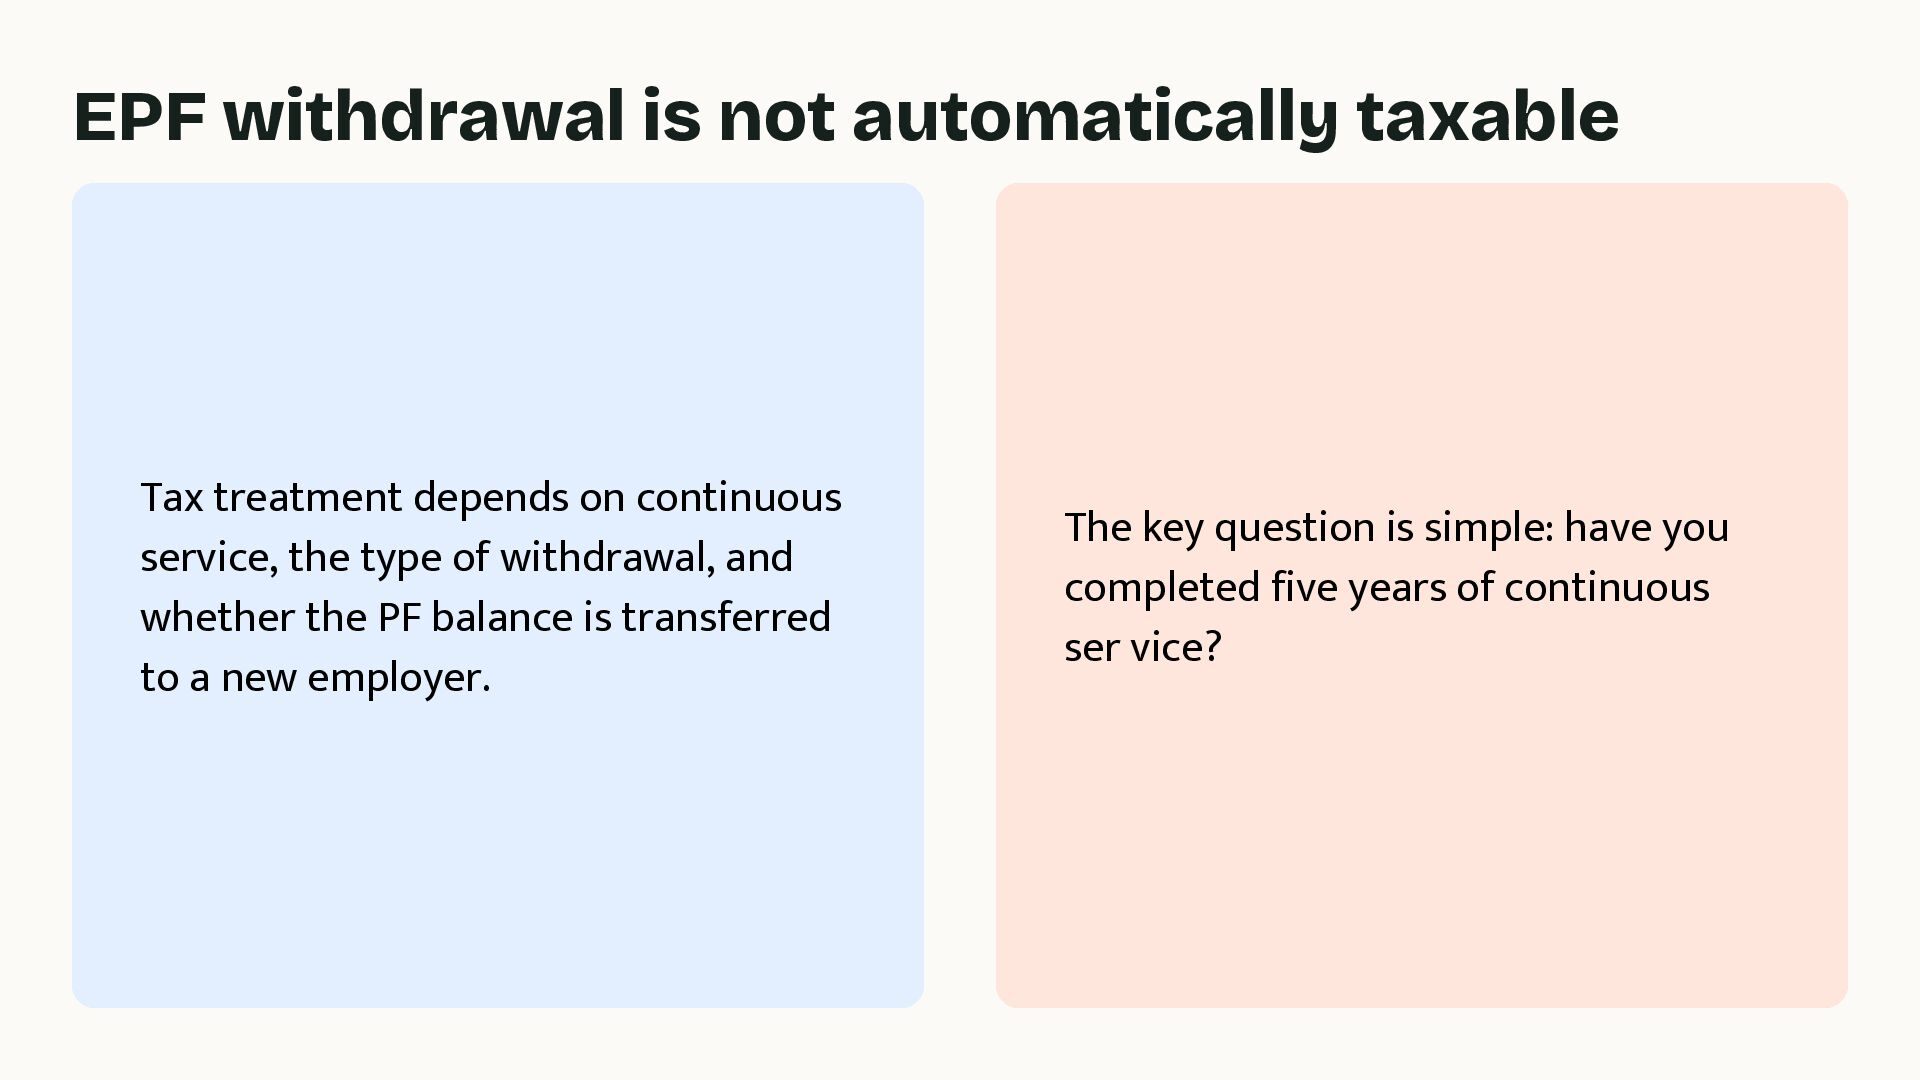
  1. EPF withdrawal is not automatically taxable Tax treatment depends on

    continuous service, the type of withdrawal, and whether the PF balance is transferred to a new employer. The key question is simple: have you completed five years of continuous ser vice?
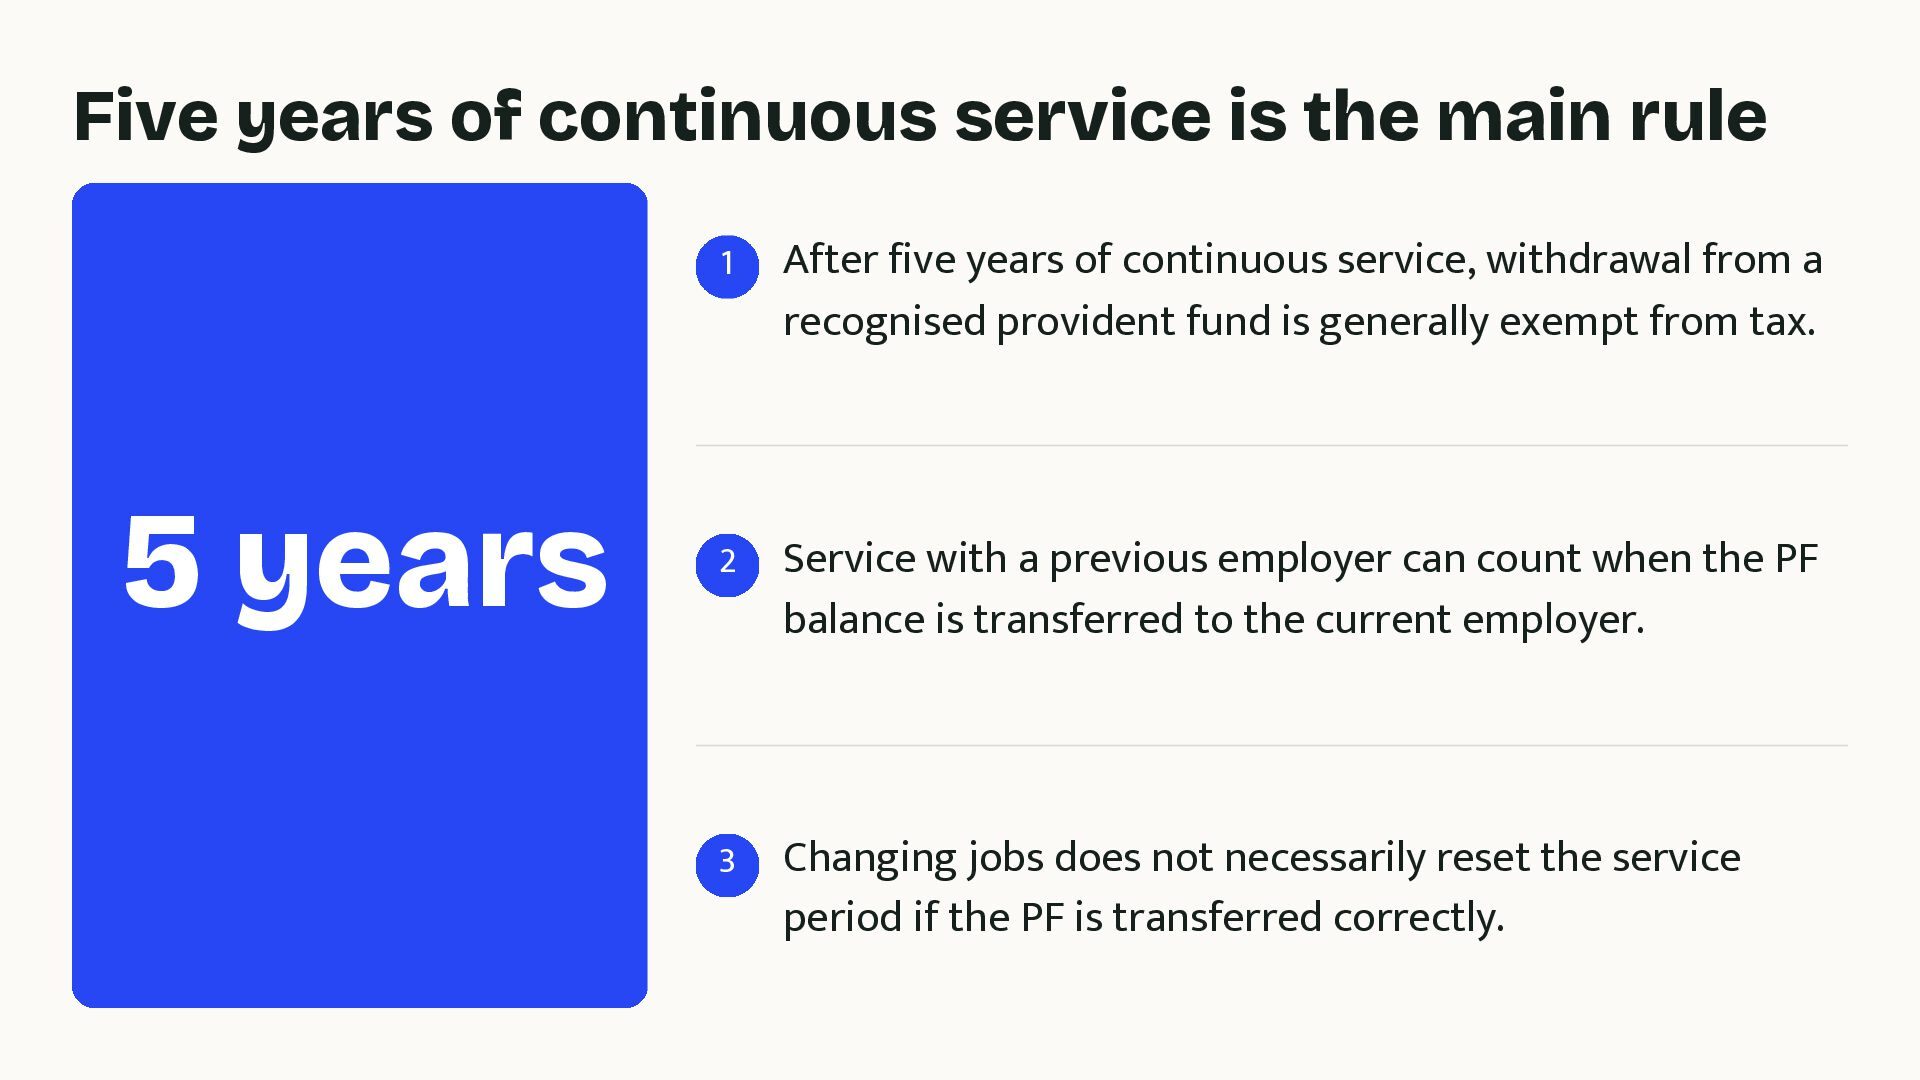
  2. Five years of continuous service is the main rule 5

    years 1 After five years of continuous service, withdrawal from a recognised provident fund is generally exempt from tax. 2 Service with a previous employer can count when the PF balance is transferred to the current employer. 3 Changing jobs does not necessarily reset the service period if the PF is transferred correctly.
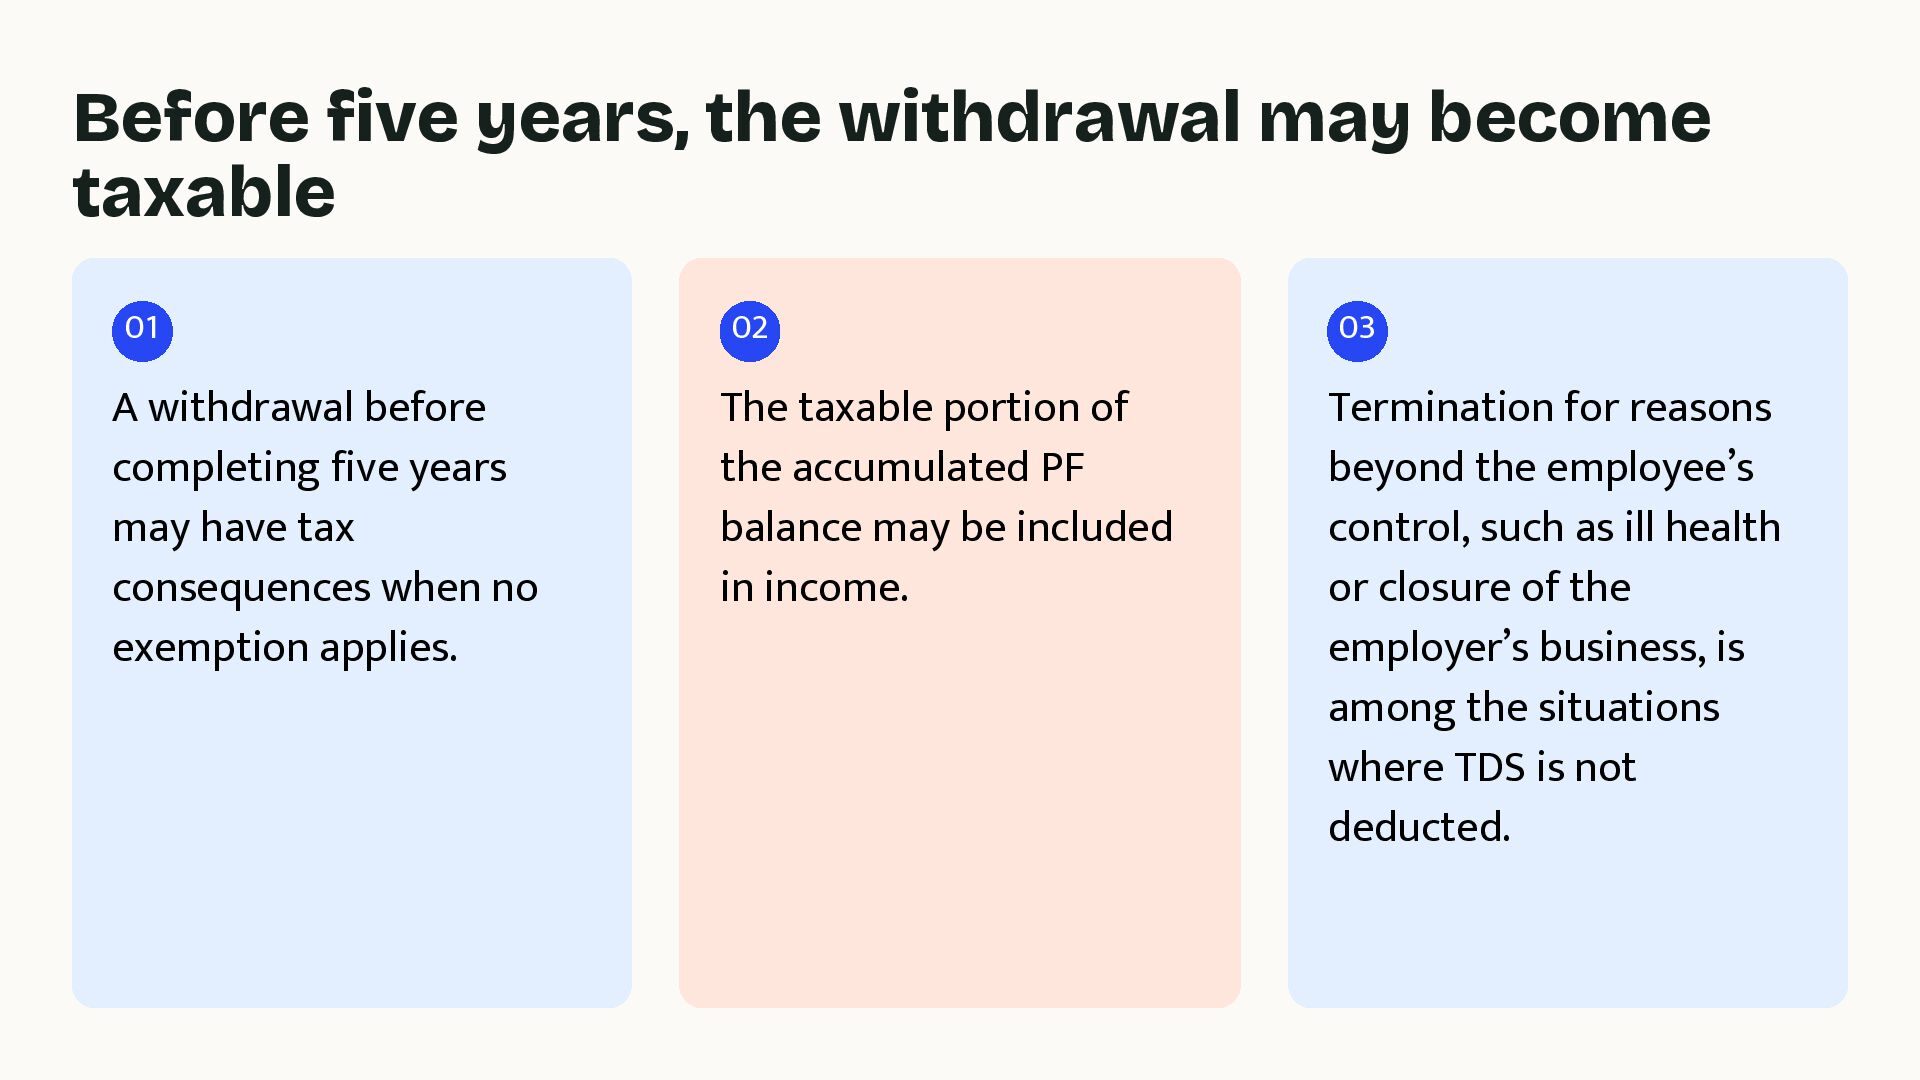
  3. Before five years, the withdrawal may become taxable 01 02

    03 A withdrawal before completing five years may have tax consequences when no exemption applies. The taxable portion of the accumulated PF balance may be included in income. Termination for reasons beyond the employee’s control, such as ill health or closure of the employer’s business, is among the situations where TDS is not deducted.
  4. Transfer is different from a cash withdrawal 1 Transferring the

    EPF balance to the recognised provident fund of a new employer generally does not trigger TDS under the applicable EPF rules. 2 Transferring PF after changing jobs can be more taxefficient than withdrawing the entire balance soon after leaving an employer.
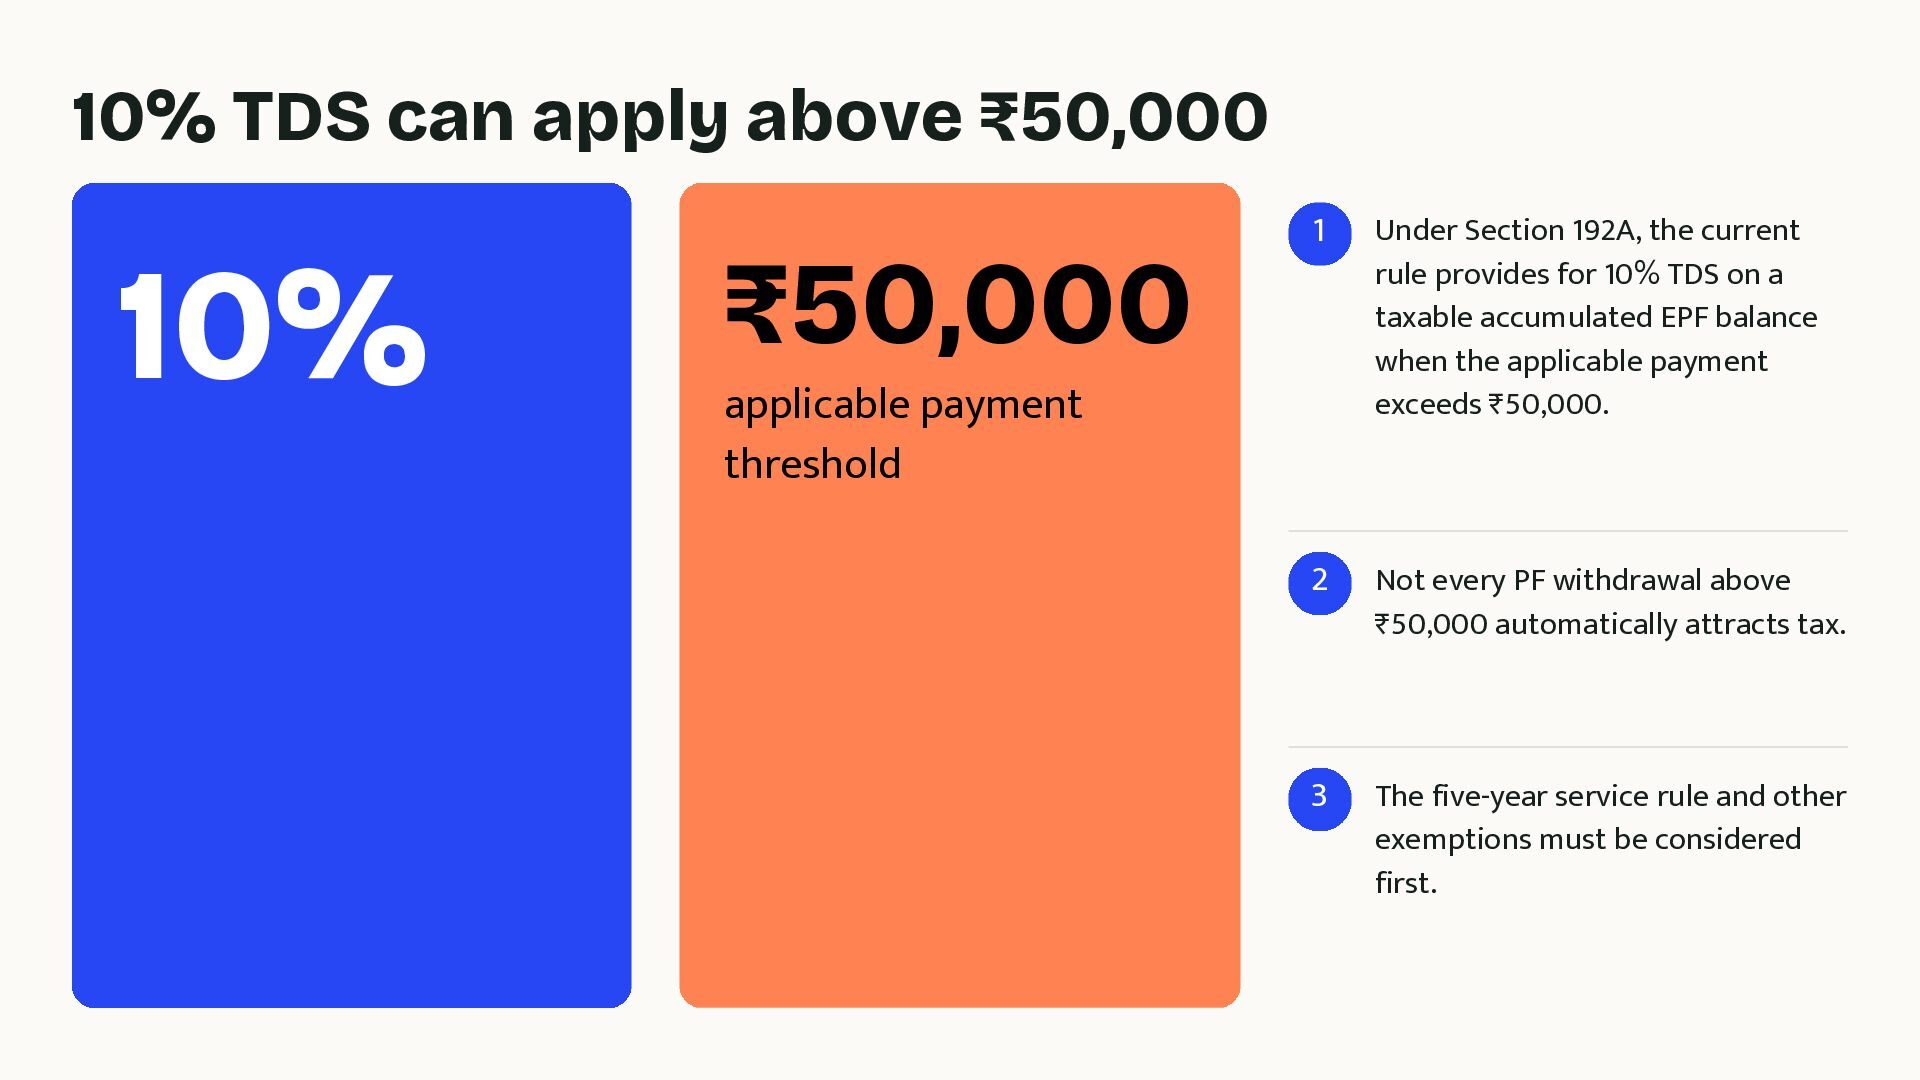
  5. 10% TDS can apply above ₹50,000 10% ₹50,000 1 Under

    Section 192A, the current rule provides for 10% TDS on a taxable accumulated EPF balance when the applicable payment exceeds ₹50,000. 2 Not every PF withdrawal above ₹50,000 automatically attracts tax. 3 The five-year service rule and other exemptions must be considered first. applicable payment threshold
  6. TDS is not the same as final tax liability 01

    02 TDS is tax collected at the time of payment. Actual tax liability depends on the applicable income-tax rules and your overall income for the relevant tax year. 03 04 No TDS does not necessarily mean every part of the transaction is exempt. TDS deducted from a PF payment does not always represent the final tax liability.
  7. Form 121 replaces Forms 15G and 15H in 2026 1

    TheIncome-taxAct, 2025introduced a consolidated Form 121 foreligible declarations relating to specified payments where the taxpayer meets the conditions for non-deduction of TDS. 2 EPFO has issued a 2026 circular regarding the transition from Forms 15G and 15H to Form 121 for TDS-exempted incomes. 3 Check the latest EPFO and Income Tax Department instructions before submitting a declaration.
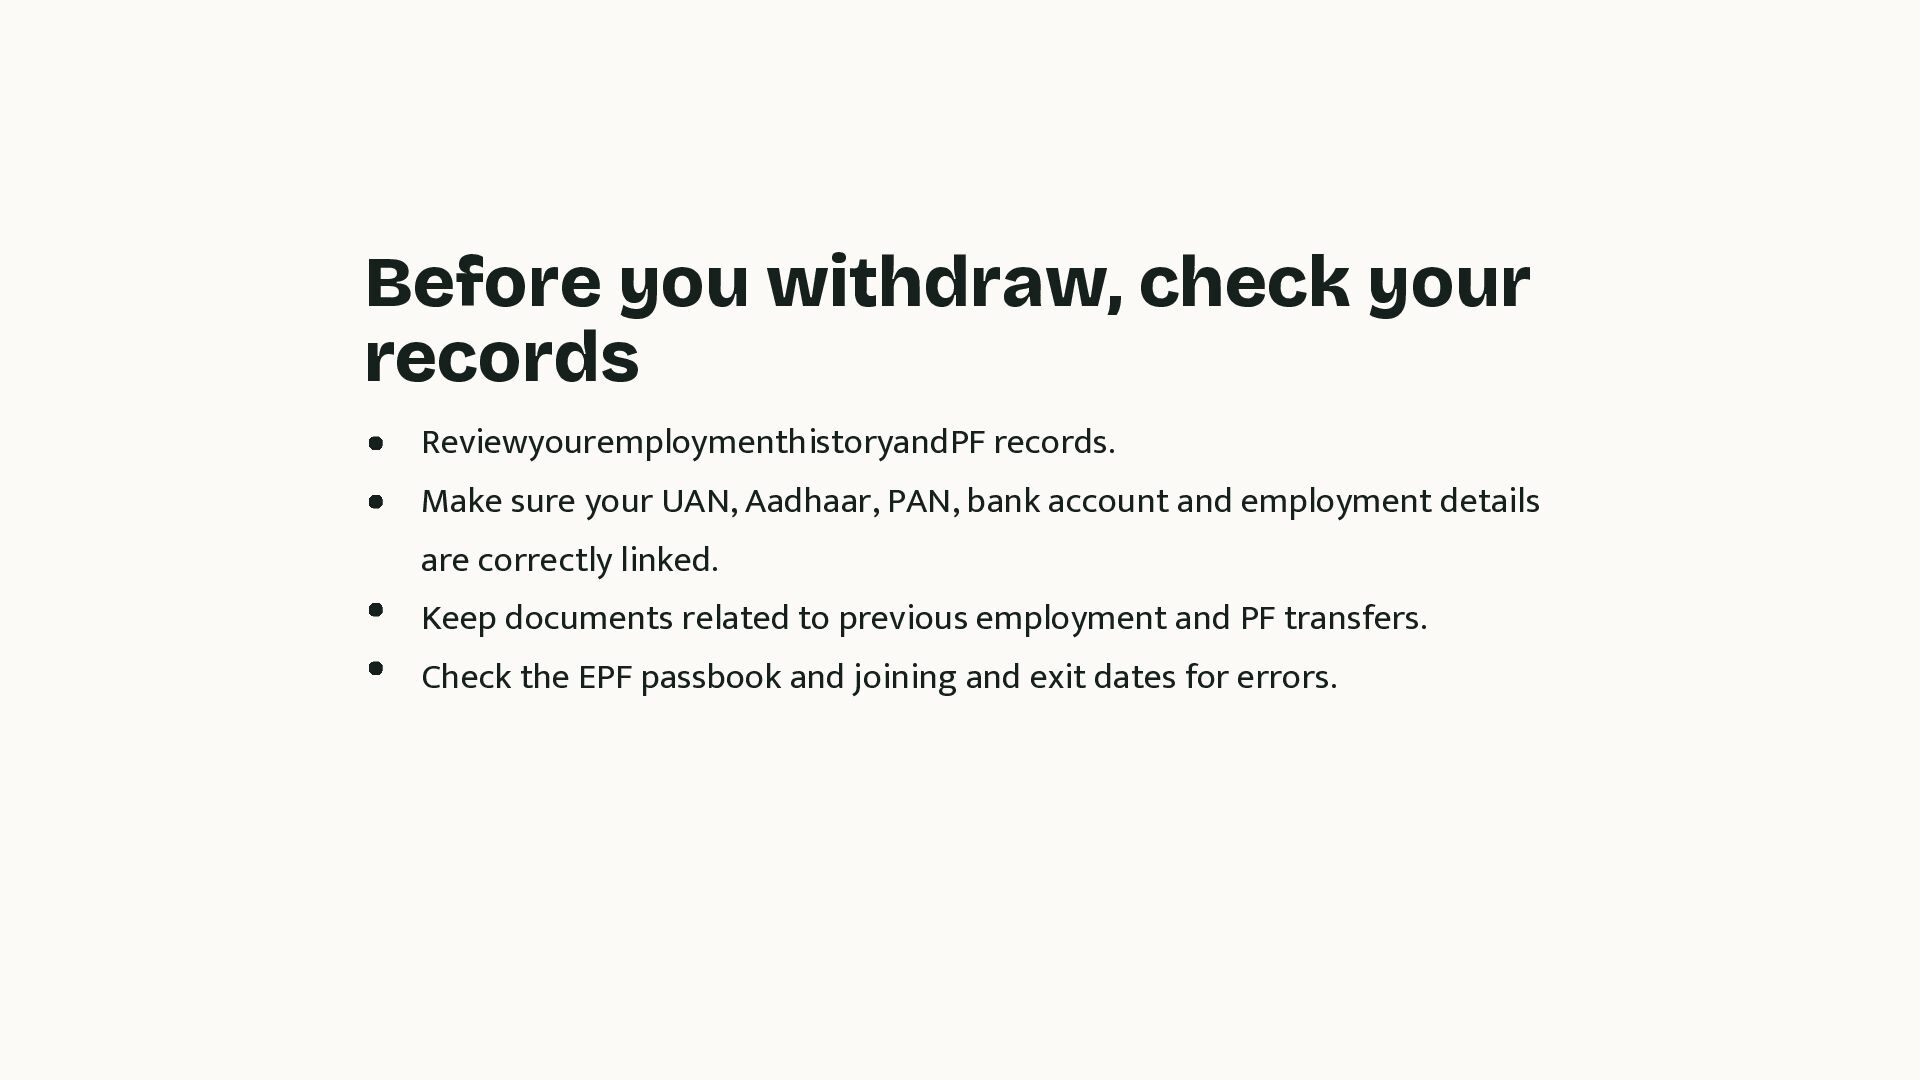
  8. Before you withdraw, check your records ReviewyouremploymenthistoryandPF records. Make sure

    your UAN, Aadhaar, PAN, bank account and employment details are correctly linked. Keep documents related to previous employment and PF transfers. Check the EPF passbook and joining and exit dates for errors.
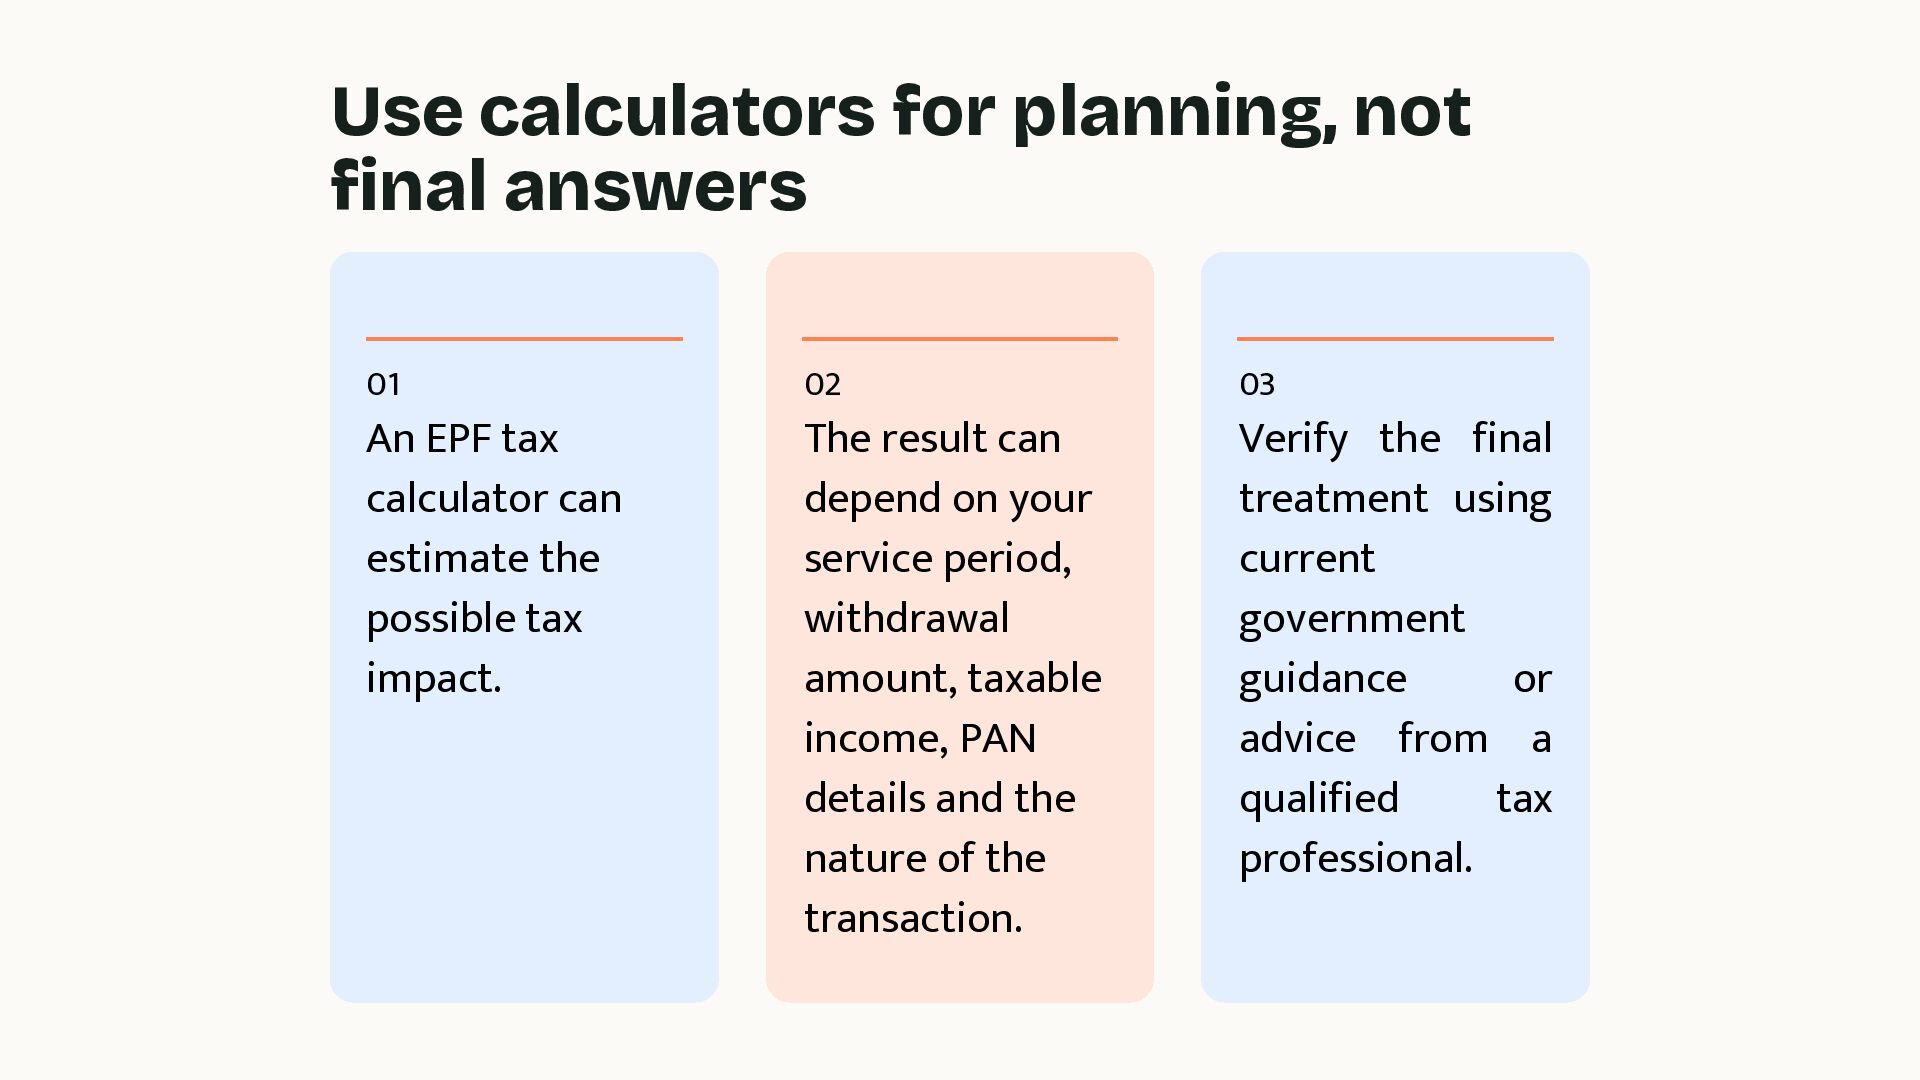
  9. Use calculators for planning, not final answers 01 An EPF

    tax calculator can estimate the possible tax impact. 02 The result can depend on your service period, withdrawal amount, taxable income, PAN details and the nature of the transaction. 03 Verify the final treatment using current government guidance or advice from a qualified tax professional.