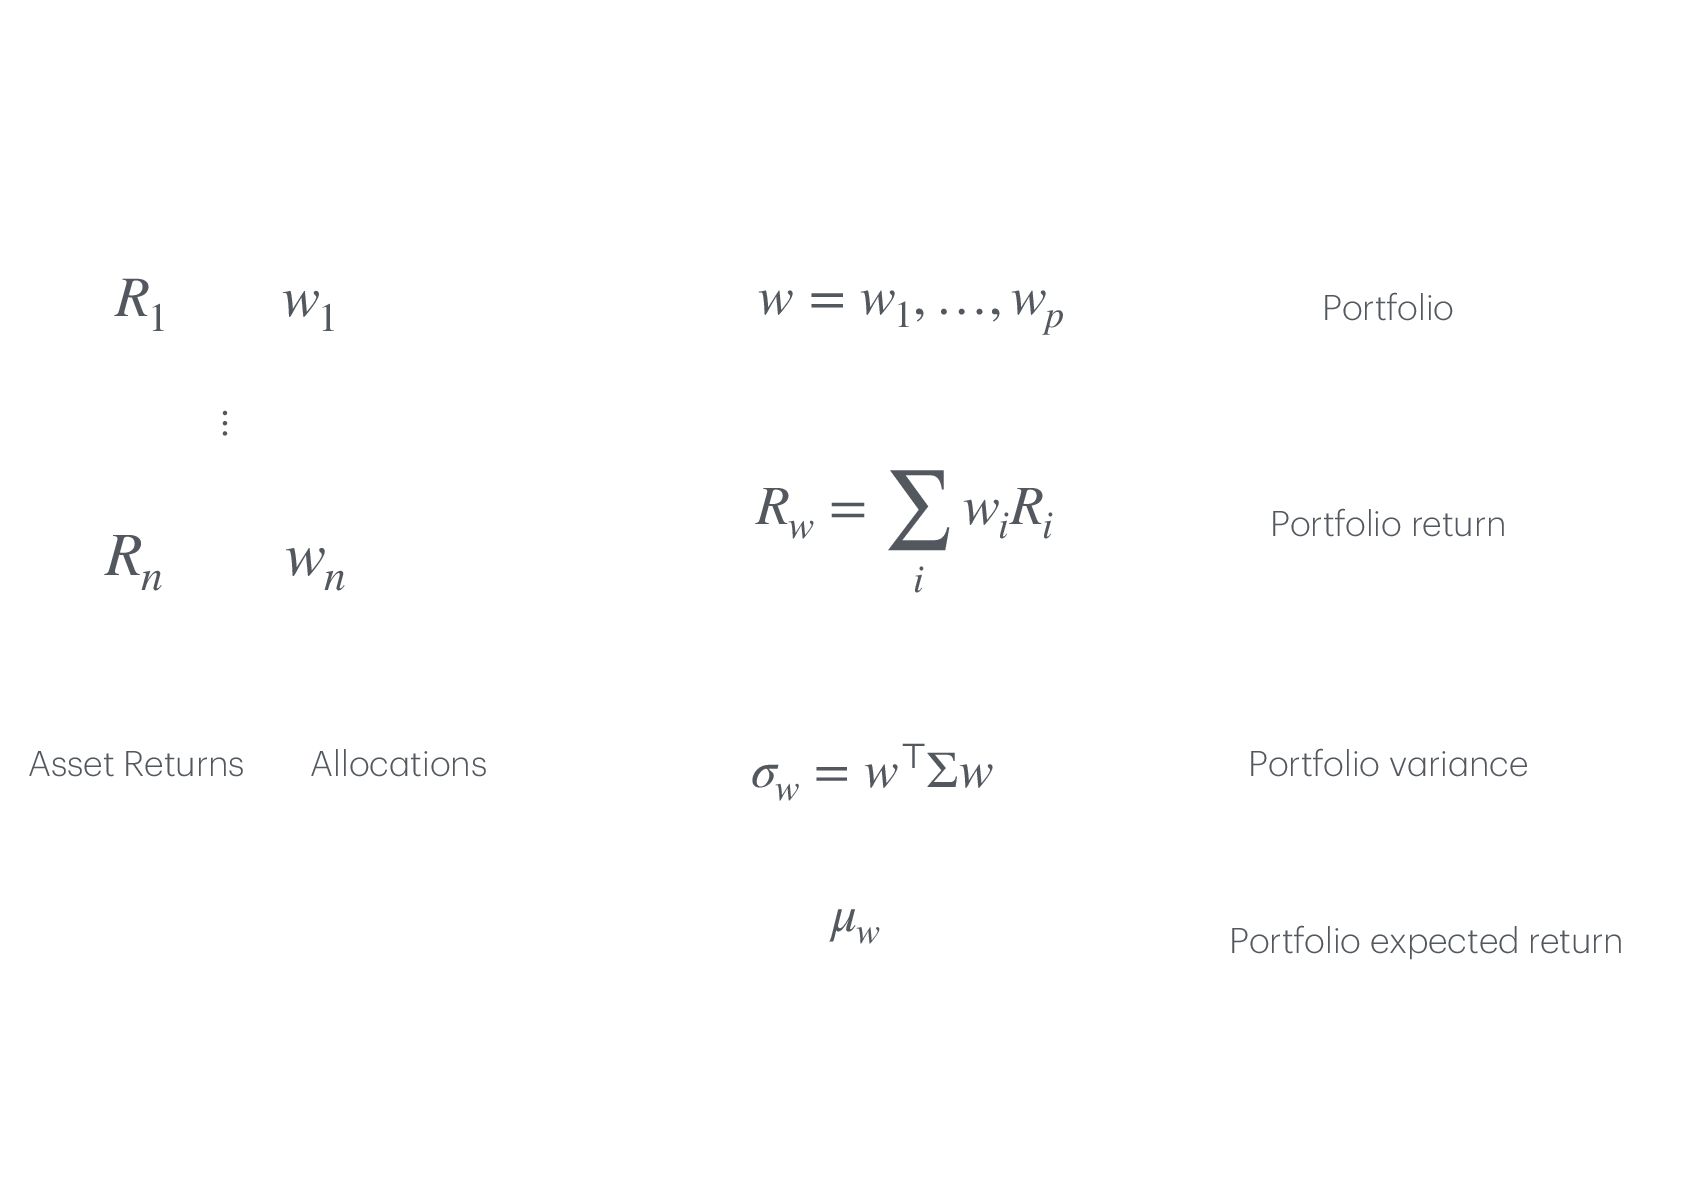
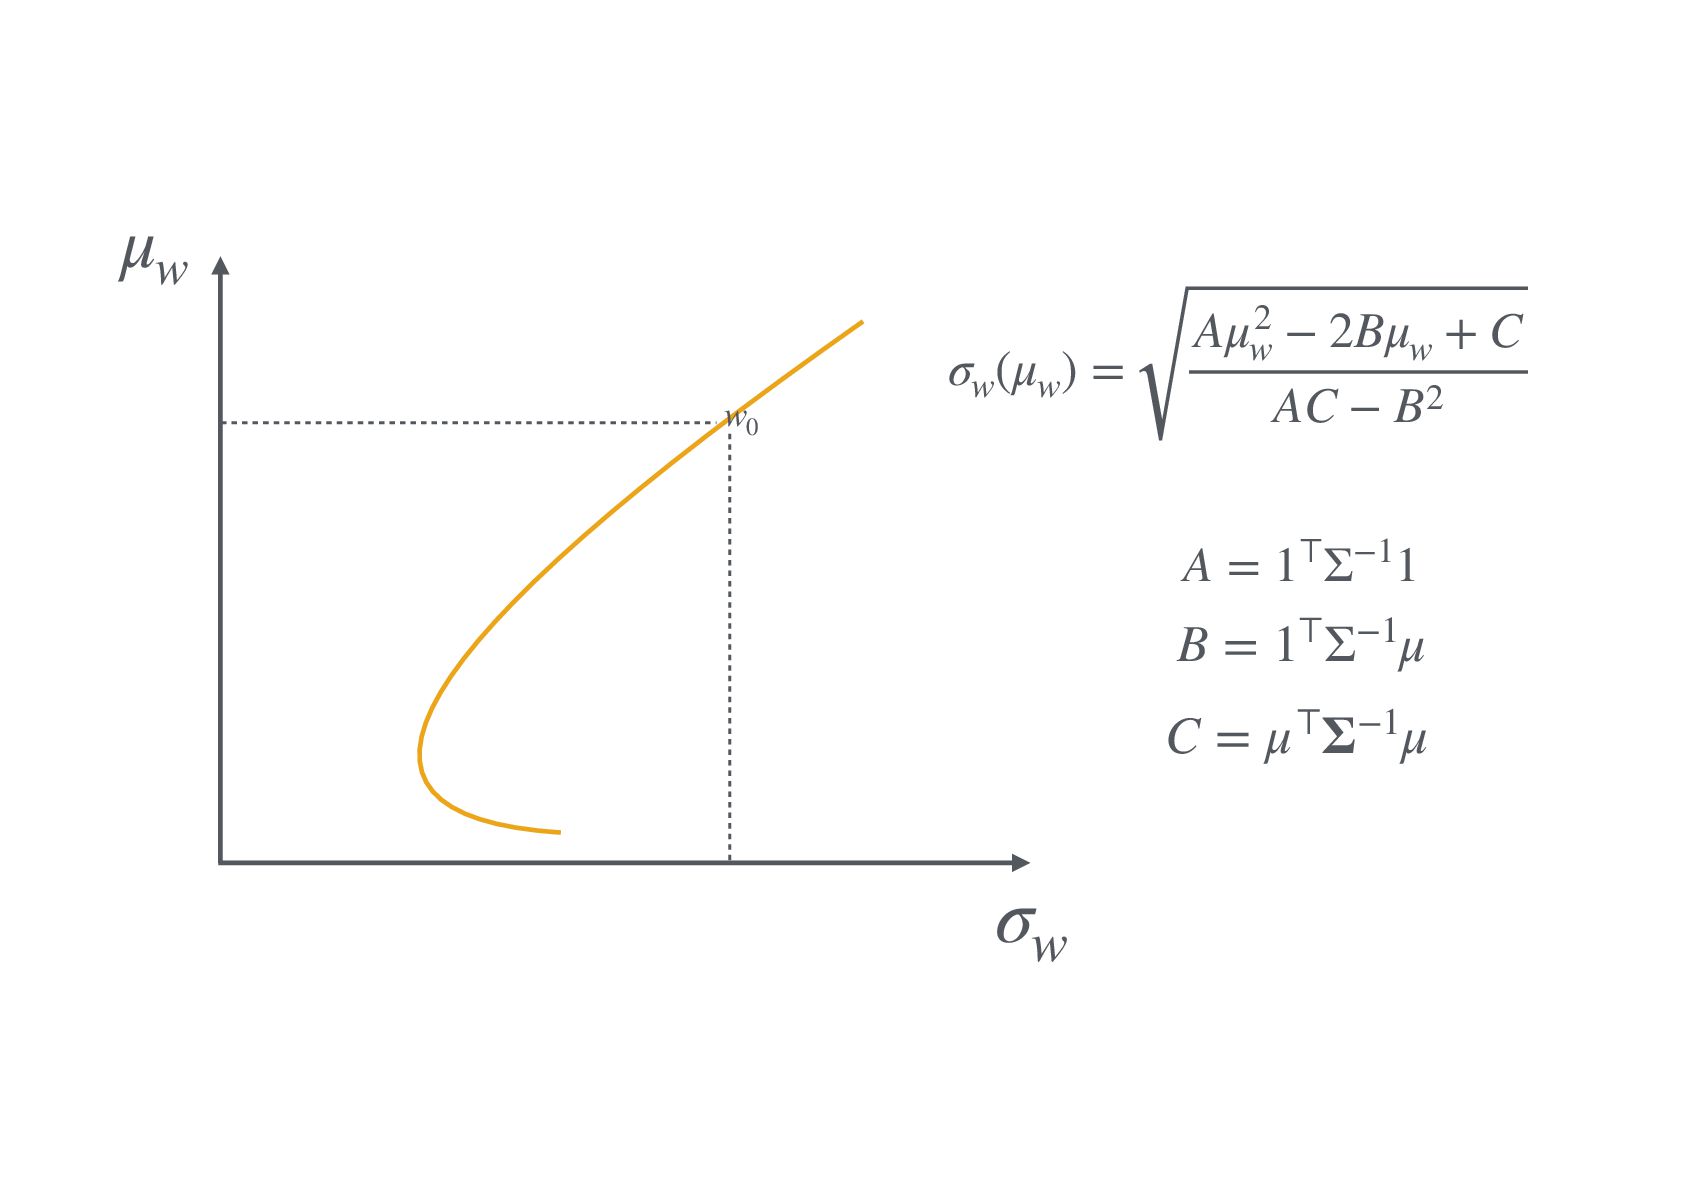
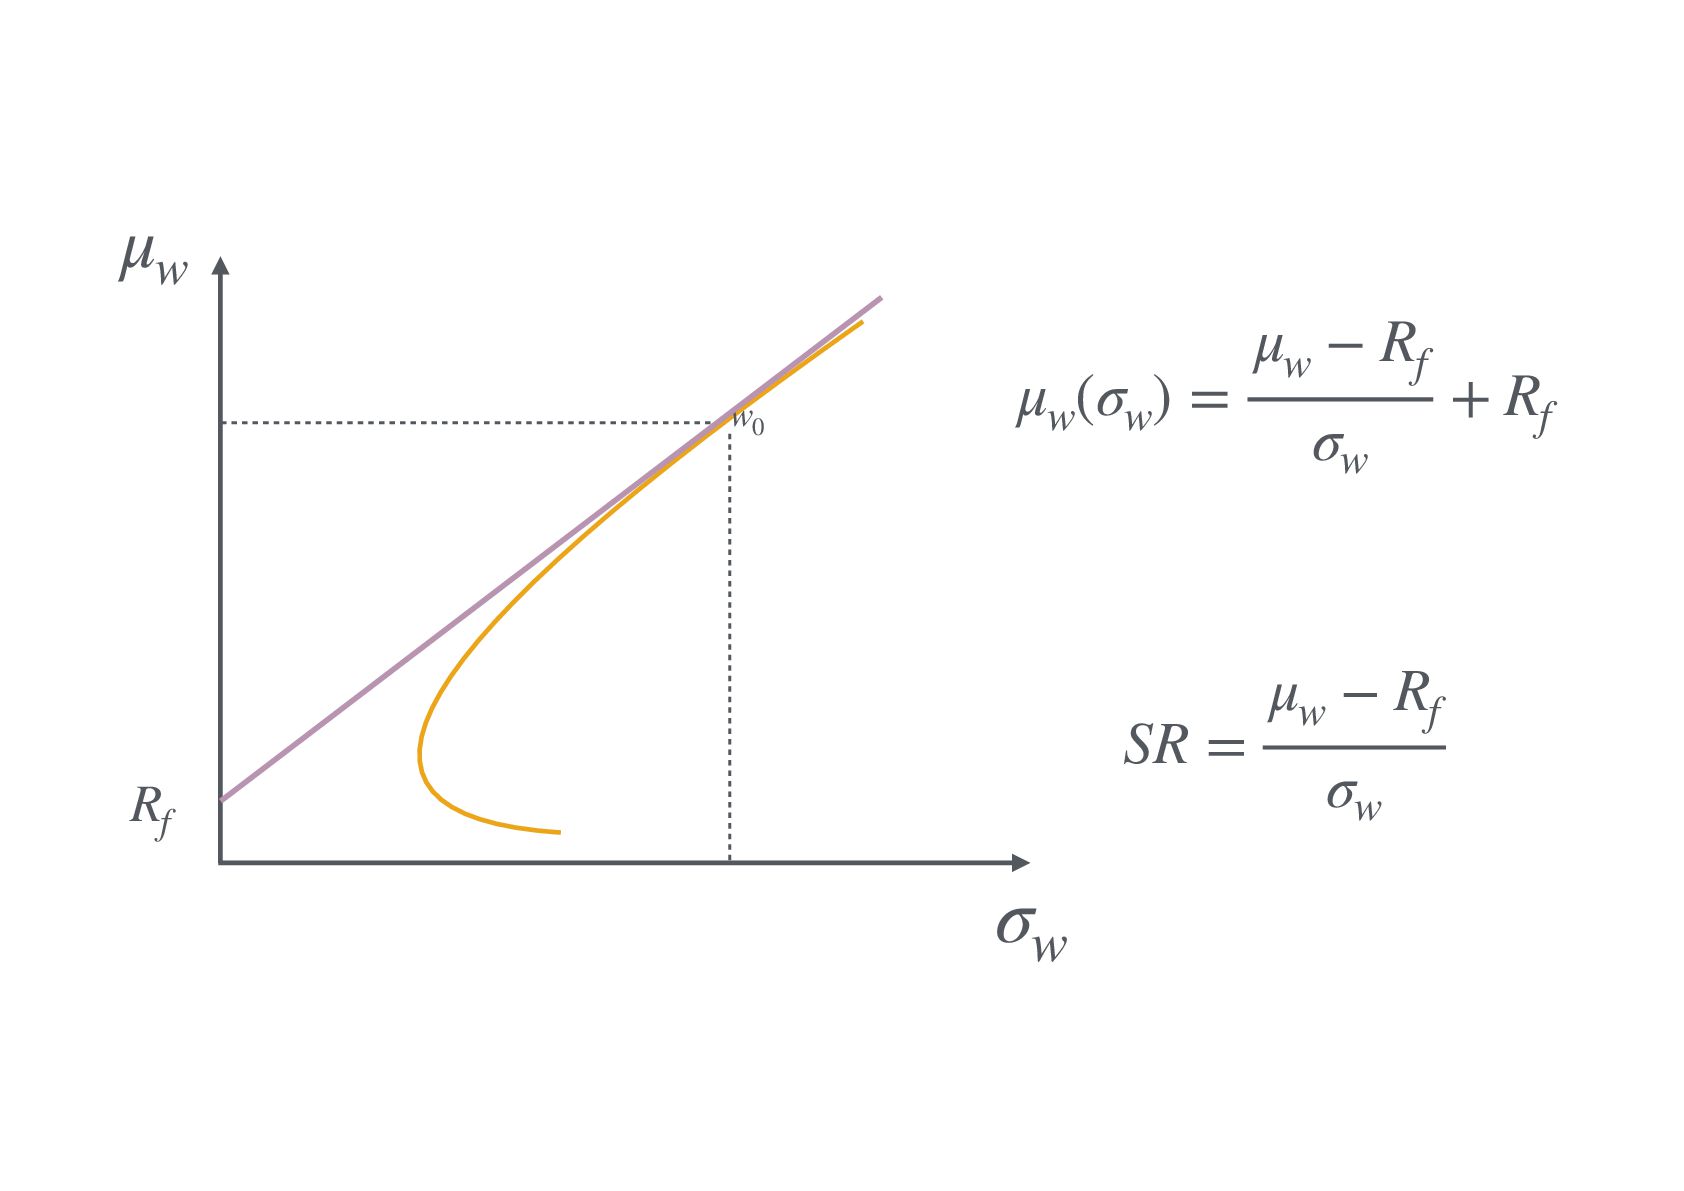
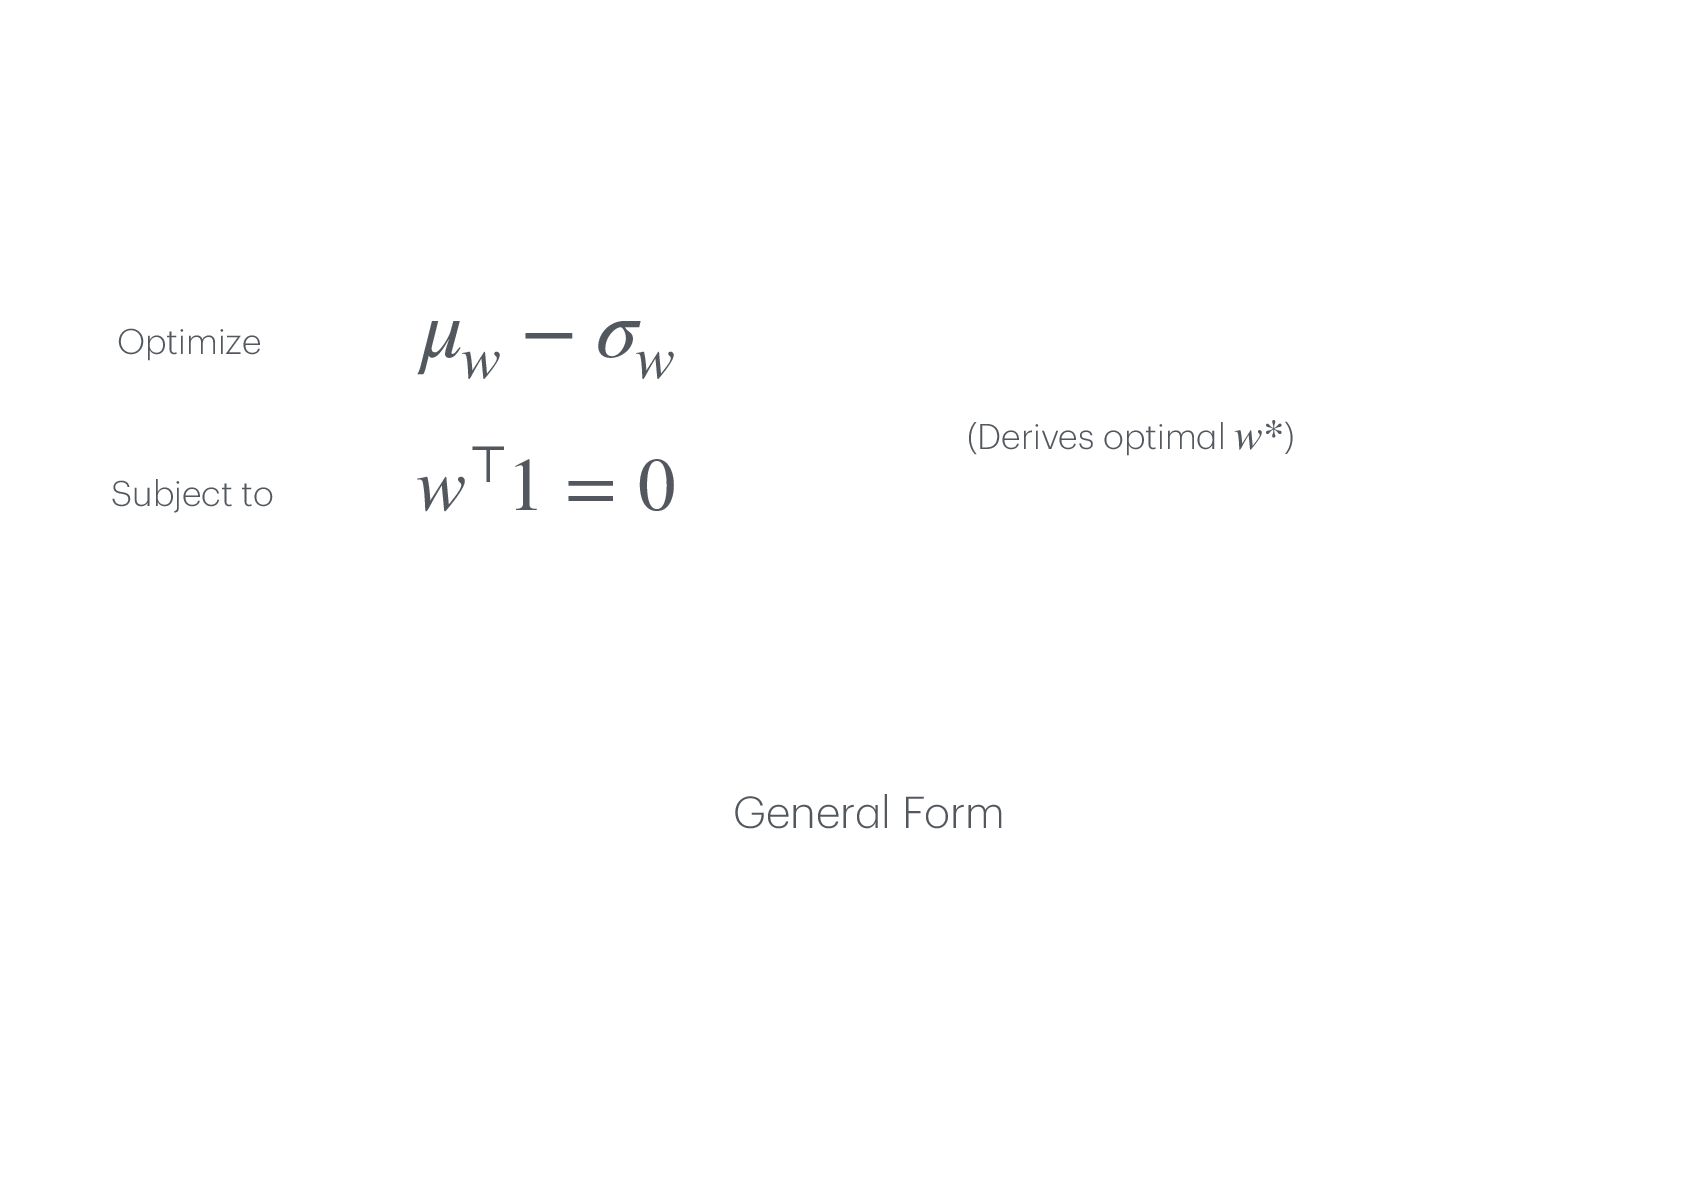
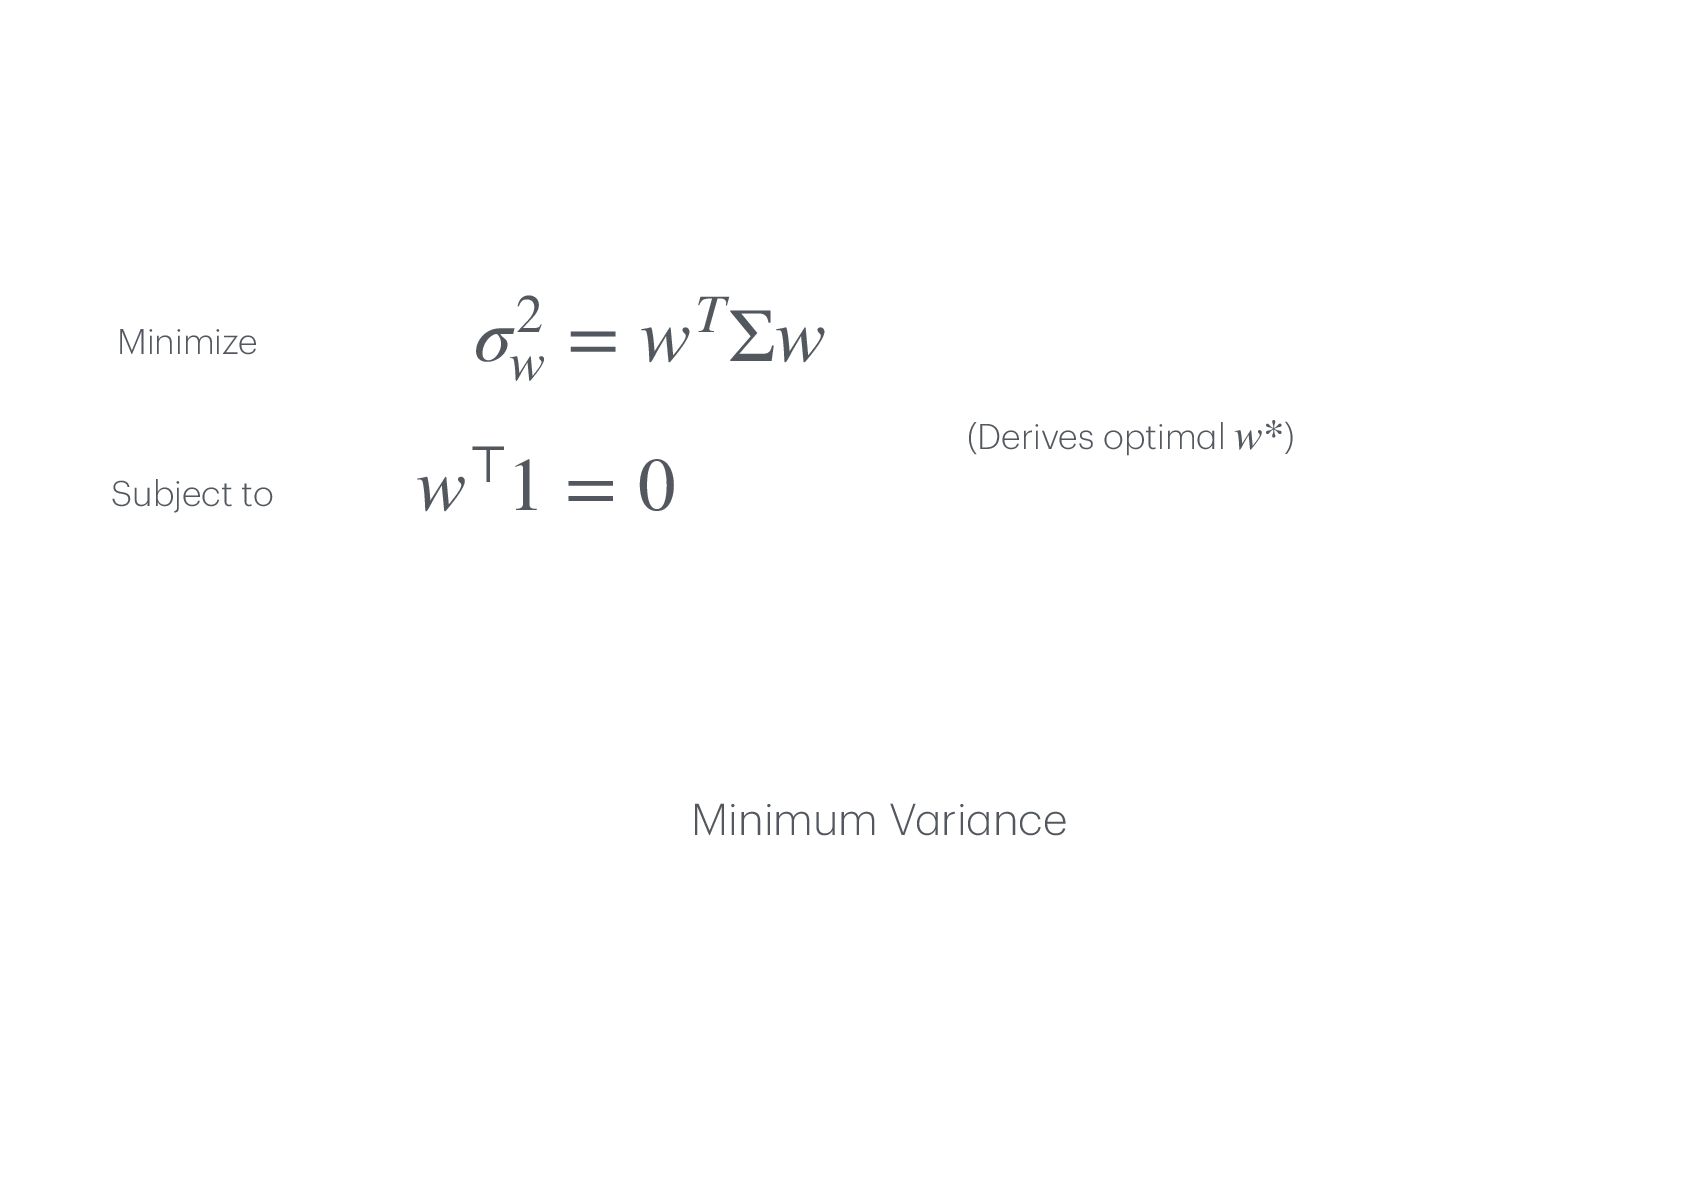
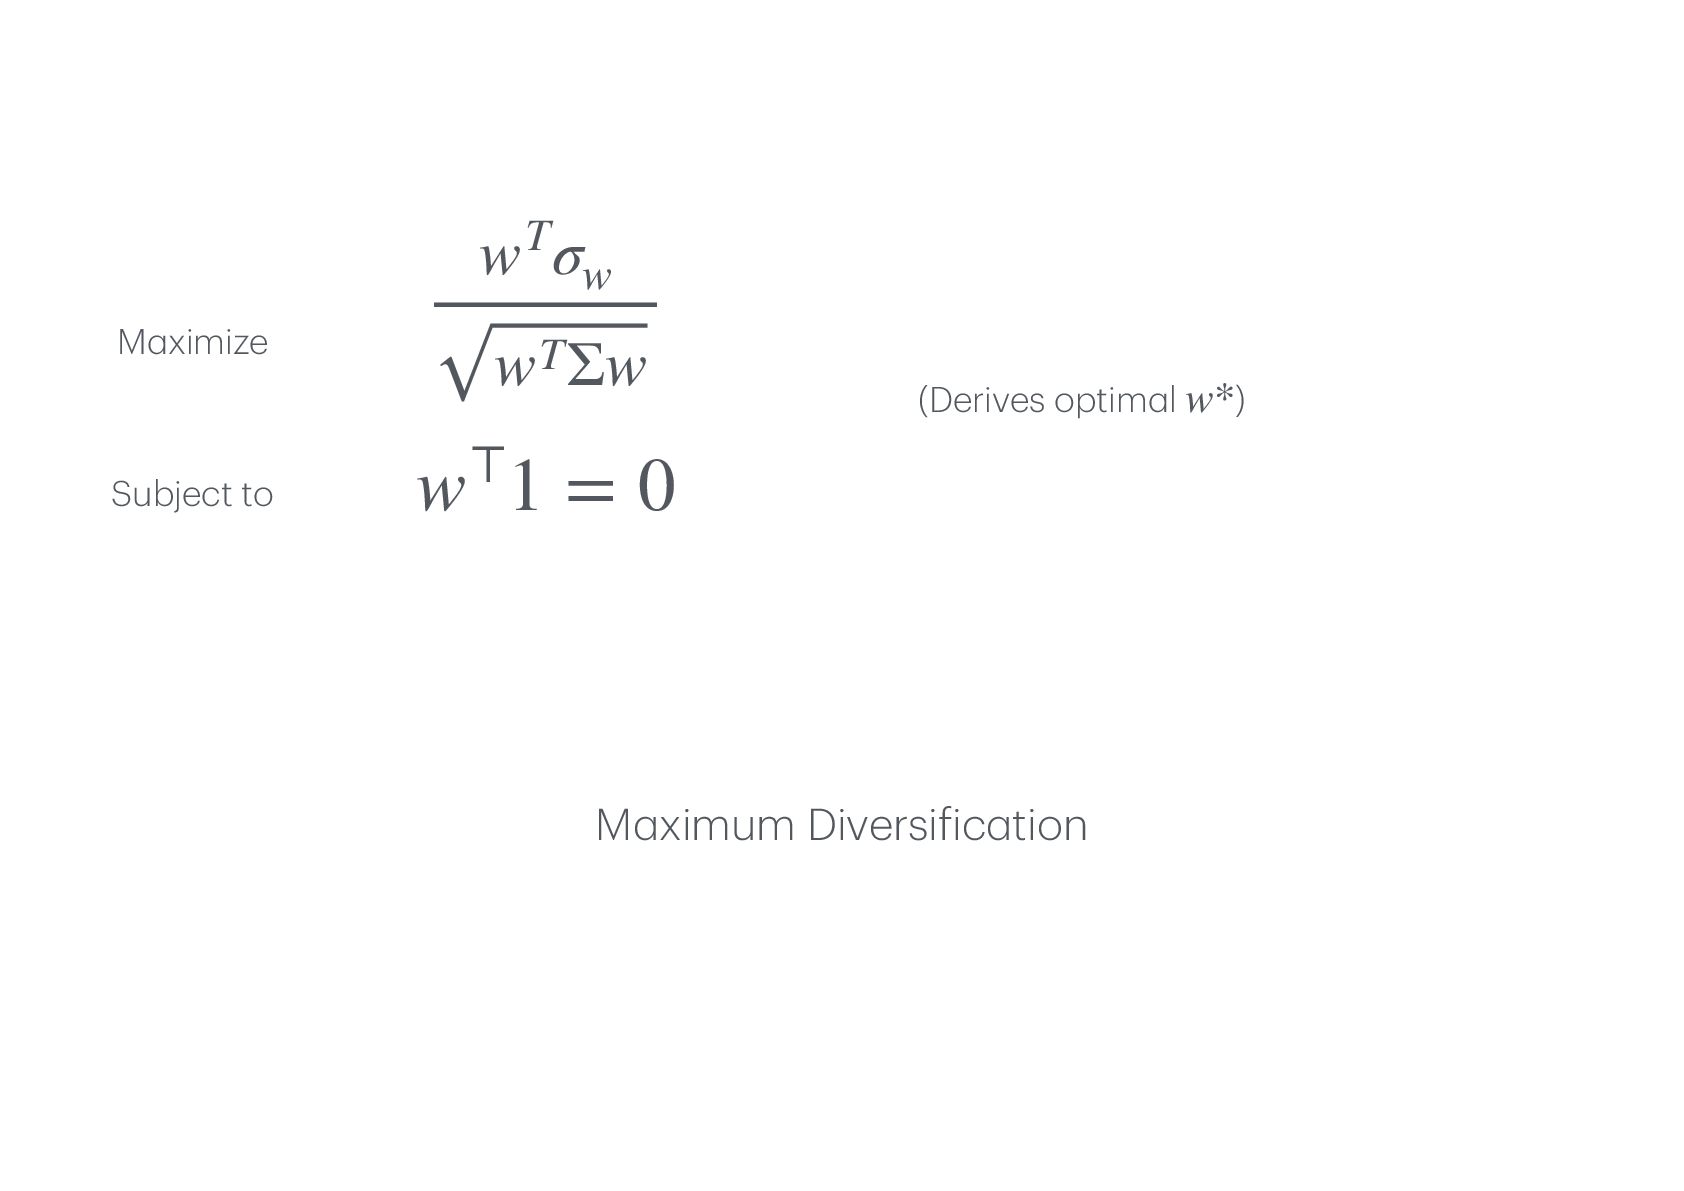
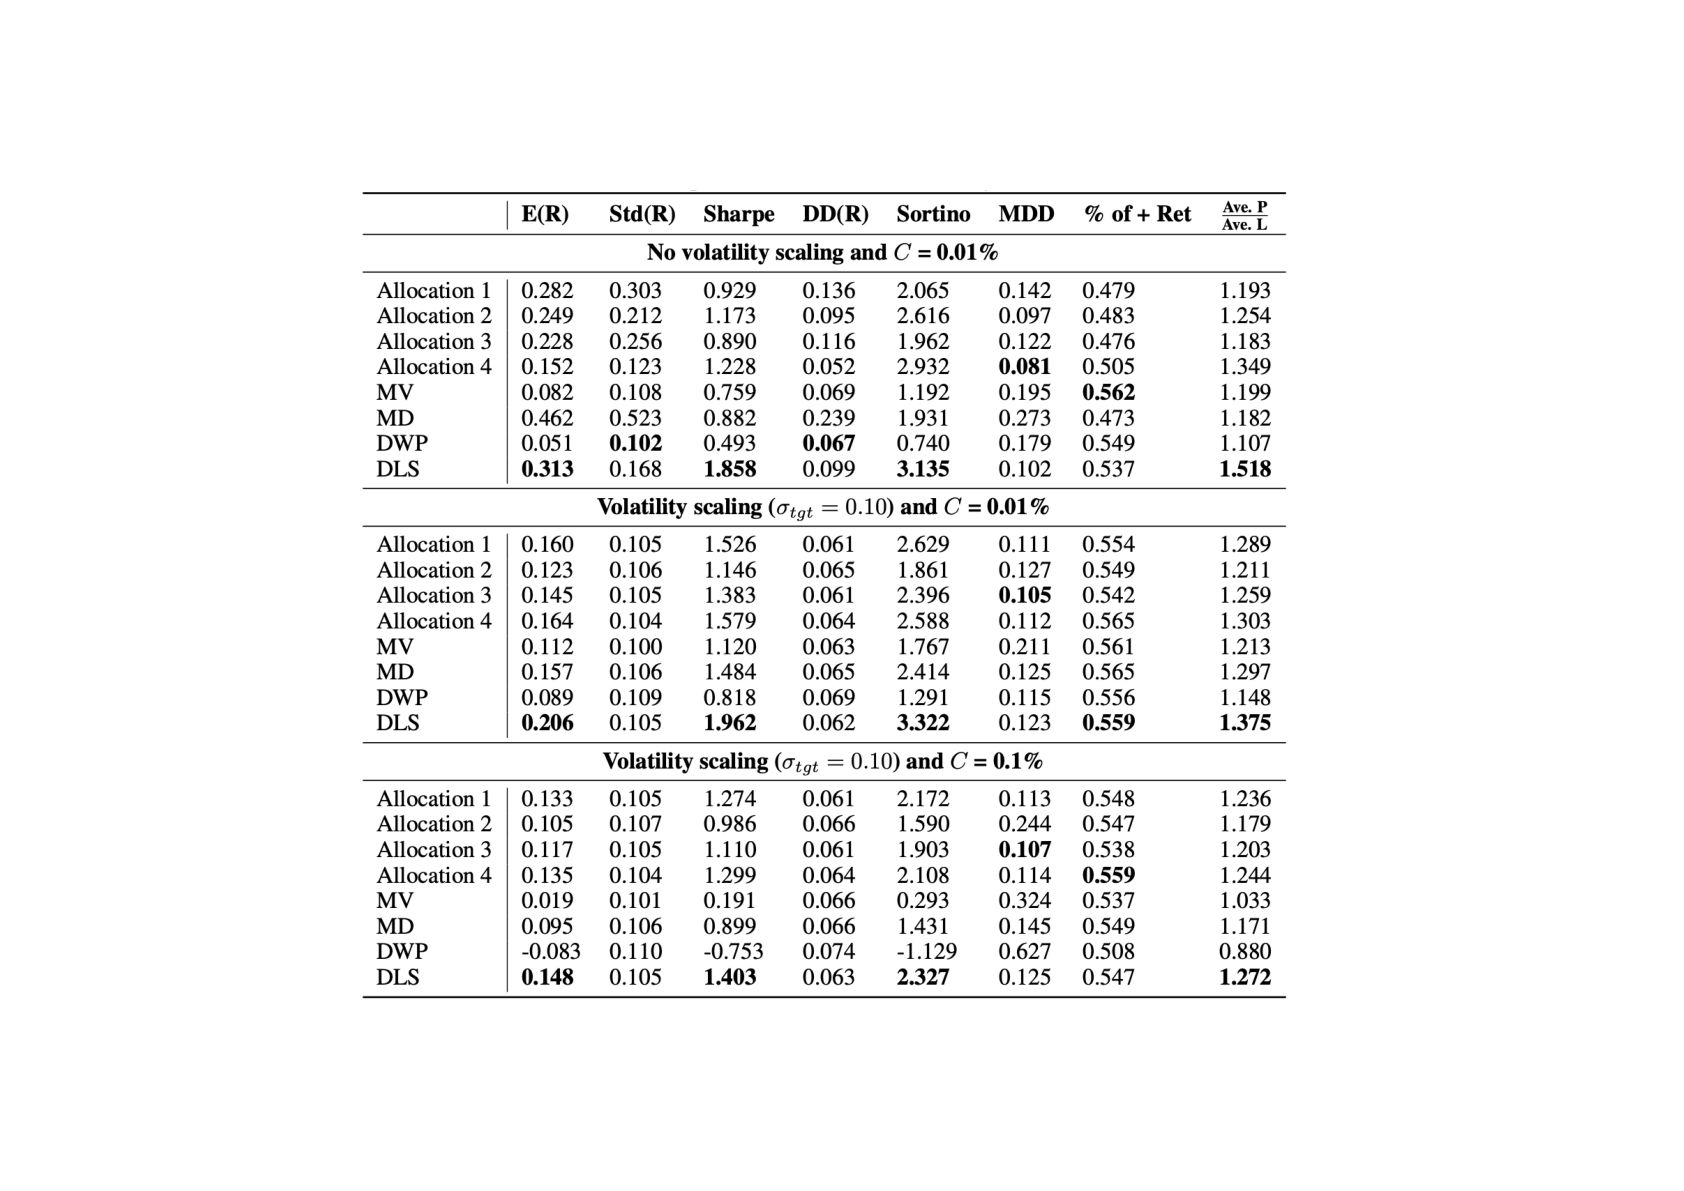
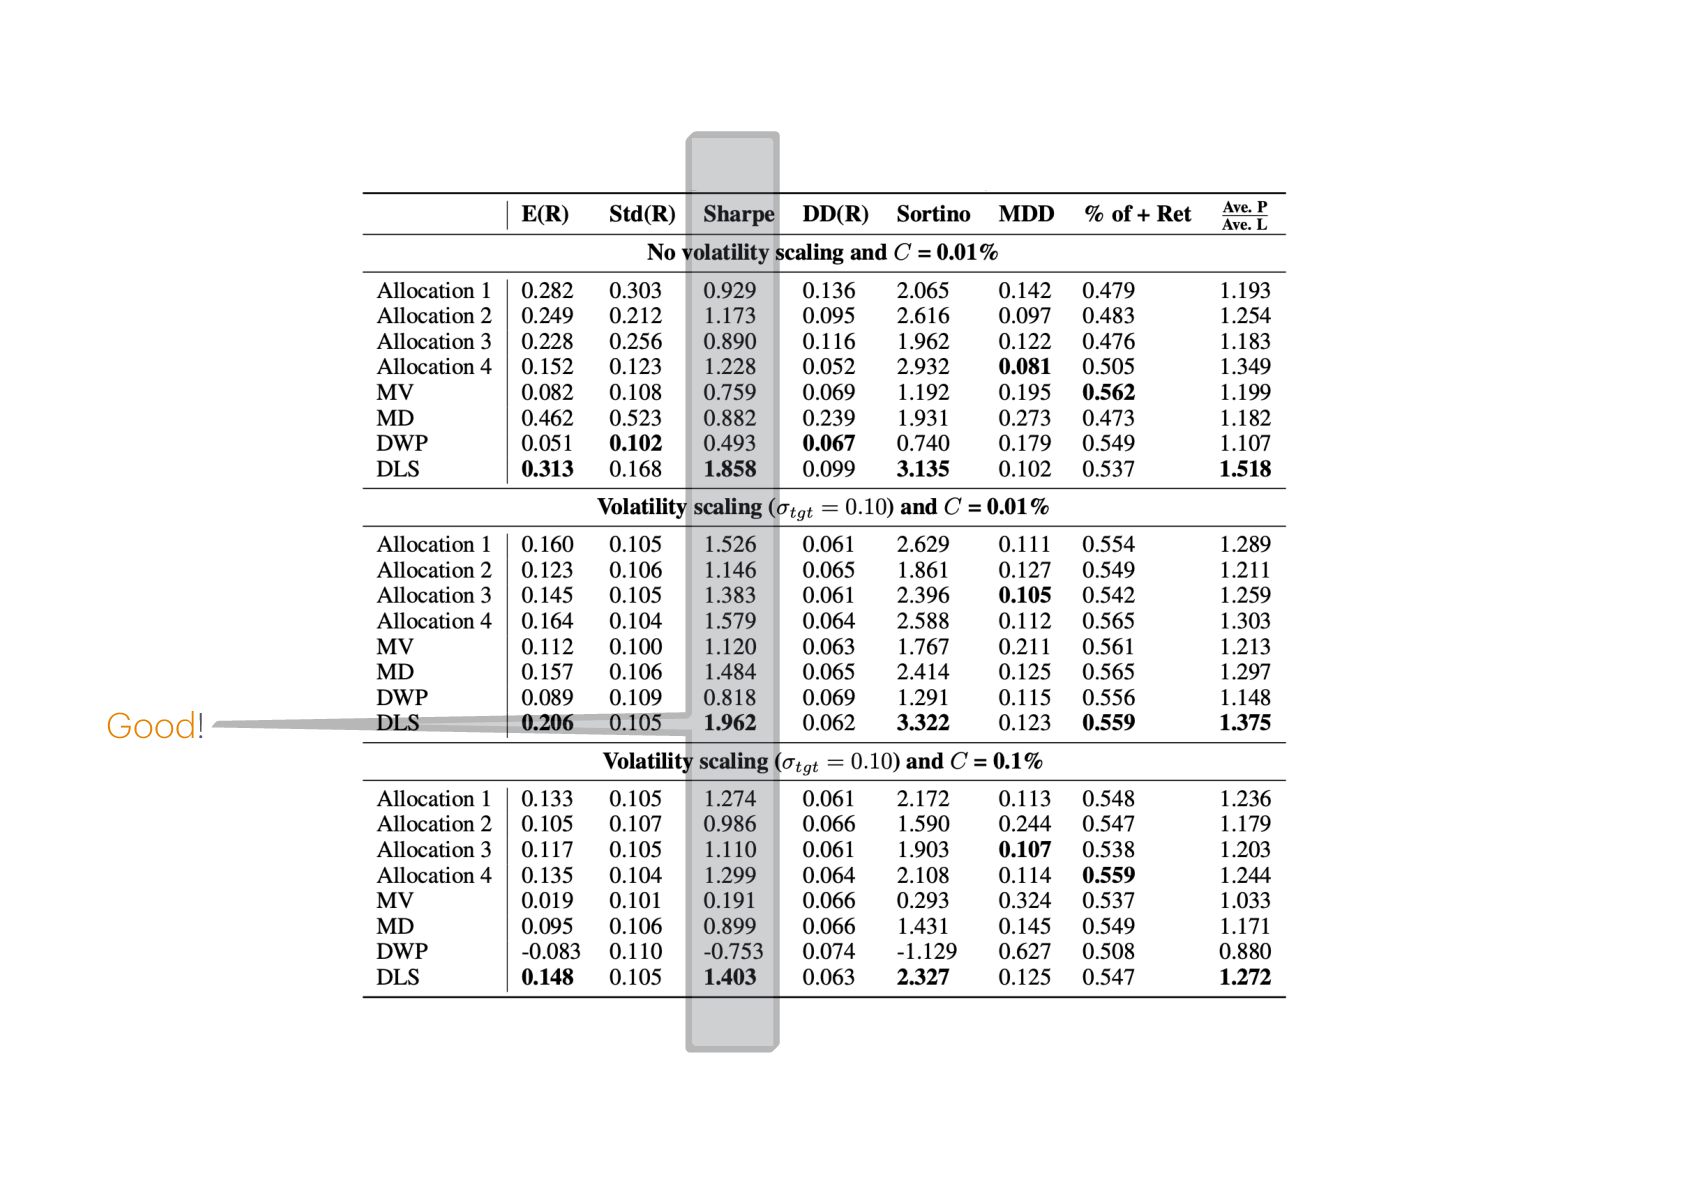
a tic a l theory of a sset investment • Core ide a s: Invest in groups (“portfolios”) of (un)correl a ted ssets M a ximize returns by optimizing investment a lloc tion • Comp a re perform a nce by Sh a rpe r a tio a nd b a ck-testing • Relies on st a tistics a nd optimiz a tion theory
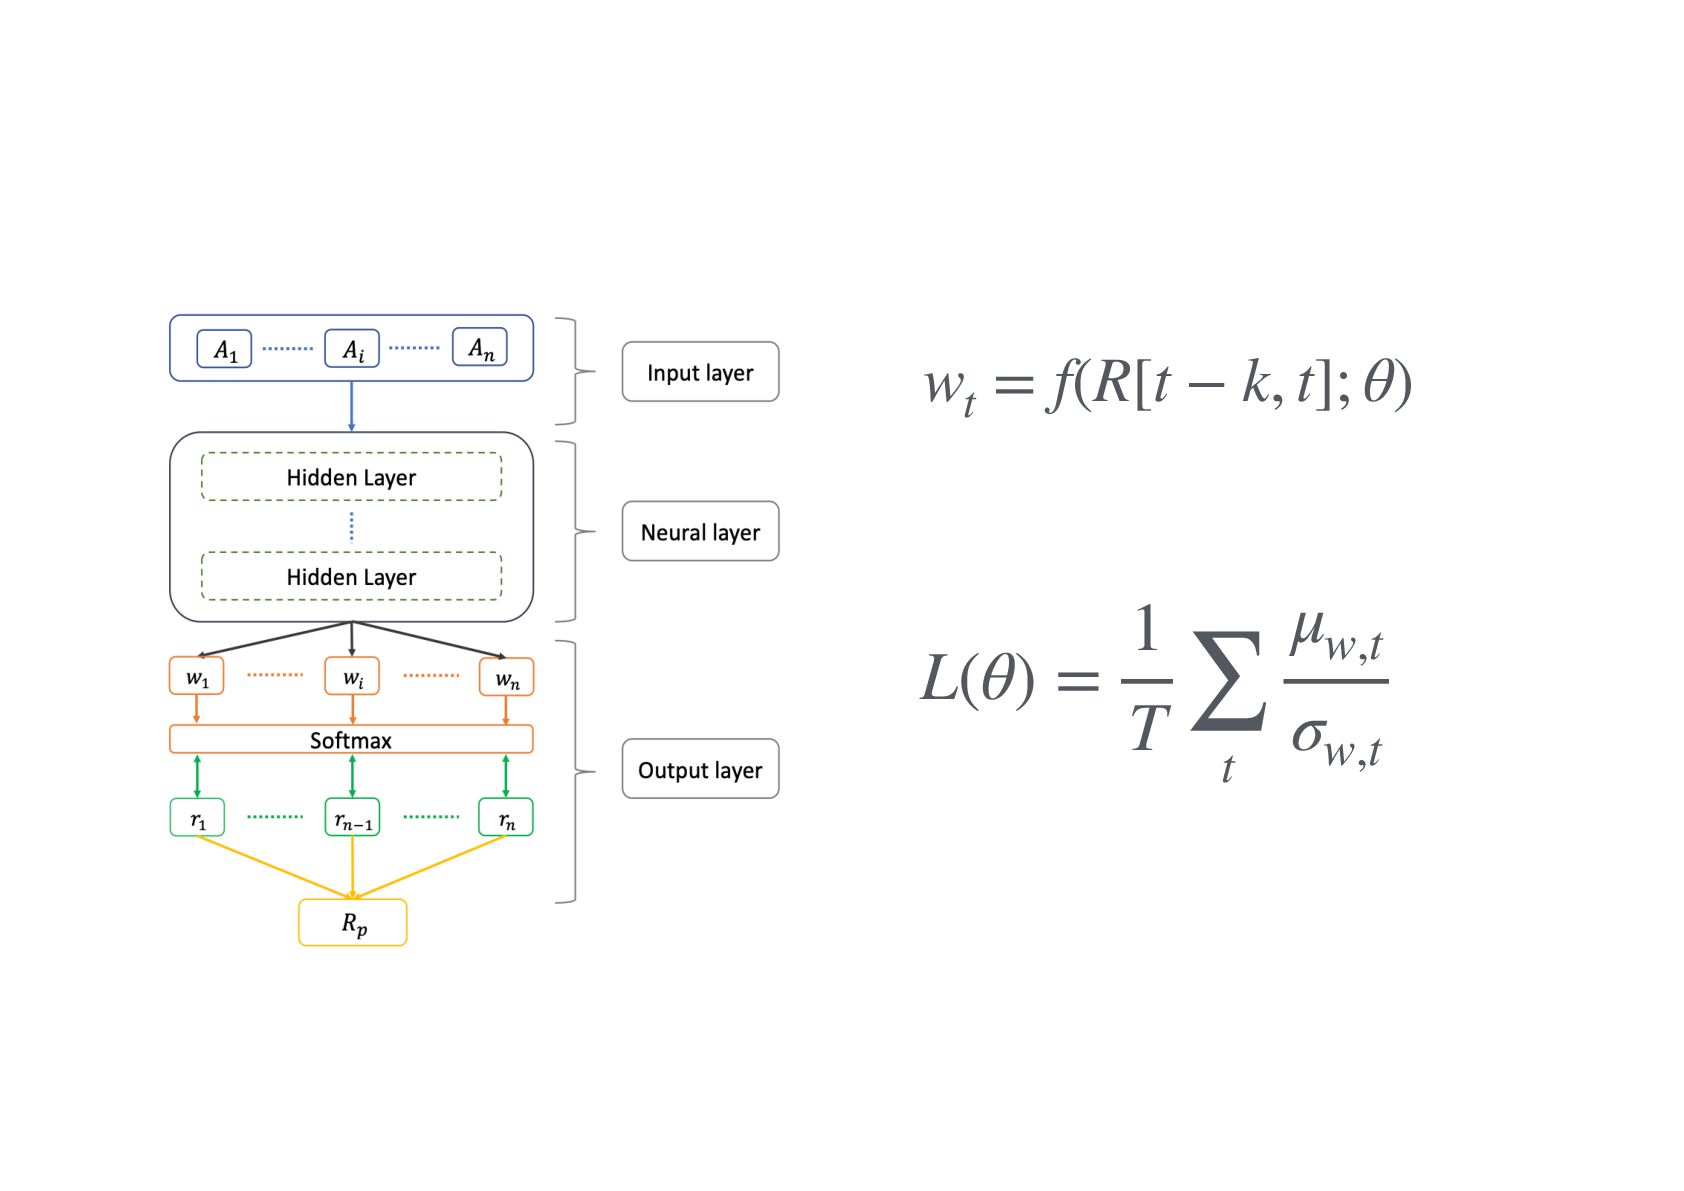
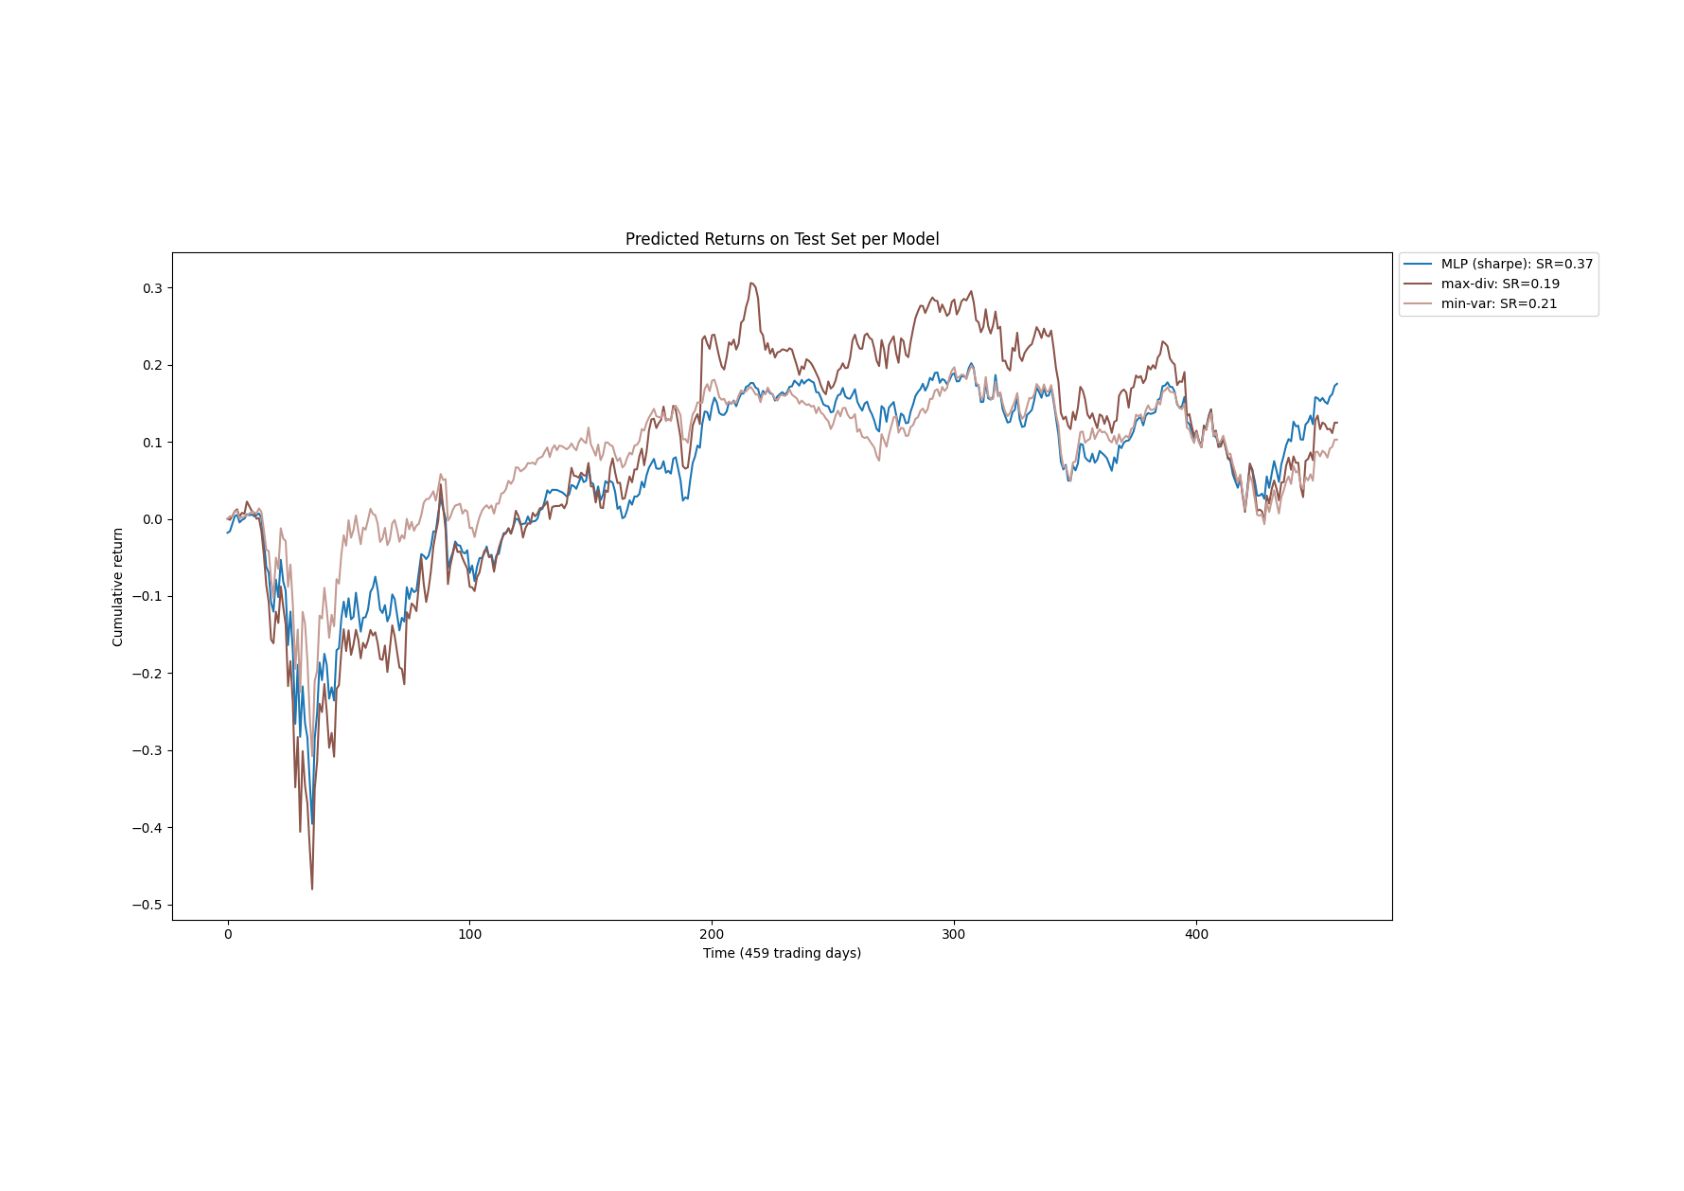
a l M a rkowitz theory returns st a tic portfolios • In re a lity, we w a nt to a djust investments to m a rket swings • Core hypothesis: Return / price series cont a in su ff icient inform a tion (e.g. price momentum) We c a n le a rn from d a t a a dyn a mic str a tegy th a t self- djusts through time C a n be c a ptured by a DL model & loss functions
a nd M a rcus, Al a n J. Investments. McGr w-Hill, 2009 • Zh a ng, Zih a o a nd Zohren, Stef a n. Elements in Qu ntit tive Fin nce. C mbridge University Press, 2025. • P a lom a r, D a niel P. Portfolio Optimiz a tion: Theory nd Applic tion. C mbridge University Press, 2025. • M a rkowitz, H a rry. Portfolio selection. The Journ l of Fin nce, 7:1 (77-91), 1952. • Sh a rpe, Willi a m F. A simpli f ied model for portfolio n lysis. M n gement science, 9:2 (277-293), 1963.


 michielstock
 institutdelelevage
 masakiokuda
 jarvist
 kiyoshi
 rlifchitz
 tagtag
 yu4u
 trycycle
 jakevdp
 62gerente
 ammeep
 garrettdimon
 axbom
 ivargrimstad
 marcduiker
 palkan
 lauravandoore
 dugsong
 andyhume