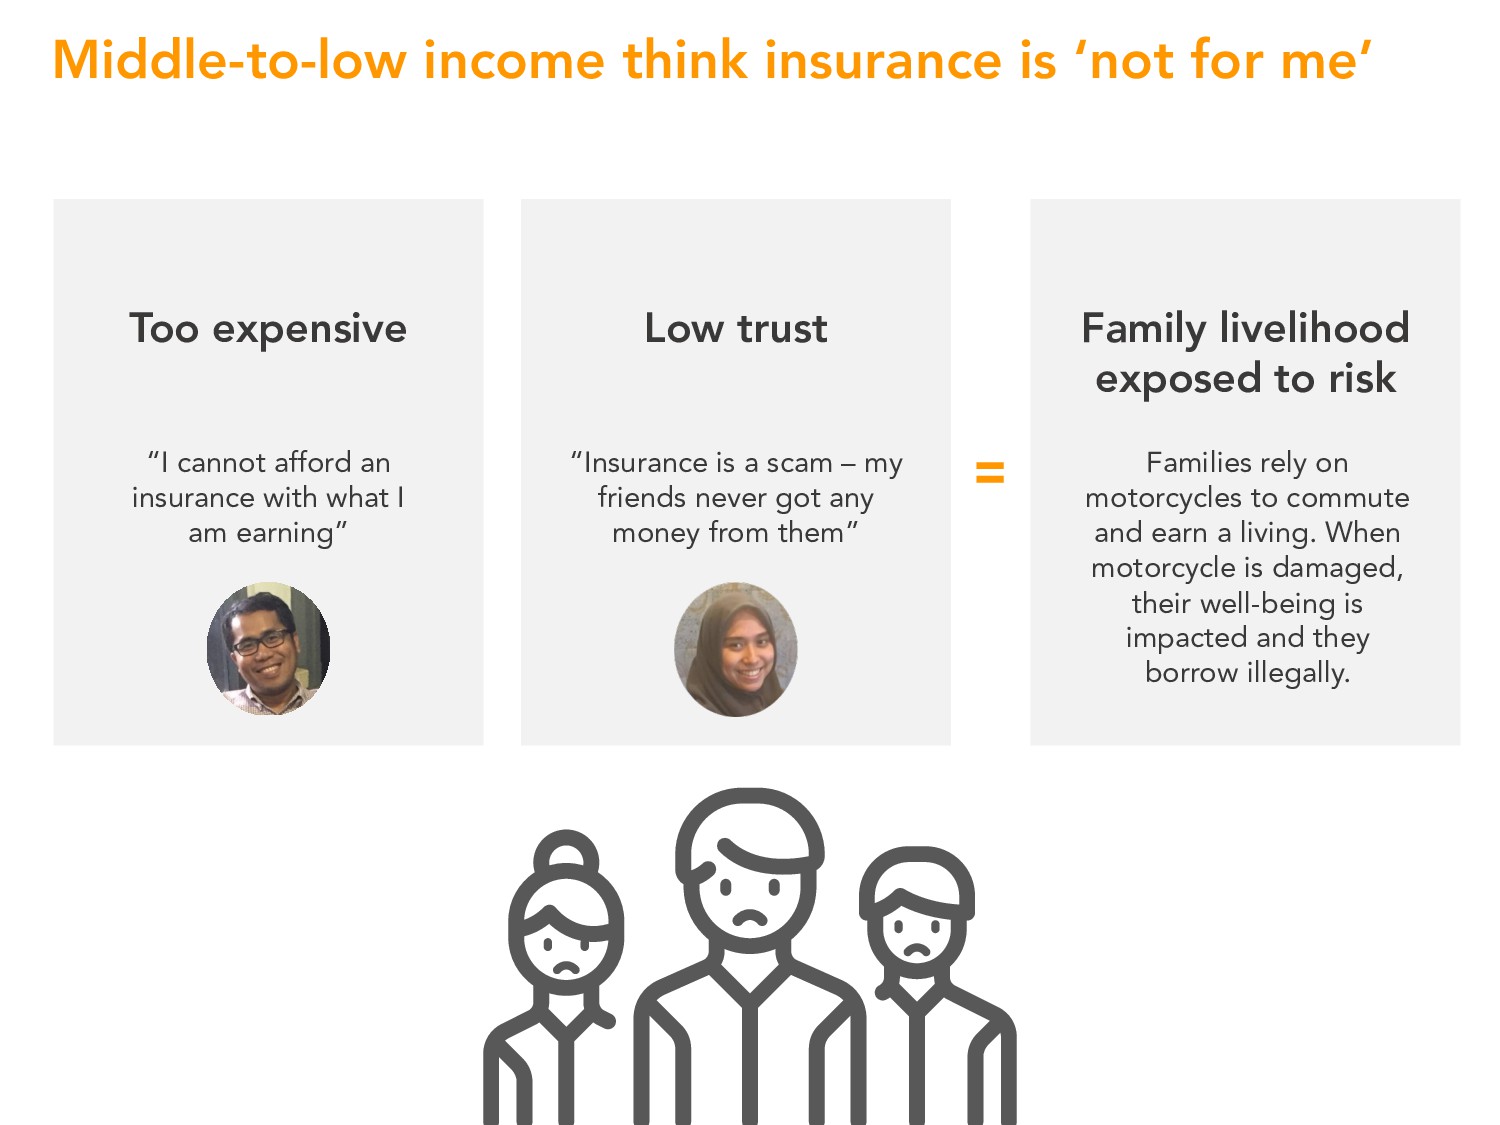
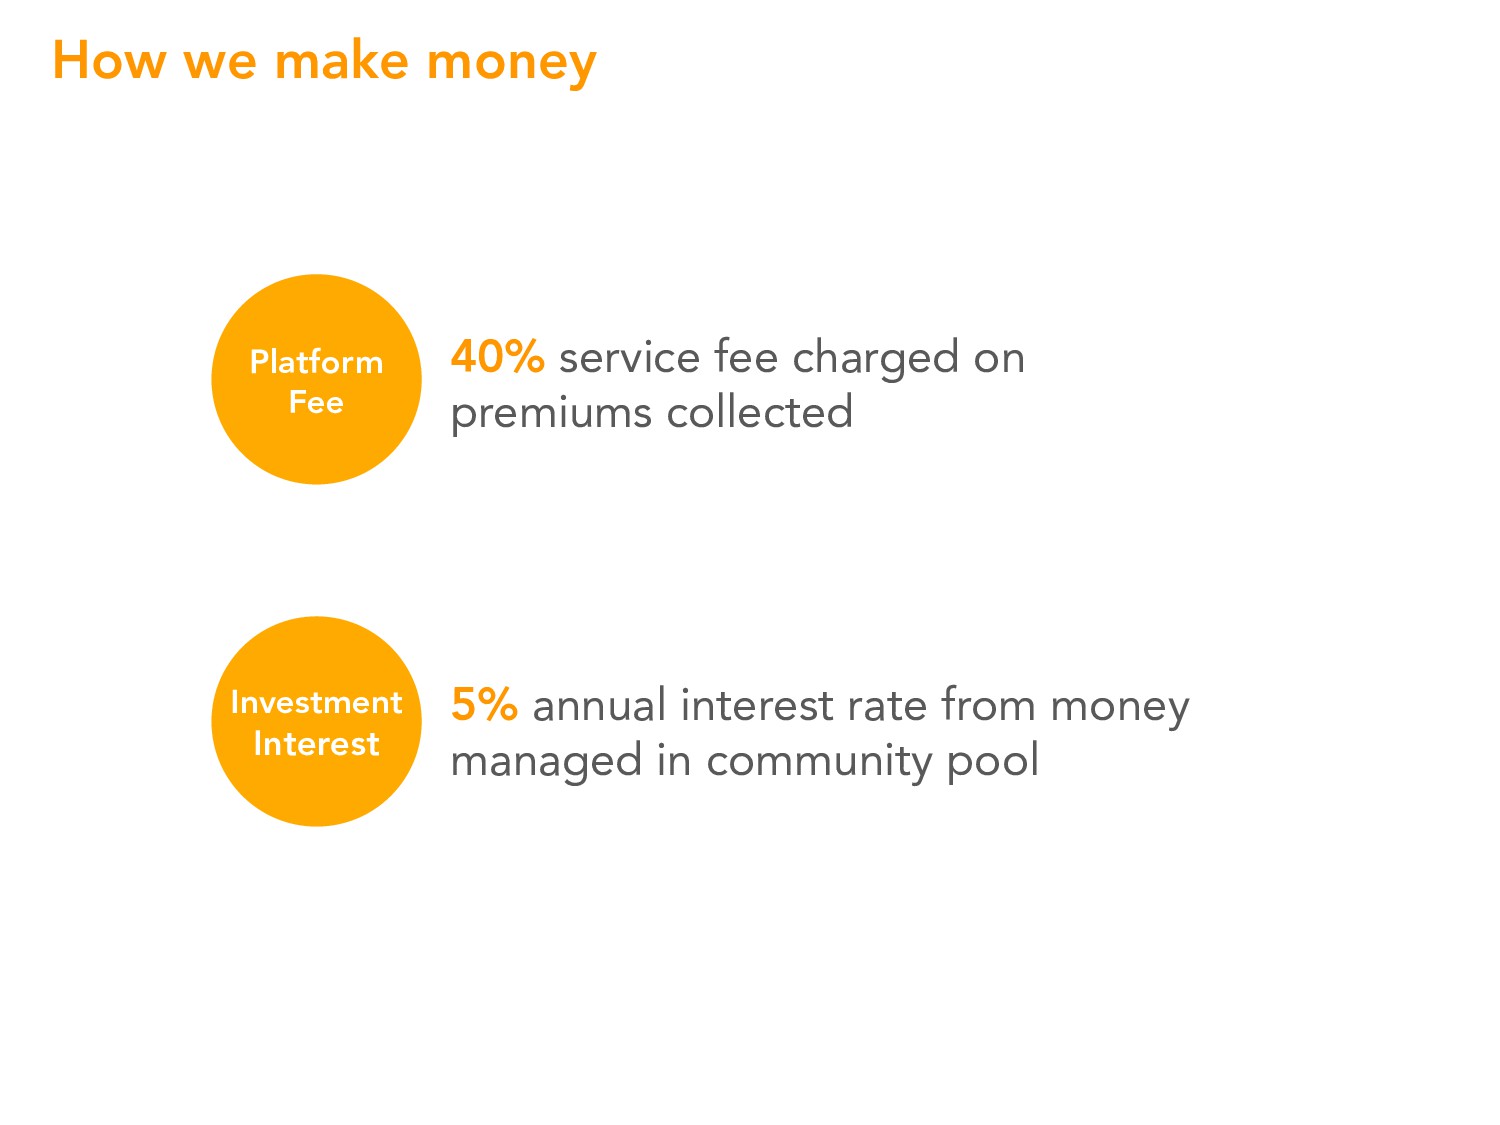
Low trust Family livelihood exposed to risk “I cannot afford an insurance with what I am earning” “Insurance is a scam – my friends never got any money from them” Families rely on motorcycles to commute and earn a living. When motorcycle is damaged, their well-being is impacted and they borrow illegally.
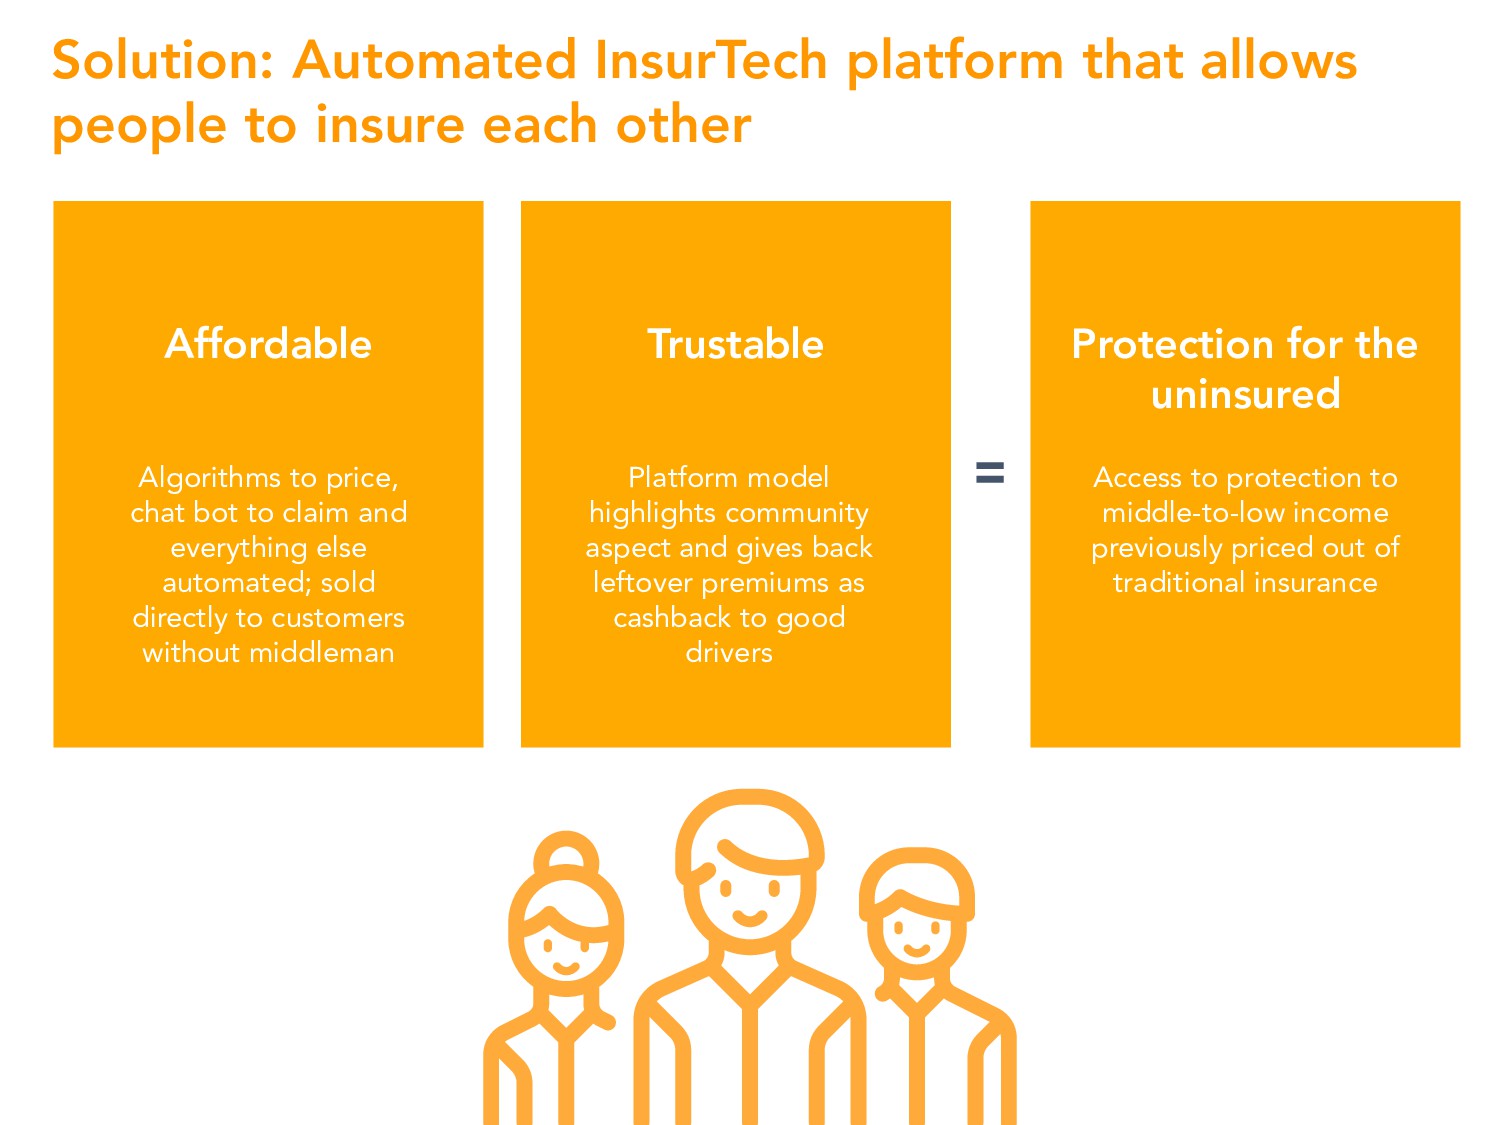
other Affordable Trustable Protection for the uninsured Algorithms to price, chat bot to claim and everything else automated; sold directly to customers without middleman Platform model highlights community aspect and gives back leftover premiums as cashback to good drivers Access to protection to middle-to-low income previously priced out of traditional insurance
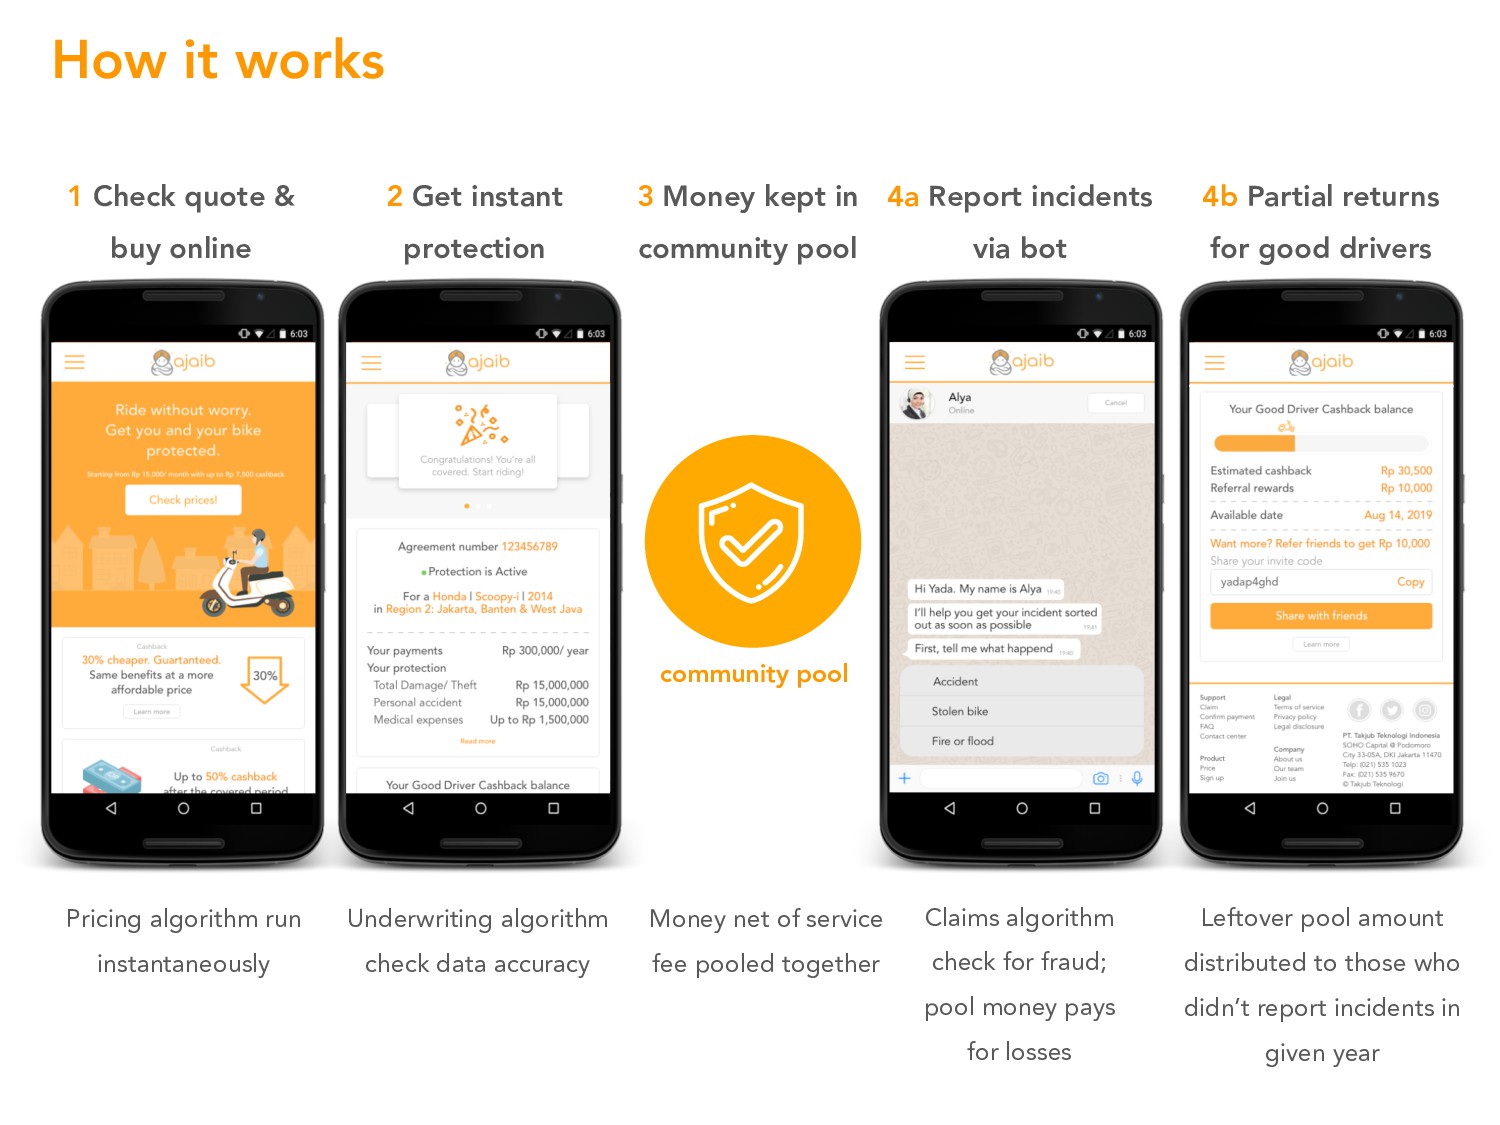
Get instant protection 3 Money kept in community pool community pool 4a Report incidents via bot 4b Partial returns for good drivers Pricing algorithm run instantaneously Underwriting algorithm check data accuracy Money net of service fee pooled together Claims algorithm check for fraud; pool money pays for losses Leftover pool amount distributed to those who didn’t report incidents in given year
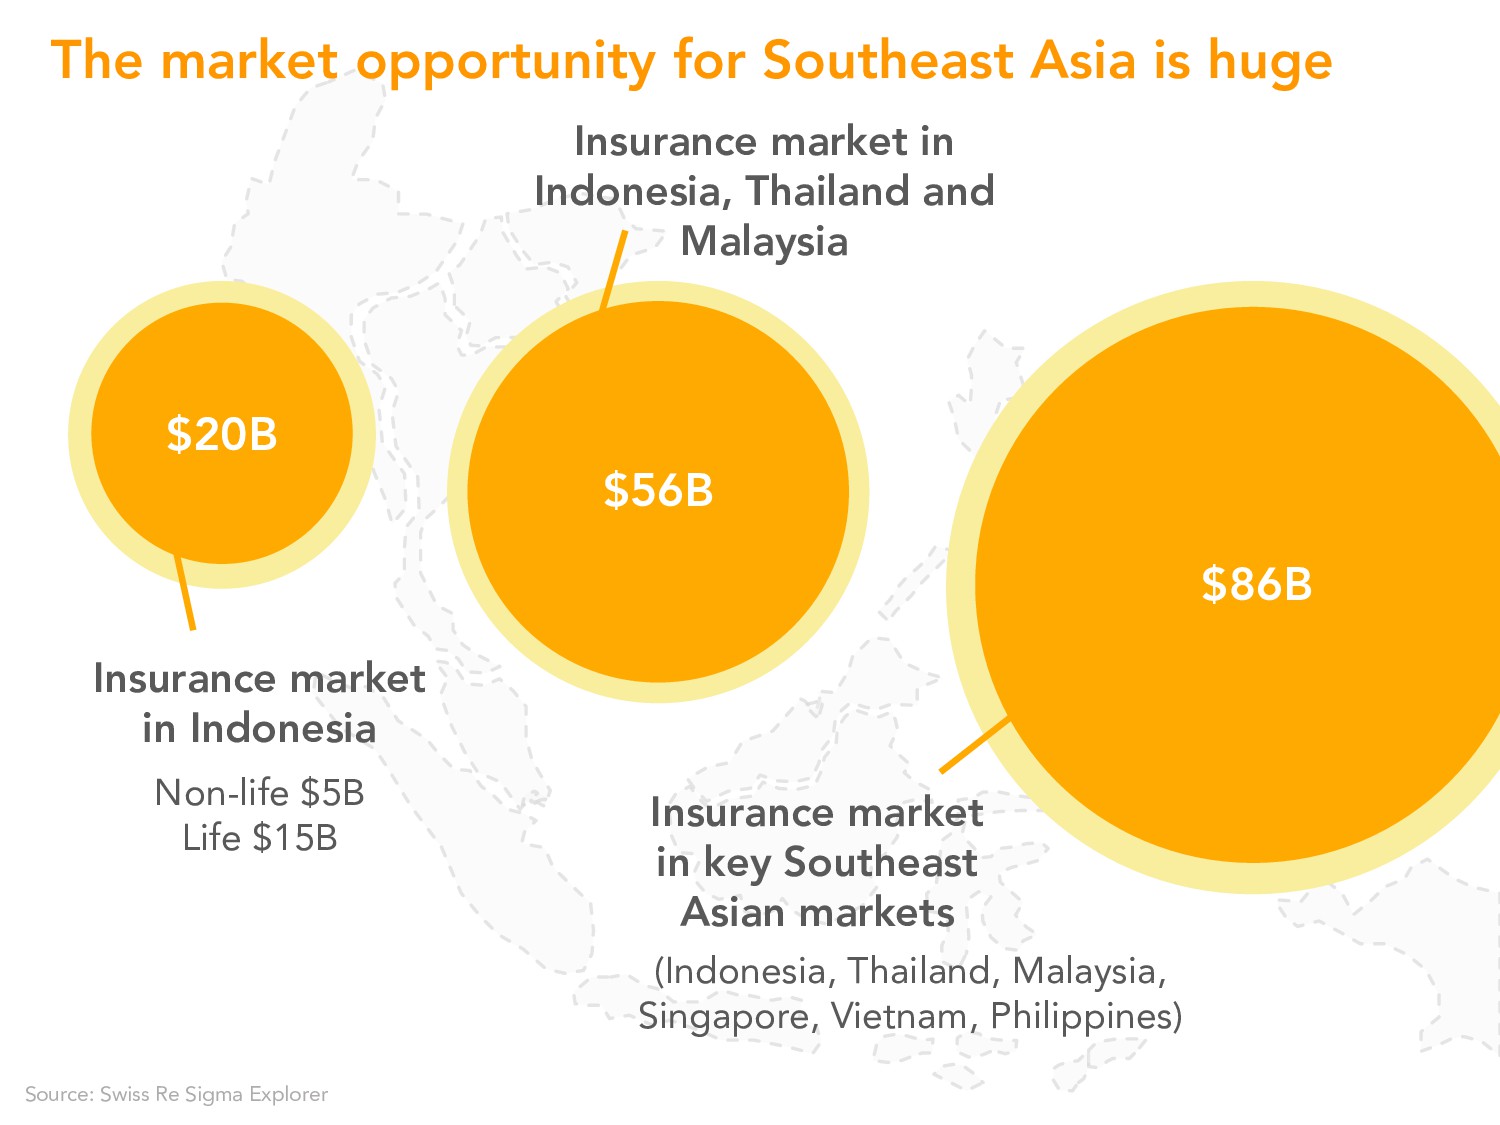
Re Sigma Explorer Insurance market in Indonesia Insurance market in Indonesia, Thailand and Malaysia Insurance market in key Southeast Asian markets Non-life $5B Life $15B (Indonesia, Thailand, Malaysia, Singapore, Vietnam, Philippines) $20B $56B $86B
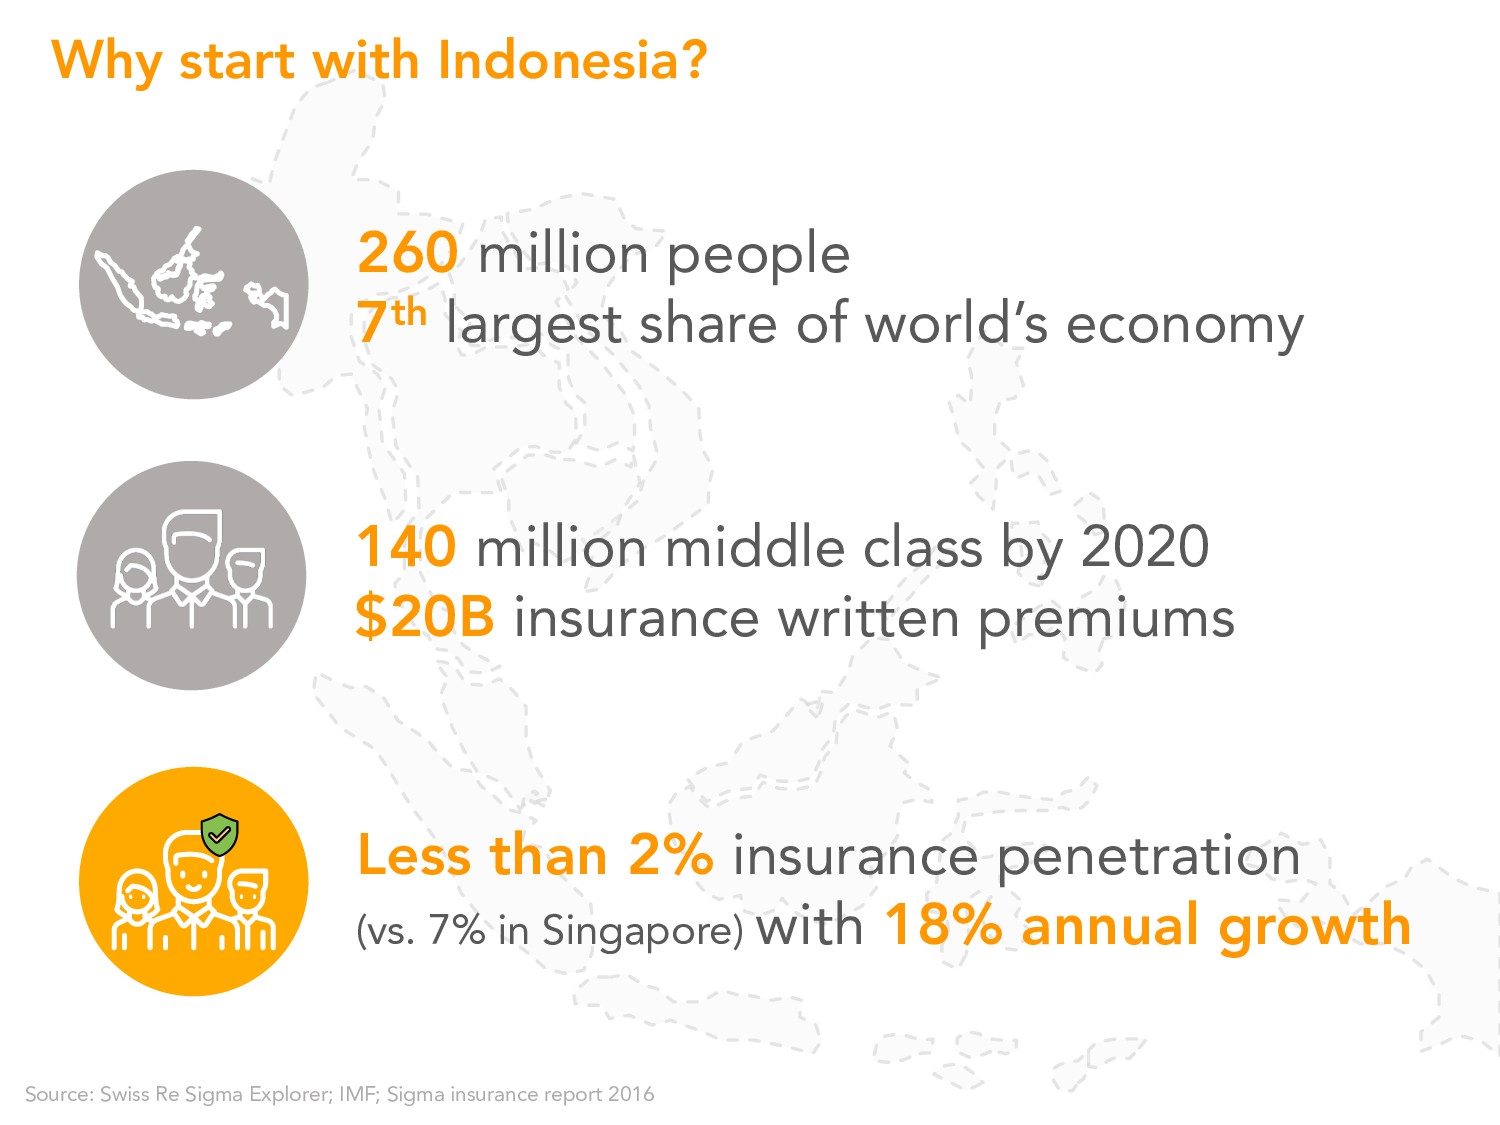
than 2% insurance penetration (vs. 7% in Singapore) with 18% annual growth Why start with Indonesia? 140 million middle class by 2020 $20B insurance written premiums Source: Swiss Re Sigma Explorer; IMF; Sigma insurance report 2016
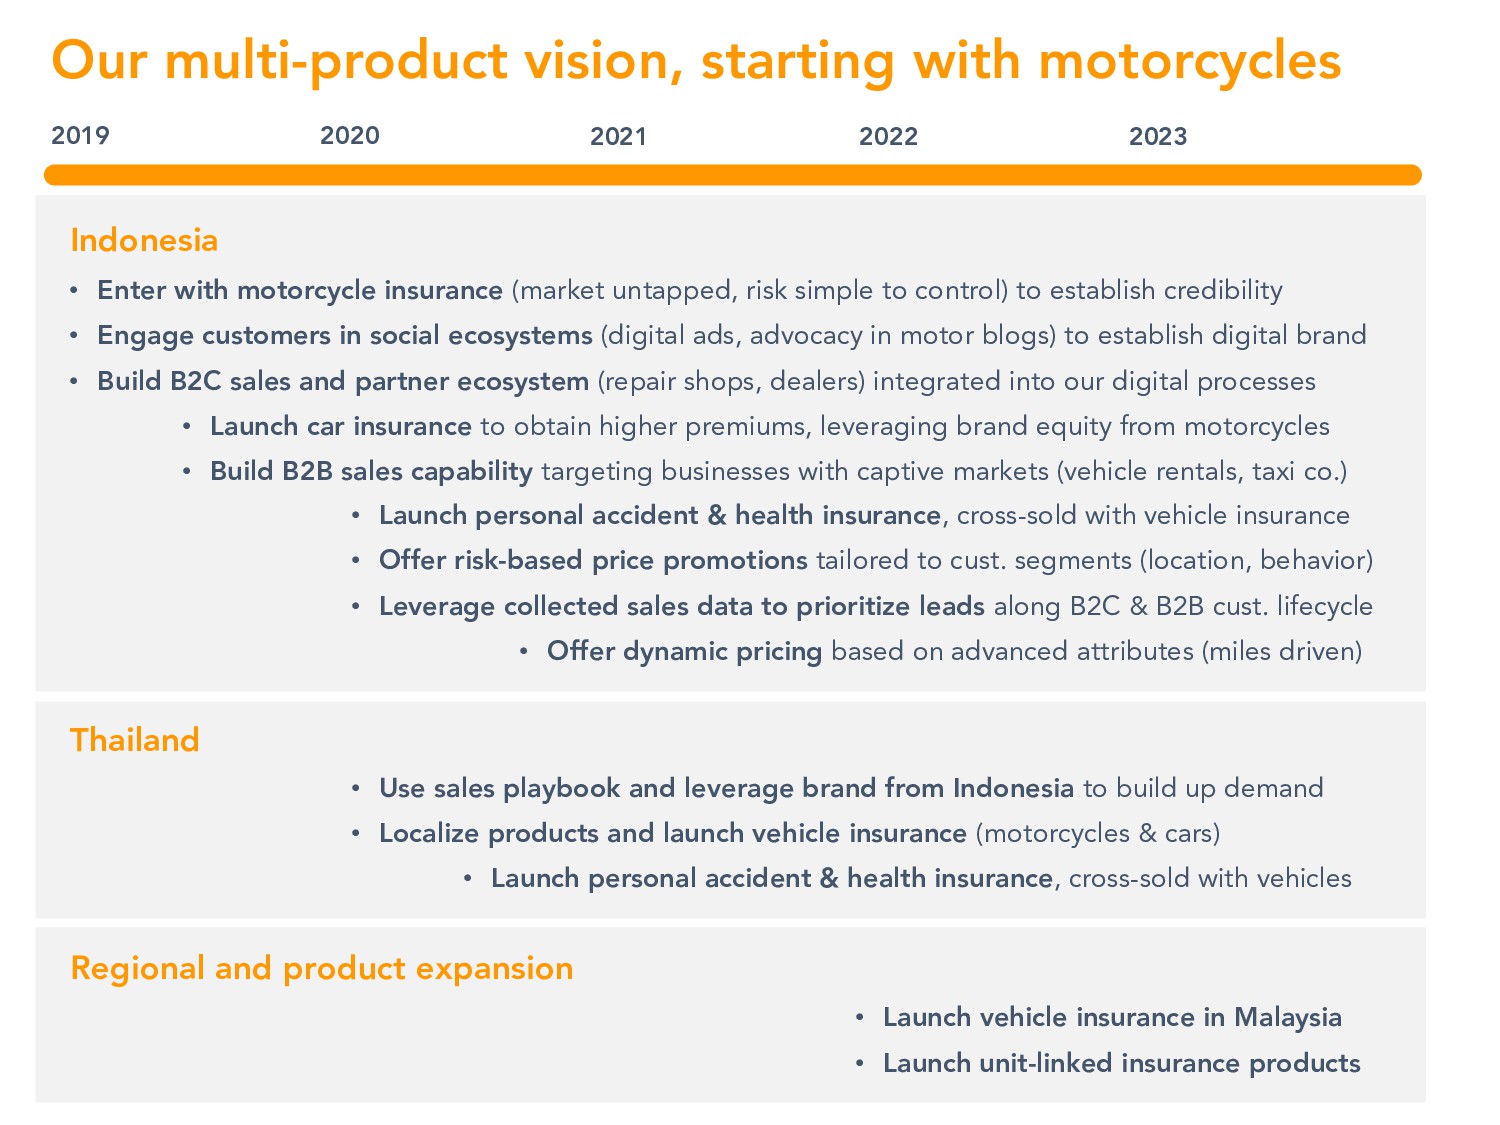
with motorcycle insurance (market untapped, risk simple to control) to establish credibility • Engage customers in social ecosystems (digital ads, advocacy in motor blogs) to establish digital brand • Build B2C sales and partner ecosystem (repair shops, dealers) integrated into our digital processes • Launch car insurance to obtain higher premiums, leveraging brand equity from motorcycles • Build B2B sales capability targeting businesses with captive markets (vehicle rentals, taxi co.) • Launch personal accident & health insurance, cross-sold with vehicle insurance • Offer risk-based price promotions tailored to cust. segments (location, behavior) • Leverage collected sales data to prioritize leads along B2C & B2B cust. lifecycle • Offer dynamic pricing based on advanced attributes (miles driven) • Use sales playbook and leverage brand from Indonesia to build up demand • Localize products and launch vehicle insurance (motorcycles & cars) • Launch personal accident & health insurance, cross-sold with vehicles 2019 2020 2021 2022 2023 Regional and product expansion • Launch vehicle insurance in Malaysia • Launch unit-linked insurance products
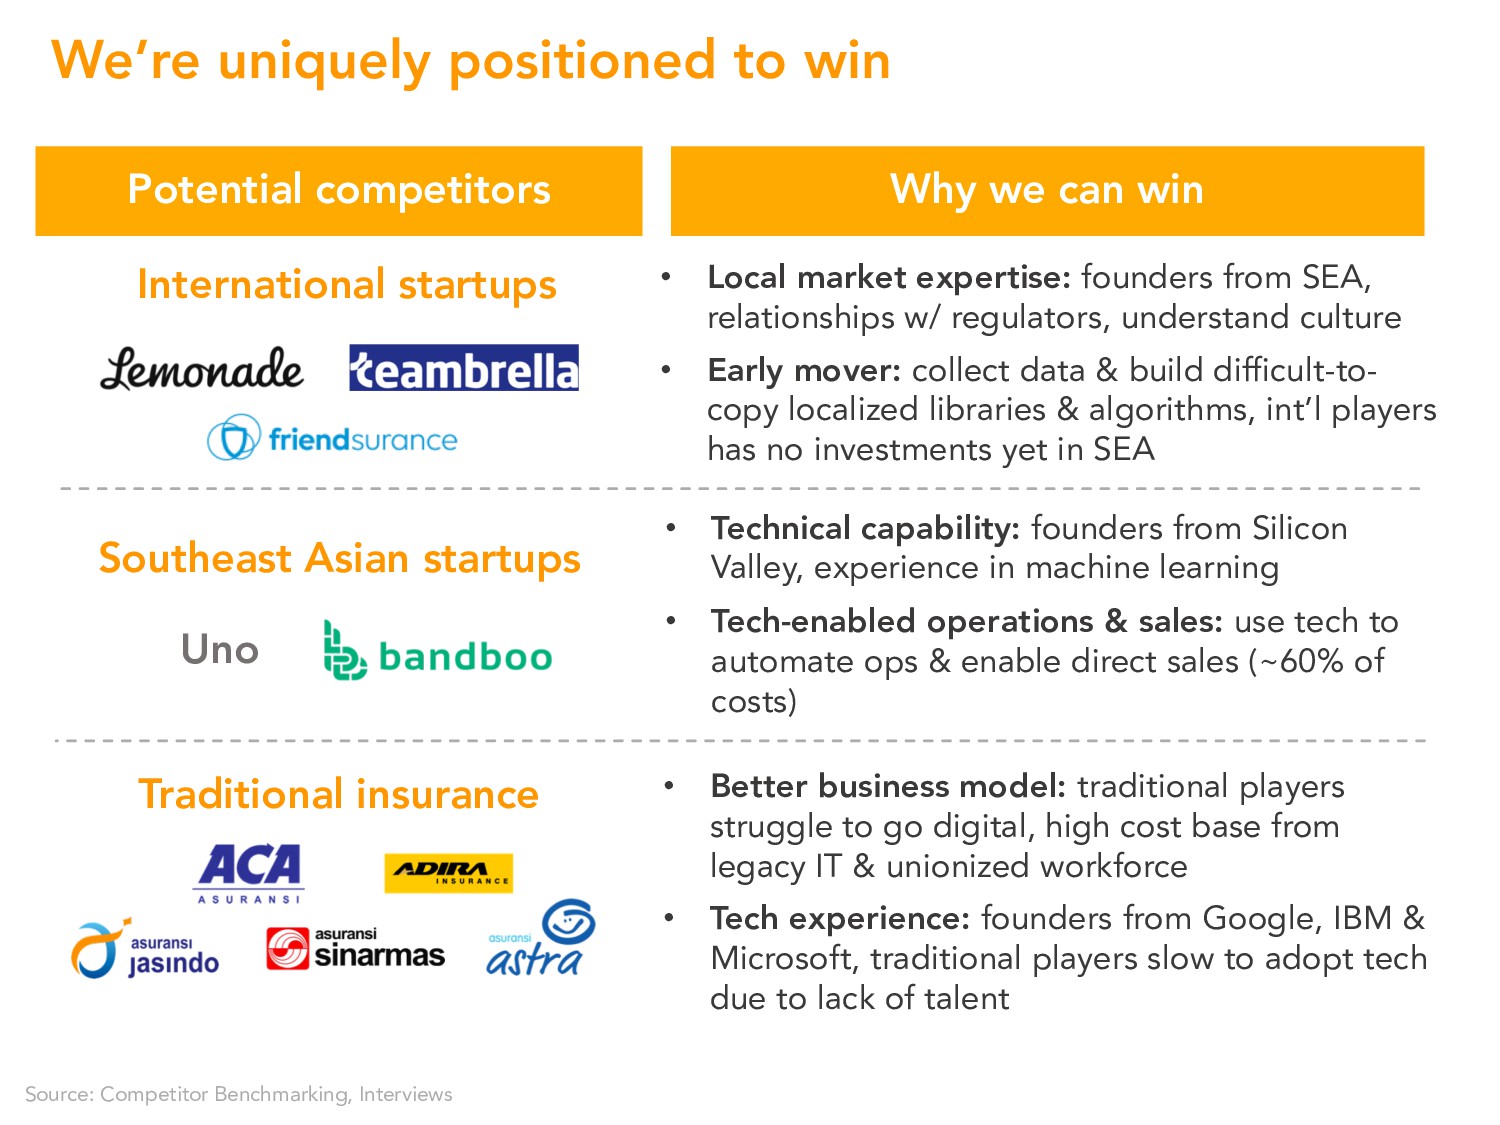
insurance Potential competitors Why we can win International startups Uno Southeast Asian startups • Local market expertise: founders from SEA, relationships w/ regulators, understand culture • Early mover: collect data & build difficult-to- copy localized libraries & algorithms, int’l players has no investments yet in SEA • Technical capability: founders from Silicon Valley, experience in machine learning • Tech-enabled operations & sales: use tech to automate ops & enable direct sales (~60% of costs) • Better business model: traditional players struggle to go digital, high cost base from legacy IT & unionized workforce • Tech experience: founders from Google, IBM & Microsoft, traditional players slow to adopt tech due to lack of talent
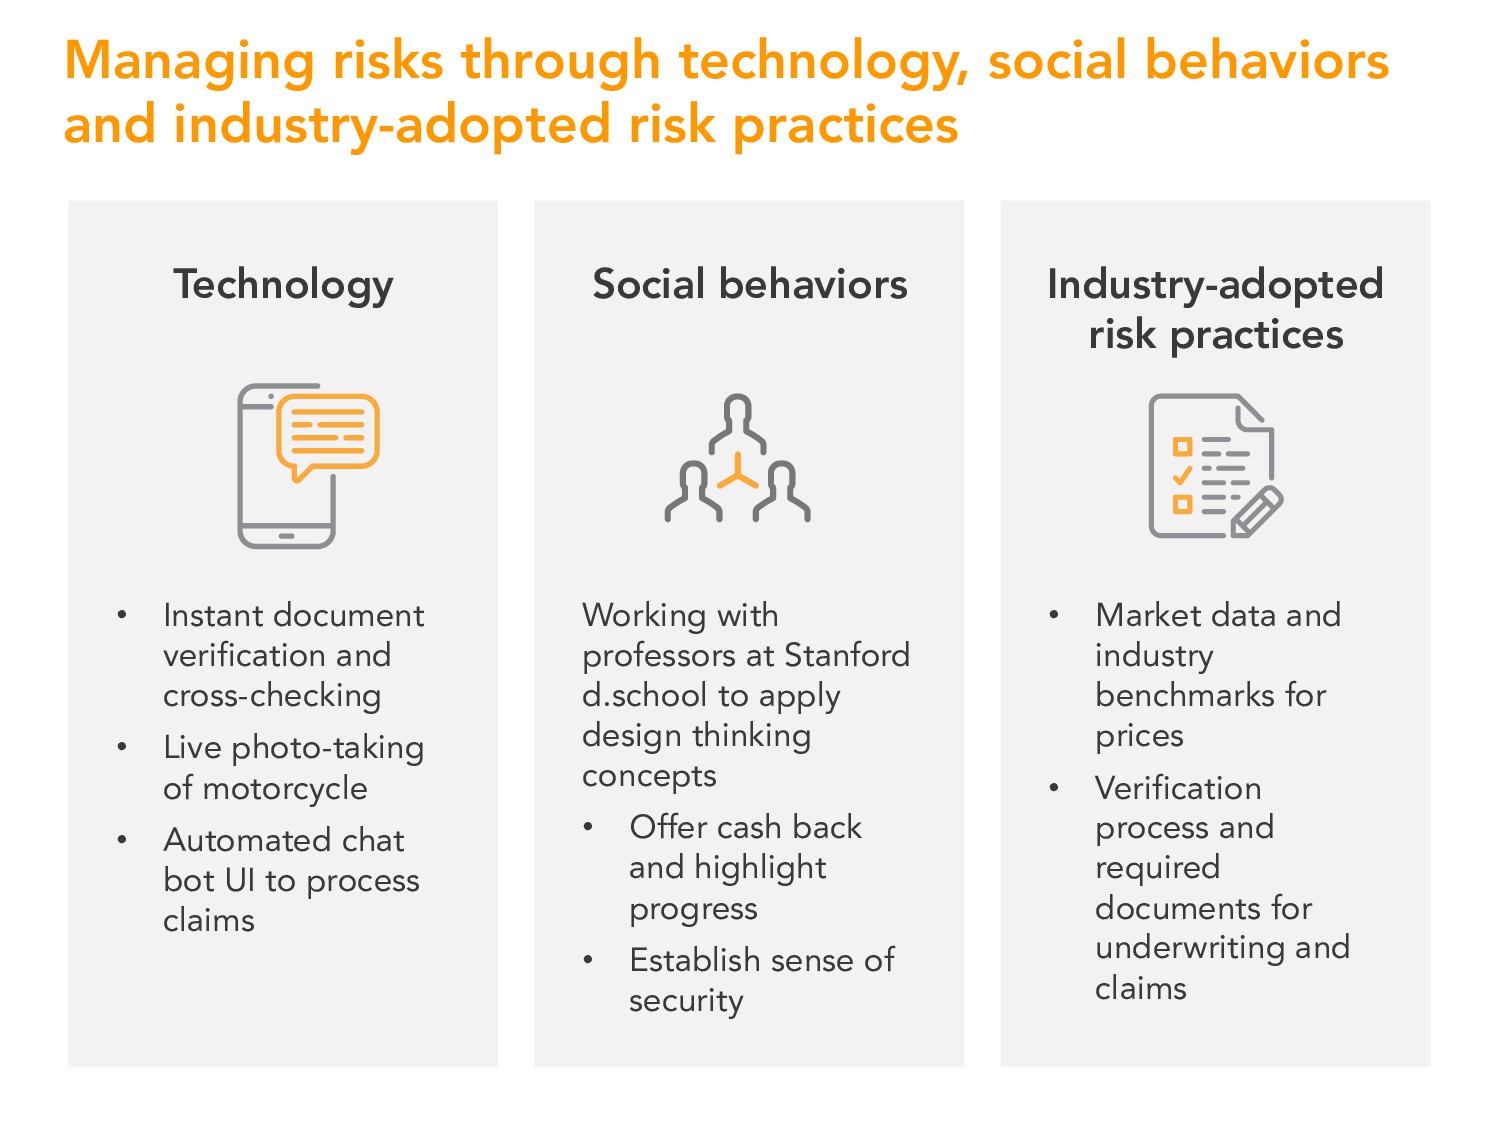
Technology Social behaviors Industry-adopted risk practices • Instant document verification and cross-checking • Live photo-taking of motorcycle • Automated chat bot UI to process claims Working with professors at Stanford d.school to apply design thinking concepts • Offer cash back and highlight progress • Establish sense of security • Market data and industry benchmarks for prices • Verification process and required documents for underwriting and claims
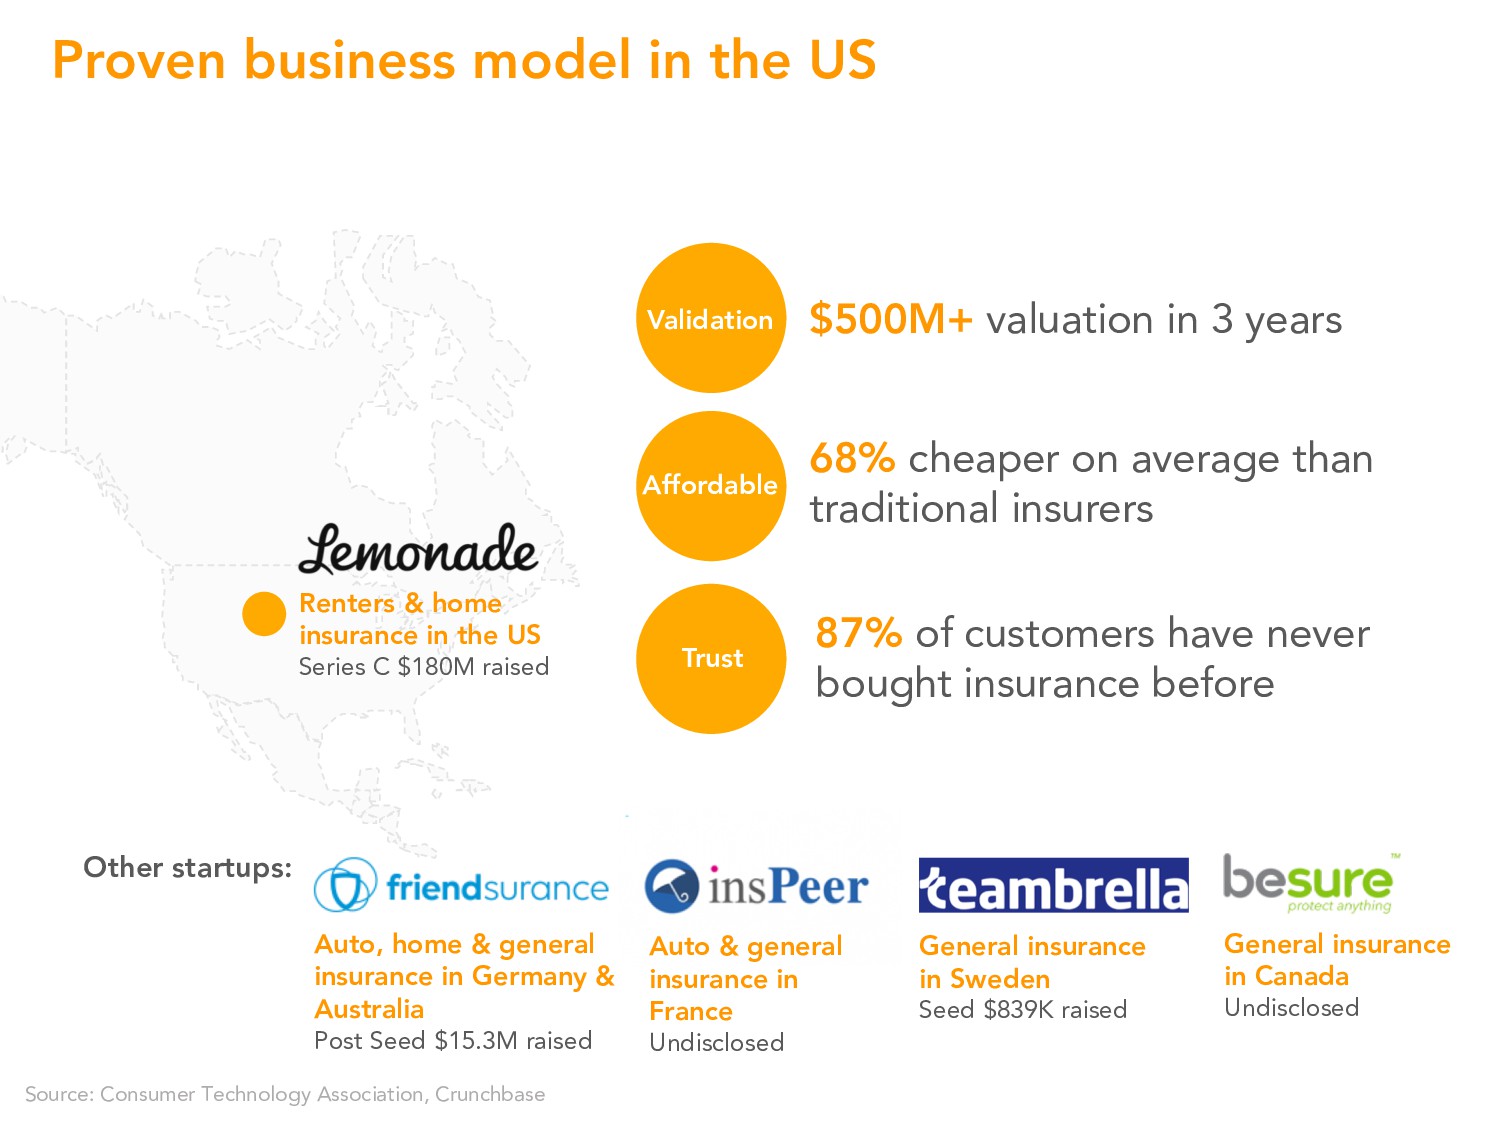
years Renters & home insurance in the US Series C $180M raised Other startups: Source: Consumer Technology Association, Crunchbase 68% cheaper on average than traditional insurers 87% of customers have never bought insurance before Affordable Trust Validation General insurance in Sweden Seed $839K raised Auto, home & general insurance in Germany & Australia Post Seed $15.3M raised Auto & general insurance in France Undisclosed General insurance in Canada Undisclosed
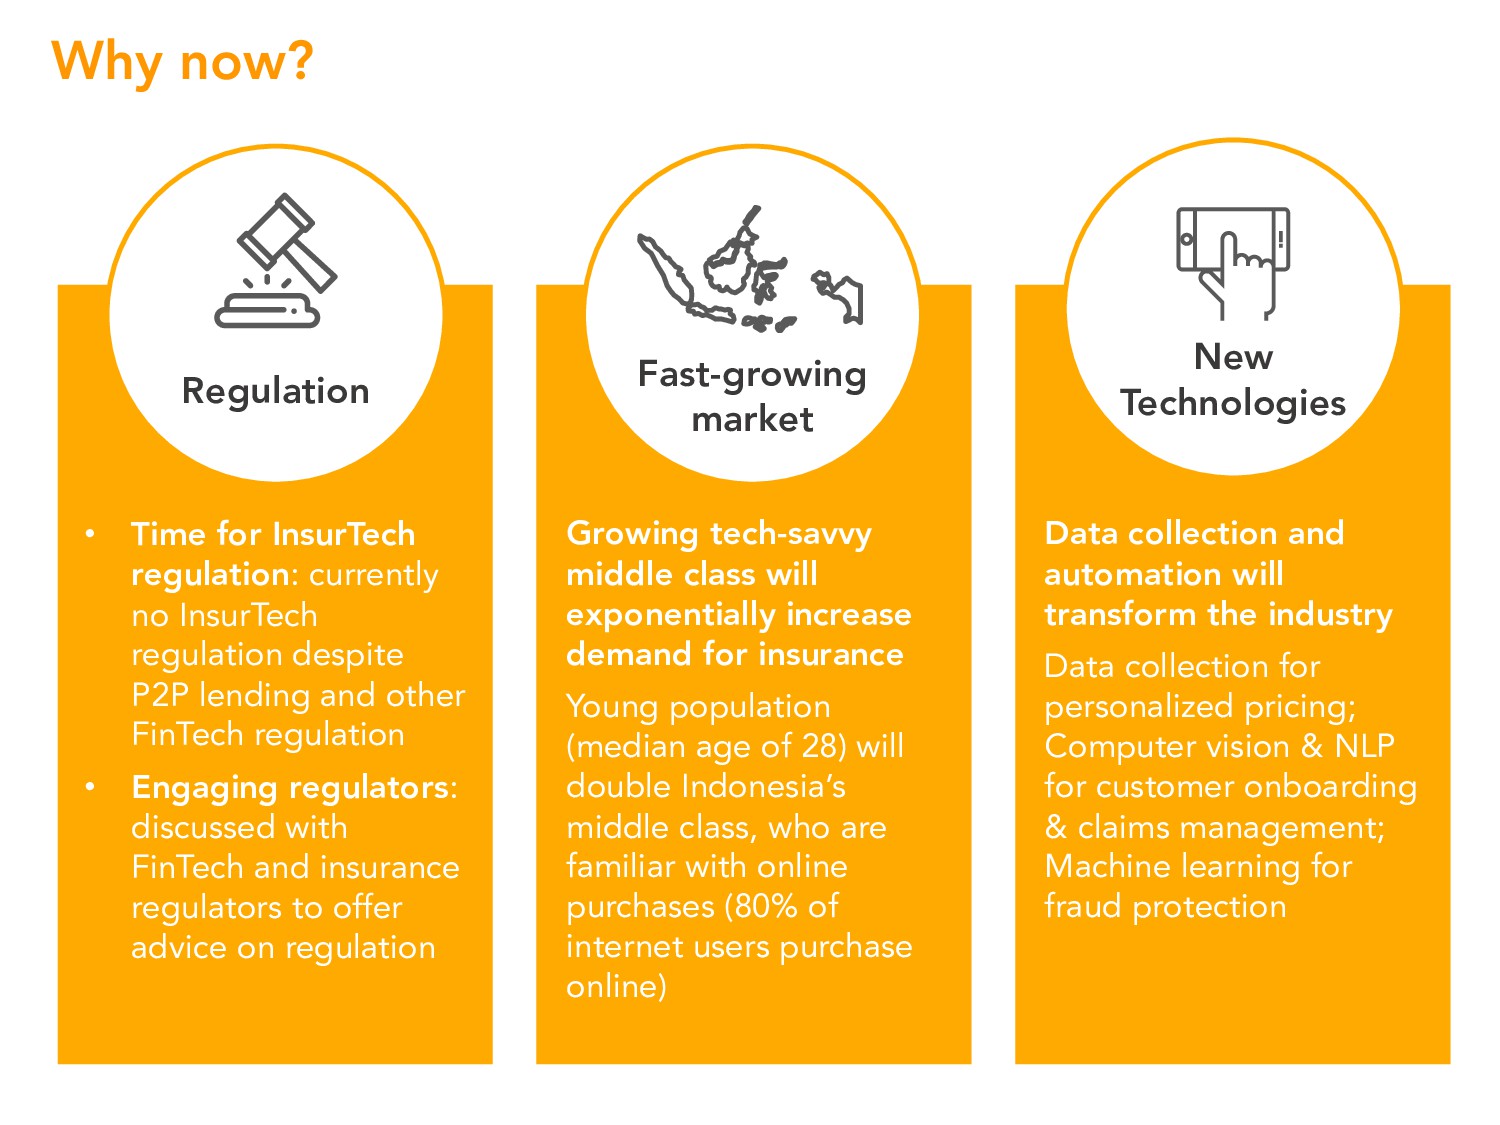
InsurTech regulation: currently no InsurTech regulation despite P2P lending and other FinTech regulation • Engaging regulators: discussed with FinTech and insurance regulators to offer advice on regulation Growing tech-savvy middle class will exponentially increase demand for insurance Young population (median age of 28) will double Indonesia’s middle class, who are familiar with online purchases (80% of internet users purchase online) Data collection and automation will transform the industry Data collection for personalized pricing; Computer vision & NLP for customer onboarding & claims management; Machine learning for fraud protection
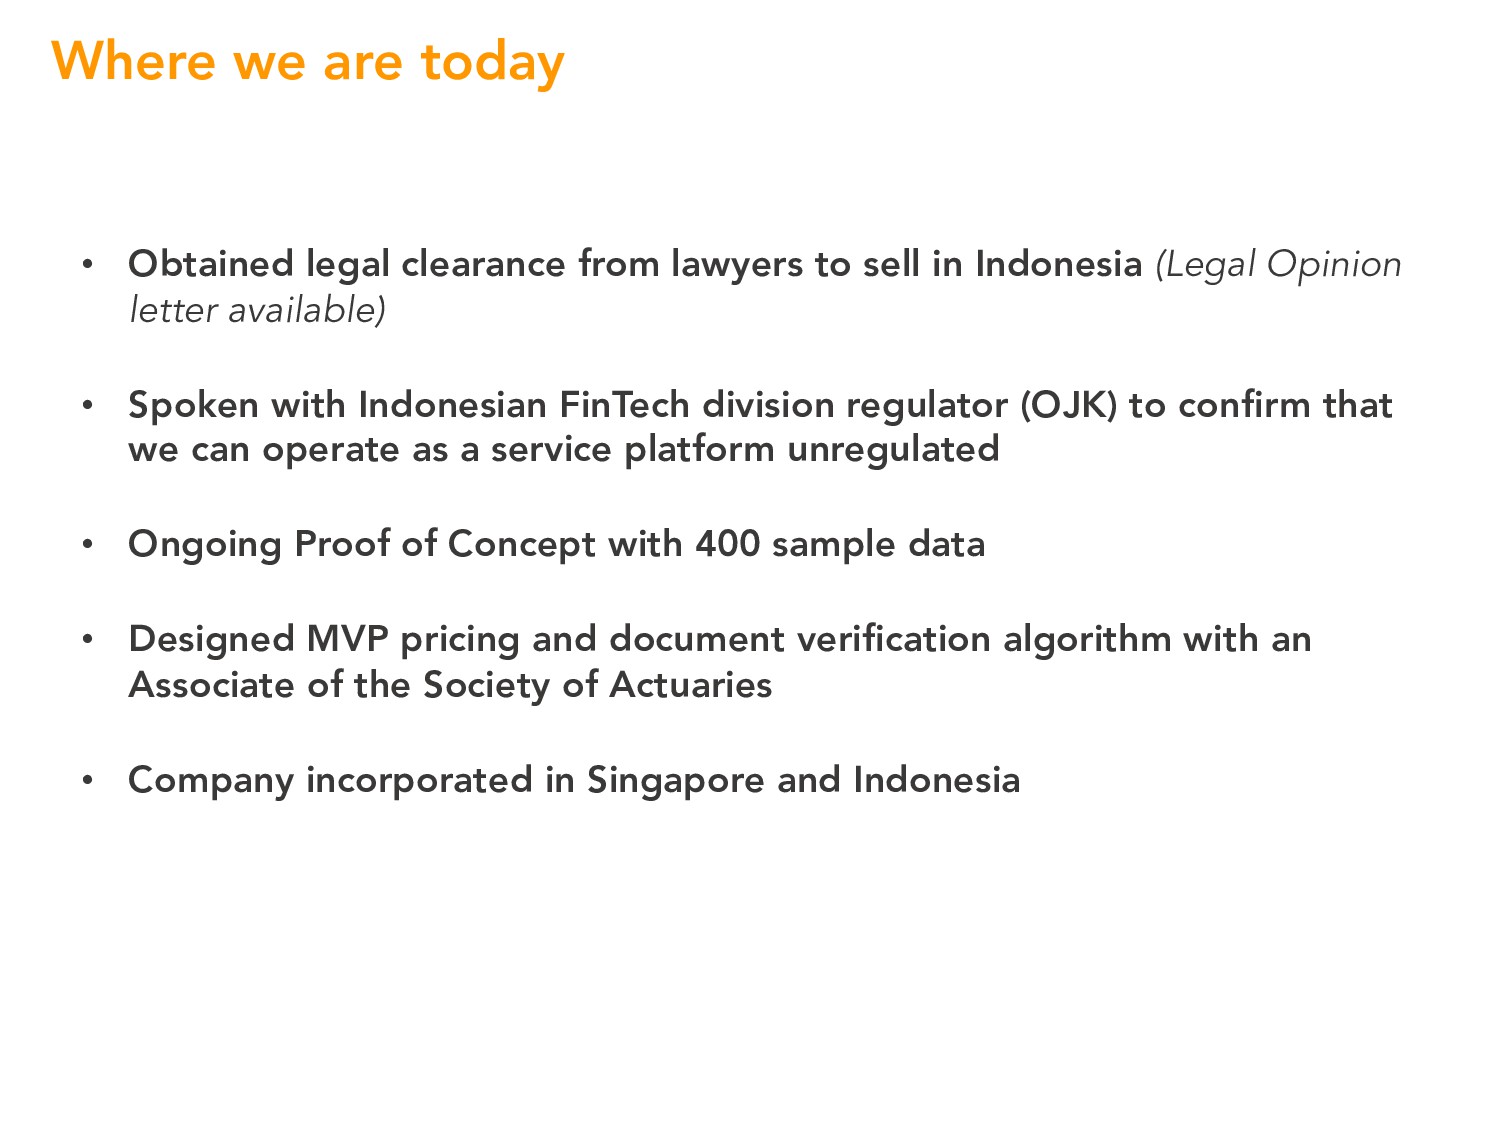
to sell in Indonesia (Legal Opinion letter available) • Spoken with Indonesian FinTech division regulator (OJK) to confirm that we can operate as a service platform unregulated • Ongoing Proof of Concept with 400 sample data • Designed MVP pricing and document verification algorithm with an Associate of the Society of Actuaries • Company incorporated in Singapore and Indonesia
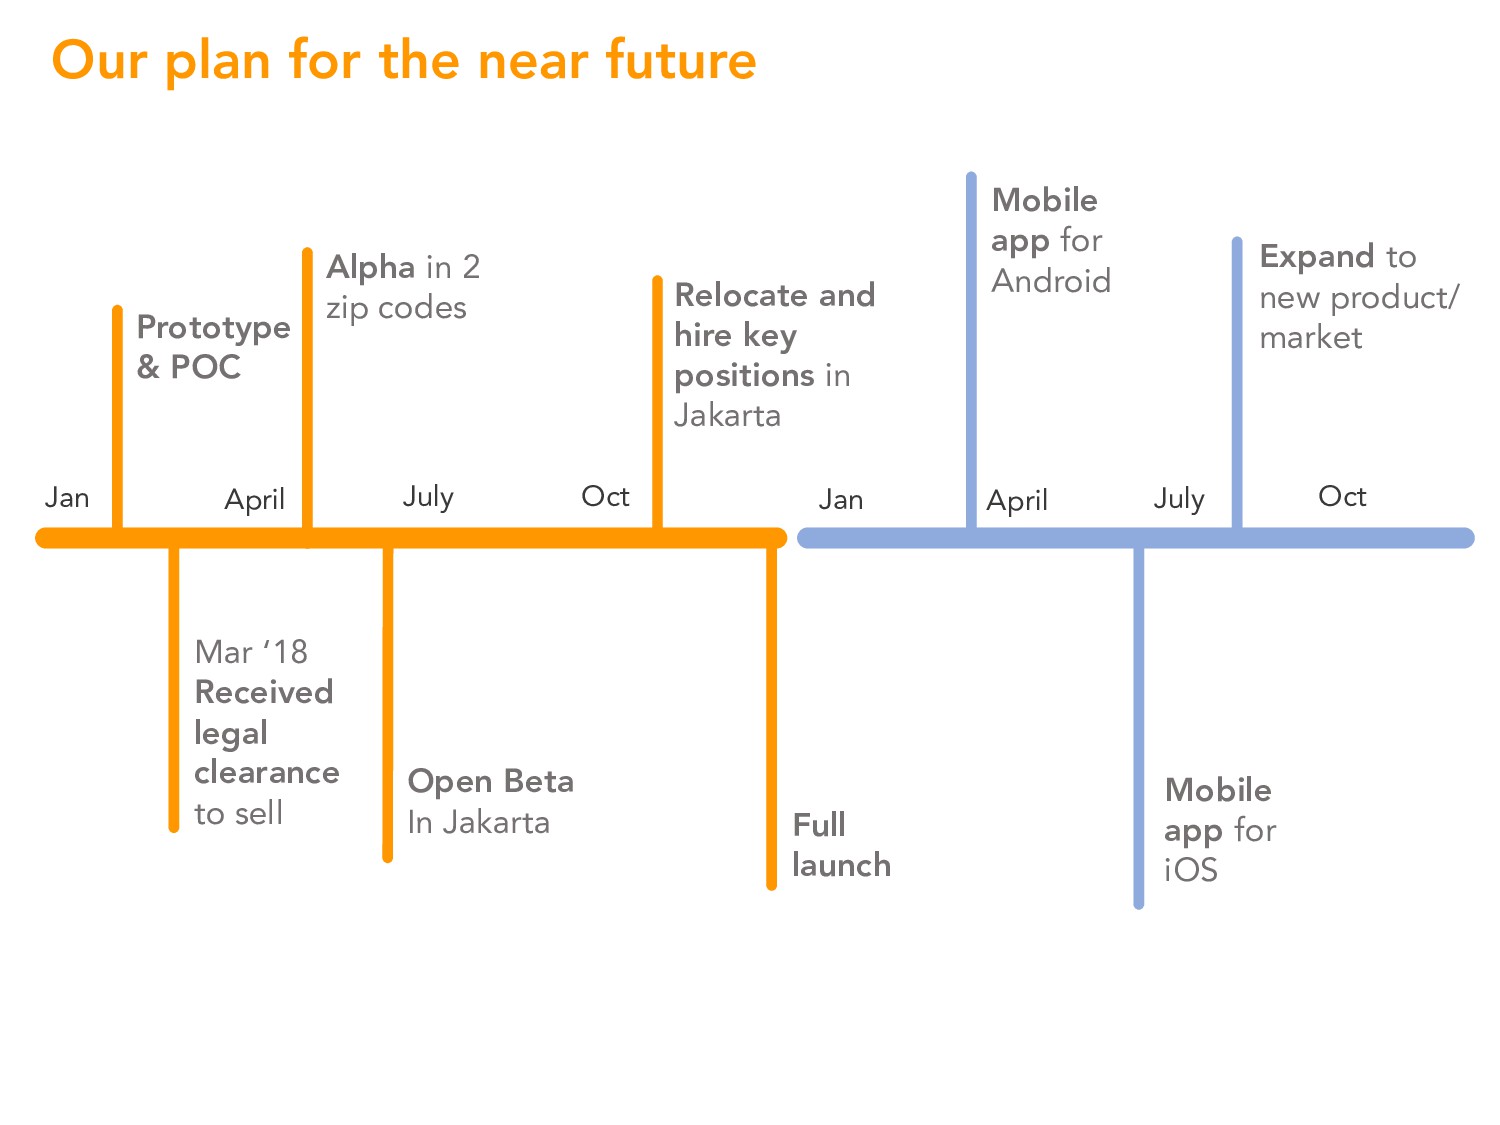
April July Prototype & POC Relocate and hire key positions in Jakarta Open Beta In Jakarta Full launch Mobile app for Android Expand to new product/ market Jan Oct Mar ‘18 Received legal clearance to sell Alpha in 2 zip codes Mobile app for iOS
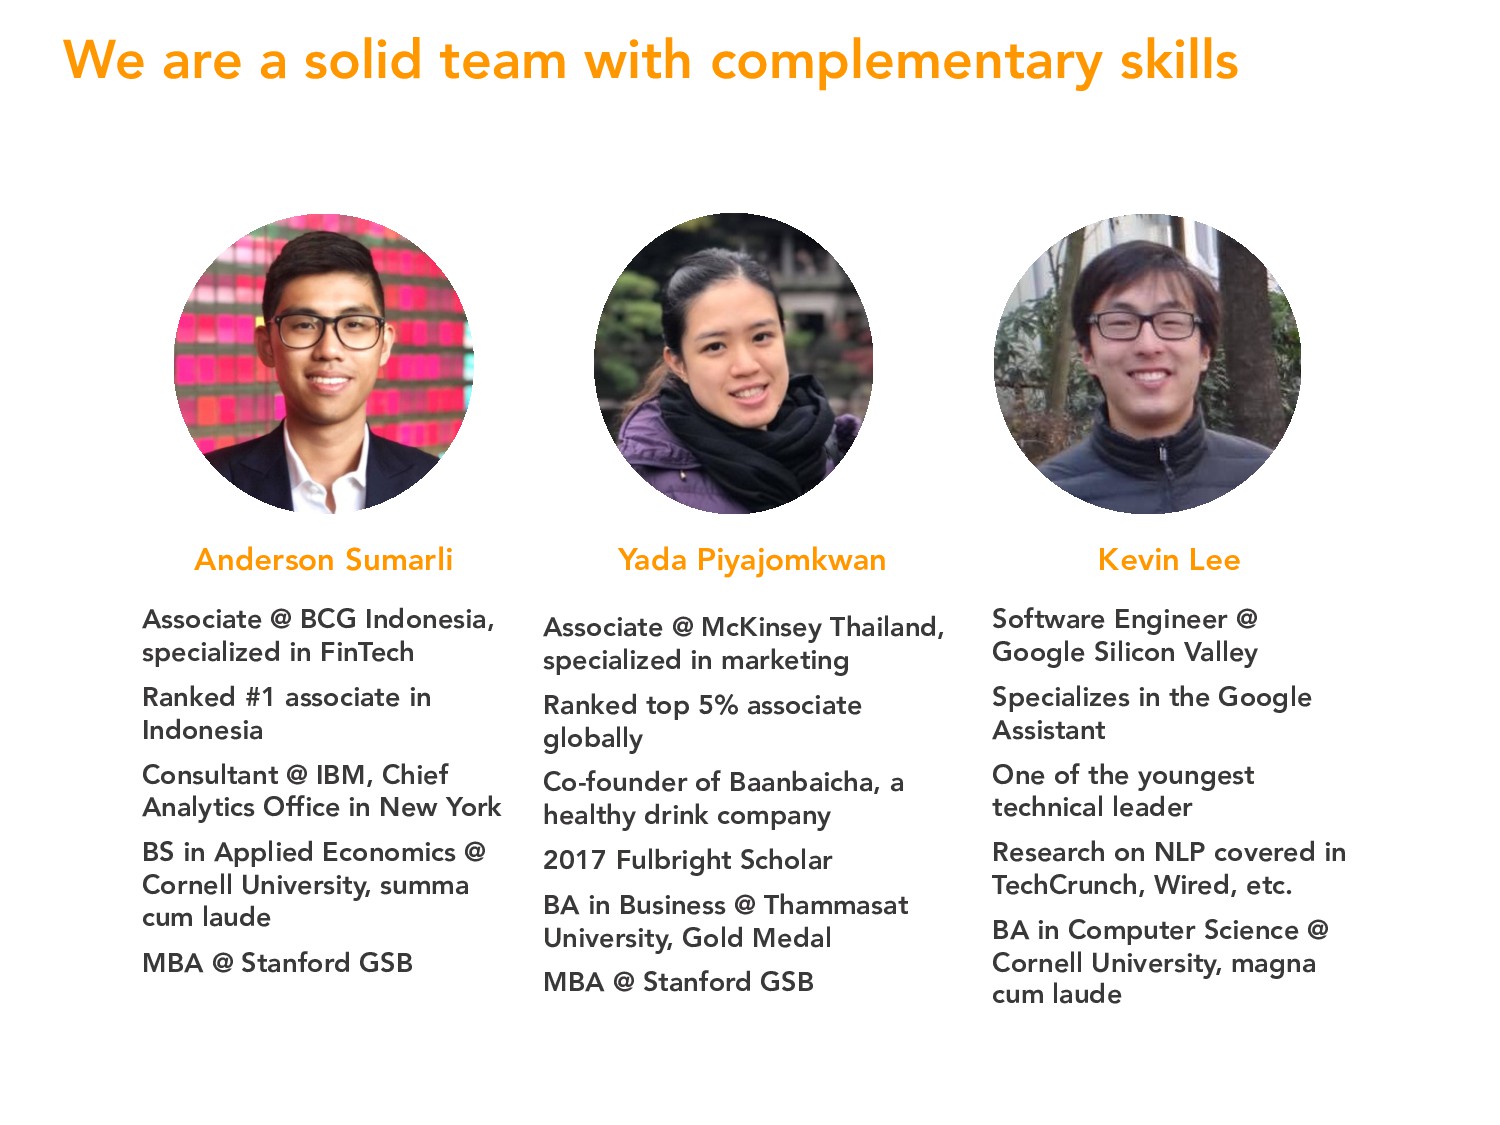
Associate @ BCG Indonesia, specialized in FinTech Ranked #1 associate in Indonesia Consultant @ IBM, Chief Analytics Office in New York BS in Applied Economics @ Cornell University, summa cum laude MBA @ Stanford GSB Yada Piyajomkwan Associate @ McKinsey Thailand, specialized in marketing Ranked top 5% associate globally Co-founder of Baanbaicha, a healthy drink company 2017 Fulbright Scholar BA in Business @ Thammasat University, Gold Medal MBA @ Stanford GSB Kevin Lee Software Engineer @ Google Silicon Valley Specializes in the Google Assistant One of the youngest technical leader Research on NLP covered in TechCrunch, Wired, etc. BA in Computer Science @ Cornell University, magna cum laude


 uemura2024
 ikmwatanabe
 kaonavi
 kazumakitao
 nakasonejusetsu
 tamagakiyuya
 sukatsu1222
 layerx
 ikuodanaka
 gatechnologies
 hiyoriyamakankou
 lara
 dugsong
 retrage
 ks91
 baasie
 vanstee
 aleyda
 mfonobong
 seathinner
 mayatellez
 smashingmag
 skipperchong