Upgrade to Pro — share decks privately, control downloads, hide ads and more …

Breaking Your Mortgage Early in a Spousal Buyou...

Sponsored · Your Podcast. Everywhere. Effortlessly. Share. Educate. Inspire. Entertain. You do you. We'll handle the rest. →

Breaking Your Mortgage Early in a Spousal Buyout: How Prepayment Penalties Work

Most spousal buyouts mean breaking your current mortgage, and the penalty can run into five figures. This guide explains the two ways lenders usually charge it: three months’ interest, and the interest rate differential (IRD), which is based on the gap between your rate and today’s rates. It works through an example with real numbers, then covers who pays the penalty and four ways you may be able to lower it.

Want to build the penalty into your plan? Try the free Matrimonial Home Buyout Calculator: https://divorcethesmartway.ca/tools/matrimonial-home-buyout/

Ken S. Maynard, AP.fm, CDFA | Divorce the Smartway
General information only, not legal or financial advice.

Avatar for Ken Maynard

Ken Maynard PRO

November 02, 2026

More Decks by Ken Maynard

Other Decks in Storyboards

Transcript

  1. Ontario Matrimonial Home Guide Breaking Your Mortgage Early in a

    Spousal Buyout How prepayment penalties work, who pays them, and how to keep them small. Ken S. Maynard, AP.fm, CDFA Divorce the Smartway divorcethesmartway.ca
  2. The hidden cost Most buyouts end your current mortgage early.

    That can cost thousands. To pay your spouse, you usually replace the old mortgage with a bigger one. If you’re partway through a closed term (a term you agreed not to pay off early), the lender charges a prepayment penalty for ending it. divorcethesmartway.ca · 2
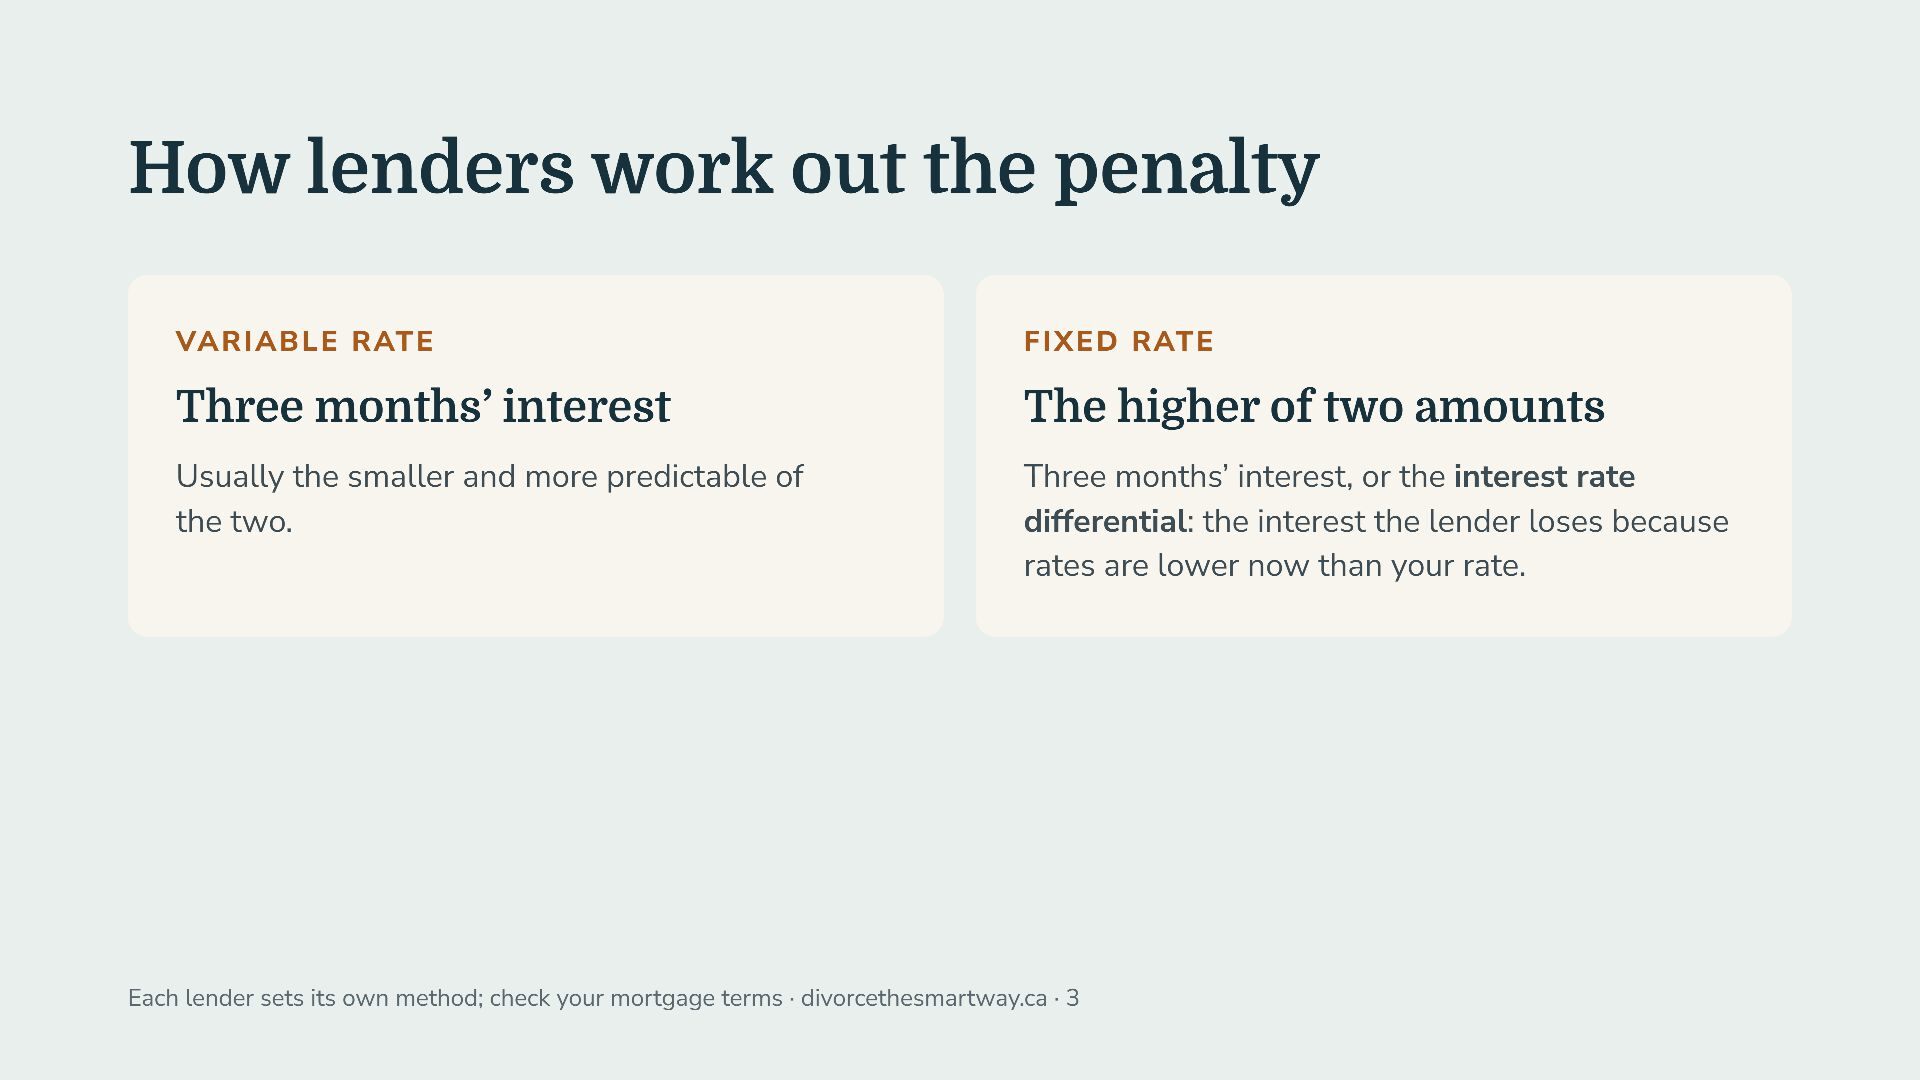
  3. How lenders work out the penalty Variable rate Fixed rate

    Three months’ interest The higher of two amounts Usually the smaller and more predictable of the two. Three months’ interest, or the interest rate differential: the interest the lender loses because rates are lower now than your rate. Each lender sets its own method; check your mortgage terms · divorcethesmartway.ca · 3
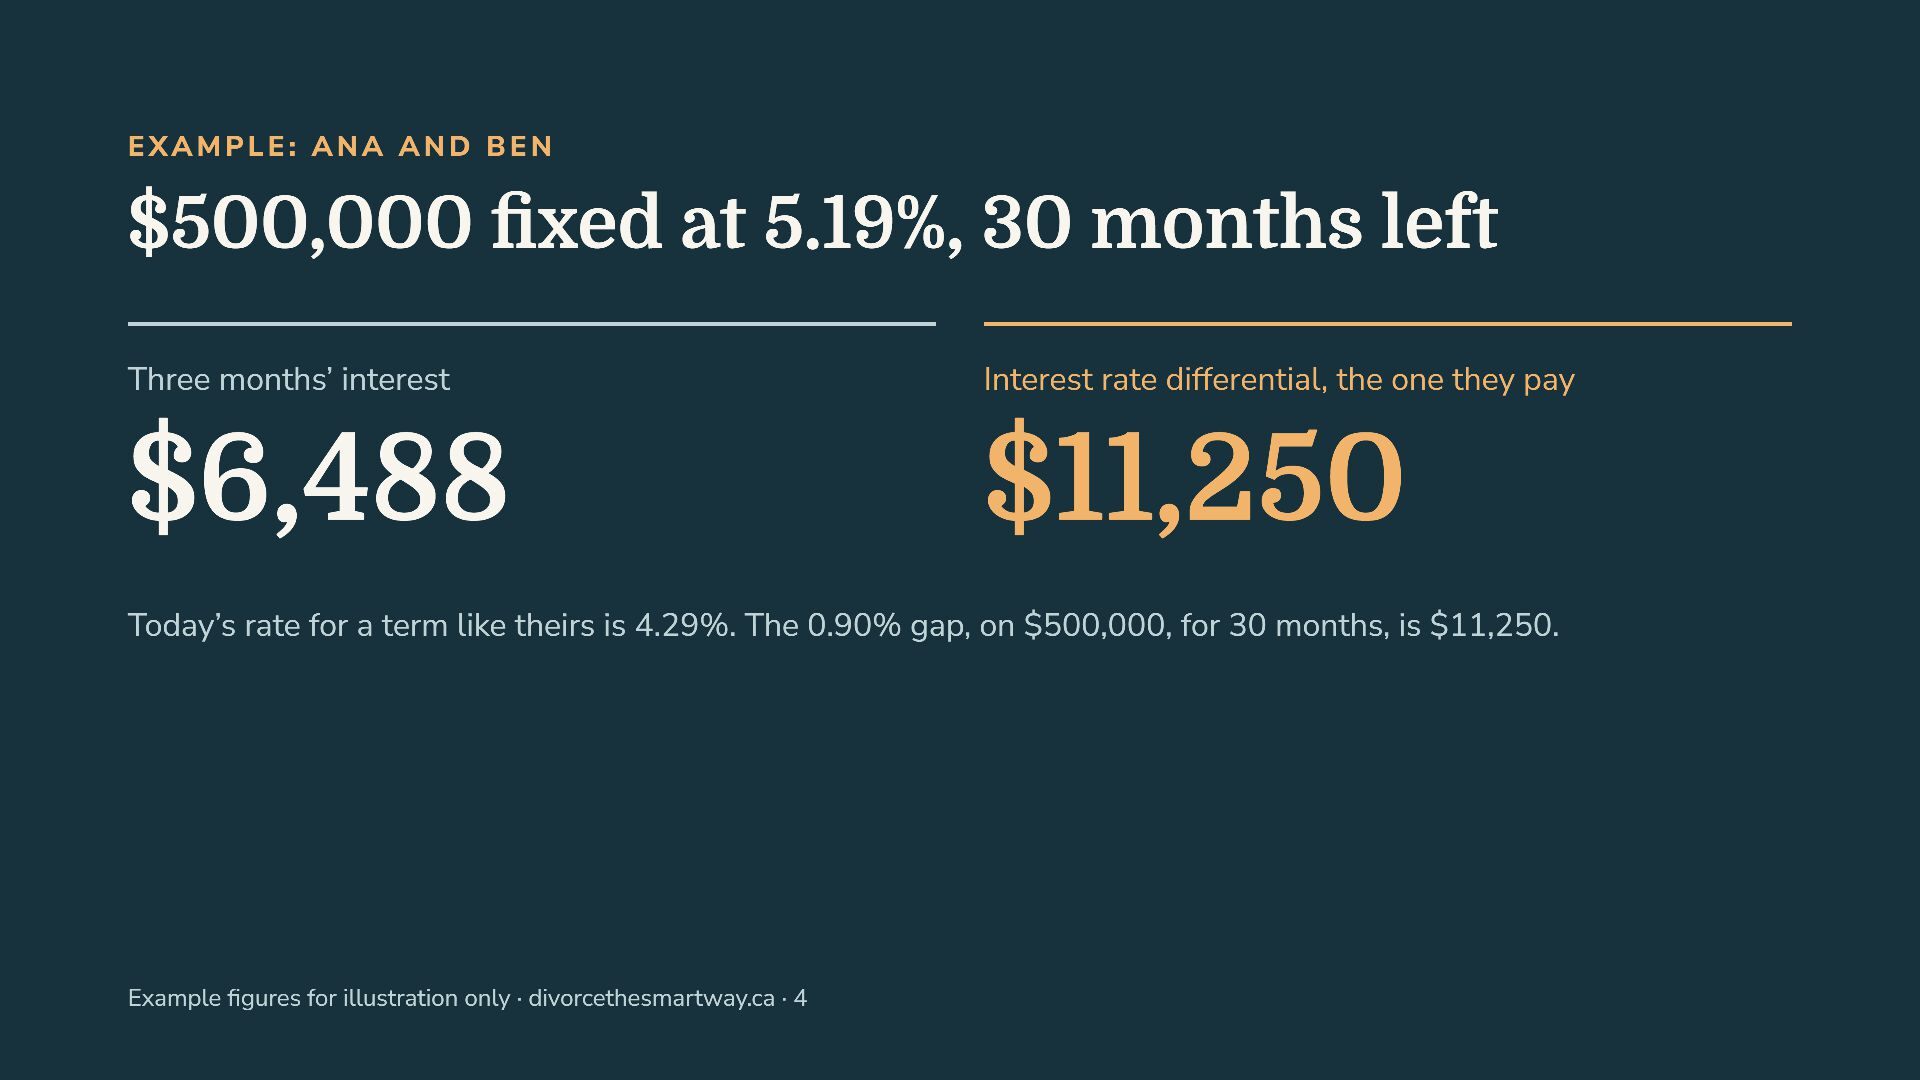
  4. Example: Ana and Ben $500,000 fixed at 5.19%, 30 months

    left Three months’ interest Interest rate differential, the one they pay $6,488 $11,250 Today’s rate for a term like theirs is 4.29%. The 0.90% gap, on $500,000, for 30 months, is $11,250. Example figures for illustration only · divorcethesmartway.ca · 4
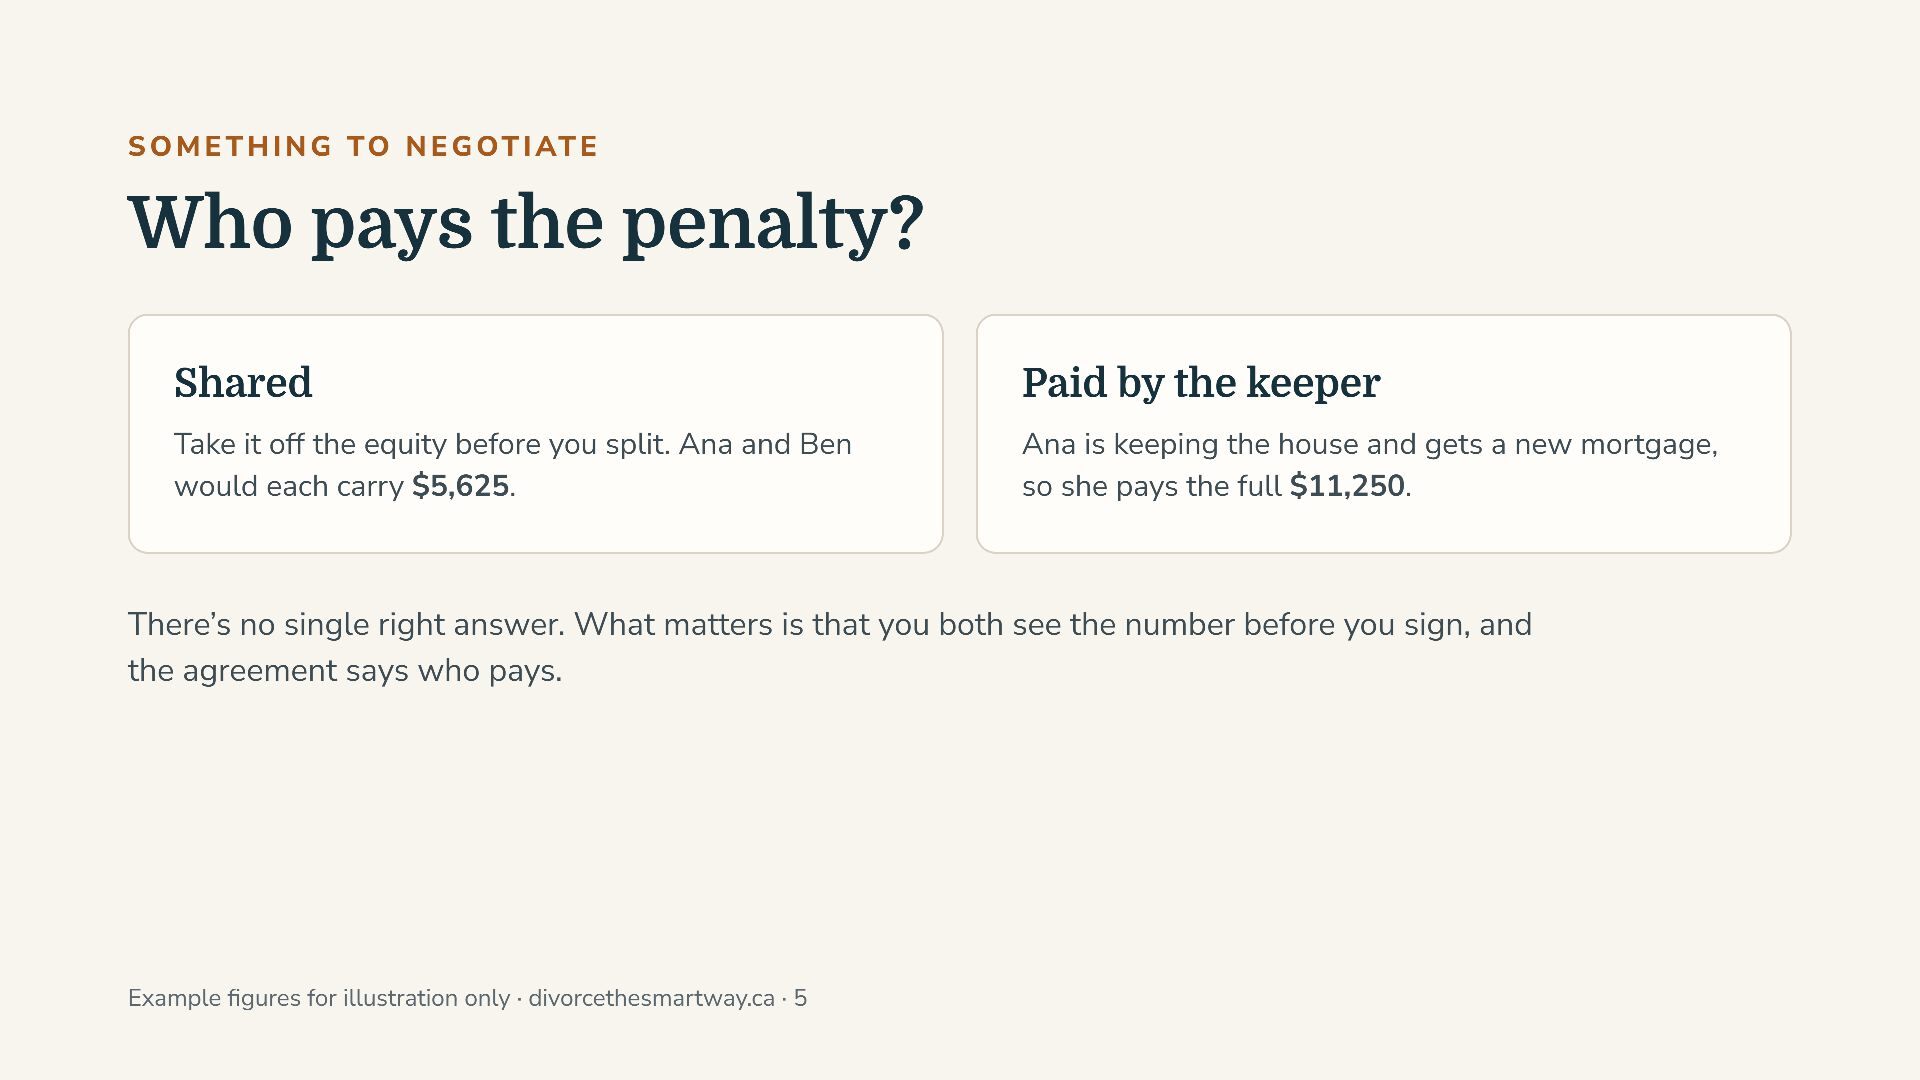
  5. Something to negotiate Who pays the penalty? Shared Paid by

    the keeper Take it off the equity before you split. Ana and Ben would each carry $5,625. Ana is keeping the house and gets a new mortgage, so she pays the full $11,250. There’s no single right answer. What matters is that you both see the number before you sign, and the agreement says who pays. Example figures for illustration only · divorcethesmartway.ca · 5
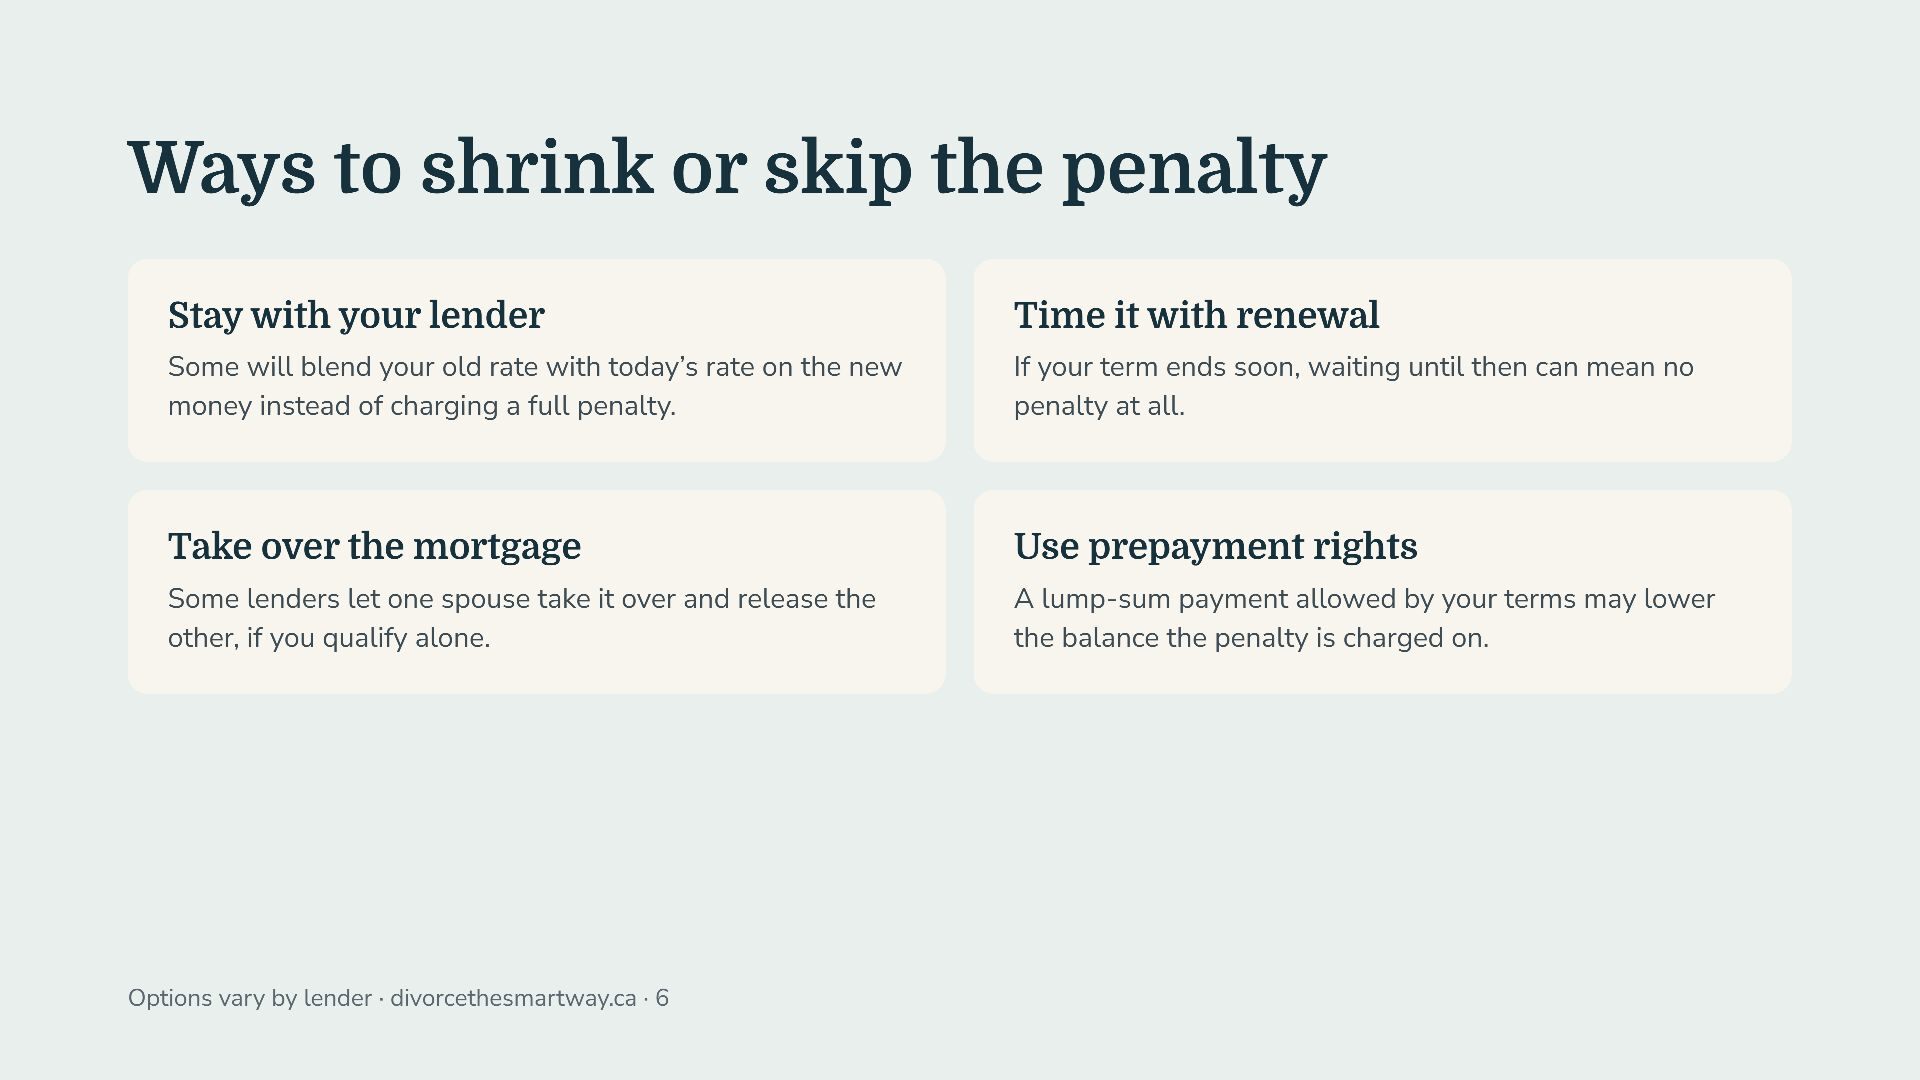
  6. Ways to shrink or skip the penalty Stay with your

    lender Time it with renewal Some will blend your old rate with today’s rate on the new money instead of charging a full penalty. If your term ends soon, waiting until then can mean no penalty at all. Take over the mortgage Use prepayment rights Some lenders let one spouse take it over and release the other, if you qualify alone. A lump-sum payment allowed by your terms may lower the balance the penalty is charged on. Options vary by lender · divorcethesmartway.ca · 6
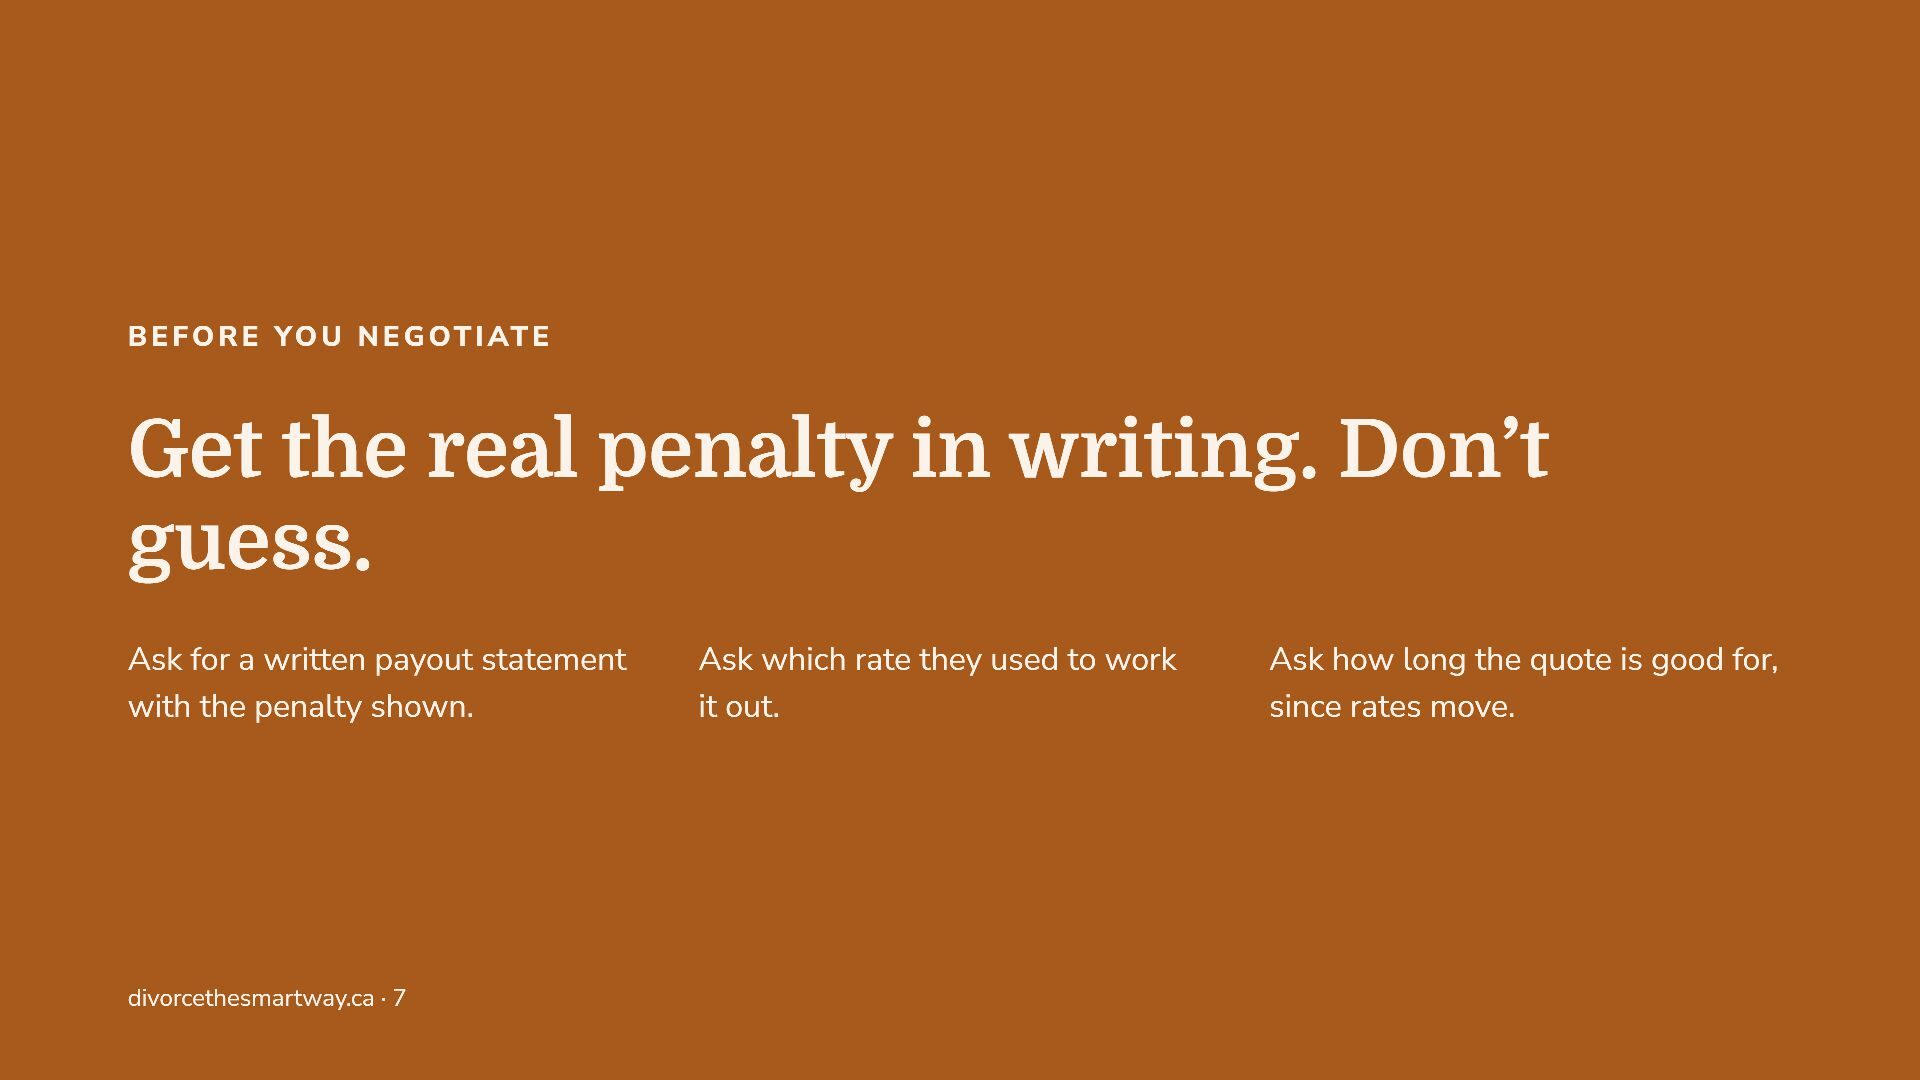
  7. Before you negotiate Get the real penalty in writing. Don’t

    guess. Ask for a written payout statement with the penalty shown. divorcethesmartway.ca · 7 Ask which rate they used to work it out. Ask how long the quote is good for, since rates move.
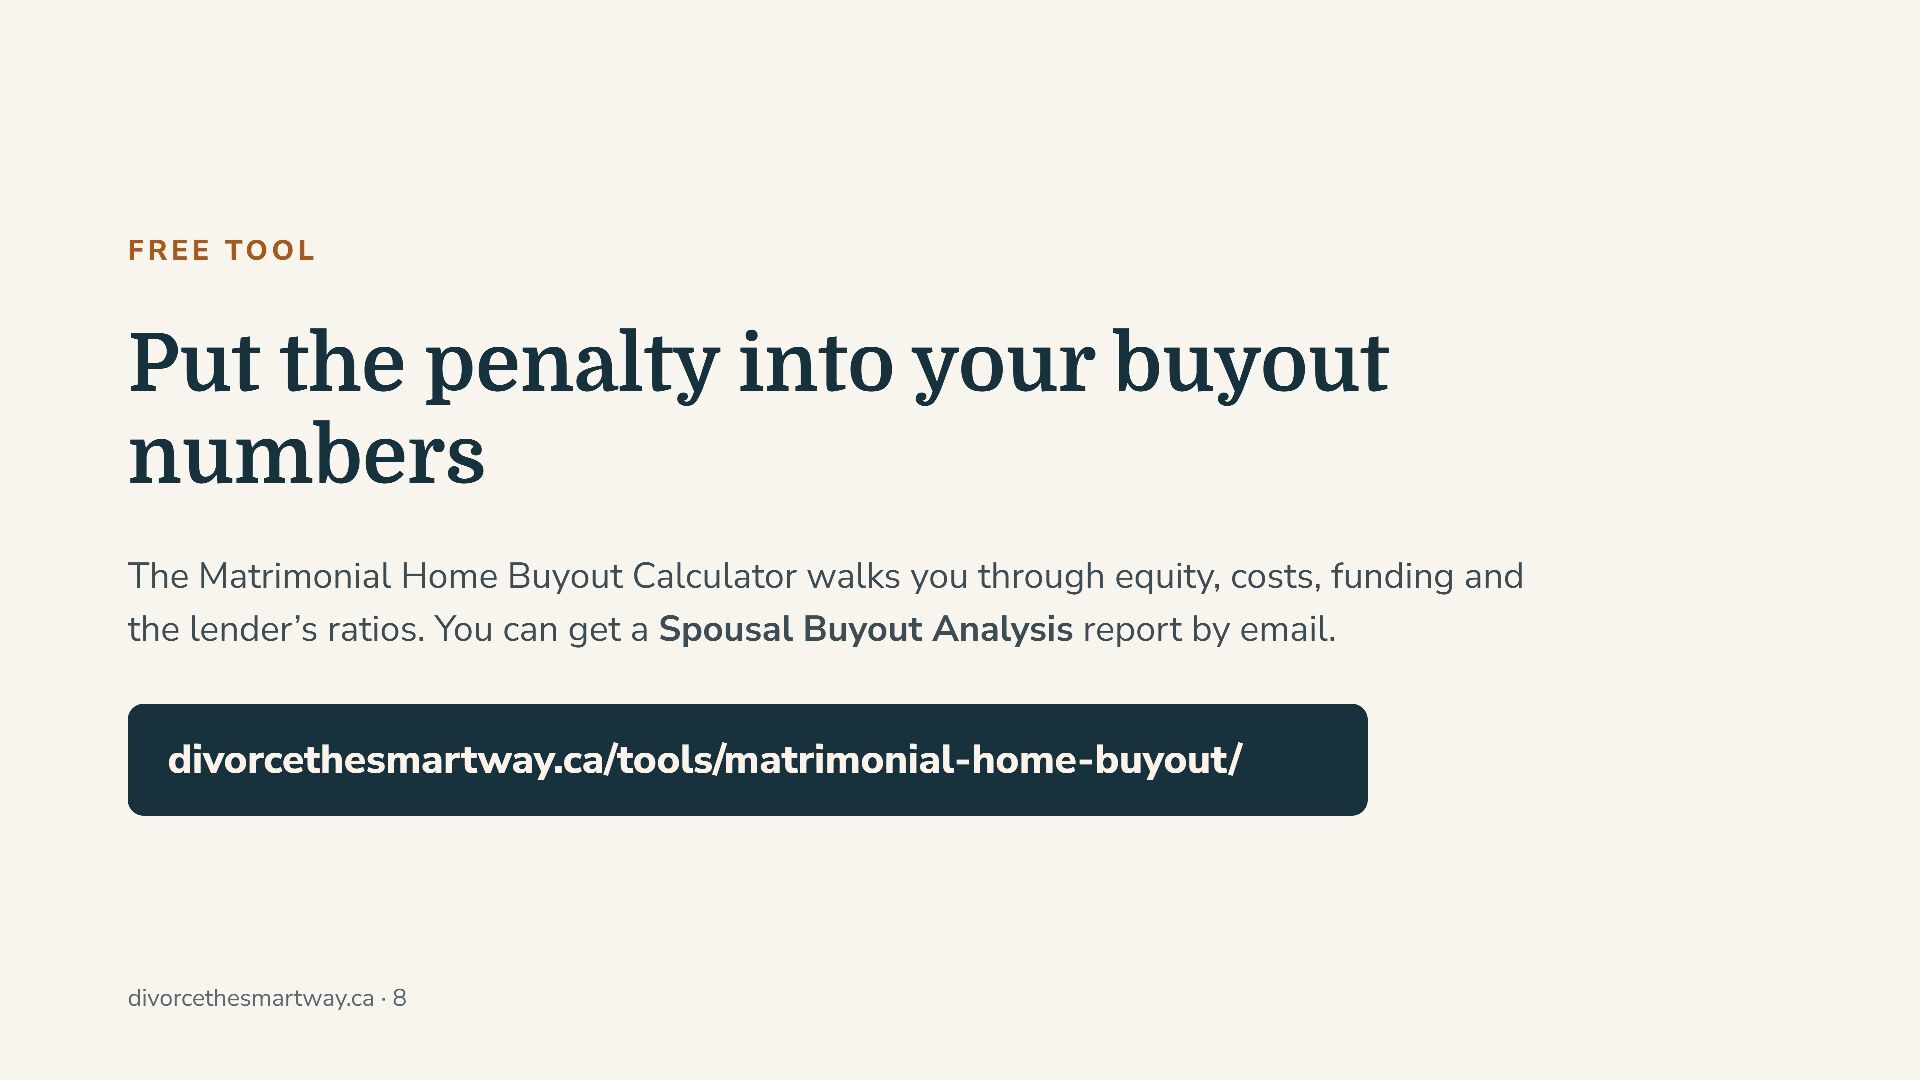
  8. Free tool Put the penalty into your buyout numbers The

    Matrimonial Home Buyout Calculator walks you through equity, costs, funding and the lender’s ratios. You can get a Spousal Buyout Analysis report by email. divorcethesmartway.ca/tools/matrimonial-home-buyout/ divorcethesmartway.ca · 8
  9. Not sure what breaking your mortgage will cost? Book a

    free Get Acquainted Call by phone or video. We’ll help you build the penalty into a buyout plan you both understand. Ken S. Maynard, AP.fm, CDFA Divorce the Smartway 416-849-1696 · divorcethesmartway.ca General information only, not legal or financial advice. Talk to a lawyer and a mortgage professional about your situation.