Upgrade to Pro — share decks privately, control downloads, hide ads and more …

Trading Your RRSP or Pension for the House: The...

Sponsored · Your Podcast. Everywhere. Effortlessly. Share. Educate. Inspire. Entertain. You do you. We'll handle the rest. →

Trading Your RRSP or Pension for the House: The After-Tax Math in a Divorce

Swapping retirement savings for the family home is a common way to fund a spousal buyout. But a dollar in an RRSP isn’t worth a dollar of tax-free home equity, because tax comes off when the money is withdrawn. This guide works through the after-tax math with an example. It also explains how an RRSP can be moved to a spouse without tax using Form T2220, and why locked-in pension money changes the trade.

Want to see what the buyout would cost in cash first? Try the free Matrimonial Home Buyout Calculator: https://divorcethesmartway.ca/tools/matrimonial-home-buyout/

Ken S. Maynard, AP.fm, CDFA | Divorce the Smartway
General information only, not legal, tax or financial advice.

Avatar for Ken Maynard

Ken Maynard PRO

November 02, 2026

More Decks by Ken Maynard

Other Decks in Storyboards

Transcript

  1. Ontario Matrimonial Home Guide Trading Your RRSP or Pension for

    the House Why a dollar of RRSP isn’t a dollar of home equity, and how to make the swap fair. Ken S. Maynard, AP.fm, CDFA Divorce the Smartway divorcethesmartway.ca
  2. A common swap Keep the house. Give your spouse more

    of the retirement savings instead. When there isn’t enough cash or borrowing room for a buyout, couples often trade. One keeps the home, the other takes a bigger share of the RRSPs or pension. It can work well, as long as you count the dollars the right way. divorcethesmartway.ca · 2
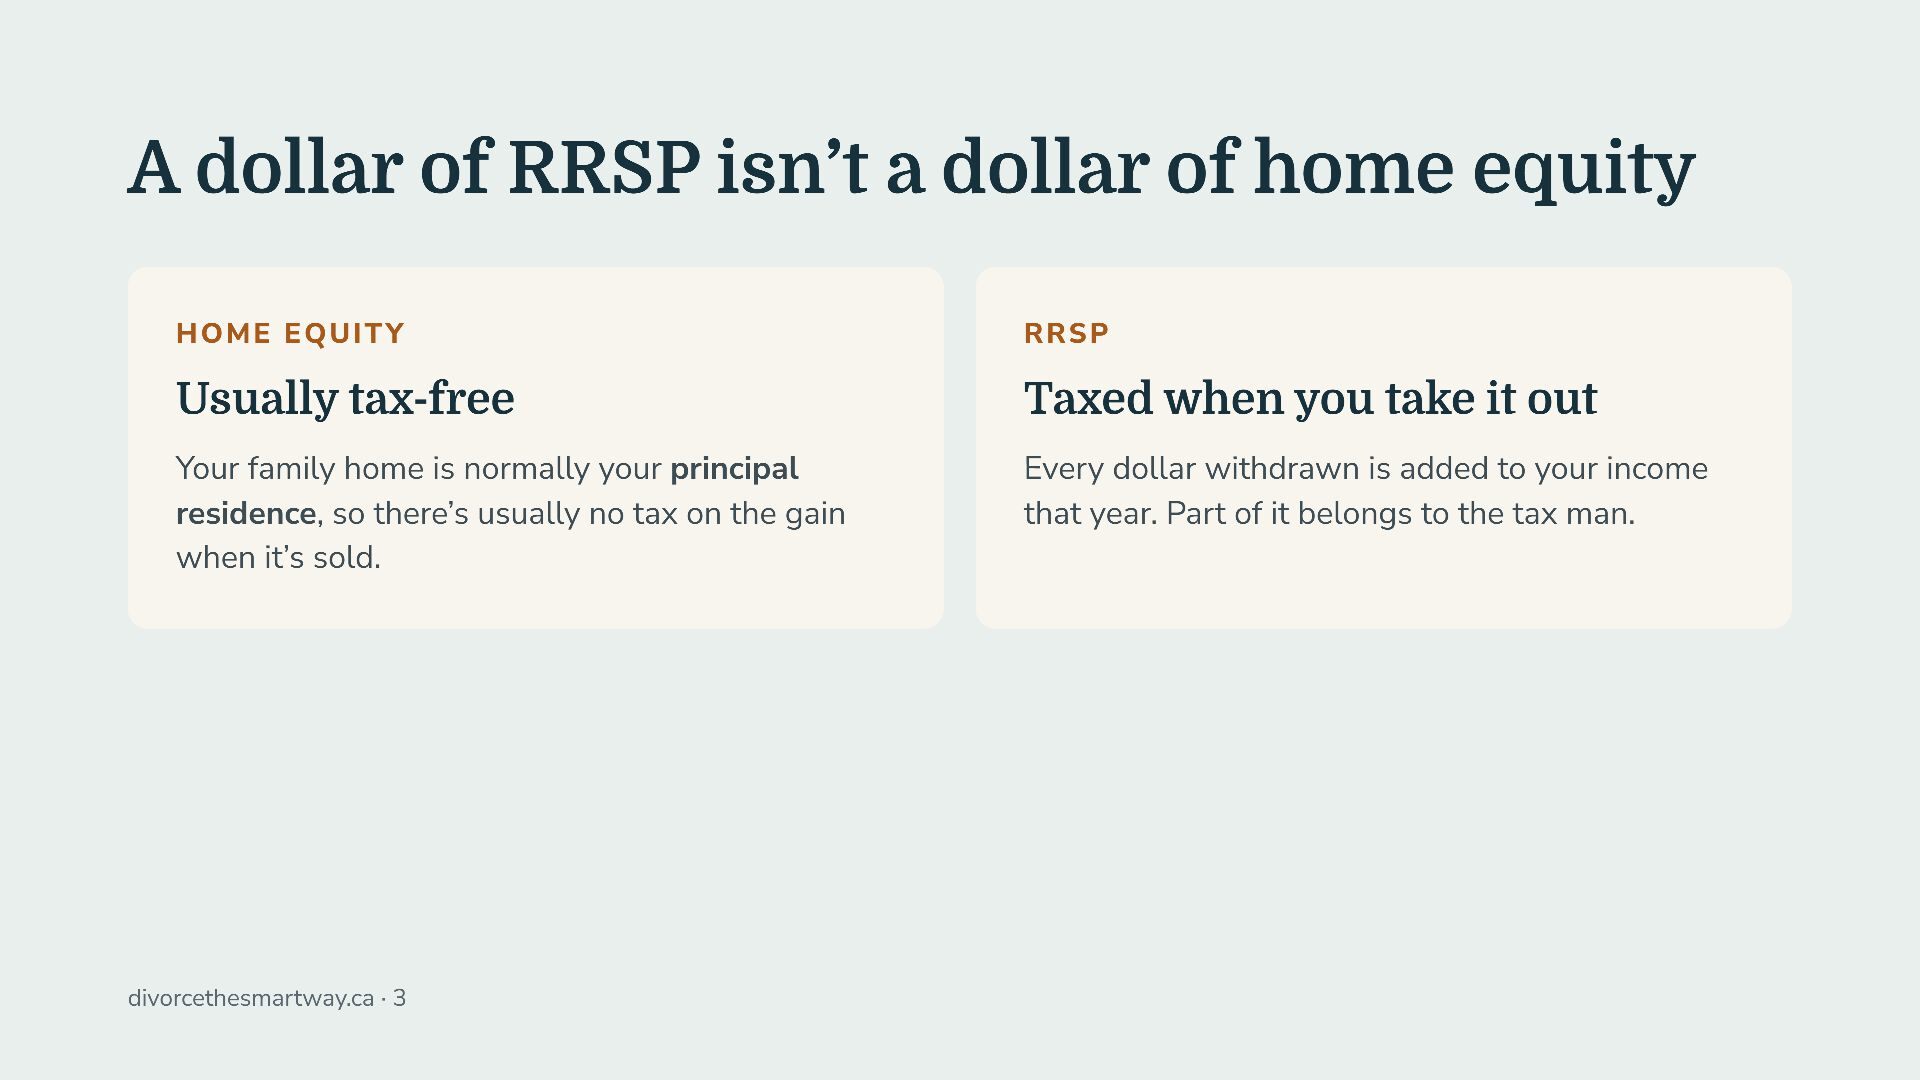
  3. A dollar of RRSP isn’t a dollar of home equity

    Home equity RRSP Usually tax-free Taxed when you take it out Your family home is normally your principal residence, so there’s usually no tax on the gain when it’s sold. Every dollar withdrawn is added to your income that year. Part of it belongs to the tax man. divorcethesmartway.ca · 3
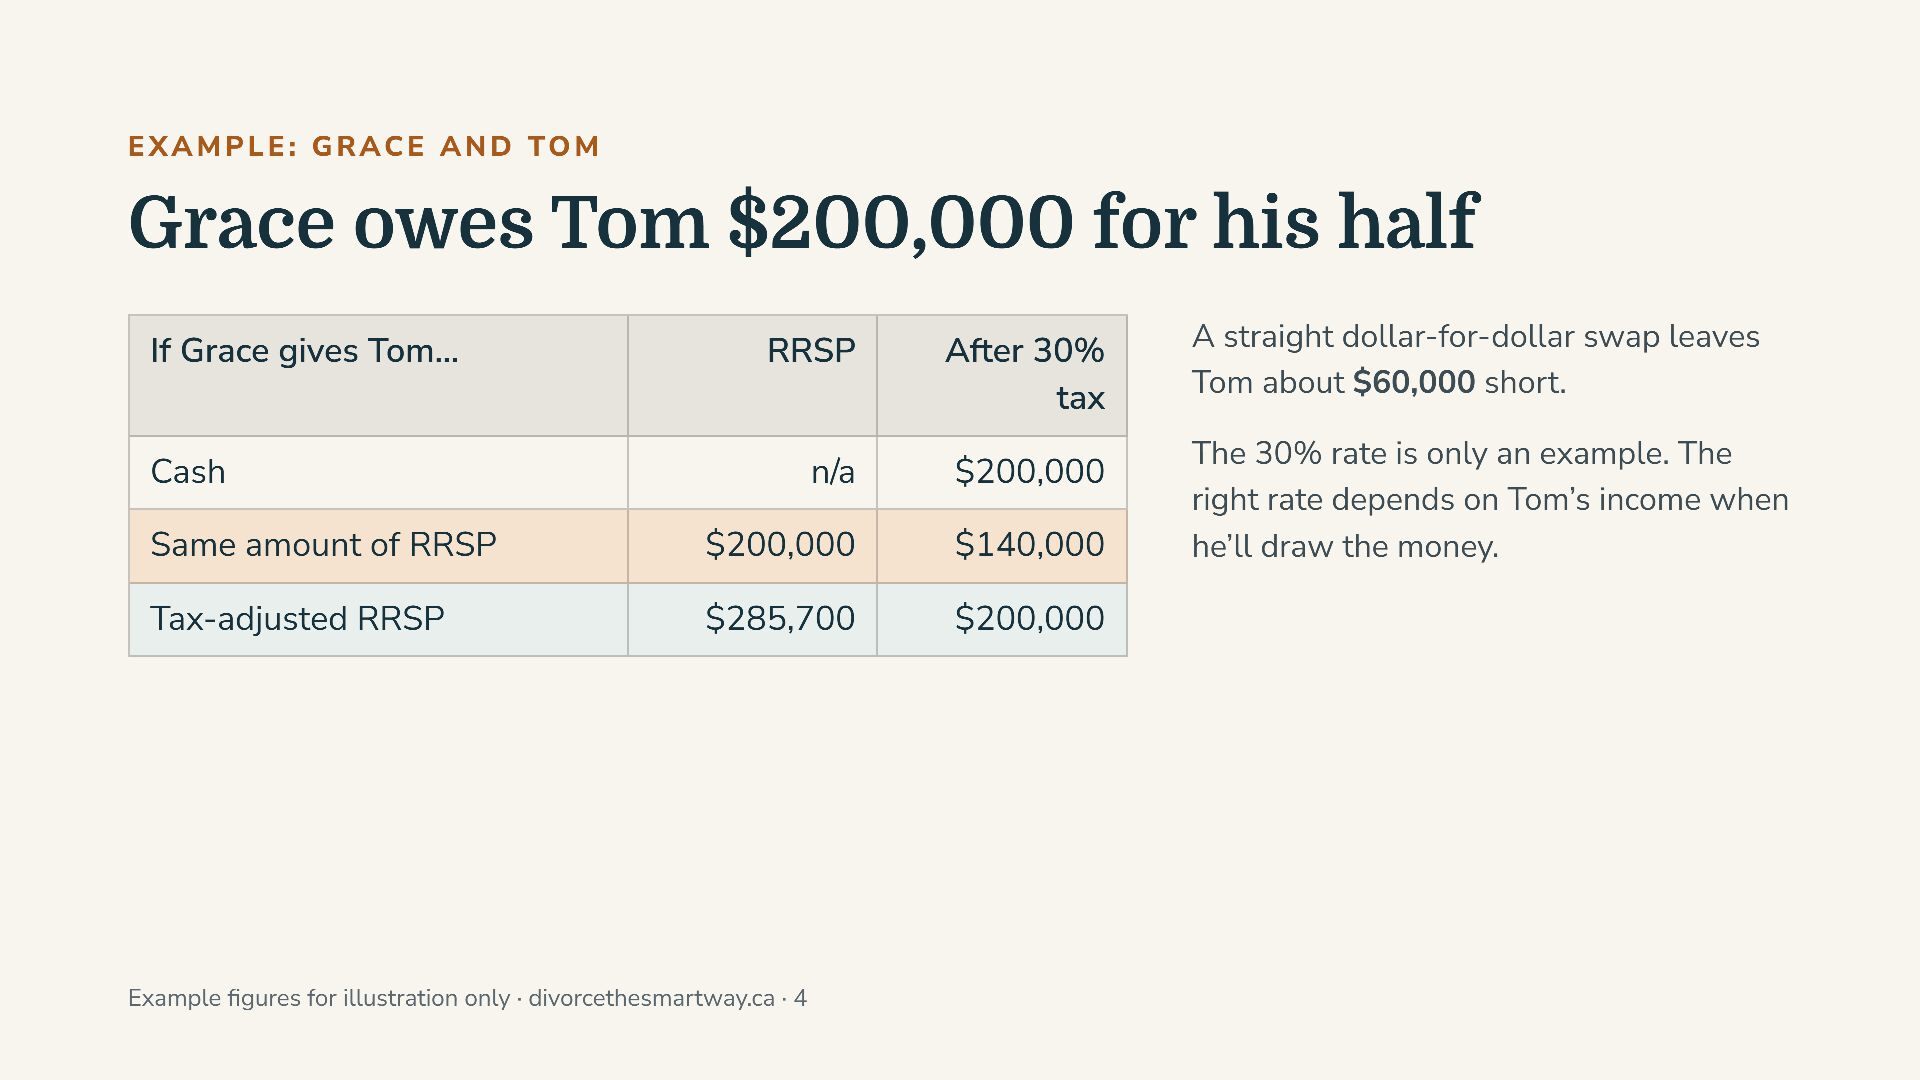
  4. Example: Grace and Tom Grace owes Tom $200,000 for his

    half If Grace gives Tom… RRSP After 30% tax n/a $200,000 Same amount of RRSP $200,000 $140,000 Tax-adjusted RRSP $285,700 $200,000 Cash Example figures for illustration only · divorcethesmartway.ca · 4 A straight dollar-for-dollar swap leaves Tom about $60,000 short. The 30% rate is only an example. The right rate depends on Tom’s income when he’ll draw the money.
  5. Moving the RRSP Transfer it the right way and no

    tax is due now Tax-free transfer Costly mistake You live apart, a written separation agreement or court order divides the money, and it moves straight from your plan to theirs using CRA Form T2220. Cash it out first and hand over the money, and the full withdrawal counts as your income. You pay the tax, not your spouse. Confirm the details with your financial institution · divorcethesmartway.ca · 5
  6. Trading a pension Pension money is locked in In Ontario,

    the pension plan works out the family law value of the pension for you. That number is the starting point. A share moved to your spouse usually goes into a locked-in account. They can’t spend it until retirement age, apart from a few special cases. Rules vary by plan; ask the plan administrator · divorcethesmartway.ca · 6 What that means for the trade The spouse giving up the house gets money they can’t touch for years. That’s a real cost, so talk it through before you agree.
  7. Before you swap Compare what each of you can actually

    use, and when. Tax: how much is left after tax comes off? divorcethesmartway.ca · 7 Access: can the money be spent now, or is it locked in? Need: who needs a home today, and who needs income later?
  8. Free tool Start with what the buyout would cost in

    cash The Matrimonial Home Buyout Calculator works out the equity, the buyout amount and whether you can fund it. You can get a Spousal Buyout Analysis report by email. divorcethesmartway.ca/tools/matrimonial-home-buyout/ divorcethesmartway.ca · 8
  9. Want the after-tax numbers run for you? Book a free

    Get Acquainted Call by phone or video. As a CDFA, Ken can compare the house, RRSPs and pensions on an after-tax basis, so the trade is fair to both of you. Ken S. Maynard, AP.fm, CDFA Divorce the Smartway 416-849-1696 · divorcethesmartway.ca General information only, not legal, tax or financial advice. Talk to a lawyer and a tax professional about your situation.