Share
Embed
OpenTalks.AI - Евгений Бурнаев, Перцептивное повышение разрешения глубины на основе нейросетей
OpenTalks.AI
February 21, 2020
Transcript
45 slides
-
1/20 Bayesian Models for Prediction of Deposit Churn Profile and
Net Income from Acquiring Sberbank, Treasury Sergey Strelkov, Ksenia Gubina, Denis Orlov Skoltech, ADASE Evgeny Burnaev, Evgeny Egorov -
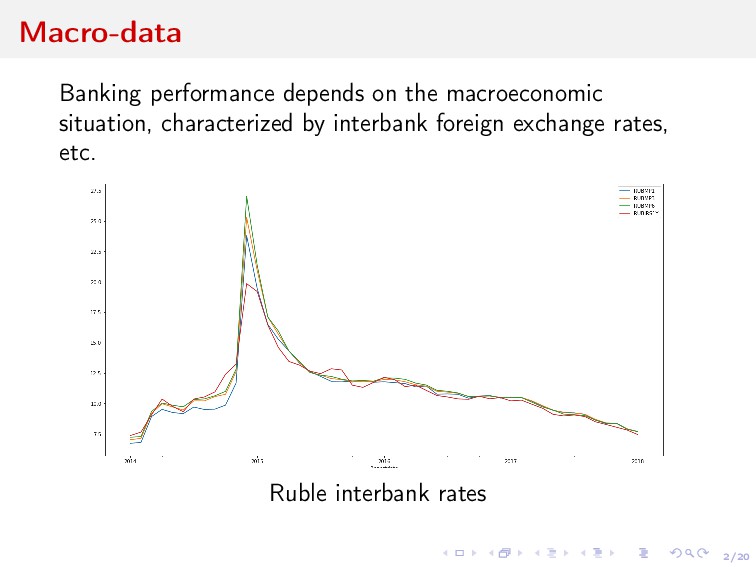
2/20 Macro-data Banking performance depends on the macroeconomic situation, characterized
by interbank foreign exchange rates, etc. Ruble interbank rates -
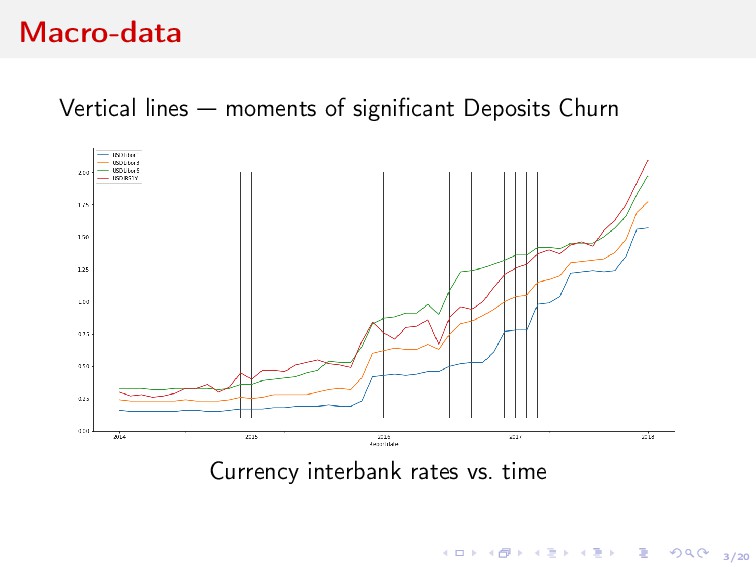
3/20 Macro-data Vertical lines moments of significant Deposits Сhurn Currency
interbank rates vs. time -
4/20 Prediction of Income from Acquiring Capital adequacy and liquidity
risks ⇒ long-term forecasting Net Revenue from Acquiring Deposits Churn -
4/20 Prediction of Income from Acquiring Capital adequacy and liquidity
risks ⇒ long-term forecasting Net Revenue from Acquiring Deposits Churn Vintage economic units grouped by some categorical characteristics and united by time interval -
4/20 Prediction of Income from Acquiring Capital adequacy and liquidity
risks ⇒ long-term forecasting Net Revenue from Acquiring Deposits Churn Vintage economic units grouped by some categorical characteristics and united by time interval Forecast the value of the vintage, or the sum w.r.t. some vintages -
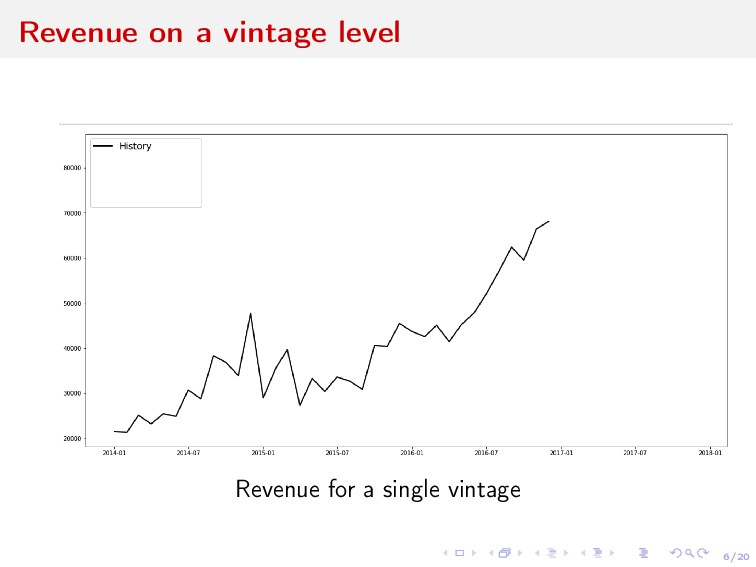
5/20 Acquiring 48 groups j (segment, territory, affiliation of a
client to a bank) Vintage w.r.t. to a starting month of a contract -
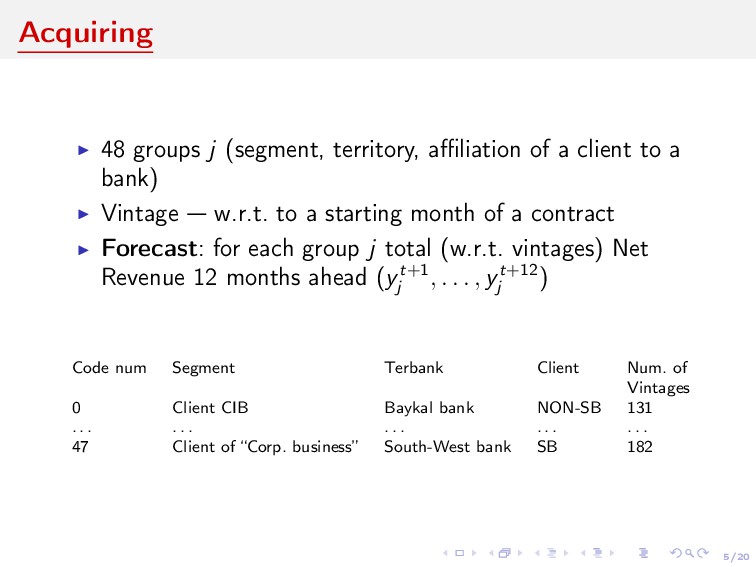
5/20 Acquiring 48 groups j (segment, territory, affiliation of a
client to a bank) Vintage w.r.t. to a starting month of a contract Forecast: for each group j total (w.r.t. vintages) Net Revenue 12 months ahead (yt+1 j , . . . , yt+12 j ) Code num Segment Terbank Client Num. of Vintages 0 Client CIB Baykal bank NON-SB 131 . . . . . . . . . . . . . . . 47 Client of “Corp. business” South-West bank SB 182 -
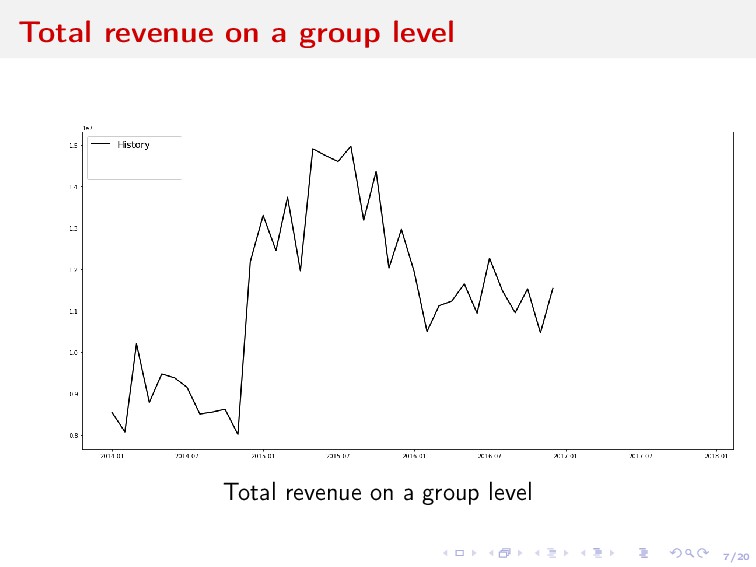
7/20 Total revenue on a group level Total revenue on
a group level -
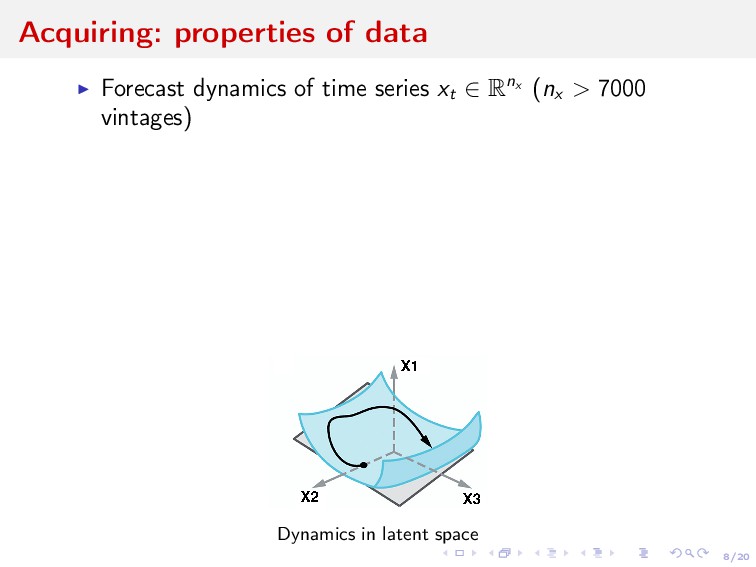
8/20 Acquiring: properties of data Forecast dynamics of time series
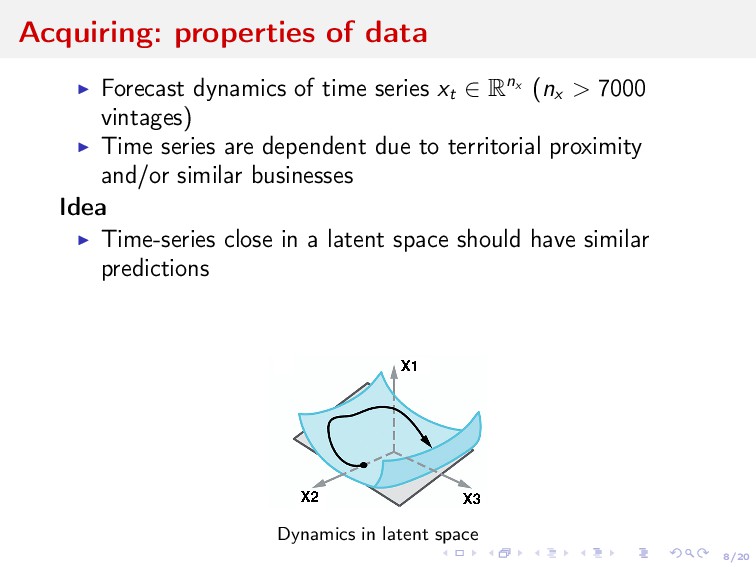
xt ∈ Rnx (nx > 7000 vintages) Dynamics in latent space -
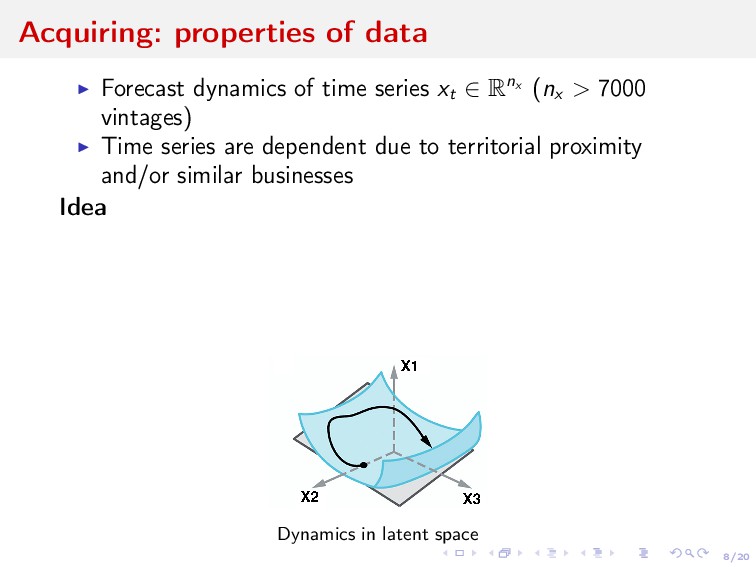
8/20 Acquiring: properties of data Forecast dynamics of time series
xt ∈ Rnx (nx > 7000 vintages) Time series are dependent due to territorial proximity and/or similar businesses Dynamics in latent space -
8/20 Acquiring: properties of data Forecast dynamics of time series
xt ∈ Rnx (nx > 7000 vintages) Time series are dependent due to territorial proximity and/or similar businesses Idea Dynamics in latent space -
8/20 Acquiring: properties of data Forecast dynamics of time series
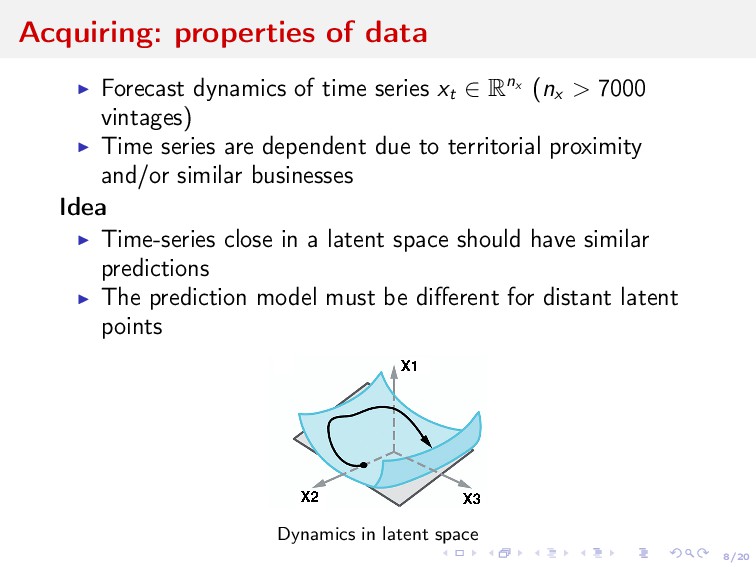
xt ∈ Rnx (nx > 7000 vintages) Time series are dependent due to territorial proximity and/or similar businesses Idea Time-series close in a latent space should have similar predictions Dynamics in latent space -
8/20 Acquiring: properties of data Forecast dynamics of time series
xt ∈ Rnx (nx > 7000 vintages) Time series are dependent due to territorial proximity and/or similar businesses Idea Time-series close in a latent space should have similar predictions The prediction model must be different for distant latent points Dynamics in latent space -
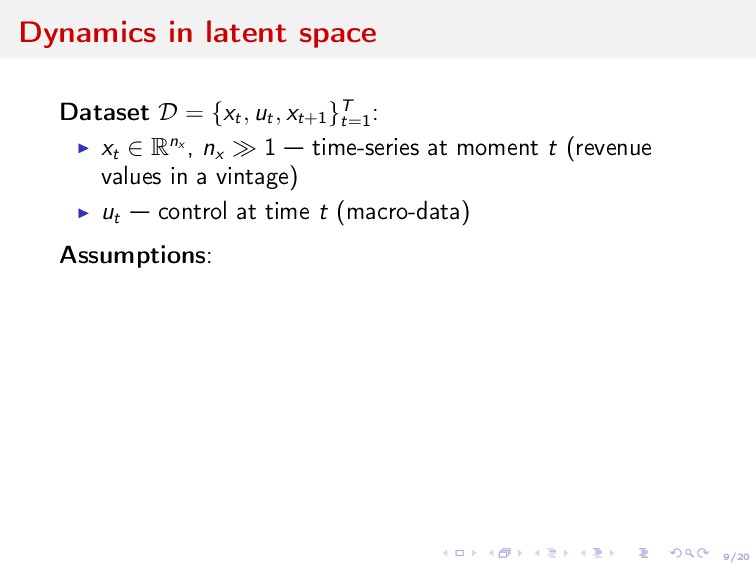
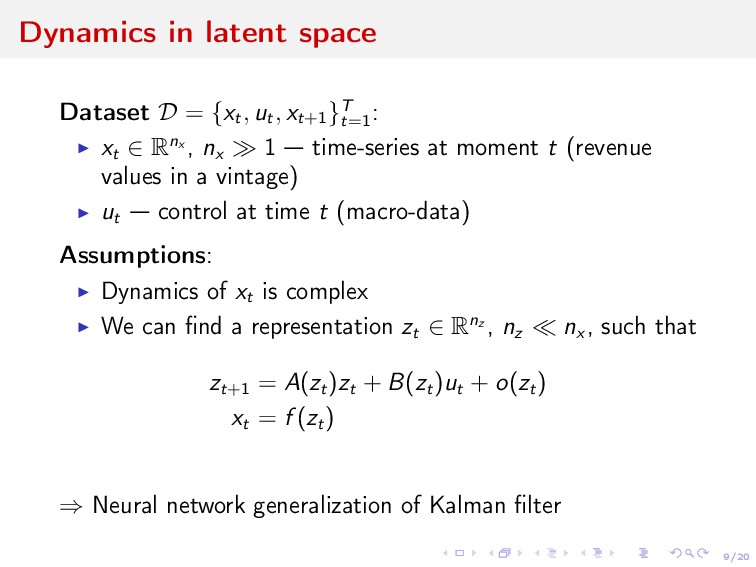
9/20 Dynamics in latent space Dataset D = {xt ,
ut , xt+1 }T t=1 : -
9/20 Dynamics in latent space Dataset D = {xt ,
ut , xt+1 }T t=1 : xt ∈ Rnx , nx 1 time-series at moment t (revenue values in a vintage) -
9/20 Dynamics in latent space Dataset D = {xt ,
ut , xt+1 }T t=1 : xt ∈ Rnx , nx 1 time-series at moment t (revenue values in a vintage) ut control at time t (macro-data) -
9/20 Dynamics in latent space Dataset D = {xt ,
ut , xt+1 }T t=1 : xt ∈ Rnx , nx 1 time-series at moment t (revenue values in a vintage) ut control at time t (macro-data) Assumptions: -
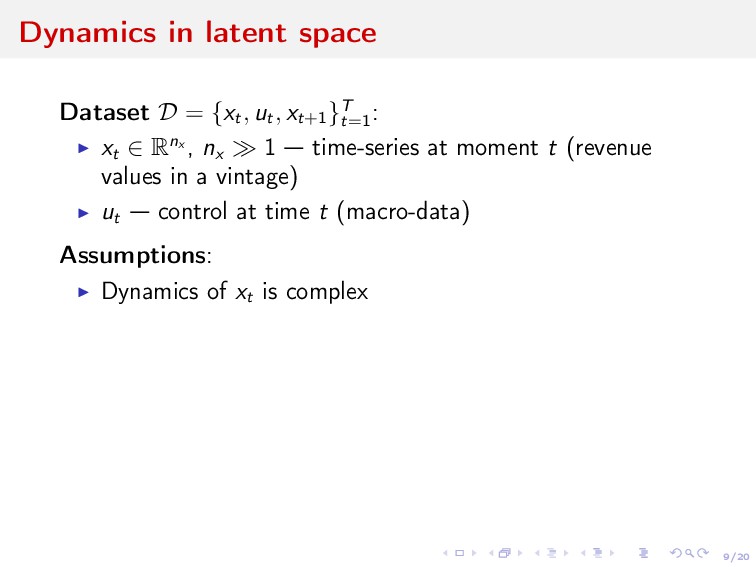
9/20 Dynamics in latent space Dataset D = {xt ,
ut , xt+1 }T t=1 : xt ∈ Rnx , nx 1 time-series at moment t (revenue values in a vintage) ut control at time t (macro-data) Assumptions: Dynamics of xt is complex -
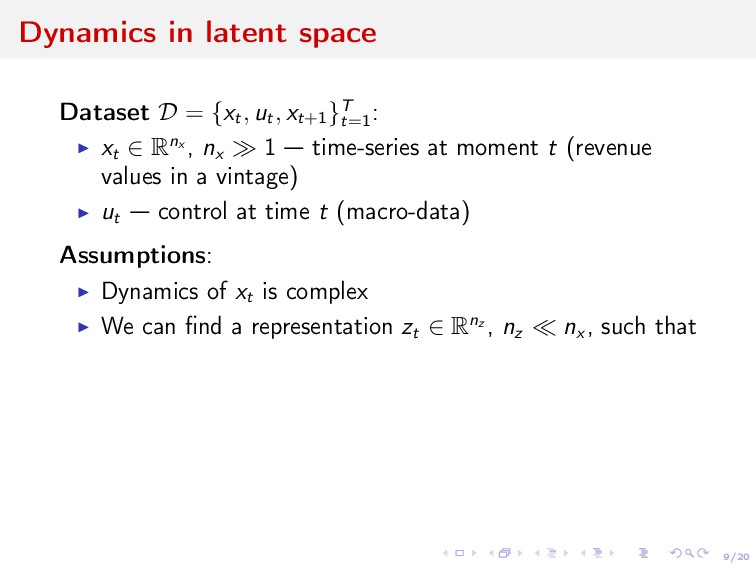
9/20 Dynamics in latent space Dataset D = {xt ,
ut , xt+1 }T t=1 : xt ∈ Rnx , nx 1 time-series at moment t (revenue values in a vintage) ut control at time t (macro-data) Assumptions: Dynamics of xt is complex We can find a representation zt ∈ Rnz , nz nx , such that -
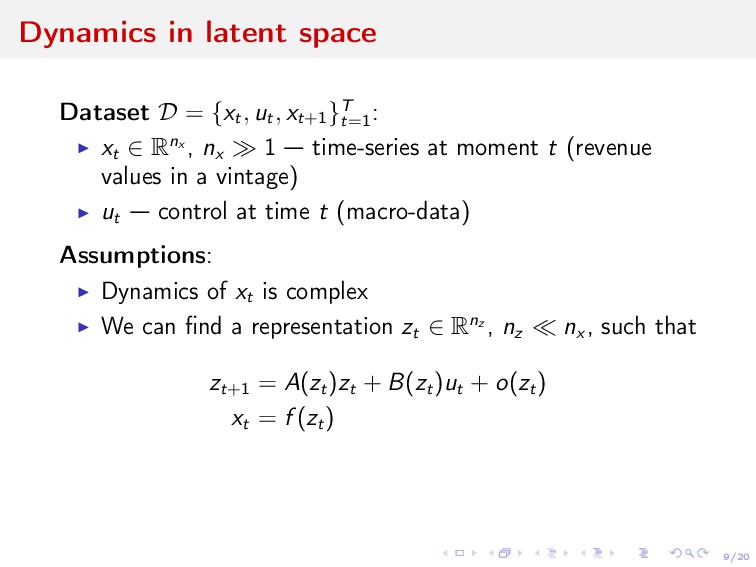
9/20 Dynamics in latent space Dataset D = {xt ,
ut , xt+1 }T t=1 : xt ∈ Rnx , nx 1 time-series at moment t (revenue values in a vintage) ut control at time t (macro-data) Assumptions: Dynamics of xt is complex We can find a representation zt ∈ Rnz , nz nx , such that zt+1 = A(zt )zt + B(zt )ut + o(zt ) xt = f (zt ) -
9/20 Dynamics in latent space Dataset D = {xt ,
ut , xt+1 }T t=1 : xt ∈ Rnx , nx 1 time-series at moment t (revenue values in a vintage) ut control at time t (macro-data) Assumptions: Dynamics of xt is complex We can find a representation zt ∈ Rnz , nz nx , such that zt+1 = A(zt )zt + B(zt )ut + o(zt ) xt = f (zt ) ⇒ Neural network generalization of Kalman filter -
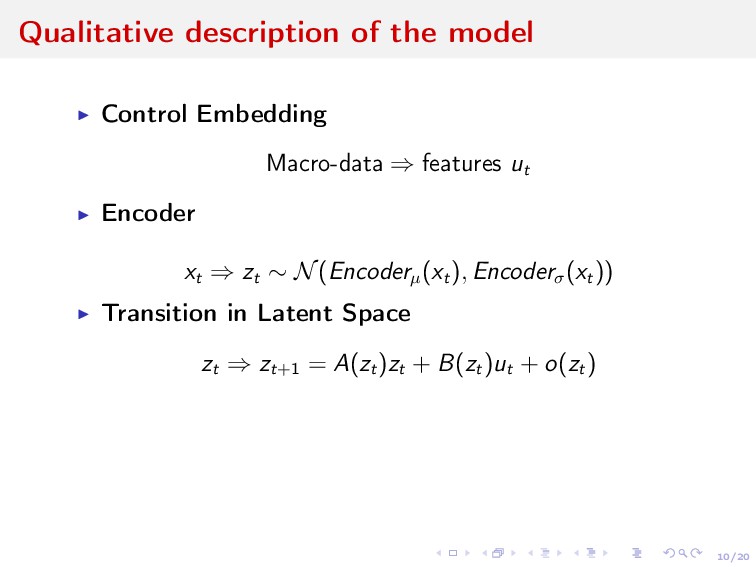
10/20 Qualitative description of the model Control Embedding Macro-data ⇒
features ut Encoder xt ⇒ zt ∼ N(Encoderµ (xt ), Encoderσ (xt )) -
10/20 Qualitative description of the model Control Embedding Macro-data ⇒
features ut Encoder xt ⇒ zt ∼ N(Encoderµ (xt ), Encoderσ (xt )) Transition in Latent Space zt ⇒ zt+1 = A(zt )zt + B(zt )ut + o(zt ) -
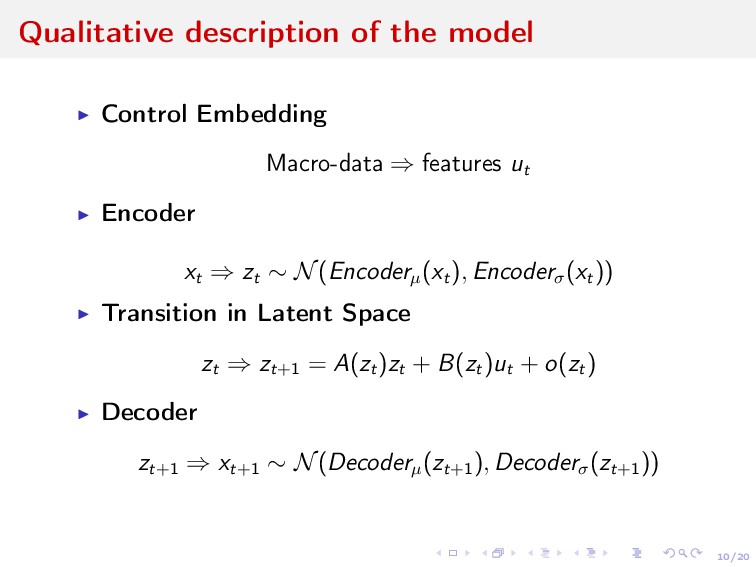
10/20 Qualitative description of the model Control Embedding Macro-data ⇒
features ut Encoder xt ⇒ zt ∼ N(Encoderµ (xt ), Encoderσ (xt )) Transition in Latent Space zt ⇒ zt+1 = A(zt )zt + B(zt )ut + o(zt ) Decoder zt+1 ⇒ xt+1 ∼ N(Decoderµ (zt+1 ), Decoderσ (zt+1 )) -
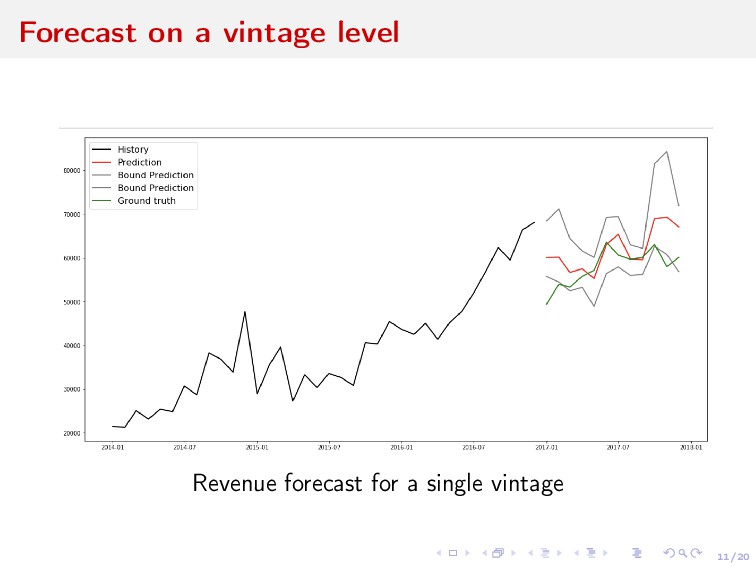
11/20 Forecast on a vintage level Revenue forecast for a
single vintage -
12/20 Forecast on a vintage level Revenue forecast for a
single vintage -
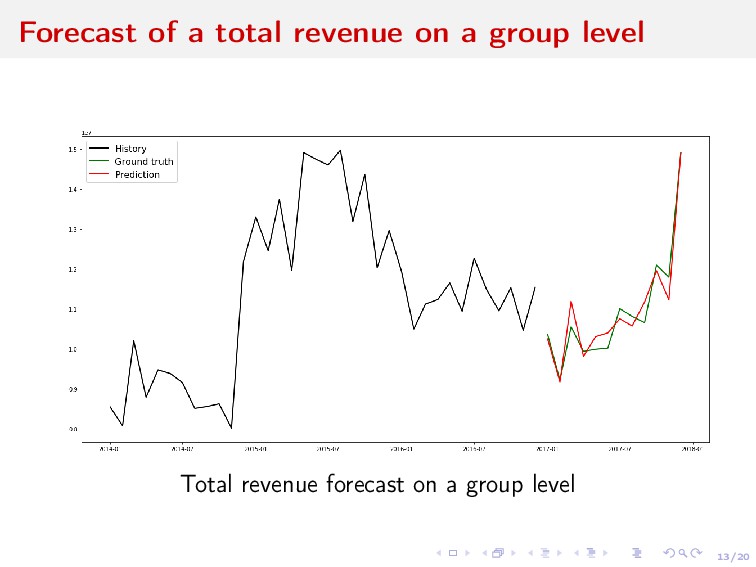
13/20 Forecast of a total revenue on a group level
Total revenue forecast on a group level -
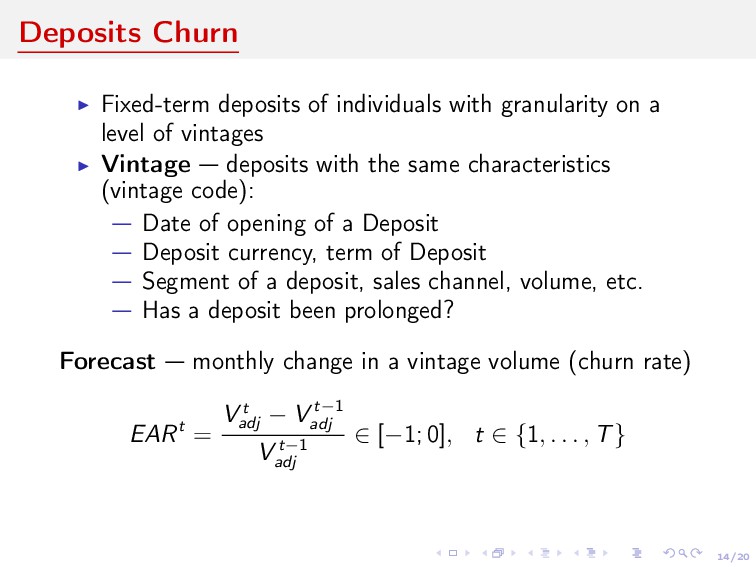
14/20 Deposits Churn Fixed-term deposits of individuals with granularity on
a level of vintages Vintage deposits with the same characteristics (vintage code): -
14/20 Deposits Churn Fixed-term deposits of individuals with granularity on
a level of vintages Vintage deposits with the same characteristics (vintage code): Date of opening of a Deposit Deposit currency, term of Deposit Segment of a deposit, sales channel, volume, etc. Has a deposit been prolonged? -
14/20 Deposits Churn Fixed-term deposits of individuals with granularity on
a level of vintages Vintage deposits with the same characteristics (vintage code): Date of opening of a Deposit Deposit currency, term of Deposit Segment of a deposit, sales channel, volume, etc. Has a deposit been prolonged? Forecast monthly change in a vintage volume (churn rate) EARt = V t adj − V t−1 adj V t−1 adj ∈ [−1; 0], t ∈ {1, . . . , T} -
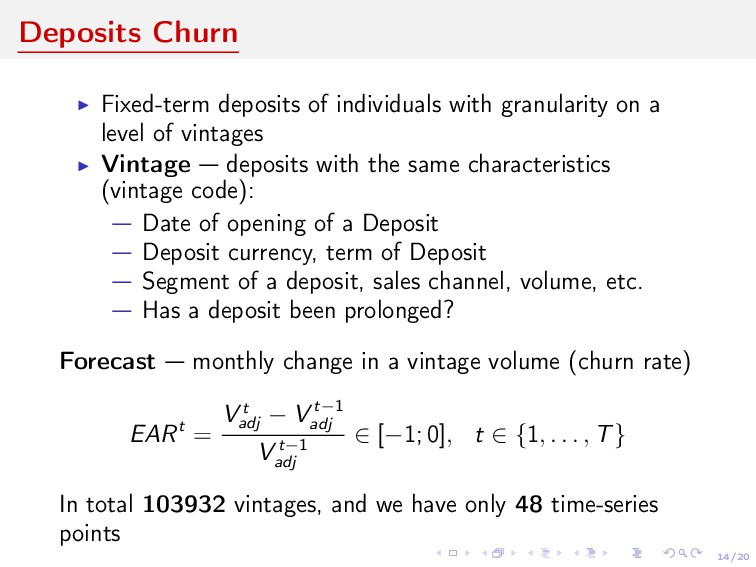
14/20 Deposits Churn Fixed-term deposits of individuals with granularity on
a level of vintages Vintage deposits with the same characteristics (vintage code): Date of opening of a Deposit Deposit currency, term of Deposit Segment of a deposit, sales channel, volume, etc. Has a deposit been prolonged? Forecast monthly change in a vintage volume (churn rate) EARt = V t adj − V t−1 adj V t−1 adj ∈ [−1; 0], t ∈ {1, . . . , T} In total 103932 vintages, and we have only 48 time-series points -
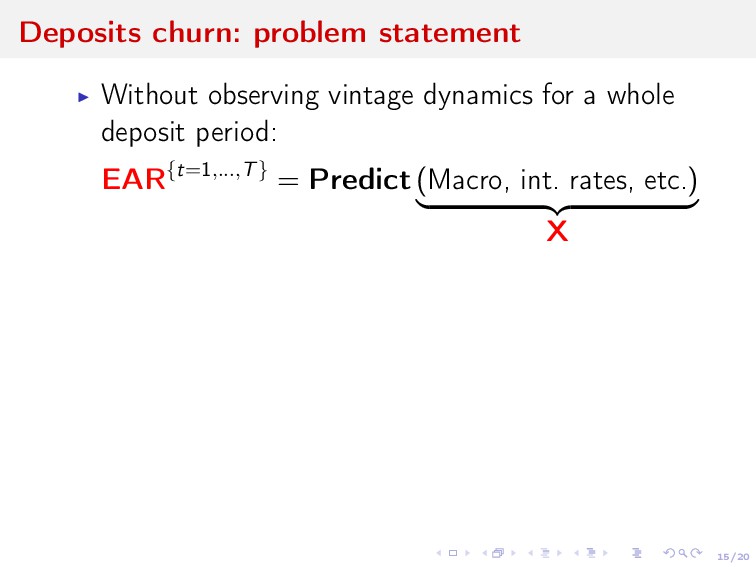
15/20 Deposits churn: problem statement Without observing vintage dynamics for
a whole deposit period: EAR{t=1,...,T} = Predict (Macro, int. rates, etc.) X -
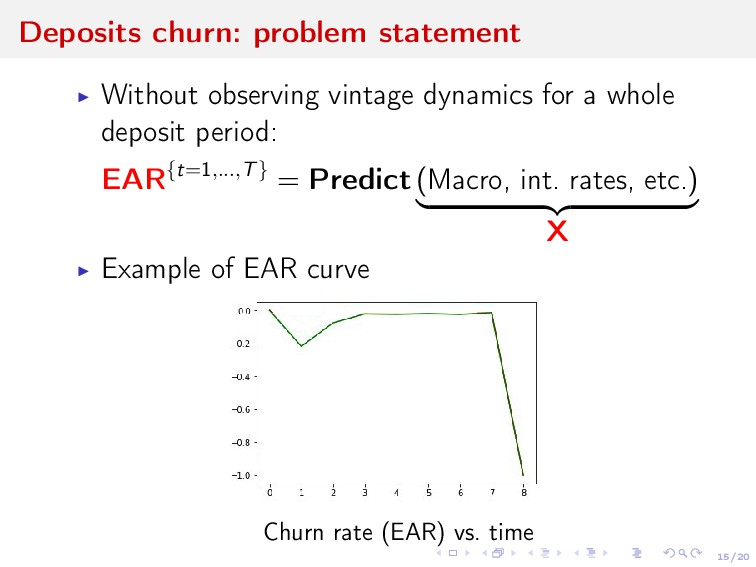
15/20 Deposits churn: problem statement Without observing vintage dynamics for
a whole deposit period: EAR{t=1,...,T} = Predict (Macro, int. rates, etc.) X Example of EAR curve Churn rate (EAR) vs. time -
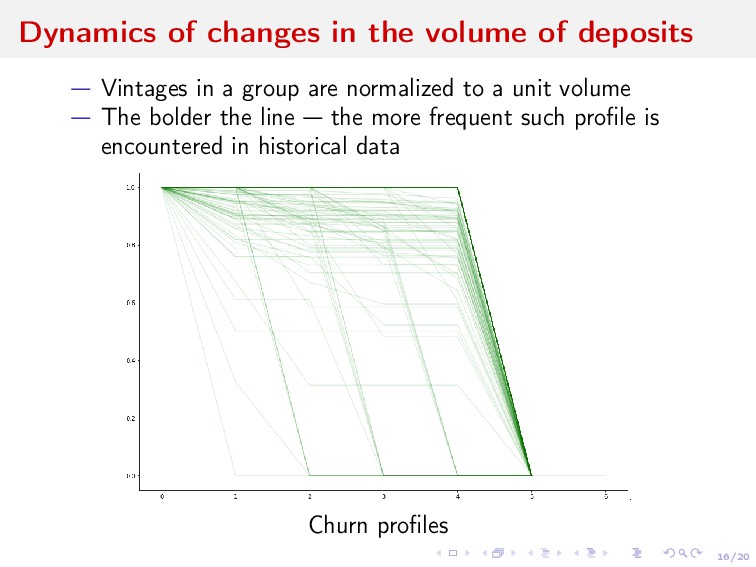
16/20 Dynamics of changes in the volume of deposits Vintages
in a group are normalized to a unit volume The bolder the line the more frequent such profile is encountered in historical data Churn profiles -
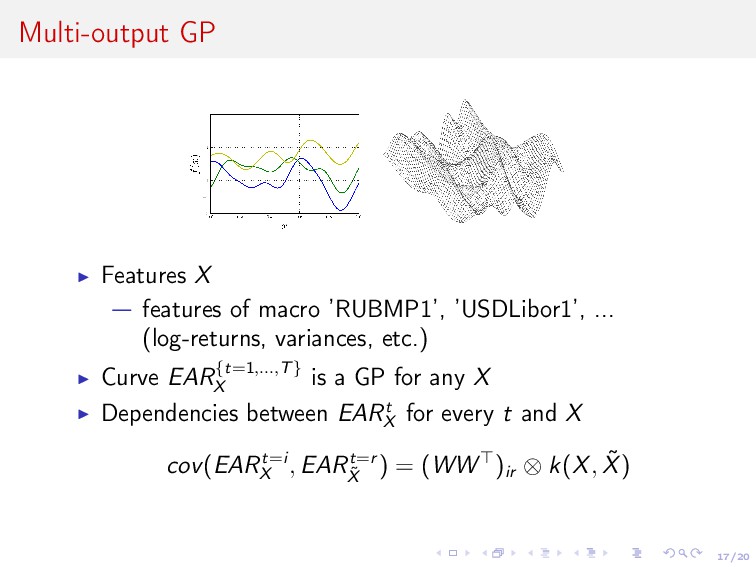
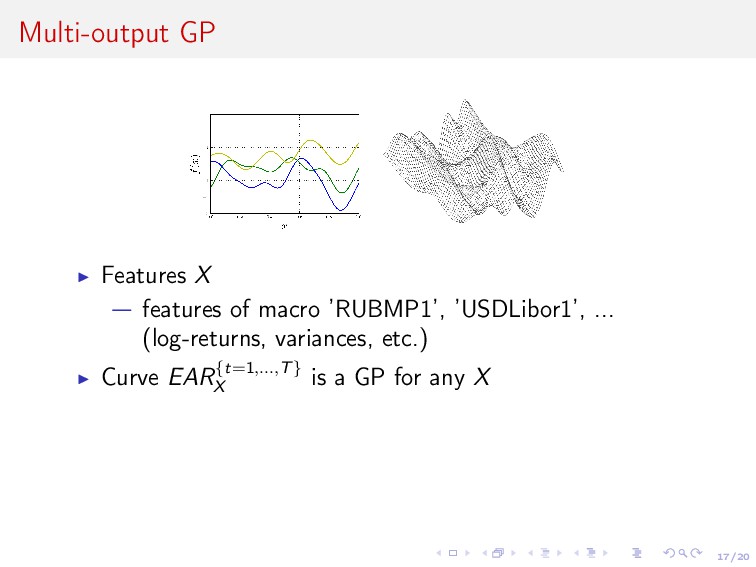
17/20 Multi-output GP Features X features of macro ’RUBMP1’, ’USDLibor1’,
... (log-returns, variances, etc.) -
17/20 Multi-output GP Features X features of macro ’RUBMP1’, ’USDLibor1’,
... (log-returns, variances, etc.) Curve EAR{t=1,...,T} X is a GP for any X -
17/20 Multi-output GP Features X features of macro ’RUBMP1’, ’USDLibor1’,
... (log-returns, variances, etc.) Curve EAR{t=1,...,T} X is a GP for any X Dependencies between EARt X for every t and X cov(EARt=i X , EARt=r ˜ X ) = (WW )ir ⊗ k(X, ˜ X) -
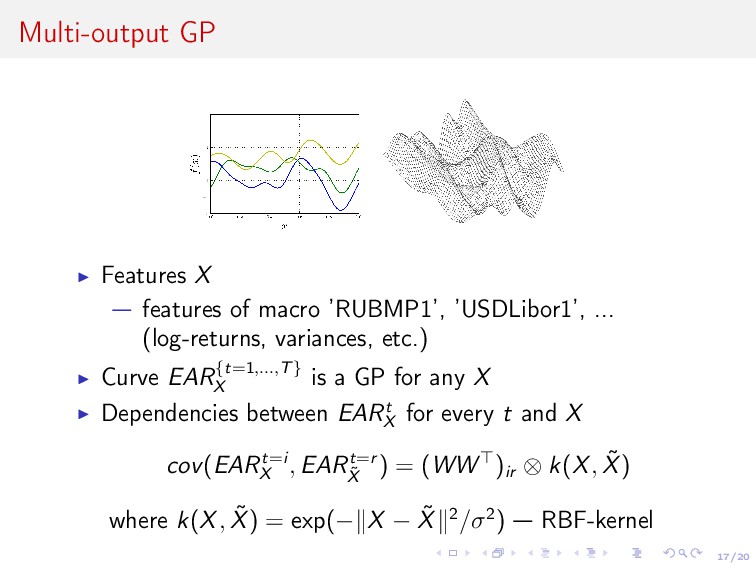
17/20 Multi-output GP Features X features of macro ’RUBMP1’, ’USDLibor1’,
... (log-returns, variances, etc.) Curve EAR{t=1,...,T} X is a GP for any X Dependencies between EARt X for every t and X cov(EARt=i X , EARt=r ˜ X ) = (WW )ir ⊗ k(X, ˜ X) where k(X, ˜ X) = exp(− X − ˜ X 2/σ2) RBF-kernel -
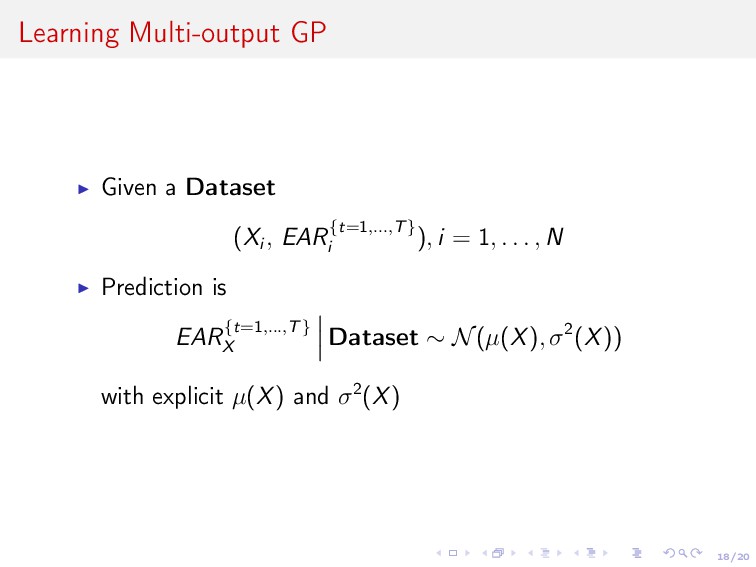
18/20 Learning Multi-output GP Given a Dataset (Xi , EAR{t=1,...,T}
i ), i = 1, . . . , N -
18/20 Learning Multi-output GP Given a Dataset (Xi , EAR{t=1,...,T}
i ), i = 1, . . . , N Prediction is EAR{t=1,...,T} X Dataset ∼ N(µ(X), σ2(X)) with explicit µ(X) and σ2(X) -
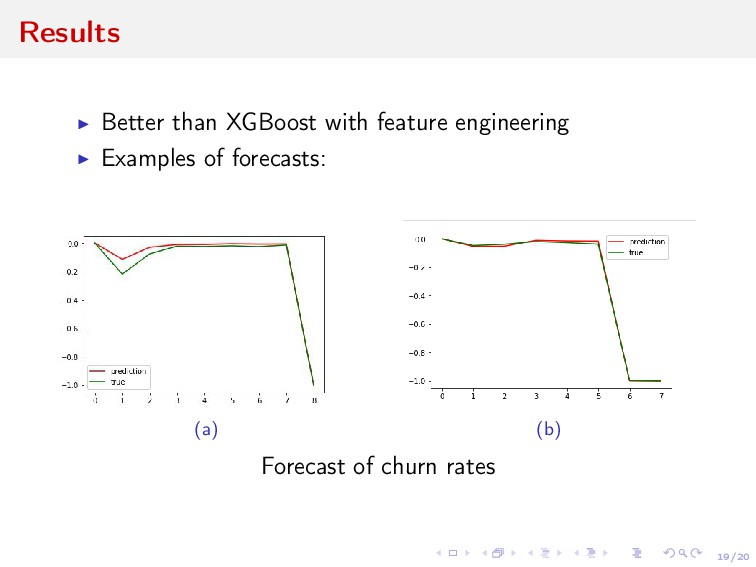
19/20 Results Better than XGBoost with feature engineering Examples of
forecasts: (a) (b) Forecast of churn rates -
20/20 Conclusions Modern Bayesian structural models R&D results are being
tested Production implementation of the constructed models is planned