Upgrade to Pro — share decks privately, control downloads, hide ads and more …

Indonesia Macroeconomic Outlook

Indonesia Macroeconomic Outlook

Avatar for S&P Global Ratings

S&P Global Ratings

May 09, 2019

Other Decks in Business

Transcript

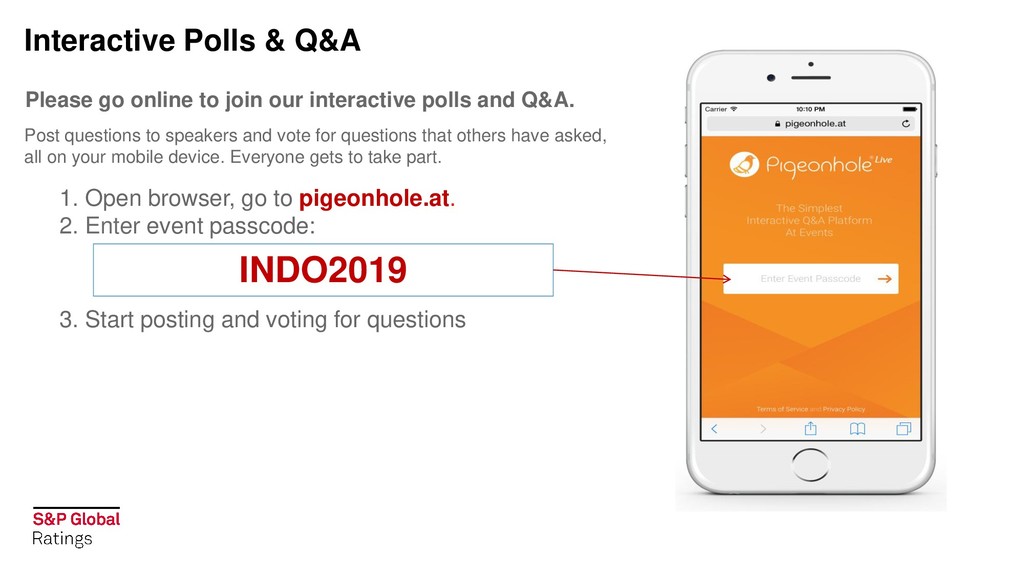
  1. Please go online to join our interactive polls and Q&A.

    Post questions to speakers and vote for questions that others have asked, all on your mobile device. Everyone gets to take part. Interactive Polls & Q&A 1. Open browser, go to pigeonhole.at. 2. Enter event passcode: INDO2019 3. Start posting and voting for questions
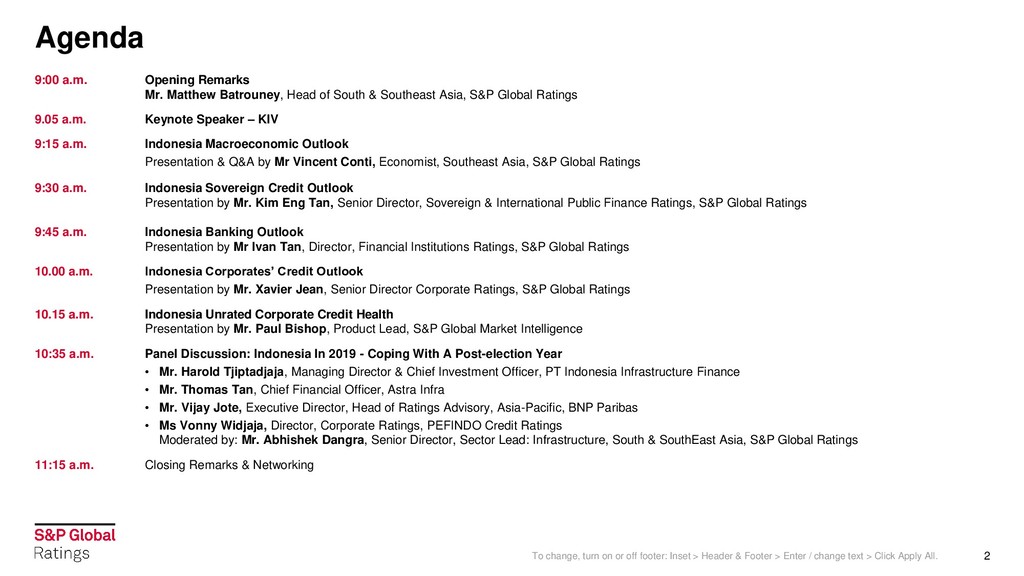
  2. 9:00 a.m. Opening Remarks Mr. Matthew Batrouney, Head of South

    & Southeast Asia, S&P Global Ratings 9.05 a.m. Keynote Speaker – KIV 9:15 a.m. Indonesia Macroeconomic Outlook Presentation & Q&A by Mr Vincent Conti, Economist, Southeast Asia, S&P Global Ratings 9:30 a.m. Indonesia Sovereign Credit Outlook Presentation by Mr. Kim Eng Tan, Senior Director, Sovereign & International Public Finance Ratings, S&P Global Ratings 9:45 a.m. Indonesia Banking Outlook Presentation by Mr Ivan Tan, Director, Financial Institutions Ratings, S&P Global Ratings 10.00 a.m. Indonesia Corporates’ Credit Outlook Presentation by Mr. Xavier Jean, Senior Director Corporate Ratings, S&P Global Ratings 10.15 a.m. Indonesia Unrated Corporate Credit Health Presentation by Mr. Paul Bishop, Product Lead, S&P Global Market Intelligence 10:35 a.m. Panel Discussion: Indonesia In 2019 - Coping With A Post-election Year • Mr. Harold Tjiptadjaja, Managing Director & Chief Investment Officer, PT Indonesia Infrastructure Finance • Mr. Thomas Tan, Chief Financial Officer, Astra Infra • Mr. Vijay Jote, Executive Director, Head of Ratings Advisory, Asia-Pacific, BNP Paribas • Ms Vonny Widjaja, Director, Corporate Ratings, PEFINDO Credit Ratings Moderated by: Mr. Abhishek Dangra, Senior Director, Sector Lead: Infrastructure, South & SouthEast Asia, S&P Global Ratings 11:15 a.m. Closing Remarks & Networking Agenda To change, turn on or off footer: Inset > Header & Footer > Enter / change text > Click Apply All. 2
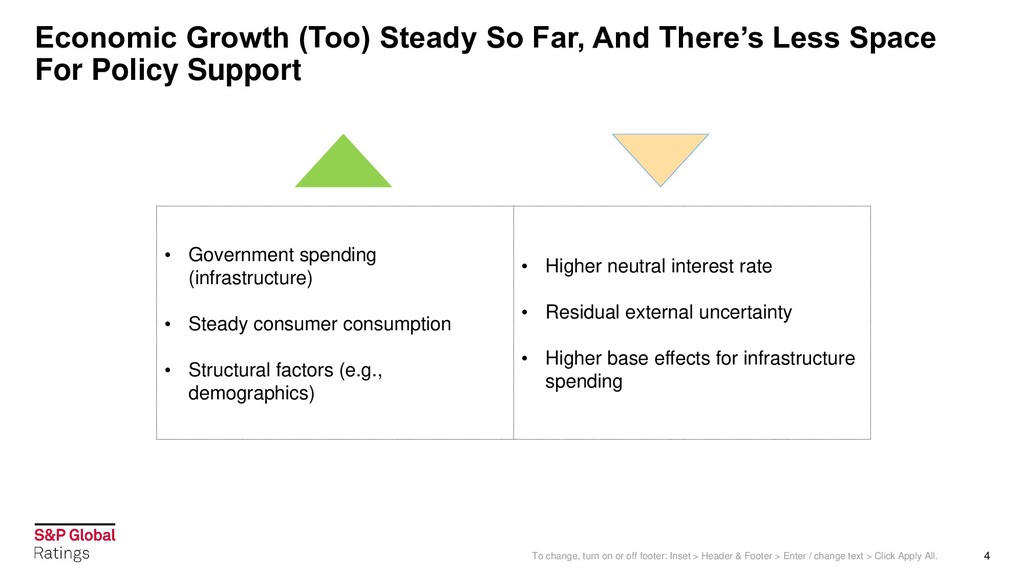
  3. Economic Growth (Too) Steady So Far, And There’s Less Space

    For Policy Support To change, turn on or off footer: Inset > Header & Footer > Enter / change text > Click Apply All. 4 • Government spending (infrastructure) • Steady consumer consumption • Structural factors (e.g., demographics) • Higher neutral interest rate • Residual external uncertainty • Higher base effects for infrastructure spending
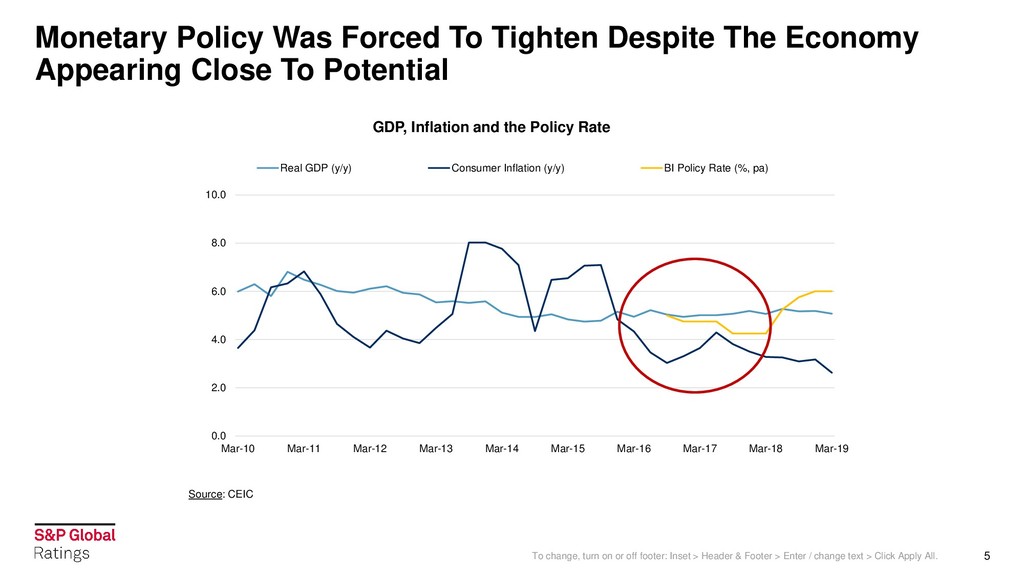
  4. Monetary Policy Was Forced To Tighten Despite The Economy Appearing

    Close To Potential To change, turn on or off footer: Inset > Header & Footer > Enter / change text > Click Apply All. 5 Source: CEIC GDP, Inflation and the Policy Rate 0.0 2.0 4.0 6.0 8.0 10.0 Mar-10 Mar-11 Mar-12 Mar-13 Mar-14 Mar-15 Mar-16 Mar-17 Mar-18 Mar-19 Real GDP (y/y) Consumer Inflation (y/y) BI Policy Rate (%, pa)
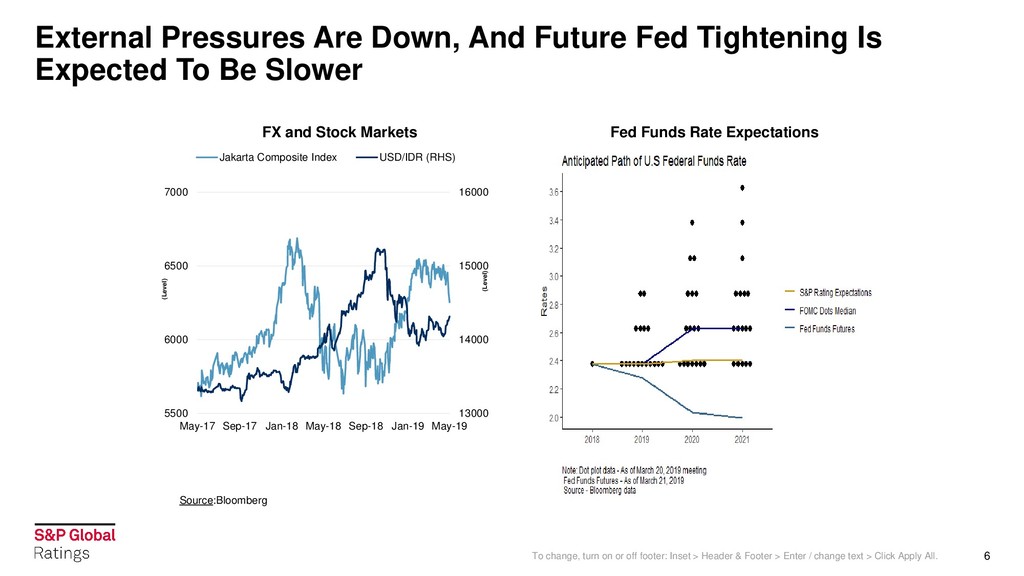
  5. External Pressures Are Down, And Future Fed Tightening Is Expected

    To Be Slower To change, turn on or off footer: Inset > Header & Footer > Enter / change text > Click Apply All. 6 Source:Bloomberg FX and Stock Markets Fed Funds Rate Expectations 13000 14000 15000 16000 5500 6000 6500 7000 May-17 Sep-17 Jan-18 May-18 Sep-18 Jan-19 May-19 (Level) (Level) Jakarta Composite Index USD/IDR (RHS)
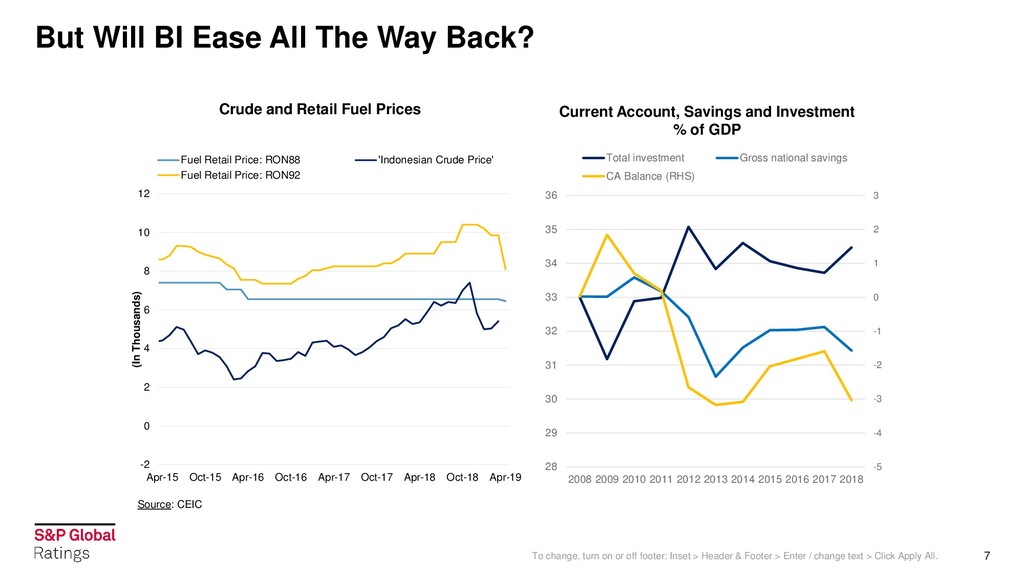
  6. -2 0 2 4 6 8 10 12 Apr-15 Oct-15

    Apr-16 Oct-16 Apr-17 Oct-17 Apr-18 Oct-18 Apr-19 (In Thousands) Fuel Retail Price: RON88 'Indonesian Crude Price' Fuel Retail Price: RON92 But Will BI Ease All The Way Back? To change, turn on or off footer: Inset > Header & Footer > Enter / change text > Click Apply All. 7 Source: CEIC Crude and Retail Fuel Prices Current Account, Savings and Investment % of GDP -5 -4 -3 -2 -1 0 1 2 3 28 29 30 31 32 33 34 35 36 2008 2009 2010 2011 2012 2013 2014 2015 2016 2017 2018 Total investment Gross national savings CA Balance (RHS)
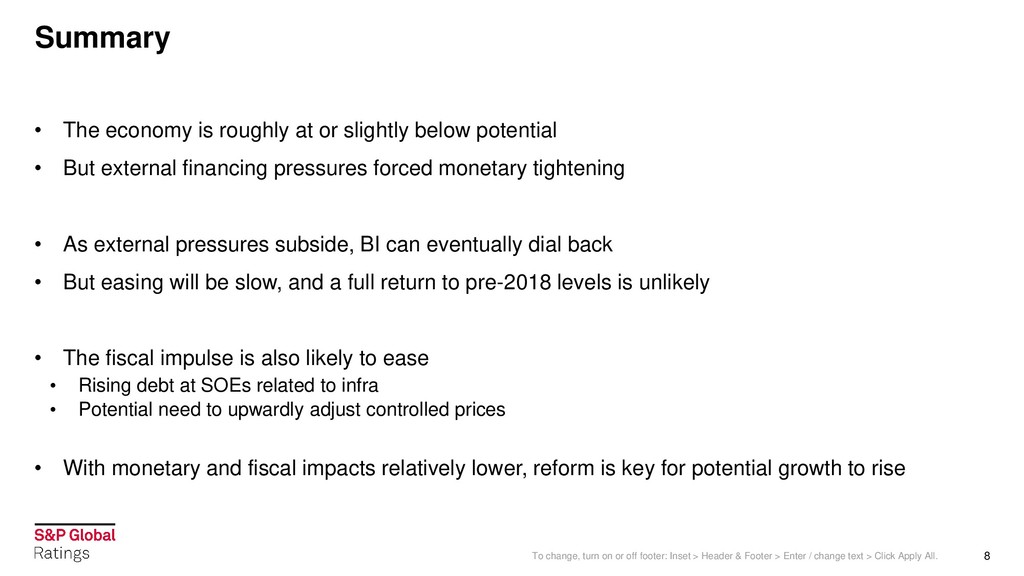
  7. • The economy is roughly at or slightly below potential

    • But external financing pressures forced monetary tightening • As external pressures subside, BI can eventually dial back • But easing will be slow, and a full return to pre-2018 levels is unlikely • The fiscal impulse is also likely to ease • Rising debt at SOEs related to infra • Potential need to upwardly adjust controlled prices • With monetary and fiscal impacts relatively lower, reform is key for potential growth to rise To change, turn on or off footer: Inset > Header & Footer > Enter / change text > Click Apply All. 8 Summary