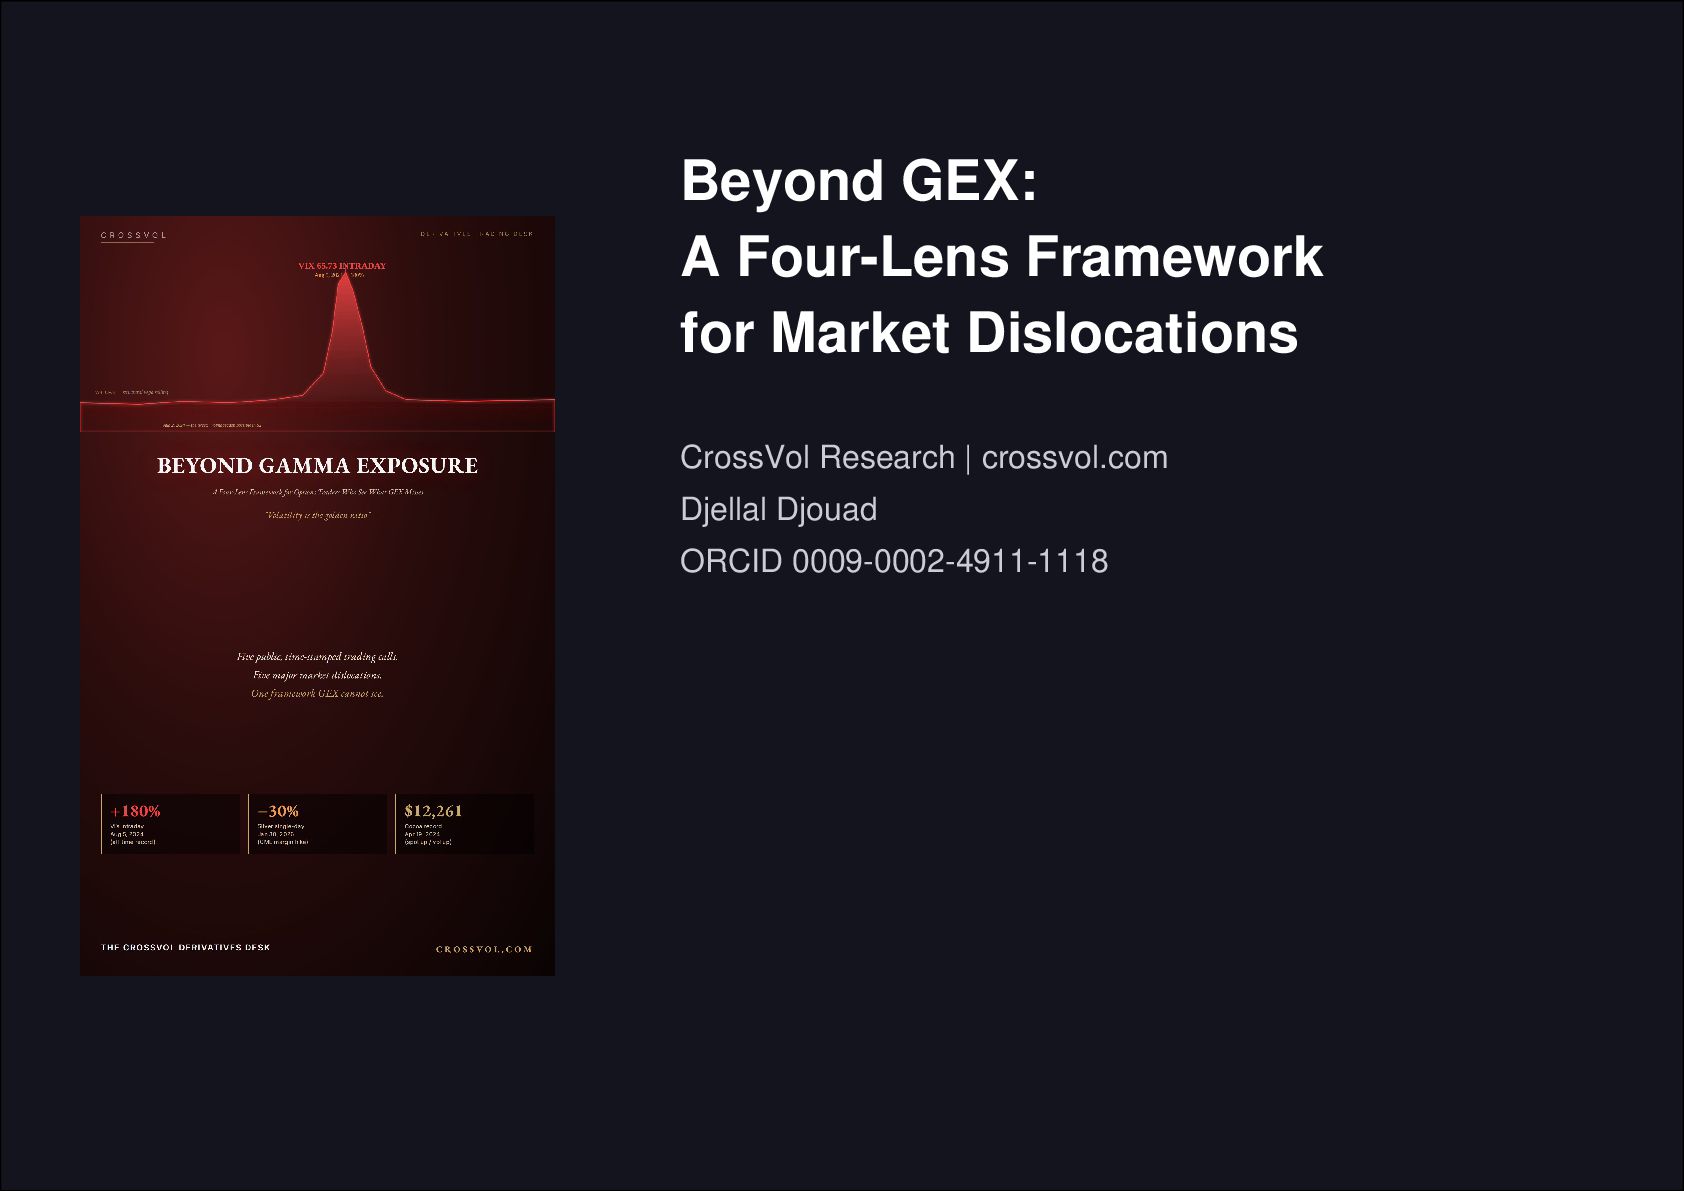
GEX carries a 30-50% error margin. This presentation introduces a four-lens framework reading gamma, vanna, charm, and
volga simultaneously to identify market dislocations before they become consensus.
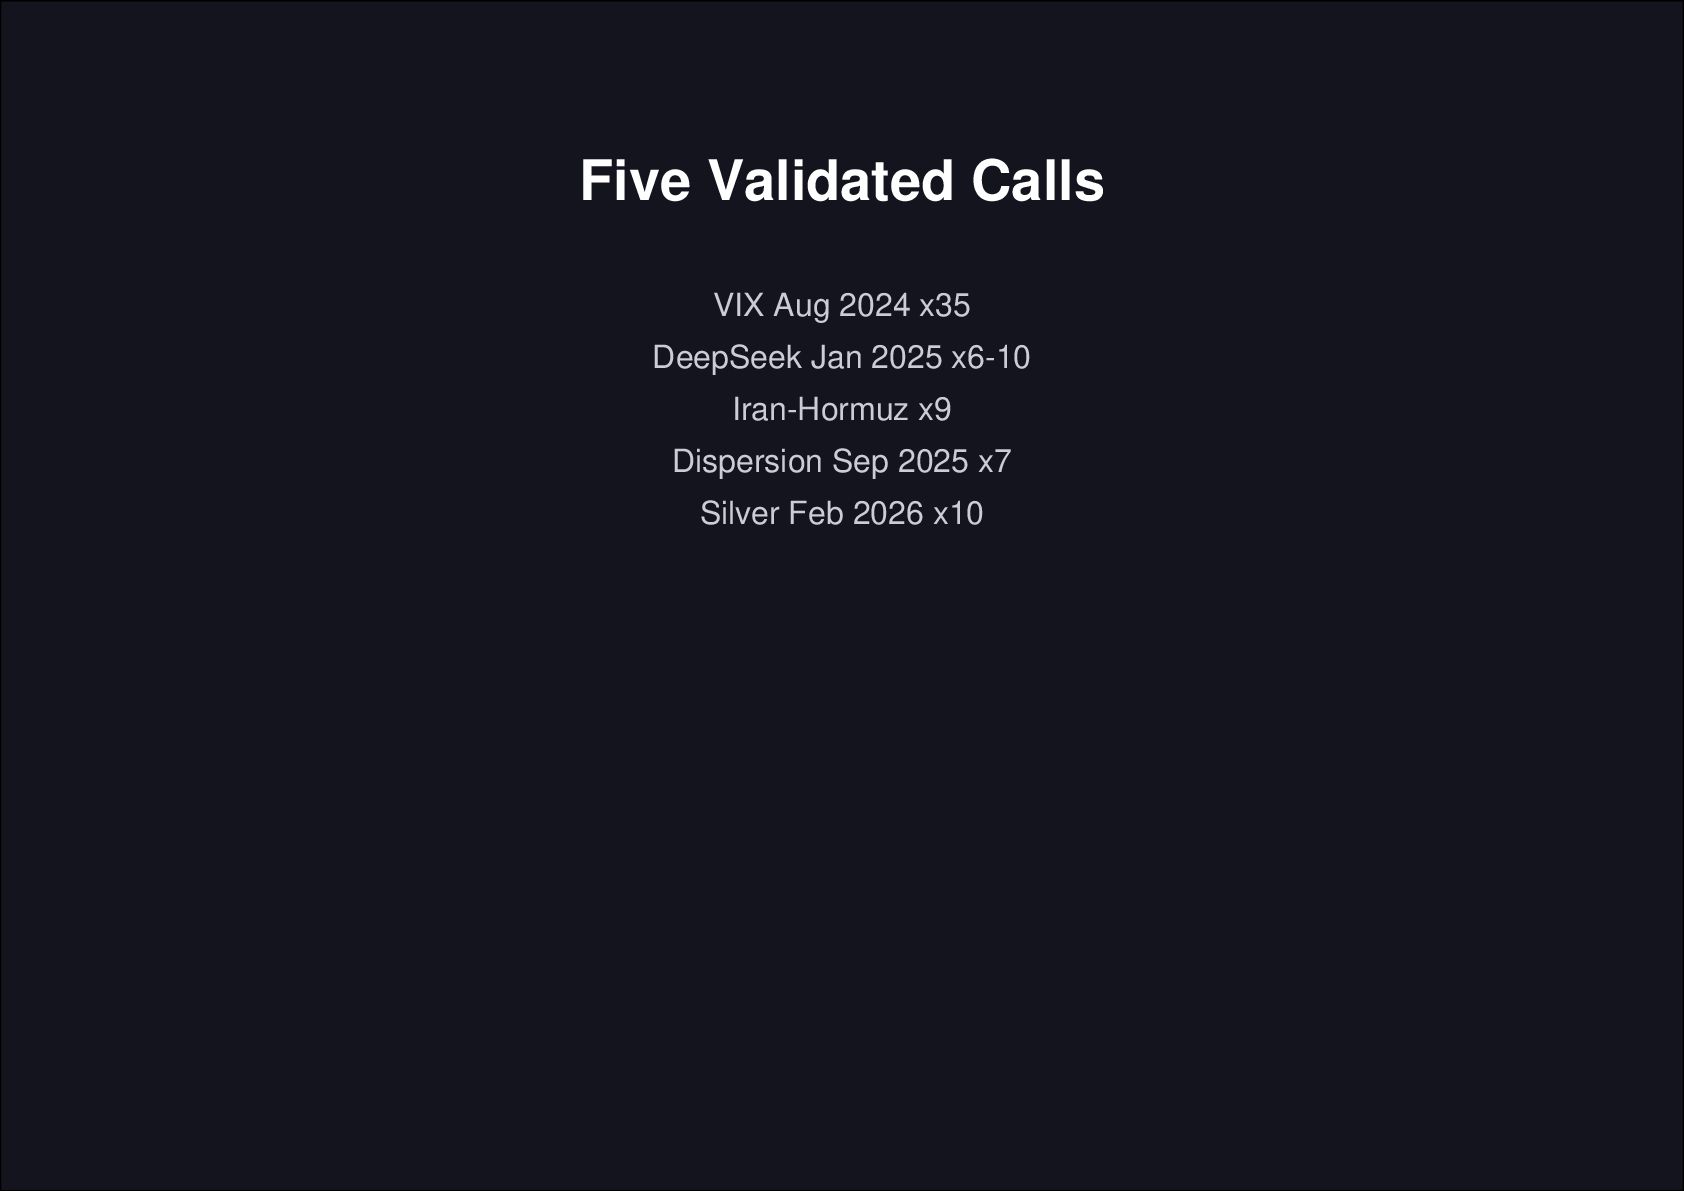
Five validated calls documented: VIX Aug 2024 x35, DeepSeek Jan 2025 x6-10, Iran-Hormuz x9, Dispersion Sep 2025 x7,
Silver Feb 2026 x10.
Topics: options market microstructure, dealer positioning, gamma exposure, vanna exposure, risk reversal, term
structure, pin risk, European autocalls, SPX open interest, private credit systemic risk, AI infrastructure pricing,
FX derivatives structural biases, Chinese AI disruption.
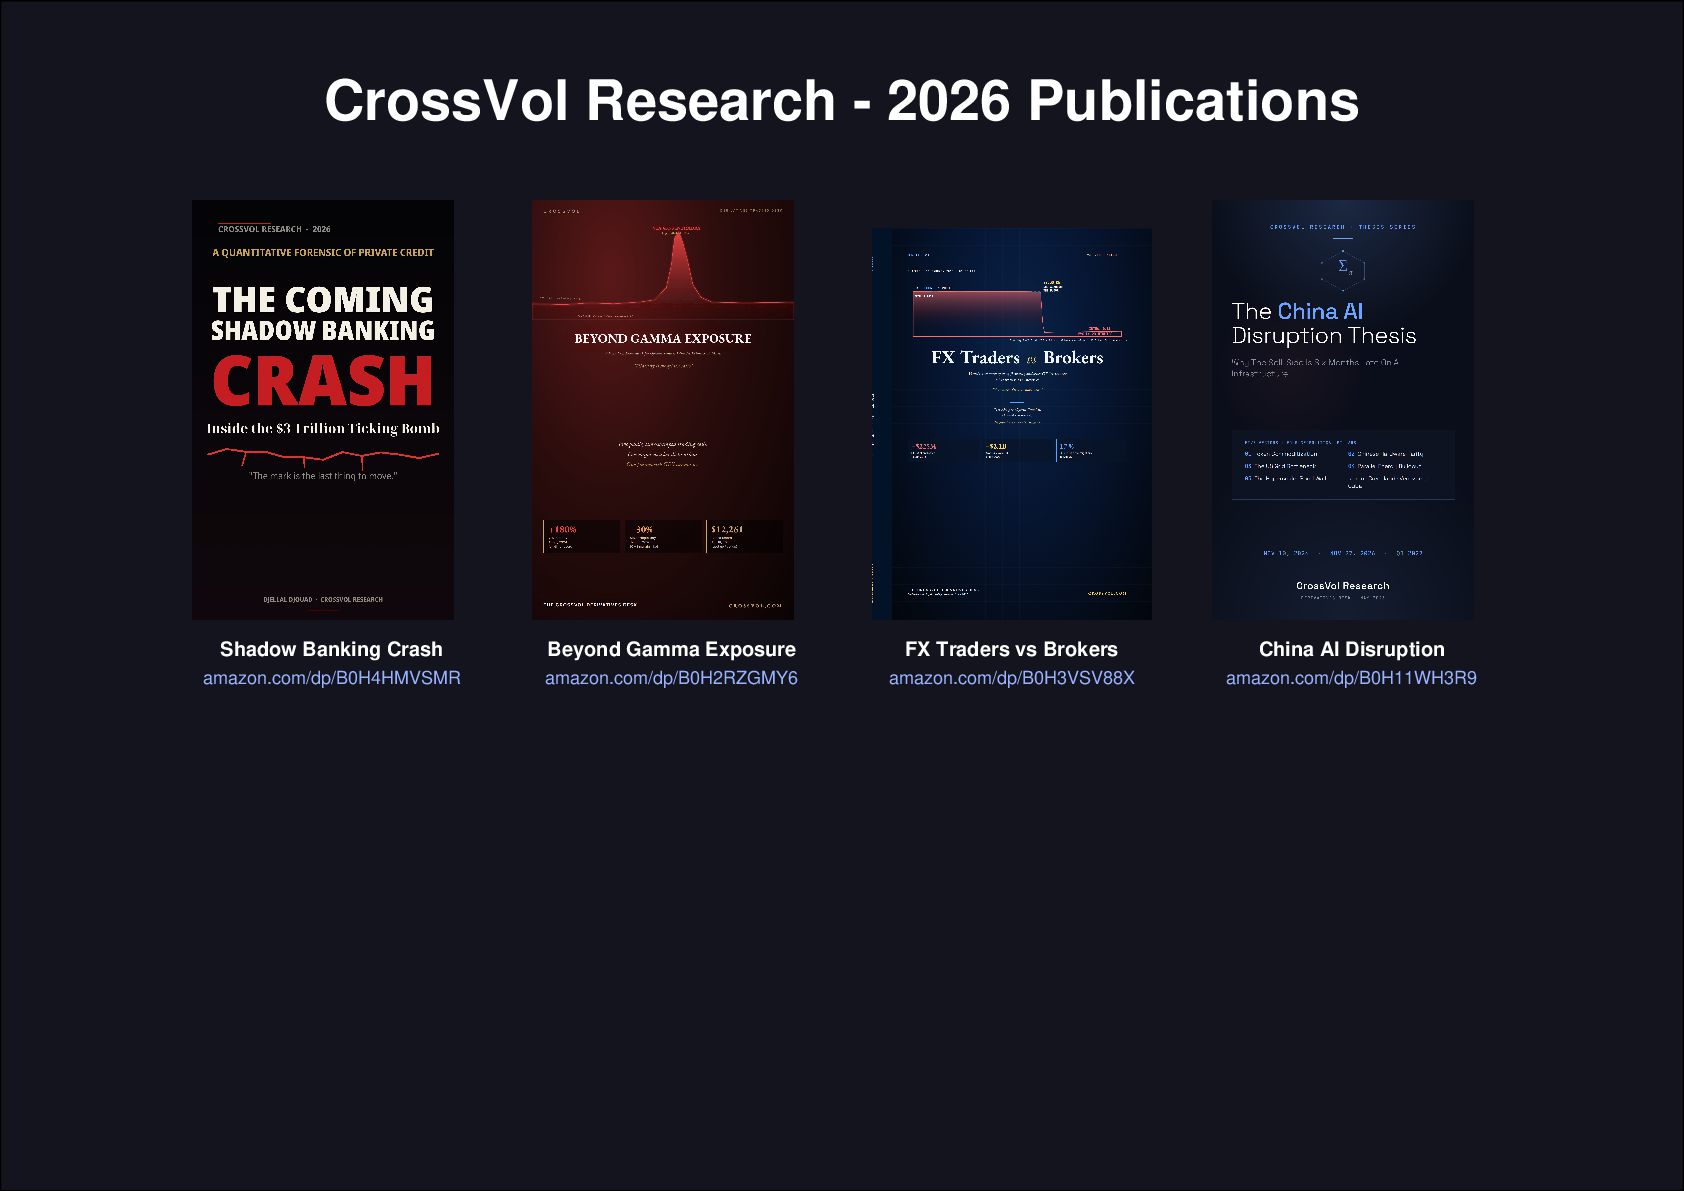
Books by Djellal Djouad (CrossVol Research):
- The Coming Shadow Banking Crash: amazon.com/dp/B0H4HMVSMR
- Beyond Gamma Exposure: amazon.com/dp/B0H2RZGMY6
- FX Traders vs Brokers: amazon.com/dp/B0H3VSV88X
- The China AI Disruption Thesis: amazon.com/dp/B0H11WH3R9
Working papers (open access on Zenodo):
- Convergent Faults — Private Credit Systemic Risk: doi.org/10.5281/zenodo.20558733
- Tokens, Watts, and Geography — AI Inference Pricing: doi.org/10.5281/zenodo.20543628
- Beyond Gamma Exposure — Options Framework: doi.org/10.5281/zenodo.20509786
- FX Retail Structural Biases: doi.org/10.5281/zenodo.20509708
- China AI Disruption Repricing: doi.org/10.5281/zenodo.20509816
ORCID: orcid.org/0009-0002-4911-1118
Google Books: books.google.com/books?id=GGjiEQAAQBAJ
crossvol.com


 arid2
 nakahara
 uniam
 reiwatravel_0405
 takemura_yuto
 todatomohiro
 xinghr
 gpol
 nishika_kae
 ashisuto_career
 mj6237
 rasmusluckow
 thoeni
 szymonslowik
 codingconduct
 chrisshort
 tamaranovitovic
 soudai
 eileencodes
 stephaniewalter
 pedronauck
 lfama
 lindahogenes