Share
Scott Dyer - Mobile Apps in the Canadian Broadcast Ecosystem
Scott Dyer, CTO at Corus Entertainment, will discuss the impact of mobile on the broadcast business. Corus Entertainment is a integrated media company, operating 24 specialty broadcast channels (including YTV, Wnetwork, and Treehouse), 37 radio stations across Canada, and producing kids content through its Nelvana division.
The talk will look at Corus' history in the mobile space, in terms of second screen, game apps, and video distribution, and what we've learned along the way. Mobile is at the center of rapid change in the television industry, and each player in the ecosystem (content producer, broadcaster, and distributor) is evolving their business model to capture mindshare with consumers. Mobile threatens to upend traditional models and financing structures, which is particularly challenging in the regulated Canadian broadcast system. Mobile also ignores most geographic boundaries, further pressuring the traditional models.
Our experiments, both good and bad, customer data, usage statistics, learnings about iOS and Android, and the feedback we get from consumers will be part of this talk.
AndroidTO 2013
Transcript
34 slides
-
Mobile Apps, Android, and a
A Canadian Broadcaster October 17, 2013 -
WHY AM I HERE? Corus Entertainment is a Canadian media
company • Very successful – focused on specialty broadcast • Valuable audiences – Women & Kids • Canadian ecosystem is protected and profitable But … we are in a period of unprecedented change • Technology • Consumer consump=on pa>erns • Deluge of content New broadcast models (for example NeFlix) threaten to upend and destroy the old model before the ecosystem can react and change Content consumpHon anywhere, anyHme has become a consumer requirement How do broadcasters react? 2 -
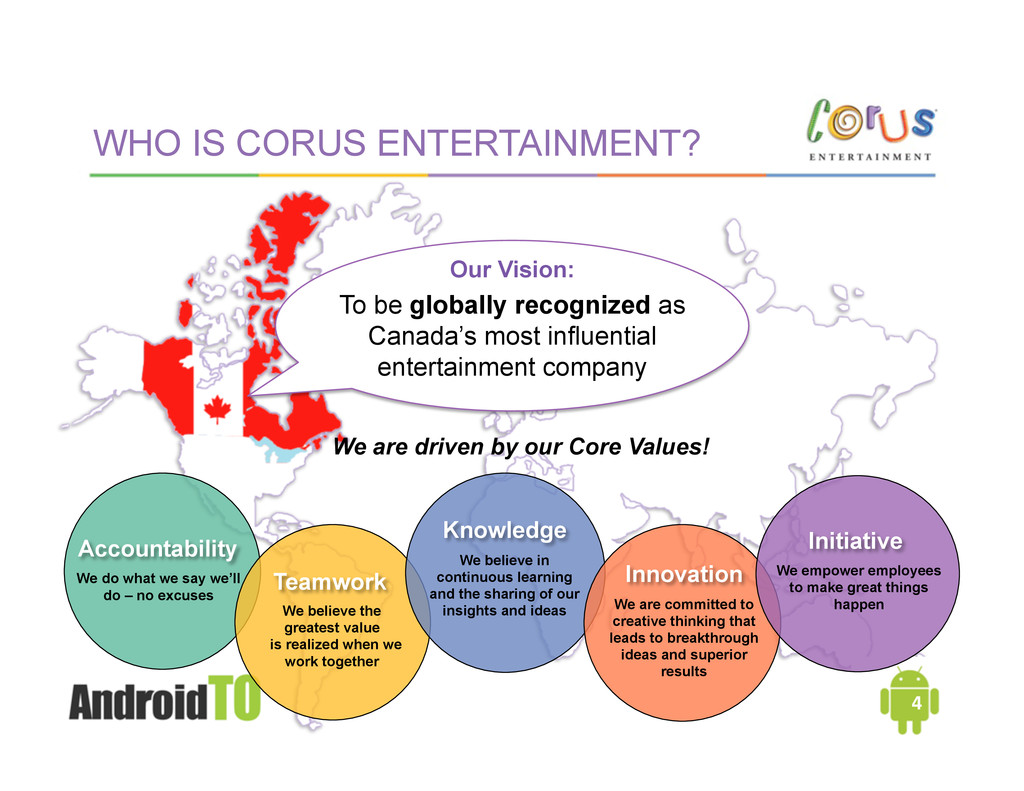
WHO IS CORUS ENTERTAINMENT? Our Vision: To be globally recognized
as Canada’s most influential entertainment company Accountability We do what we say we’ll do – no excuses Teamwork We believe the greatest value is realized when we work together Knowledge We believe in continuous learning and the sharing of our insights and ideas Innovation We are committed to creative thinking that leads to breakthrough ideas and superior results We are driven by our Core Values! 4 Initiative We empower employees to make great things happen -
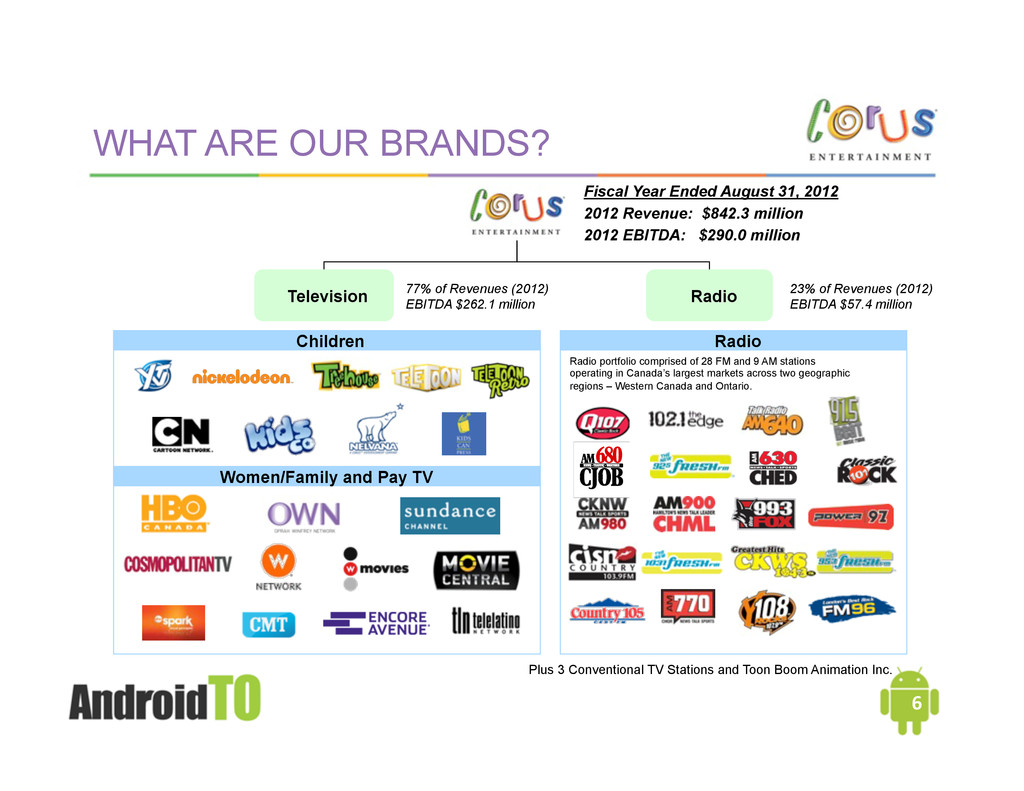
WHAT ARE OUR BRANDS? Television Radio Women/Family and Pay TV
Radio Children Radio portfolio comprised of 28 FM and 9 AM stations operating in Canada’s largest markets across two geographic regions – Western Canada and Ontario. 77% of Revenues (2012) EBITDA $262.1 million Fiscal Year Ended August 31, 2012 2012 Revenue: $842.3 million 2012 EBITDA: $290.0 million 23% of Revenues (2012) EBITDA $57.4 million Plus 3 Conventional TV Stations and Toon Boom Animation Inc. 6 -
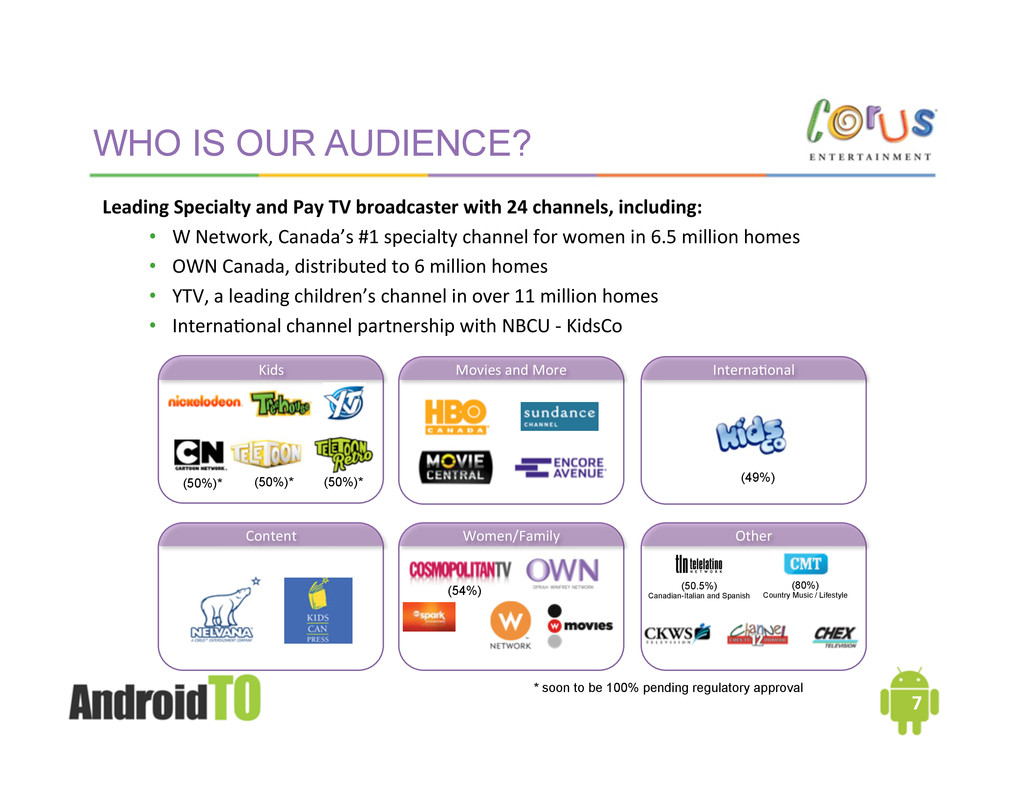
WHO IS OUR AUDIENCE? Leading Specialty and Pay TV broadcaster
with 24 channels, including: • W Network, Canada’s #1 specialty channel for women in 6.5 million homes • OWN Canada, distributed to 6 million homes • YTV, a leading children’s channel in over 11 million homes • Interna=onal channel partnership with NBCU -‐ KidsCo Kids Movies and More Interna=onal Content Women/Family Other (50%)* (50%)* (49%) (54%) (50.5%) Canadian-Italian and Spanish (80%) Country Music / Lifestyle * soon to be 100% pending regulatory approval (50%)* 7 -
WHAT IS OUR CONTENT? Most broadcast content is licensed from
Canadian or internaHonal producers, limiHng our ability to exploit beyond our television services… but Corus owns Nelvana Limited, an integrated kids entertainment company • 40+ year history as a producer of animated content for kids • Content library of 4,000+ half-‐hour episodes • Merchandising success with brands like Beyblade and Bakugan • Content is sold in 100+ countries in dozens of languages 8 -
THE CANADIAN ADVANTAGE BroadcasHng in Canada, both radio and television,
is highly highly regulated • Canadian Radio-‐Television Telecommunica=ons Commission (CRTC) • Recently in the news with hearings (and decision) on Bell’s acquisi=on of Astral Among other things, CRTC regulaHons focus on the creaHon and broadcast of Canadian content • Rules define what is Canadian – creators, funding, producers • Most broadcasters have both significant spend and exhibi=on obliga=ons Canadian Content (Cancon) enjoys significant benefits • Access to higher tax credits • Access to CMF (Canadian Media Fund) and other funding • Be>er broadcast placement 11 -
THE CANADIAN DISADVANTAGE 12 ✘ Complex and occasionally arcane
rules; compliance essenHal to achieving Canadian advantages ✘ Canadian Content regulaHons protect small producers; negoHated Terms of Trade are difficult for producers and broadcasters alike ✘ Canada is a small market • Good content of any form is difficult to exploit/profit (Canada = 10% of U.S) • Regula=ons prevent entry of some US content; Terms of Trade make it difficult to export content south ✘ CRTC regulates spectrum – important for OTA TV, Radio, phone service but meaningless to the internet • Canadians compete on a level playing field against global en==es far larger than domes=c players • Nedlix commands significant viewership but is NOT regulated in Canada -
CORUS & NEW MEDIA New Media is where the acHon
is …. • Fastest growing “consumer” segment (=me spent, impact, reach, analyst coverage) • Adver=sing dollars are moving to Digital … more than TV in 2012 • The change is even more pronounced amongst younger audiences … but Corus is a small player in New Media • Total revenues less than 5%; total profit less than 1% • Mixed bag of assets – websites, limited apps, social media, streaming • Category grouping (ie kids, family, women) to create scale and relevance New Media strategy aaempts to serve mulHple interests • Are we driving viewers/listeners to tradi=onal media OR driving revenue? • Do we want a consumer rela=onship OR a rela=onship via tradi=onal partners (i.e. distributors such as Bell and Rogers)? ! We want everything. 14 -
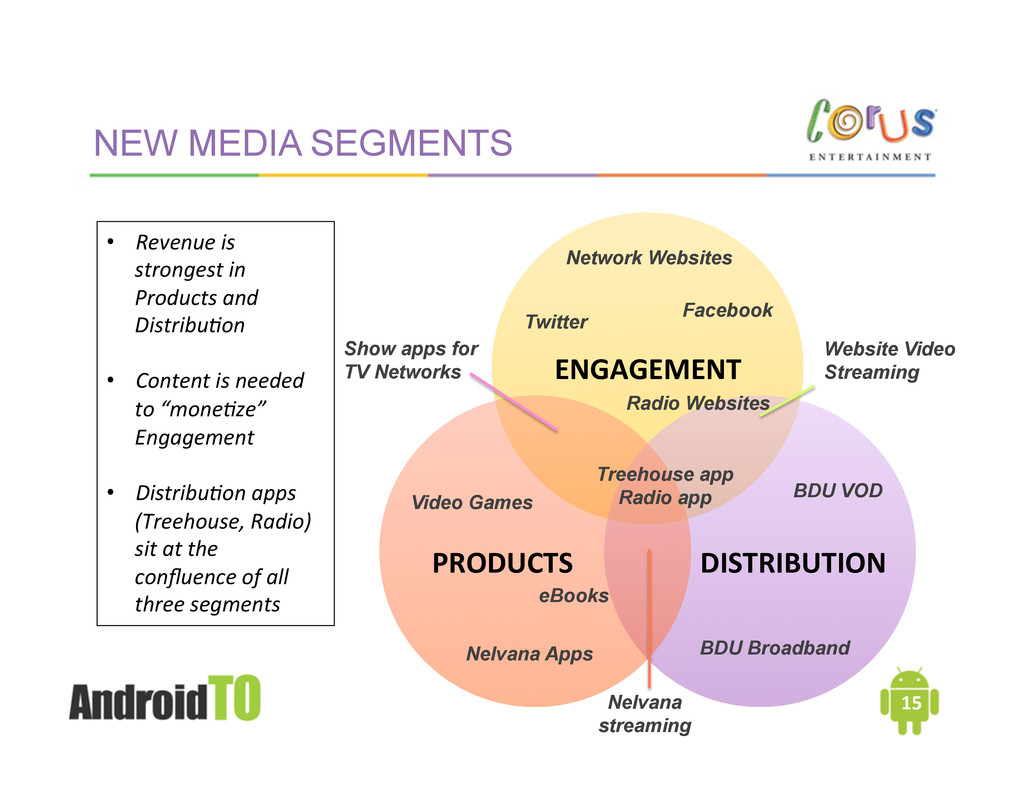
NEW MEDIA SEGMENTS ENGAGEMENT DISTRIBUTION PRODUCTS
Treehouse app Radio app BDU VOD Video Games BDU Broadband Website Video Streaming Network Websites Facebook Nelvana Apps eBooks Show apps for TV Networks Nelvana streaming Twitter Radio Websites • Revenue is strongest in Products and Distribu4on • Content is needed to “mone4ze” Engagement • Distribu4on apps (Treehouse, Radio) sit at the confluence of all three segments 15 -
CORUS & NEW MEDIA Content comes first for kids
• Kids want compelling content – video, games, digital toys – and don’t care about devices • For Corus, the mobile priority has been on video distribuHon and games Video: Delivering kids’ favorite shows • In Canada, our ability to distribute video is limited by the current broadcast ecosystem • Canada is catching up to US and UK models where broadcasters manage channel apps and users can authen=cate into their MSO • During 2014, mul=ple BDU authen=ca=on will likely be available, resul=ng in the growth of video apps in Canada. Ø US examples: Nickelodeon and Cartoon Network apps 17 -
CORUS & NEW MEDIA Games: Fun & Games
• Web games are used to drive audience engagement; typically delivered to broadcasters for websites like Nick, Cartoon Network, & Disney around the world • Websites feature flash (and Unity) gaming – ytv.com is a top site for kids in Canada (but not mobile enabled, yet) • Apps drive incremental revenue and have mone=za=on strategies since launching in 2011 AnalyHcs drives the content strategy • The content offering and available pladorms change based on how kids watch or play the games • It has required changing our team culture from manufacturing to servicing, from product publishing to product itera=on 18 -
GROWING A STRONG MOBILE PORTFOLIO Corus (via Nelvana) has successfully
launched 18 applicaHons (apps) for mobile and tablet • Modest revenue but growing steadily; 96% growth in revenue YoY • Over 1,500,000 app downloads to date We have been “Hot housing” and tesHng product and markeHng strategies in Canada before launching internaHonally with key partners • 2013 launch of Franklin, Max & Ruby, Sidekick, and Scaredy Squirrel apps in the US with on-‐air promo=on, integra=on with the Fingerprint pladorm, and other marke=ng partners • Trial freemium model for kids app with Max & Ruby and Sidekick Robust porFolio in development with 12 new apps slated for launch in Q42013 and 2014 19 -
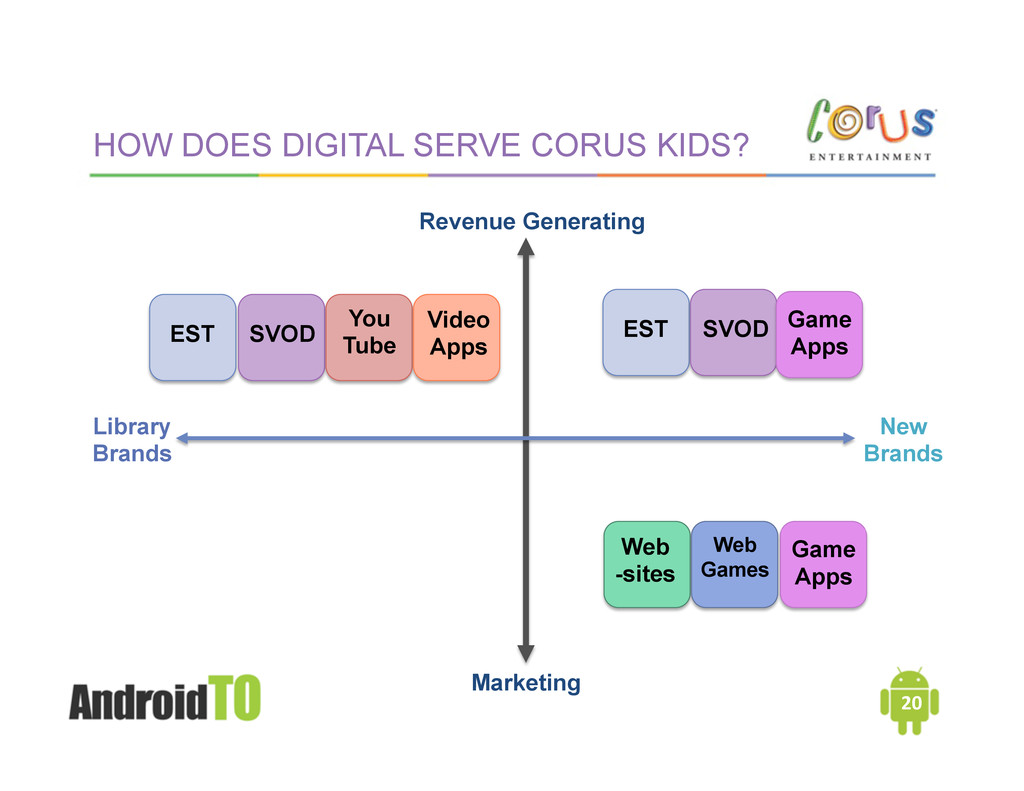
HOW DOES DIGITAL SERVE CORUS KIDS? Revenue Generating Marketing Library
Brands New Brands EST SVOD EST SVOD You Tube Video Apps Game Apps Web -sites Web Games Game Apps 20 -
WHO ARE THE KEY CUSTOMERS FOR CORUS KIDS DIGITAL PRODUCTS?
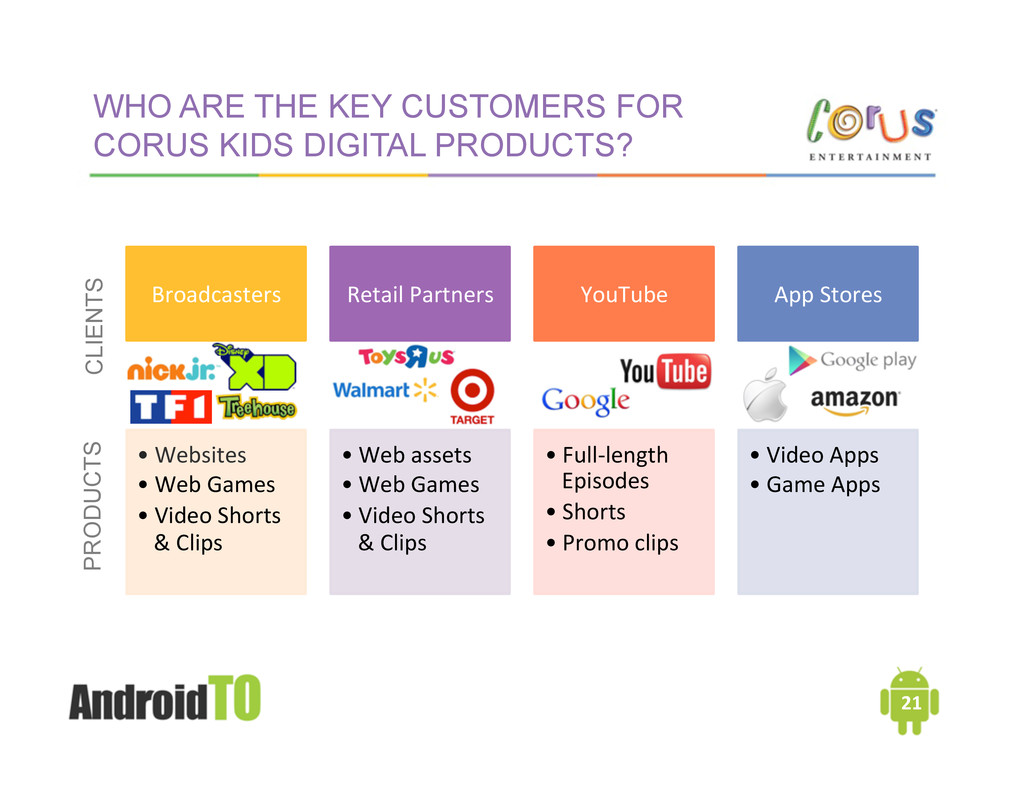
Broadcasters • Websites • Web Games • Video Shorts & Clips Retail Partners • Web assets • Web Games • Video Shorts & Clips YouTube • Full-‐length Episodes • Shorts • Promo clips App Stores • Video Apps • Game Apps PRODUCTS CLIENTS 21 -
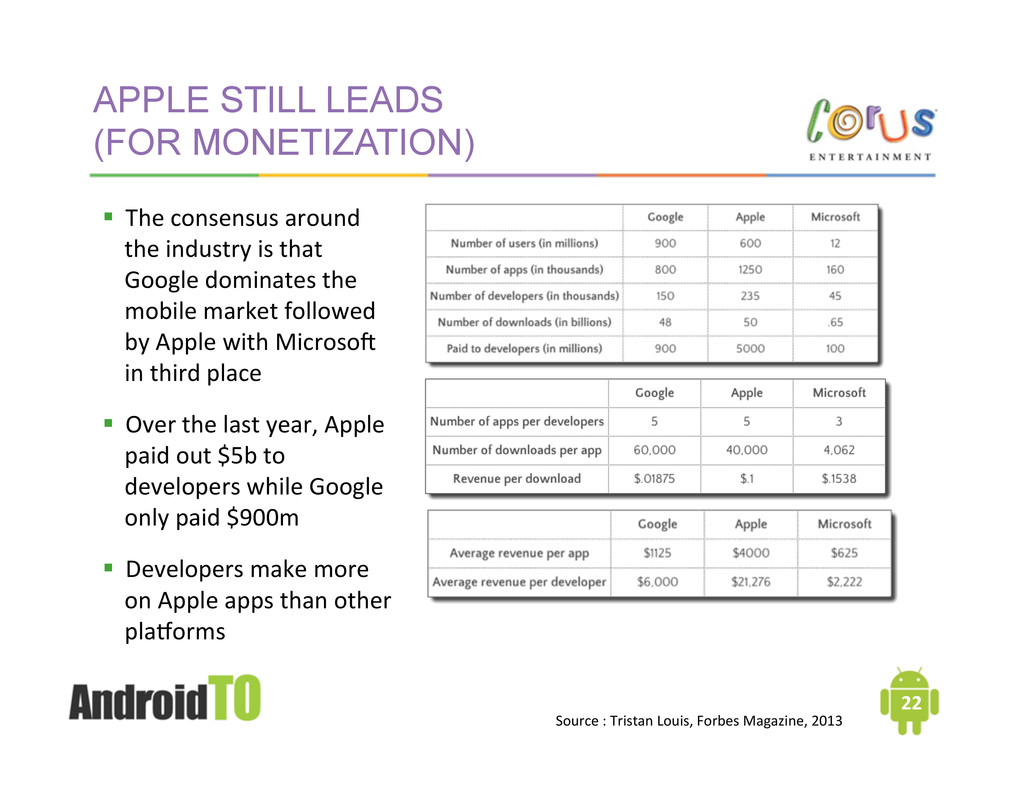
APPLE STILL LEADS (FOR MONETIZATION) 22 § The consensus
around the industry is that Google dominates the mobile market followed by Apple with Microsoq in third place § Over the last year, Apple paid out $5b to developers while Google only paid $900m § Developers make more on Apple apps than other pladorms Source : Tristan Louis, Forbes Magazine, 2013 -
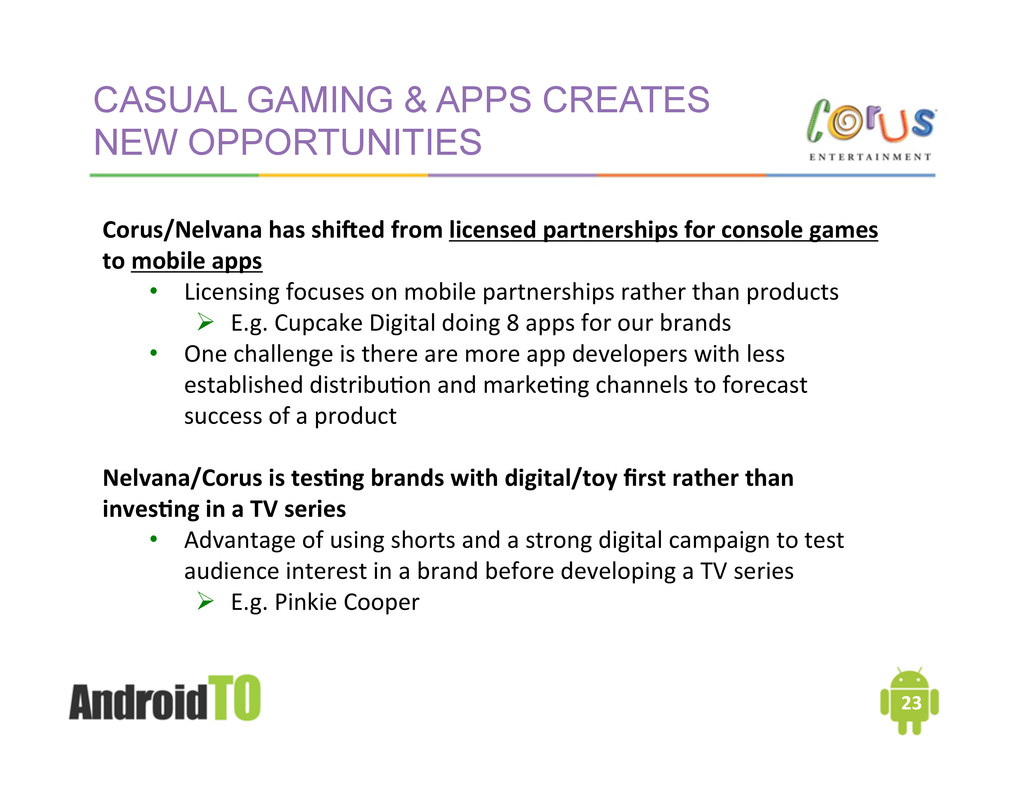
CASUAL GAMING & APPS CREATES NEW OPPORTUNITIES 23 Corus/Nelvana
has shined from licensed partnerships for console games to mobile apps • Licensing focuses on mobile partnerships rather than products Ø E.g. Cupcake Digital doing 8 apps for our brands • One challenge is there are more app developers with less established distribu=on and marke=ng channels to forecast success of a product Nelvana/Corus is tesHng brands with digital/toy first rather than invesHng in a TV series • Advantage of using shorts and a strong digital campaign to test audience interest in a brand before developing a TV series Ø E.g. Pinkie Cooper -
PRODUCTION PROCESS IS ADAPTING 24 ProducHon Framework
§ Mul=pladorm-‐first approach • Mobile partners now deliver on both iOS and Android devices (Amazon Kindle Fire is priority) • Internal app produc=on has recently changed from na=ve iOS to Unity • Web games are TBD; likely Unity for 3D; Flash or HTML5 for 2D -
HTML5, IOS, ANDROID 25 HTML5 vs NaHve apps
• Likely need both for most experiences • HTML5: Familiar programming, Na=ve to the browser, can be wri>en once and used on any device and OS, with much lower costs, no approval and no downloads. • Mobile Apps: More professional, more reliable, no need for an Internet connec=on, faster and be>er device integra=on. DistribuHon • Go direct to Google Play and Amazon Kindle • Link to a device (such as Samsung) • Link to a distributor (such as Spoiled Milk) -
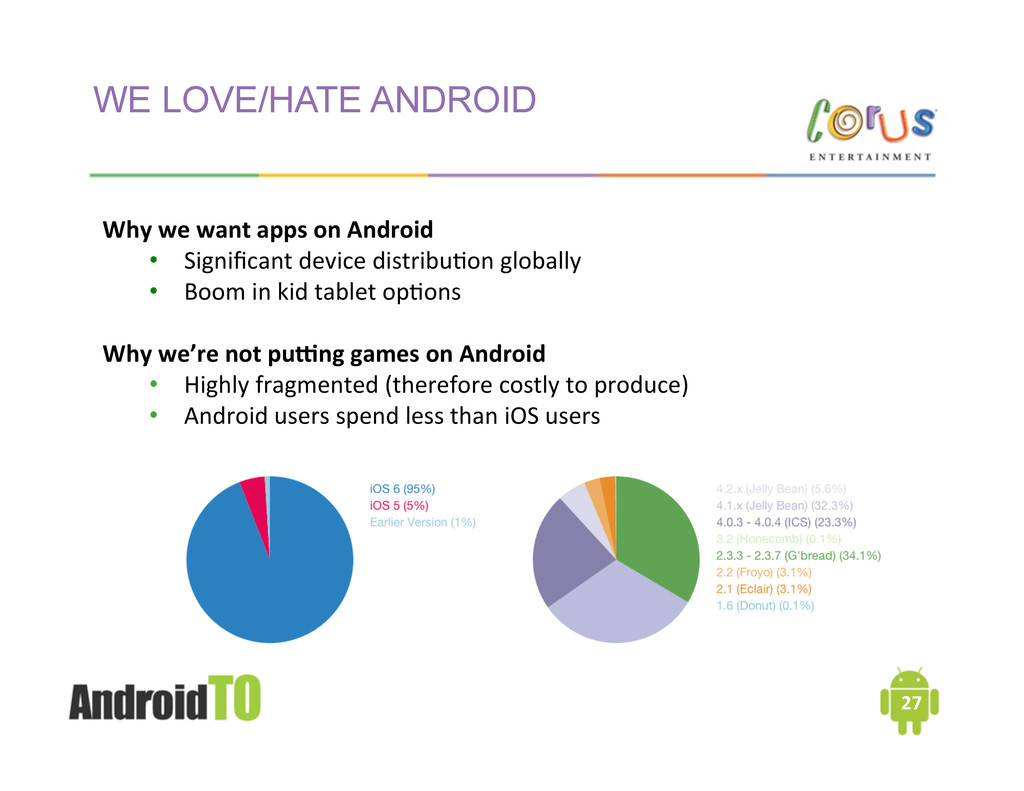
WE LOVE/HATE ANDROID 27 Why we want apps on
Android • Significant device distribu=on globally • Boom in kid tablet op=ons Why we’re not puong games on Android • Highly fragmented (therefore costly to produce) • Android users spend less than iOS users -
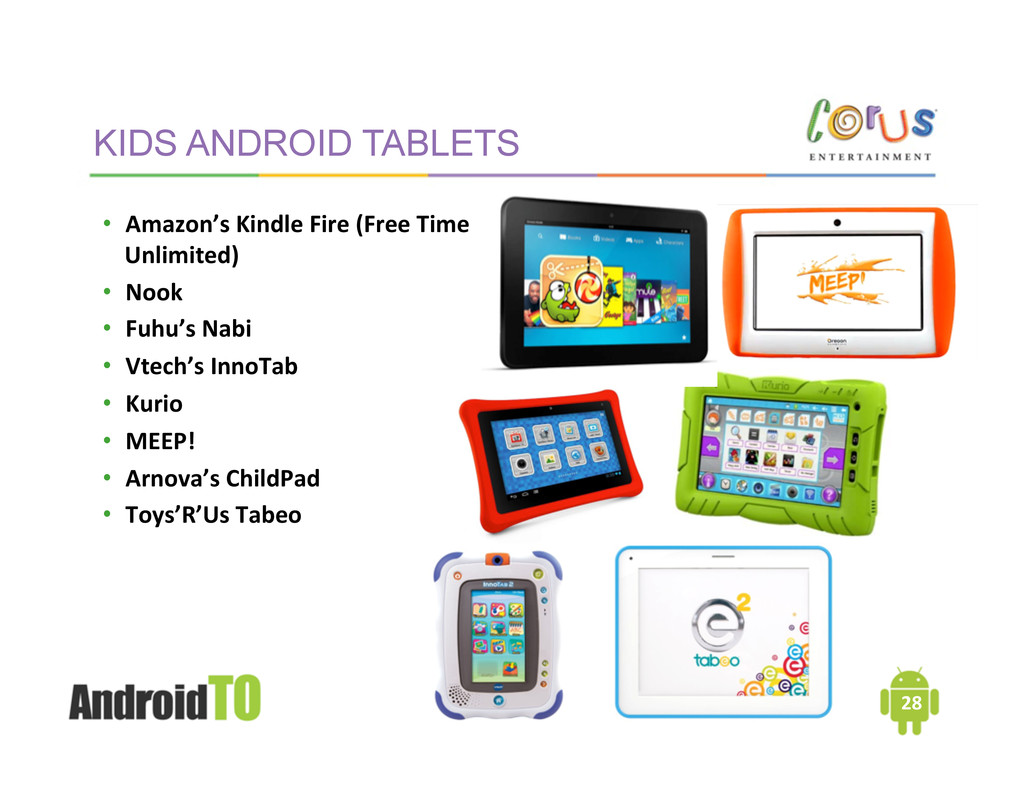
KIDS ANDROID TABLETS • Amazon’s Kindle Fire (Free Time
Unlimited) • Nook • Fuhu’s Nabi • Vtech’s InnoTab • Kurio • MEEP! • Arnova’s ChildPad • Toys’R’Us Tabeo 28 -
Many parents buy iPads for themselves then let children use
them, but a growing number of parents are buying a separate tablet for their kids – and onen that's a more-‐affordable Android device. 2013 was a good year for Android Kids app releases which made these tablets a viable opHon for parents that are looking to entertain their kids But while there are more players, content owners are realizing that there are fewer plaForms that deliver incremental revenue. • Apple, Amazon, Google Play are the top 3 stores, with Apple con=nuing to out-‐ perform all others by significant amount ANDROID & KIDS 29 -
ADDITIONAL THOUGHTS Mobile “lightweight” entertainment market is showing signs of
maturing • Top grossing charts are se>ling in and there isn’t much change Ø Power of being the chart itself; re-‐elec=ng incumbents Ø only 2% of the top 250 publishers in Apple’s store are “newcomers” • Difficult =me for product to be discovered and move up the chart • Top publishers spend a lot of money to stay in the top charts • Difference makers aren’t the product but the marke=ng spend Ø Typical 50% drop off below the fold when user is scrolling in an app store Ø With mobile this is more significant because the screens are smaller The good news is there is a level of creaHvity in the indie sphere that hasn’t been seen since the 80s in gaming and mobile and has much lower barriers to entry. Even though it’s harder than it was 3 years ago, it is sHll possible for new studios to make a break-‐out hit 30 -
THE MOBILE AD ECONOMY: NOT SO GREAT (YET) AdverHsing Agencies
are looking for scale and impact RTB and automaHon are driving down CPM on display ads; in turn this drives more mobile spending and opportuniHes There is an assumpHon from agencies that all major TV publishers have (or should have) an App experience that contains bulk video – although consumpHon of video online and mobile varies by content type The main barrier to growth in Mobile (apps) is cost and a lack of pre-‐ established offerings; • Agencies don’t want to spend on produc=on costs • Typically nonworking money can only be 10-‐20% of the budget ! Challenging for Android 32 -
CONCLUSION 34 Everything is Mobile Follow the
audience – don’t expect them to come to you Android will command the media space when … • The revenue opportunity is real, both in subscrip=on & adver=sing • Developers are willing to share the risk with content owners and broadcasters • Content discovery is seamless, logical and orderly • OS fragmenta=on slows, to allow a single development stream, and the mul=pladorm issues between Android and iOS are solved The world is changing and will conHnue to do so