Share
Embed

Transcript
40 slides
-
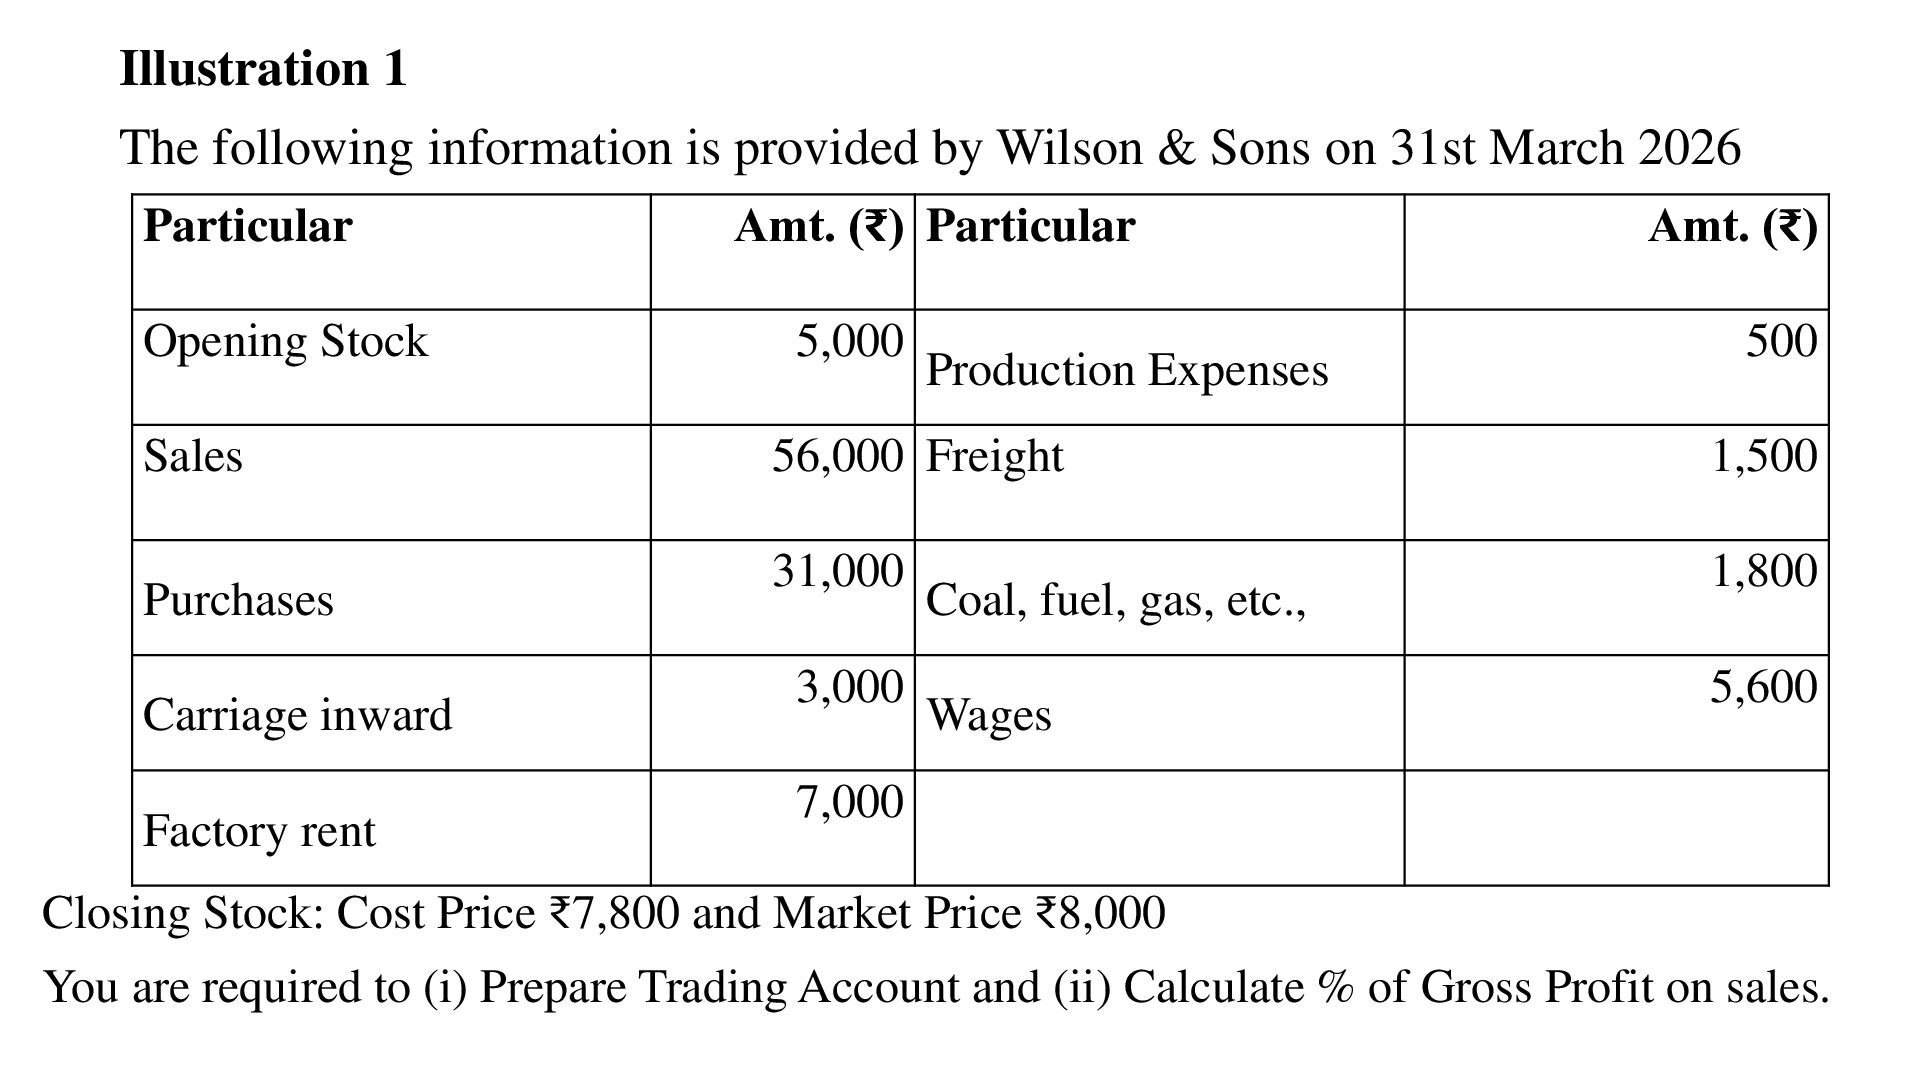
Illustration 1 The following information is provided by Wilson &
Sons on 31st March 2026 Particular Amt. (₹) Particular Amt. (₹) Opening Stock 5,000 Sales 56,000 Freight 1,500 31,000 1,800 Purchases Carriage inward Factory rent 3,000 Production Expenses Coal, fuel, gas, etc., Wages 500 5,600 7,000 Closing Stock: Cost Price ₹7,800 and Market Price ₹8,000 You are required to (i) Prepare Trading Account and (ii) Calculate % of Gross Profit on sales. -
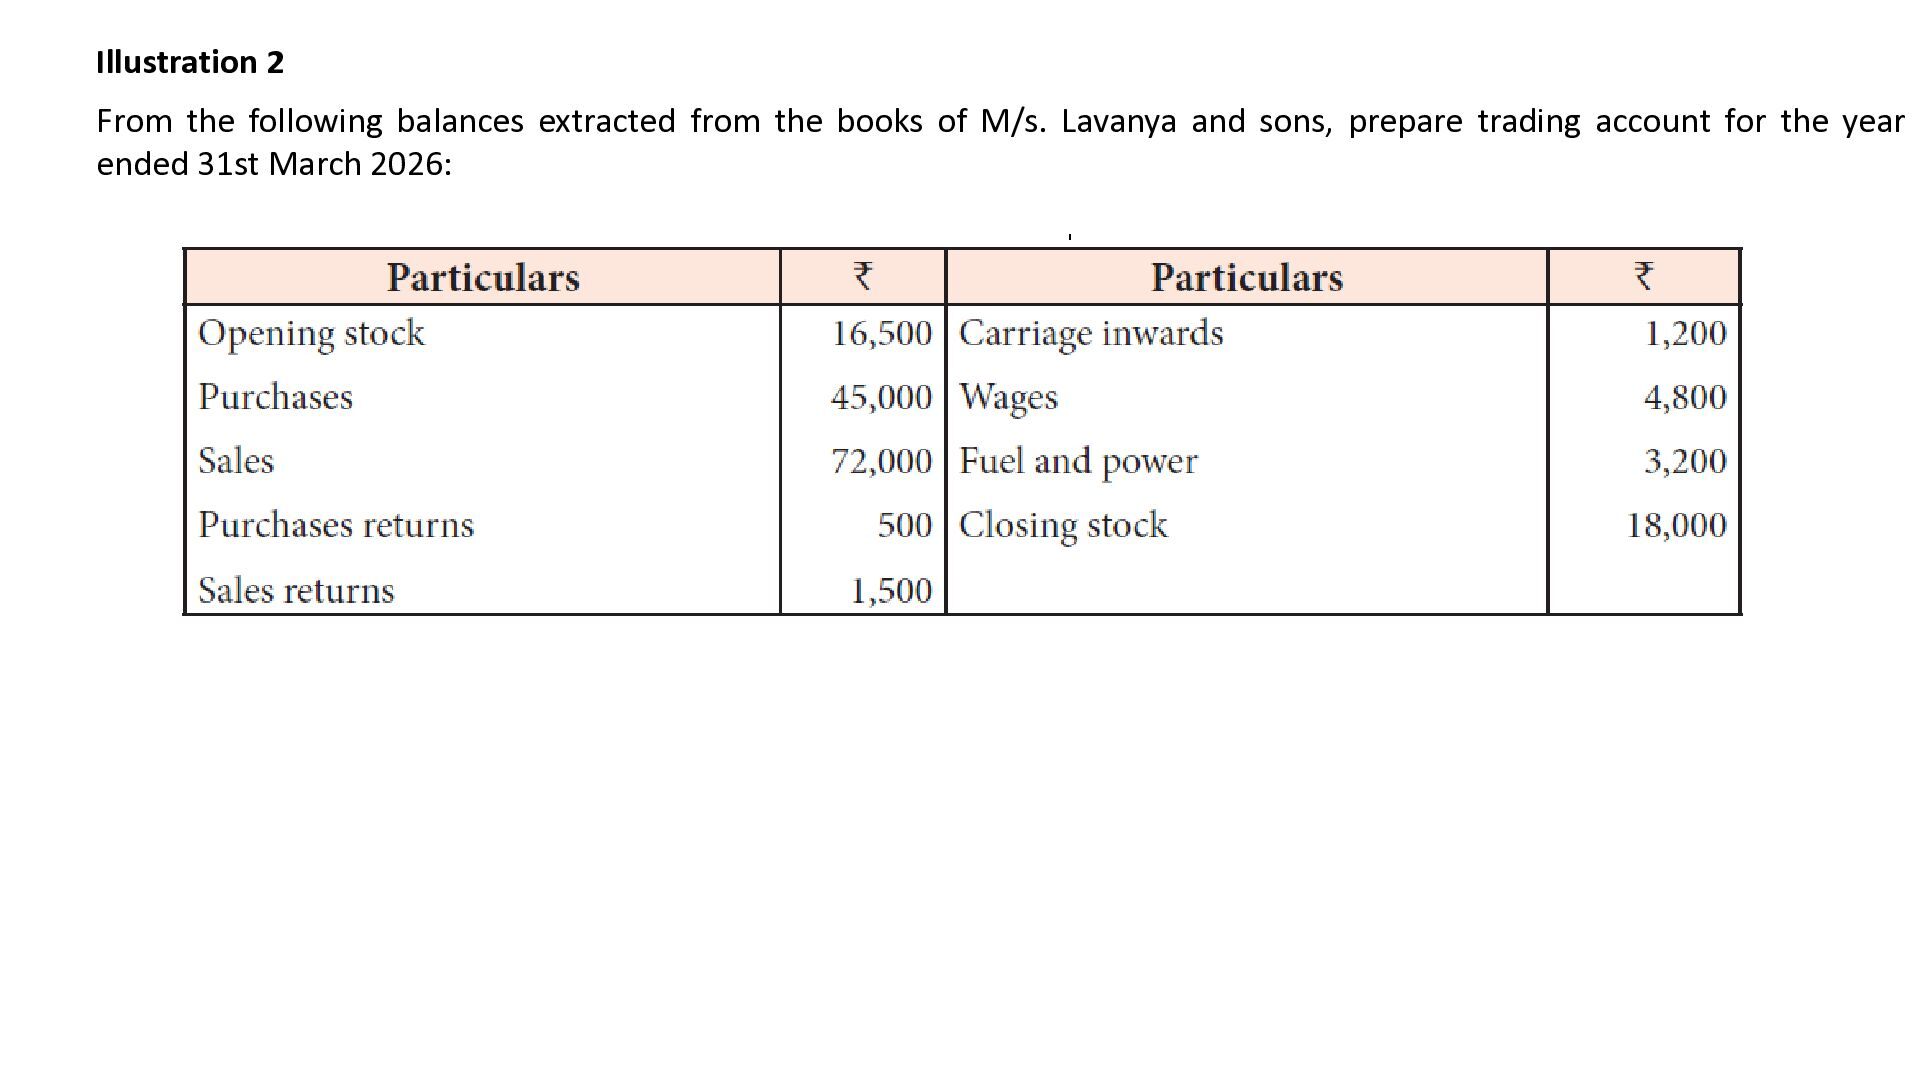
Illustration 2 From the following balances extracted from the books
of M/s. Lavanya and sons, prepare trading account for the year ended 31st March 2026: -
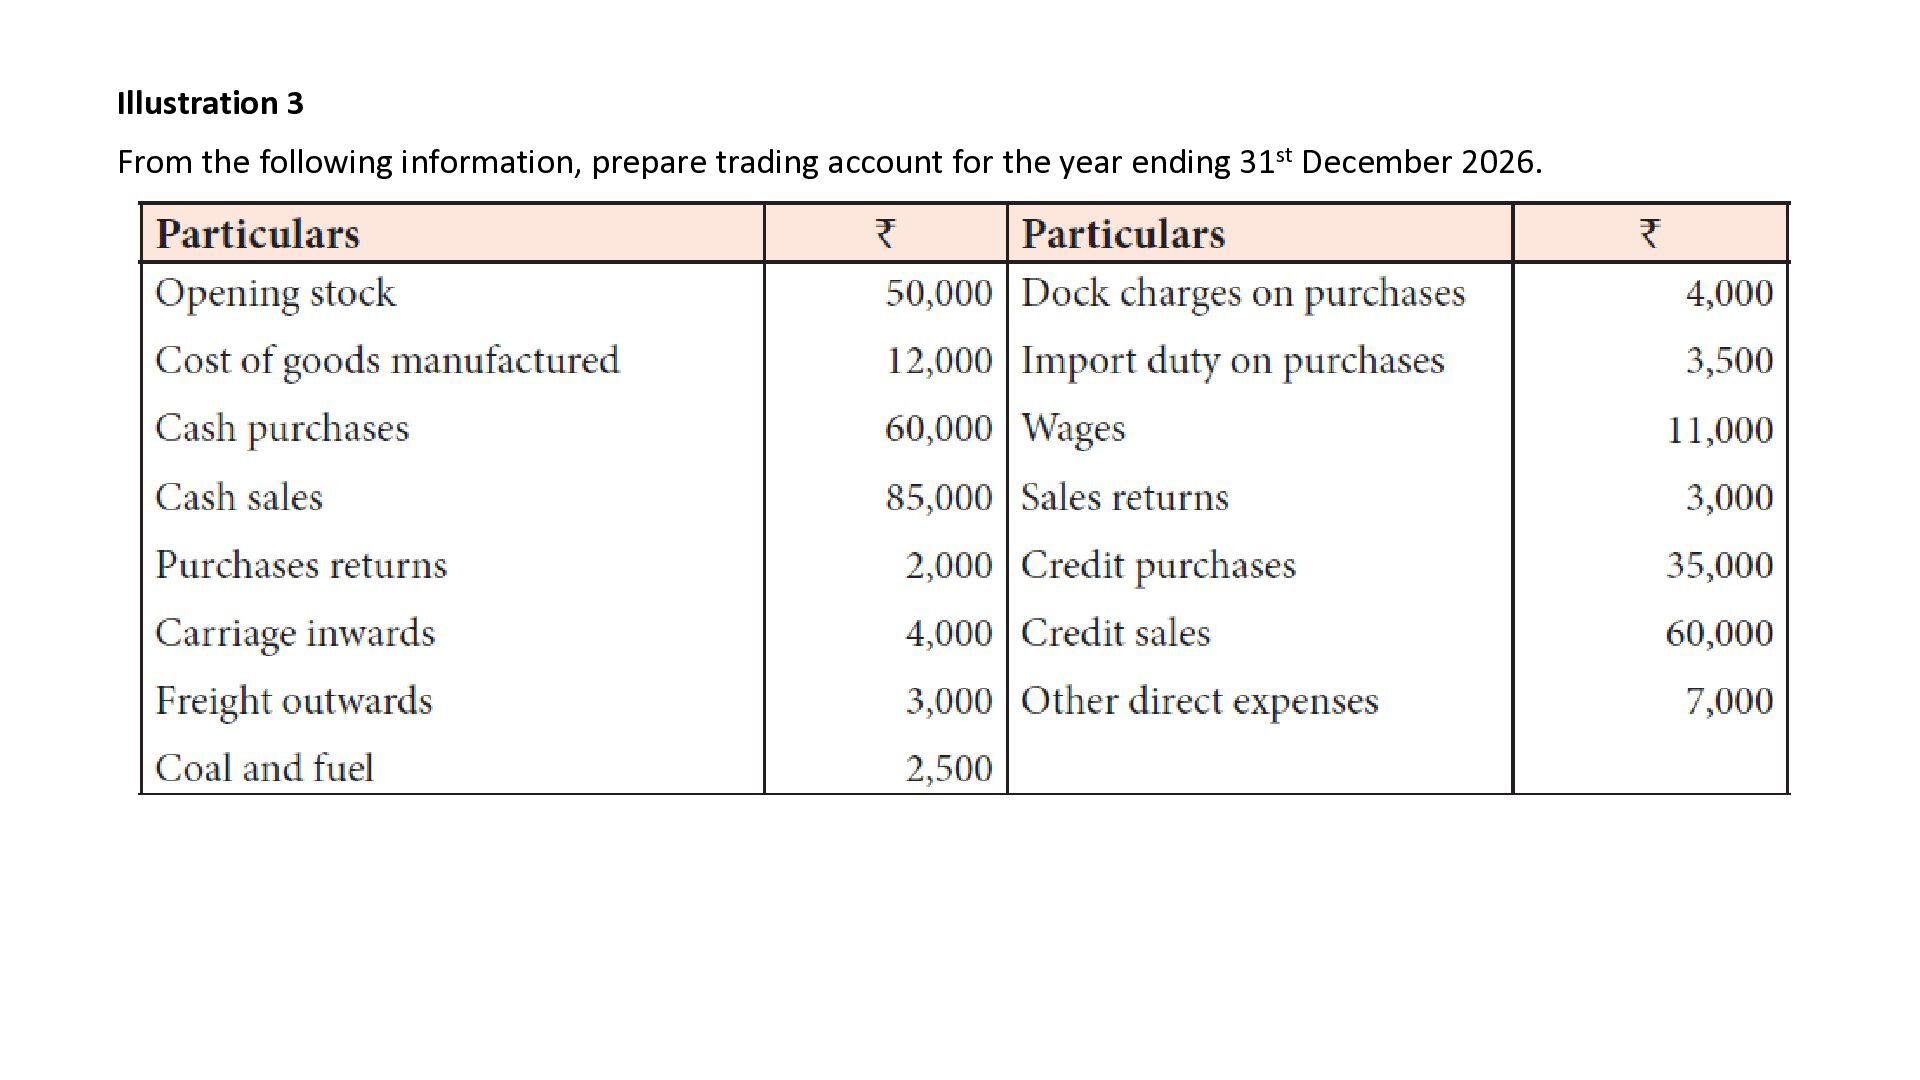
Illustration 3 From the following information, prepare trading account for
the year ending 31st December 2026. -
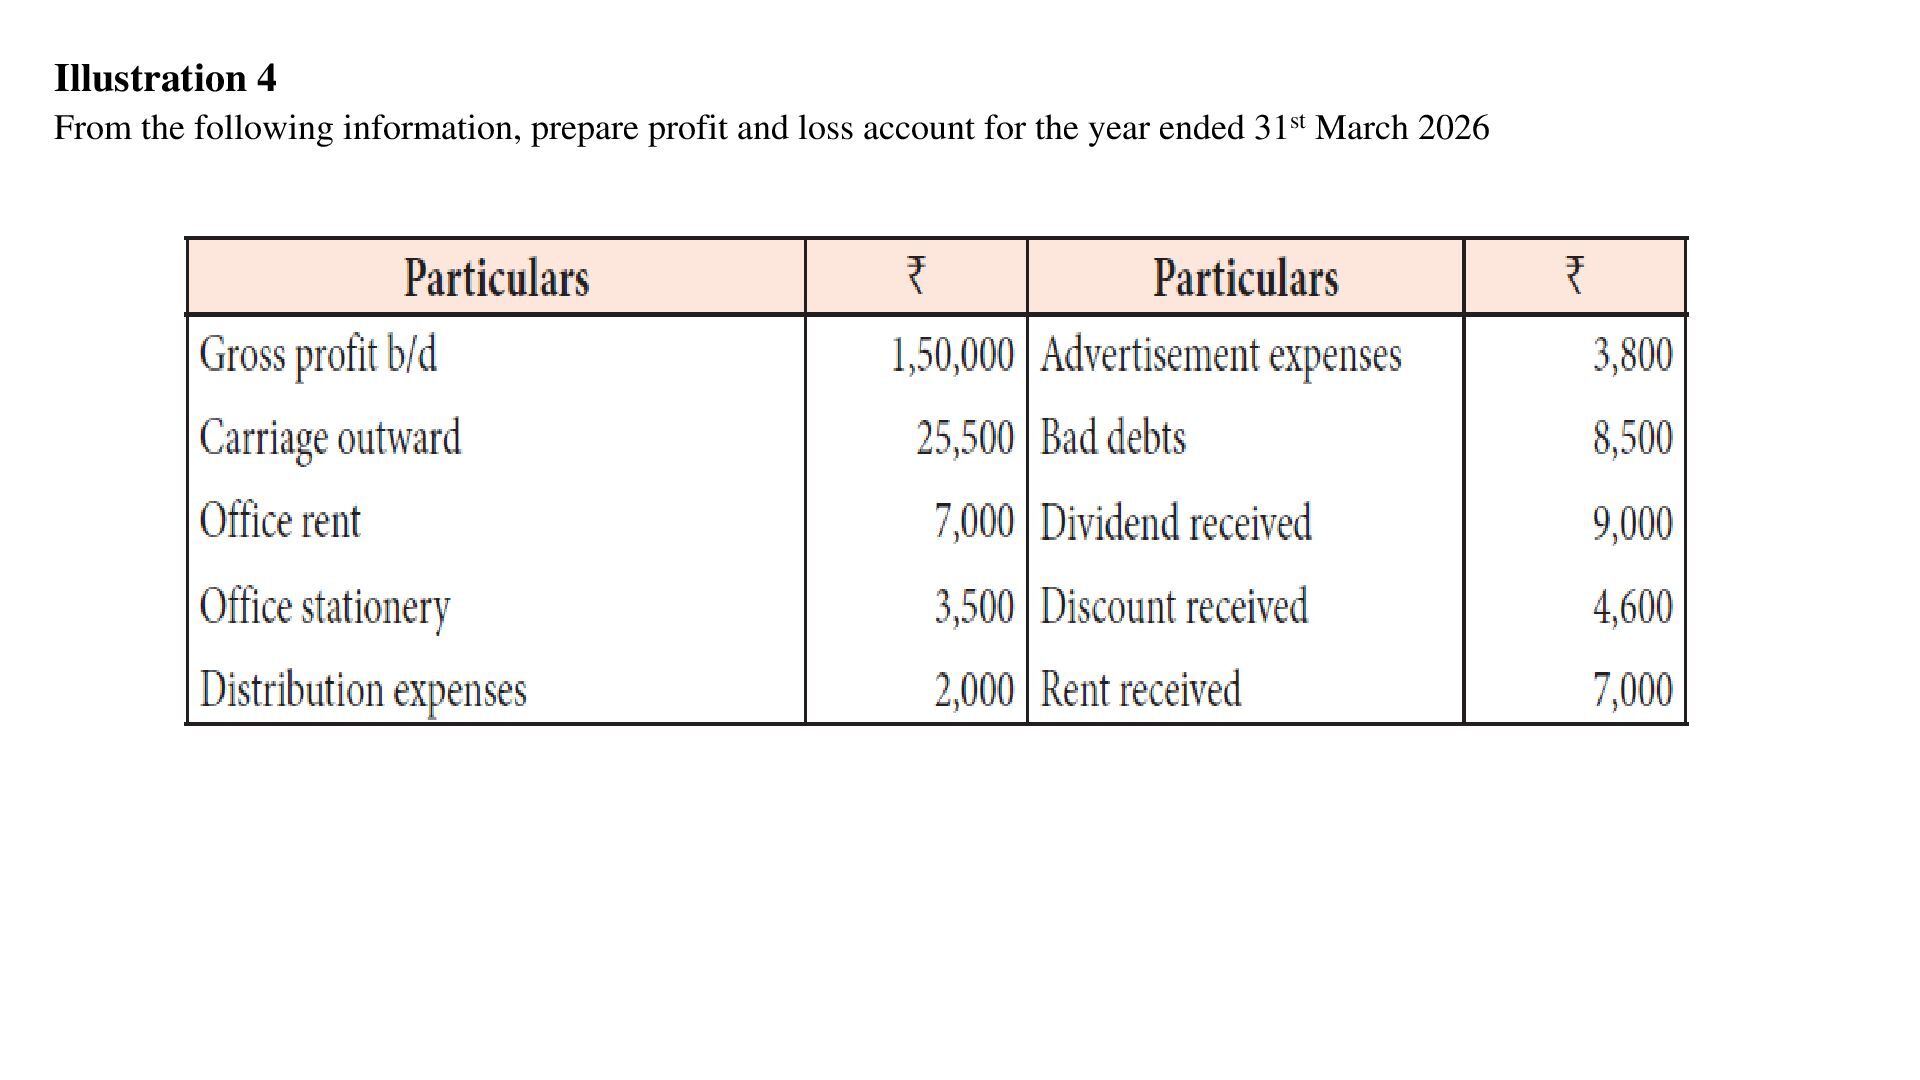
Illustration 4 From the following information, prepare profit and loss
account for the year ended 31st March 2026 -
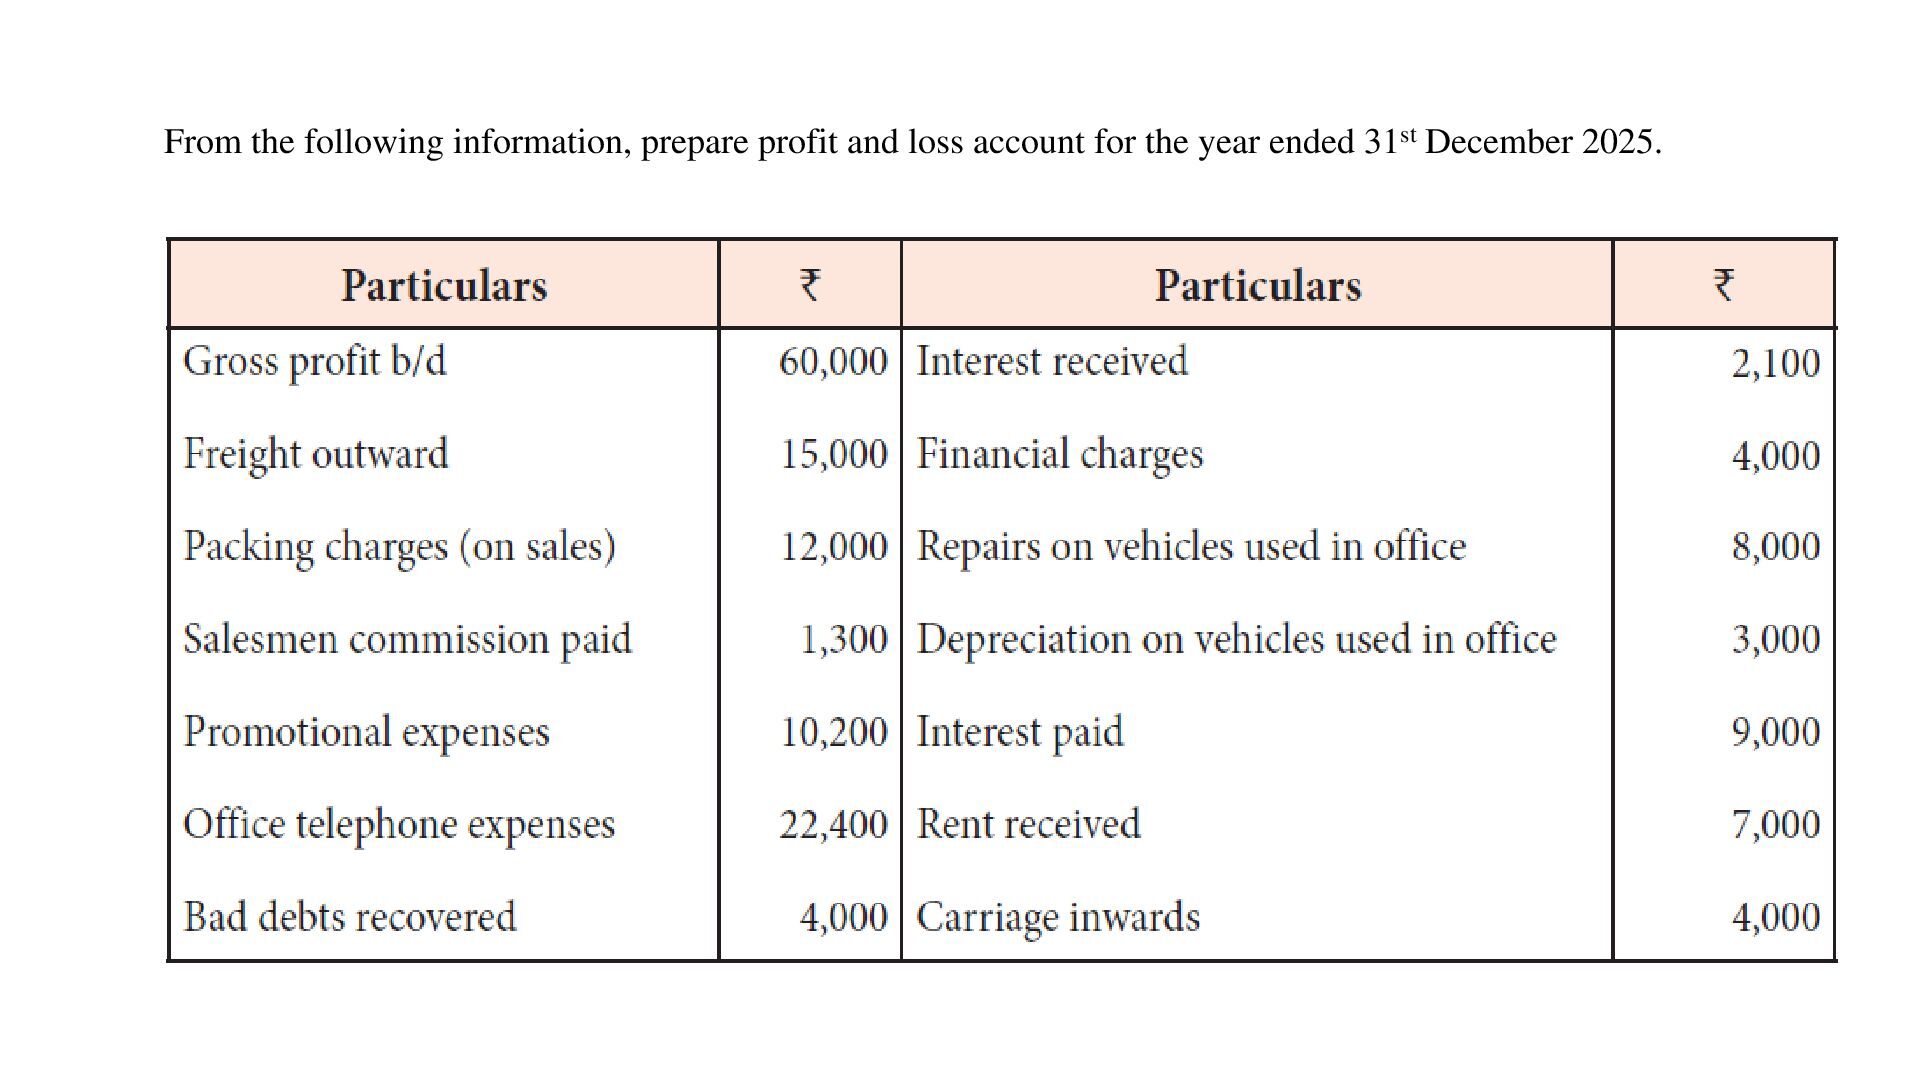
From the following information, prepare profit and loss account for
the year ended 31st December 2025. -
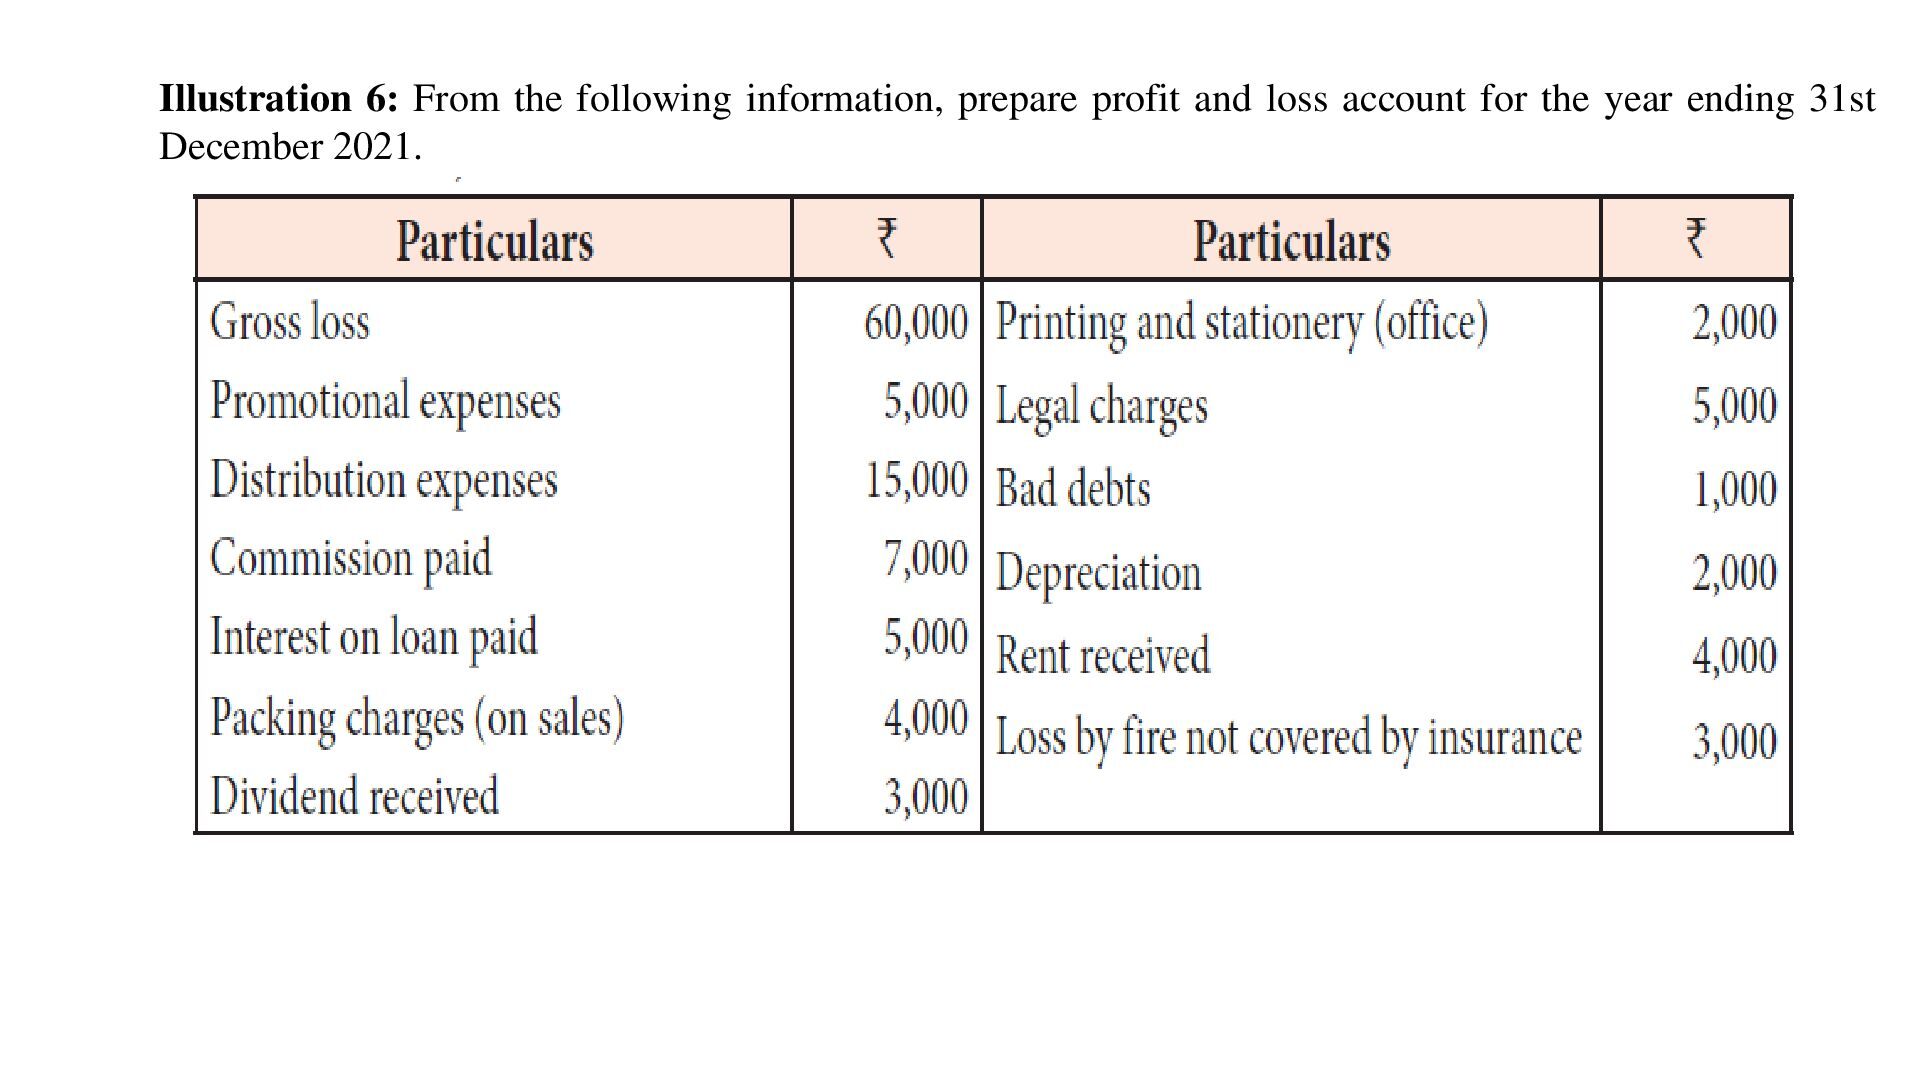
Illustration 6: From the following information, prepare profit and loss
account for the year ending 31st December 2021. -
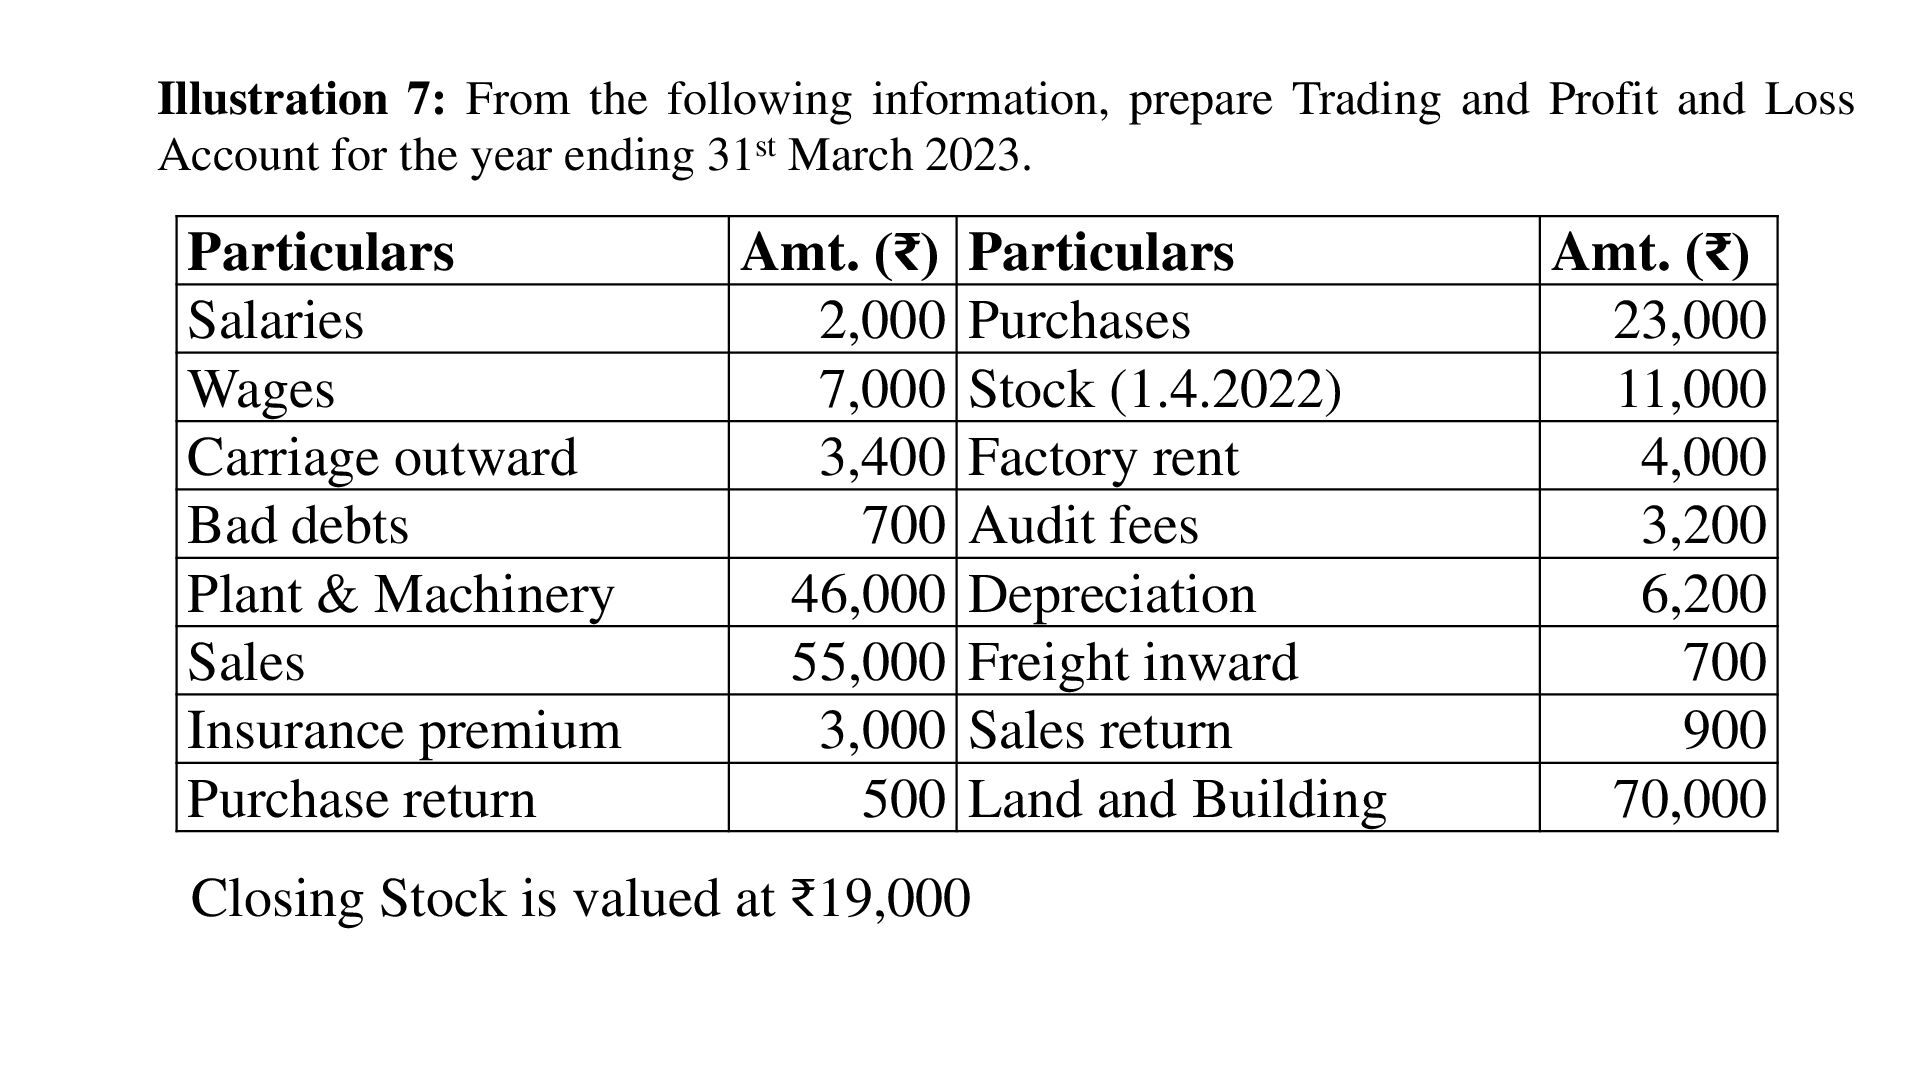
Illustration 7: From the following information, prepare Trading and Profit
and Loss Account for the year ending 31st March 2023. Particulars Salaries Wages Carriage outward Bad debts Plant & Machinery Sales Insurance premium Purchase return Amt. (₹) Particulars 2,000 Purchases 7,000 Stock (1.4.2022) 3,400 Factory rent 700 Audit fees 46,000 Depreciation 55,000 Freight inward 3,000 Sales return 500 Land and Building Closing Stock is valued at ₹19,000 Amt. (₹) 23,000 11,000 4,000 3,200 6,200 700 900 70,000 -
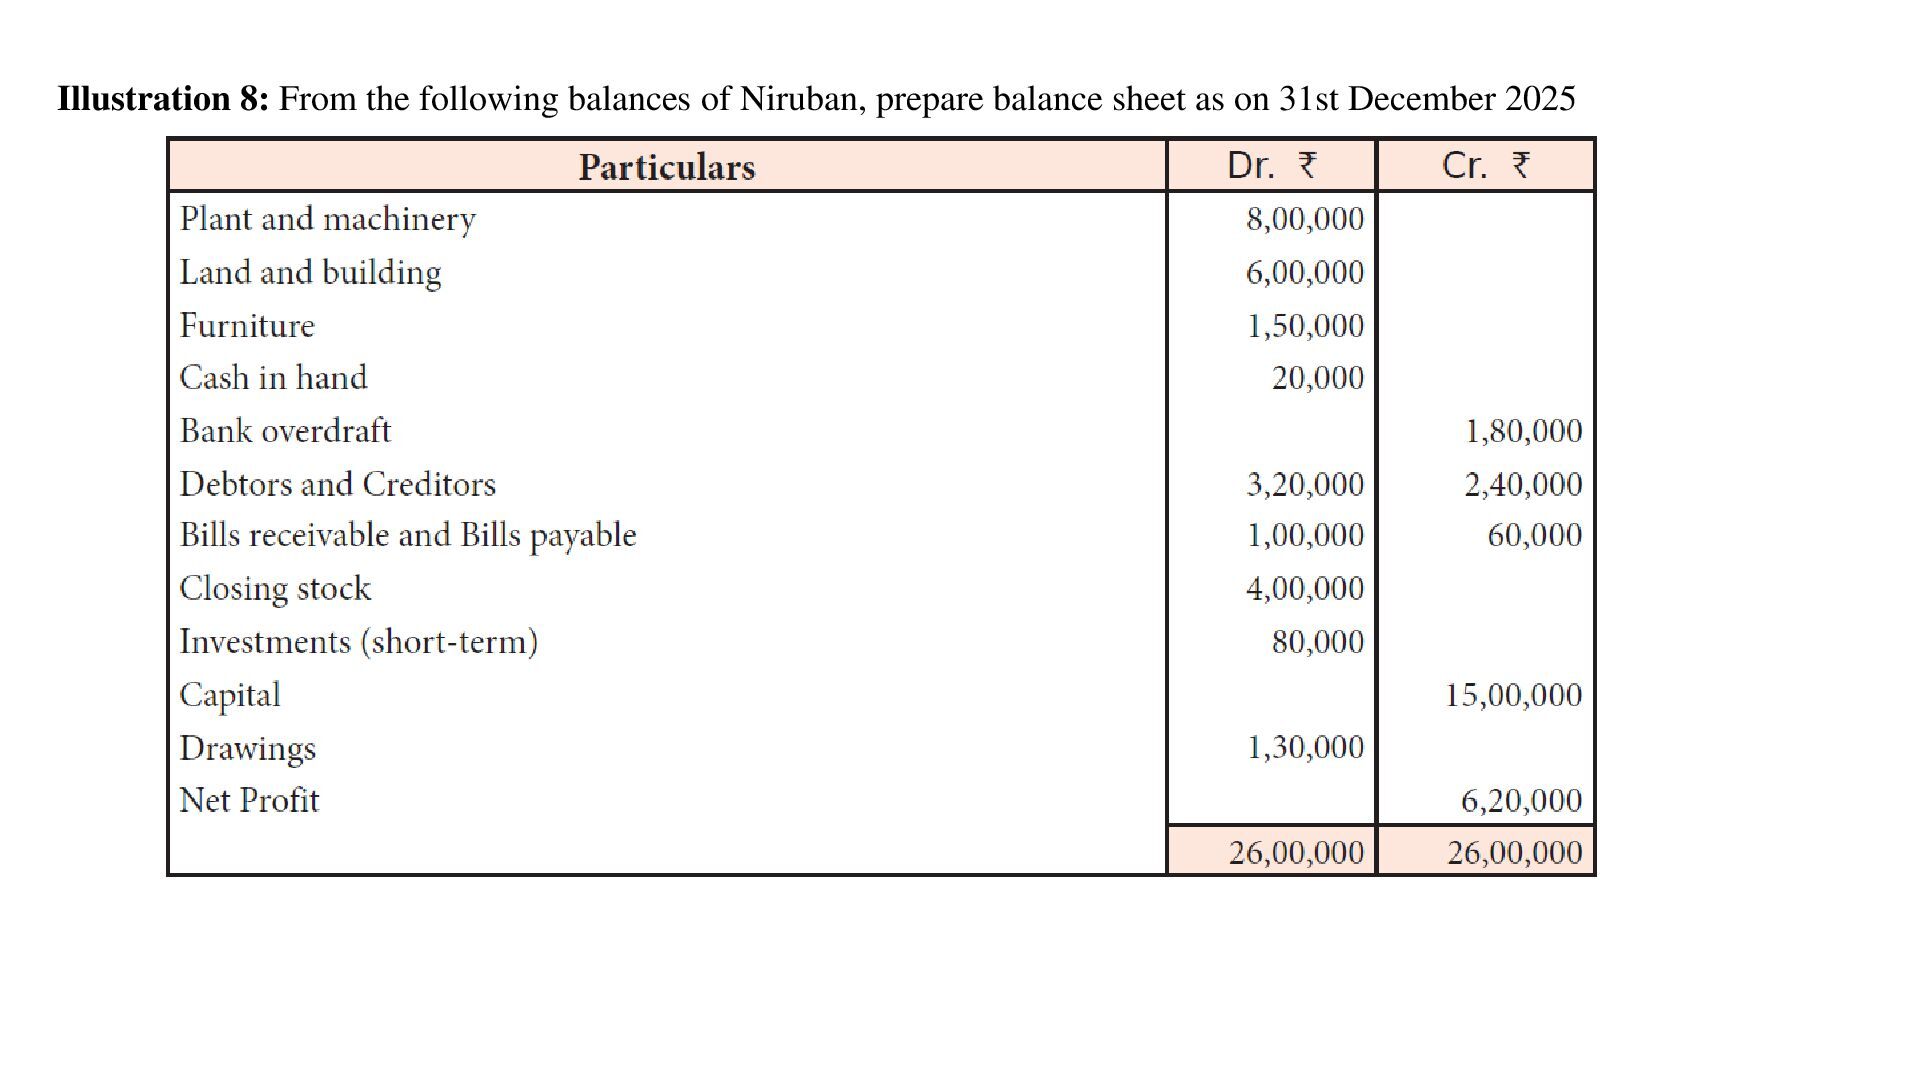
Illustration 8: From the following balances of Niruban, prepare balance
sheet as on 31st December 2025 -
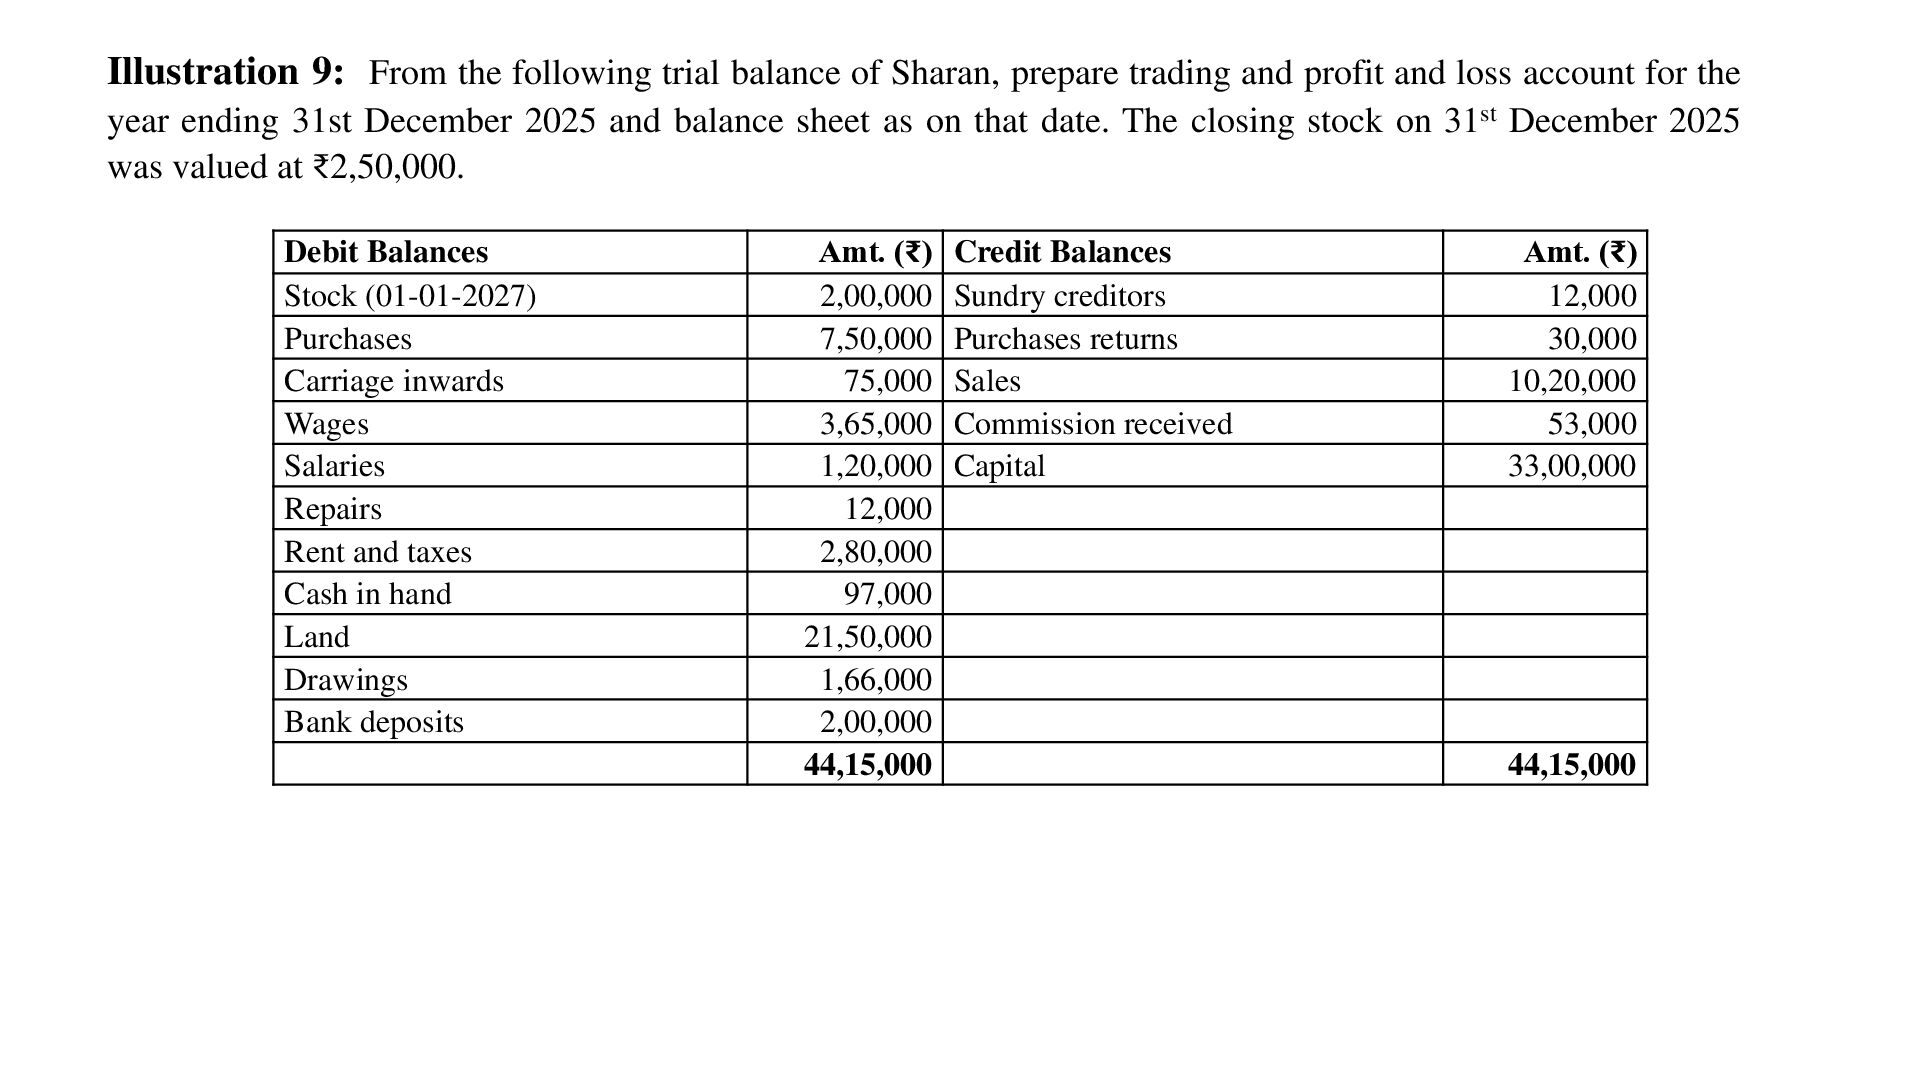
Illustration 9: From the following trial balance of Sharan, prepare
trading and profit and loss account for the year ending 31st December 2025 and balance sheet as on that date. The closing stock on 31st December 2025 was valued at ₹2,50,000. Debit Balances Stock (01-01-2027) Purchases Carriage inwards Wages Salaries Repairs Rent and taxes Cash in hand Land Drawings Bank deposits Amt. (₹) Credit Balances 2,00,000 Sundry creditors 7,50,000 Purchases returns 75,000 Sales 3,65,000 Commission received 1,20,000 Capital 12,000 2,80,000 97,000 21,50,000 1,66,000 2,00,000 44,15,000 Amt. (₹) 12,000 30,000 10,20,000 53,000 33,00,000 44,15,000 -
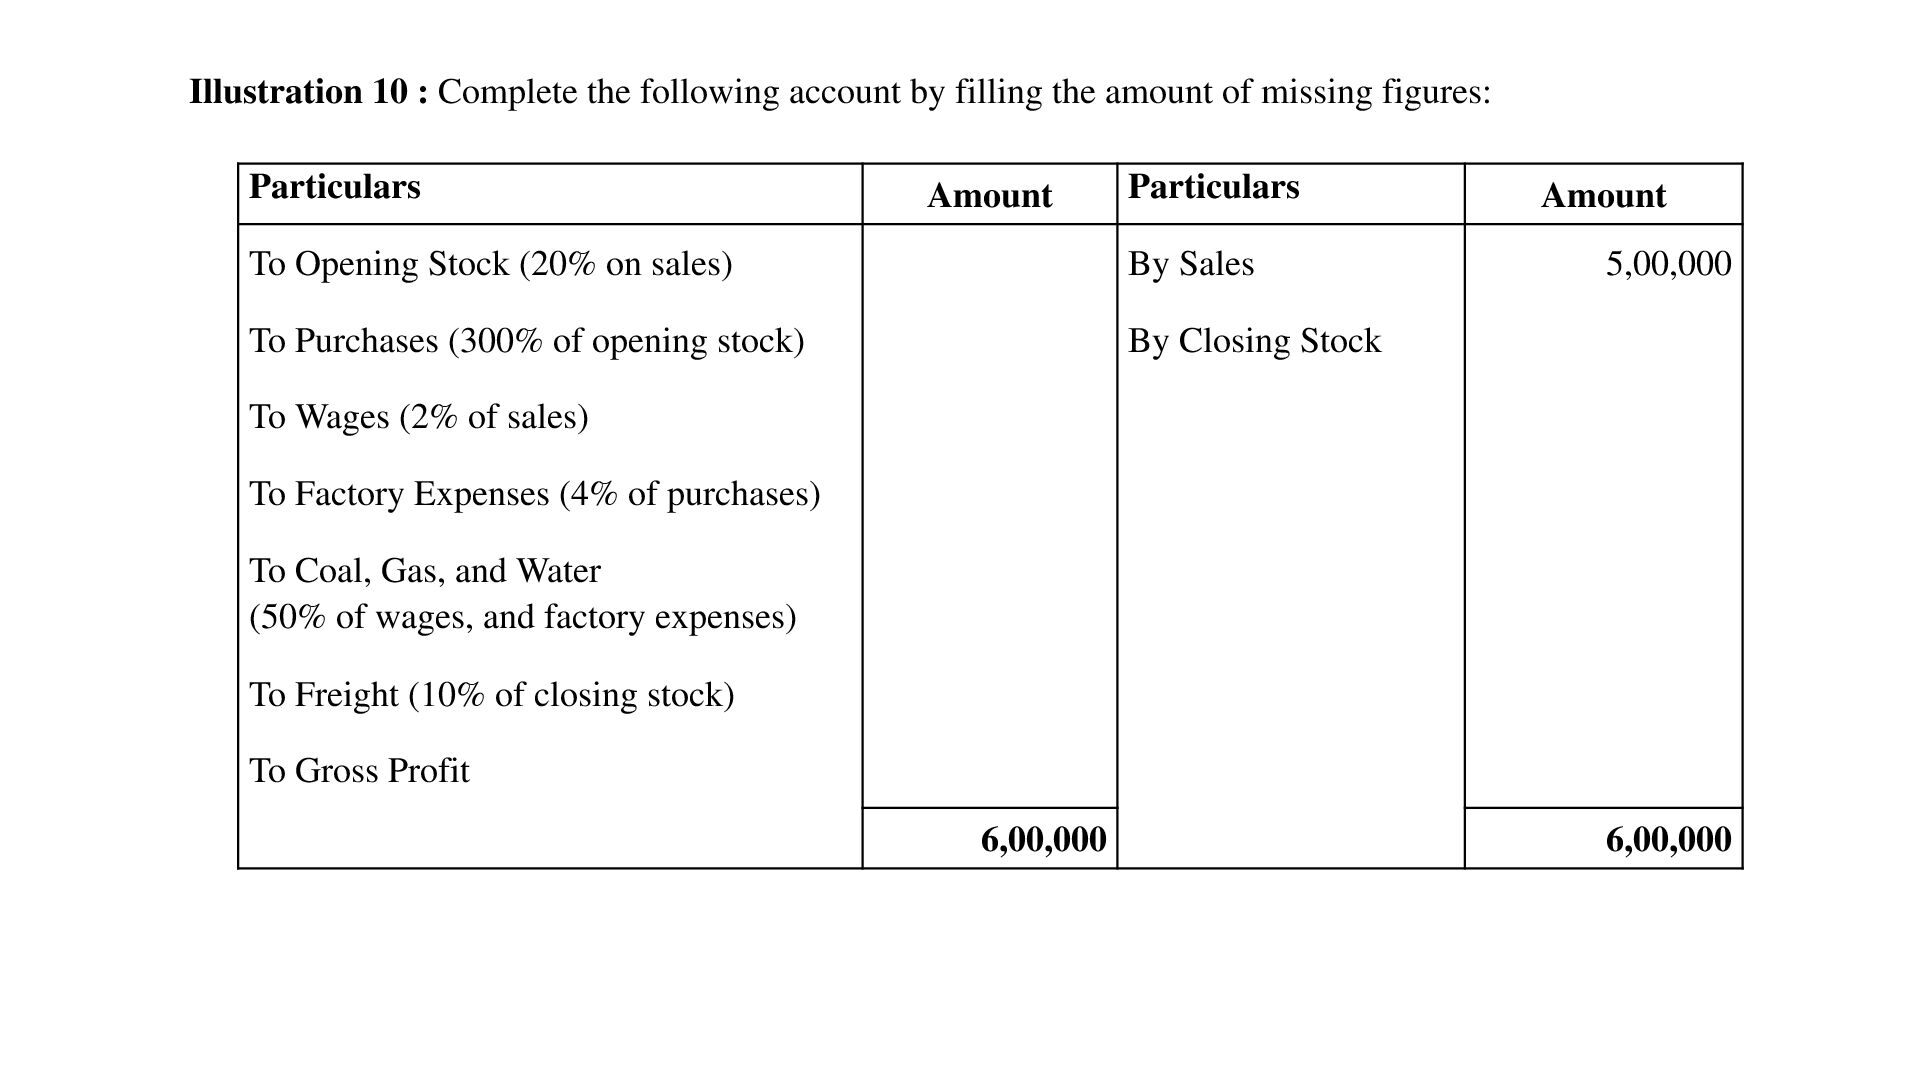
Illustration 10 : Complete the following account by filling the
amount of missing figures: Particulars Amount Particulars To Opening Stock (20% on sales) By Sales To Purchases (300% of opening stock) By Closing Stock Amount 5,00,000 To Wages (2% of sales) To Factory Expenses (4% of purchases) To Coal, Gas, and Water (50% of wages, and factory expenses) To Freight (10% of closing stock) To Gross Profit 6,00,000 6,00,000 -
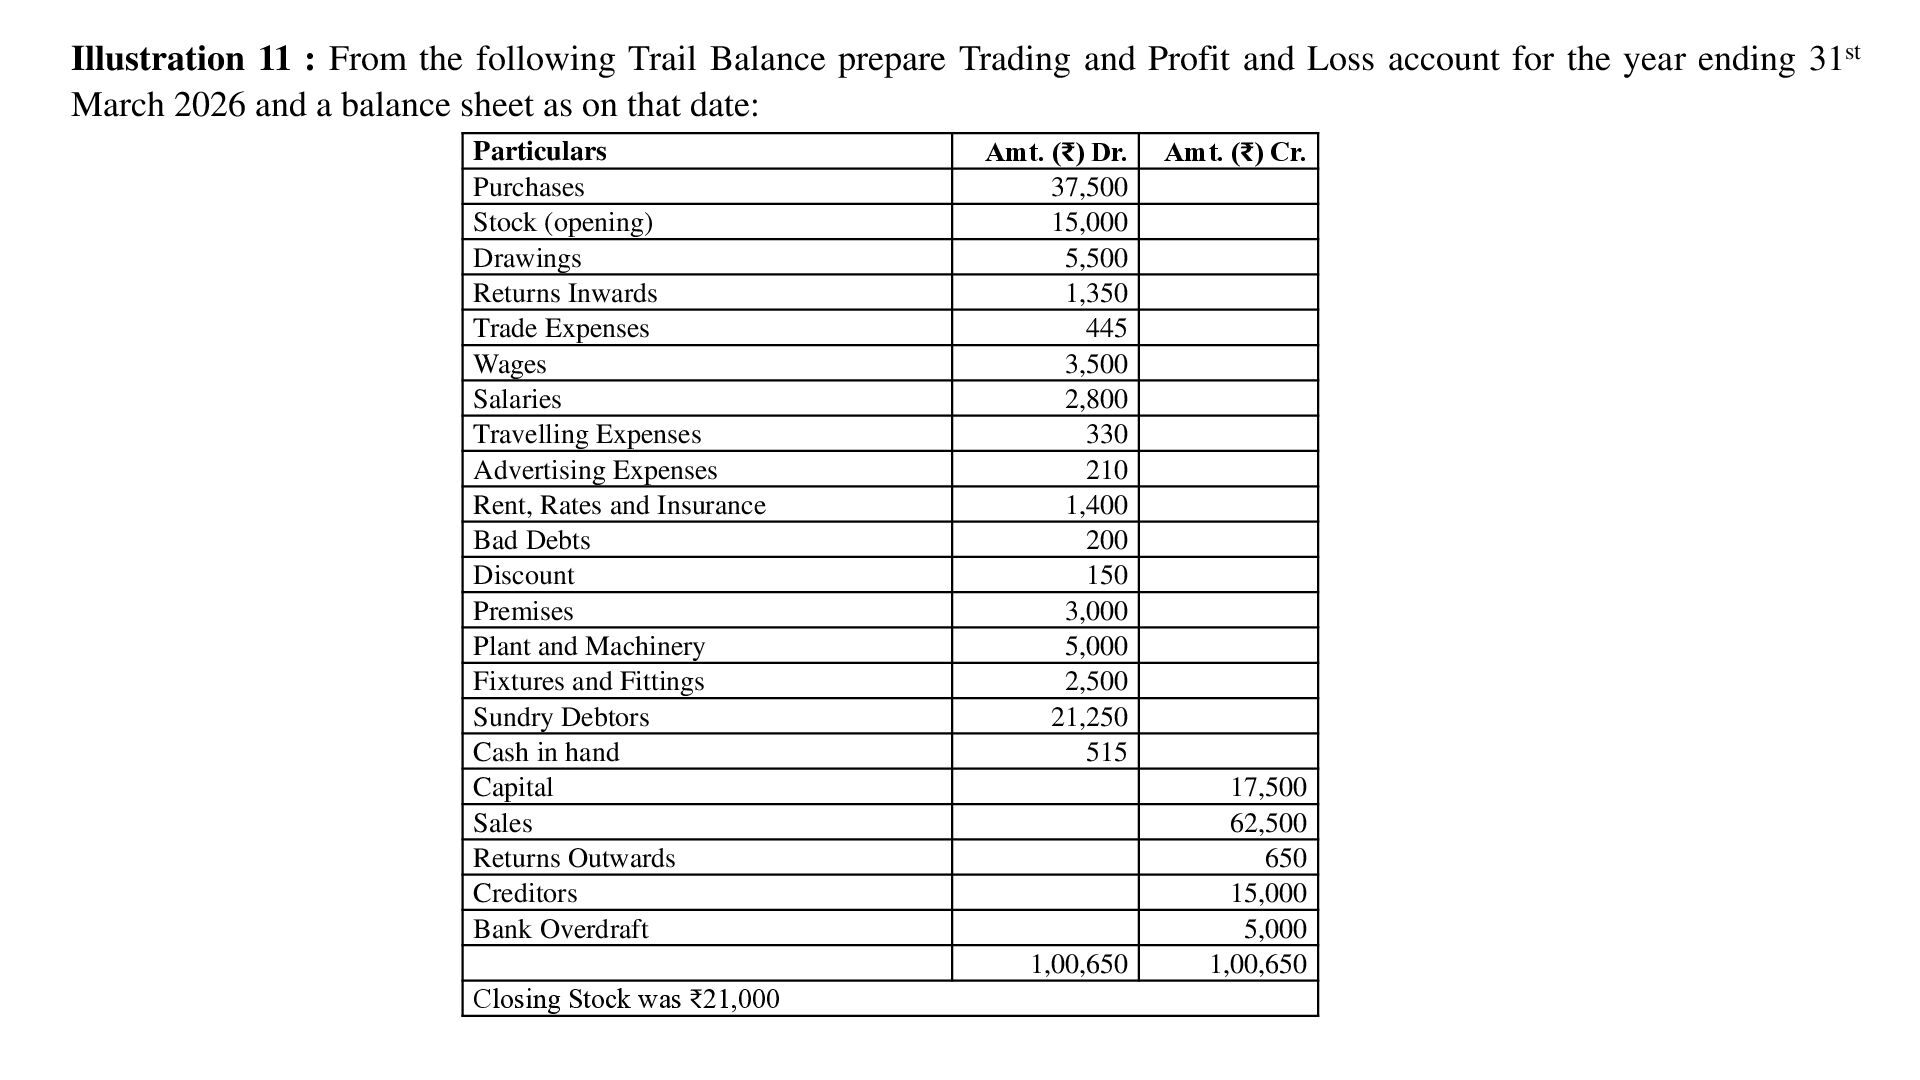
Illustration 11 : From the following Trail Balance prepare Trading
and Profit and Loss account for the year ending 31st March 2026 and a balance sheet as on that date: Particulars Purchases Stock (opening) Drawings Returns Inwards Trade Expenses Wages Salaries Travelling Expenses Advertising Expenses Rent, Rates and Insurance Bad Debts Discount Premises Plant and Machinery Fixtures and Fittings Sundry Debtors Cash in hand Capital Sales Returns Outwards Creditors Bank Overdraft Amt. (₹) Dr. 37,500 15,000 5,500 1,350 445 3,500 2,800 330 210 1,400 200 150 3,000 5,000 2,500 21,250 515 1,00,650 Closing Stock was ₹21,000 Amt. (₹) Cr. 17,500 62,500 650 15,000 5,000 1,00,650 -
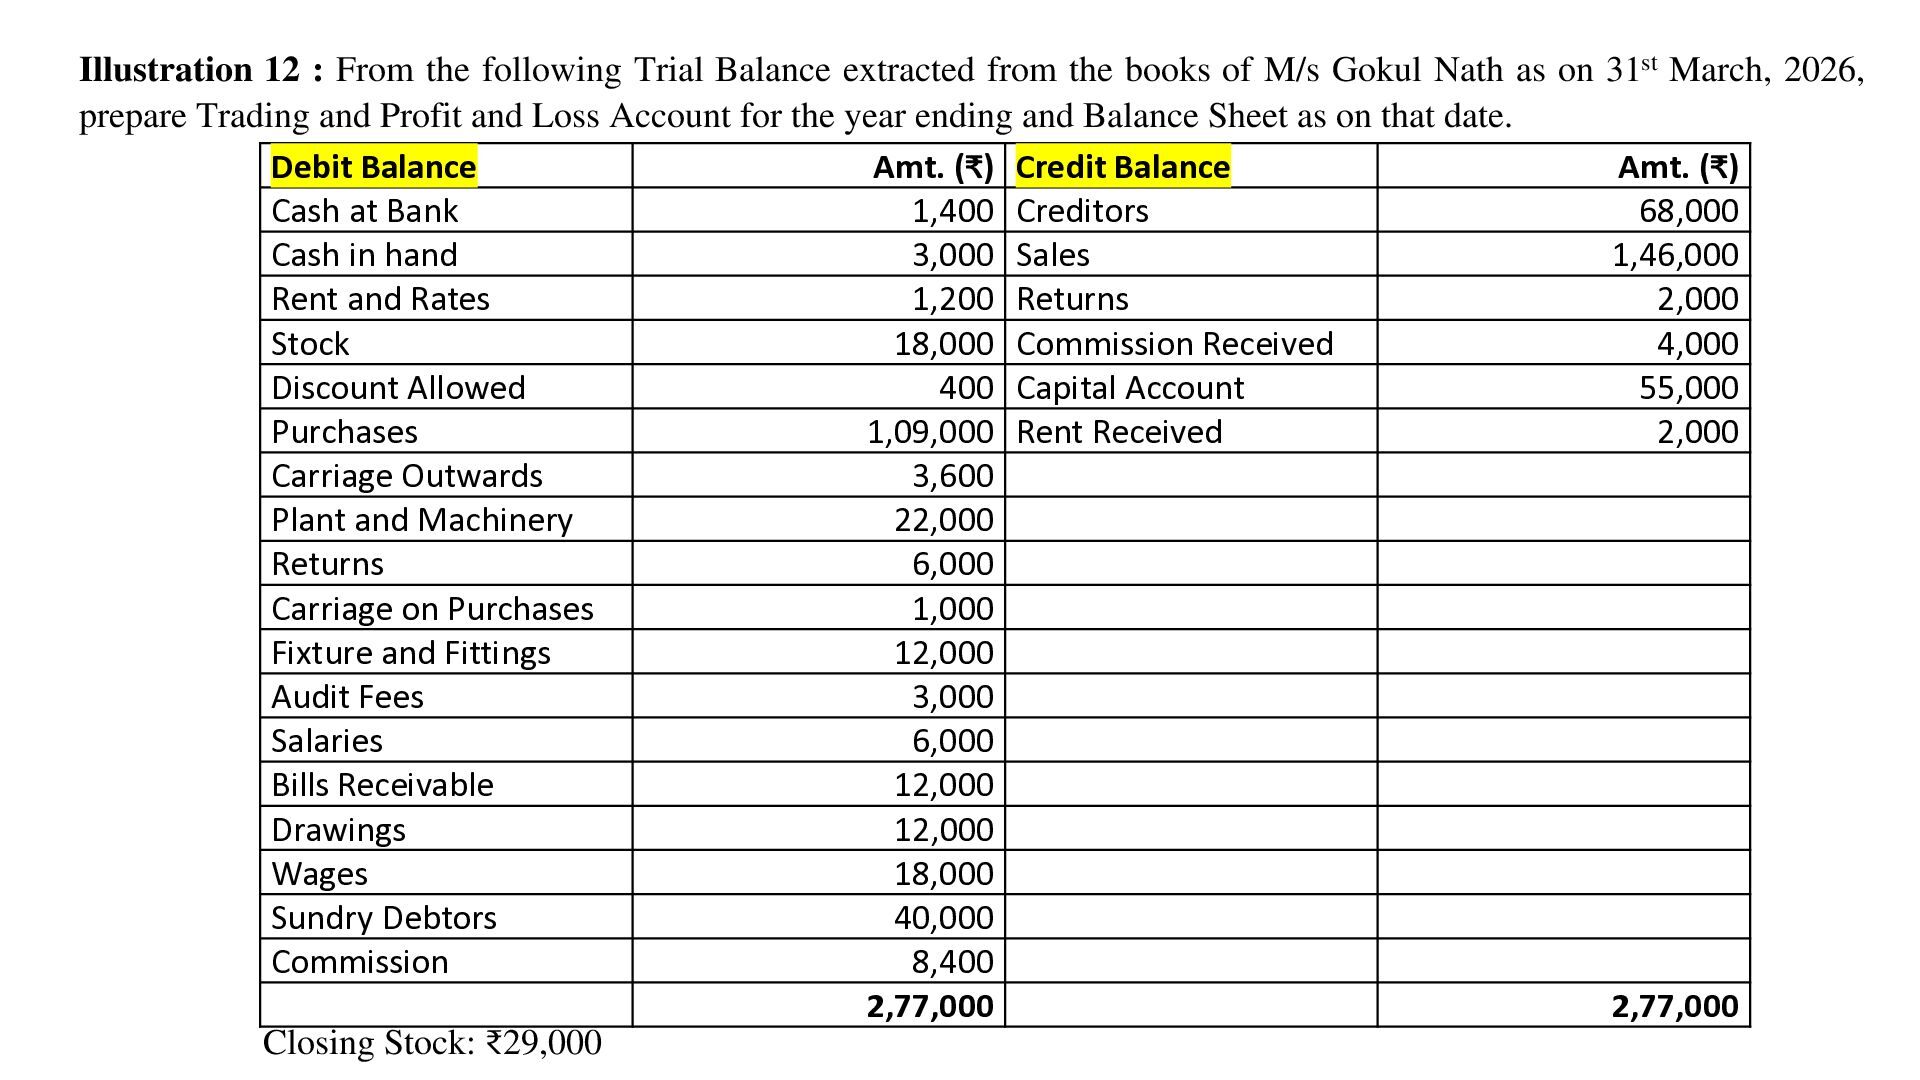
Illustration 12 : From the following Trial Balance extracted from
the books of M/s Gokul Nath as on 31st March, 2026, prepare Trading and Profit and Loss Account for the year ending and Balance Sheet as on that date. Debit Balance Amt. (₹) Credit Balance Amt. (₹) Cash at Bank 1,400 Creditors 68,000 Cash in hand 3,000 Sales 1,46,000 Rent and Rates 1,200 Returns 2,000 Stock 18,000 Commission Received 4,000 Discount Allowed 400 Capital Account 55,000 Purchases 1,09,000 Rent Received 2,000 Carriage Outwards 3,600 Plant and Machinery 22,000 Returns 6,000 Carriage on Purchases 1,000 Fixture and Fittings 12,000 Audit Fees 3,000 Salaries 6,000 Bills Receivable 12,000 Drawings 12,000 Wages 18,000 Sundry Debtors 40,000 Commission 8,400 2,77,000 2,77,000 Closing Stock: ₹29,000 -
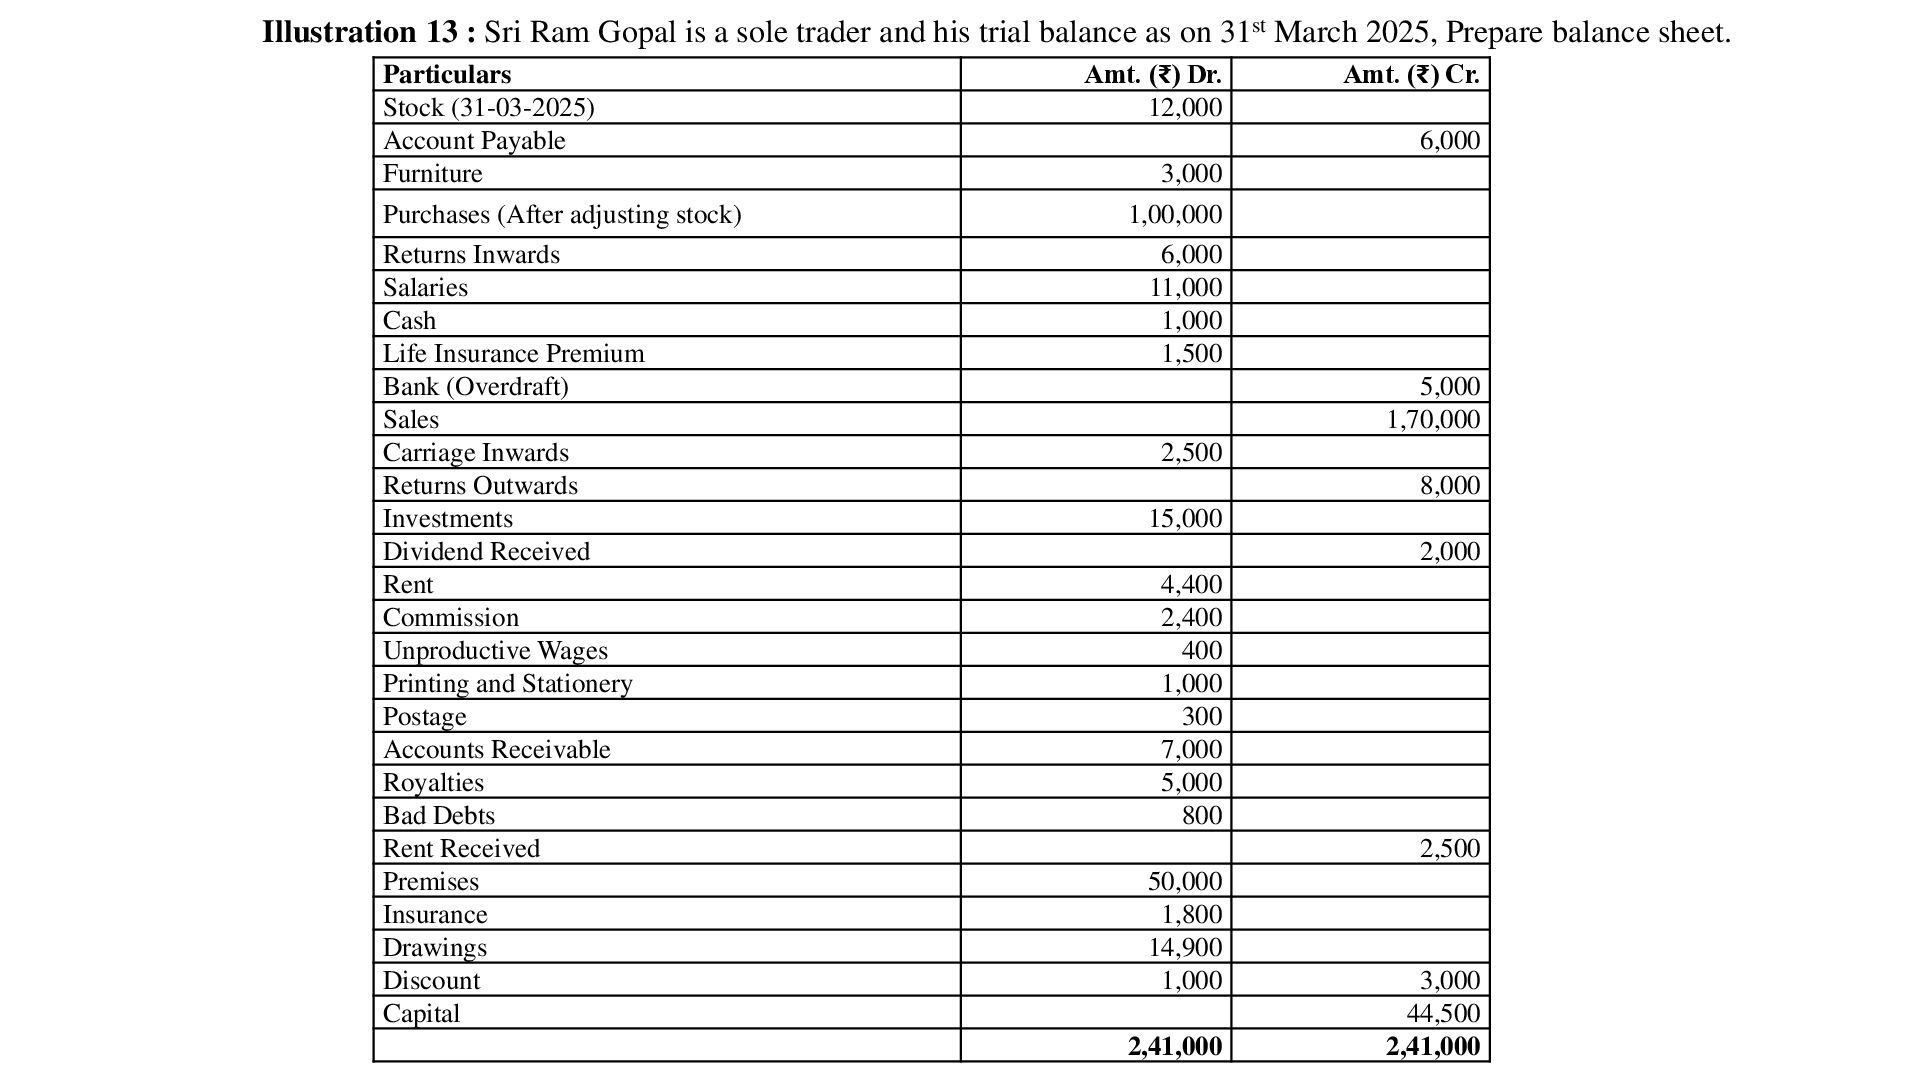
Illustration 13 : Sri Ram Gopal is a sole trader
and his trial balance as on 31st March 2025, Prepare balance sheet. Particulars Stock (31-03-2025) Account Payable Furniture Purchases (After adjusting stock) Returns Inwards Salaries Cash Life Insurance Premium Bank (Overdraft) Sales Carriage Inwards Returns Outwards Investments Dividend Received Rent Commission Unproductive Wages Printing and Stationery Postage Accounts Receivable Royalties Bad Debts Rent Received Premises Insurance Drawings Discount Capital Amt. (₹) Dr. 12,000 Amt. (₹) Cr. 6,000 3,000 1,00,000 6,000 11,000 1,000 1,500 5,000 1,70,000 2,500 8,000 15,000 2,000 4,400 2,400 400 1,000 300 7,000 5,000 800 2,500 50,000 1,800 14,900 1,000 2,41,000 3,000 44,500 2,41,000 -
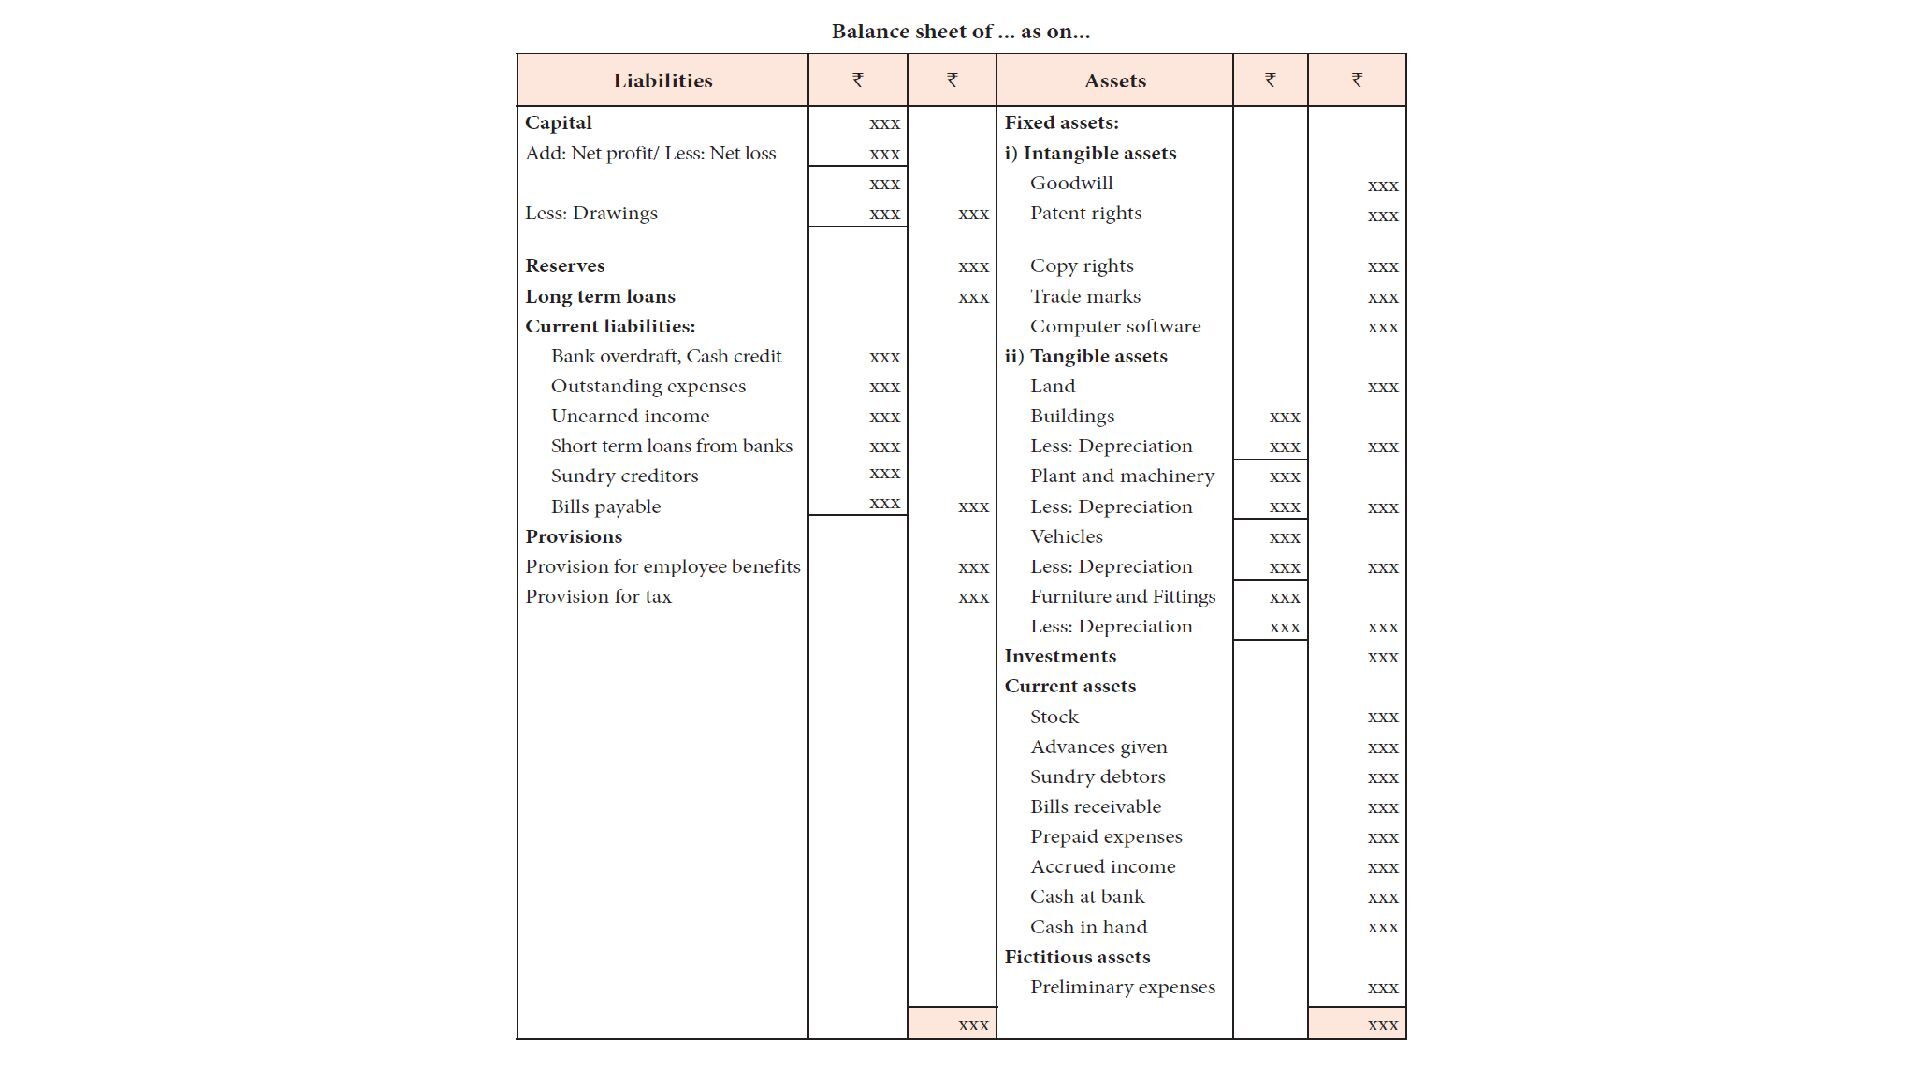
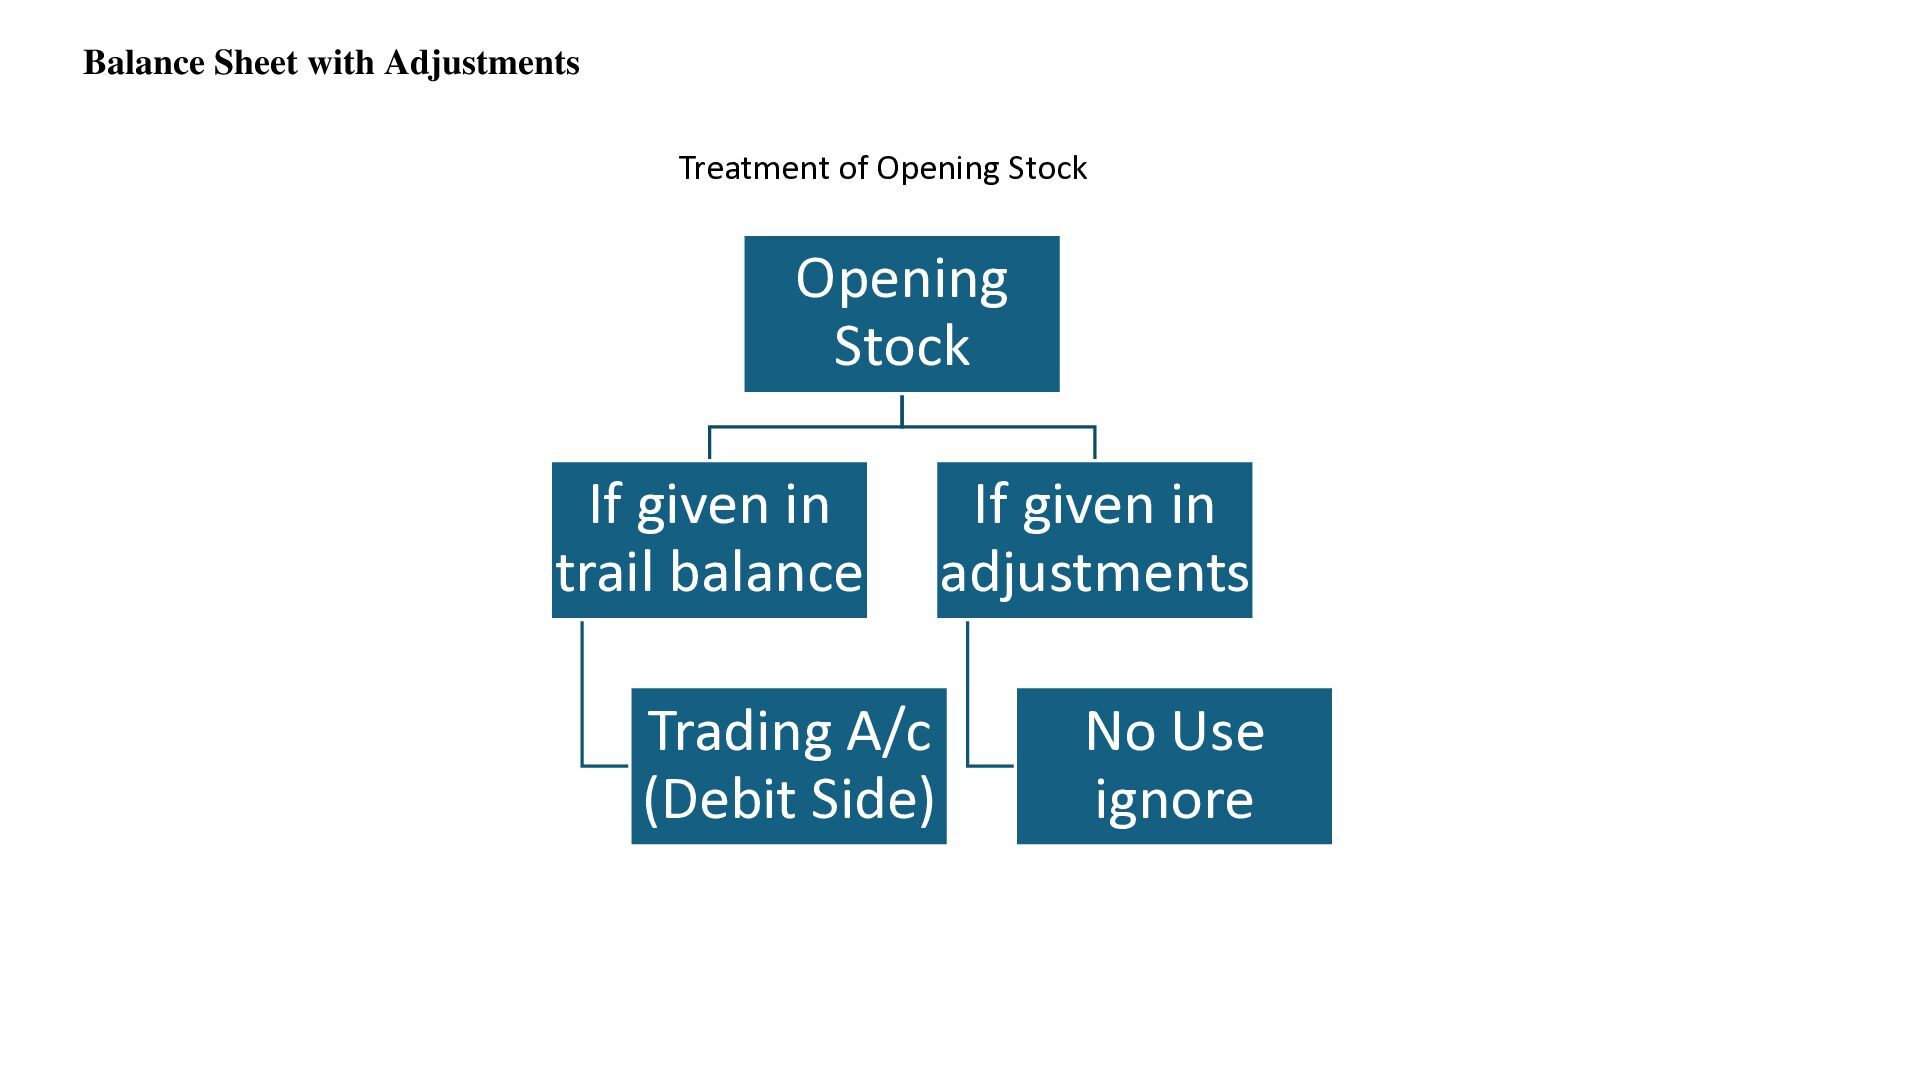
Balance Sheet with Adjustments Treatment of Opening Stock Opening Stock
If given in trail balance Trading A/c (Debit Side) If given in adjustments No Use ignore -
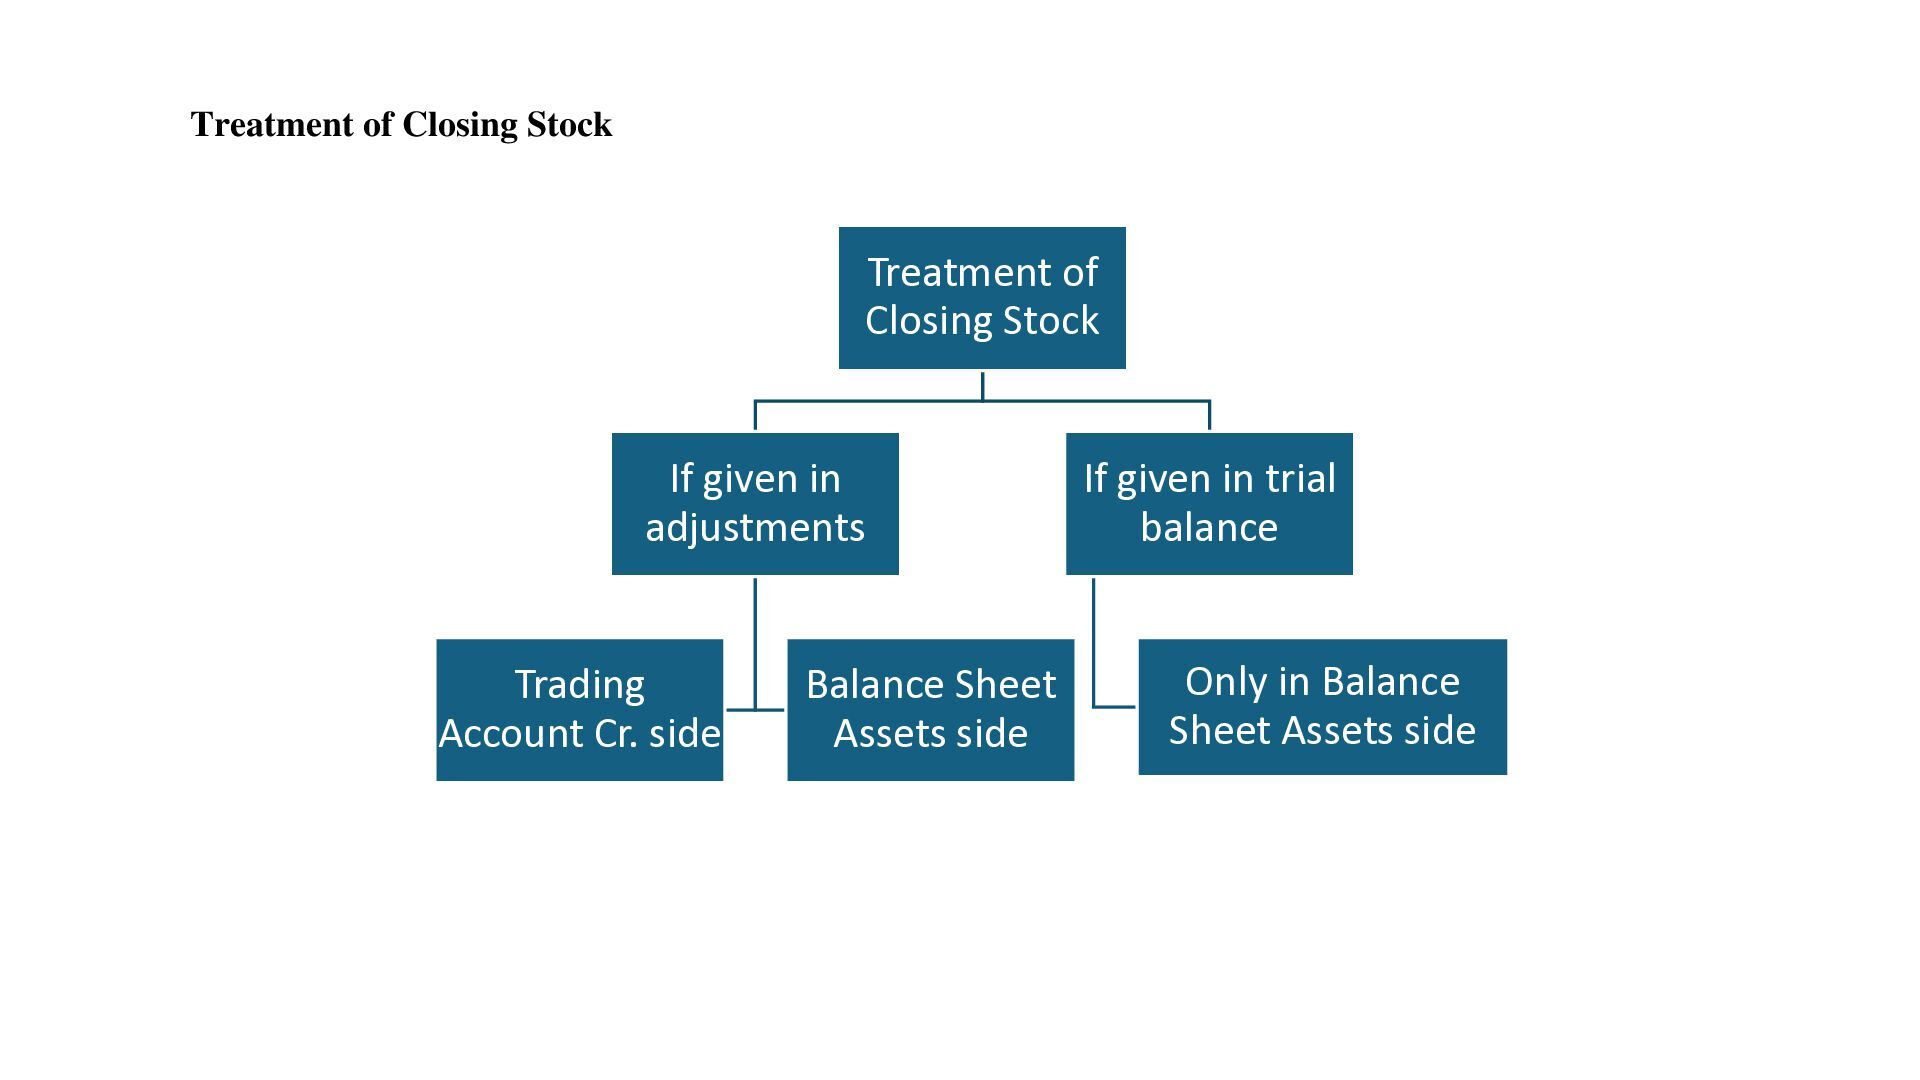
Treatment of Closing Stock Treatment of Closing Stock If given
in adjustments Trading Account Cr. side Balance Sheet Assets side If given in trial balance Only in Balance Sheet Assets side -
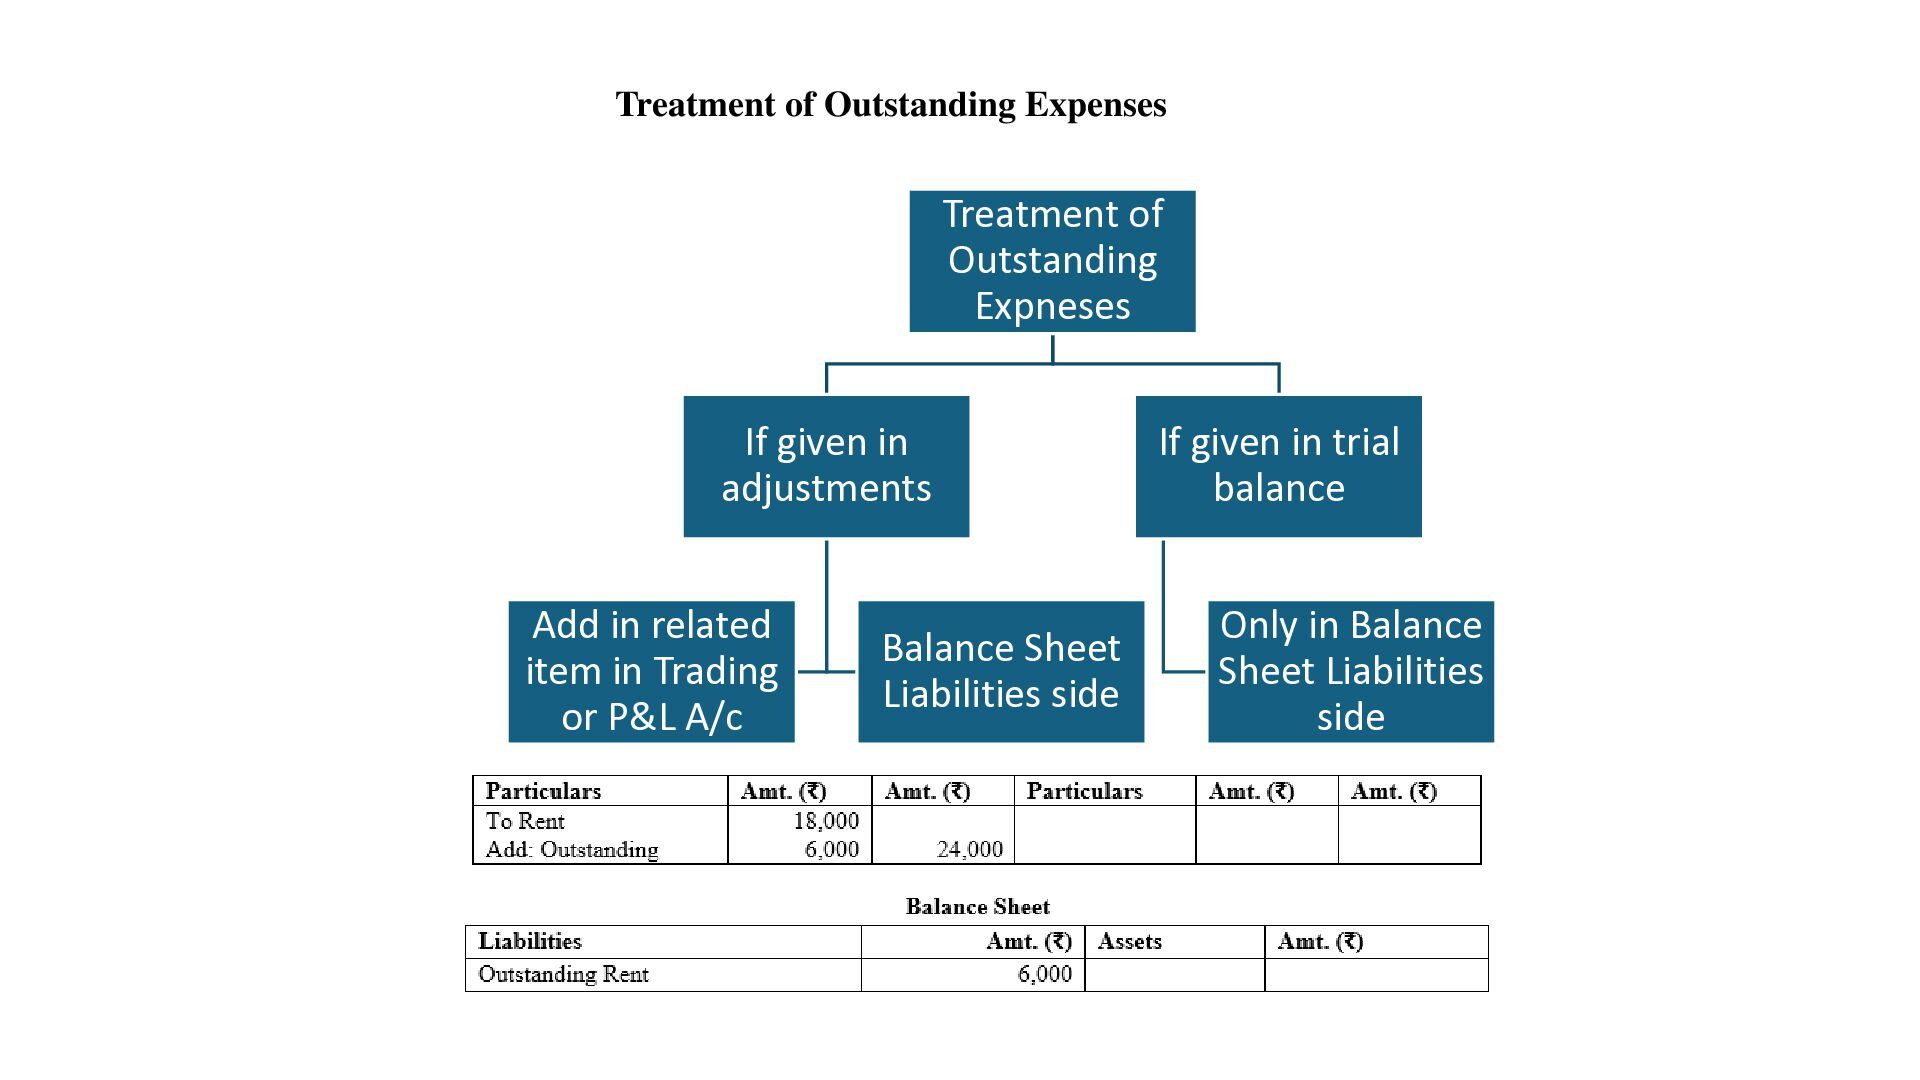
Treatment of Outstanding Expenses Treatment of Outstanding Expneses If given
in adjustments Add in related item in Trading or P&L A/c Balance Sheet Liabilities side If given in trial balance Only in Balance Sheet Liabilities side -
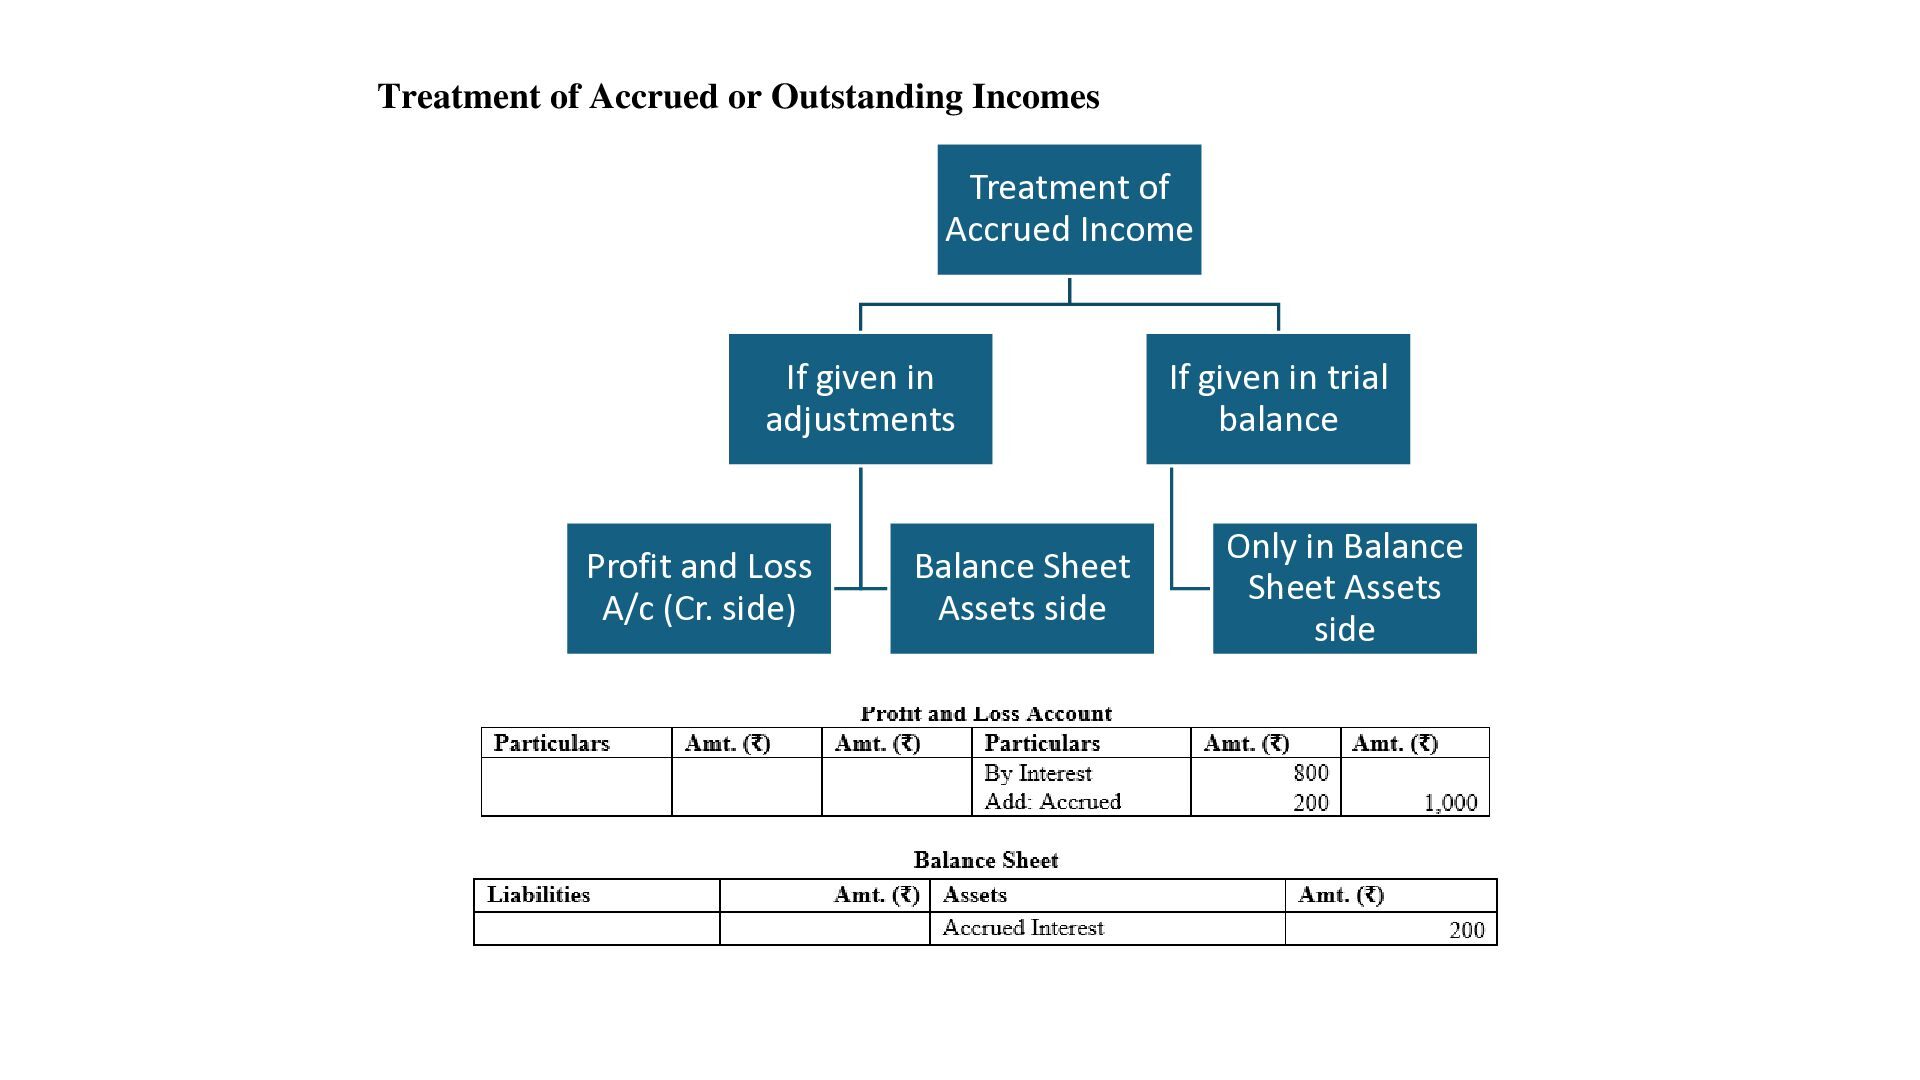
Treatment of Accrued or Outstanding Incomes Treatment of Accrued Income
If given in adjustments Profit and Loss A/c (Cr. side) Balance Sheet Assets side If given in trial balance Only in Balance Sheet Assets side -
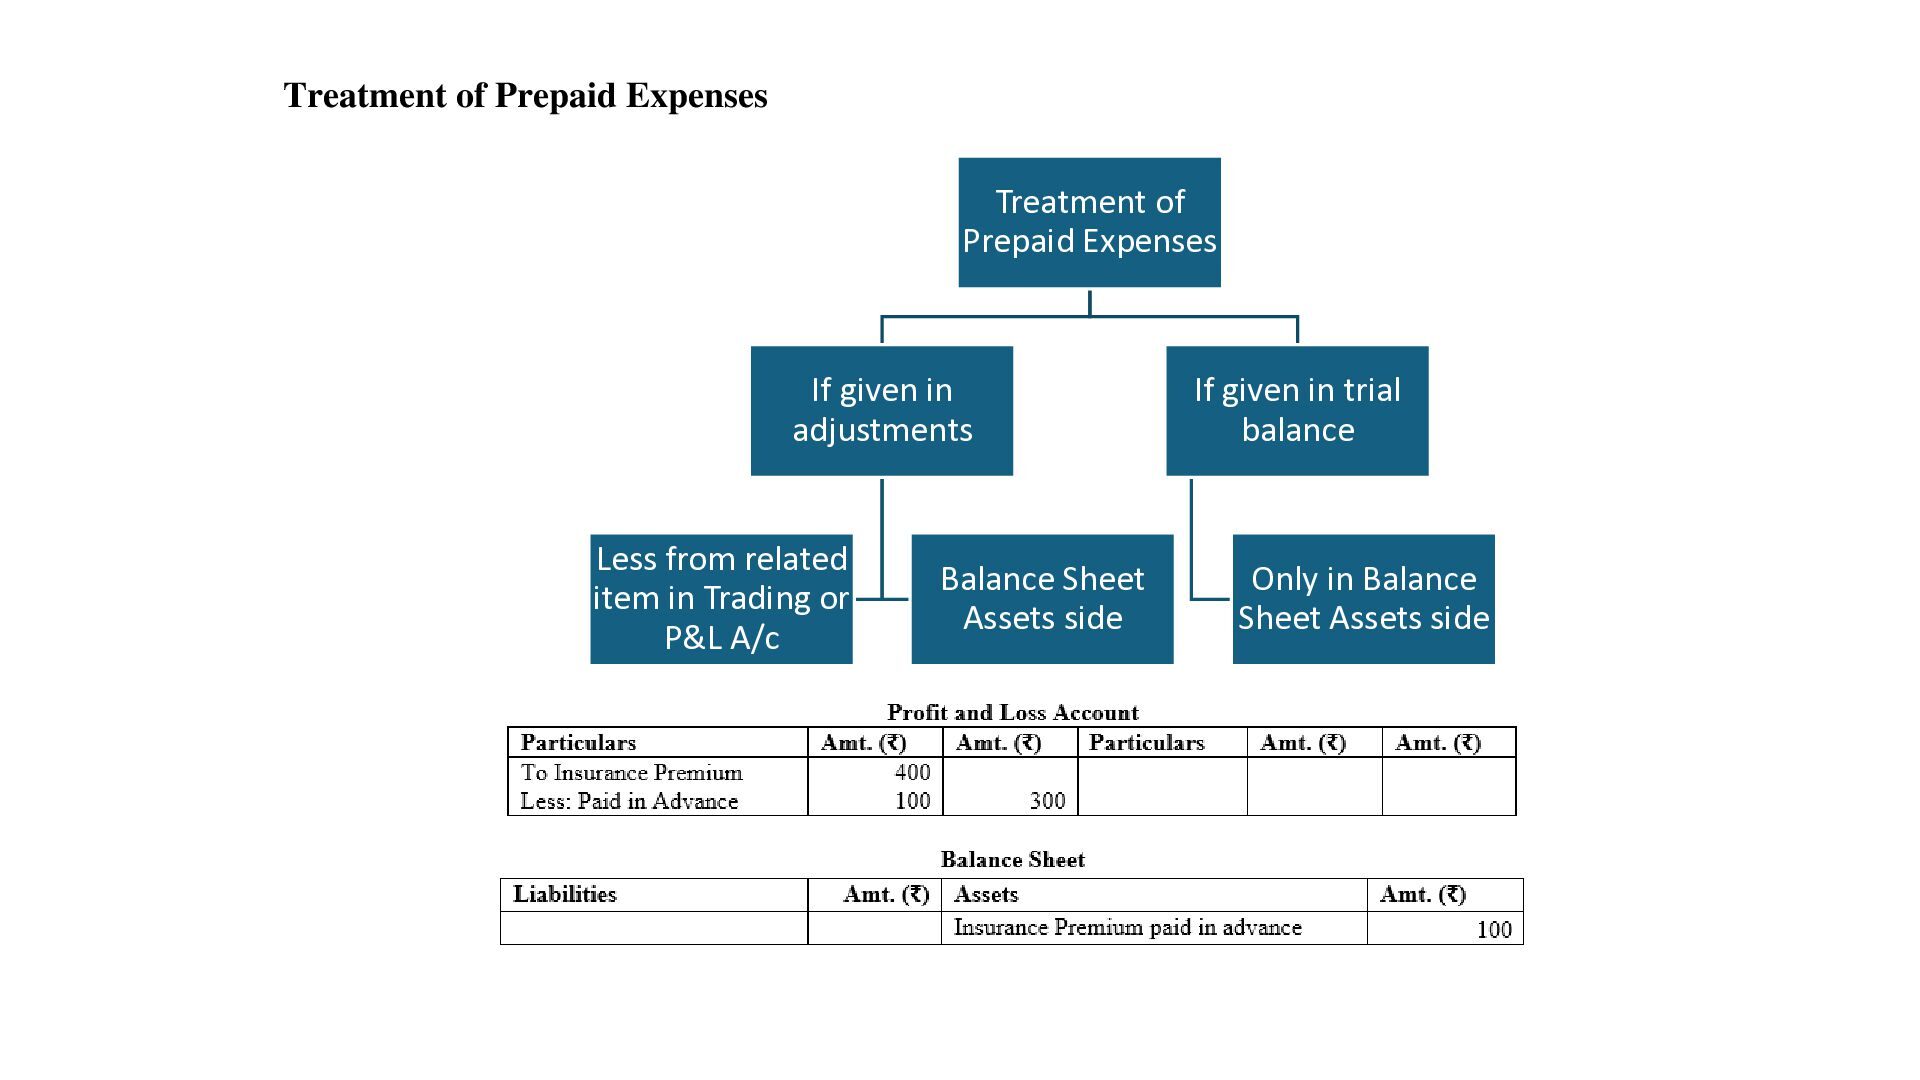
Treatment of Prepaid Expenses Treatment of Prepaid Expenses If given
in adjustments Less from related item in Trading or P&L A/c Balance Sheet Assets side If given in trial balance Only in Balance Sheet Assets side -
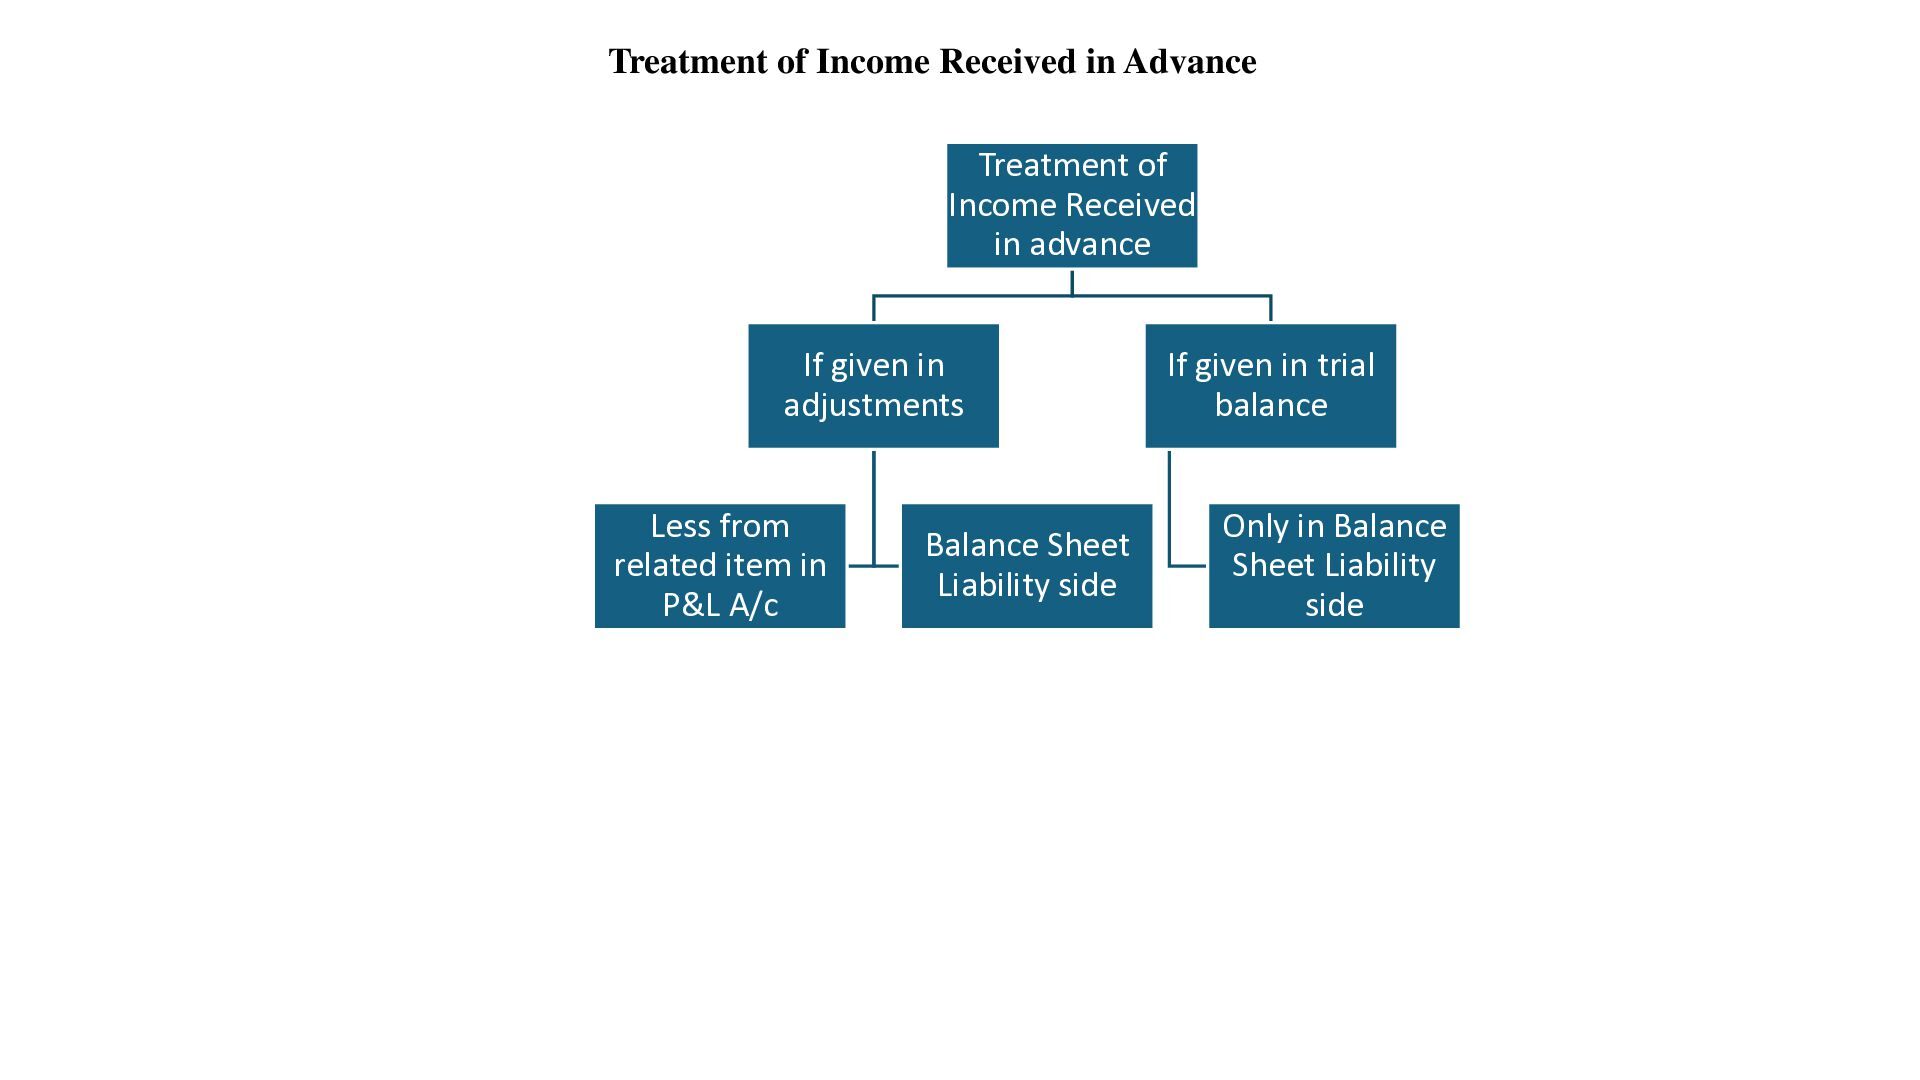
Treatment of Income Received in Advance Treatment of Income Received
in advance If given in adjustments Less from related item in P&L A/c Balance Sheet Liability side If given in trial balance Only in Balance Sheet Liability side -
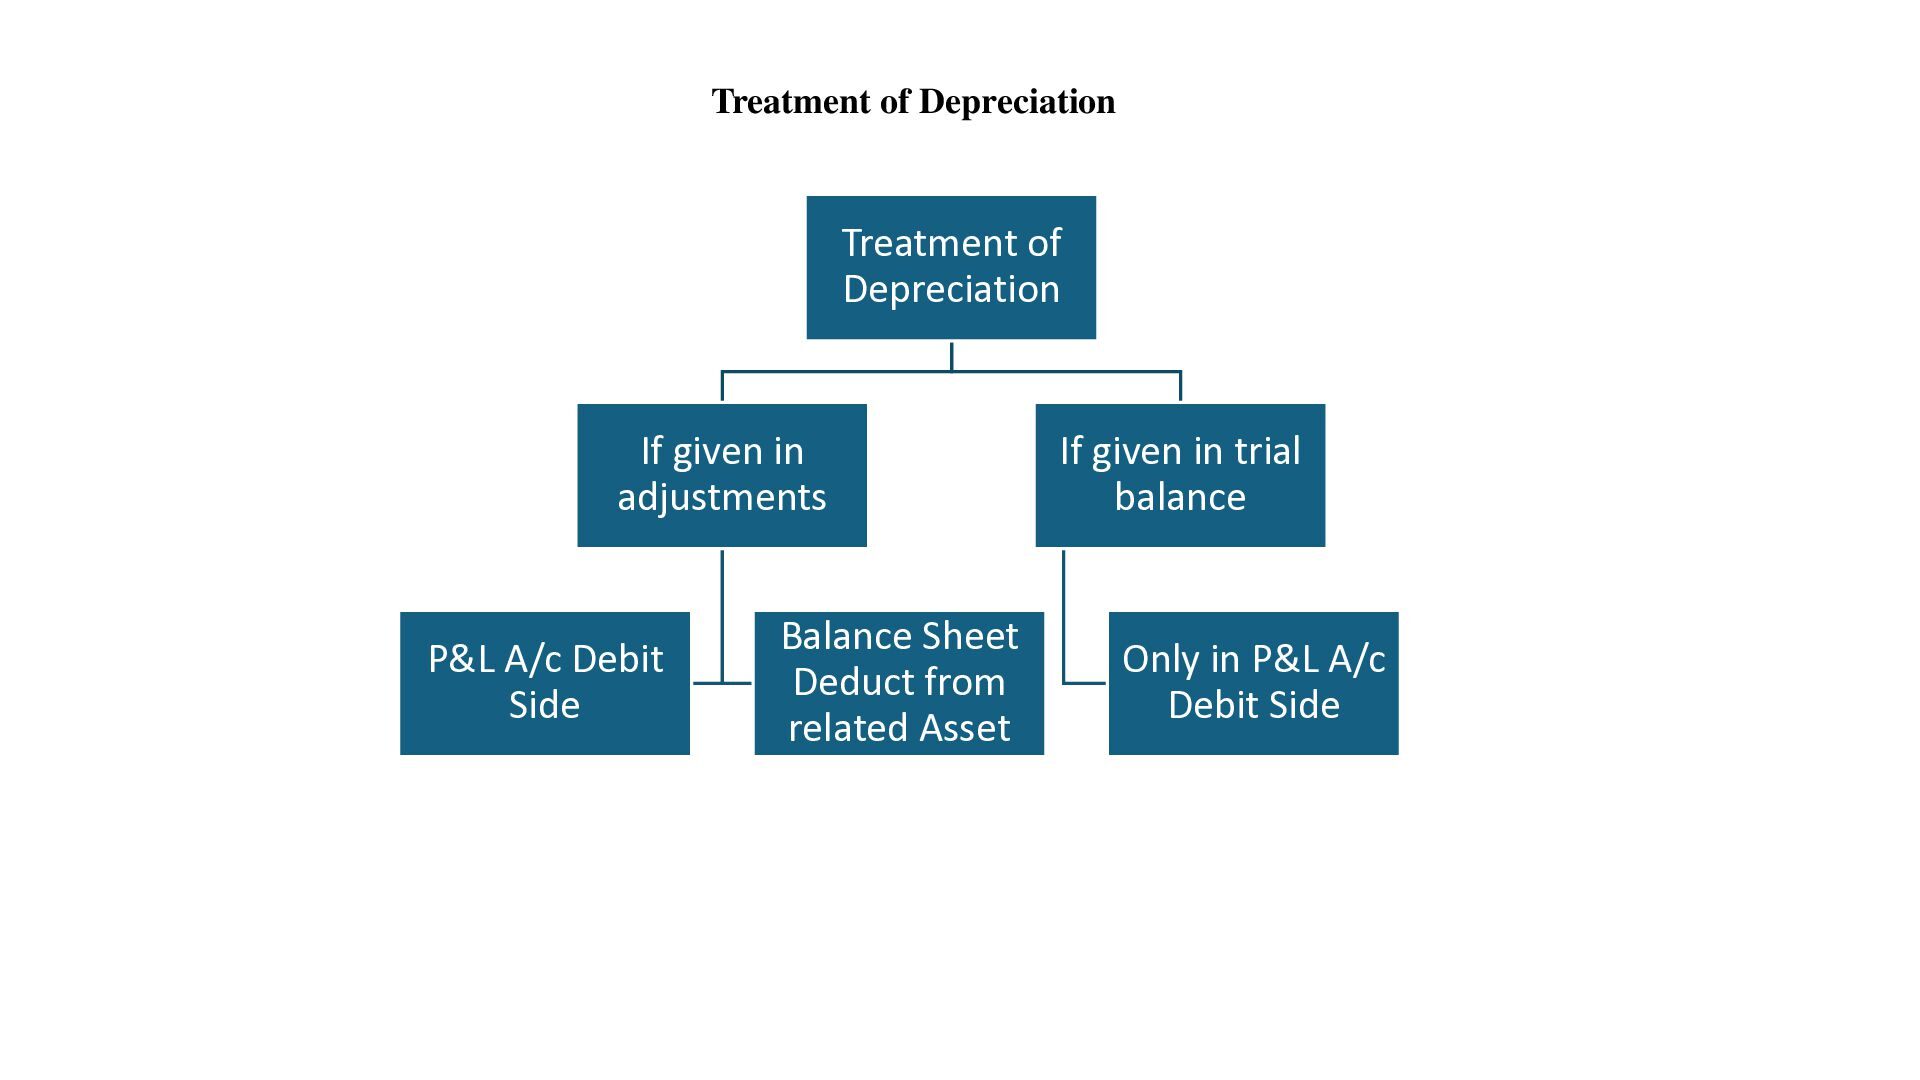
Treatment of Depreciation Treatment of Depreciation If given in adjustments
P&L A/c Debit Side Balance Sheet Deduct from related Asset If given in trial balance Only in P&L A/c Debit Side -
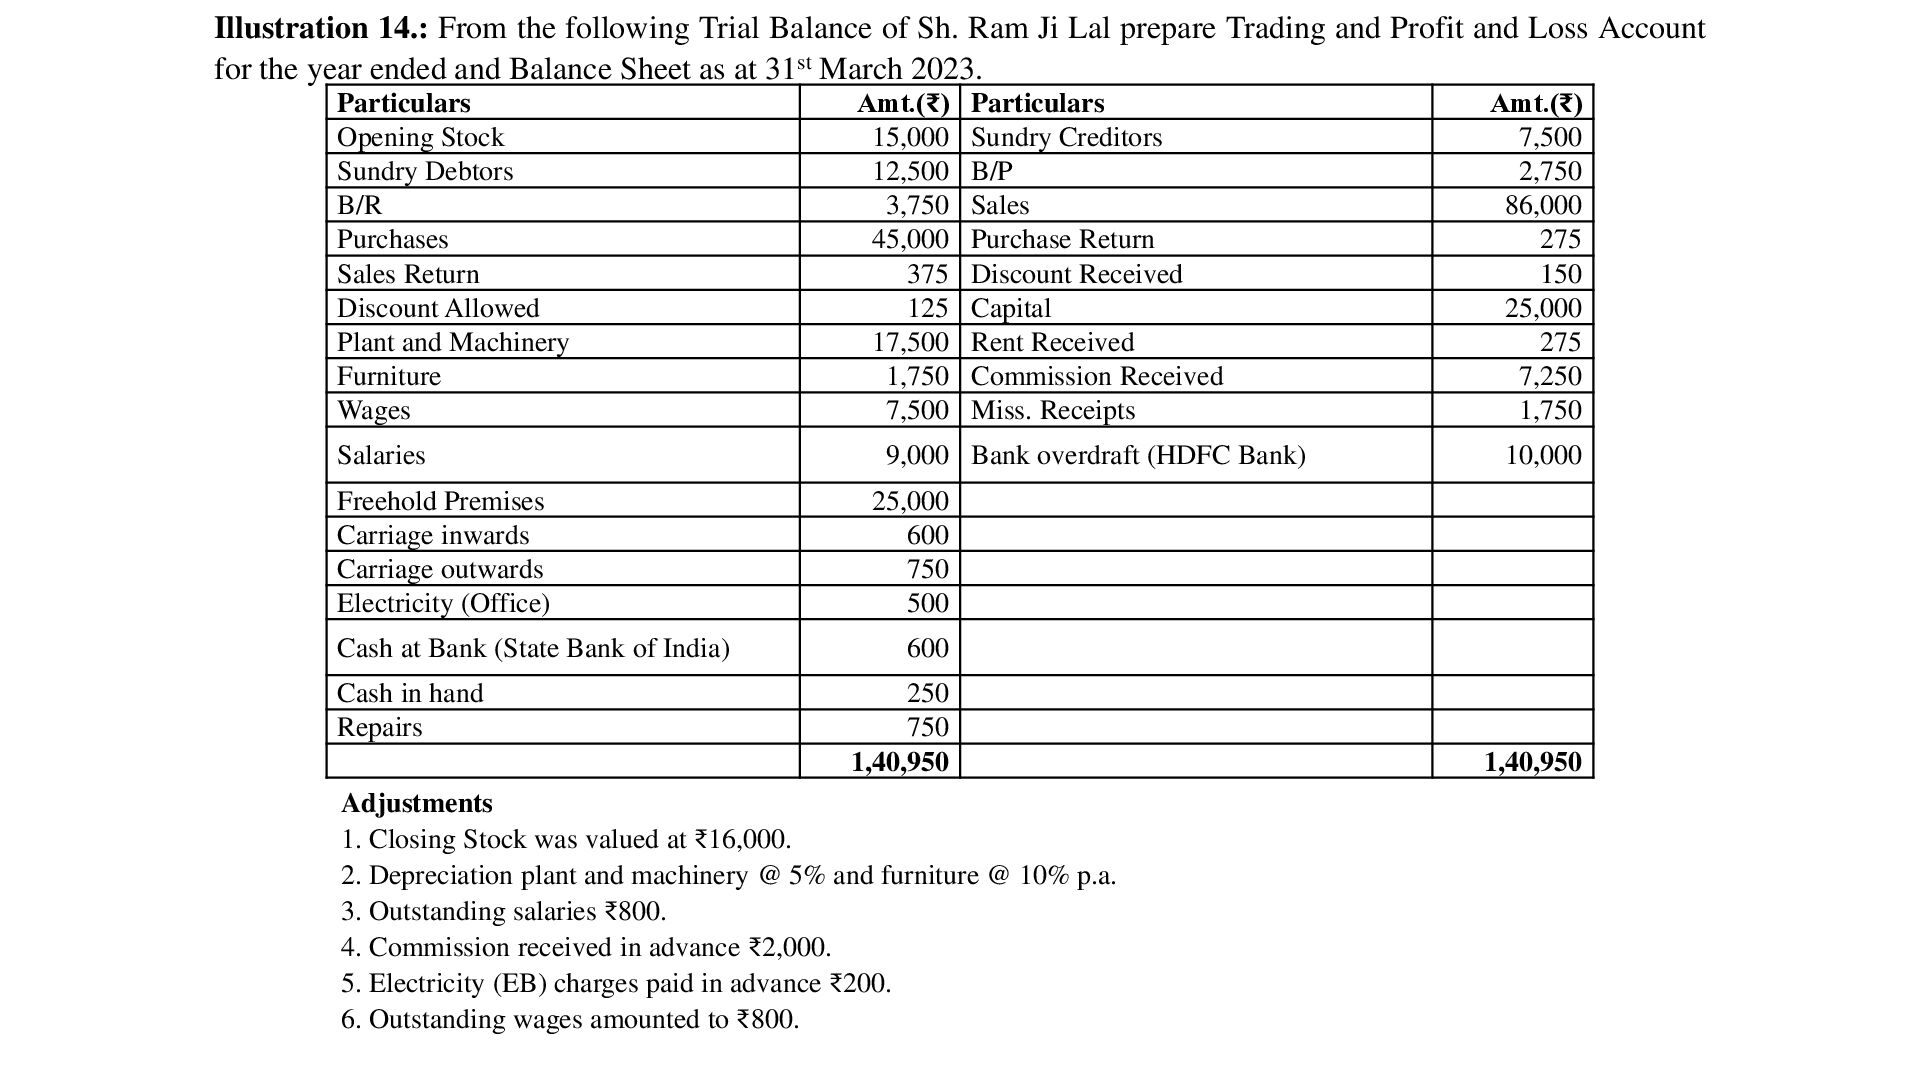
Illustration 14.: From the following Trial Balance of Sh. Ram
Ji Lal prepare Trading and Profit and Loss Account for the year ended and Balance Sheet as at 31st March 2023. Particulars Sundry Creditors B/P Sales Purchase Return Discount Received Capital Rent Received Commission Received Miss. Receipts Amt.(₹) 7,500 2,750 86,000 275 150 25,000 275 7,250 1,750 Salaries 9,000 Bank overdraft (HDFC Bank) 10,000 Freehold Premises Carriage inwards Carriage outwards Electricity (Office) 25,000 600 750 500 Particulars Opening Stock Sundry Debtors B/R Purchases Sales Return Discount Allowed Plant and Machinery Furniture Wages Cash at Bank (State Bank of India) Cash in hand Repairs Amt.(₹) 15,000 12,500 3,750 45,000 375 125 17,500 1,750 7,500 600 250 750 1,40,950 Adjustments 1. Closing Stock was valued at ₹16,000. 2. Depreciation plant and machinery @ 5% and furniture @ 10% p.a. 3. Outstanding salaries ₹800. 4. Commission received in advance ₹2,000. 5. Electricity (EB) charges paid in advance ₹200. 6. Outstanding wages amounted to ₹800. 1,40,950 -
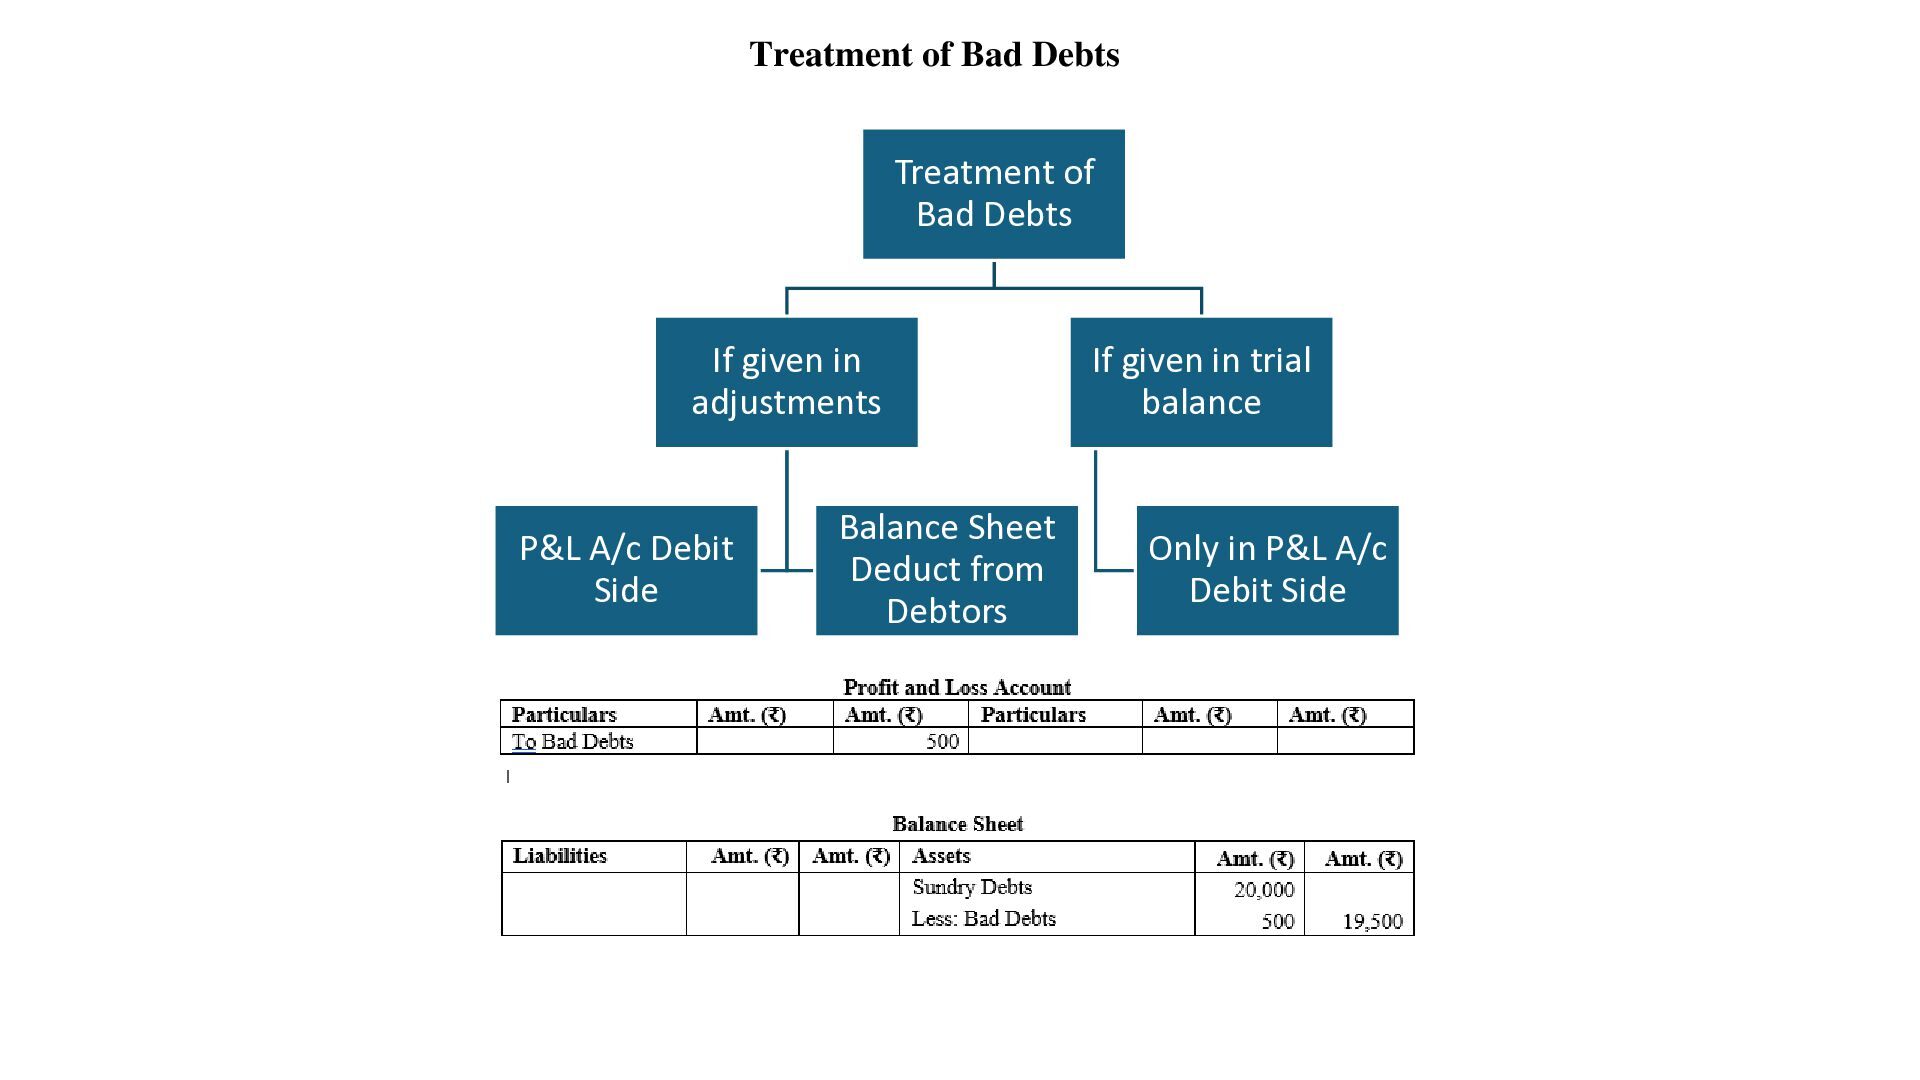
Treatment of Bad Debts Treatment of Bad Debts If given
in adjustments P&L A/c Debit Side Balance Sheet Deduct from Debtors If given in trial balance Only in P&L A/c Debit Side -
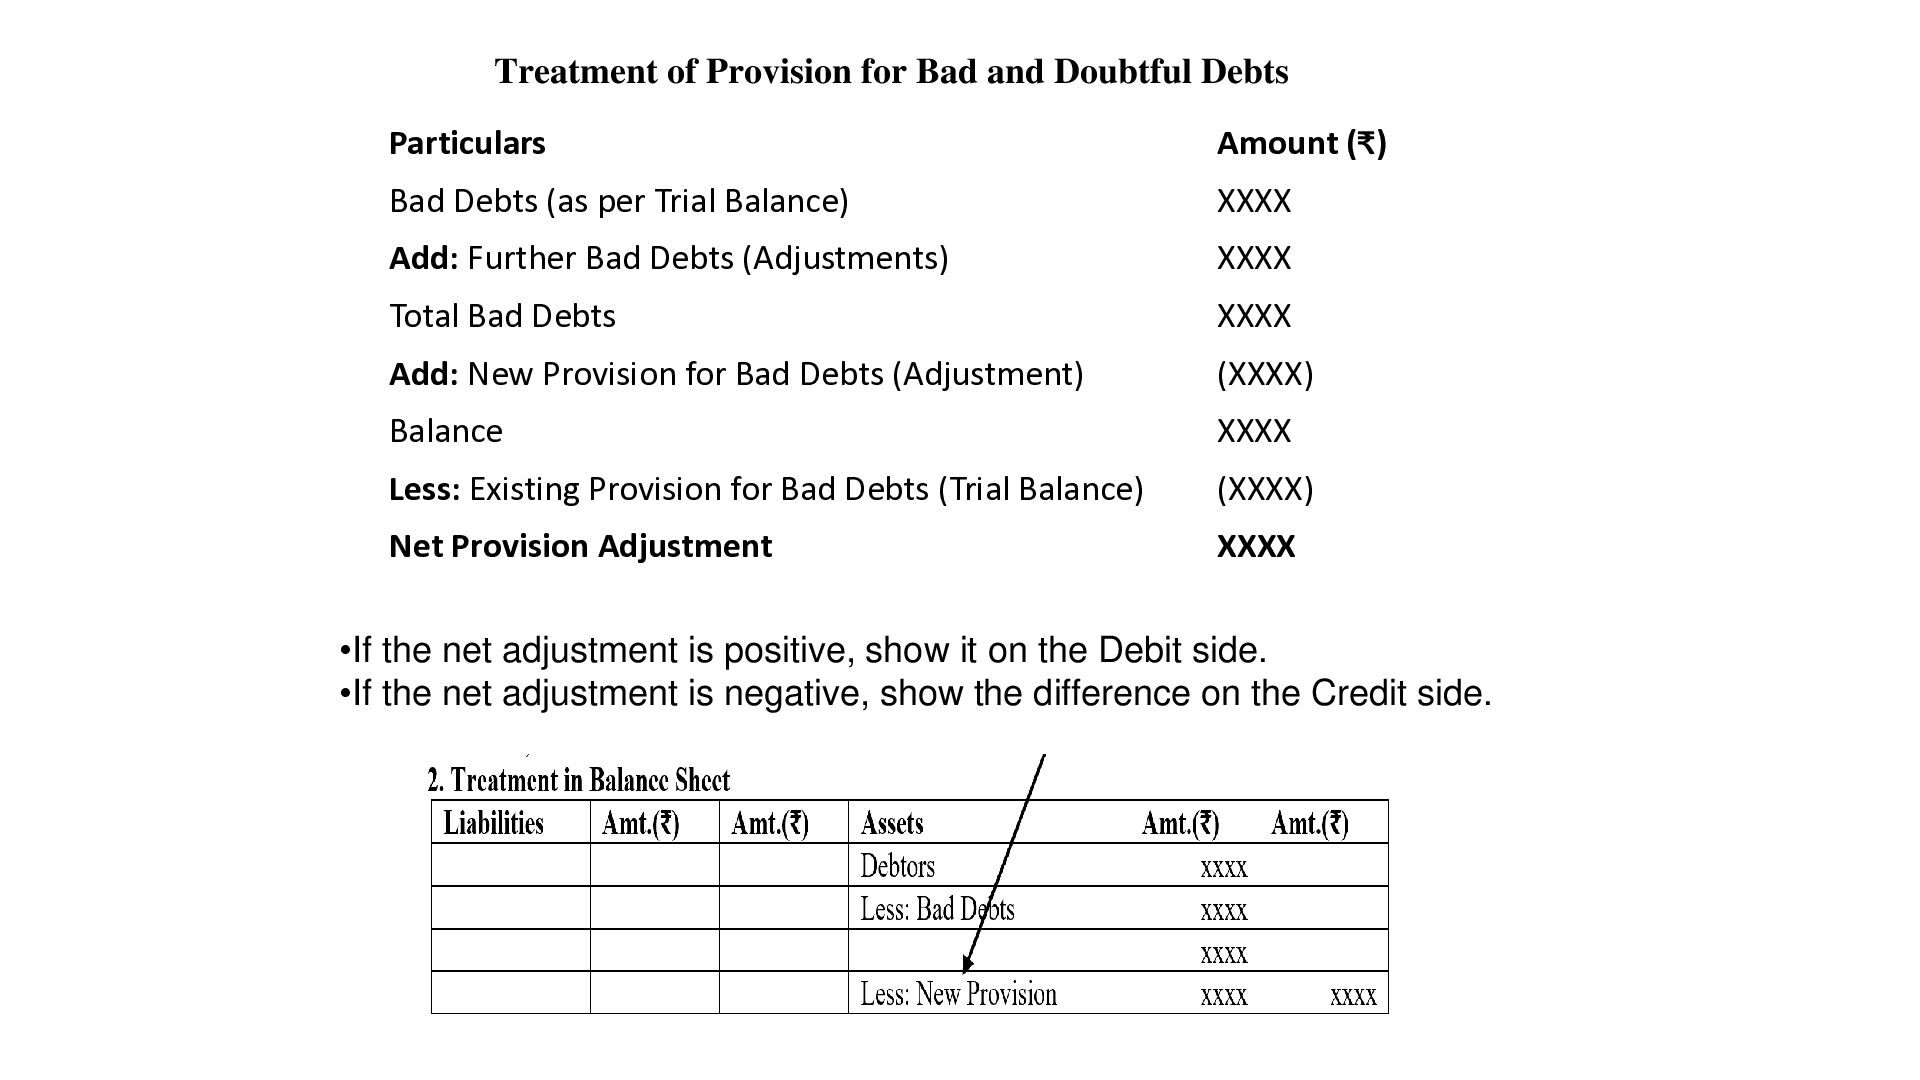
Treatment of Provision for Bad and Doubtful Debts Particulars Amount
(₹) Bad Debts (as per Trial Balance) XXXX Add: Further Bad Debts (Adjustments) XXXX Total Bad Debts XXXX Add: New Provision for Bad Debts (Adjustment) (XXXX) Balance XXXX Less: Existing Provision for Bad Debts (Trial Balance) (XXXX) Net Provision Adjustment XXXX •If the net adjustment is positive, show it on the Debit side. •If the net adjustment is negative, show the difference on the Credit side. -
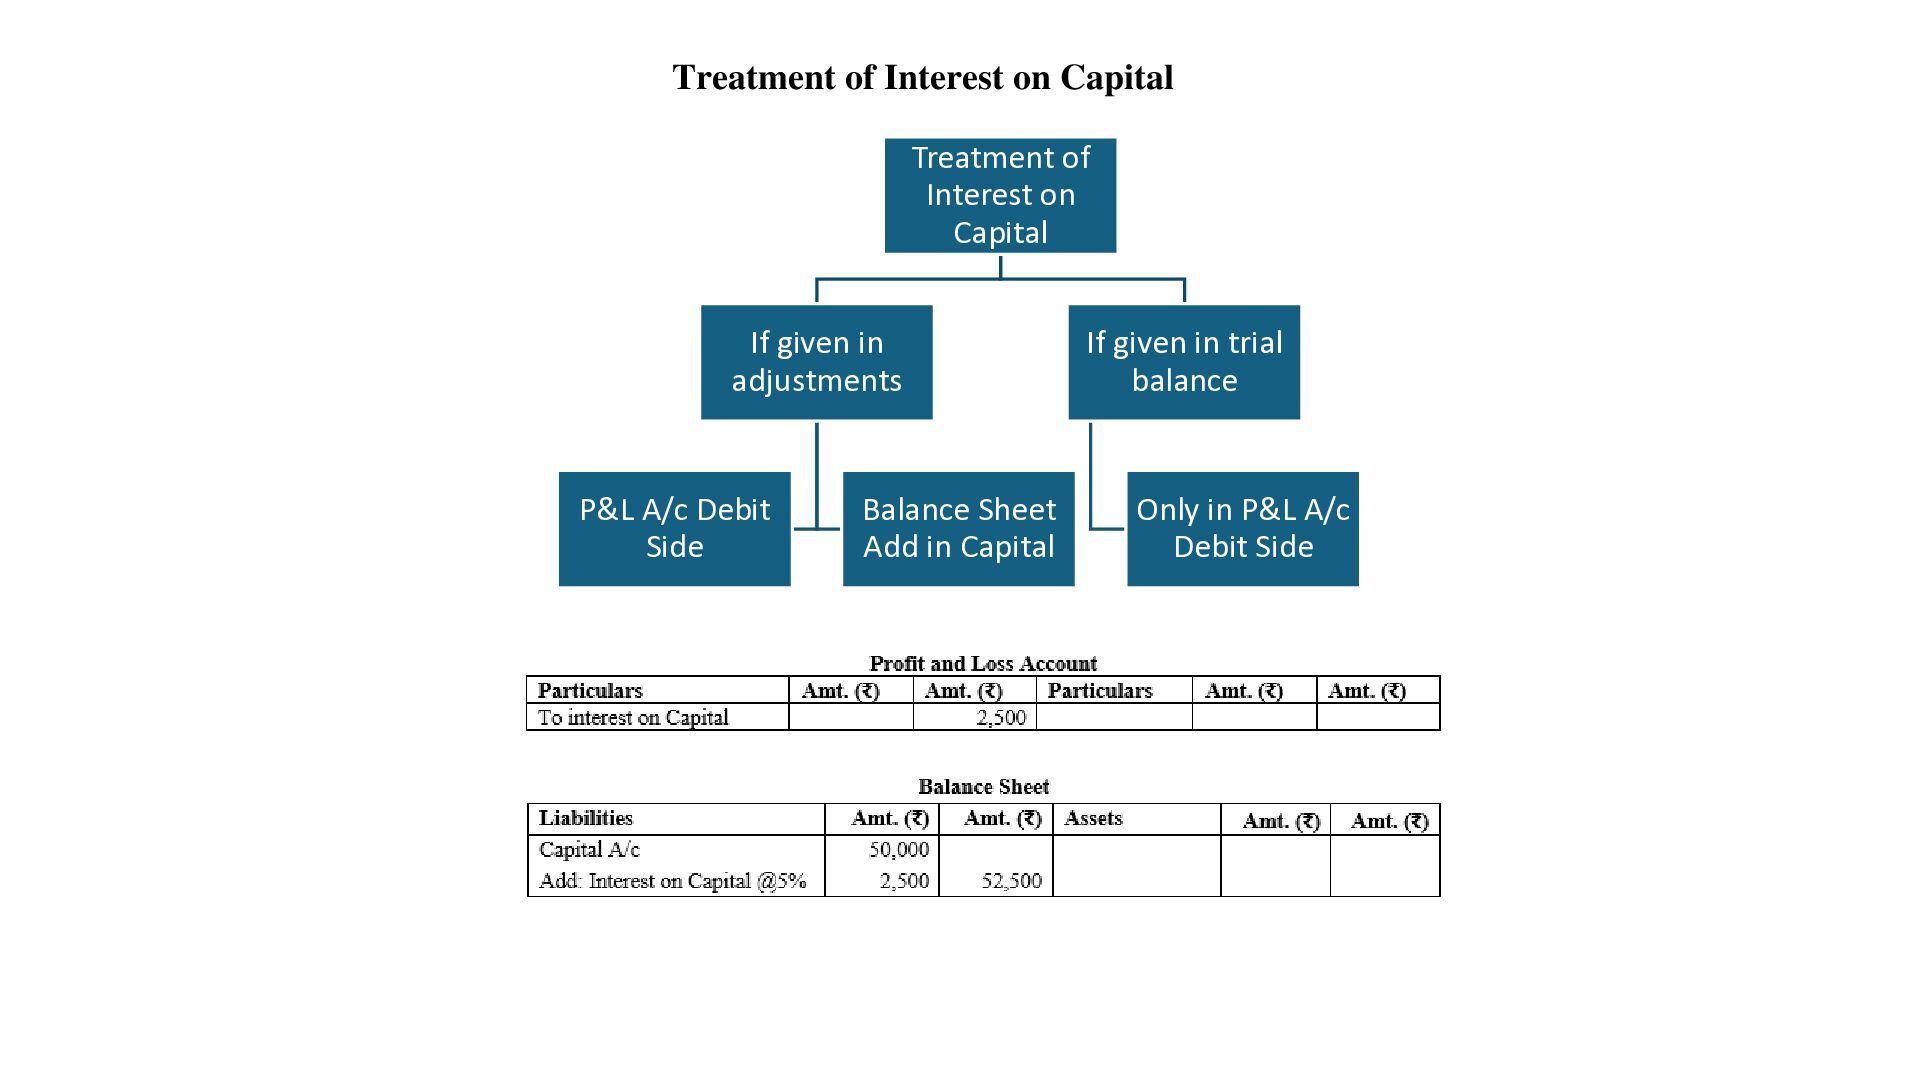
Treatment of Interest on Capital Treatment of Interest on Capital
If given in adjustments P&L A/c Debit Side Balance Sheet Add in Capital If given in trial balance Only in P&L A/c Debit Side -
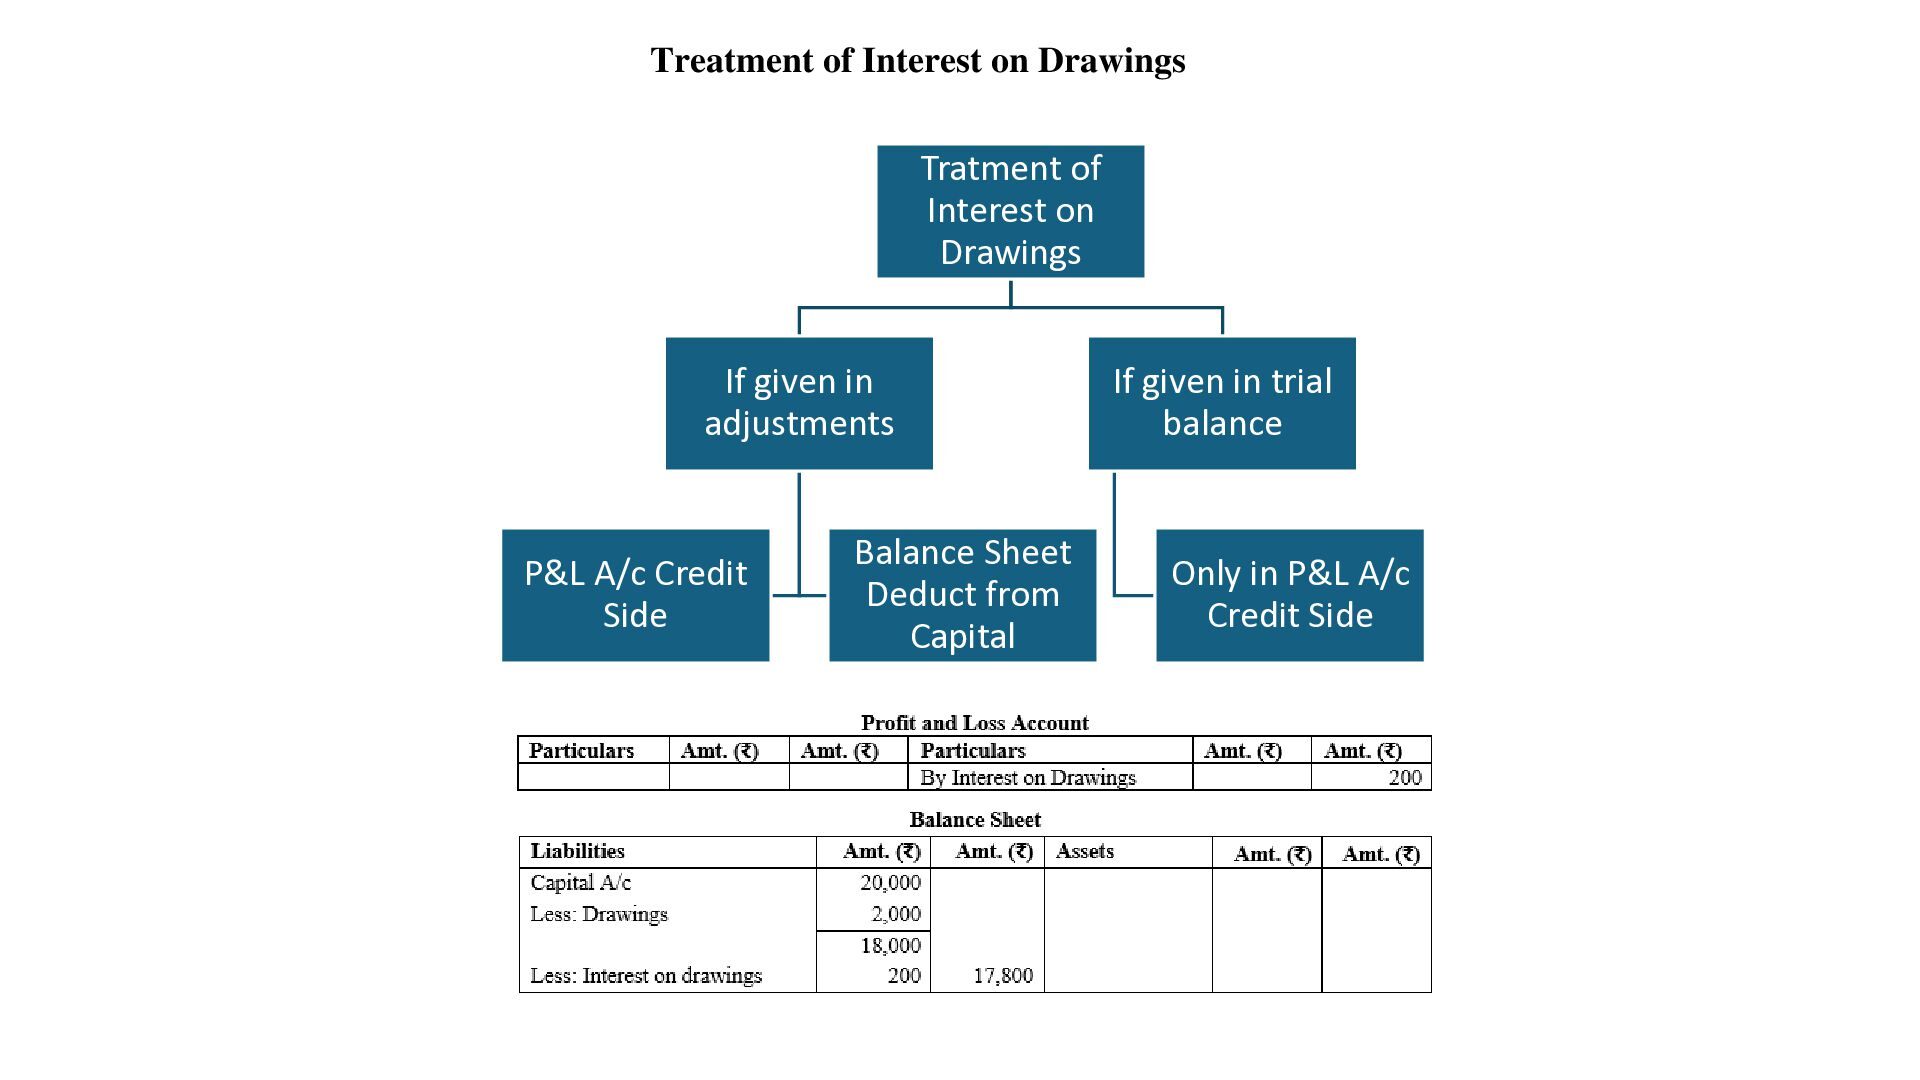
Treatment of Interest on Drawings Tratment of Interest on Drawings
If given in adjustments P&L A/c Credit Side Balance Sheet Deduct from Capital If given in trial balance Only in P&L A/c Credit Side -
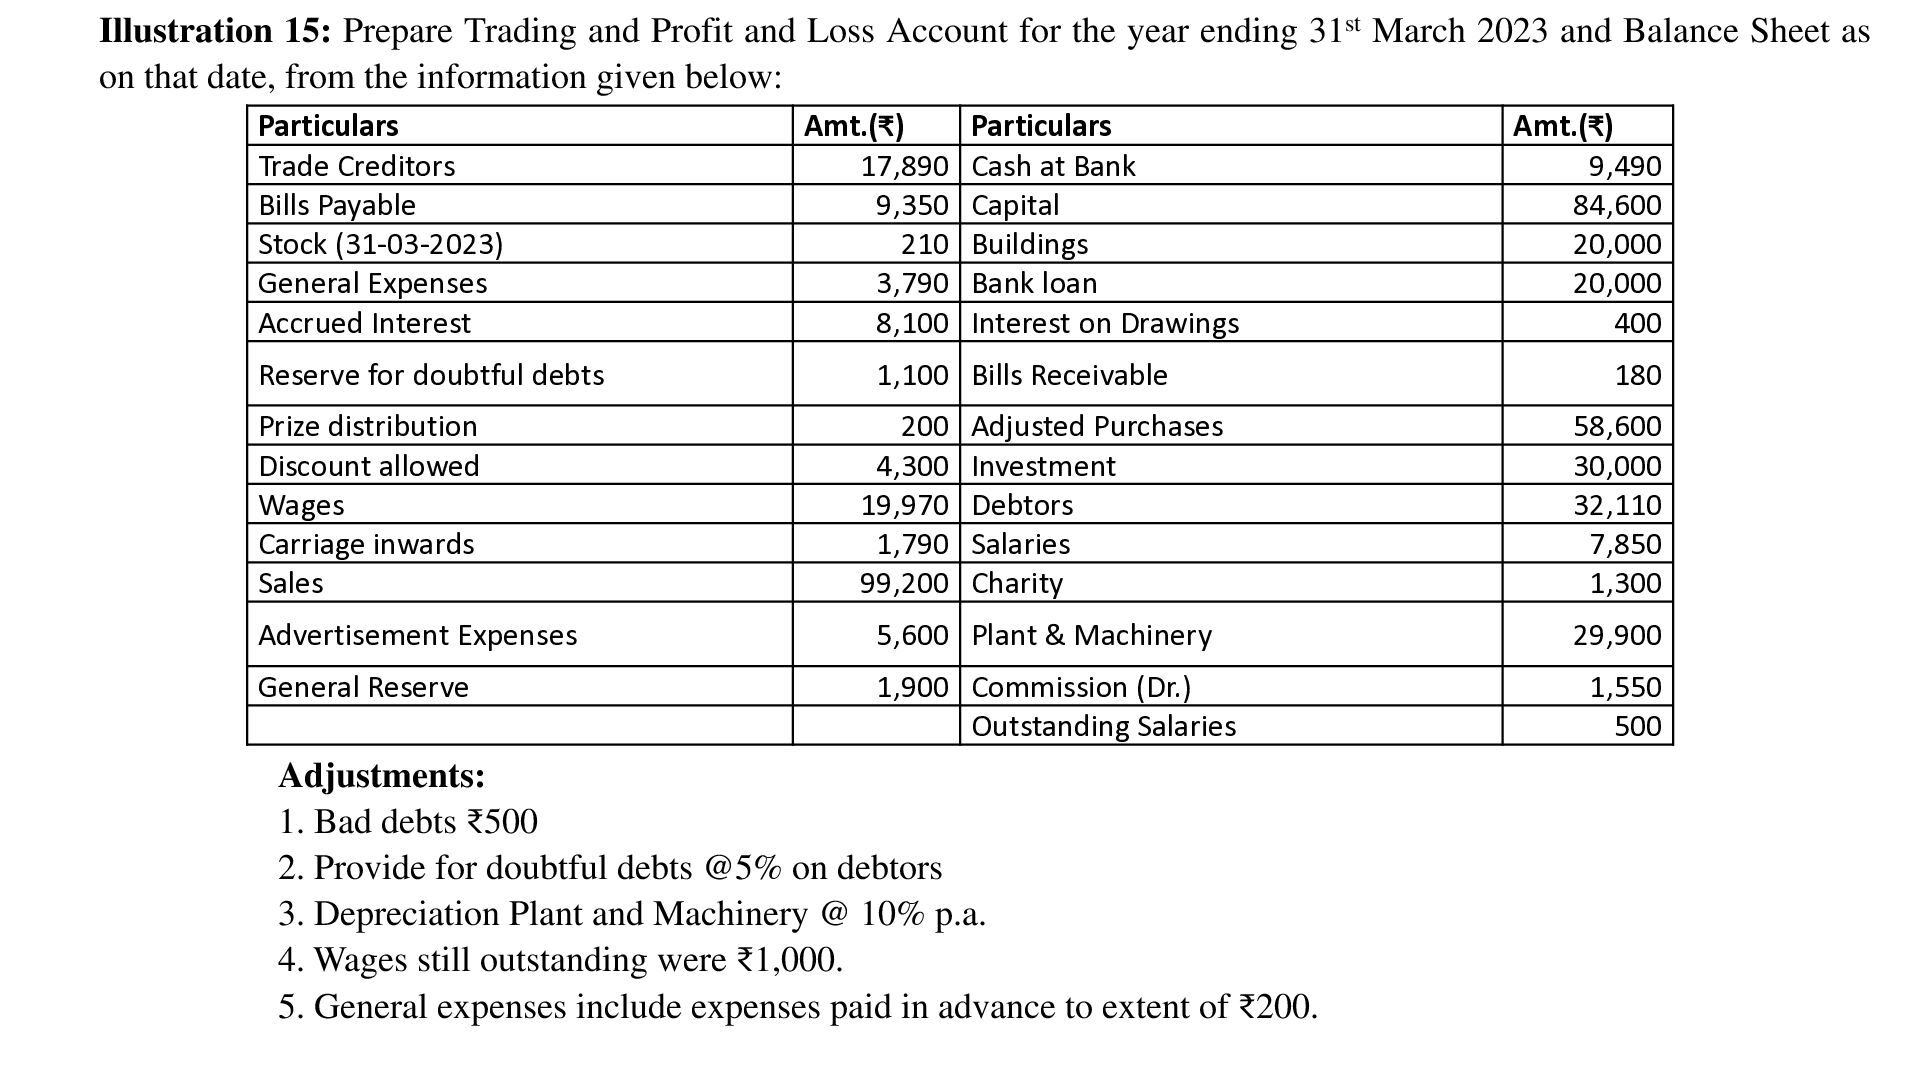
Illustration 15: Prepare Trading and Profit and Loss Account for
the year ending 31st March 2023 and Balance Sheet as on that date, from the information given below: Particulars Trade Creditors Bills Payable Stock (31-03-2023) General Expenses Accrued Interest Amt.(₹) Particulars 17,890 Cash at Bank 9,350 Capital 210 Buildings 3,790 Bank loan 8,100 Interest on Drawings Amt.(₹) 9,490 84,600 20,000 20,000 400 Reserve for doubtful debts 1,100 Bills Receivable 180 Prize distribution Discount allowed Wages Carriage inwards Sales 200 Adjusted Purchases 4,300 Investment 19,970 Debtors 1,790 Salaries 99,200 Charity 58,600 30,000 32,110 7,850 1,300 Advertisement Expenses 5,600 Plant & Machinery 29,900 General Reserve 1,900 Commission (Dr.) Outstanding Salaries 1,550 500 Adjustments: 1. Bad debts ₹500 2. Provide for doubtful debts @5% on debtors 3. Depreciation Plant and Machinery @ 10% p.a. 4. Wages still outstanding were ₹1,000. 5. General expenses include expenses paid in advance to extent of ₹200. -
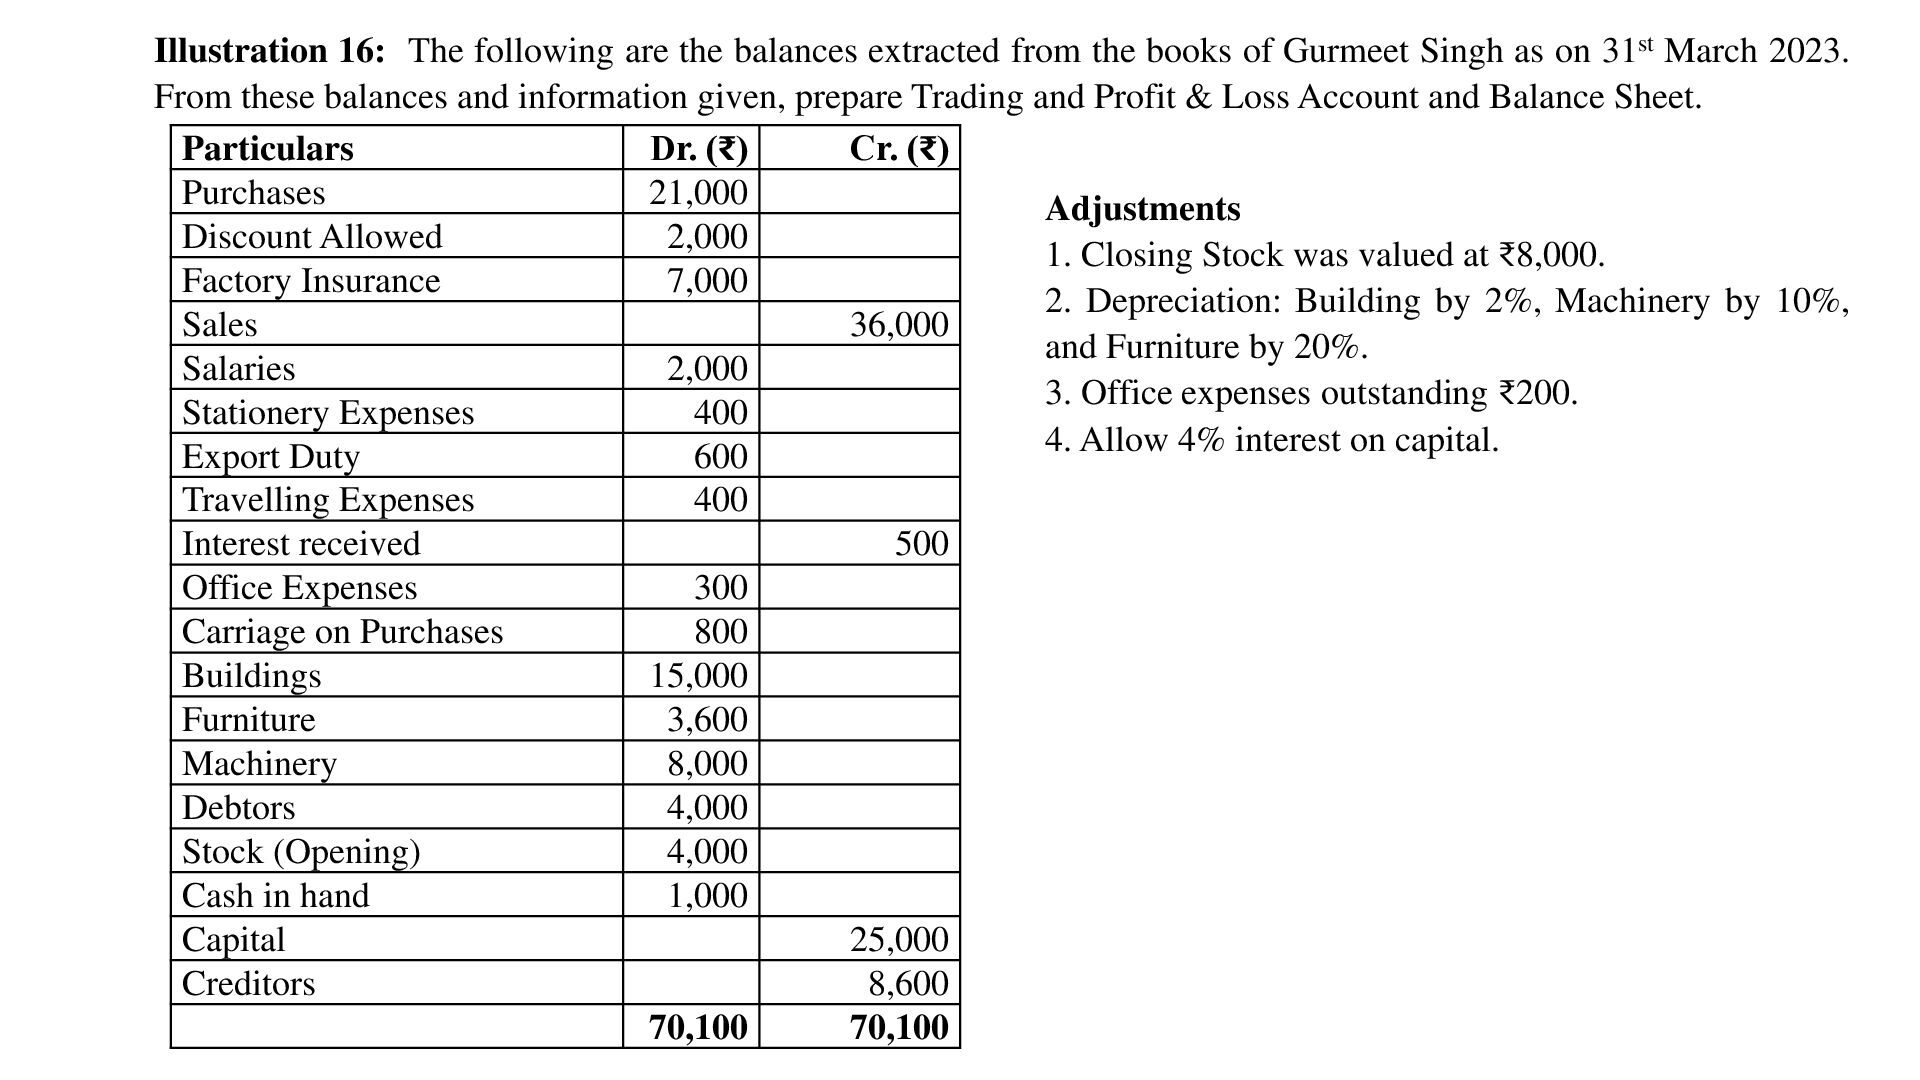
Illustration 16: The following are the balances extracted from the
books of Gurmeet Singh as on 31st March 2023. From these balances and information given, prepare Trading and Profit & Loss Account and Balance Sheet. Particulars Dr. (₹) Cr. (₹) Purchases 21,000 Adjustments Discount Allowed 2,000 1. Closing Stock was valued at ₹8,000. Factory Insurance 7,000 2. Depreciation: Building by 2%, Machinery by 10%, Sales 36,000 and Furniture by 20%. Salaries 2,000 3. Office expenses outstanding ₹200. Stationery Expenses 400 4. Allow 4% interest on capital. Export Duty 600 Travelling Expenses 400 Interest received 500 Office Expenses 300 Carriage on Purchases 800 Buildings 15,000 Furniture 3,600 Machinery 8,000 Debtors 4,000 Stock (Opening) 4,000 Cash in hand 1,000 Capital 25,000 Creditors 8,600 70,100 70,100 -
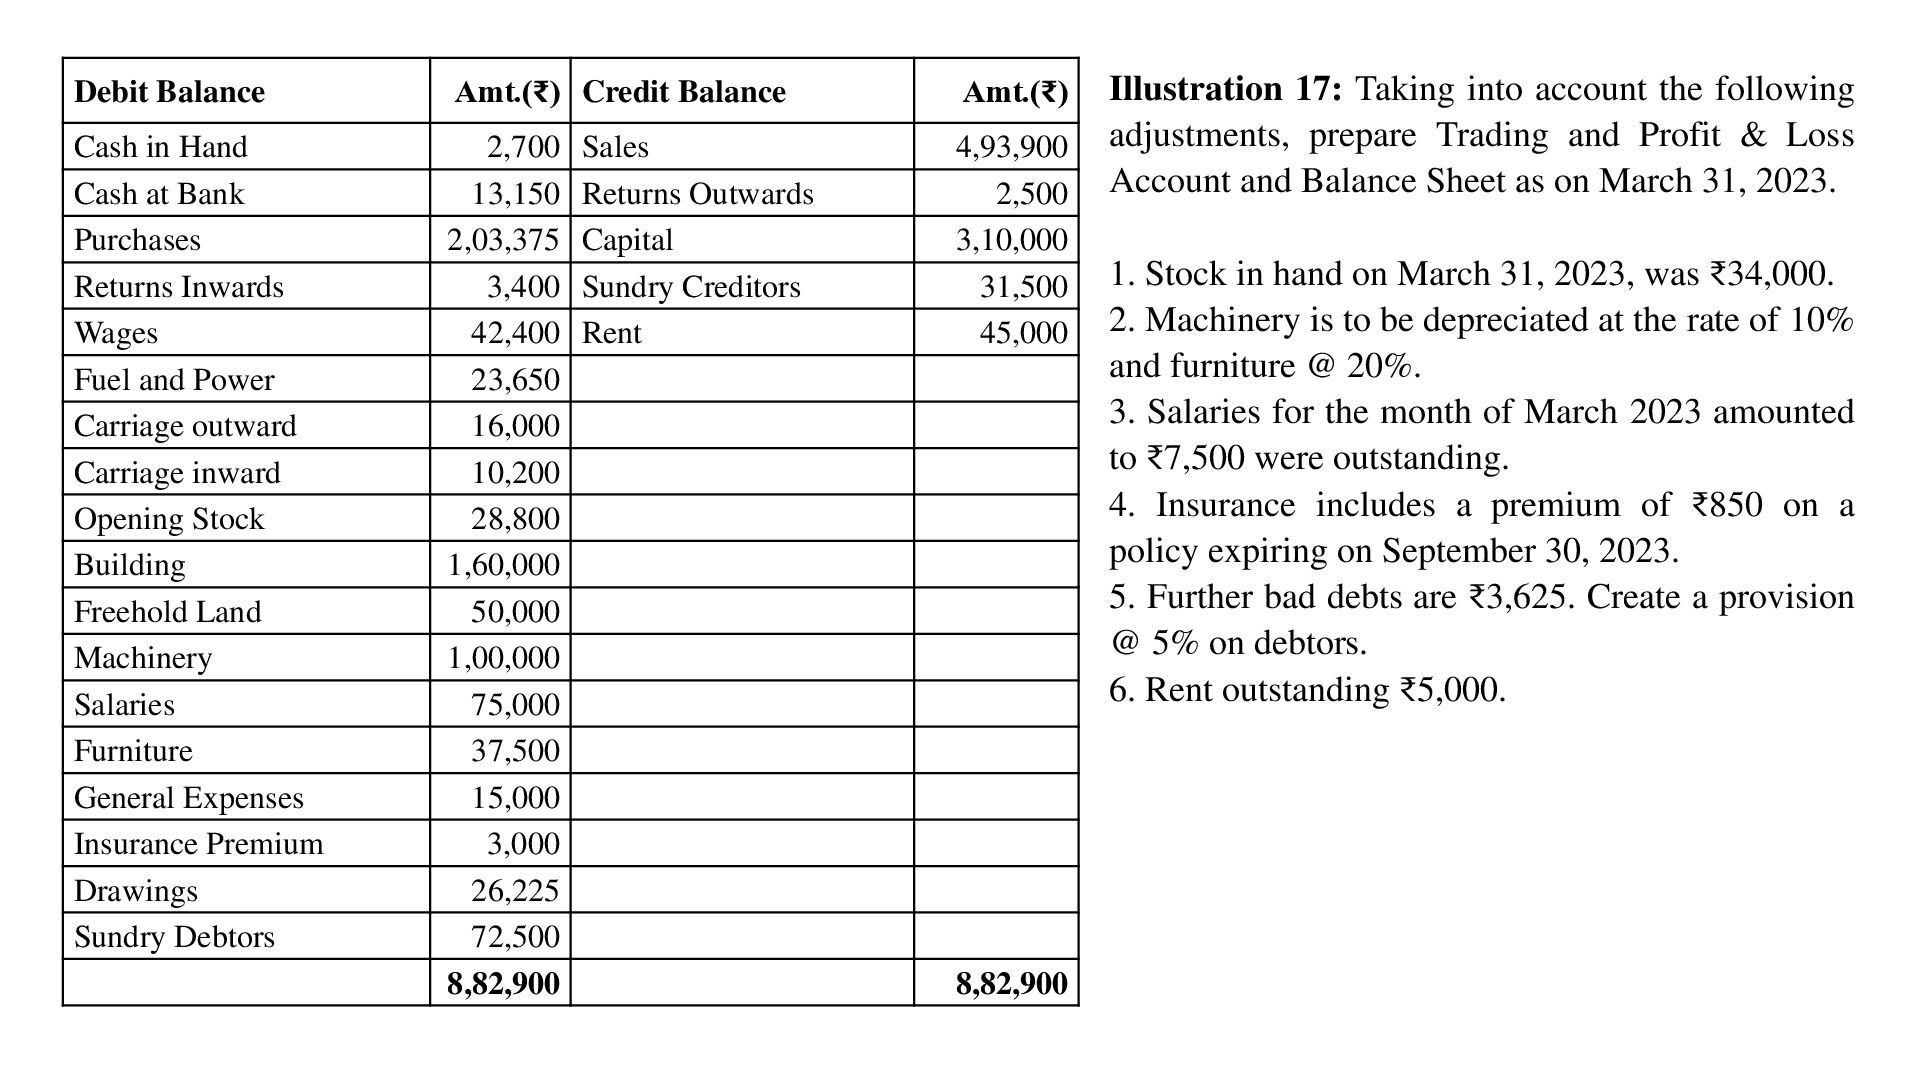
Debit Balance Amt.(₹) Credit Balance Amt.(₹) Cash in Hand Cash
at Bank Purchases Returns Inwards Wages Fuel and Power Carriage outward Carriage inward Opening Stock Building Freehold Land Machinery Salaries Furniture General Expenses Insurance Premium Drawings Sundry Debtors 2,700 Sales 13,150 Returns Outwards 2,03,375 Capital 3,400 Sundry Creditors 42,400 Rent 23,650 16,000 10,200 28,800 1,60,000 50,000 1,00,000 75,000 37,500 15,000 3,000 26,225 72,500 8,82,900 4,93,900 2,500 3,10,000 31,500 45,000 8,82,900 Illustration 17: Taking into account the following adjustments, prepare Trading and Profit & Loss Account and Balance Sheet as on March 31, 2023. 1. Stock in hand on March 31, 2023, was ₹34,000. 2. Machinery is to be depreciated at the rate of 10% and furniture @ 20%. 3. Salaries for the month of March 2023 amounted to ₹7,500 were outstanding. 4. Insurance includes a premium of ₹850 on a policy expiring on September 30, 2023. 5. Further bad debts are ₹3,625. Create a provision @ 5% on debtors. 6. Rent outstanding ₹5,000. -
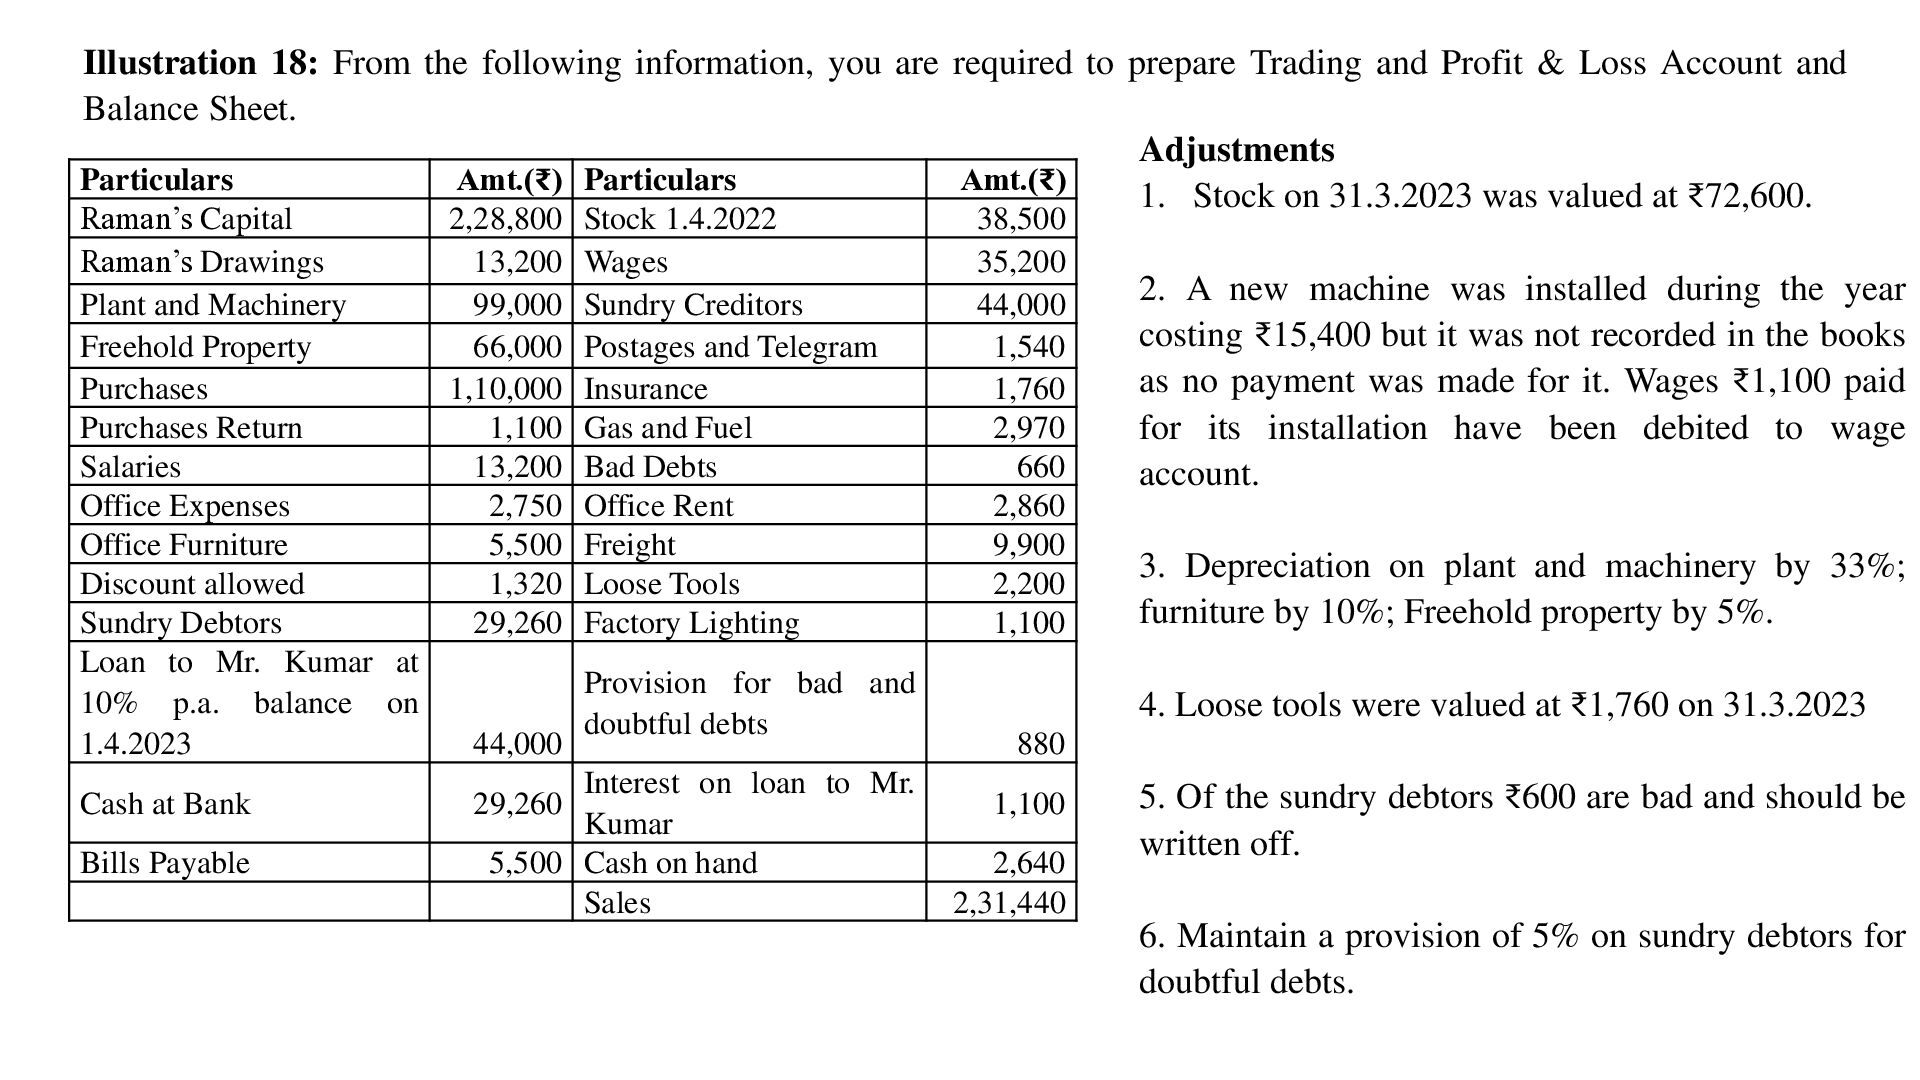
Illustration 18: From the following information, you are required to
prepare Trading and Profit & Loss Account and Balance Sheet. Adjustments Particulars Amt.(₹) Particulars Amt.(₹) 1. Stock on 31.3.2023 was valued at ₹72,600. Raman’s Capital 2,28,800 Stock 1.4.2022 Raman’s Drawings 13,200 Wages Plant and Machinery 99,000 Sundry Creditors Freehold Property 66,000 Postages and Telegram Purchases 1,10,000 Insurance Purchases Return 1,100 Gas and Fuel Salaries 13,200 Bad Debts Office Expenses 2,750 Office Rent Office Furniture 5,500 Freight Discount allowed 1,320 Loose Tools Sundry Debtors 29,260 Factory Lighting Loan to Mr. Kumar at Provision for bad and 10% p.a. balance on doubtful debts 1.4.2023 44,000 Interest on loan to Mr. Cash at Bank 29,260 Kumar Bills Payable 5,500 Cash on hand Sales 38,500 35,200 44,000 1,540 1,760 2,970 660 2,860 9,900 2,200 1,100 2. A new machine was installed during the year costing ₹15,400 but it was not recorded in the books as no payment was made for it. Wages ₹1,100 paid for its installation have been debited to wage account. 3. Depreciation on plant and machinery by 33%; furniture by 10%; Freehold property by 5%. 4. Loose tools were valued at ₹1,760 on 31.3.2023 880 1,100 2,640 2,31,440 5. Of the sundry debtors ₹600 are bad and should be written off. 6. Maintain a provision of 5% on sundry debtors for doubtful debts. -
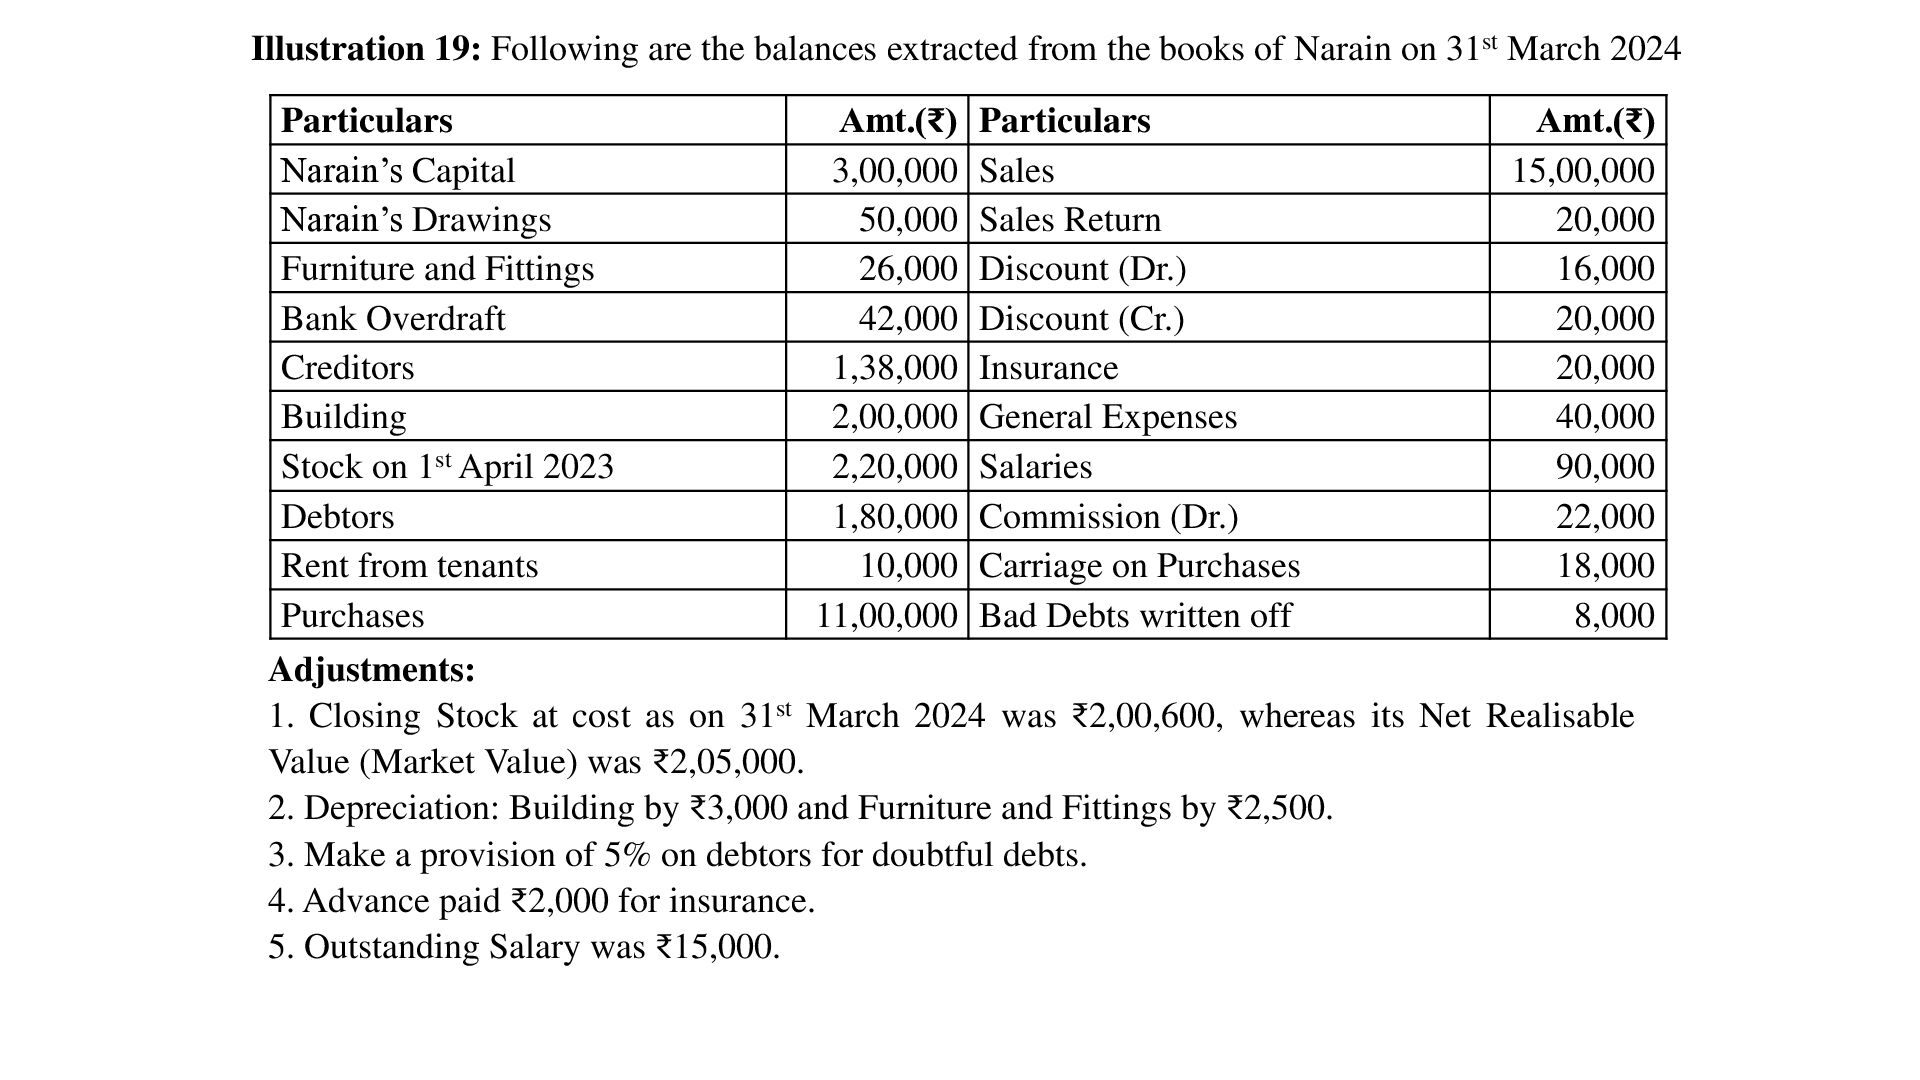
Illustration 19: Following are the balances extracted from the books
of Narain on 31st March 2024 Particulars Amt.(₹) Particulars Amt.(₹) Narain’s Capital 3,00,000 Sales 15,00,000 Narain’s Drawings 50,000 Sales Return 20,000 Furniture and Fittings 26,000 Discount (Dr.) 16,000 Bank Overdraft 42,000 Discount (Cr.) 20,000 Creditors 1,38,000 Insurance 20,000 Building 2,00,000 General Expenses 40,000 Stock on 1st April 2023 2,20,000 Salaries 90,000 Debtors 1,80,000 Commission (Dr.) 22,000 Rent from tenants 10,000 Carriage on Purchases 18,000 Purchases 11,00,000 Bad Debts written off 8,000 Adjustments: 1. Closing Stock at cost as on 31st March 2024 was ₹2,00,600, whereas its Net Realisable Value (Market Value) was ₹2,05,000. 2. Depreciation: Building by ₹3,000 and Furniture and Fittings by ₹2,500. 3. Make a provision of 5% on debtors for doubtful debts. 4. Advance paid ₹2,000 for insurance. 5. Outstanding Salary was ₹15,000.
 bvr7352
 ainischool
 signer
 bernhardsvt
 hiola
 cbtlibrary
 baltimoreniso
 akiraasano
 tammyeverts
 inesmontani
 techseoconnect
 denniskardys
 marketingsoph
 soudai
 eileencodes
 jnunemaker
 thirion
 katiecoart
 nikkihalliwell