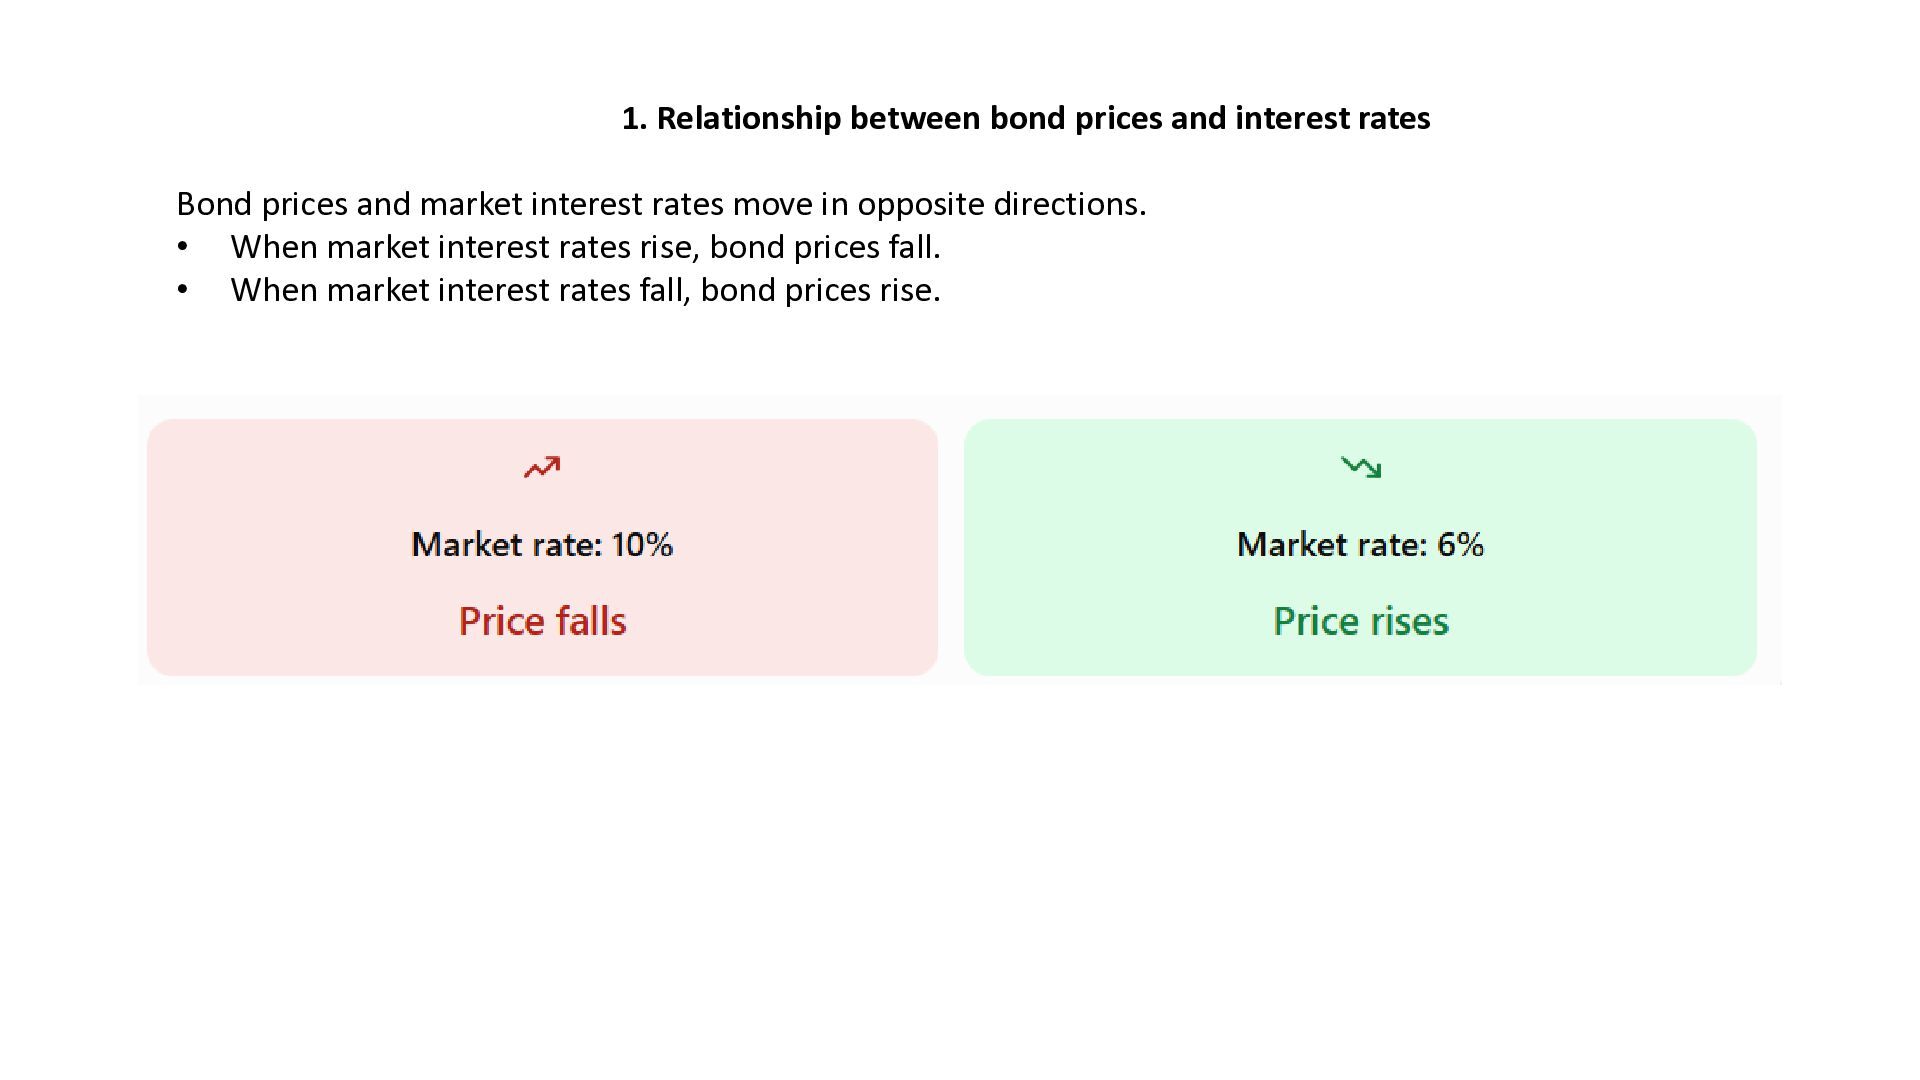
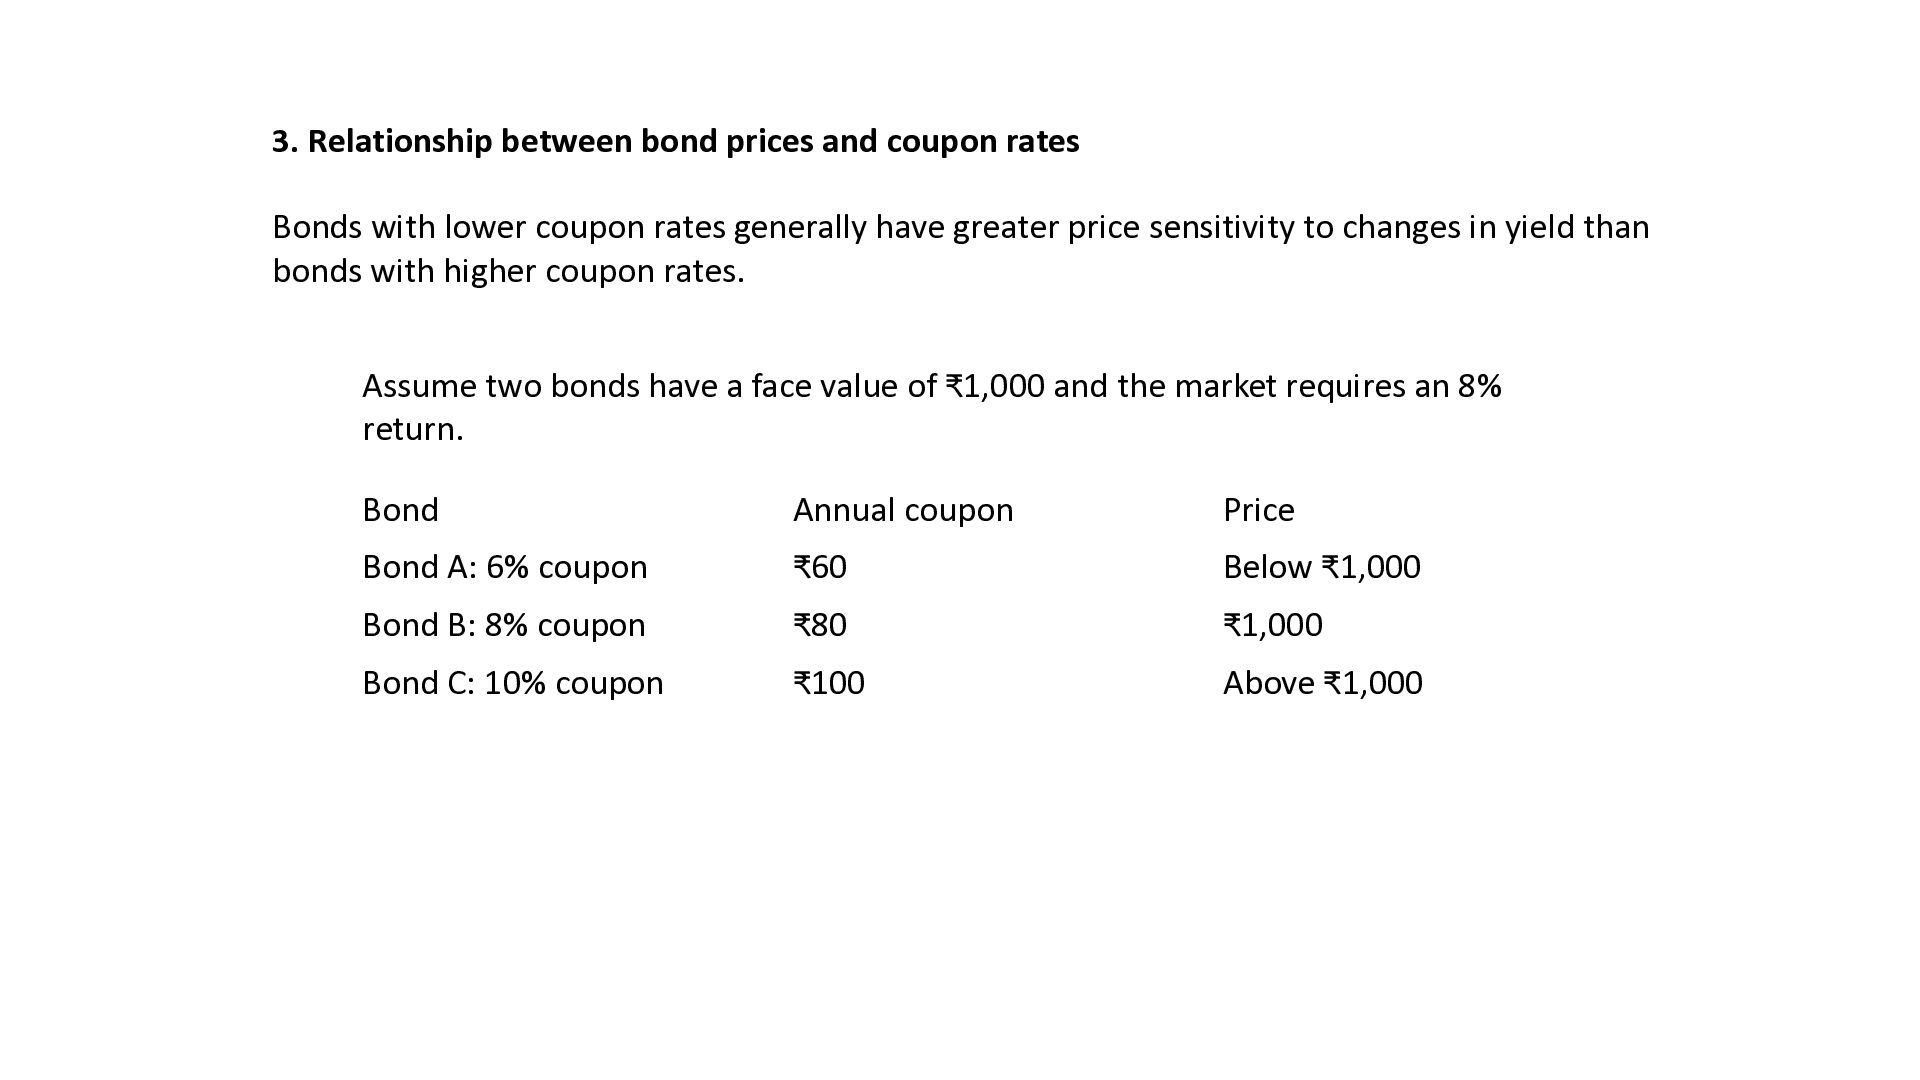and market interest rates move in opposite directions. • When market interest rates rise, bond prices fall. • When market interest rates fall, bond prices rise.
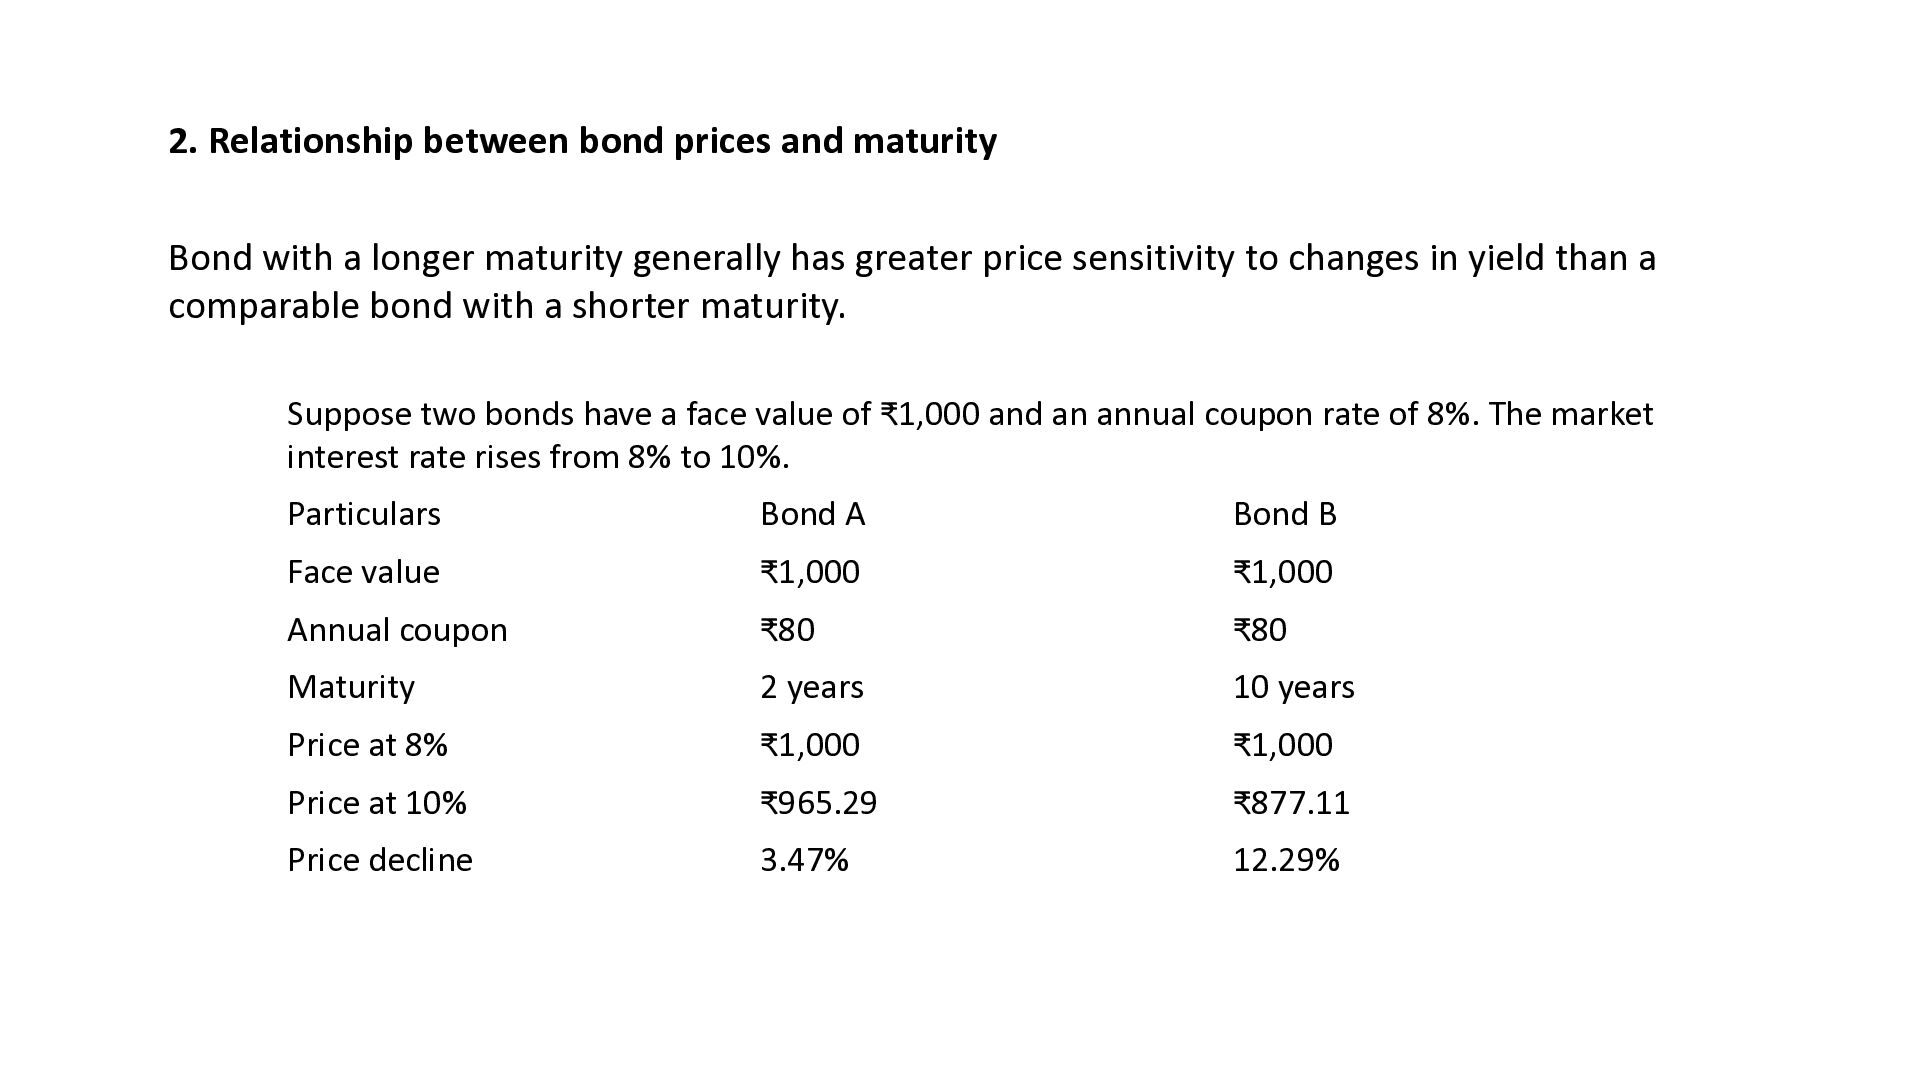
longer maturity generally has greater price sensitivity to changes in yield than a comparable bond with a shorter maturity. Suppose two bonds have a face value of ₹1,000 and an annual coupon rate of 8%. The market interest rate rises from 8% to 10%. Particulars Bond A Bond B Face value ₹1,000 ₹1,000 Annual coupon ₹80 ₹80 Maturity 2 years 10 years Price at 8% ₹1,000 ₹1,000 Price at 10% ₹965.29 ₹877.11 Price decline 3.47% 12.29%
lower coupon rates generally have greater price sensitivity to changes in yield than bonds with higher coupon rates. Assume two bonds have a face value of ₹1,000 and the market requires an 8% return. Bond Annual coupon Price Bond A: 6% coupon ₹60 Below ₹1,000 Bond B: 8% coupon ₹80 ₹1,000 Bond C: 10% coupon ₹100 Above ₹1,000
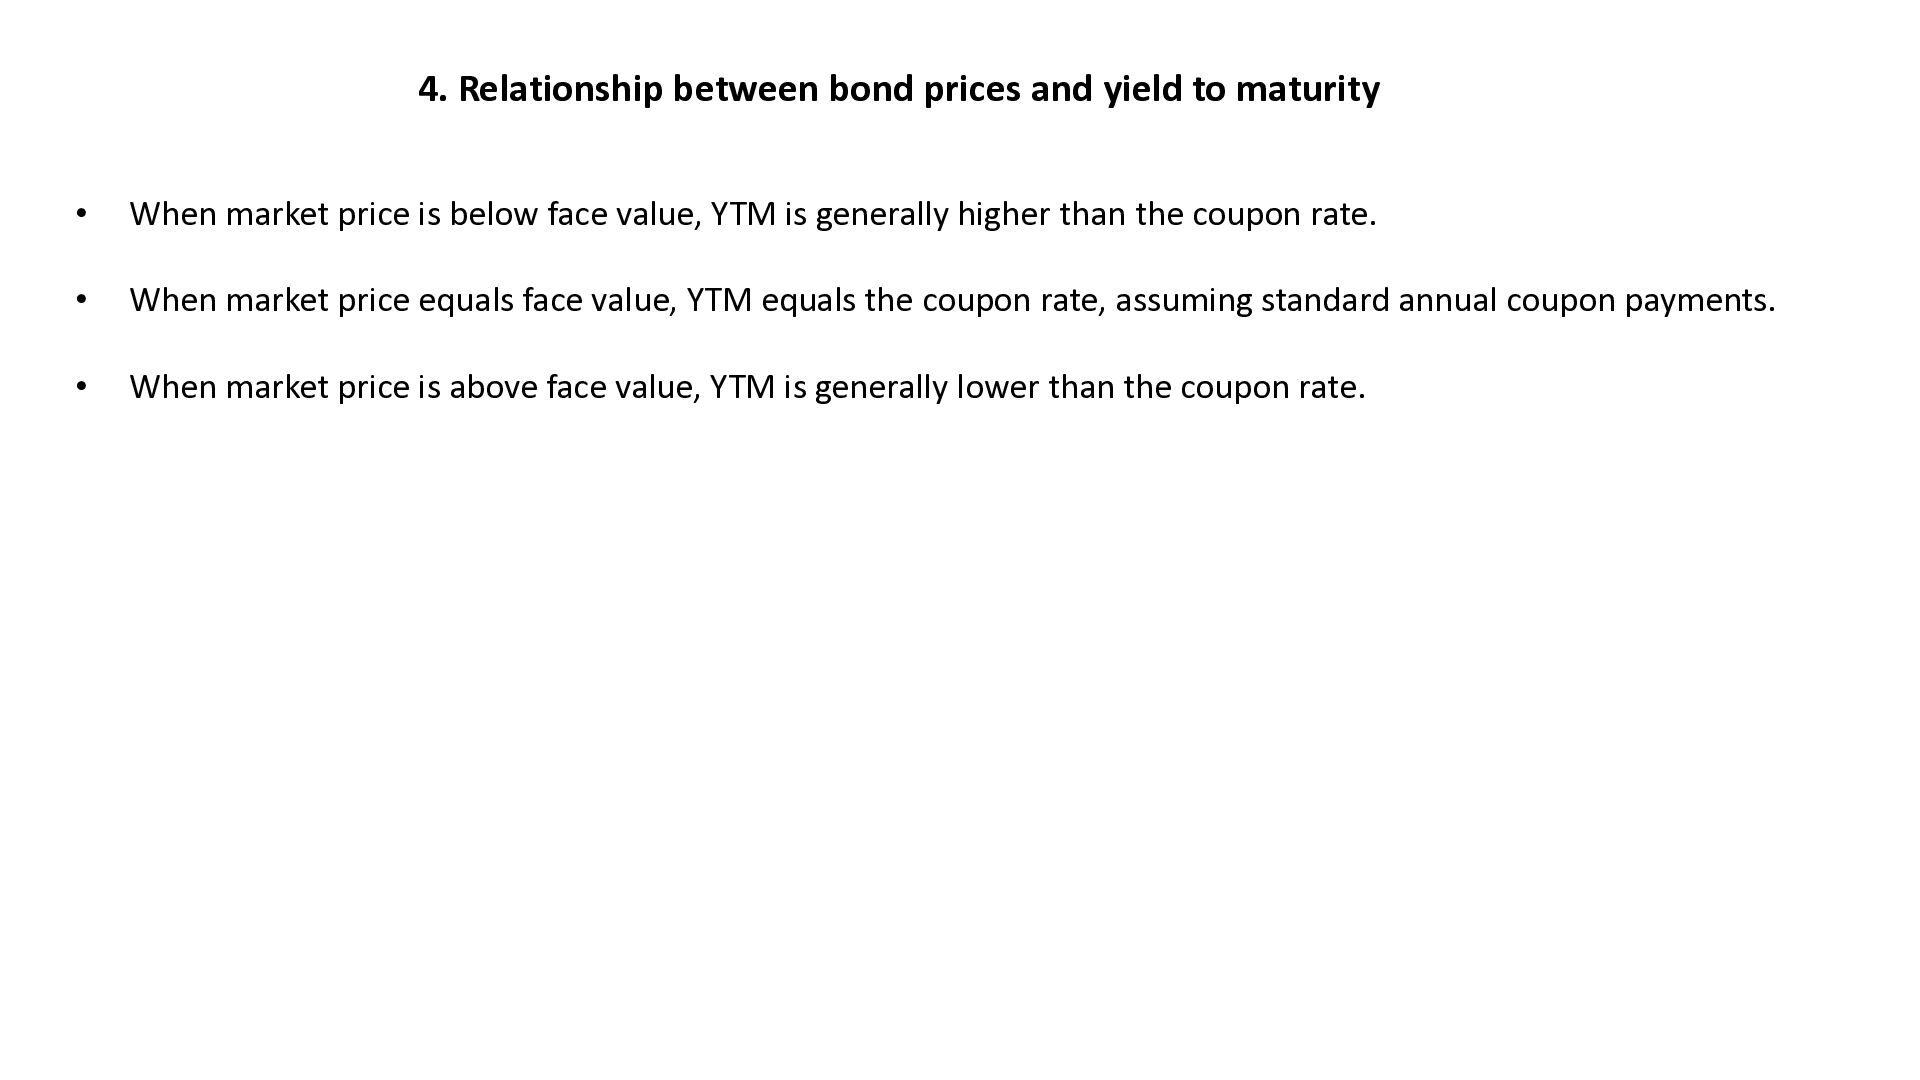
When market price is below face value, YTM is generally higher than the coupon rate. • When market price equals face value, YTM equals the coupon rate, assuming standard annual coupon payments. • When market price is above face value, YTM is generally lower than the coupon rate.
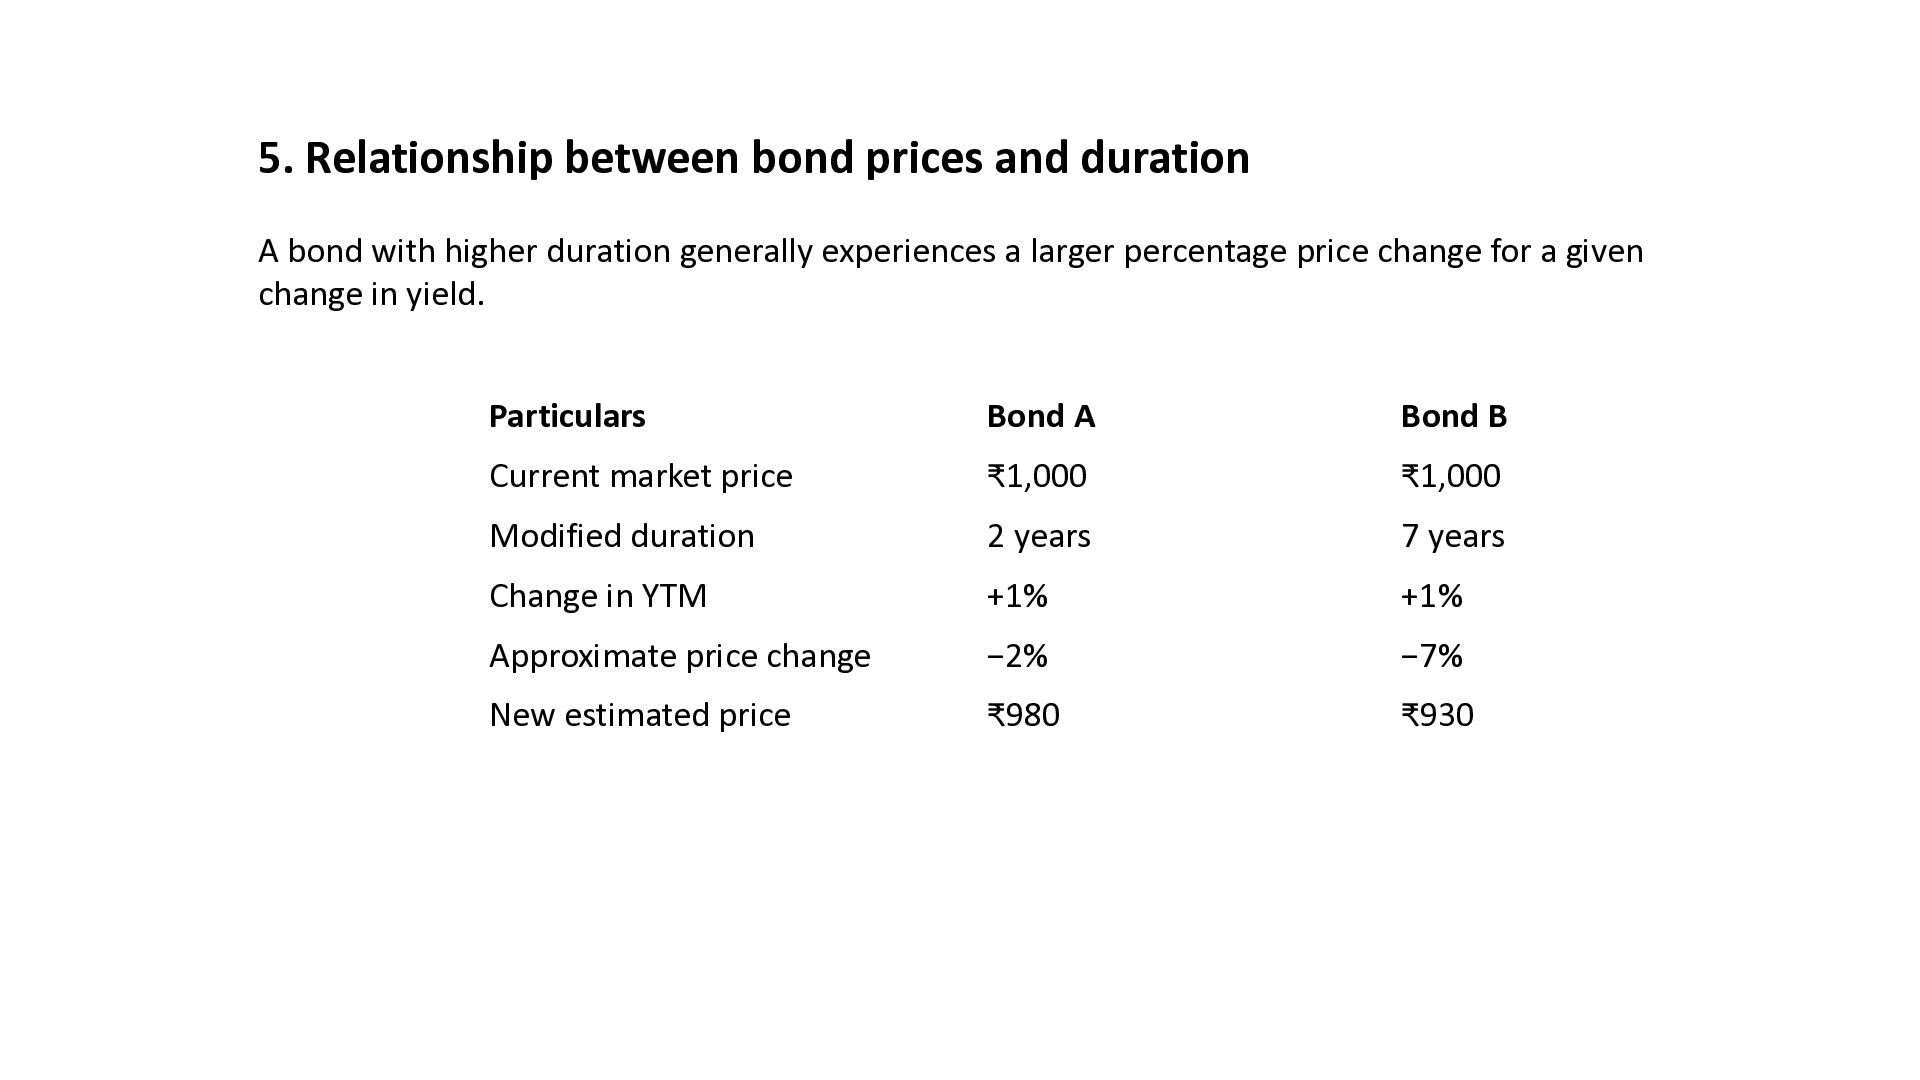
higher duration generally experiences a larger percentage price change for a given change in yield. Particulars Bond A Bond B Current market price ₹1,000 ₹1,000 Modified duration 2 years 7 years Change in YTM +1% +1% Approximate price change −2% −7% New estimated price ₹980 ₹930


 bvr7352
 akiraasano
 matleenalaakso
 pfn
 signer
 cbtlibrary
 baltimoreniso
 rashwhitman
 minorun365
 kaityo256
 gmoriki
 ks91
 jnunemaker
 oripsolob
 bkeepers
 livdayseo
 nonsquared
 reverentgeek
 andyhume
 baasie
 techseoconnect
 marketingsoph
 danielanewman