Upgrade to Pro
— share decks privately, control downloads, hide ads and more …
Speaker Deck
Sign up for free
Menu
Search
Features
All features
Private URLs
Password Protection
Custom URLS
Scheduled publishing
Remove Branding
Restrict embedding
Deck Collections
Notes
Features
All features
Private URLs
Password Protection
Custom URLS
Scheduled publishing
Remove Branding
Restrict embedding
Deck Collections
Notes
Explore
Featured decks
Featured speakers
Programming
Technology
Storyboards
Explore
Featured decks
Featured speakers
Programming
Technology
Storyboards
Pricing
Search
Sign in
Sign up for free
Startupbootcamp - State Of Tech 2015
Search
SBCAmsterdam
November 05, 2015
Business
320
0
Share
Embed
Copy iframe code
Copy JS code
Copy link
Start on current slide
Startupbootcamp - State Of Tech 2015
SBCAmsterdam
November 05, 2015
Other Decks in Business
See All in Business
AIと働く実践 Agentがあなたの生産性を上げてくれない理由
ozakiomumkj
0
170
AI立国論(2026年9月)
noritaka88tax
0
220
向山純平 メニュー表 / Junpei Mukouyama – Professional Services
mj6237
3
330
コーポレートストーリー(新規投資家様向け会社説明資料)
gatechnologies
2
21k
uniam_事業概要.pdf
uniam
PRO
0
1k
事業計画及び成長可能性に関する事項
kuradashi
0
2k
株式会社レボルト採用deck
takemura_yuto
0
540
株式会社kanaL|会社紹介資料(Company Deck 2026)
tamagakiyuya
0
160
freeeの福利厚生と働き方
freee
PRO
1
110k
Podpora KOVY | 24. 9. 2026
ggfs
PRO
0
430
シナジーマーケティング株式会社 採用ピッチ資料
synergymarketing
1
68k
変化の時代に自分のハンドルを握る ── イチから始めるセルフマネジメント/Self-Management in the Winds of Change
ikuodanaka
2
290
Featured
See All Featured
Build The Right Thing And Hit Your Dates
maggiecrowley
39
3.5k
The untapped power of vector embeddings
frankvandijk
2
1.9k
Sam Torres - BigQuery for SEOs
techseoconnect
PRO
0
580
RailsConf 2023
tenderlove
30
1.6k
Technical Leadership for Architectural Decision Making
baasie
3
600
Crafting Experiences
bethany
1
380
First, design no harm
axbom
PRO
2
1.3k
Odyssey Design
rkendrick25
PRO
2
870
How GitHub (no longer) Works
holman
316
150k
Art, The Web, and Tiny UX
lynnandtonic
304
22k
Thoughts on Productivity
jonyablonski
76
5.4k
Lightning Talk: Beautiful Slides for Beginners
inesmontani
PRO
2
730
Transcript
None
In 5 years the tech industry will grow from $500
billion to 2.2 trillion.
Startupbootcamp is the world’s global accelerator, operating 13 programs in
11 cities
We built global vertical innovation systems. Startups and corporates are
our clients
Innoleaps is the world’s first accelerator for corporates
State Of Tech Resources • 13000 Startupbootcamp applications • Startups
we’re sourcing, tracking and tracing • 150 partners, 2000 mentors and own team of 300 • Startupbootcamp Verticals reports • Partners reports (PWC)
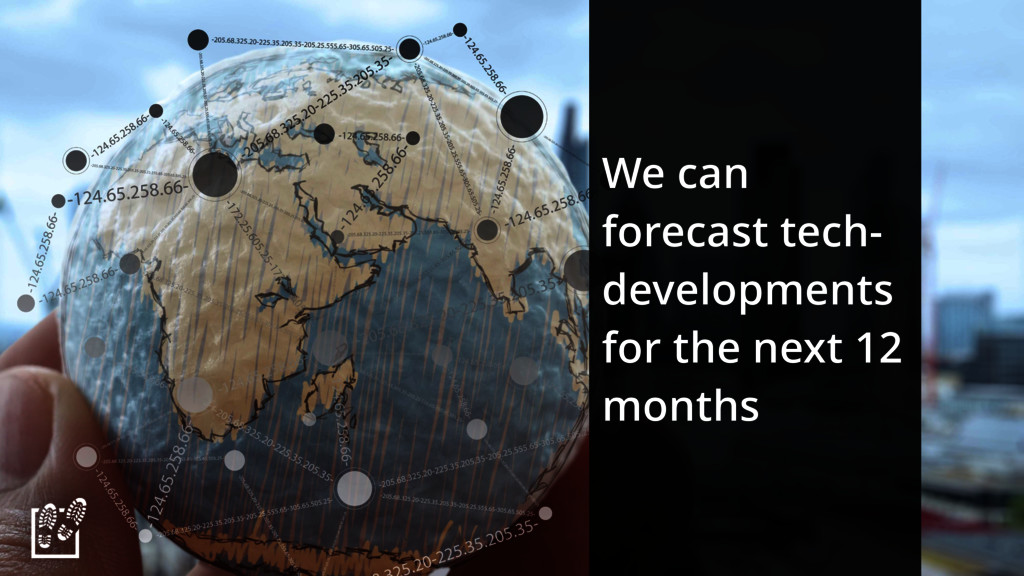
We can forecast tech- developments for the next 12 months
7.2 billion people, growing older. There will be more of
us
Global population aged 60+ years 2015: 901 million 2030: 1.4
billion 2050: 2.1 billion 2100: 3.2 billion
But Millennials are steering developments
•Access instead of ownership •Technology savvy •Emphasis on general wellness
(Health, Food) •Flexible workplaces
2016: Nearly 70 percent of sharing- economy workers are between
18 and 34
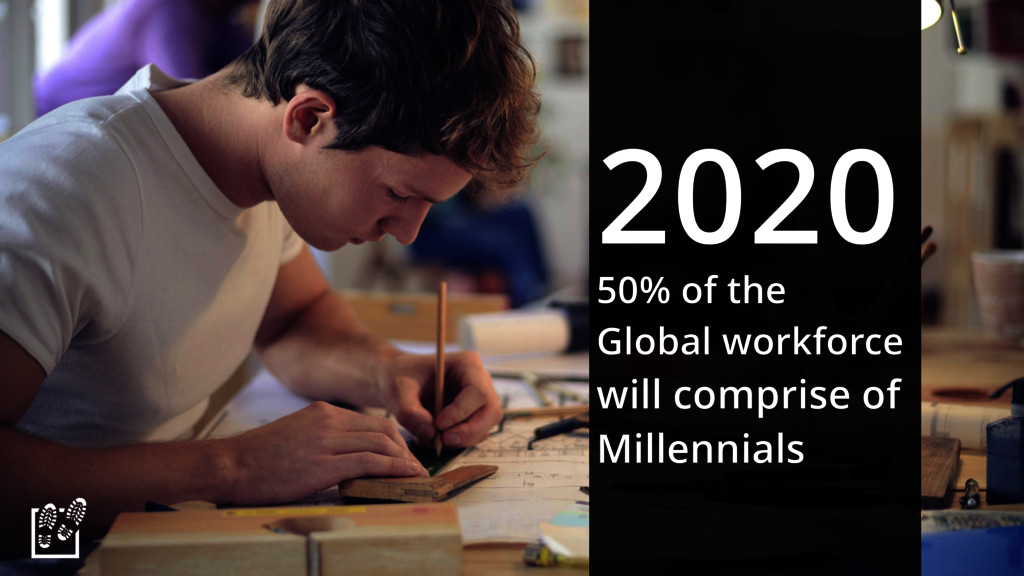
2020 50% of the Global workforce will comprise of Millennials
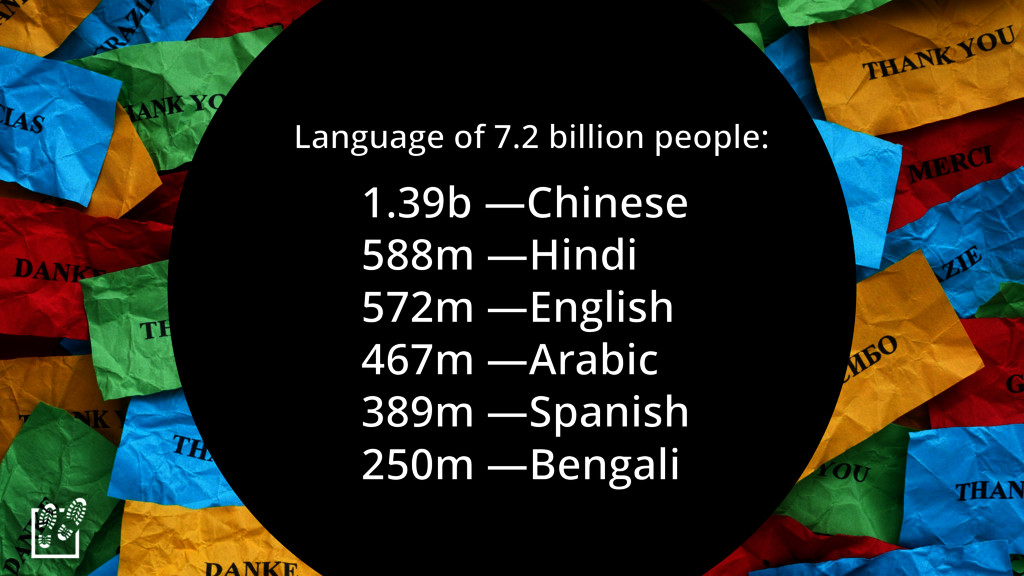
Language of 7.2 billion people: 1.39b —Chinese 588m —Hindi 572m
—English 467m —Arabic 389m —Spanish 250m —Bengali
One day we’ll all speak tech!
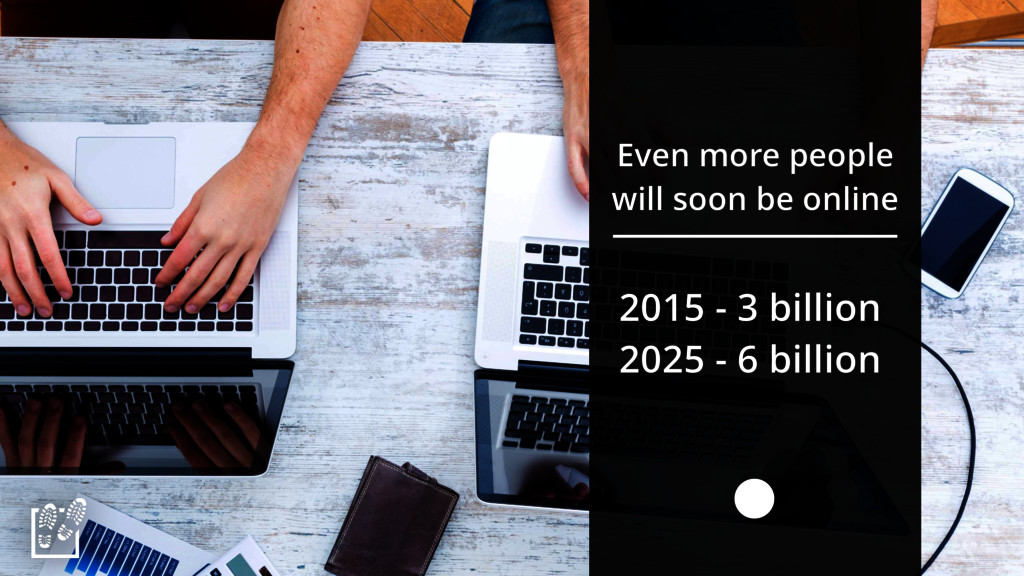
Even more people will soon be online 2015 - 3
billion 2025 - 6 billion
Mobile continues to grow rapidly
- Greater availability of smartphones - Better network coverage -
Mobile extending beyond developed markets
2014 - 3.6 billion unique owners 2020 - 4.6 billion
unique owners (60%)
2020 70% broadband 80% of global population within 3G reach
• Skype, WhatsApp, Facebook Messenger increasingly popular • More traction
with growth of 4G networks Picture: Twin Design / shutterstock.com
• Telcos need partnerships or over-the-top models to drive long
term revenues • All IP future solution is vital to retain customer relevance
4G networks becoming dominant in developed world
2014 - 3G 39% 2020 - 4G 69%
2020 - 5.9 billion smartphones 2020 - DATA traffic will
have grown tenfold from 2014
• Video the key driver • YouTube: Mobile now generates
50% of its global traffic • Netflix: takes 50% of all prime time US broadband capacity Picture: Alexey Boldin / shutterstock.com
5G already is being tested
•1000 times faster then 4G •Realtime-apps: autonomous driving, VR, AR
and high-res video
•South Korea: launch in 2020 •KPN, TNO, Huawei and Ericsson
now testing in Loppersum, Netherlands
However mobile internet penetration is still pretty limited
• Brings fintech to unbanked populations • Now over 255
live services across 89 countries
The Internet Of Everything Is Really Hot
•Digital ‘nervous system’ for interactions between people and machines •Creating
new kinds of applications and services
• Key to Smart Cities • Only just reached the
public consciousness
Number of ‘connected things’ in 2020: •PWC: 8 billion •Cisco:
50 billion
1 million new #IoT devices will be purchased every hour
of every day in 2021
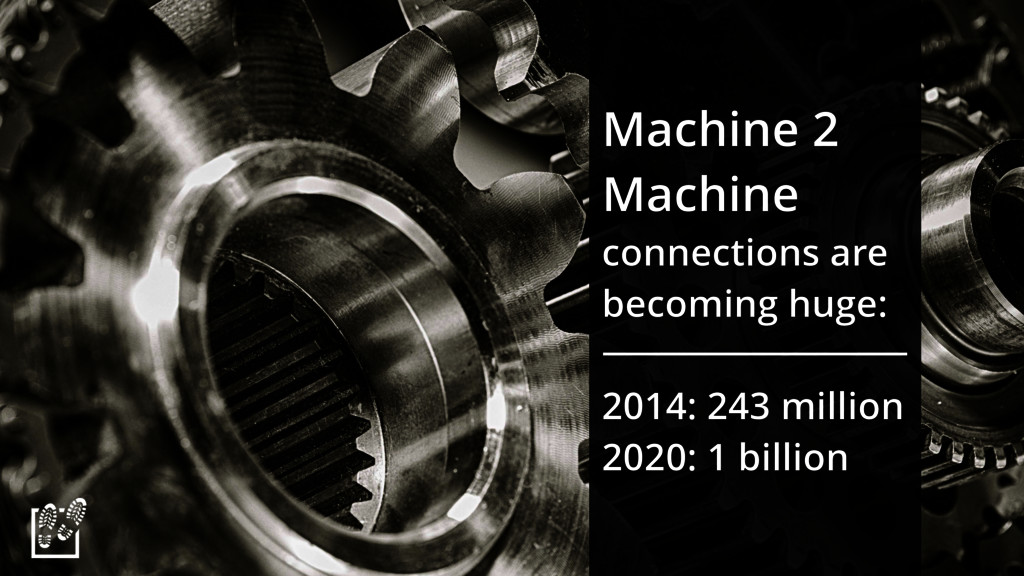
Machine 2 Machine connections are becoming huge: 2014: 243 million
2020: 1 billion
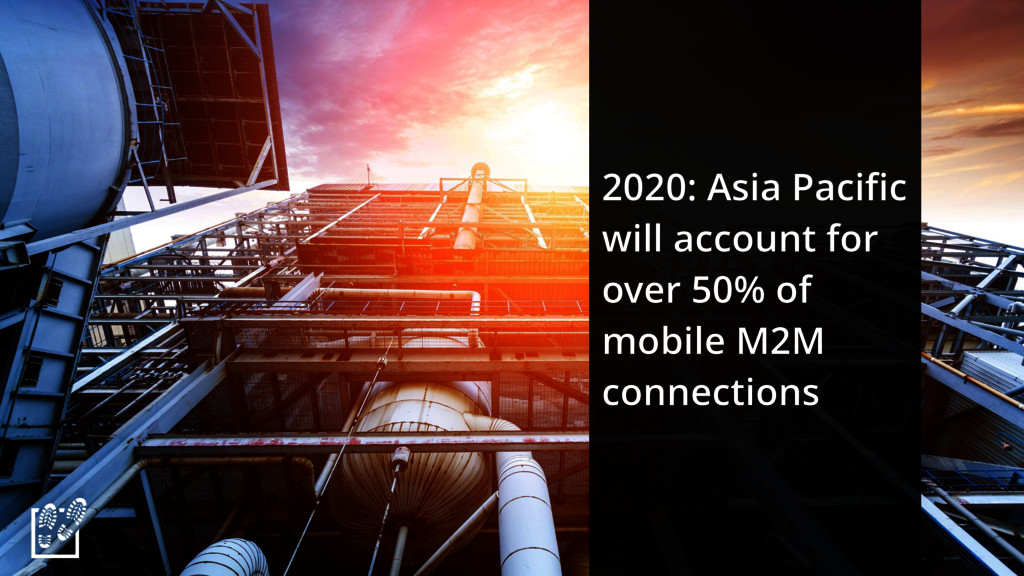
2020: Asia Pacific will account for over 50% of mobile
M2M connections
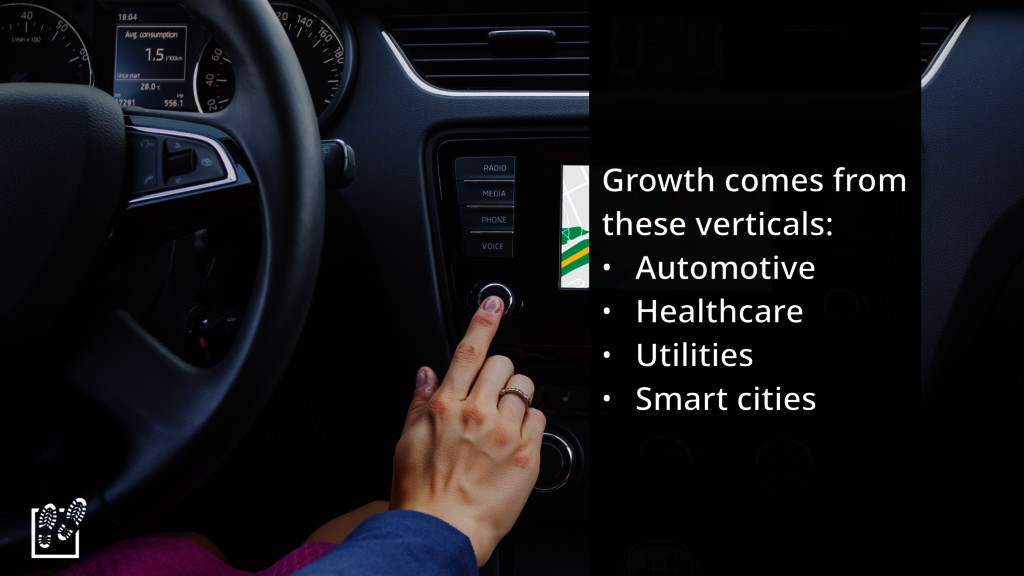
Growth comes from these verticals: • Automotive • Healthcare •
Utilities • Smart cities
Growth factors: • Low power network roll-out • Increased standardisation
• Improved regulation • Greater assurance of end-to-end security
Wearables have only just taken off
35% annual growth over the next 5 years: • 2015
- 33 million • 2019 - 148 million Editorial Credit: Giuseppe Costantino / shutterstock.com
• People don't understand the benefits yet • Small screen
• Limited battery life • No "killer app" yet Editorial Credit: Hattanas / shutterstock.com
• Still we are anticipating increased use • Especially for
fintech and enterprise purposes
• Smartwatch will be the leading wearable • 40% Apple
watch Editorial Credit: Canadapanda / Shutterstock.com
• Will grow 41% p/y over the next 5 years
• Must become standalone device to become mainstream Editorial Credit: Lukas Gojda / shutterstock.com
• Wearable tech drives IOT and Health startups • Not
yet dominant in 2016
Apple and Google will dominate,just like in the smartphone and
tablet markets. Editorial Credit: robert cicchetti / shutterstock.com
Cybersecurity: The hottest and fastest growing tech sector
• 2015: $77 billion • 2020: $170 billion • Corporate
investors are major funding sources for cybersecurity startups.
The U.S. spent $100 billion on cybersecurity over the past
decade $14 billion budgeted in 2016
• Cyber-attacks costing $400 to $500 billion a year. •
Cyber insurance market has grown from $1 billion to $2.5 billion in two years.
• Expected to grow dramatically over the next 5 years
• Creating new opportunities
• 50% of all present jobs will disappear • Over
200,000 U.S. cybersecurity jobs are unfilled. 2019: 1.5 million
Security services market will grow from $8 billion to $30
billion by 2020
The mobile security market is exploding
The average Android phone only gets 1.26 updates per year
- 86% of people leave a website when asked to
register - 40% using "forgot password" once a month - 78% don’t trust companies with their data
IoT market is expected to further lift security spending through
2025
Driven by Drones, Health wearables, Self driving cars, Digital banking
3D-printing At a tipping point, about to change industries
Economic impact of up to $550 billion a year by
2025
• Capabilities of hardware evolving rapidly • Larger components, greater
precision, finer resolution • Higher speeds, lower costs. • Viable alternative to conventional manufacturing
Driven by smart materials
• Quality of materials improves rapidly • Will soon be
suitable and used • More industries will start 3D-printing: Space, Healthcare, Automotives, Energy and the Army
Low cost of market entry makes it easier to begin
manufacturing
3-D printed firearms shows the potential to create ethical dilemmas
and to disrupt industries
The sharing economy grows
•Raised 8 billion since 2009 •World’s most valuable private startup
•300 cities in 63 countries •Spends $35 million per week Editorial Credit: Prathan Chorruangsak / shutterstock.com
•Investing heavily in ride-sharing service Uber Pool •30% of trips
now take place in China •But Didi Kuaidi is the most popular ride-hailing app in China
• Extra income, reciprocity, social interaction • Easy to join
and make a profit. • Nearly 70% of ‘sharing’ workers 18 to 34 years • 40% have a college degree
IOT becomes the Internet of Shared Things
•Millennials paving the way •Sharing more then others •Lower prices,
Higher demand for work
Fighting Rules and regulations
• Startups use loopholes above legitimate business models • Face
stricter rules than providers working in other businesses. • Governments will create laws to protect customers.
As a result real sector leaders are emerging
• More online comparison marketplaces popping up • Quality based
on ratings • Consolidation of the sharing market is near
Sharing platforms will gain even more popularity and redefine aspects
of economies.
Smart City & Living
Cities getting smarter driven by IoT and Big Data
• Safer living environments • Less pollution • Less traffic
congestion • Real time service networks
Autonomous driving
Ninety percent of car accidents are caused by human error
Increased safety, road capacity, fuel efficiency and reduced pollution
• Fastest growing field in automotive • Requires the most
complex coding that car-makers ever faced • Correct software integration paramount for safety
Risks • System failures (“death by computer”) • Cyberterrorism •
Users taking additional risks when they feel safer. • Increased travelling resulting from faster or cheaper cars
2025 • 15–20% of cars using highly autonomous driving •
Truly autonomous driving is likely to be below 5%.
Future: • 2030 - Implementation for taxis and car sharing
• 2040 - Dedicating some highway lanes • 2050 - Change roadway design and management practices • 2060 - Restrict human- driving
• Key tech players involved, Google, Apple, Uber, Tesla •
Incumbents struggling to catch up
Legislation bigger hurdle than technology
The drone invasion is underway
Consumers looking for instant gratification
• Months away from being ready • 10 times cheaper
and faster than any alternative • Ideal for less developed countries
• Biggest enemy: weather • Regulatory framework in the US
appears to have stalled • Amazon & Google: pushing hard
• 2020: $140 billion market • 56% US, 12% China
• Google’s “Project Wing", deliver items within 5 miles in
5 minutes • Google’s Adwords fear: Amazon to capture all searches with commercial intent
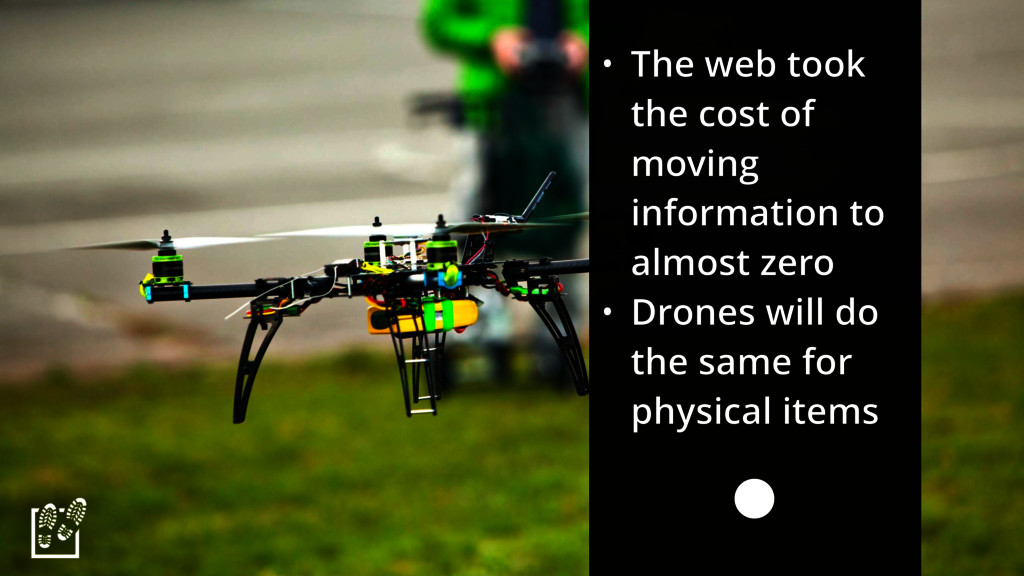
• The web took the cost of moving information to
almost zero • Drones will do the same for physical items
E-commerce
Trends • Last Mile • Hyper Local • City Sensors
• Open Data
November 2015: 51% of all internet usage is now mobile
Mobile is at the heart of future E-commerce
The B2C e-commerce market is becoming more and more mature
• 2015 growth rate: 15.9% • Global B2C e-commerce turnover
$2,3bn
E-Commerce Is The Future Of Retail:
• Marketplaces doing well (convenience) • Hybrid shopping looks promising
• Those that focus on only one channel will be less successful
Shoppers are changing...
• But key aspects of shopping remain the same •
Social activity, particularly for the younger age group
• People expect a high level of security for their
personal data. • But still want individualized offers
Shoppers have high expectations
• Seamless cross- channel experience • Convenience, very demanding in
a complex environment
Logistics, Huge need for new supply chain
• Same-day delivery means new air freight facilities will be
needed • Fulfilment centres will be built next to airports
This will change the landscape around them
• From mega distribution facilities to smaller fulfilment centres •
Package pick-up options covering the last mile
FinTech
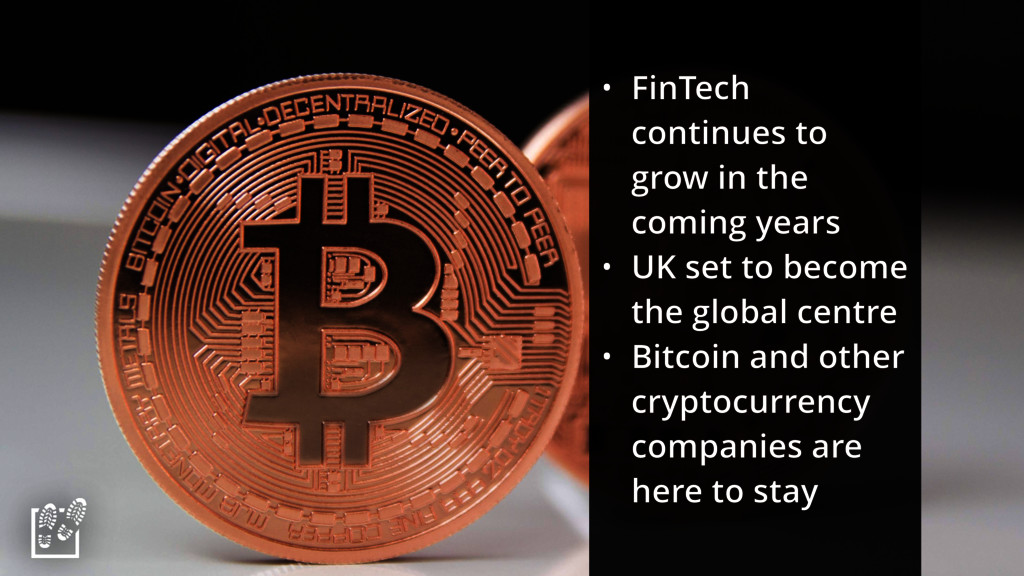
• FinTech continues to grow in the coming years •
UK set to become the global centre • Bitcoin and other cryptocurrency companies are here to stay
• Traditional financial institutions seriously interested • Increasingly making R&D
investments
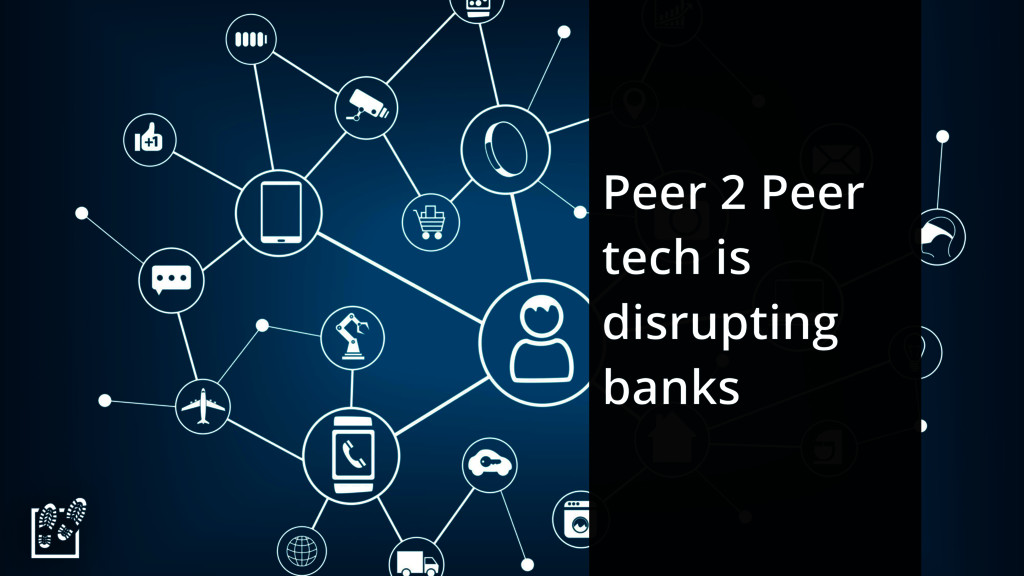
Peer 2 Peer tech is disrupting banks
• Big surge in P2P lending • Startups growing fast,
landing large deals
• Alternative payment methods grow at an incredible rate •
Crowdfunding still small but here to stay
Wealth Management moves into a new era
• Big shift in mindset • More attention and power
to the small investor
• Wealth management startups becoming prominent • Giving clients the
same opportunities as large investors.
Automated Investment Management will soon be normal
• Large increase in development and use of platforms •
More services for high-net worth individuals
• New startups offering these services for large portfolios •
Cutting out the middleman
Western banks are weakening
• Need for cost reduction • Startup disruption • Coping
with digitisation, don’t understand the new role of business platforms
• Believe that “digital” is somehow a solution-set • Global
economic change switching the balance away from North- South to South- South
Leadership: Too much orientation towards product instead of process innovation
• Leaders are very slow to develop a vision for
the next 10 or 20 years • Urgent need to host an inter- generational dialogue
• Need a deeper understanding of new operating models •
Need to truly engage employees into improve processes
• Have begun to embark on fail fast, fail cheap
innovation methods • But too often this is divorced from executive decision making
FinTech & Security in 2016
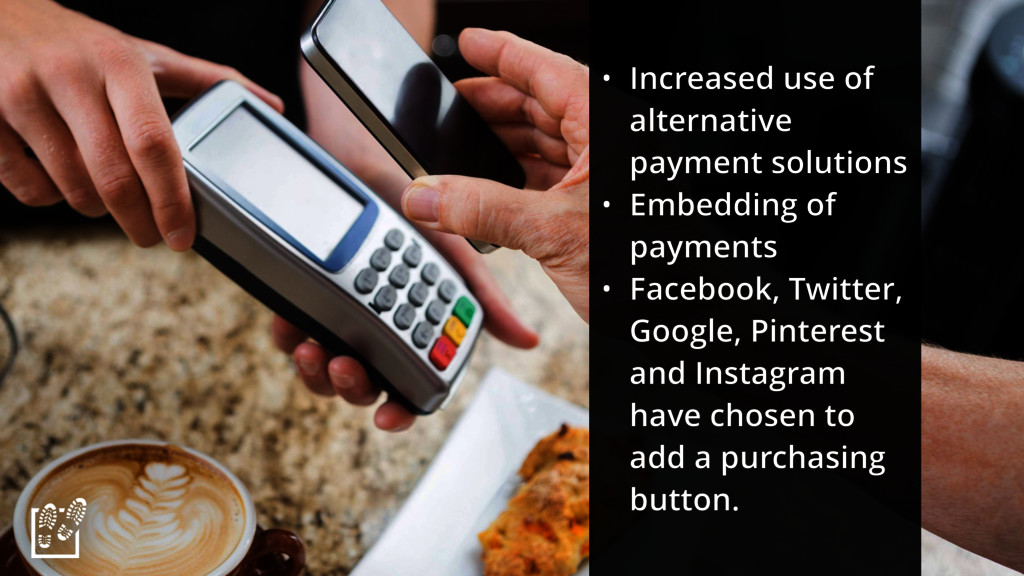
• Increased use of alternative payment solutions • Embedding of
payments • Facebook, Twitter, Google, Pinterest and Instagram have chosen to add a purchasing button.
Large incumbents continue to the biggest acquirers of new FinTech
startups.
Insurance, the Next Frontier for Fintech
• Regulations were designed for a different era • But
where are the insurance tech entrepreneurs?
• Capital requirements very steep for startups • Large insurers
will gobble up insurance tech startups • Driving more venture capital into the space
Now software Is eating Insurance
By changing the way insurance companies price risk
•By empowering an ongoing relationship between an insurer and insured
•Letting you make smart lifestyle decisions.
The sharing economy needs new insurance products that are pay-per-
use, not pay- per-year
• We’ll see more crowdsourced insurance companies • Changing the
way insurance companies pool capital
• Big Data easier measures risk and locate stolen goods
• Risk shifts away from individuals and traditional companies to software providers
Insurance also goes mobile
• Industry appears to have found the right partnership and
commercial models. • Total of 100 live services mobile insurance services now operating • Over 20 million policies already been issued
Digital Health • Four of the last 5 quarters have
seen more than $200M in digital health financing
Apps are becoming a regular part of care
Healthy food, weight loss, exercise, education and information
• Healthcare widely deploying mobile apps – but difficult to
engage patients • 33% already offer apps • Lack of funding main barrier for effective use
Top 5 digital health categories
• Cost transparency • Big data analytics • Wearables
• Real-time healthcare • Personal medicine and information
Social Media Picture: Twin Design / shutterstock.com
Messaging services are becoming more powerful than social media
Picture: Twin Design / shutterstock.com • What’s App and Facebook
Messenger, clear global leaders • Others dominate locally • Messaging services are becoming platforms
Snapchat • Growing fast, 200 million users • Key driver
for vertical video usage • Vertical viewing time 2010: 5% 2015: 29%
• Full-Screen Vertical Video Ads on Snapchat = 9x Higher
Completion Rate vs. Horizontal • But no proven business model yet
Slack Real Time messaging with co-workers
• Rapidly becoming #1 in company communication tool • Unprecedented
user growth. 1.2 million daily users after 15 months
• 370K paid accounts • Unicorn after only 8 months
• Making real money, Truly global
ChatWork • Founded in 2011 • Biggest in Asia •
70% market share in Japan • Now spreading in the U.S • 80,000 client companies
Media
• Revenues will rise 5.1% (CAGR) over the coming five
years • 2014: $1.74 • 2019: US$2.23trn
• Non-digital will still contribute well over 80% of global
consumer revenues in 2019 • But new products expand the number of multitasking moments
Consumers call the shots
• Content experience trumps delivery platforms • Empowered consumers seek
inspiring content transcending platforms
Streaming audio
• Growing fast but radio is still dominant • You
Tube (53%), Spotify are leading, Apple catching up
• Subscriber loyalty is a major cause of concern •
Smart curation through algorithms and social sharing is a key issue
2020 Digital music services revenues: 10 billion (50% streaming)
Cable and TV are ripe for disruption
• TV has reached its tipping point • Situation is
comparable to print in 2005
• Netflix and You Tube grabbing traditional viewers • TV
ad spending decreasing, online spending on its way up Picture: Twin Design / shutterstock.com
Video on Demand
• Complementary media form, driven by millennials • A truly
on demand generation. • 33 % watches more VOD than traditional TV
• 1 in 4 users watches VOD daily • 5%
of users doesn’t have a standard TV service at all
Accelerators, We foresee a shake out • 2010 - 10
serious players • 2015 - 1500 accelerators
• Only global players will survive • Business model will
change • Startupbootcamp leads trend towards global verticals
• Increasing level of interest from corporates • Corporates creating
in- house accelerators
UNBUNDLING OF OUR OWN INDUSTRY
While Startup valuations are rising • # of US startups
worth more than $1bn (Unicorns) • 2014: 30 • 2015: 80
But companies are increasingly exiting at or below last private
valuation
Total billion+ exits: • 2014: 12 • 1H 2015: 7
We’re in a Bubble Private tech markets are overvalued Driven
by new capital sources with less discipline Yet tech innovation will continue to grow
Finally • The entrepreneurial revolution has only just begun •
The internet is still in its infant stage
Tech continues to grow. Amazing companies are being created. More
than we’ve ever seen
None
http://www.pwc.com/us/tech-trends http://www.mckinsey.com/insights/ manufacturing/3-d_printing_takes_shape http://www.compareandshare.com/blog/4- sharing-economy-trends-in-2015/ http://www.usnews.com/cmsmedia/19/ d3/3333fd744cbb94ba6480e59612fc/150821- sharingeconomy3-graphic.jpg http://www.nytimes.com/2015/10/24/business/ dealbook/uber-said-to-plan-another-1-billion-in-
fund-raising.html https://www.linkedin.com/pulse/drone-delivery- could-reality-within-months-government-aaref- hilaly?trk=prof- post&utm_content=buffer8e9ea&utm_mediu m=social&utm_source=twitter.com&utm_cam paign=buffer https://www.digitalpulse.pwc.com.au/wp- content/uploads/2015/05/drones-for-good- infographic.jpg Mhealth infographic: http://www.pwc.com/us/ en/health-industries/top-health-industry-issues/ assets/mhealth.png Mhealth survey outcome with lots of data: https://www.digitalpulse.pwc.com.au/ infographic-mhealth-survey/ http://uk.businessinsider.com/michael-wolf- predicts-what-will-happen-in-the-tech-industry- in-2016-2015-10?op=0#/#-1 Sources https://www.cbinsights.com/blog/insurance-tech-vc- commentary/?utm_source=CB+Insights +Newsletter&utm_campaign=707706f16e- Theranos_10_18_2015&utm_medium=email&utm_term=0_ 9dc0513989-707706f16e-86601977&goal=0_9dc0513989-7 07706f16e-86601977 http://www.forbes.com/sites/stevemorgan/2015/10/16/the- business-of-cybersecurity-2015-market-size-cyber-crime- employment-and-industry-statistics/5/ http://www.pwc.com/us/tech-trends (source:https://www.pwc.com/m1/en/services/consulting/ documents/millennials-at-work.pdf) (Source: http://www.goldmansachs.com/our-thinking/pages/ millennials/) http://www.gartner.com/smarterwithgartner/a-view-into- digital-disruptions/ http://gartner.com/smarterwithgartner https://www.cl.cam.ac.uk/~drt24/papers/spsm-scoring.pdf Venture Capital Outlook 2016 by Mark Suster & Kevin Zhang (upfront Ventures) https://www.elektrobit.com/trends/autonomous-driving/ http://www.vtpi.org/avip.pdf http://uk.businessinsider.com/the-wearable-computing- market-report-2014-10?r=US&IR=T https://www.digitalpulse.pwc.com.au/infographic-wearable- technology-change-internet/ http://www.globest.com/news/12_1225/ chicago/industrial/E-Commerce-to- Shape-Logistics-for- Decades-362872-1.html https://www.digitalpulse.pwc.com.au/ infographic-video-on-demand http://www.pwc.com/gx/en/industries/ entertainment-media/outlook/global- data-insights.html http://www.pwc.com/gx/en/global- entertainment-media-outlook/assets/ 2015/cross-segment-highlights.pdf All Pictures Shutterstock. Startupbootcamp 2015


 ozakiomumkj
 noritaka88tax
 mj6237
 gatechnologies
 uniam
 kuradashi
 takemura_yuto
 tamagakiyuya
 freee
 ggfs
 synergymarketing
 ikuodanaka
 maggiecrowley
 frankvandijk
 techseoconnect
 tenderlove
 baasie
 bethany
 axbom
 rkendrick25
 holman
 lynnandtonic
 jonyablonski
 inesmontani