Upgrade to Pro — share decks privately, control downloads, hide ads and more …

Global Startup Landscape 2026

Global Startup Landscape 2026

Global startup investment across six markets, with five-year funding trends, financing-stage comparisons and 24 company profiles.

The 15-page report examines the concentration of large funding rounds, robotics growth, and the differences between fintech and cybersecurity financing. Original sources and methodology are linked throughout.

Avatar for Takuya Shimano

Takuya Shimano

October 02, 2026

More Decks by Takuya Shimano

Other Decks in Research

Transcript

  1. GLOBAL TECHNOLOGY 2026 Global Startup Landscape 2026 Venture investment trends

    and startup products across six business domains Company directory: 19,993 companies | 7 organizations | 6 domains Research as of 25 September 2026
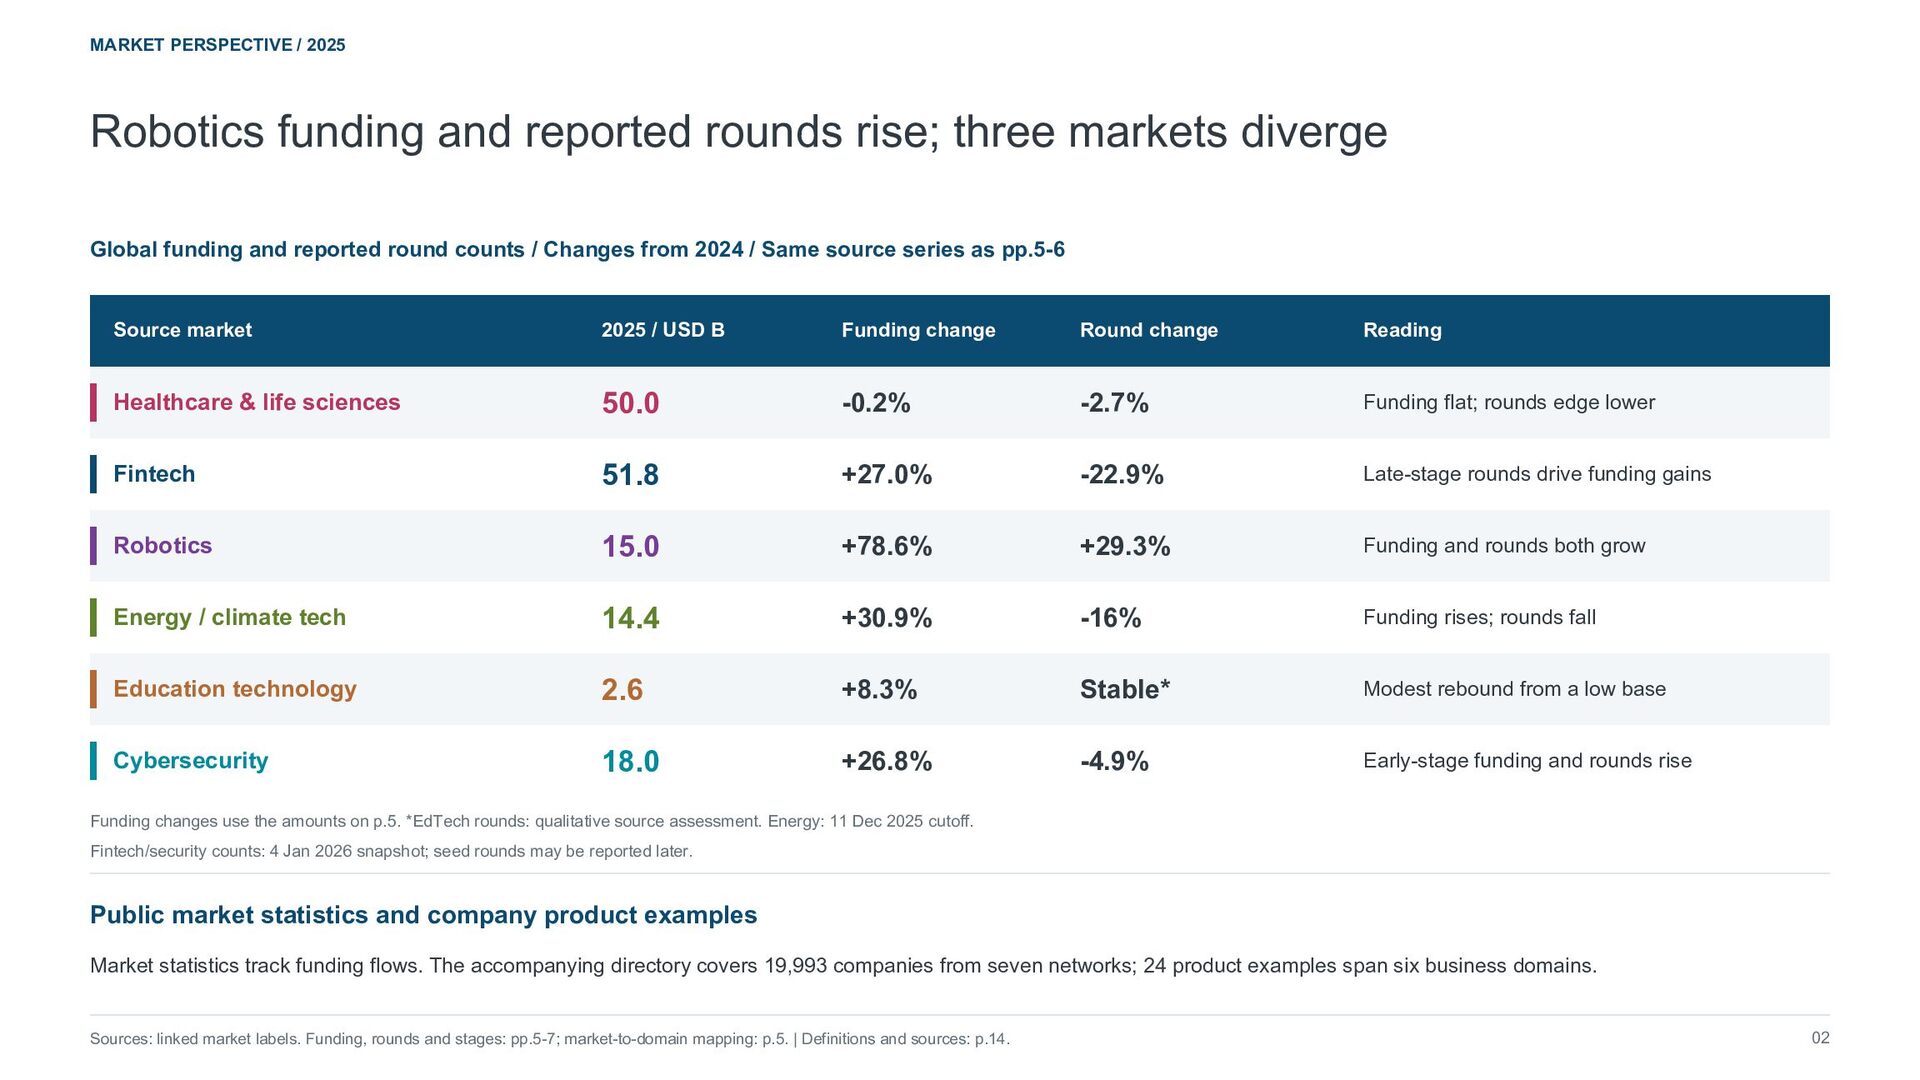
  2. MARKET PERSPECTIVE / 2025 Robotics funding and reported rounds rise;

    three markets diverge Global funding and reported round counts / Changes from 2024 / Same source series as pp.5-6 Source market 2025 / USD B Funding change Round change Reading Healthcare & life sciences 50.0 -0.2% -2.7% Funding flat; rounds edge lower Fintech 51.8 +27.0% -22.9% Late-stage rounds drive funding gains Robotics 15.0 +78.6% +29.3% Funding and rounds both grow Energy / climate tech 14.4 +30.9% -16% Funding rises; rounds fall Education technology 2.6 +8.3% Stable* Modest rebound from a low base Cybersecurity 18.0 +26.8% -4.9% Early-stage funding and rounds rise Funding changes use the amounts on p.5. *EdTech rounds: qualitative source assessment. Energy: 11 Dec 2025 cutoff. Fintech/security counts: 4 Jan 2026 snapshot; seed rounds may be reported later. Public market statistics and company product examples Market statistics track funding flows. The accompanying directory covers 19,993 companies from seven networks; 24 product examples span six business domains. Sources: linked market labels. Funding, rounds and stages: pp.5-7; market-to-domain mapping: p.5. | Definitions and sources: p.14. 02
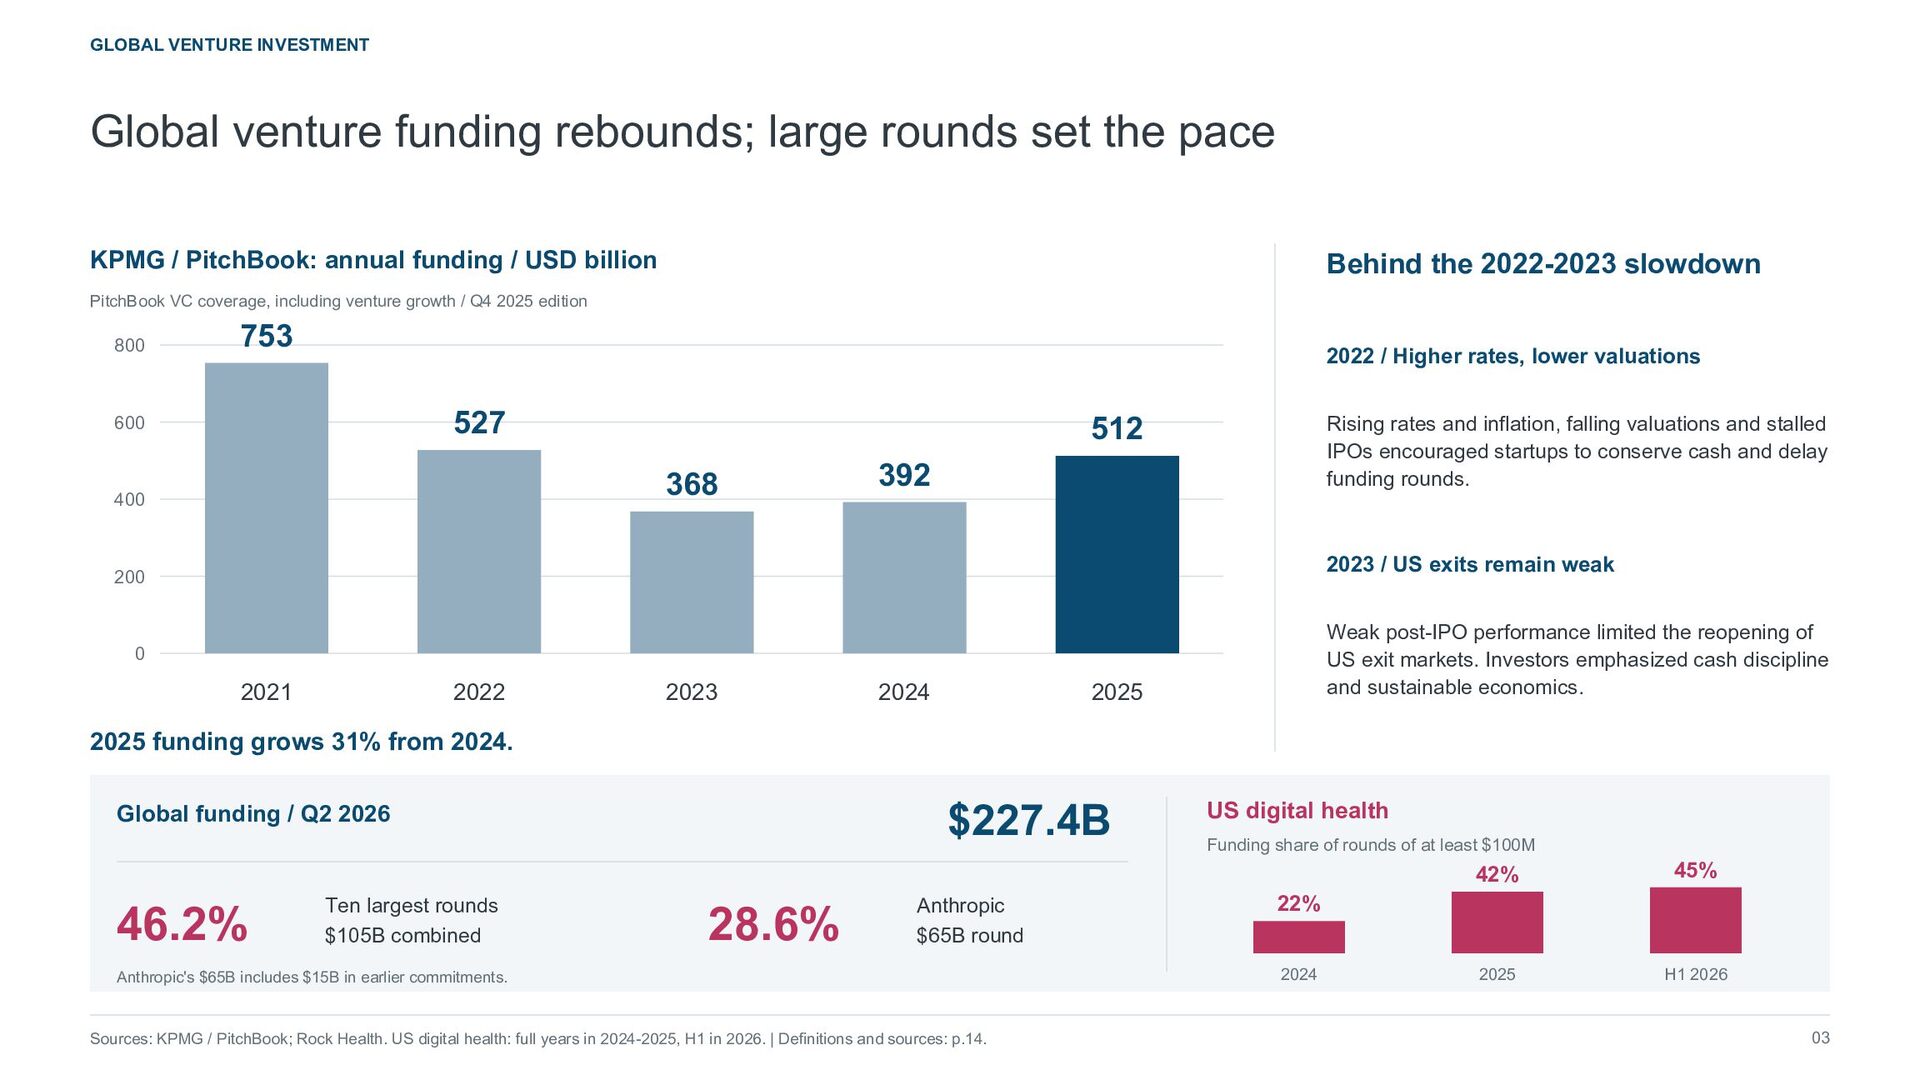
  3. GLOBAL VENTURE INVESTMENT Global venture funding rebounds; large rounds set

    the pace KPMG / PitchBook: annual funding / USD billion Behind the 2022-2023 slowdown PitchBook VC coverage, including venture growth / Q4 2025 edition 800 753 2022 / Higher rates, lower valuations 527 600 368 400 Rising rates and inflation, falling valuations and stalled IPOs encouraged startups to conserve cash and delay funding rounds. 512 392 2023 / US exits remain weak 200 Weak post-IPO performance limited the reopening of US exit markets. Investors emphasized cash discipline and sustainable economics. 0 2021 2022 2023 2024 2025 2025 funding grows 31% from 2024. $227.4B Global funding / Q2 2026 46.2% Ten largest rounds $105B combined 28.6% Anthropic $65B round Anthropic's $65B includes $15B in earlier commitments. Sources: KPMG / PitchBook; Rock Health. US digital health: full years in 2024-2025, H1 in 2026. | Definitions and sources: p.14. US digital health Funding share of rounds of at least $100M 42% 45% 2025 H1 2026 22% 2024 03
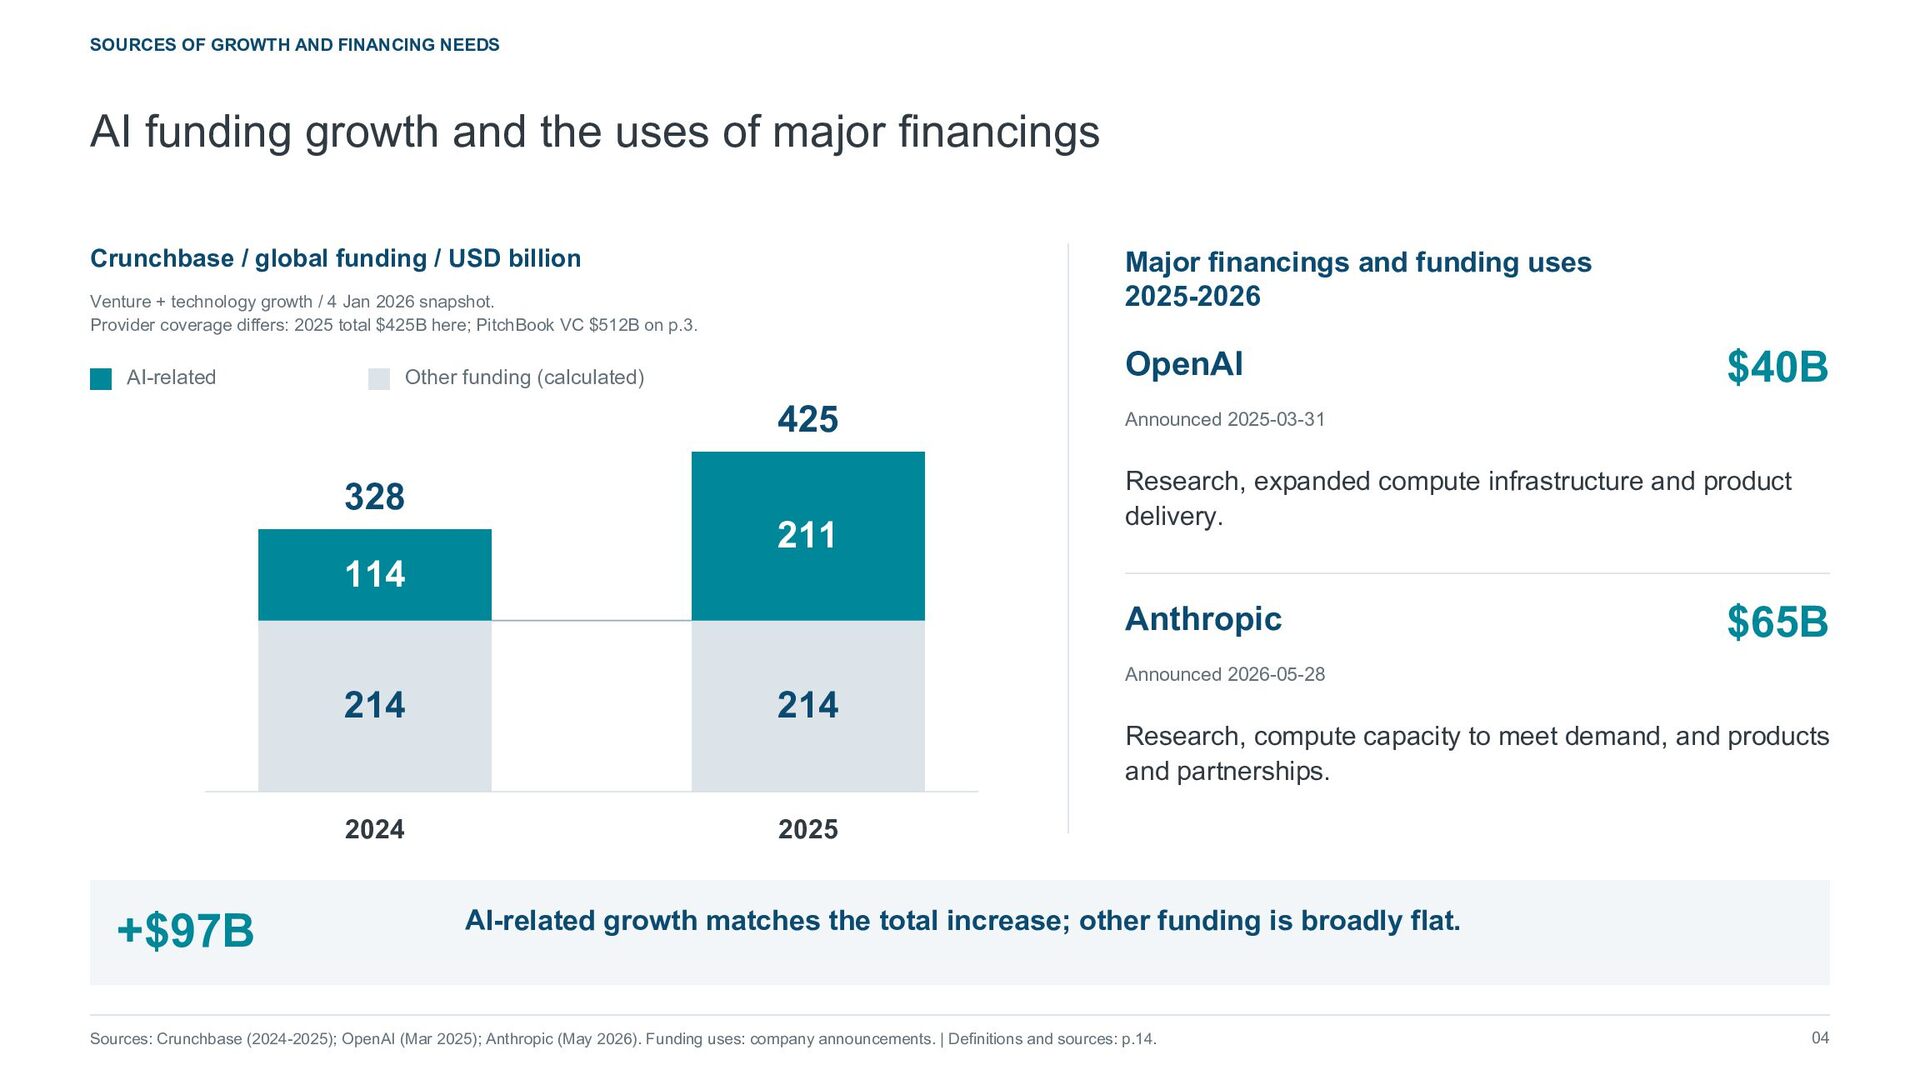
  4. SOURCES OF GROWTH AND FINANCING NEEDS AI funding growth and

    the uses of major financings Crunchbase / global funding / USD billion Major financings and funding uses 2025-2026 Venture + technology growth / 4 Jan 2026 snapshot. Provider coverage differs: 2025 total $425B here; PitchBook VC $512B on p.3. AI-related OpenAI Other funding (calculated) 425 328 211 $40B Announced 2025-03-31 Research, expanded compute infrastructure and product delivery. 114 Anthropic $65B Announced 2026-05-28 214 214 Research, compute capacity to meet demand, and products and partnerships. 2024 +$97B 2025 AI-related growth matches the total increase; other funding is broadly flat. Sources: Crunchbase (2024-2025); OpenAI (Mar 2025); Anthropic (May 2026). Funding uses: company announcements. | Definitions and sources: p.14. 04
  5. FIVE-YEAR SECTOR FUNDING TRENDS Funding trends across markets linked to

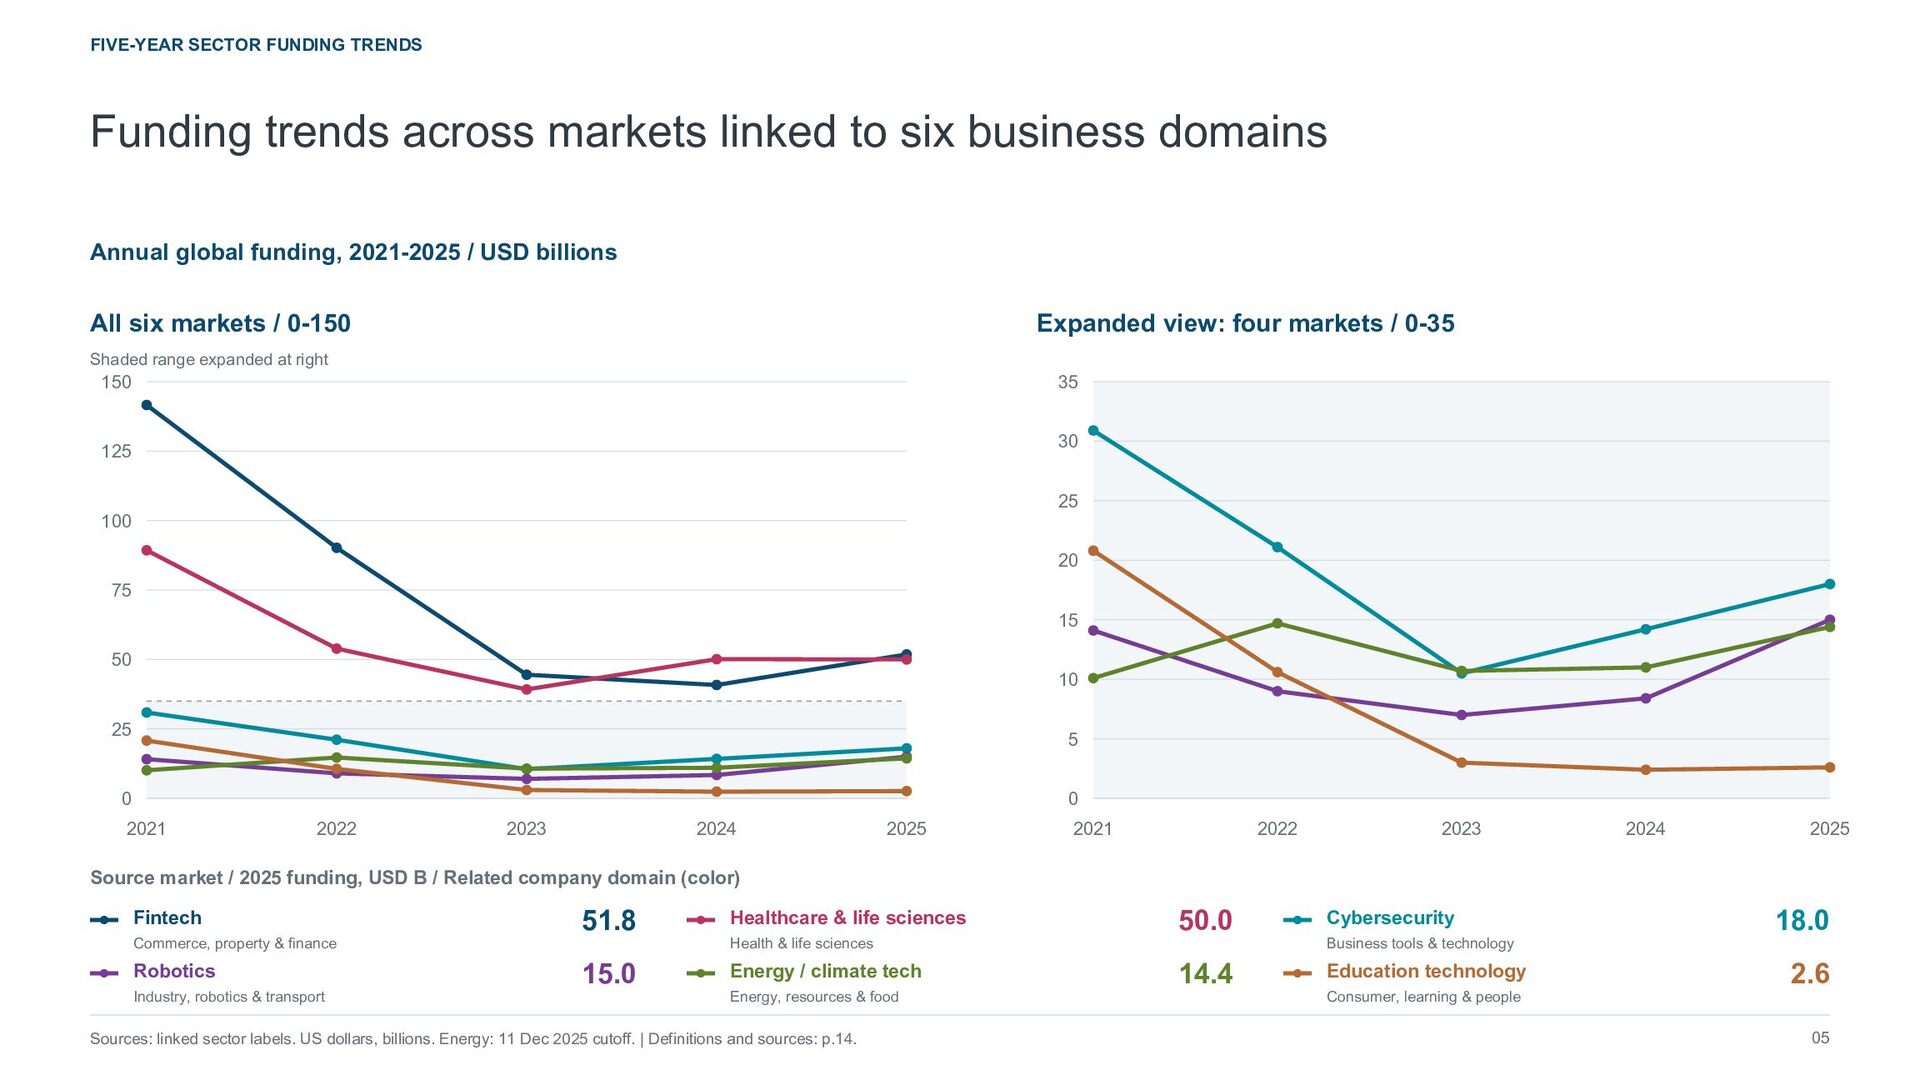
    six business domains Annual global funding, 2021-2025 / USD billions All six markets / 0-150 Expanded view: four markets / 0-35 Shaded range expanded at right 150 35 30 125 25 100 20 75 15 50 10 25 5 0 0 2021 2022 2023 2024 2025 2021 2022 2023 2024 2025 Source market / 2025 funding, USD B / Related company domain (color) Fintech 51.8 Commerce, property & finance Robotics Industry, robotics & transport Healthcare & life sciences 50.0 Health & life sciences 15.0 Energy / climate tech Energy, resources & food Sources: linked sector labels. US dollars, billions. Energy: 11 Dec 2025 cutoff. | Definitions and sources: p.14. Cybersecurity 18.0 Business tools & technology 14.4 Education technology 2.6 Consumer, learning & people 05
  6. FIVE-YEAR FUNDING ACTIVITY Reported rounds rise in robotics and fall

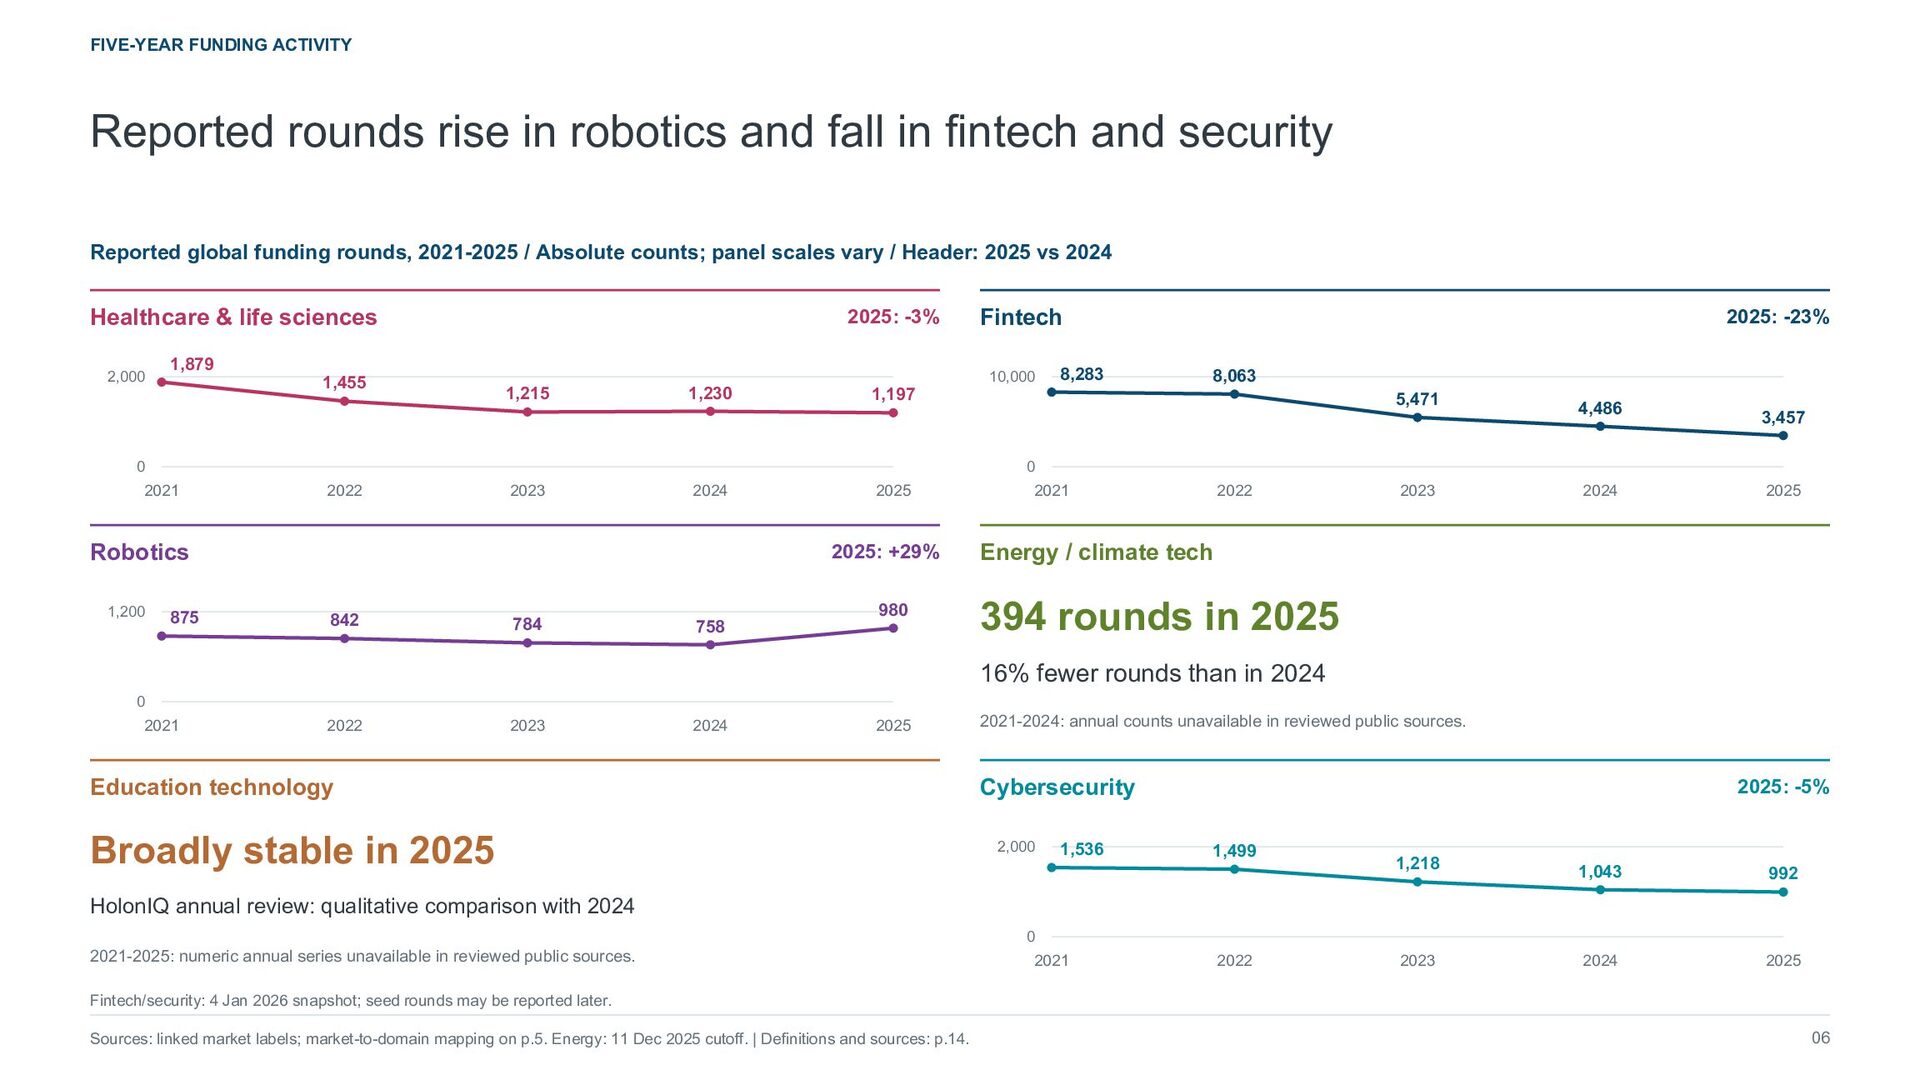
    in fintech and security Reported global funding rounds, 2021-2025 / Absolute counts; panel scales vary / Header: 2025 vs 2024 Healthcare & life sciences 2,000 2025: -3% 1,879 1,455 10,000 1,215 1,230 8,283 2025: -23% 8,063 1,197 0 5,471 4,486 3,457 0 2021 2022 2023 2024 Robotics 1,200 Fintech 875 2025 2025: +29% 842 784 980 758 2021 2022 2023 2024 2025 Energy / climate tech 394 rounds in 2025 16% fewer rounds than in 2024 0 2021 2022 2023 2024 2025 Education technology Broadly stable in 2025 2021-2024: annual counts unavailable in reviewed public sources. Cybersecurity 2,000 1,536 2025: -5% 1,499 1,218 1,043 992 2023 2024 2025 HolonIQ annual review: qualitative comparison with 2024 0 2021-2025: numeric annual series unavailable in reviewed public sources. 2021 2022 Fintech/security: 4 Jan 2026 snapshot; seed rounds may be reported later. Sources: linked market labels; market-to-domain mapping on p.5. Energy: 11 Dec 2025 cutoff. | Definitions and sources: p.14. 06
  7. FUNDING STAGES / TWO-MARKET COMPARISON Late-stage fintech and early-stage security

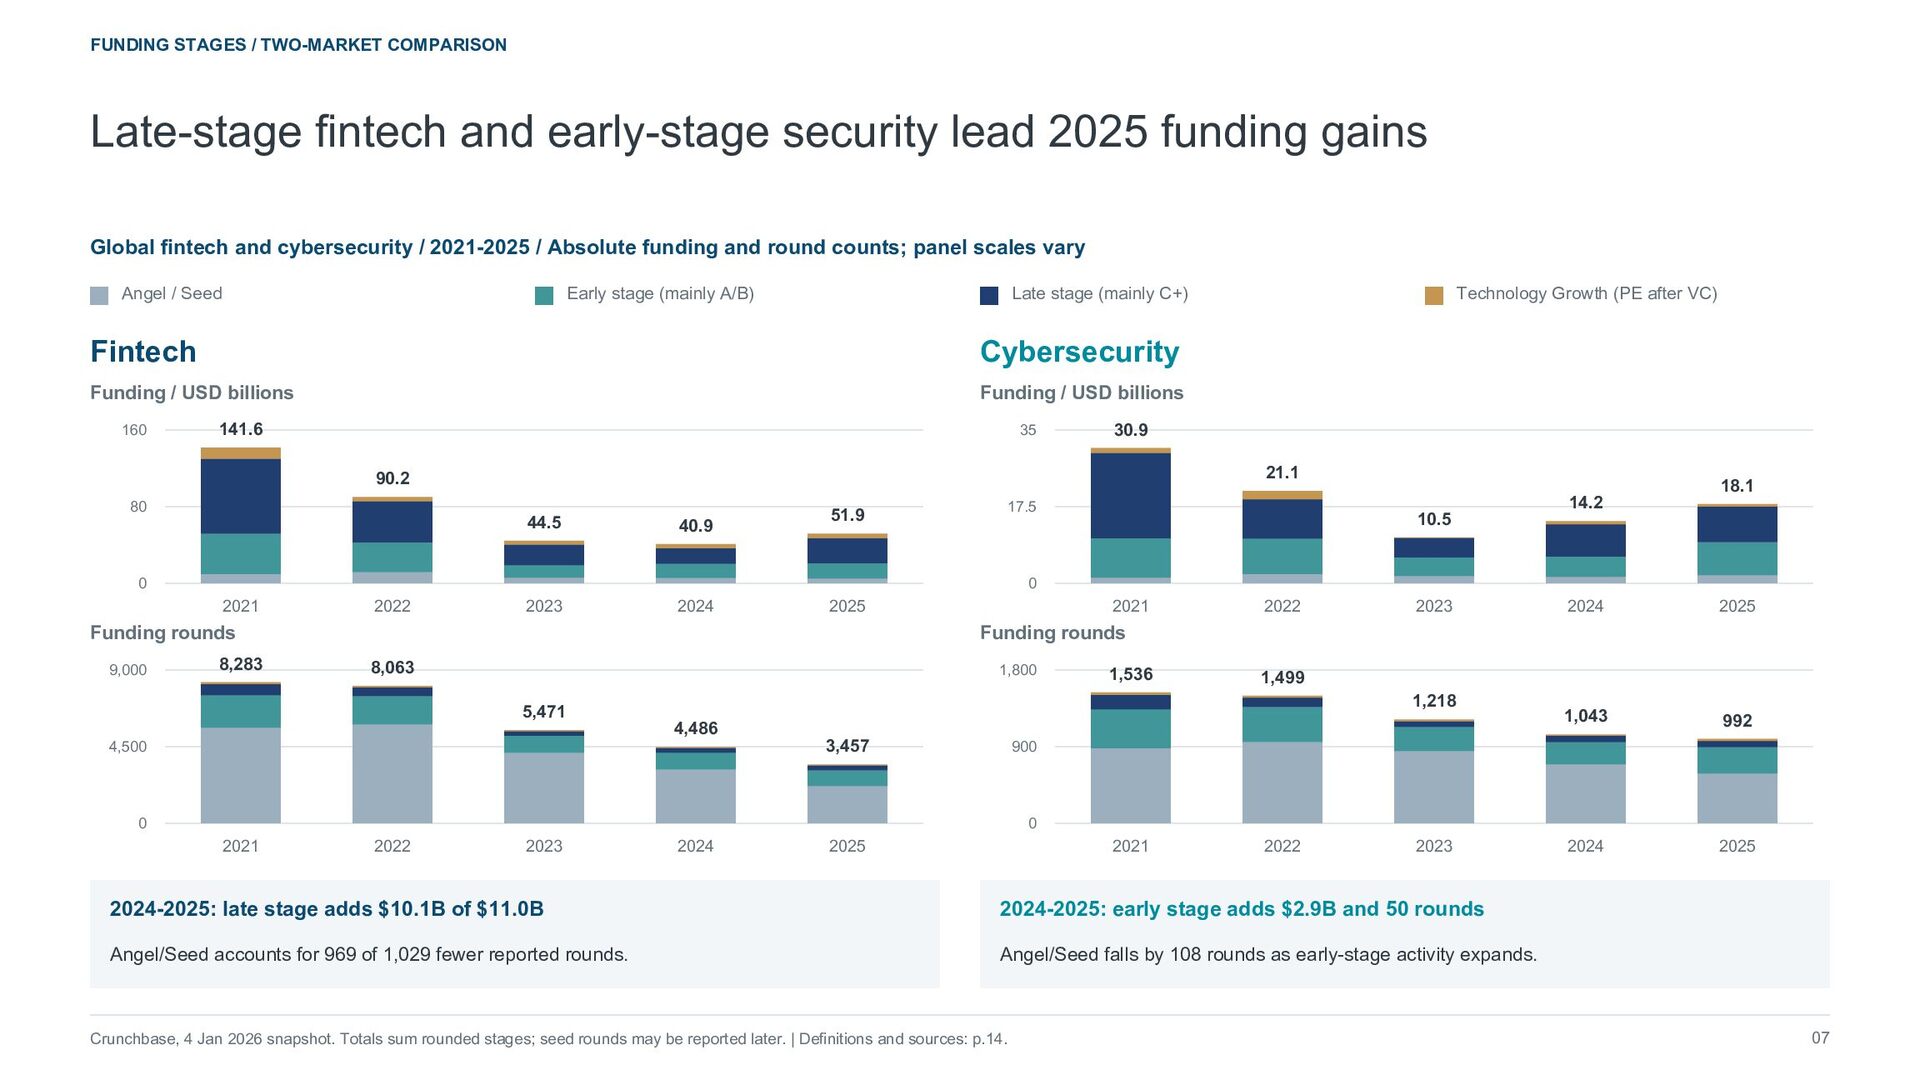
    lead 2025 funding gains Global fintech and cybersecurity / 2021-2025 / Absolute funding and round counts; panel scales vary Angel / Seed Early stage (mainly A/B) Late stage (mainly C+) Fintech Cybersecurity Funding / USD billions Funding / USD billions 160 141.6 35 30.9 21.1 90.2 80 44.5 40.9 2023 2024 51.9 17.5 0 18.1 10.5 14.2 0 2021 2022 2025 Funding rounds 9,000 Technology Growth (PE after VC) 8,283 2021 2022 2023 2024 2025 1,043 992 2024 2025 Funding rounds 8,063 1,800 1,536 1,499 1,218 5,471 4,486 3,457 4,500 900 0 0 2021 2022 2023 2024 2025 2021 2022 2023 2024-2025: late stage adds $10.1B of $11.0B 2024-2025: early stage adds $2.9B and 50 rounds Angel/Seed accounts for 969 of 1,029 fewer reported rounds. Angel/Seed falls by 108 rounds as early-stage activity expands. Crunchbase, 4 Jan 2026 snapshot. Totals sum rounded stages; seed rounds may be reported later. | Definitions and sources: p.14. 07
  8. HEALTH & LIFE SCIENCES Protein analysis, imaging and clinical data

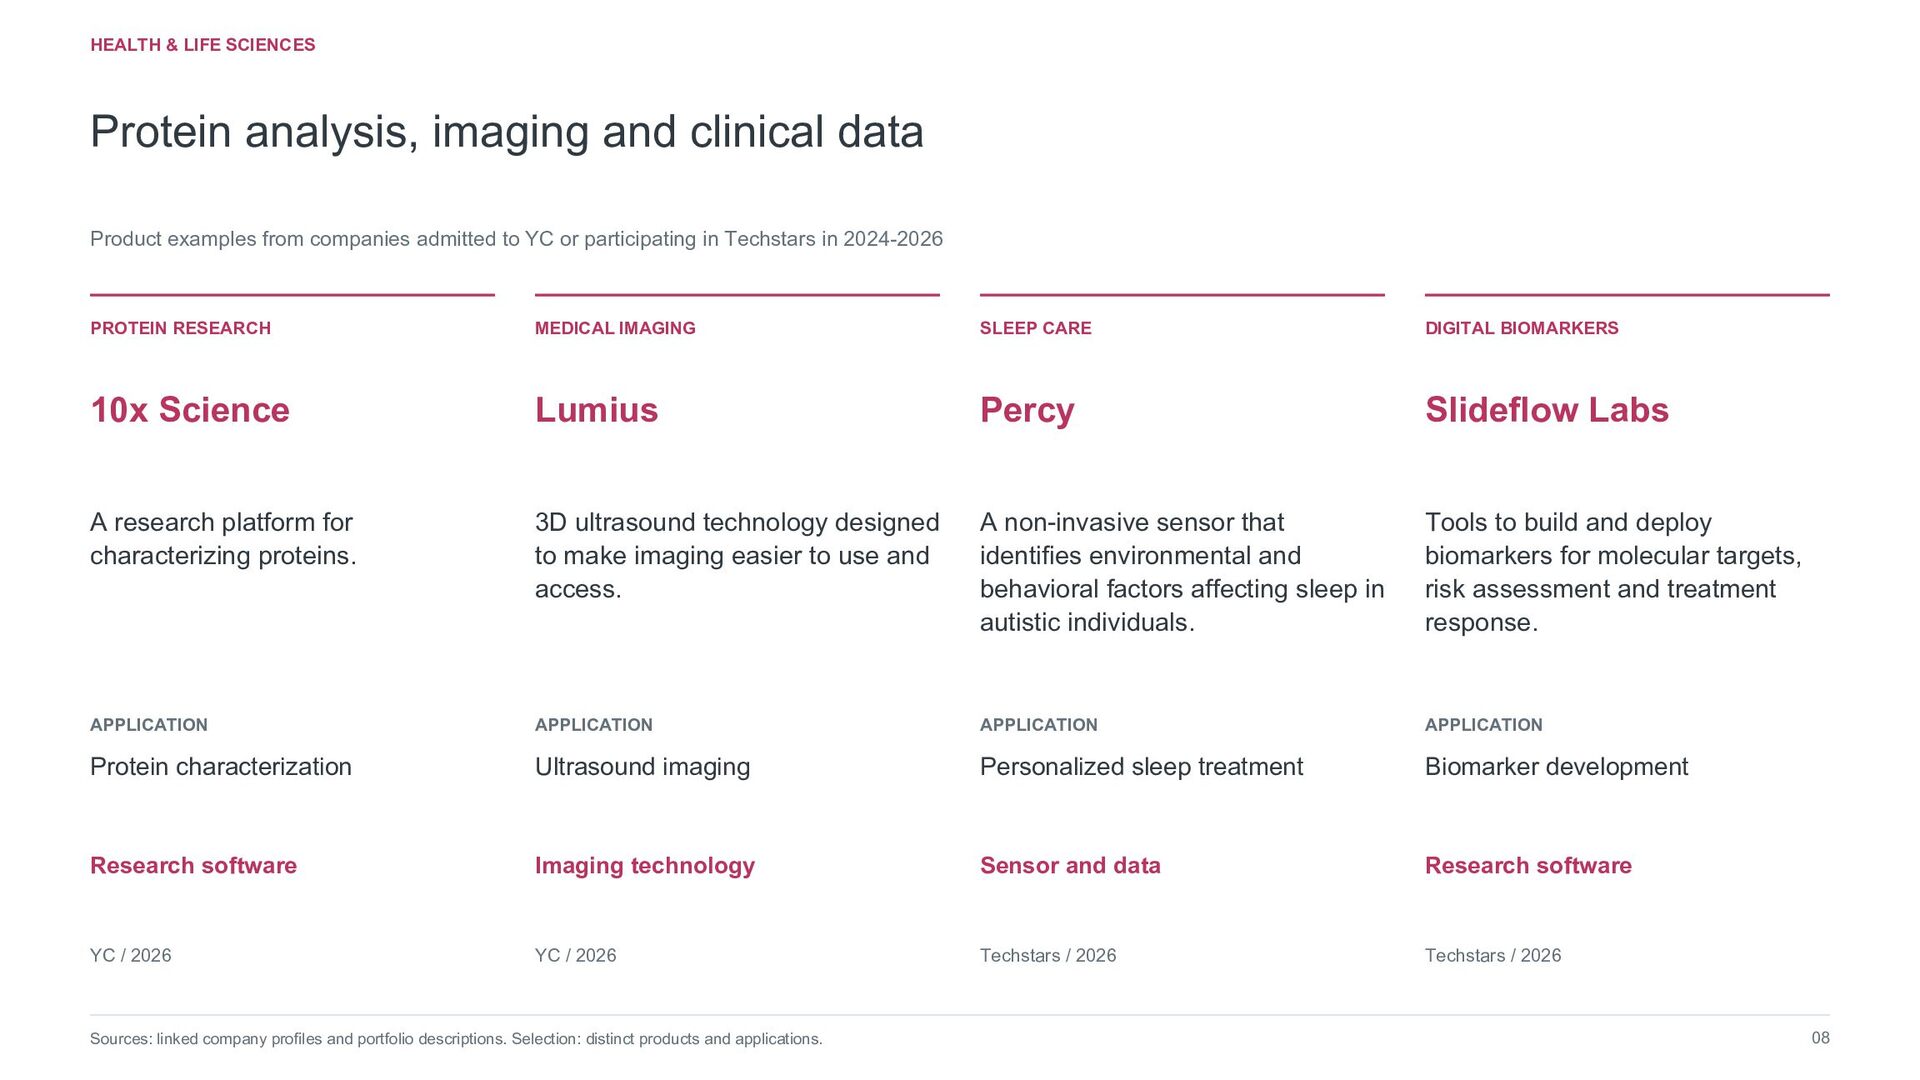
    Product examples from companies admitted to YC or participating in Techstars in 2024-2026 PROTEIN RESEARCH MEDICAL IMAGING SLEEP CARE DIGITAL BIOMARKERS 10x Science Lumius Percy Slideflow Labs A research platform for characterizing proteins. 3D ultrasound technology designed to make imaging easier to use and access. A non-invasive sensor that identifies environmental and behavioral factors affecting sleep in autistic individuals. Tools to build and deploy biomarkers for molecular targets, risk assessment and treatment response. APPLICATION APPLICATION APPLICATION APPLICATION Protein characterization Ultrasound imaging Personalized sleep treatment Biomarker development Research software Imaging technology Sensor and data Research software YC / 2026 YC / 2026 Techstars / 2026 Techstars / 2026 Sources: linked company profiles and portfolio descriptions. Selection: distinct products and applications. 08
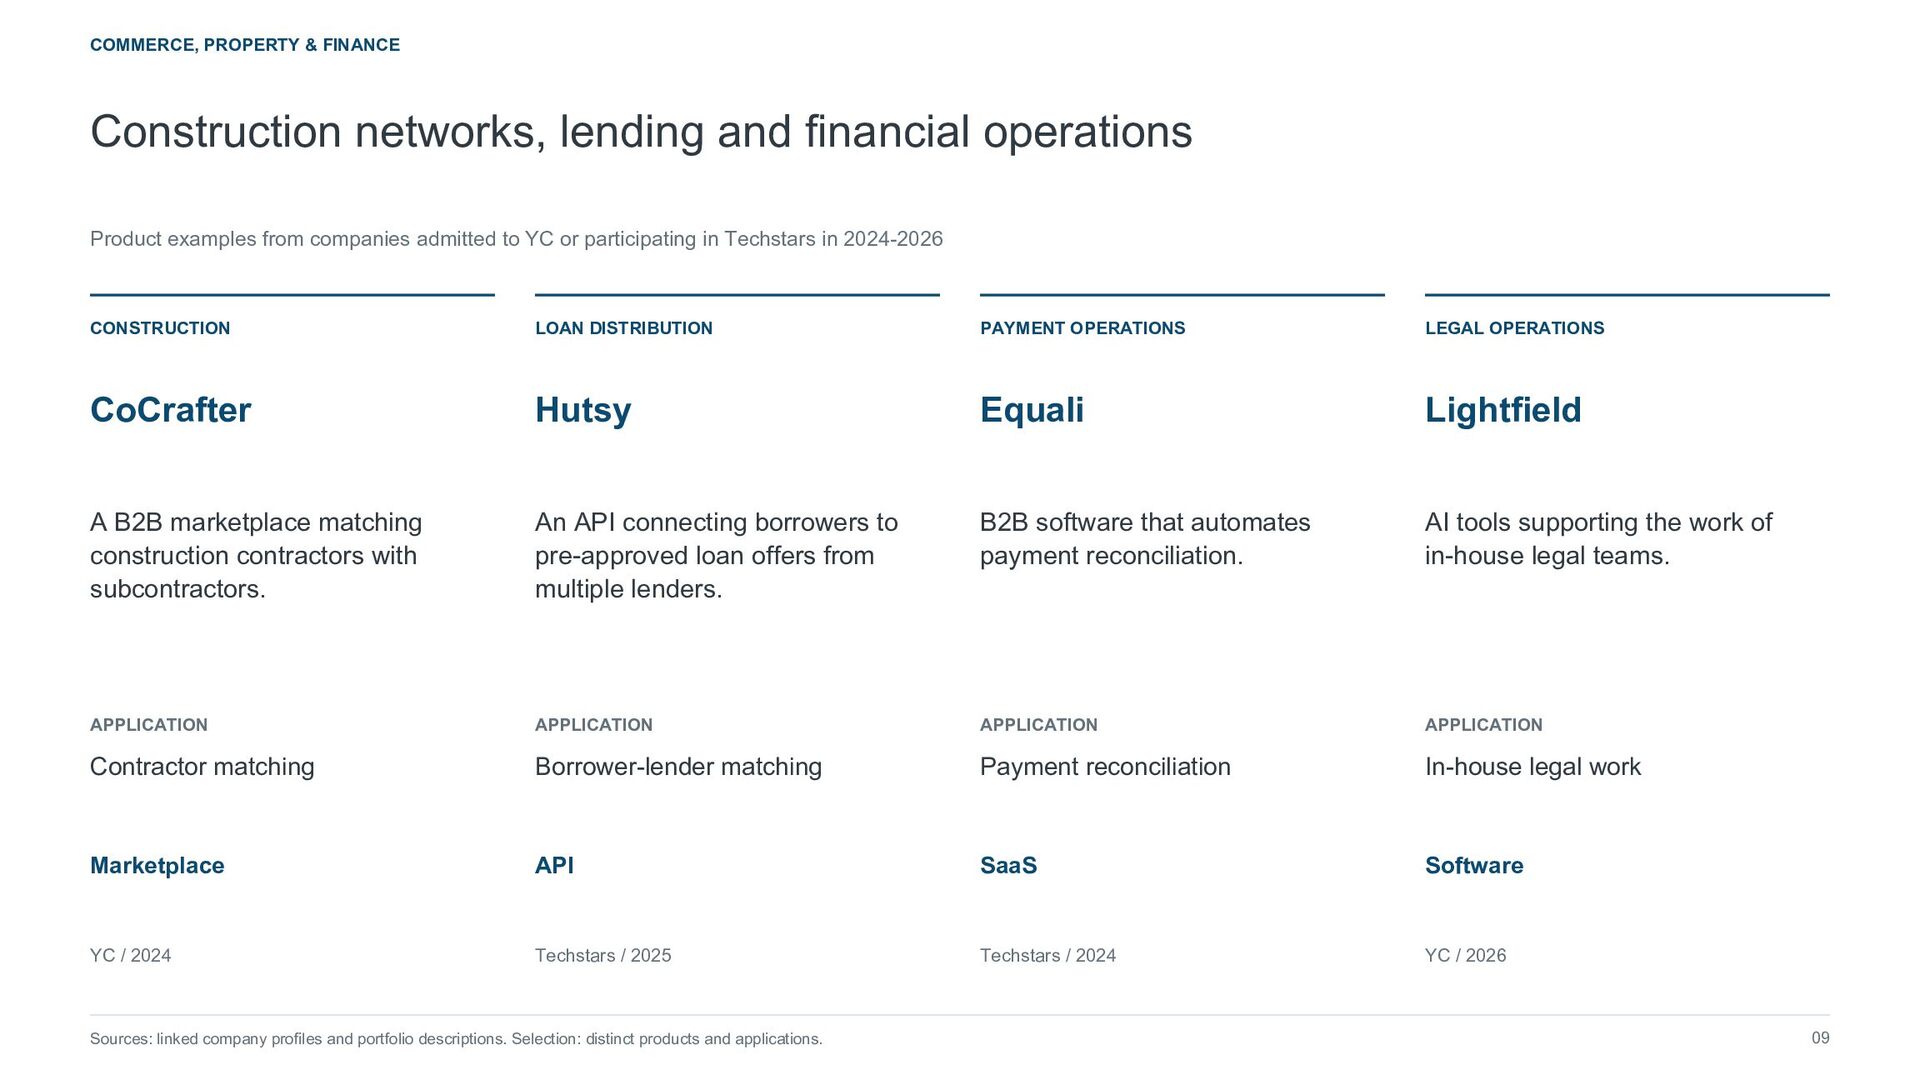
  9. COMMERCE, PROPERTY & FINANCE Construction networks, lending and financial operations

    Product examples from companies admitted to YC or participating in Techstars in 2024-2026 CONSTRUCTION LOAN DISTRIBUTION PAYMENT OPERATIONS LEGAL OPERATIONS CoCrafter Hutsy Equali Lightfield A B2B marketplace matching construction contractors with subcontractors. An API connecting borrowers to pre-approved loan offers from multiple lenders. B2B software that automates payment reconciliation. AI tools supporting the work of in-house legal teams. APPLICATION APPLICATION APPLICATION APPLICATION Contractor matching Borrower-lender matching Payment reconciliation In-house legal work Marketplace API SaaS Software YC / 2024 Techstars / 2025 Techstars / 2024 YC / 2026 Sources: linked company profiles and portfolio descriptions. Selection: distinct products and applications. 09
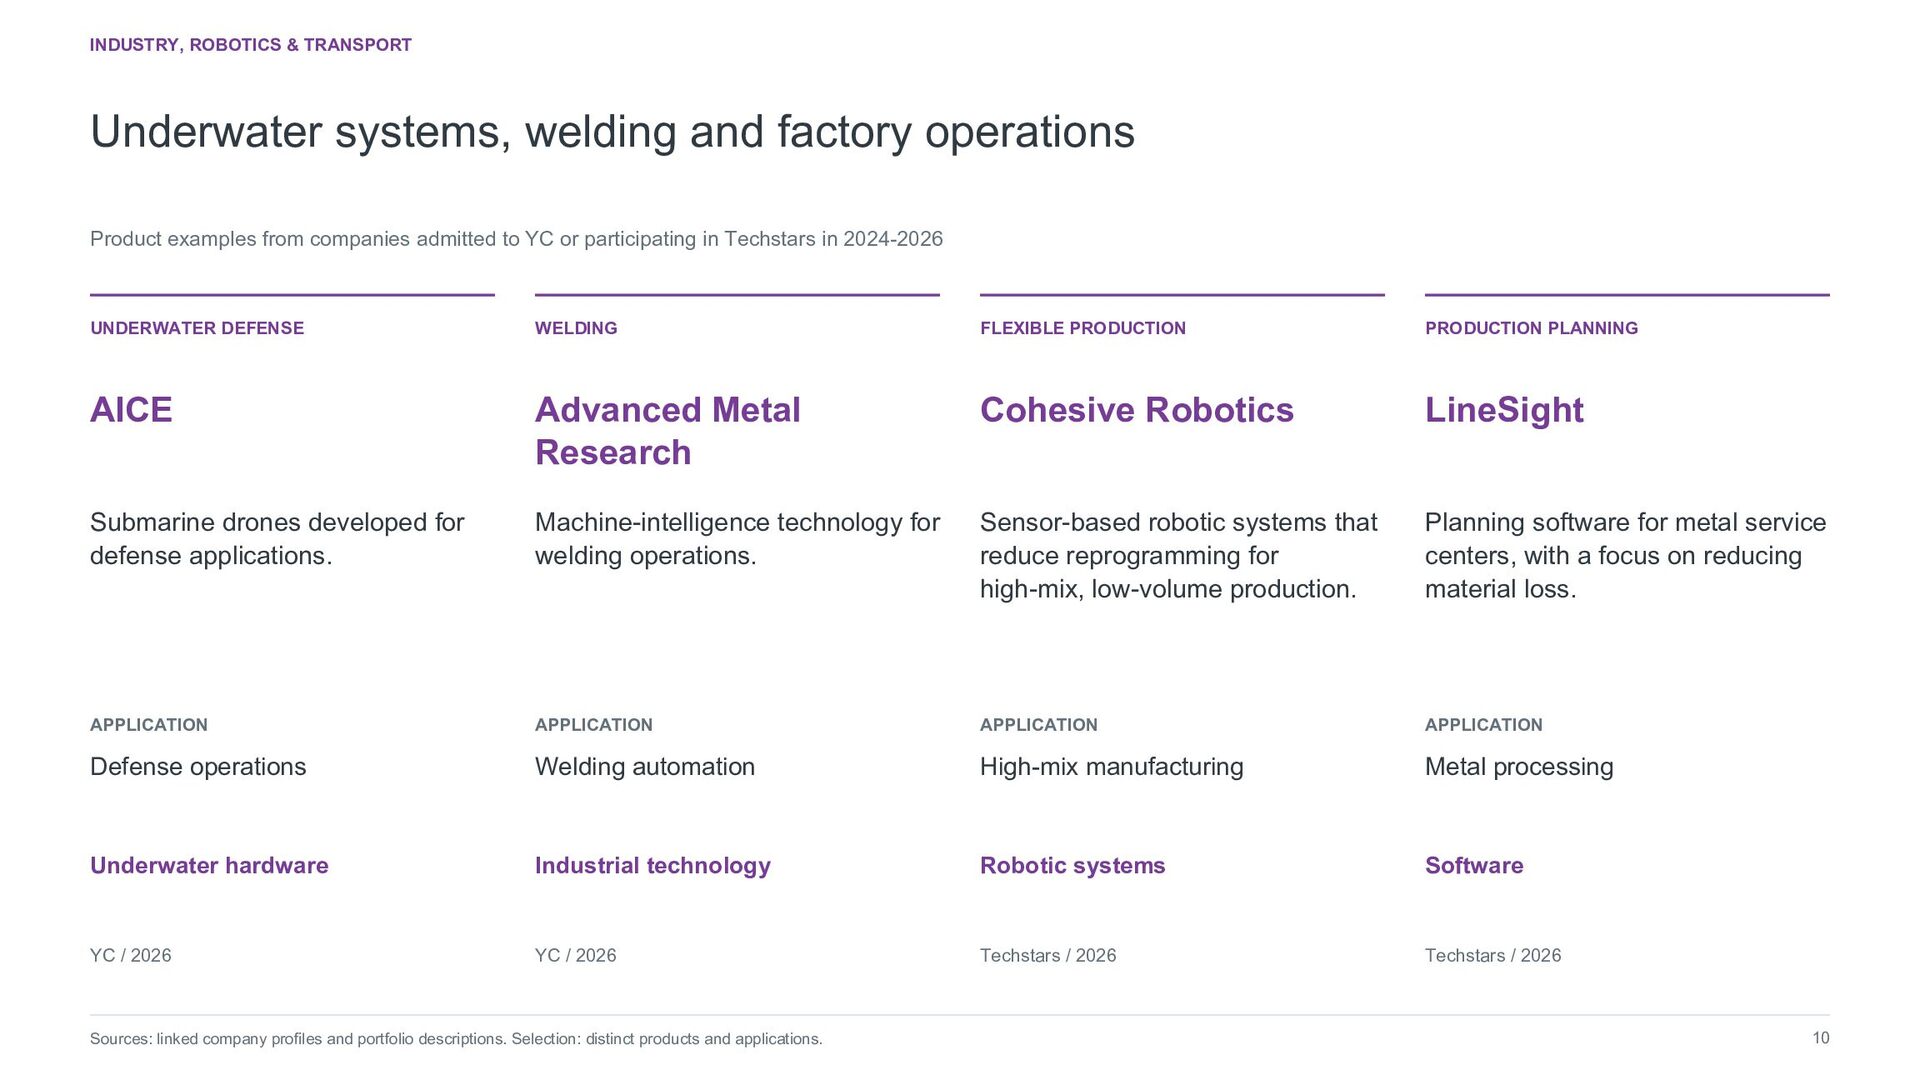
  10. INDUSTRY, ROBOTICS & TRANSPORT Underwater systems, welding and factory operations

    Product examples from companies admitted to YC or participating in Techstars in 2024-2026 UNDERWATER DEFENSE WELDING FLEXIBLE PRODUCTION PRODUCTION PLANNING AICE Advanced Metal Research Cohesive Robotics LineSight Submarine drones developed for defense applications. Machine-intelligence technology for welding operations. Sensor-based robotic systems that reduce reprogramming for high-mix, low-volume production. Planning software for metal service centers, with a focus on reducing material loss. APPLICATION APPLICATION APPLICATION APPLICATION Defense operations Welding automation High-mix manufacturing Metal processing Underwater hardware Industrial technology Robotic systems Software YC / 2026 YC / 2026 Techstars / 2026 Techstars / 2026 Sources: linked company profiles and portfolio descriptions. Selection: distinct products and applications. 10
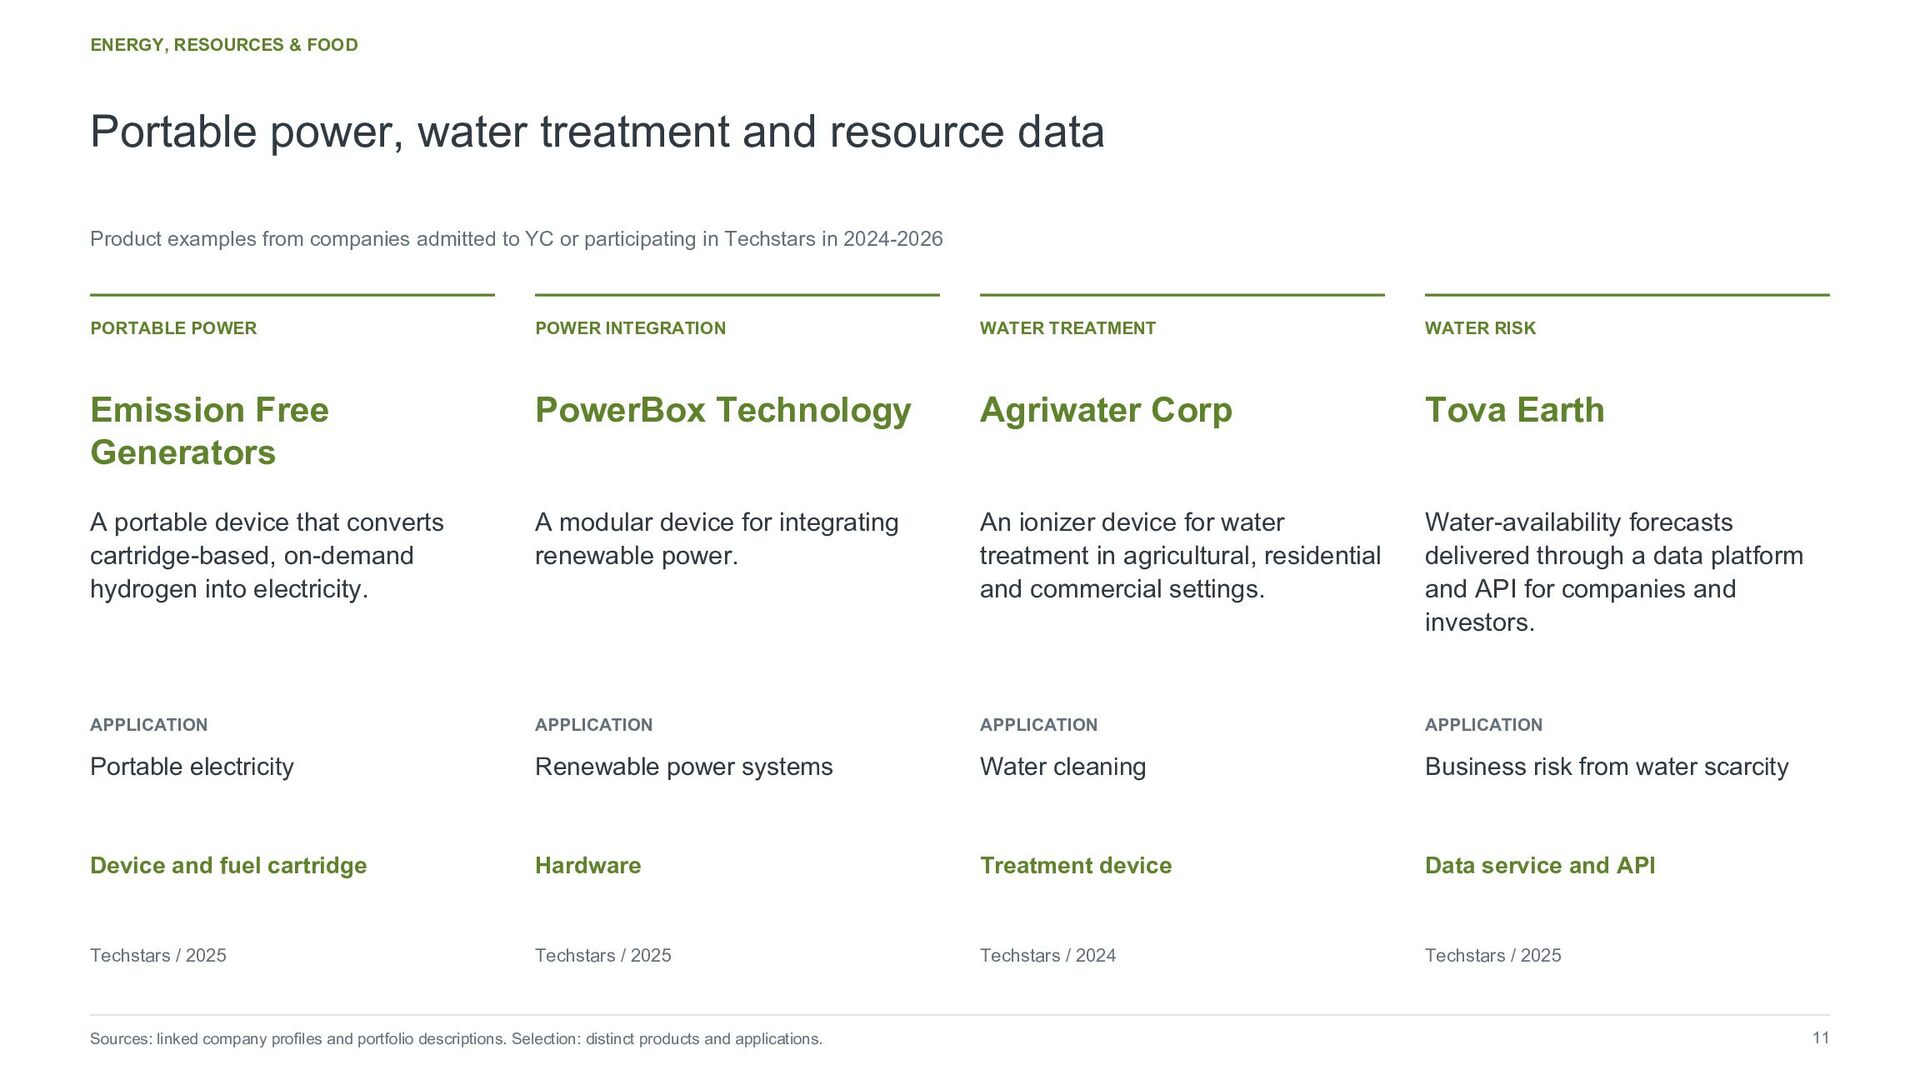
  11. ENERGY, RESOURCES & FOOD Portable power, water treatment and resource

    data Product examples from companies admitted to YC or participating in Techstars in 2024-2026 PORTABLE POWER POWER INTEGRATION WATER TREATMENT WATER RISK Emission Free Generators PowerBox Technology Agriwater Corp Tova Earth A portable device that converts cartridge-based, on-demand hydrogen into electricity. A modular device for integrating renewable power. An ionizer device for water treatment in agricultural, residential and commercial settings. Water-availability forecasts delivered through a data platform and API for companies and investors. APPLICATION APPLICATION APPLICATION APPLICATION Portable electricity Renewable power systems Water cleaning Business risk from water scarcity Device and fuel cartridge Hardware Treatment device Data service and API Techstars / 2025 Techstars / 2025 Techstars / 2024 Techstars / 2025 Sources: linked company profiles and portfolio descriptions. Selection: distinct products and applications. 11
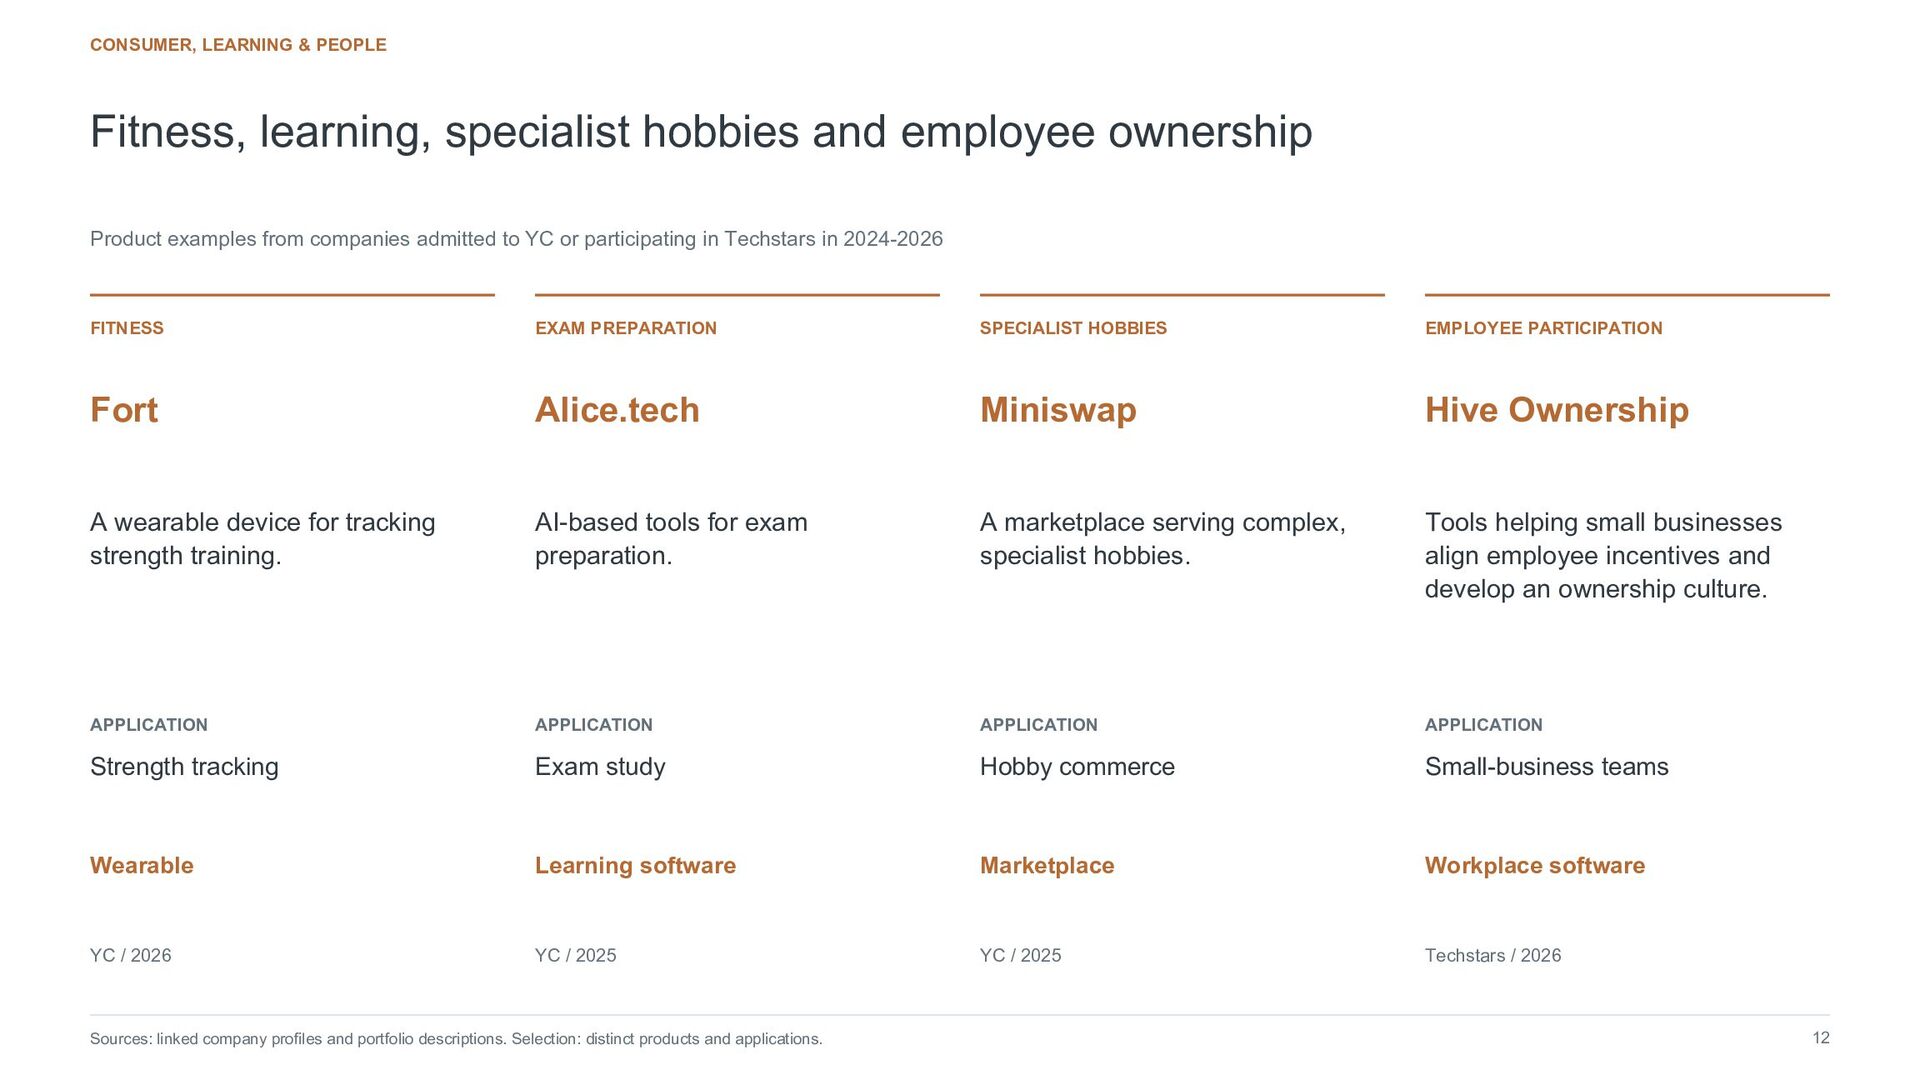
  12. CONSUMER, LEARNING & PEOPLE Fitness, learning, specialist hobbies and employee

    ownership Product examples from companies admitted to YC or participating in Techstars in 2024-2026 FITNESS EXAM PREPARATION SPECIALIST HOBBIES EMPLOYEE PARTICIPATION Fort Alice.tech Miniswap Hive Ownership A wearable device for tracking strength training. AI-based tools for exam preparation. A marketplace serving complex, specialist hobbies. Tools helping small businesses align employee incentives and develop an ownership culture. APPLICATION APPLICATION APPLICATION APPLICATION Strength tracking Exam study Hobby commerce Small-business teams Wearable Learning software Marketplace Workplace software YC / 2026 YC / 2025 YC / 2025 Techstars / 2026 Sources: linked company profiles and portfolio descriptions. Selection: distinct products and applications. 12
  13. BUSINESS TOOLS & TECHNOLOGY Computing hardware, inference and product development

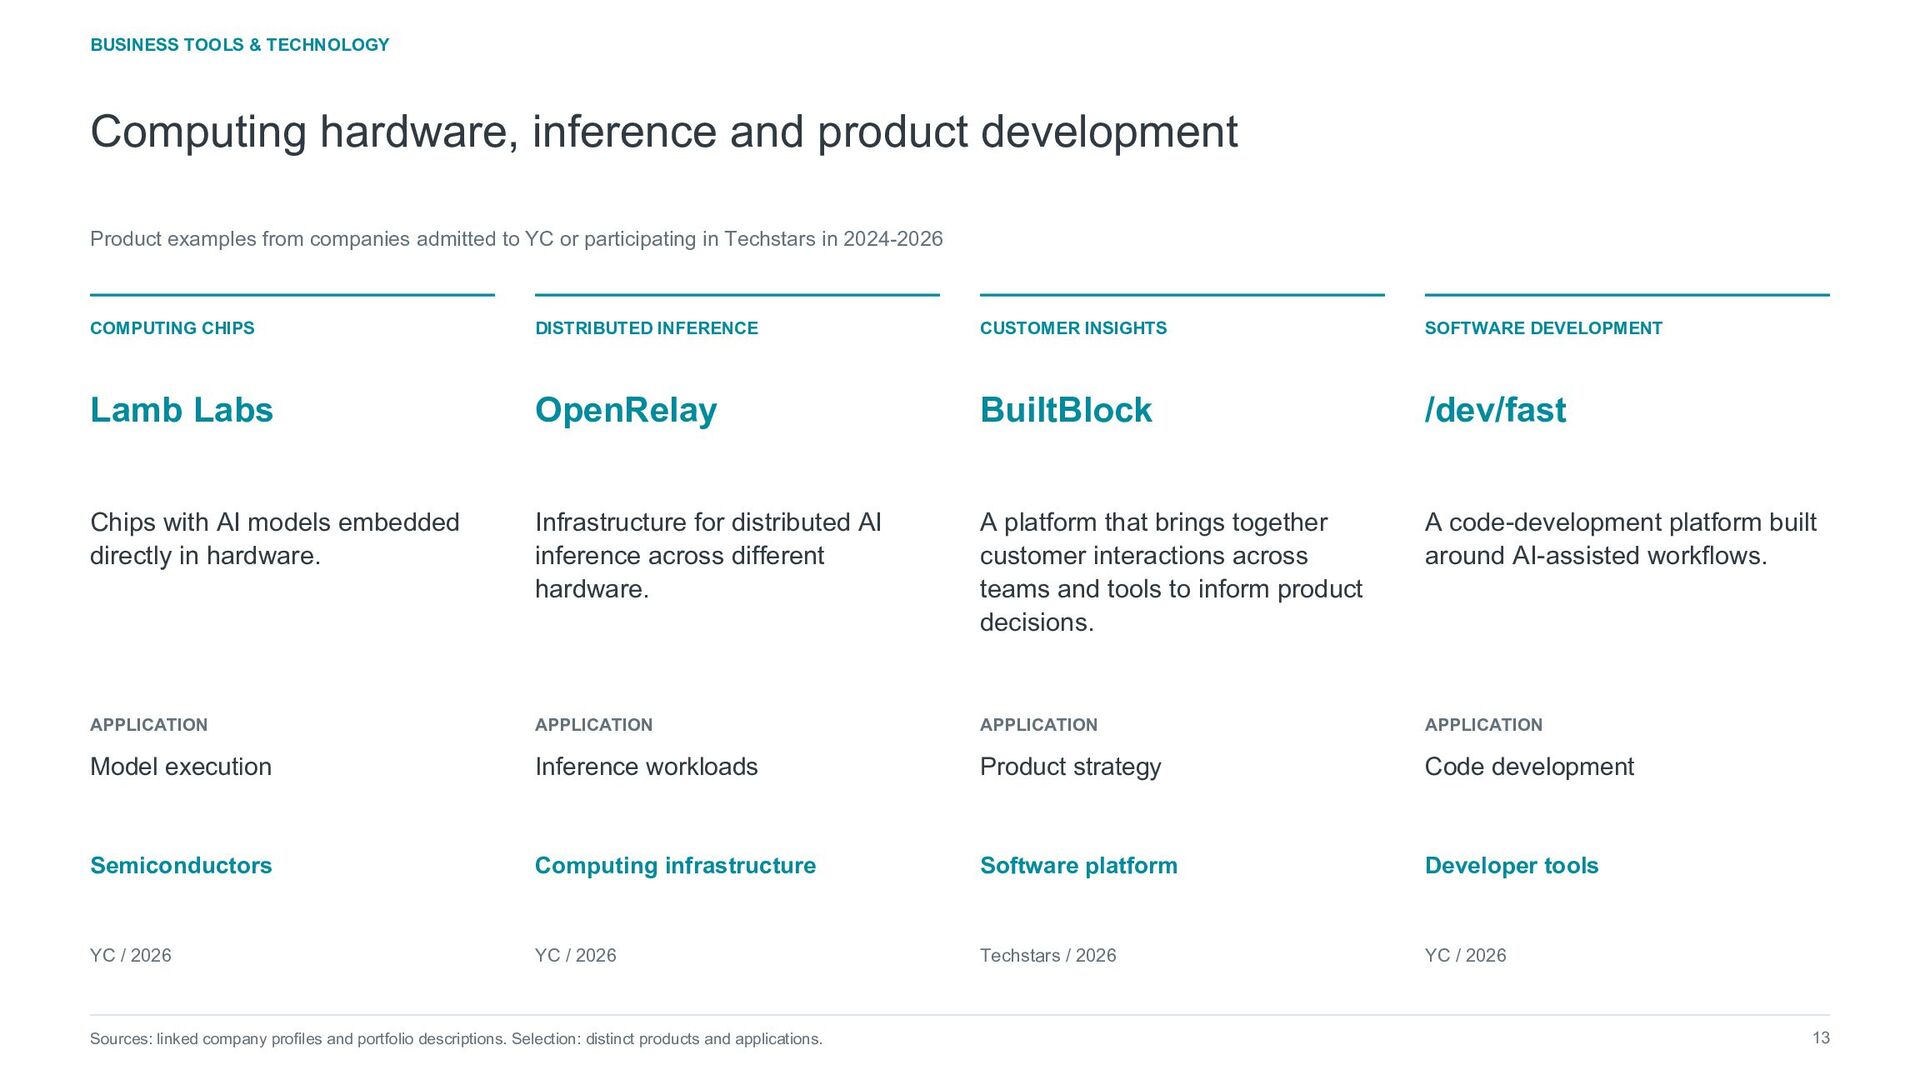
    Product examples from companies admitted to YC or participating in Techstars in 2024-2026 COMPUTING CHIPS DISTRIBUTED INFERENCE CUSTOMER INSIGHTS SOFTWARE DEVELOPMENT Lamb Labs OpenRelay BuiltBlock /dev/fast Chips with AI models embedded directly in hardware. Infrastructure for distributed AI inference across different hardware. A platform that brings together customer interactions across teams and tools to inform product decisions. A code-development platform built around AI-assisted workflows. APPLICATION APPLICATION APPLICATION APPLICATION Model execution Inference workloads Product strategy Code development Semiconductors Computing infrastructure Software platform Developer tools YC / 2026 YC / 2026 Techstars / 2026 YC / 2026 Sources: linked company profiles and portfolio descriptions. Selection: distinct products and applications. 13
  14. REFERENCE / MARKET EVIDENCE Market data: scope, periods and public

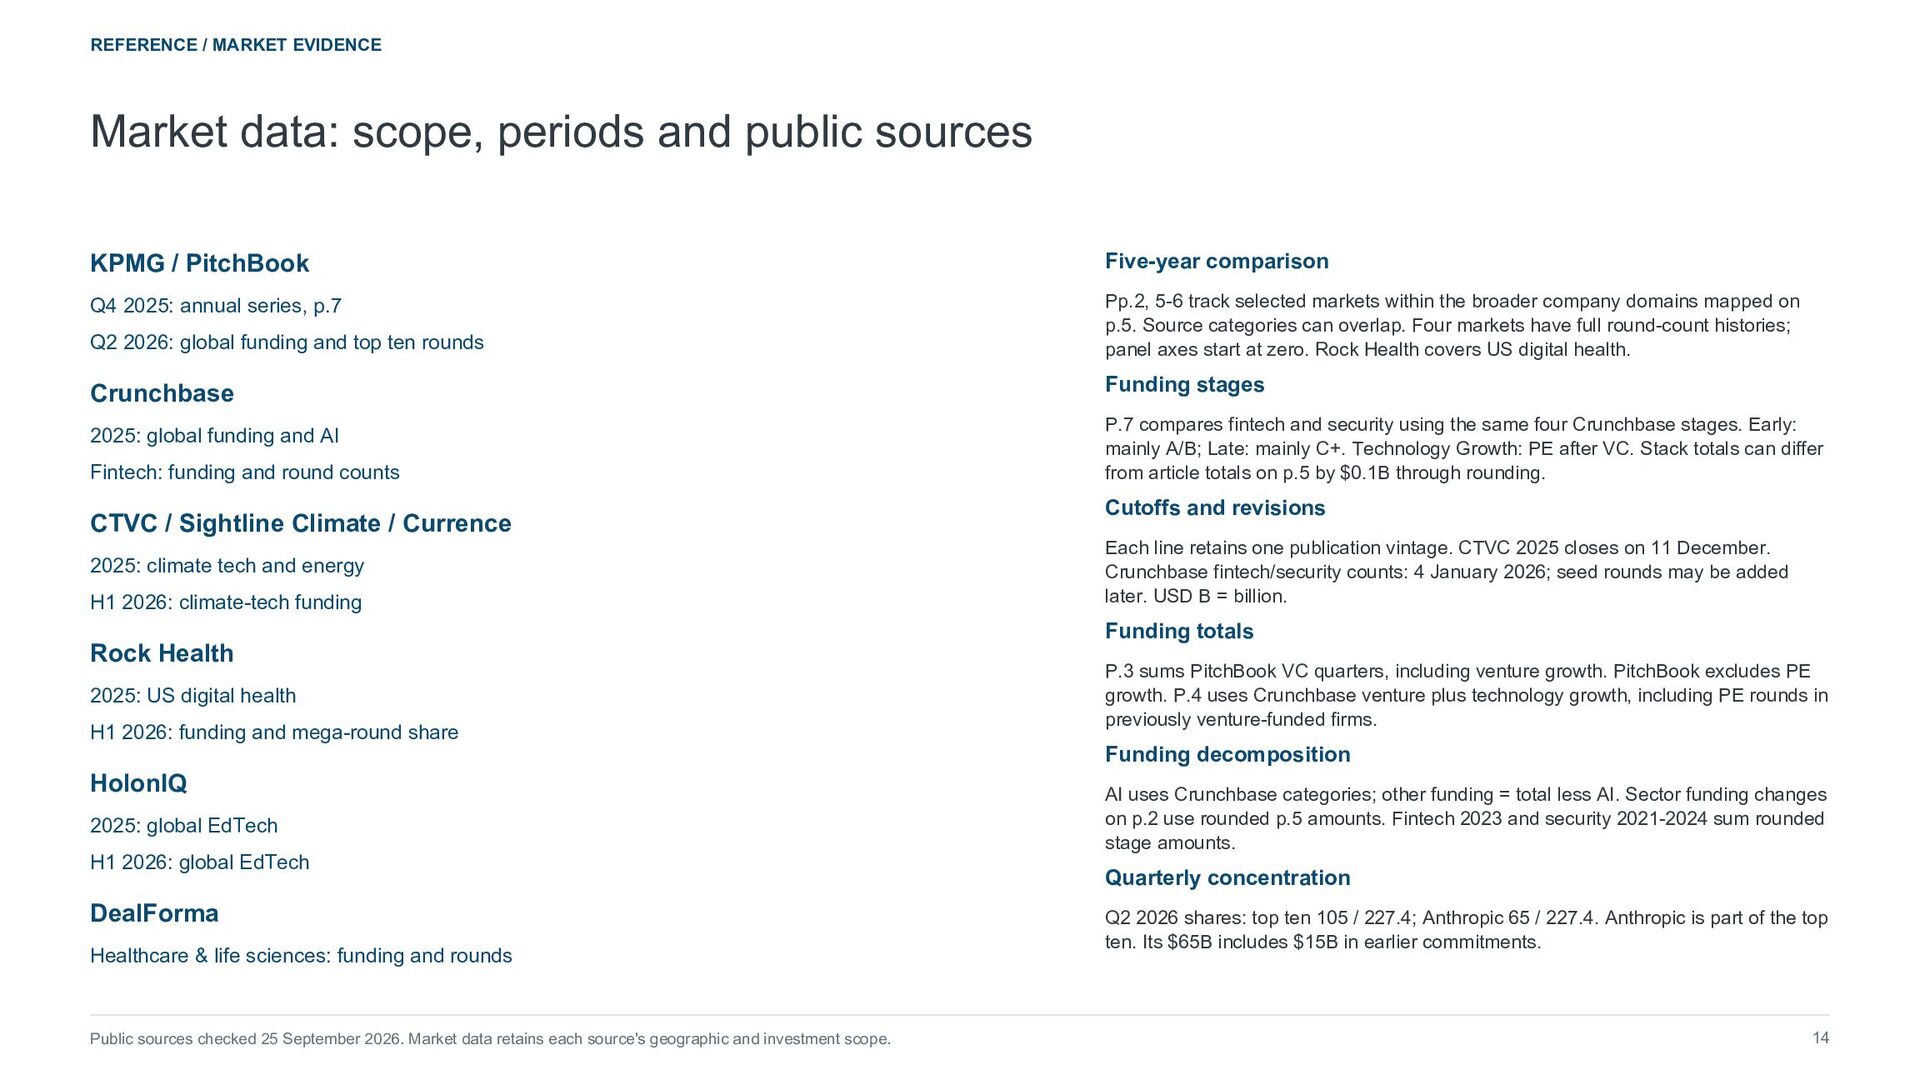
    sources KPMG / PitchBook Five-year comparison Q4 2025: annual series, p.7 Pp.2, 5-6 track selected markets within the broader company domains mapped on p.5. Source categories can overlap. Four markets have full round-count histories; panel axes start at zero. Rock Health covers US digital health. Q2 2026: global funding and top ten rounds Crunchbase 2025: global funding and AI Fintech: funding and round counts CTVC / Sightline Climate / Currence 2025: climate tech and energy H1 2026: climate-tech funding Funding stages P.7 compares fintech and security using the same four Crunchbase stages. Early: mainly A/B; Late: mainly C+. Technology Growth: PE after VC. Stack totals can differ from article totals on p.5 by $0.1B through rounding. Cutoffs and revisions Each line retains one publication vintage. CTVC 2025 closes on 11 December. Crunchbase fintech/security counts: 4 January 2026; seed rounds may be added later. USD B = billion. Funding totals Rock Health 2025: US digital health H1 2026: funding and mega-round share P.3 sums PitchBook VC quarters, including venture growth. PitchBook excludes PE growth. P.4 uses Crunchbase venture plus technology growth, including PE rounds in previously venture-funded firms. Funding decomposition HolonIQ 2025: global EdTech H1 2026: global EdTech DealForma Healthcare & life sciences: funding and rounds Public sources checked 25 September 2026. Market data retains each source's geographic and investment scope. AI uses Crunchbase categories; other funding = total less AI. Sector funding changes on p.2 use rounded p.5 amounts. Fintech 2023 and security 2021-2024 sum rounded stage amounts. Quarterly concentration Q2 2026 shares: top ten 105 / 227.4; Anthropic 65 / 227.4. Anthropic is part of the top ten. Its $65B includes $15B in earlier commitments. 14
  15. REFERENCE / COMPANY LANDSCAPE Company universe, product selection and sources

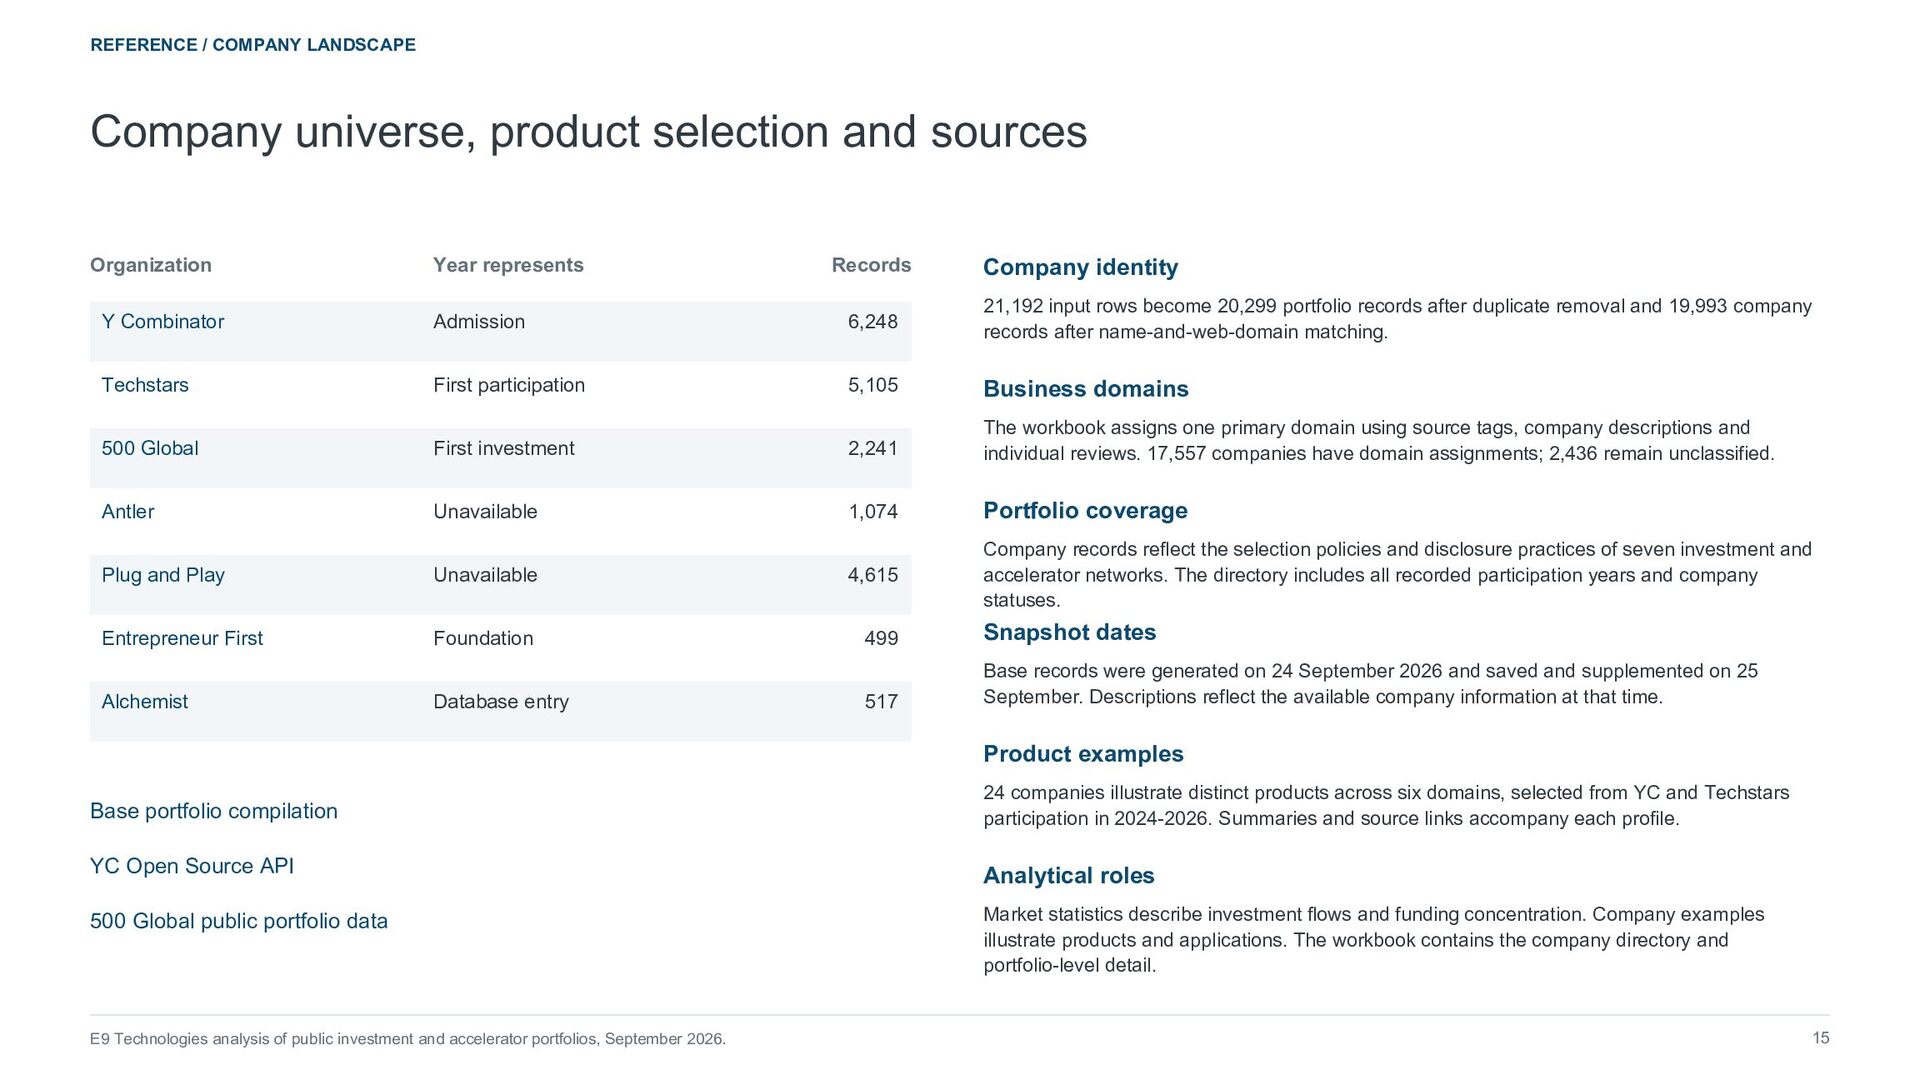
    Organization Year represents Records Y Combinator Admission 6,248 21,192 input rows become 20,299 portfolio records after duplicate removal and 19,993 company records after name-and-web-domain matching. Techstars First participation 5,105 Business domains 500 Global First investment 2,241 The workbook assigns one primary domain using source tags, company descriptions and individual reviews. 17,557 companies have domain assignments; 2,436 remain unclassified. Antler Unavailable 1,074 Portfolio coverage Company records reflect the selection policies and disclosure practices of seven investment and accelerator networks. The directory includes all recorded participation years and company statuses. Company identity Plug and Play Unavailable 4,615 Entrepreneur First Foundation 499 Snapshot dates 517 Base records were generated on 24 September 2026 and saved and supplemented on 25 September. Descriptions reflect the available company information at that time. Alchemist Database entry Product examples Base portfolio compilation 24 companies illustrate distinct products across six domains, selected from YC and Techstars participation in 2024-2026. Summaries and source links accompany each profile. YC Open Source API Analytical roles 500 Global public portfolio data Market statistics describe investment flows and funding concentration. Company examples illustrate products and applications. The workbook contains the company directory and portfolio-level detail. E9 Technologies analysis of public investment and accelerator portfolios, September 2026. 15