Upgrade to Pro — share decks privately, control downloads, hide ads and more …

SVB Registration in India and Related Party Cus...

Avatar for SKMC Global SKMC Global
September 16, 2026

SVB Registration in India and Related Party Customs Valuation

A practical guide to SVB Registration in India, Special Valuation Branch examination, related-party imports and Customs valuation. Learn when SVB may become relevant, how related-party import valuation works, key documentation requirements, common compliance risks, and the difference between Customs valuation and transfer pricing.

SKMC Global assists businesses with SVB advisory, related-party Customs valuation, documentation review and support during Customs and SVB proceedings in India.

Learn more about SVB Registration in India:
https://www.skmcglobal.com/service/special-valuation-branch-registrations

Avatar for SKMC Global

SKMC Global

September 16, 2026

Other Decks in Business

Transcript

  1. SKMC GLOBAL SVB Registration in India Related-Party Customs Valuation Guide

    A practical overview for Indian importers purchasing goods from overseas parent companies, group entities or other related suppliers. SPECIAL VALUATION BRANCH Noida | Mumbai | Bangalore | Singapore | Japan RELATED-PARTY IMPORTS CUSTOMS VALUATION 1 | SKMC Global
  2. SKMC GLOBAL What is the Special Valuation Branch (SVB)? SVB

    is a Customs mechanism used to examine valuation issues in specified import transactions, particularly where the buyer and seller are related. KEY QUESTION The central question is whether the relationship between the importer and overseas supplier has influenced the declared transaction value. Has the relationship Being related does not, by itself, mean that the declared value must be rejected. The facts, pricing arrangement and supporting evidence matter. influenced the price declared to Customs? The Customs valuation analysis is carried out under the applicable provisions of the Customs Act and Customs Valuation Rules. SVB should be viewed as a Customs valuation process not simply as a licence. Noida | Mumbai | Bangalore | Singapore | Japan 2 | SKMC Global
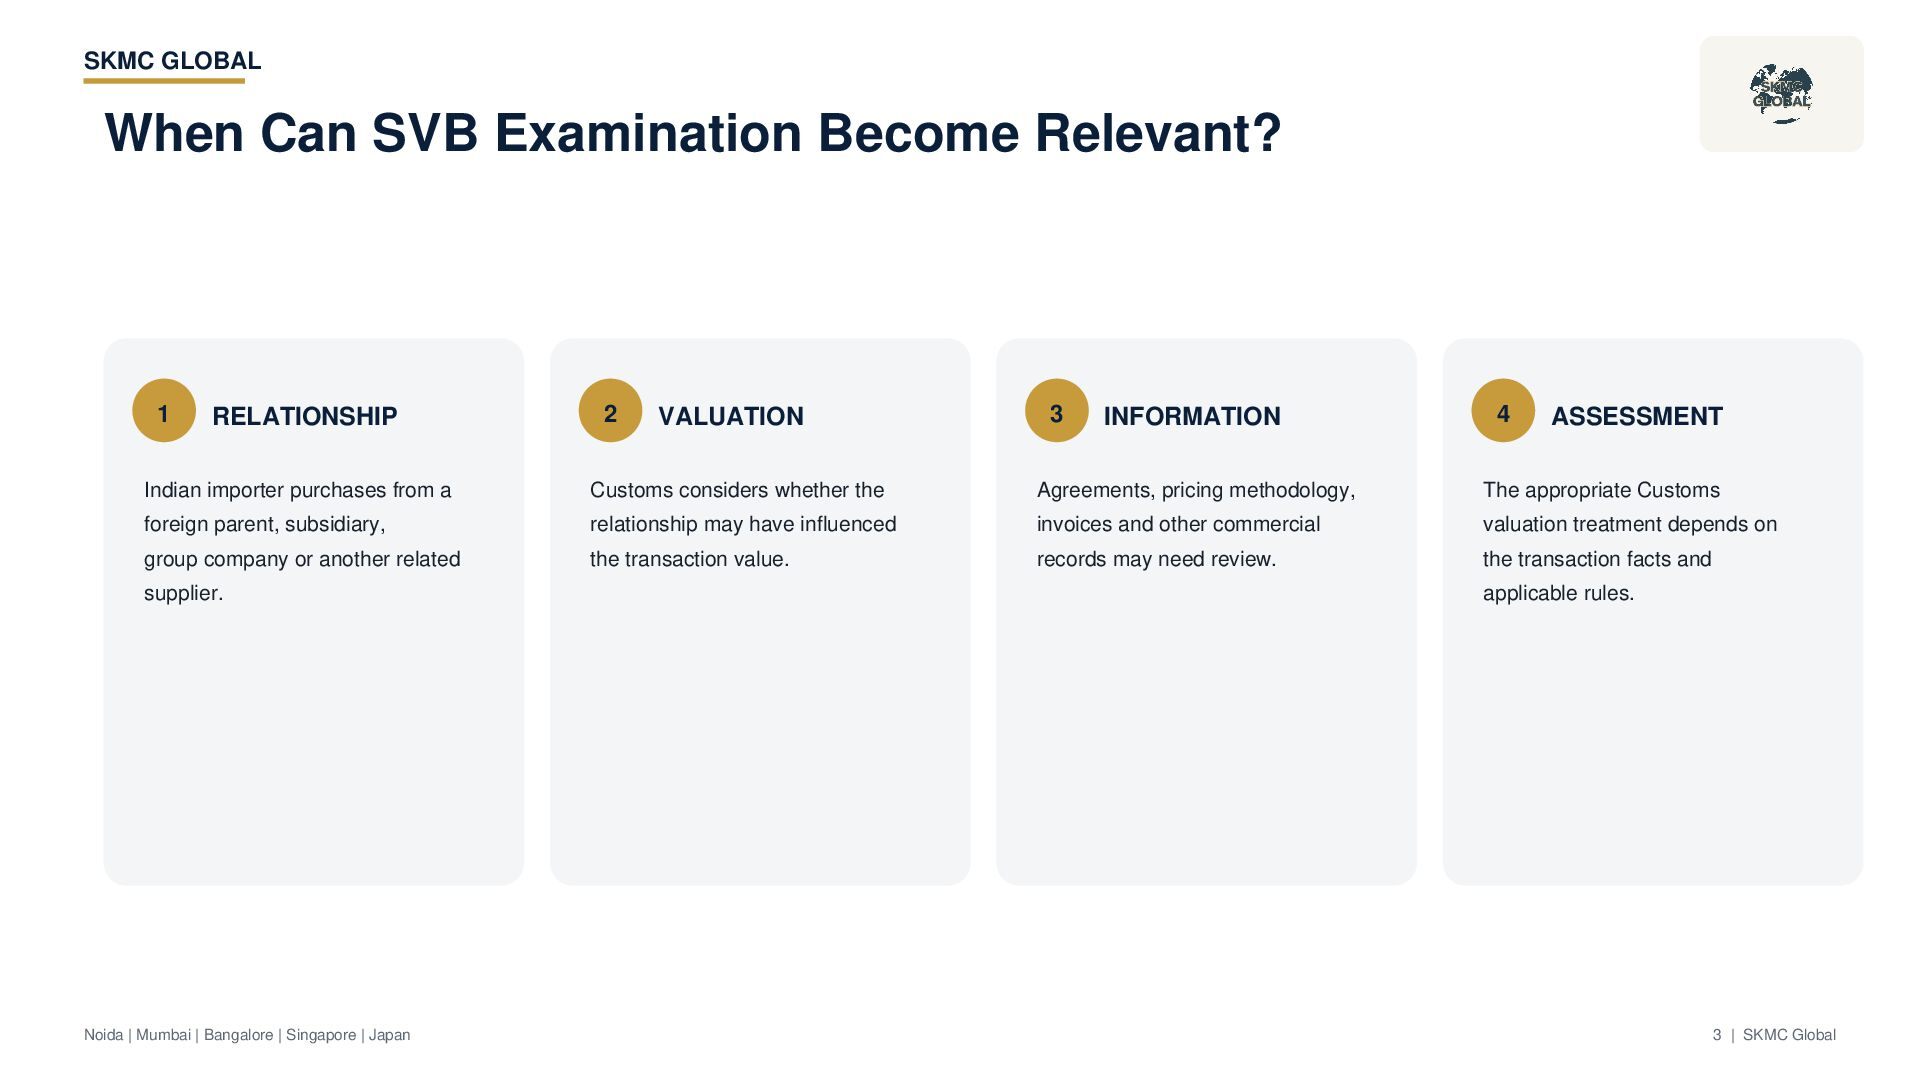
  3. SKMC GLOBAL When Can SVB Examination Become Relevant? 1 RELATIONSHIP

    2 VALUATION 3 INFORMATION 4 ASSESSMENT Indian importer purchases from a Customs considers whether the Agreements, pricing methodology, The appropriate Customs foreign parent, subsidiary, relationship may have influenced invoices and other commercial valuation treatment depends on group company or another related the transaction value. records may need review. the transaction facts and supplier. Noida | Mumbai | Bangalore | Singapore | Japan applicable rules. 3 | SKMC Global
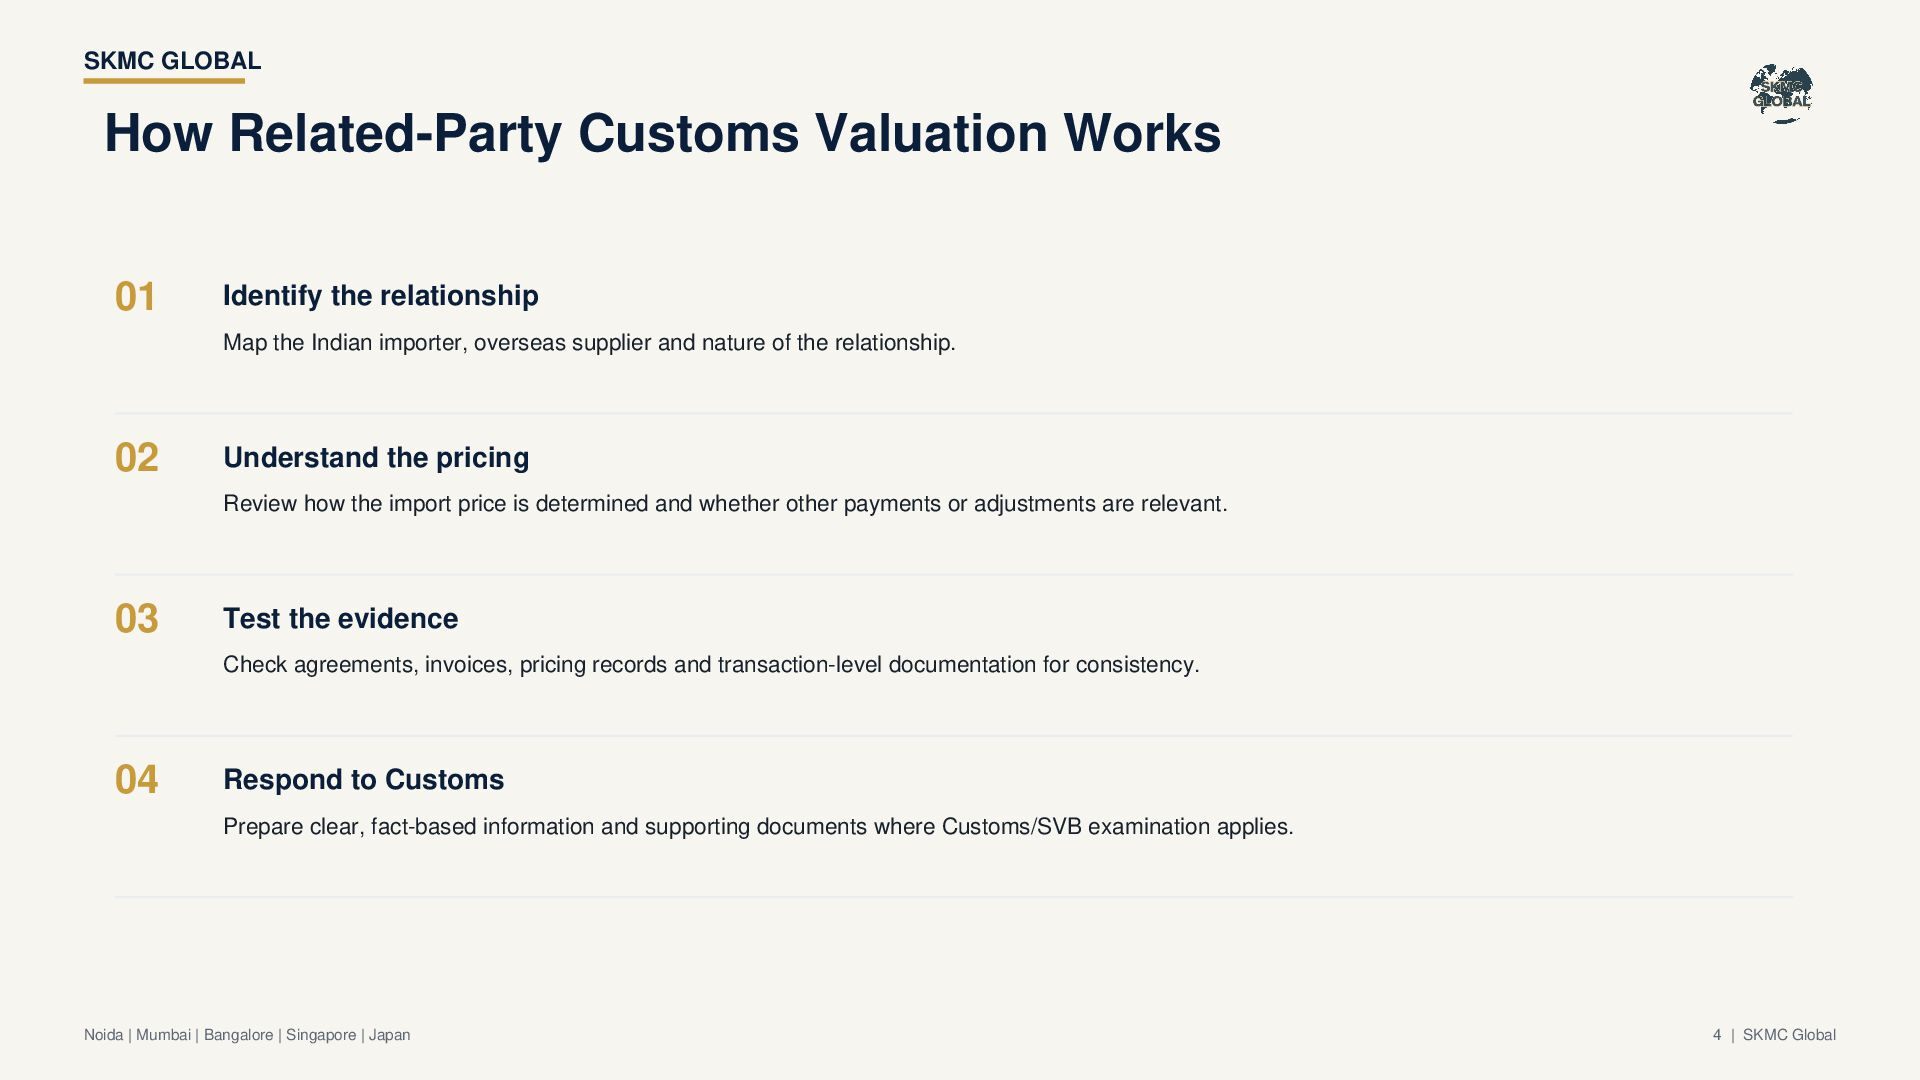
  4. SKMC GLOBAL How Related-Party Customs Valuation Works 01 Identify the

    relationship Map the Indian importer, overseas supplier and nature of the relationship. 02 Understand the pricing Review how the import price is determined and whether other payments or adjustments are relevant. 03 Test the evidence Check agreements, invoices, pricing records and transaction-level documentation for consistency. 04 Respond to Customs Prepare clear, fact-based information and supporting documents where Customs/SVB examination applies. Noida | Mumbai | Bangalore | Singapore | Japan 4 | SKMC Global
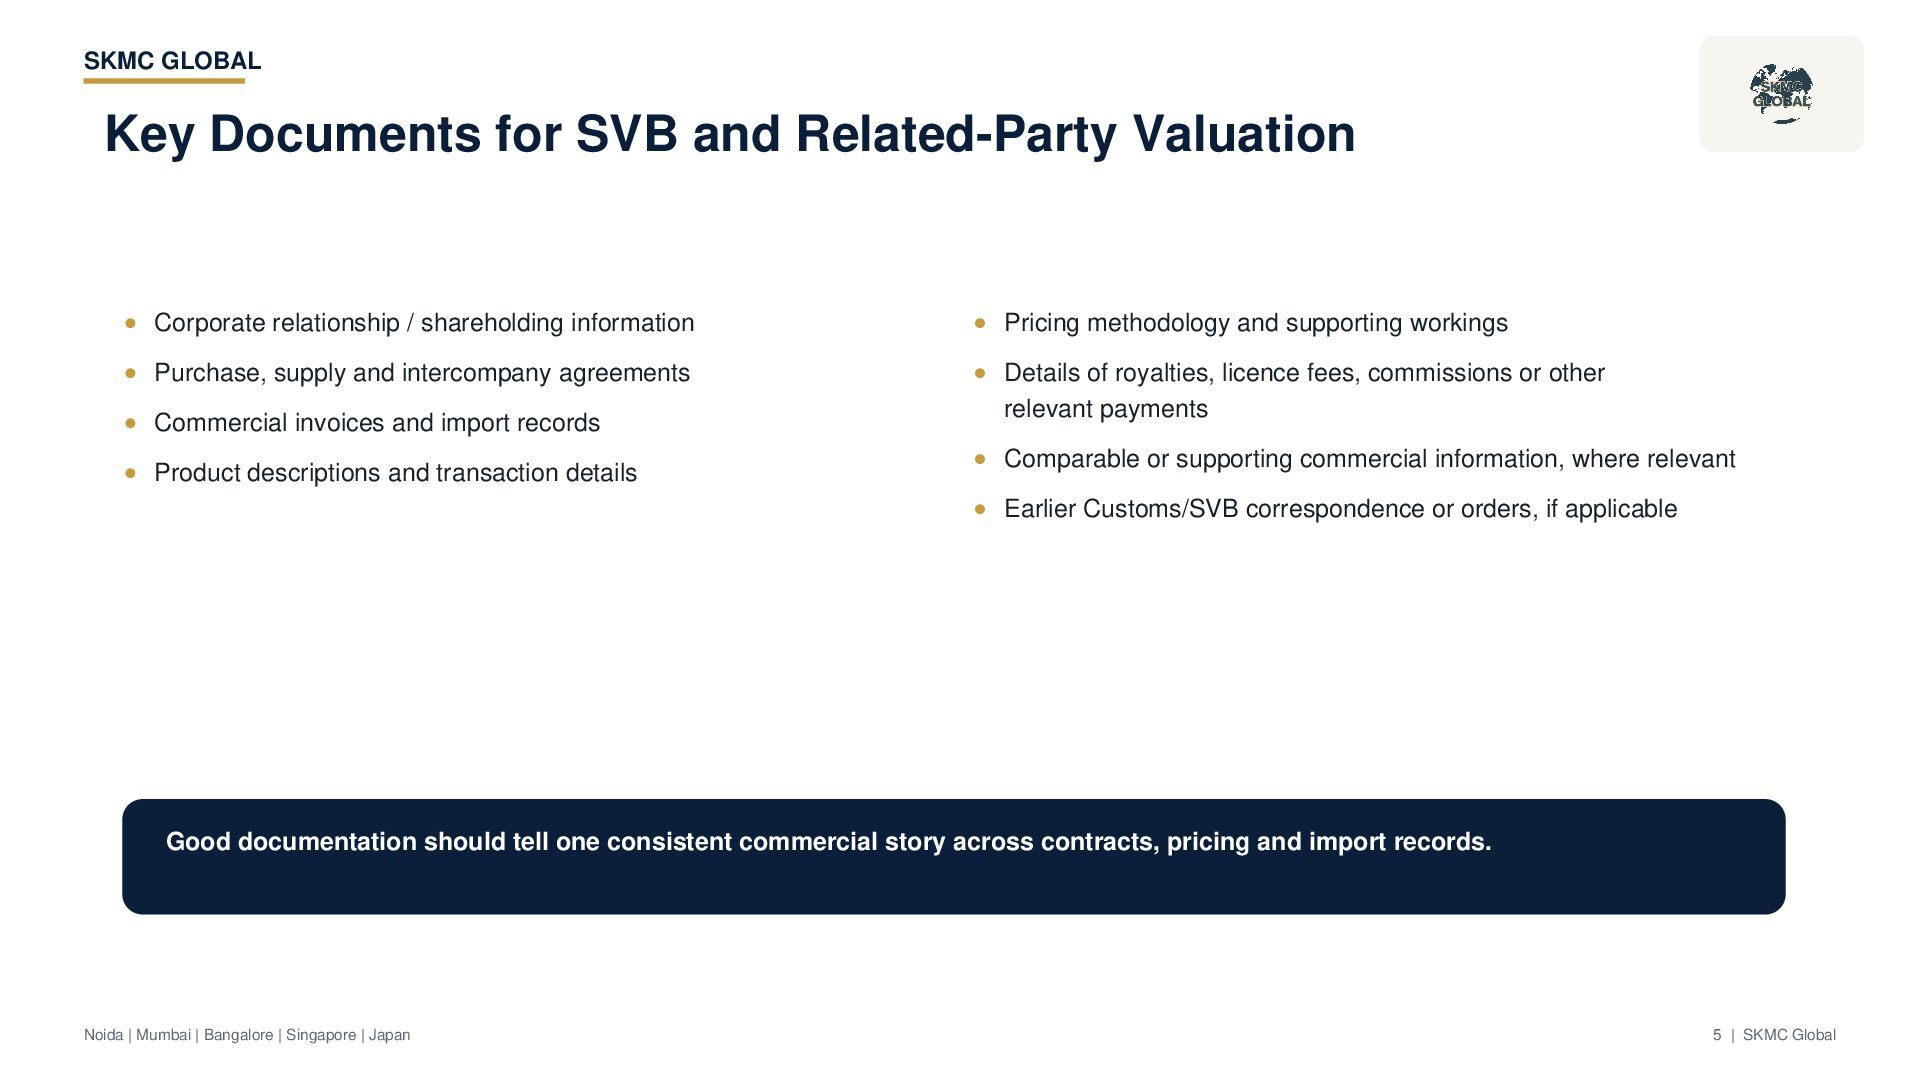
  5. SKMC GLOBAL Key Documents for SVB and Related-Party Valuation Corporate

    relationship / shareholding information Pricing methodology and supporting workings Purchase, supply and intercompany agreements Details of royalties, licence fees, commissions or other relevant payments Commercial invoices and import records Product descriptions and transaction details Comparable or supporting commercial information, where relevant Earlier Customs/SVB correspondence or orders, if applicable Good documentation should tell one consistent commercial story across contracts, pricing and import records. Noida | Mumbai | Bangalore | Singapore | Japan 5 | SKMC Global
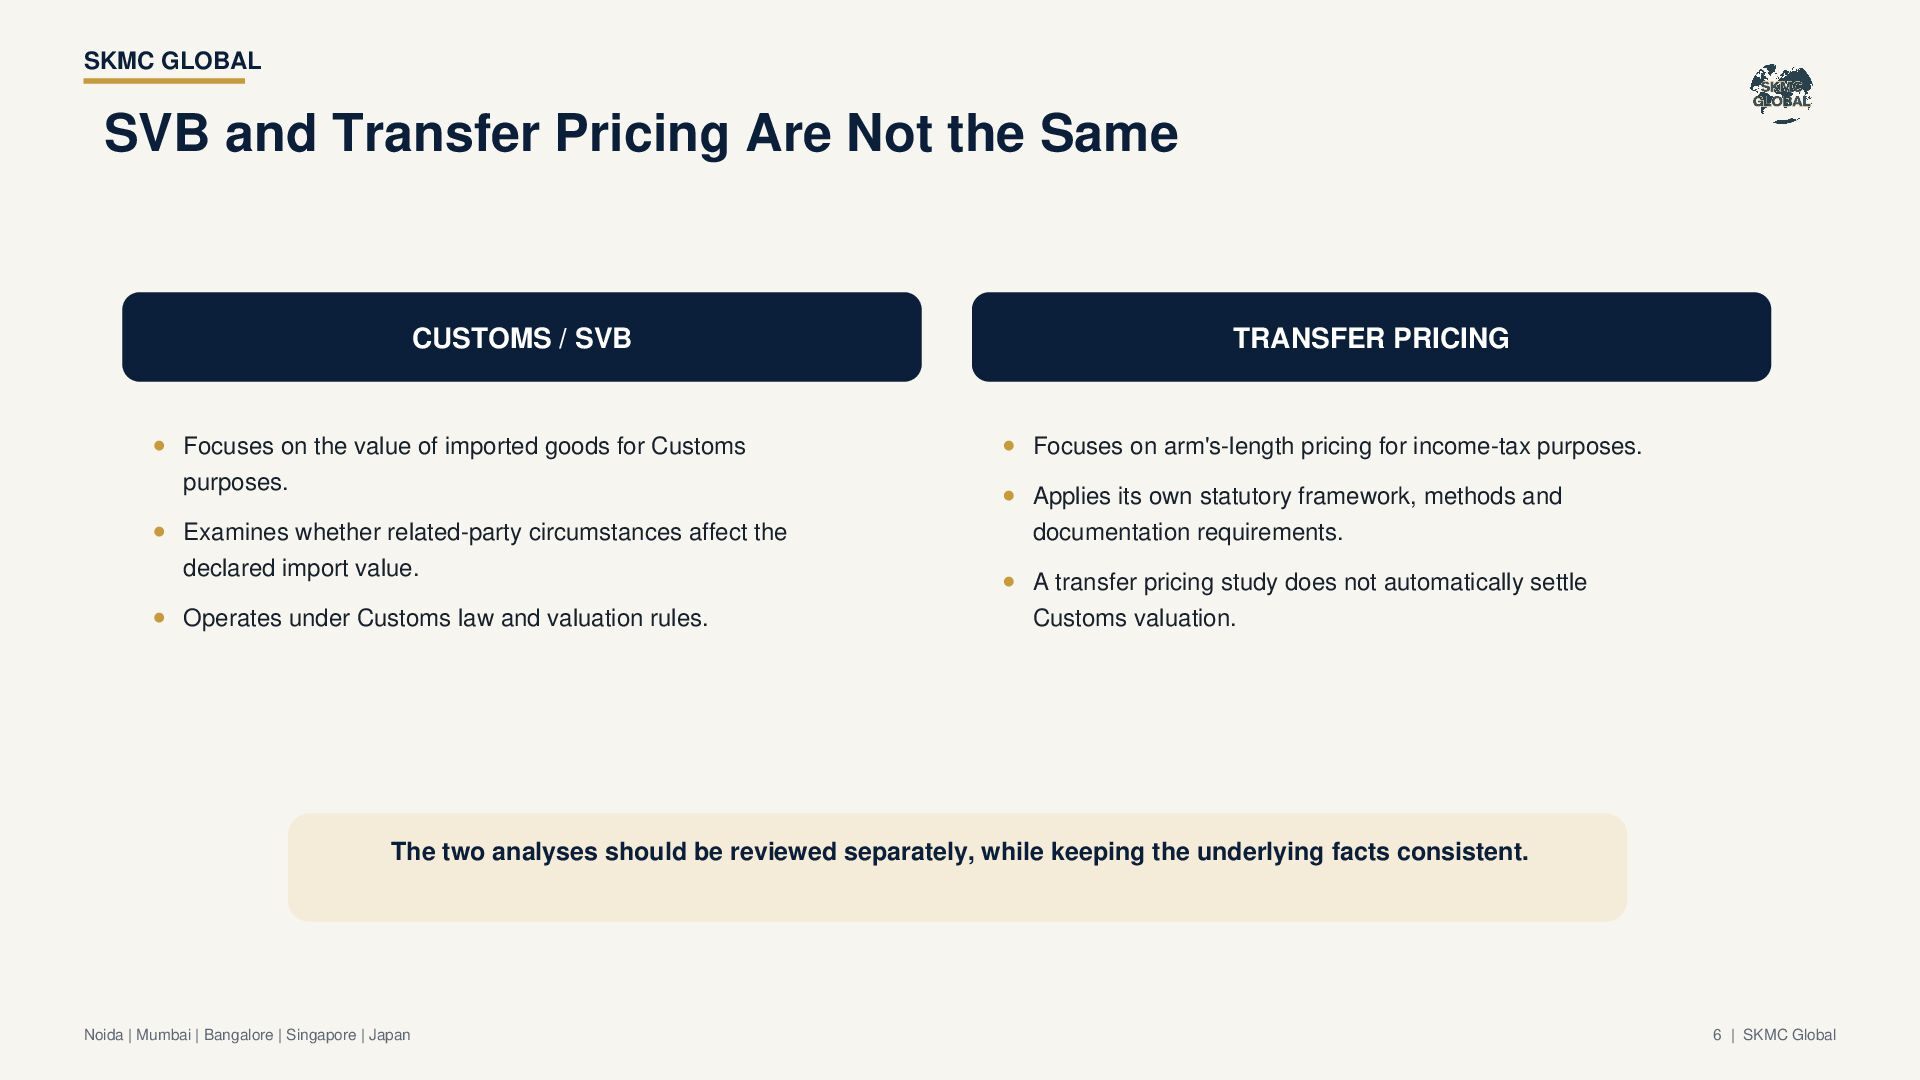
  6. SKMC GLOBAL SVB and Transfer Pricing Are Not the Same

    CUSTOMS / SVB Focuses on the value of imported goods for Customs purposes. Examines whether related-party circumstances affect the declared import value. Operates under Customs law and valuation rules. TRANSFER PRICING Focuses on arm's-length pricing for income-tax purposes. Applies its own statutory framework, methods and documentation requirements. A transfer pricing study does not automatically settle Customs valuation. The two analyses should be reviewed separately, while keeping the underlying facts consistent. Noida | Mumbai | Bangalore | Singapore | Japan 6 | SKMC Global
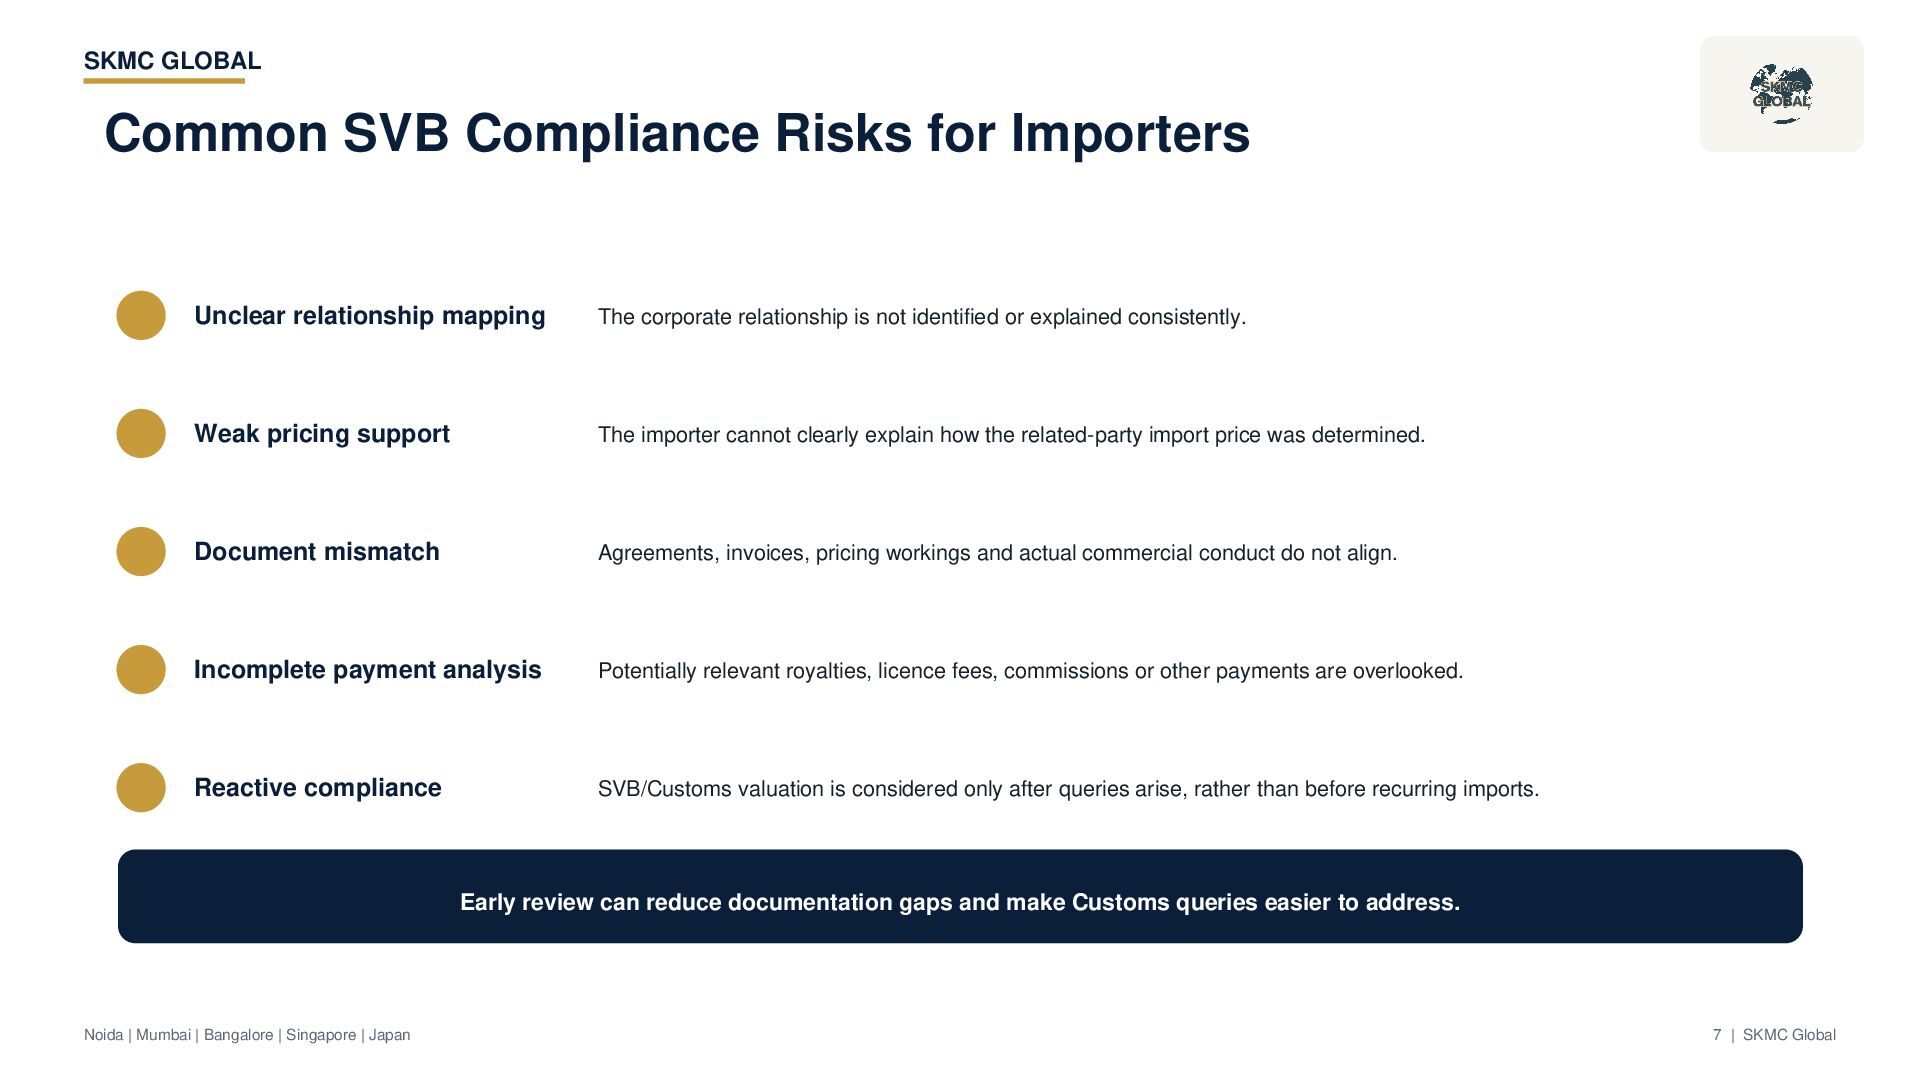
  7. SKMC GLOBAL Common SVB Compliance Risks for Importers Unclear relationship

    mapping The corporate relationship is not identified or explained consistently. Weak pricing support The importer cannot clearly explain how the related-party import price was determined. Document mismatch Agreements, invoices, pricing workings and actual commercial conduct do not align. Incomplete payment analysis Potentially relevant royalties, licence fees, commissions or other payments are overlooked. Reactive compliance SVB/Customs valuation is considered only after queries arise, rather than before recurring imports. Early review can reduce documentation gaps and make Customs queries easier to address. Noida | Mumbai | Bangalore | Singapore | Japan 7 | SKMC Global
  8. SKMC GLOBAL How SKMC Global Can Assist SVB applicability and

    related-party import assessment Review of intercompany agreements and import arrangements Customs valuation documentation and information support Assistance with SVB / Customs queries and proceedings Coordination of transaction facts, pricing records and supporting evidence LEARN MORE Special Valuation Branch (SVB) Registration in India [email protected] | +91 989-125-5499 | www.skmcglobal.com Disclaimer: General information only. Customs valuation treatment depends on transaction facts and applicable law.